
 Upper Limb Prosthetics Market | 2026-2036
Upper Limb Prosthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Upper Limb Prosthetics Market Analysis
Software-defined myoelectric calibration and remote tuning services is rebalancing how manufacturers capture lifetime value from each device deployment. Ottobock leverages its global rehabilitation clinic network to sustain recurring patient relationships across fitting and maintenance cycles. Össur anchors its competitive stance through R&D intensity in bionic signal processing, while Open Bionics differentiates via accessible 3D-printed designs that occupy the pediatric and emerging-market price tier.
Upper limb prosthetics are electromechanical or passive devices engineered to replace partial or complete arm or hand function, typically incorporating carbon fiber sockets, silicone liners, and terminal devices rated for specific grip force and wrist rotation parameters. Their primary purpose is restoring manipulative capability for amputees across vocational, recreational, and self-care activities. Myoelectric prosthetics command the premium segment where signal fidelity and battery efficiency determine clinical outcomes, while body-powered systems retain cost-sensitive volume through mechanical durability and lower maintenance burden. The robotics technology layer within smart sensor-integrated devices represents the fastest-expanding margin pool as pattern recognition algorithms improve intuitive control.
The FDA regulates these devices as Class II medical products requiring 510(k) premarket notification, while the EU MDR mandates notified body conformity assessment and post-market clinical follow-up for CE-marked prosthetics. ISO 10328 structural testing standards govern load-bearing specifications, shaping how manufacturers design socket interfaces and component durability. Stakeholders must monitor evolving reimbursement codes from CMS and parallel national health technology assessment bodies, as coverage determinations for advanced myoelectric and robotic systems will dictate which patient populations access next-generation functionality.
Market Dynamics
Myoelectric signal processing algorithms are compressing the functional gap between prosthetic devices and natural limb control, forcing manufacturers to restructure R&D spending toward software-defined architectures rather than mechanical refinement alone.
Growth Catalysts
- Reimbursement Framework Modernization:CMS coverage determinations for advanced myoelectric systems in the United States are expanding patient eligibility beyond traumatic amputation to include dysvascular and congenital indications.
- Pediatric Early Intervention Protocols:Specialized rehabilitation centers in Germany now fit body-powered devices as young as 18 months, establishing prosthetic acceptance patterns before neural plasticity windows narrow.
- Carbon Fiber Manufacturing Scale:Automated filament winding and resin transfer molding from aerospace suppliers is reducing socket production costs while improving strength-to-weight ratios for active users.
Market Restraints
- Supply Concentration in Lithium-Ion Cells:Battery pack sourcing for myoelectric devices depends on cylindrical cell formats dominated by East Asian chemical suppliers, exposing manufacturers to raw material price volatility and export control friction.
- Technical Limitation in Signal Latency:Surface electrode arrays cannot resolve deep muscle activation patterns, capping intuitive control fidelity below the threshold required for fine manipulation tasks in occupational settings.
- Regulatory Friction from EU MDR:Notified body capacity constraints and expanded clinical evidence requirements for CE marking are extending commercialization timelines by 18-24 months for novel terminal device designs.
Strategic Opportunities
- Underpenetrated Geography:India's tier-2 cities present whitespace where government disability benefit expansion and nascent prosthetic technician training programs are creating first-time access corridors for body-powered systems.
- Technology Convergence:Integration of haptic feedback arrays with pattern recognition software is enabling closed-loop control systems that restore sensory awareness for grip force modulation.
- Distribution Channel Innovation:Direct-to-patient remote fitting platforms using 3D scanning and telehealth consultations are bypassing traditional orthotic-prosthetic clinic networks in rural Australia and Canada.
Industry Challenges
- Prosthetist Training Pipeline Bottleneck:Accredited myoelectric fitting certification programs in the United States and Germany graduate fewer specialists than replacement demand requires, constraining device utilization rates.
- Post-Market Surveillance Burden:EU MDR mandates for systematic clinical follow-up data collection are forcing manufacturers to rebuild quality management systems around real-world performance registries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Upper Limb Prosthetics Market |
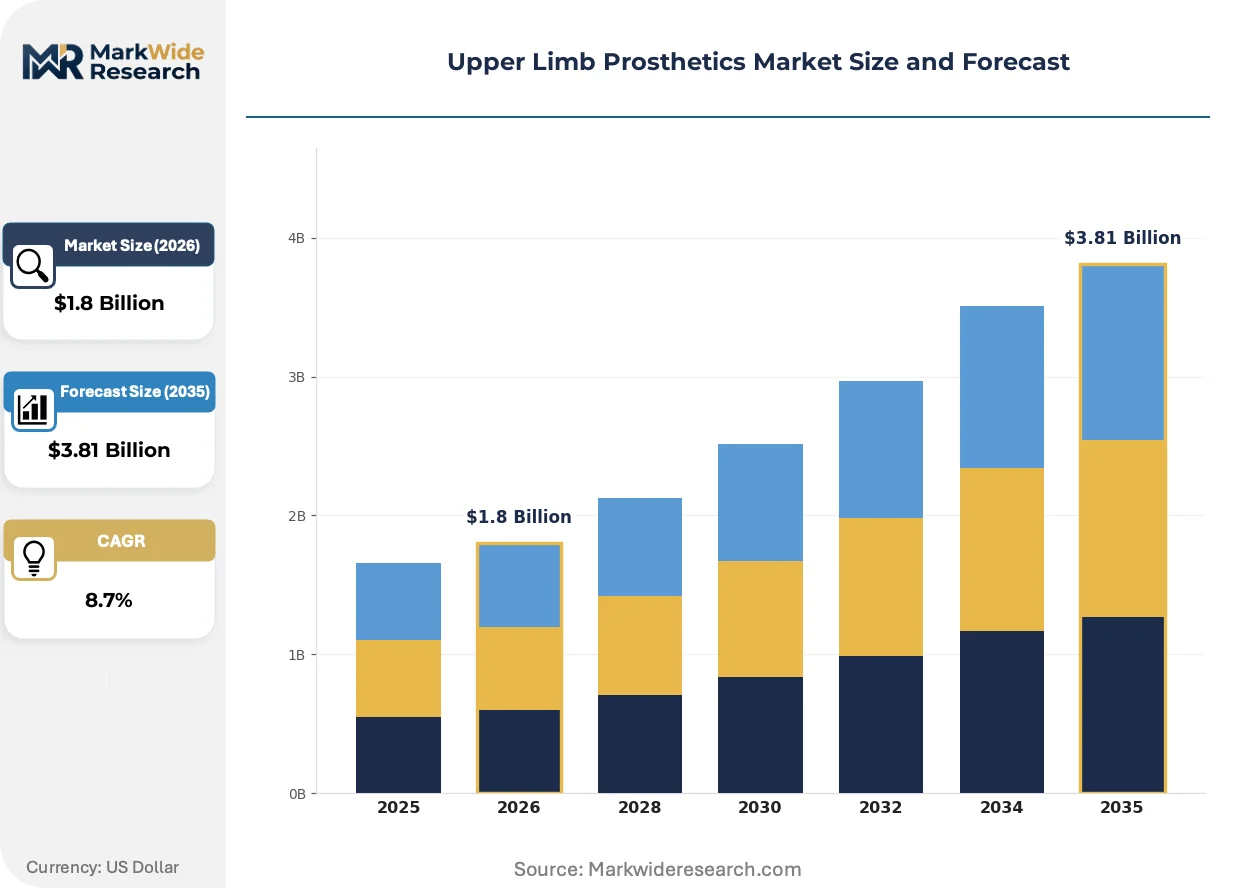
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Prosthetics, Myoelectric Prosthetics, Hybrid Prosthetics, Body-Powered Prosthetics End User: Adults, Children, Veterans, Amputees Technology: Robotics, Smart Sensors, 3D Printing, Assistive Technology Application: Rehabilitation, Enhancement, Sports, Daily Living |
| Companies Covered | Ottobock, Össur, Fillauer LLC, Steeper Group, Blatchford, Open Bionics, Mobius Bionics, Coapt LLC, COVVI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Upper Limb Prosthetics Market Emerging Trajectories
Neural interface architectures and software-defined calibration protocols are displacing hardware-centric design paradigms, compressing product development cycles while fragmenting competitive advantage across new capability domains.
Implantable myoelectric sensors are expanding into the high-activity user segment where socket-suspended surface electrodes fail under sweat and movement artifact conditions. Veterans' healthcare systems in the United States are piloting these devices for bilateral amputees requiring coordinated bilateral control. The technology is expanding into recreational and vocational applications previously considered incompatible with external power systems.
The EU MDR's post-market clinical follow-up requirements are forcing manufacturers to restructure quality management systems around systematic performance registries rather than adverse event reporting alone. Small-to-mid-sized device companies face disproportionate compliance costs, accelerating consolidation toward firms with captive notified body relationships. Myoelectric hand systems with novel grip patterns are experiencing the longest assessment backlogs as clinical evidence standards remain unsettled.
Hospital procurement committees are unbundling device acquisition from fitting and maintenance services, creating separate vendor relationships for hardware supply and clinical delivery. This disintermediation pressures traditional orthotic-prosthetic clinic networks in Germany and Japan to compete on service efficiency rather than exclusive manufacturer relationships. The shift is most visible in workers' compensation cases where payers seek direct warranty and performance accountability from device manufacturers.
Upper Limb Prosthetics Market Segmentation
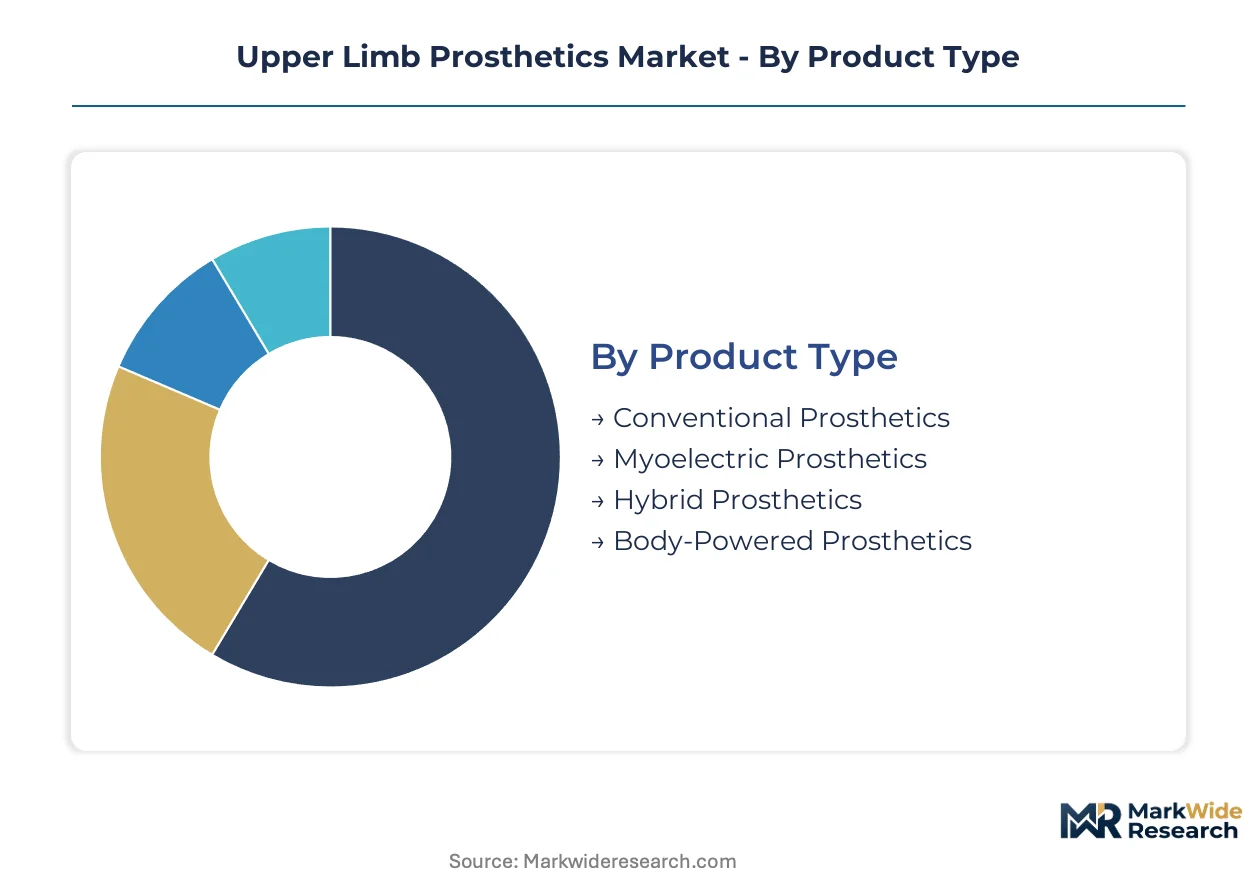
Upper limb prosthetics manufacturers configure product portfolios across four distinct axes: power source, patient demographics, embedded technology, and intended functional use. Each segmentation dimension carries different margin profiles, regulatory pathways, and service attachment rates that reshape how firms allocate R&D and distribution resources.
Product Type:
Customization intensity varies sharply across this spectrum, from standardized body-powered mechanisms to patient-specific myoelectric socket interfaces requiring iterative electromyographic mapping.
- Myoelectric Prosthetics:Surface electrode arrays detect voluntary muscle contractions to drive motorized grippers and wrist rotators. Demand clusters in Germany and Japan where statutory health insurance covers microprocessor-controlled terminal devices for working-age traumatic amputees. Battery efficiency and signal processing fidelity determine clinical outcomes and replacement cycles.
- Body-Powered Prosthetics:Cable-driven harness systems translate shoulder or chest movement into mechanical grip force through voluntary opening or closing mechanisms. Volume concentrates in India's tier-2 cities and United States workers' compensation programs where durability and maintenance simplicity outweigh functional sophistication. These devices retain cost-sensitive share through mechanical reliability in agricultural and industrial vocational settings.
- Conventional Prosthetics:Passive cosmetic devices without active grasp functionality serve aesthetic restoration needs in post-surgical recovery phases.
- Hybrid Prosthetics:Combined body-powered and myoelectric elements address specific functional gaps for transhumeral amputees requiring both elbow flexion and powered prehension.
Most installed capacity flows through body-powered systems. Expansion is steepest in myoelectric prosthetics.
End User:
Reimbursement eligibility criteria and neural plasticity windows create divergent service models across patient life stages and etiology.
- Adults:Working-age traumatic and dysvascular amputees drive premium myoelectric adoption where vocational reintegration justifies advanced functionality. United States CMS coverage determinations increasingly include this population for bionic hand systems with multi-articulating digits.
- Veterans:Bilateral upper limb loss from combat trauma has accelerated implantable myoelectric sensor development through United States Veterans Health Administration pilot programs. These users demand coordinated bilateral control for recreational and vocational applications exceeding standard commercial specifications.
- Children:Early fitting protocols in German rehabilitation centers establish prosthetic acceptance before neural plasticity narrows, though growth-related socket replacement creates recurring service relationships.
- Amputees:Congenital limb deficiency patients require specialized pediatric-to-adult transition pathways with sequential device scaling.
Adult traumatic cases absorb the majority of myoelectric unit shipments. Pediatric segments are climbing the fastest as early intervention protocols expand.
Technology:
Intellectual property concentration and component sourcing strategies fragment competitive advantage across hardware and software layers.
- Robotics:Multi-articulating hands with independent digit control and adaptive grip patterns represent the highest-value hardware tier. Pattern recognition algorithms for intuitive control are concentrating R&D investment among firms with captive software development capabilities.
- Smart Sensors:Force-sensitive resistors and inertial measurement units enable closed-loop grip modulation. These components are gaining share fastest as haptic feedback integration restores sensory awareness for delicate object manipulation.
- 3D Printing:Fused deposition modeling and selective laser sintering reduce socket fabrication lead times for pediatric and emerging-market applications where traditional plaster casting infrastructure is scarce.
- Assistive Technology:Terminal device accessories and activity-specific attachments extend functional range for recreational and vocational tasks without replacing core prosthetic systems.
Robotics platforms command the highest average selling prices. Smart sensor integration is expanding most quickly as manufacturers differentiate through software-defined feature upgrades.
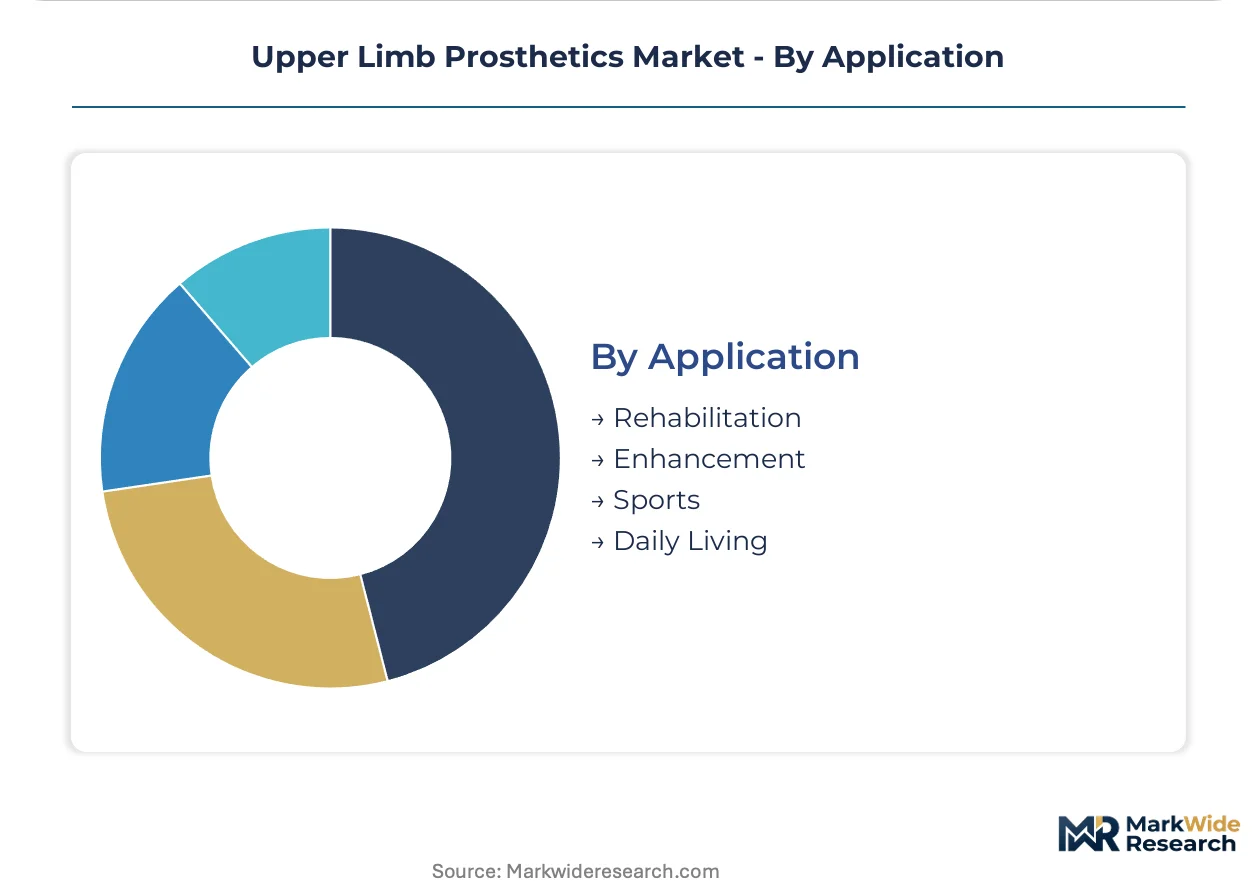
Application:
Functional requirements and performance validation protocols vary across medical, lifestyle, and performance-oriented use cases.
- Rehabilitation:Post-amputation fitting and training services within specialized clinics in Germany and Japan establish long-term patient relationships. These settings prioritize socket comfort and control training over terminal device sophistication.
- Daily Living:Self-care and household task performance drives demand for reliable grip force and wrist rotation in unilateral amputees. United States Medicare coverage determinations focus heavily on functional assessment scores in this category.
- Sports:Activity-specific terminal devices for cycling, climbing, and weightlifting require custom fabrication and rapid interchange mechanisms. These applications push material durability limits for carbon fiber and polymer components.
- Enhancement:Supernumerary and augmentation devices for non-amputees remain experimental, with regulatory pathways undefined under FDA and EU MDR frameworks.
Rehabilitation channels process the greatest device volume. Sports applications are gaining share fastest as recreational user segments expand beyond medical necessity definitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost disparities between jurisdictions are redirecting manufacturing investment toward markets with streamlined medical device approval pathways. The United States, Germany, and Japan concentrate demand through mature reimbursement frameworks, while India and emerging Asian markets attract production seeking lower compliance burdens.
United States
CMS coverage determinations for advanced myoelectric systems now extend beyond traumatic amputation to dysvascular and congenital indications, broadening eligible patient populations. FDA 510(k) premarket notification pathways remain the dominant regulatory route for Class II prosthetic devices. Veterans Health Administration pilot programs in Pittsburgh and San Antonio are accelerating implantable myoelectric sensor development for bilateral amputees.
Germany
Statutory health insurance covers microprocessor-controlled terminal devices for working-age traumatic amputees, sustaining premium myoelectric demand. EU MDR notified body conformity assessment and post-market clinical follow-up requirements govern CE marking timelines. Specialized rehabilitation centers in Berlin and Munich fit body-powered devices to children as young as 18 months, establishing early prosthetic acceptance patterns.
Japan
METI industrial policy supports domestic prosthetic component manufacturing through targeted R&D subsidies and standards harmonization. PMDA medical device review pathways align with international convergence initiatives to reduce regulatory duplication. Tokyo and Osaka host concentrated orthotic-prosthetic clinic networks that prioritize socket comfort and control training over terminal device sophistication.
India
Government disability benefit expansion in tier-2 cities is creating first-time access corridors for body-powered prosthetic systems. CDSCO medical device regulations are evolving toward risk-based classification harmonized with international frameworks. Prosthetic technician training programs in Pune and Hyderabad are scaling fabrication capacity for carbon fiber socket production.
Australia
TGA medical device approval pathways support direct-to-patient remote fitting platforms using 3D scanning and telehealth consultations. National Disability Insurance Scheme funding structures determine patient access to myoelectric versus body-powered device categories. Rural clinic networks in Queensland and Western Australia are bypassing traditional orthotic-prosthetic delivery models through digital fabrication integration.
Upper Limb Prosthetics Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated rehabilitation clinic networks competing against standalone component suppliers for patient relationship control. The market structure tilts toward consolidation at the premium myoelectric tier while fragmenting across body-powered and pediatric price tiers. Three archetypes dominate: vertically integrated rehabilitation service providers, R&D-intensive bionic technology developers, and accessible manufacturing innovators leveraging distributed fabrication. M&A activity concentrates on acquiring captive notified body relationships and software-defined calibration capabilities.
Within the integrated service tier, Ottobock anchors competitive positioning through its global rehabilitation clinic network sustaining recurring patient relationships. Among R&D-intensive developers, Össur occupies a position exemplifying signal processing specialization for intuitive control systems. On the accessible manufacturing vector, Open Bionics represents archetype innovation through 3D-printed design approaches targeting pediatric and emerging-market price tiers.
| Leading Market Players |
|---|
| Ottobock |
| Össur |
| Fillauer LLC |
| Steeper Group |
| Blatchford |
| Open Bionics |
| Mobius Bionics |
| Coapt LLC |
| COVVI |
| Others |
Supply Flow & Price Mechanics
Myoelectric versus body-powered device bifurcation creates divergent margin architectures across the upper limb prosthetics value chain, with premium signal-processing systems commanding reimbursement-linked pricing while mechanical durability determines cost-sensitive tier economics. This performance gap manifests in socket fabrication methods—automated carbon fiber winding for high-activity users versus thermoplastic sheet forming for emerging-market volume—and in battery chemistry sourcing, where cylindrical lithium-ion cell qualification requirements filter supplier pools differently than passive component procurement.
Pricing Analysis
Distributor margins absorb the service bundling complexity that manufacturers increasingly unbundle from hardware transactions. Three-tier pricing structure across premium myoelectric, standard body-powered, and economy passive cosmetic levels stratifies by FDA 510(k) clearance tier and CMS coverage determination eligibility. Cost compression in body-powered sockets intensifies as Indian tier-2 city procurement shifts toward government disability benefit tenders. Pediatric rehabilitation centers exhibit lowest price sensitivity due to statutory insurance mandates, while workers' compensation payers drive hardest bargain for vocational reintegration cases.
Supply Chain Analysis
Dual-sourcing requirements for myoelectric battery packs mandate qualification of cylindrical cell suppliers across China, South Korea, and Japan to mitigate export control friction. Carbon fiber prepeg draws from aerospace supplier networks in the United States and Germany, while silicone liner formulations rest on medical-grade polymer specialists in Switzerland and the United States. Single-source vulnerability concentrates in pattern recognition algorithm licensing for multi-articulating hands. Distribution runs through orthotic-prosthetic clinic networks in Germany and Japan, with direct-to-patient remote fitting platforms emerging in rural Australia and Canada.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The upper limb prosthetics market compounds steadily as reimbursement framework modernization expands eligible patient populations beyond traumatic amputation into dysvascular and congenital indications.
For Market Incumbents: Hedge against software-defined calibration disruption by acquiring captive pattern recognition algorithm developers before haptic feedback integration becomes table stakes. Secure backward integration into carbon fiber socket fabrication to defend margin position as hospital procurement committees unbundle device acquisition from fitting services. Prioritize notified body relationship depth under EU MDR post-market clinical follow-up mandates. For New Entrants and Emerging Players: Enter via India's tier-2 city government tender channels where prosthetic technician training program expansion outpaces established manufacturer distribution reach. Target body-powered device white space in agricultural vocational applications where durability specifications exceed current local supply capability. Deploy 3D scanning and telehealth consultation platforms to bypass traditional clinic network gatekeeping in rural geographies. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance costs disproportionately burden small-to-mid-sized device companies lacking systematic clinical performance registries. Five-to-ten year viability favors firms with integrated rehabilitation clinic networks sustaining recurring patient relationships across socket replacement cycles. Watch Veterans Health Administration implantable myoelectric sensor pilot program expansion as signal for high-activity user segment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Accelerates commercialization timelines for novel terminal device designs beyond EU MDR backlogs. |
| CE Marking Under EU MDR | Notified body conformity assessment governs access to German statutory health insurance reimbursement channels. |
| Hospital System Partnership | Procurement committee relationships secure unbundled hardware supply contracts separate from fitting services. |
| Software Companion Development | Remote tuning applications capture lifetime value through recurring calibration service relationships. |
| Reimbursement Strategy | CMS coverage determination alignment expands patient eligibility for advanced myoelectric systems. |
Methodological Framework
Direct dialogue with prosthetists, biomedical engineers, hospital purchasing committee members, and GPO contracts managers grounded qualitative insights in clinical workflow realities. Secondary validation drew from FDA 510(k) premarket notification databases, CMS Medicare coverage determination records, EU MDR notified body assessment documentation, and hospital procurement databases. Bottom-up demand modeling across patient etiology segments triangulated against top-down reimbursement expenditure analysis.
Segment-level outputs across the projection horizon reflect power source, patient demographic, embedded technology, and intended functional use dimensions. CAGRs were derived from fitted adoption curves incorporating neural plasticity window constraints for pediatric protocols and vocational reintegration timelines for working-age traumatic cases. Pattern recognition algorithm advancement rates and carbon fiber manufacturing scale trajectories informed technology penetration assumptions.
Inputs from CMS coverage determination filings and EU MDR notified body assessment timelines were available through the study window; gaps in real-world performance registry data for novel implantable myoelectric sensors introduce uncertainty bands around high-activity user segment forecasts. Deviation in Veterans Health Administration bilateral amputee pilot program expansion pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Female Stress Urinary Incontinence Treatment Devices Market
Medical Devices
Brain-On-Chip Model Market
Medical Devices
Life Science Microscopy Devices Market
Medical Devices
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Electroceutical Devices Market
Medical Devices
Global Otoscopes Market
Medical Devices
Heel and Elbow Suspension Market
Medical Devices
I.V. Fluid Warmer Market
Medical Devices
Cardiac Ablation Devices Market
Medical Devices
Ultrasonic Aspirator Market
Medical Devices
Laser Aesthetic Devices Market
Medical Devices
Defibrillator Pads Market
Medical Devices
Global Stereotactic Surgery Devices Market
Medical Devices
Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Global Total Wrist Replacement Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market