
 Pyonex Needles Market | 2026-2036
Pyonex Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Pyonex Needles Market Outlook
Specialty pain management clinics are redrawing procurement patterns away from general hospital supply chains. Seirin Co., Ltd leverages decades of Japanese manufacturing precision to dominate premium press needle segments. Suzhou Oriental Acupuncture Equipment anchors volume production for cost-sensitive clinical networks across China. Saeshin Precision Co., Ltd specializes in micro-needle geometry for dermatological and subcutaneous applications.
Pyonex needles are semi-permanent press-type acupuncture devices, typically constructed from surgical stainless steel with hypoallergenic adhesive plasters, designed for prolonged superficial tissue stimulation lasting 24 to 72 hours. Standard Needles still occupy the largest volume share due to universal compatibility with traditional acupuncture protocols, though Safety Needles are gaining fastest as clinical liability frameworks tighten. Specialty Needles command the strongest margin pools where practitioners seek differentiated patient outcomes for migraine and musculoskeletal conditions.
Japan's PMDA, China's NMPA, and South Korea's MFDS each enforce distinct biocompatibility and sterility standards that filter market access for imported press needle devices. The EU MDR and REACH compliance requirements add cost layers for Asian manufacturers seeking European distribution channels. Stakeholders must monitor how national reimbursement decisions for acupuncture therapy reshape end-user procurement authority between hospitals and independent clinics.
Market Dynamics
Specialty pain management clinics are consolidating procurement authority away from general hospital supply chains, creating direct manufacturer-to-clinic relationships that bypass traditional medical device distributors and reshape margin allocation across the value chain.
Growth Catalysts
- Japan's Class II medical device framework:PMDA certification requirements for press needle safety create trust premiums that accelerate clinic adoption of certified semi-permanent devices for chronic pain protocols.
- East Asian metropolitan clusters:Deepening integration of traditional medicine into mainstream healthcare in Tokyo, Shanghai, and Seoul generates concentrated demand for superficial tissue stimulation devices.
- Hypoallergenic adhesive plasters:Advances in biocompatible materials extend wear duration from 24 to 72 hours, expanding clinical utility for migraine and musculoskeletal condition management.
Market Restraints
- Surgical stainless steel input volatility:Fluctuations in medical-grade steel pricing compress margins for volume manufacturers serving cost-sensitive clinical networks.
- East Asian supply concentration:Dominance of Japanese and Chinese producers creates geographic vulnerability to regional logistics disruptions and trade policy shifts.
- EU MDR compliance cost layers:Biocompatibility and sterility documentation requirements for European market entry impose fixed cost barriers on mid-scale Asian manufacturers.
Strategic Opportunities
- South Korea's MFDS reimbursement pathways:Evolving national health insurance decisions for acupuncture therapy create procurement authority shifts toward independent specialty clinics.
- Dermatological micro-needle convergence:Integration of press needle geometry with subcutaneous drug delivery opens aesthetic medicine and dermatology applications beyond traditional pain management.
- Direct-to-clinic digital platforms:E-procurement channels disintermediate medical device distributors, enabling manufacturers to capture margin previously allocated to wholesale intermediaries.
Industry Challenges
- Multi-jurisdiction certification timelines:Sequential PMDA, NMPA, and MFDS approval processes delay product launches and strain regulatory affairs staffing.
- Precision manufacturing skill scarcity:Micro-needle geometry production requires specialized tooling expertise that concentrates among aging Japanese technician cohorts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyonex Needles Market |
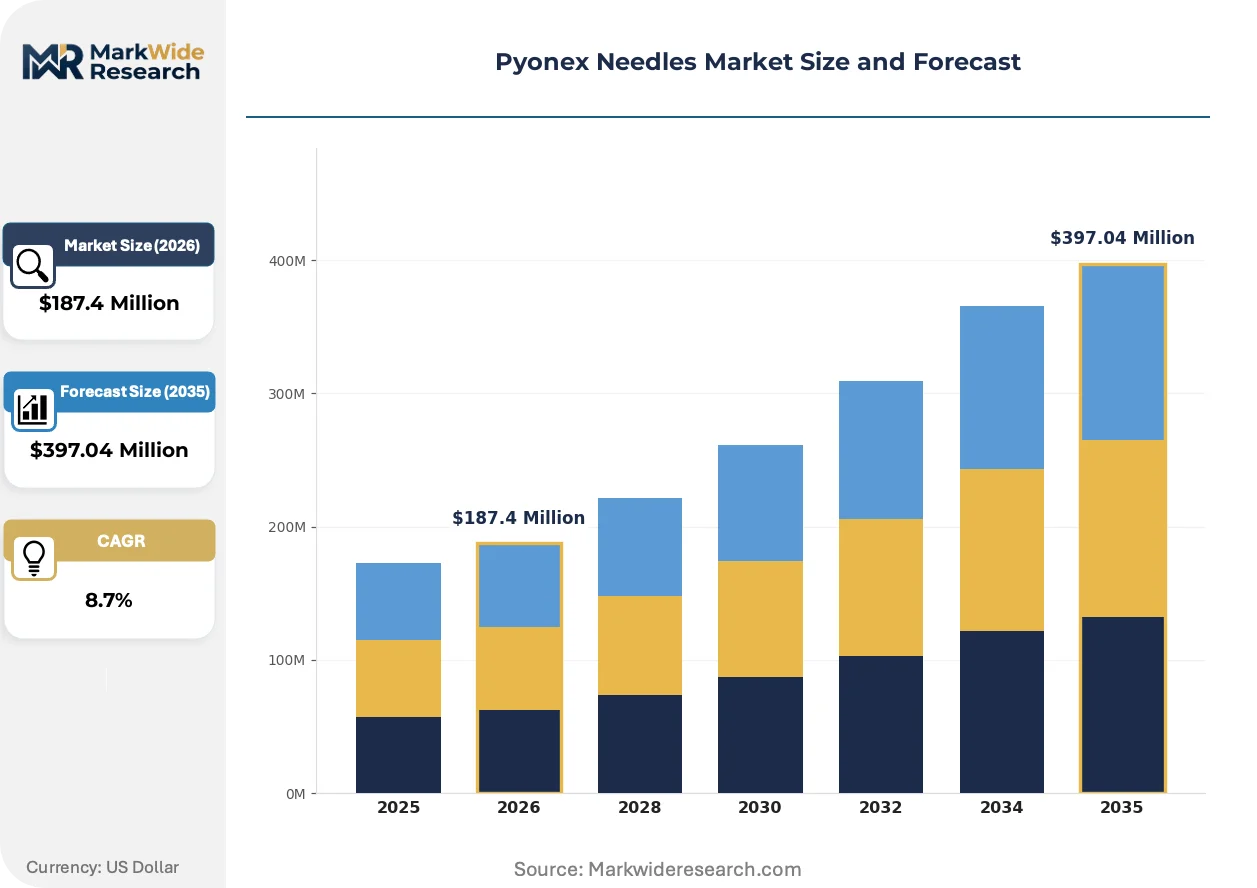
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Needles, Safety Needles, Specialty Needles, Insulin Needles Delivery Mode: Subcutaneous Injection, Intramuscular Injection, Intravenous Injection, Intradermal Injection End User: Hospitals, Clinics, Homecare, Pharmacies Application: Pain Management, Diabetes Management, Vaccination, Biologics Delivery |
| Companies Covered | Seirin Co., Ltd, Suzhou Oriental Acupuncture Equipment, Wujiang Jiachen Acupuncture Devices, Wujiang Yunlong Medical Devices, Inman Medical Electronic Instrument, Saeshin Precision Co., Ltd, Nakanishi Inc, W & H Dentalwerk Burmoos GmbH, Kaltenbach & Voigt GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyonex Needles Market Strategic Shifts
Active reshaping of the Pyonex needles market centers on three intersecting forces: manufacturing precision advancement, regulatory harmonization pressure, and procurement channel restructuring that privileges direct manufacturer relationships.
Micro-needle geometry engineering is fragmenting competitive positioning across the press needle landscape. Manufacturers are deploying laser-guided tip formation to achieve sub-millimeter precision for superficial tissue engagement. Specialty dermatology clinics in Seoul and Tokyo are adopting these devices for aesthetic applications at twice the pace of traditional pain management settings. This technical differentiation is fragmenting the market into precision-premium and standard-volume tiers that operate on distinct margin structures.
REACH compliance requirements for adhesive plaster biocompatibility are forcing reformulation of legacy product lines. ECHA substance restrictions on specific polymer classes compel manufacturers to validate alternative hypoallergenic compounds. European distribution channels are most affected, with Asian producers accelerating in-house toxicology testing to avoid third-party certification delays that previously added six to nine months to market entry timelines.
Clinic procurement departments are consolidating supplier relationships to reduce vendor management overhead. Independent acupuncture networks in Osaka and Shanghai are replacing fragmented multi-source purchasing with single-manufacturer contracts that bundle needle supplies with training and protocol support. This concentration is most visible among specialty pain management chains with ten or more locations, where procurement standardization yields measurable administrative cost reduction.
Pyonex Needles Market Segmentation
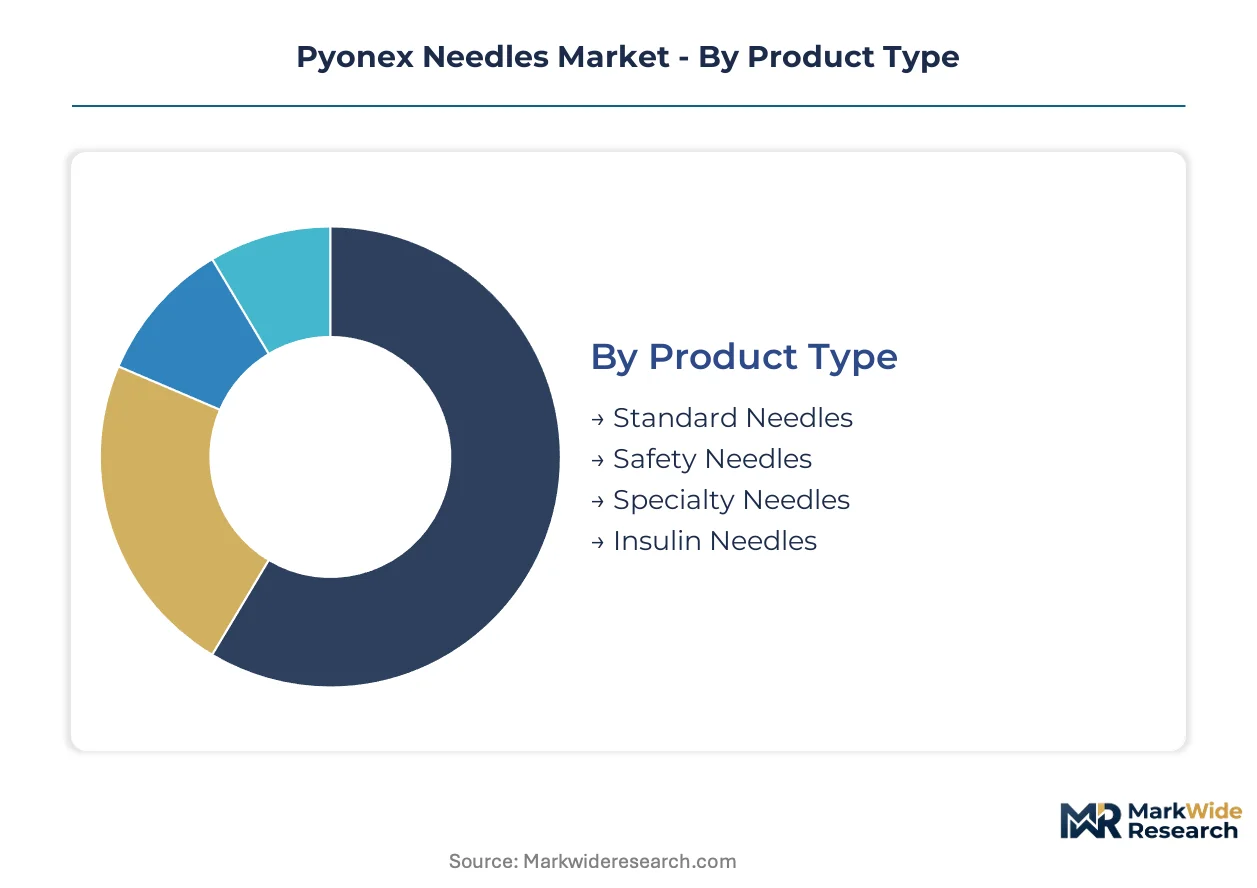
Pyonex needle segmentation reveals distinct margin architectures across product tiers, with certified safety devices commanding premium positioning while standard volumes anchor procurement economics. Delivery mode and end-user channel choices determine regulatory burden and reimbursement pathway access.
Product Type:
Margin pools concentrate in safety-certified and specialty-configured press needle segments where clinical liability frameworks and differentiated outcomes justify pricing elevation above commodity tiers.
- Standard Needles:Universal compatibility with traditional acupuncture protocols drives procurement volume across cost-sensitive clinical networks. Demand concentrates in China's provincial hospital systems where bulk purchasing agreements prioritize unit economics over feature differentiation.
- Safety Needles:Engineered with retractable or shielded mechanisms to prevent needlestick injuries, these devices meet tightening occupational safety mandates. Procurement is accelerating fastest in Japan's specialty pain management clinics where PMDA Class II certification creates trust premiums for chronic pain protocols.
- Specialty Needles:Micro-needle geometries optimized for migraine and musculoskeletal applications command strongest margin pools where practitioners seek differentiated patient outcomes.
- Insulin Needles:Short-length configurations for subcutaneous drug delivery serve diabetes management protocols in homecare and clinic settings.
Standard Needles hold installed capacity. Safety Needles is rotating up the share rankings.
Delivery Mode:
Application depth determines sterilization grade requirements and practitioner certification levels, with superficial tissue engagement carrying lighter regulatory overhead than vascular access routes.
- Subcutaneous Injection:Press needles achieve 24-72 hour superficial tissue stimulation through hypoallergenic adhesive plasters, dominating Pyonex clinical applications. Deployment concentrates in Tokyo and Seoul metropolitan clusters where traditional medicine integration into mainstream healthcare deepens.
- Intramuscular Injection:Deeper tissue penetration requires longer needle geometries and advanced practitioner certification, limiting adoption to hospital-based pain management departments.
- Intravenous Injection:Vascular access applications demand highest sterility assurance and are rarely served by semi-permanent press needle formats.
- Intradermal Injection:Shallow dermal layer targeting supports vaccination and allergy testing protocols, with micro-needle convergence opening aesthetic medicine applications.
Subcutaneous Injection anchors procedure volume. Intradermal Injection is climbing the fastest as dermatological applications expand.
End User:
Procurement authority is fragmenting across channel types, with independent specialty clinics gaining direct manufacturer relationships that bypass traditional medical device distributors.
- Hospitals:Centralized purchasing departments enforce multi-source supplier policies and volume discount frameworks that compress margins for manufacturers.
- Clinics:Specialty pain management chains with ten or more locations are consolidating to single-manufacturer contracts bundling supplies with training support, most visible in Osaka and Shanghai independent acupuncture networks.
- Homecare:Patient-directed procurement through digital platforms is emerging for chronic condition self-management, though reimbursement coverage remains inconsistent.
- Pharmacies:Retail distribution channels serve over-the-counter demand for standardized press needle configurations with lighter regulatory documentation.
Hospitals hold legacy procurement volume. Clinics is gaining share fastest as direct-to-clinic digital platforms disintermediate wholesale intermediaries.
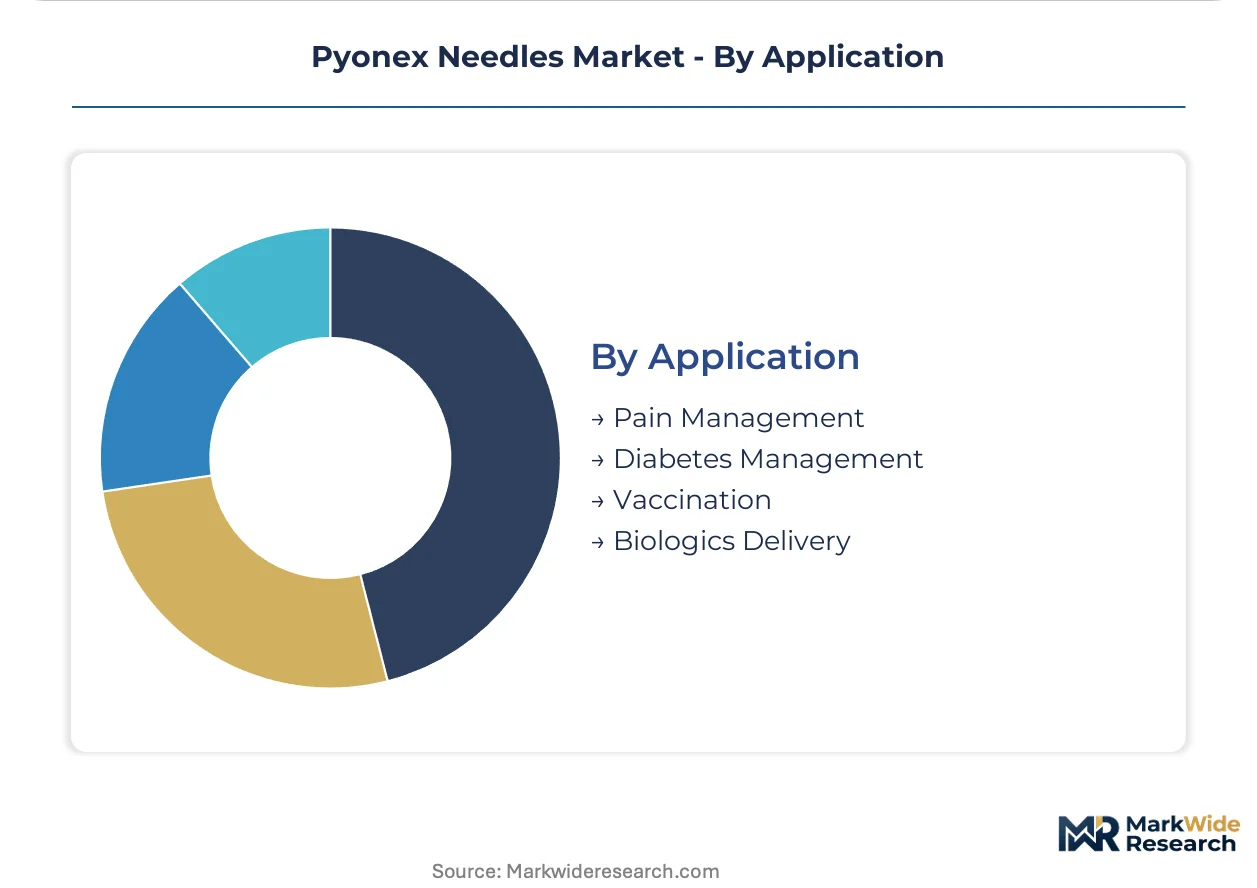
Application:
Reimbursement eligibility and protocol standardization determine addressable market breadth, with pain management enjoying broadest insurance coverage while biologics delivery requires specialized handling infrastructure.
- Pain Management:Chronic musculoskeletal and migraine protocols represent the core clinical utility for semi-permanent press needles, with South Korea's MFDS reimbursement pathways reshaping procurement authority toward independent specialty clinics.
- Diabetes Management:Insulin delivery applications leverage press needle geometry for patient self-administration, though continuous glucose monitor integration is displacing some traditional injection volumes.
- Vaccination:Intradermal micro-needle formats enable antigen delivery with reduced antigen dose requirements, attracting public health procurement interest.
- Biologics Delivery:Temperature-sensitive protein therapeutics require cold chain integrity that semi-permanent adhesive formats rarely satisfy, limiting penetration to research settings.
Pain Management holds established reimbursement codes. Vaccination is ascending the share rankings as intradermal delivery protocols advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese manufacturers export press needle devices to specialty pain clinics across South Korea and China, establishing the East Asian corridor as the dominant trade flow for semi-permanent acupuncture equipment.
Japan
Tokyo and Osaka metropolitan clusters concentrate procurement of PMDA Class II certified press needles for chronic pain protocols. The Ministry of Health, Labour and Welfare enforces strict biocompatibility standards that filter market access for imported devices. Seirin Co., Ltd anchors premium manufacturing in Kansai region, supplying certified devices to hospital-based pain management departments.
China
Suzhou and Wujiang industrial zones drive volume production for cost-sensitive clinical networks across provincial hospital systems. NMPA registration requirements for medical device sterility documentation shape import substitution dynamics. Yangtze River Delta manufacturing clusters serve both domestic demand and export orders to Southeast Asian traditional medicine markets.
South Korea
Seoul Capital Area specialty clinics are consolidating procurement authority away from general hospital supply chains. MFDS reimbursement pathway decisions for acupuncture therapy reshape end-user purchasing power toward independent pain management chains. Busan-Ulsan corridor distributors are developing direct manufacturer relationships that bypass traditional medical device intermediaries.
Germany
EU MDR compliance requirements for biocompatibility and sterility documentation add cost layers for Asian manufacturers seeking European distribution. REACH adhesive plaster reformulation mandates compel toxicology testing investments. Bavaria-based dental and medical device distributors serve as entry gateways for press needle imports into continental European markets.
United States
FDA Class II medical device clearance requirements for semi-permanent press needles create regulatory barriers for uncertified Asian imports. Specialty acupuncture networks in California and New York Metro are developing patient-directed procurement channels for chronic condition self-management. Pacific West Coast metropolitan clusters show strongest demand concentration where traditional medicine integration into integrative health systems deepens.
Pyonex Needles Market Competitive Environment
Listed leaders compete with private specialists across certification tiers, with publicly traded precision manufacturers facing off against family-owned traditional medicine equipment fabricators. Market structure fragments across three capability layers: premium-certified Japanese producers, volume-scale Chinese fabricators, and micro-geometry Korean specialists. Dominant competitive moves include direct-to-clinic digital platform development and REACH-compliant adhesive plaster reformulation.
Within the precision-manufacturing tier, Seirin Co., Ltd and Saeshin Precision Co., Ltd exemplify Japanese and Korean specialist positioning respectively. Suzhou Oriental Acupuncture Equipment anchors the volume-driven segment for cost-sensitive clinical networks. These three entities represent distinct geographic and capability archetypes that structure competitive dynamics across East Asian supply concentration.
| Leading Market Players |
|---|
| Seirin Co., Ltd |
| Suzhou Oriental Acupuncture Equipment |
| Wujiang Jiachen Acupuncture Devices |
| Wujiang Yunlong Medical Devices |
| Inman Medical Electronic Instrument |
| Saeshin Precision Co., Ltd |
| Nakanishi Inc |
| W & H Dentalwerk Burmoos GmbH |
| Kaltenbach & Voigt GmbH |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Japanese precision manufacturers and Seoul-based specialty clinic chains lock in both surgical stainless steel supply access and price visibility for PMDA-certified press needle devices. These contracts insulate premium-tier producers from spot-market volatility in medical-grade steel while compressing margins for volume players serving China's provincial hospital networks.
Pricing Analysis
Next-generation micro-needle geometries command substantial premiums over standard press needle configurations, with laser-guided tip formation technology widening the price gap against prior-generation stamped products. Three-tier pricing structure across premium, standard, and economy levels separates PMDA-certified safety devices from NMPA-registered volume products and unbranded commodity alternatives. Price differentiation hinges on certification grade and after-sales training bundling. Cost compression in the standard tier is intensifying because Suzhou-based fabricators are absorbing steel input volatility to maintain hospital contract renewals. China's provincial procurement departments exhibit highest price sensitivity; Japan's specialty pain management chains show least sensitivity due to reimbursement coverage and liability risk aversion.
Supply Chain Analysis
Inventory buffers for hypoallergenic adhesive plasters have extended from six to eight weeks as REACH-compliant polymer reformulation strains European-bound production lines. Manufacturing concentrates in Japan, China, and South Korea, with Kansai region workshops feeding premium device assembly and Yangtze River Delta plants anchoring volume output. Raw material dependencies draw from surgical stainless steel mills in Jiangsu province, medical-grade adhesive suppliers in Osaka industrial corridors, and sterilization packaging producers in Gyeonggi-do. Single-source vulnerability concentrates in precision grinding equipment sourced from aging Japanese technician cohorts. Distribution runs through medical device distributors in Germany and direct-to-clinic digital platforms in East Asian metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized micro-needle geometry expertise has become the constraining asset in this market, with laser-guided tip formation knowledge concentrated among retiring Japanese technician cohorts and limited pipeline replenishment. This capability scarcity shapes competitive durability across certification tiers.
For Market Incumbents: Fortify upstream control over precision grinding equipment supply by securing exclusive maintenance contracts with Osaka-based tooling specialists or acquiring captive capacity in Kansai region workshops. Deepen PMDA certification moats through accelerated next-generation safety device submissions before MFDS harmonization pressures converge Japanese and Korean standards. Emerging Chinese volume players threaten margin pools in standard needle segments; defend through bundling training protocols with device supply to specialty clinic chains. For New Entrants and Emerging Players: Lead with dermatological micro-needle applications in Seoul Capital Area aesthetic medicine clinics, where practitioner familiarity with press needle geometry overlaps with unmet demand for subcutaneous drug delivery devices. South Korea's evolving MFDS reimbursement pathways for acupuncture therapy represent the most penetrable regulatory entry point, with independent pain management chains consolidating procurement authority away from hospital distributors. Establish direct manufacturer relationships through e-procurement platform partnerships rather than traditional medical device wholesale channels. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale Korean manufacturers possessing micro-needle geometry R&D capabilities but lacking PMDA certification infrastructure, where acquisition fills capability gaps and accelerates multi-jurisdiction approval timelines. Long-term viability in this market rests on regulatory affairs staffing depth and precision manufacturing skill retention across generational transitions. Watch for MFDS reimbursement decisions expanding acupuncture therapy coverage as the inflection signal reshaping procurement authority toward independent clinic networks.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Class II Certification Investment | Unlocks premium pricing in Tokyo and Osaka metropolitan pain management clinics. |
| REACH-Compliant Adhesive Reformulation | Enables European distribution through ECHA-validated biocompatible polymer alternatives. |
| Direct-to-Clinic Digital Platform Launch | Disintermediates wholesale distributors and captures margin previously allocated to intermediaries. |
| Micro-Needle Geometry R&D Expansion | Opens aesthetic medicine applications in Seoul dermatology clinics beyond traditional pain protocols. |
| Precision Grinding Equipment Acquisition | Secures scarce tooling expertise concentrated among aging Japanese technician cohorts. |
Study Parameters
A standing panel of specialty pain management clinicians, hospital purchasing committee members, biomedical engineers at acupuncture device manufacturers, and GPO contracts managers provided ongoing calibration against secondary validation from PMDA device registration databases, NMPA sterility documentation filings, MFDS reimbursement bulletins, and East Asian medical device trade flow records. Primary fieldwork combined structured interviews with procurement directors at Osaka and Shanghai clinic chains alongside technical discussions with Kansai region precision manufacturing engineers. Bottom-up demand modeling from end-user procedure volumes triangulated against top-down supply capacity assessments across Japanese and Chinese production clusters.
Consistency checks validated volume and value outputs against external benchmarks including medical device export statistics from Japan's Ministry of Health, Labour and Welfare and Chinese provincial manufacturing surveys from Jiangsu and Zhejiang industrial zones. The analytical framework segmented demand across product type, delivery mode, end user, and application dimensions throughout the projection horizon. CAGRs were derived from fitted growth curves calibrated to reimbursement policy trajectories and traditional medicine integration indices across East Asian metropolitan clusters. Industry-specific forecast inputs included PMDA certification pipeline timelines and REACH adhesive plaster reformulation completion rates.
The analysis sits within stated boundaries; outcomes outside sustained East Asian regulatory harmonization or abrupt surgical stainless steel supply disruptions would require recalibration. Forecasts reflect documented assumptions regarding reimbursement expansion trajectories and precision manufacturing skill retention. Specific risk factors that could revise projections include MFDS acupuncture coverage reversals, ECHA polymer restriction amendments, or generational transition failures in Japanese micro-needle geometry expertise. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Italy Hospital Supplies Market
Medical Supplies
Specimen Transport Bags Market
Medical Supplies
Sterile Container Market
Medical Supplies
Powder-Free Disposable Medical Gloves Market
Medical Supplies
Global Povidone Iodine Market
Medical Supplies
Hospital Consumables Market
Medical Supplies
Surgical Gloves Market
Medical Supplies
Chemo Graded Nitrile Powder-Free Medical Examination Gloves Market
Medical Supplies
Nursing Breast Pads Market
Medical Supplies
Global Enema Based Products Market
Medical Supplies
Surgical Dressings and Disposables Market
Medical Supplies
Pressure Redistribution Pads Market
Medical Supplies
Trauma Products Market
Medical Supplies
Cryogenic Vials Market
Medical Supplies
Saudi Arabia Hospital Supplies Market
Medical Supplies
Anaesthesia Conduction Kits Market