
 Canada Ultrasound Devices Market | 2026-2036
Canada Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Ultrasound Devices Market Outlook
Semiconductor miniaturization is decoupling ultrasound hardware from fixed-room installations, collapsing per-unit costs while preserving image fidelity. GE HealthCare Technologies Inc leverages its deep installed base in Canadian hospital networks to sustain service revenue streams. Koninklijke Philips N.V. competes through integrated informatics platforms that anchor diagnostic workflows. Siemens Healthineers differentiates via advanced transducer architectures that dominate premium cardiology segments.
Canada ultrasound devices encompass electronic systems that generate acoustic waves between two and eighteen megahertz for non-invasive tissue imaging and therapeutic intervention, with beamforming algorithms and piezoelectric crystal arrays determining spatial resolution. These systems serve obstetric monitoring, cardiac structural assessment, and guided minimally invasive procedures across clinical settings. Diagnostic ultrasound retains the largest revenue footprint among product categories, while portable ultrasound registers the fastest structural expansion as ambulatory and rural deployment accelerates. Emergency medicine applications command premium positioning due to time-critical decision requirements, whereas obstetrics maintains volume leadership through routine screening protocols.
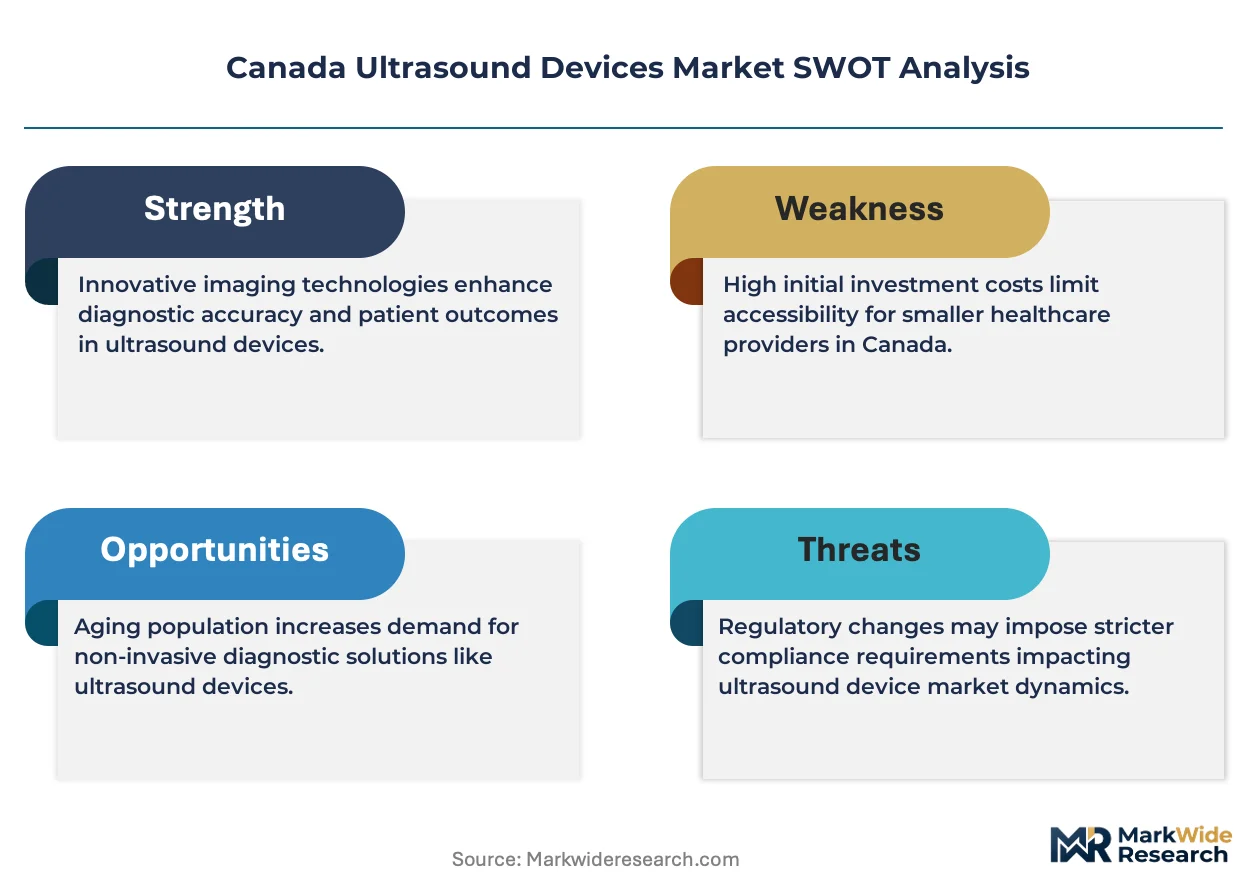
Health Canada's Medical Devices Directorate classifies ultrasound systems by risk tier, shaping premarket submission requirements and post-market surveillance obligations for manufacturers. CSA Group standards alignment with IEC 60601-2-37 governs electrical safety and acoustic output limits, directly influencing product design cycles for devices entering the Canadian market. Provincial health technology assessment bodies, including Ontario Health and INESSS in Quebec, determine reimbursement and procurement eligibility, filtering which innovations achieve scaled adoption. Stakeholders must monitor evolving point-of-care billing codes and provincial capital equipment prioritization frameworks to anticipate demand inflections.
Market Dynamics
Point-of-care ultrasound deployment is collapsing the traditional radiology workflow model across Canadian emergency departments, forcing equipment vendors to reconfigure service architectures around bedside mobility rather than centralized imaging suites.
Growth Catalysts
- CSA Group IEC 60601-2-37 alignment:Electrical safety standard harmonization is compressing regulatory approval timelines for manufacturers entering the Canadian market, accelerating product availability.
- Emergency medicine point-of-care protocols:Ontario and Quebec hospital networks are embedding portable ultrasound into triage workflows, creating institutional demand pull for compact systems.
- Piezoelectric crystal array advances:Transducer miniaturization is preserving image fidelity at reduced hardware footprints, enabling ambulatory deployment models previously restricted to fixed installations.
Market Restraints
- PMRA medical device licensing fees:Health Canada's escalating premarket submission costs are elevating capital barriers for mid-tier manufacturers seeking Canadian market entry.
- Transducer supply concentration:Specialty piezoelectric material sourcing clusters in East Asian manufacturing corridors expose Canadian distributors to input volatility and extended lead times.
- Specialized sonographer workforce scarcity:Provincial training program capacity constraints in Ontario and British Columbia are throttling deployment velocity for advanced cardiac and vascular applications.
Strategic Opportunities
- Northern and rural Quebec:Underserved remote communities present deployment white space for telemedicine-integrated portable ultrasound networks supported by provincial rural health initiatives.
- Guided minimally invasive procedures:Interventional cardiology and pain management clinics are expanding real-time ultrasound guidance adoption beyond traditional diagnostic boundaries.
- Provincial capital equipment prioritization frameworks:Ontario Health's technology assessment pathways are creating procurement fast-tracks for devices demonstrating emergency department throughput improvements.
Industry Challenges
- Legacy PACS integration complexity:Hospital networks running decade-old picture archiving systems face costly middleware development to accommodate AI-enhanced ultrasound data streams.
- Health Canada post-market surveillance compliance:Manufacturers must maintain adverse event reporting infrastructure that satisfies Medical Devices Directorate vigilance requirements across distributed point-of-care installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Ultrasound Devices Market |
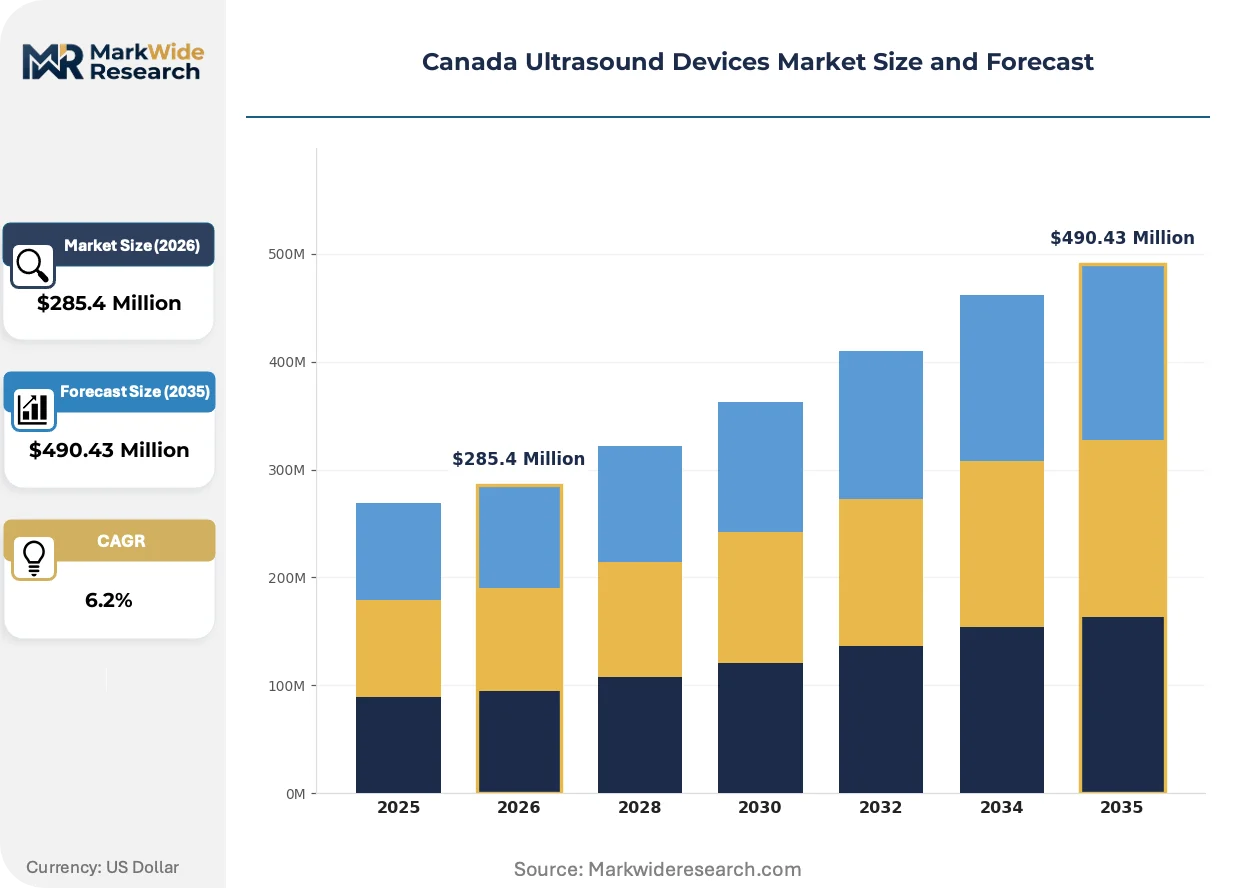
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $490.43 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Ultrasound, Therapeutic Ultrasound, Portable Ultrasound, 3D Ultrasound Application: Obstetrics, Cardiology, Urology, Emergency Medicine Technology: Digital Ultrasound, Analog Ultrasound, 2D Imaging, 4D Imaging End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions |
| Companies Covered | GE HealthCare Technologies Inc, Koninklijke Philips N.V., Siemens Healthineers, Canon Medical Systems Corporation, FUJIFILM Holdings Corporation, Hologic Inc., Mindray Medical International Limited, Samsung Medison, Esaote SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Ultrasound Devices Market Strategic Shifts
Artificial intelligence inference engines are embedding directly into ultrasound hardware, shifting diagnostic burden from operator skill toward algorithmic pattern recognition while compressing examination duration in high-throughput clinical environments.
Beamforming algorithm architectures are converging with edge computing processors to enable real-time image enhancement without tethered workstation dependency. Emergency medicine departments in Toronto and Montreal are piloting these systems for trauma triage acceleration. The structural consequence is collapsing per-examination time requirements while expanding diagnostic confidence among non-specialist operators.
Health Canada's Medical Devices Directorate is tightening software-as-a-medical-device classification guidance for AI-enabled ultrasound analytics, requiring manufacturers to submit algorithm validation datasets alongside hardware licensing applications. Cardiology imaging platforms face the steepest compliance burden due to diagnostic decision-support claims. Vendors are responding by segregating Canadian product SKUs to isolate regulatory risk from broader North American portfolios.
After-sales service unbundling is disrupting traditional equipment procurement in tertiary hospital networks. British Columbia and Alberta health authorities are negotiating hardware-only purchases with third-party maintenance contracts, compressing OEM service margins. This pattern is most visible in high-volume obstetrics departments where device utilization rates justify independent technical staffing.
Canada Ultrasound Devices Market Segmentation
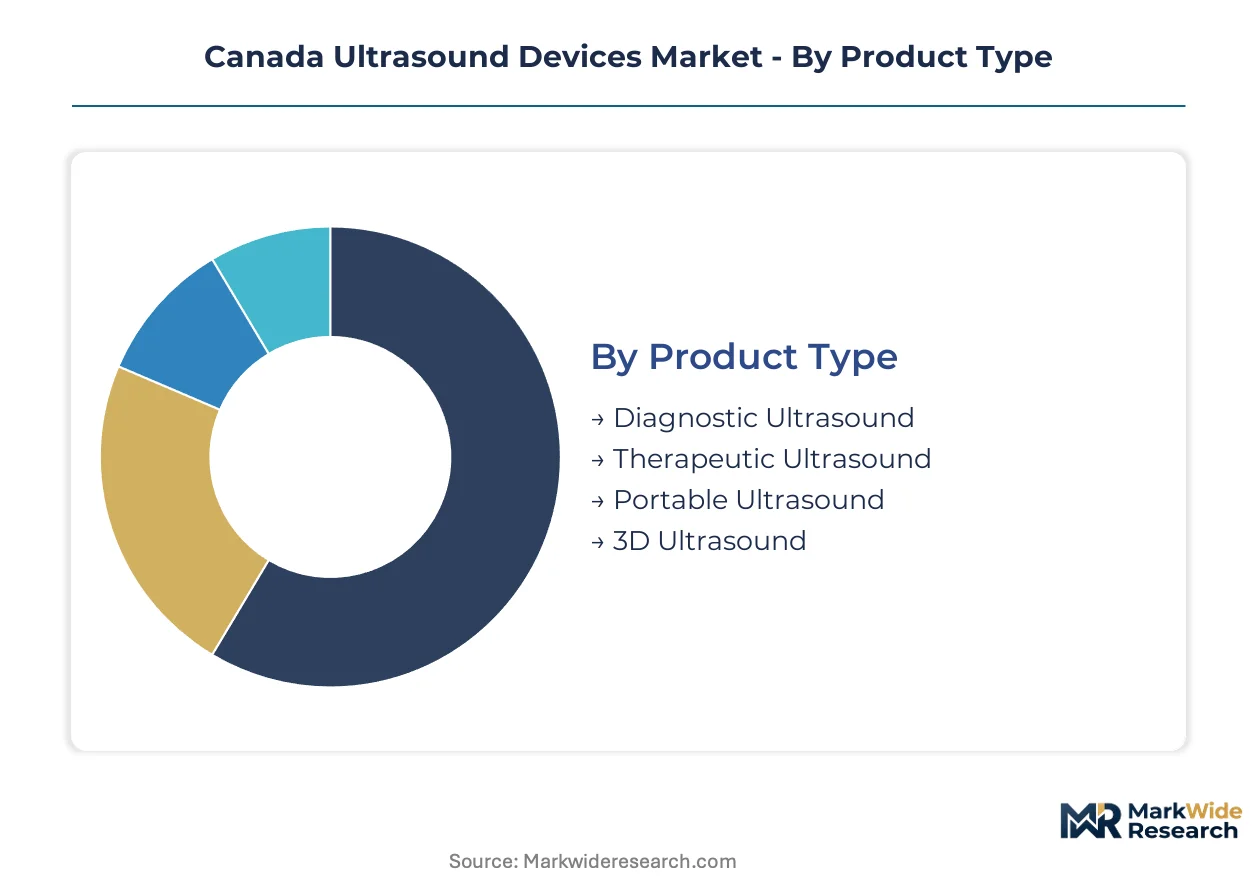
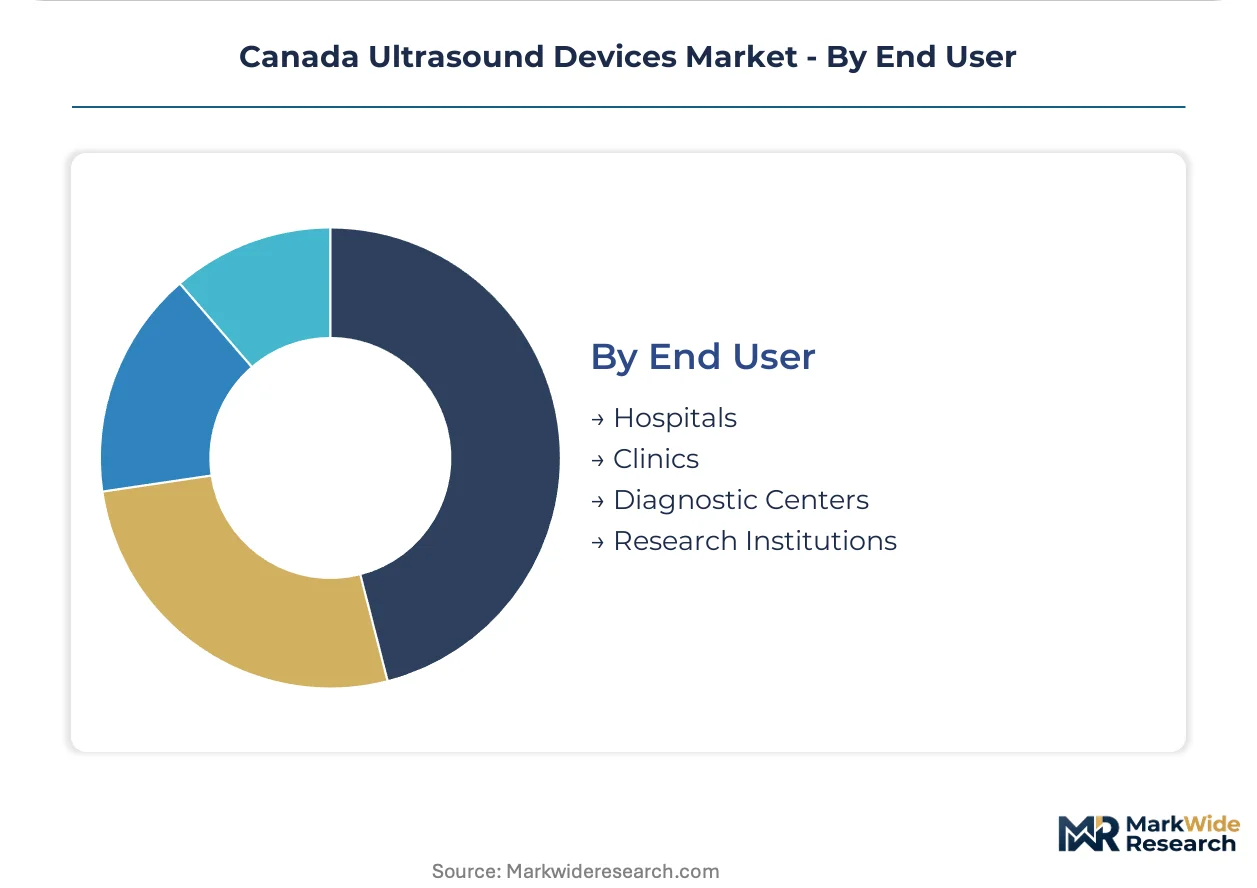
Ultrasound device segmentation in Canada reflects divergent procurement logics across clinical settings. Provincial health authorities prioritize capital efficiency in hospital networks while private operators emphasize throughput velocity in ambulatory environments.
Product Type:
Cost tier separates institutional buyers from mobile deployment specialists across Canadian healthcare infrastructure.
- Diagnostic Ultrasound:Fixed-installation systems with cart-based transducer arrays dominate tertiary hospital imaging suites in Ontario and Quebec. Tertiary networks in Toronto and Montreal anchor procurement volume through centralized radiology department budgets.
- Portable Ultrasound:Battery-powered units with wireless data transmission enable point-of-care deployment in rural emergency departments and northern nursing stations. Northern Quebec telemedicine initiatives and Ontario Health's rural access programs accelerate demand for compact systems.
- Therapeutic Ultrasound:Focused acoustic delivery systems for tissue ablation and physiotherapy applications concentrate in specialized pain management and rehabilitation clinics.
- 3D Ultrasound:Volume-rendering hardware with motorized transducer sweeps serves fetal anomaly screening protocols in high-risk obstetrics centers.
Volume sits with diagnostic installations; growth tilts toward portable configurations.
Application:
Reimbursement velocity determines adoption speed across provincial billing code frameworks.
- Obstetrics:Routine fetal biometry and anomaly screening protocols generate the highest examination frequency across Canadian prenatal care networks. Provincial maternal health programs in Ontario, Quebec, and British Columbia sustain volume through standardized trimester screening schedules.
- Emergency Medicine:Trauma triage and procedural guidance applications command premium pricing due to time-critical decision requirements. Toronto and Montreal emergency departments embed bedside ultrasound into sepsis and trauma protocols.
- Cardiology:Echocardiography and vascular assessment systems concentrate in specialized cardiac centers with certified sonographer staffing.
- Urology:Prostate imaging and renal assessment applications serve urology clinics and hospital departments with focused diagnostic workflows.
Obstetrics captures examination volume; emergency medicine claims the steepest expansion trajectory.
Technology:
Image processing architecture separates legacy replacement demand from greenfield digital deployment.
- Digital Ultrasound:Software-defined beamforming with FPGA-based processing enables real-time image optimization and AI integration. Hospital networks in Ontario and Alberta prioritize digital platforms for PACS compatibility and algorithmic enhancement pathways.
- 4D Imaging:Real-time volumetric rendering with temporal resolution supports fetal cardiac assessment and interventional guidance. Maternal-fetal medicine units in Vancouver and Calgary drive adoption for complex anomaly detection protocols.
- 2D Imaging:Conventional planar ultrasound remains prevalent in cost-constrained community clinics and rural health posts.
- Analog Ultrasound:Legacy hardware persists in limited physiotherapy and basic screening applications approaching replacement cycles.
Digital platforms dominate capital allocation; 4D capability gains share fastest in specialized centers.
End User:
Procurement scale and decision authority fragment across public health system hierarchies.
- Hospitals:Multi-departmental imaging departments with centralized capital budgets negotiate enterprise agreements for high-end cart-based systems. Ontario Health's technology assessment pathways and Quebec's INESSS evaluation frameworks filter which innovations achieve scaled hospital deployment.
- Clinics:Independent and group practice settings prioritize compact systems with rapid examination turnaround for fee-for-service billing models.
- Diagnostic Centers:Specialized imaging facilities concentrate high-throughput obstetrics and cardiac screening operations in urban corridors.
- Research Institutions:University-affiliated hospitals and medical schools acquire experimental platforms for algorithm validation and transducer development.
Hospitals anchor equipment volume; clinics expand most quickly through point-of-care decentralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's Health Innovation Excellence Program and Quebec's life sciences tax credits concentrate ultrasound device procurement authority in provincial health networks across Canada's most populous corridors.
Ontario
Toronto's hospital networks anchor diagnostic ultrasound volume through Ontario Health's centralized technology assessment pathways. The provincial government prioritizes emergency department throughput improvements in capital equipment frameworks. Research institutions in Hamilton and Ottawa validate AI-enhanced imaging algorithms for Health Canada submissions.
Quebec
Montreal's tertiary hospitals embed point-of-care ultrasound into sepsis and trauma triage protocols. INESSS evaluation frameworks filter reimbursement eligibility for innovations entering provincial procurement. Northern Quebec telemedicine initiatives deploy portable systems to remote nursing stations.
British Columbia
Vancouver's maternal-fetal medicine units drive 4D imaging adoption for complex anomaly detection. Provincial health authorities negotiate hardware-only purchases with third-party maintenance contracts. Victoria and Kelowna clinics expand ambulatory ultrasound capacity through fee-for-service models.
Alberta
Calgary's cardiac centers concentrate echocardiography systems with certified sonographer staffing. Alberta Health Services prioritizes digital platform compatibility with legacy PACS infrastructure. Edmonton research hospitals pilot edge-computing beamforming for emergency department deployment.
Atlantic Canada
Halifax and St. John's health networks address sonographer workforce scarcity through interprovincial training partnerships. Federal rural health initiatives subsidize portable ultrasound for maritime community hospitals. Diagnostic imaging backlogs in New Brunswick accelerate teleradiology-integrated mobile system procurement.
Canada Ultrasound Devices Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consolidated procurement power in provincial health networks favoring established OEMs with service infrastructure. The vendor base organizes around three archetypes: diversified health technology conglomerates with deep installed bases, specialized imaging firms with transducer engineering expertise, and emerging portable system specialists with software-defined architectures. Competitive moves center on after-sales service unbundling negotiations and AI algorithm validation partnerships for Health Canada licensing.
Among diversified health technology conglomerates, GE HealthCare Technologies Inc and Koninklijke Philips N.V. occupy positions shaped by enterprise service agreements and integrated informatics platforms. Siemens Healthineers exemplifies the specialized imaging archetype through advanced transducer architectures. These three anchors represent distinct competitive vectors: installed base leverage, workflow integration, and premium segment engineering differentiation.
| Leading Market Players |
|---|
| GE HealthCare Technologies Inc |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| FUJIFILM Holdings Corporation |
| Hologic Inc. |
| Mindray Medical International Limited |
| Samsung Medison |
| Esaote SpA |
| Others |
Value Chain & Pricing Dynamics
Provincial health authorities in Ontario and Quebec are consolidating procurement through enterprise agreements that demand hardware-only purchases with third-party maintenance, forcing manufacturers to unbundle service revenue and compress margin structures across premium system tiers.
Pricing Analysis
Lead-time premiums now separate spot-market transactions from contracted supply schedules, with emergency procurement for trauma-capable systems commanding substantial uplifts over standard delivery windows. Three-tier pricing structure across premium, standard, and economy levels reflects transducer array sophistication and AI integration depth. Price differentiation hinges on Health Canada licensing tier and after-sales service bundling status. Mid-tier manufacturers face intensifying cost compression as provincial capital frameworks prioritize throughput-proven platforms.
Supply Chain Analysis
Reverse-logistics networks for transducer refurbishment and certified pre-owned system redeployment are extending hardware lifecycles while cannibalizing new-unit sales in budget-constrained community clinics. Manufacturing concentrates in China, South Korea, and Germany for piezoelectric crystal arrays, FPGA processors, and precision acoustic components. Specialty ceramic substrate sourcing from East Asian corridors creates single-source vulnerability for high-frequency transducer production. Distribution runs through authorized medical device distributors with Health Canada establishment licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from Health Canada's escalating premarket submission costs will eliminate mid-tier competitors lacking service infrastructure scale, concentrating share among diversified OEMs with compliance war chests.
For Market Incumbents: Deploy AI algorithm validation partnerships to secure Health Canada software-as-a-medical-device licensing ahead of tightened guidance. Acquire portable ultrasound specialists with edge-computing architectures to neutralize emerging software-defined competitors. Lock in Ontario Health and INESSS evaluation pathway relationships before provincial assessment frameworks harden. For New Entrants and Emerging Players: Third-party maintenance contractors present the fastest channel to hospital network access without fronting OEM-scale service infrastructure. Northern Quebec telemedicine initiatives and Atlantic Canada rural nursing stations offer procurement white space with reduced incumbent saturation. Pursue hardware-only positioning with independent technical staffing to exploit after-sales unbundling momentum. For Investors and Strategic Acquirers: The window for entry favors specialized portable system developers with validated Health Canada submissions and established provincial pilot contracts. Long-term viability rests on regulatory compliance infrastructure rather than hardware differentiation alone. Monitor Ontario Health technology assessment pathway outcomes for emergency department throughput claims as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Licensing Pathway | Premarket submission alignment with Medical Devices Directorate software guidance accelerates provincial procurement eligibility. |
| Hospital System Partnership | Ontario Health enterprise agreements anchor volume through centralized technology assessment and capital prioritization frameworks. |
| Software Companion Development | AI-enhanced analytics modules embedded at edge-computing layer differentiate portable platforms in emergency medicine workflows. |
| Reimbursement Strategy | Provincial billing code alignment for point-of-care ultrasound protocols unlocks fee-for-service revenue in ambulatory settings. |
| CE Marking Pathway | CSA Group IEC 60601-2-37 harmonization streamlines electrical safety validation for Canadian market entry. |
Study Parameters
Multi-period observation of provincial procurement volumes, Health Canada licensing timelines, and transducer supply lead times anchored the trend analysis, supplemented by interviews with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and point-of-care ultrasound clinicians. Secondary validation drew from Health Canada Medical Devices Active Licence Listing, Ontario Health technology assessment publications, INESSS evaluation reports, and CSA Group standards documentation. Bottom-up equipment shipment tracking triangulated against top-down provincial capital budget allocations.
Input-output matrices mapped transducer array configurations, processing architectures, and software capabilities across application segments and end-user settings throughout the forecast period. CAGRs derived from regression analysis against historical procurement cycles and projected replacement demand. Industry-specific inputs included sonographer workforce expansion rates in Ontario and British Columbia, and provincial rural health initiative funding trajectories.
Caveats apply where Health Canada software-as-a-medical-device reclassification or transducer material export restrictions from East Asian manufacturing corridors could materially shift the outlook. Practitioners should monitor provincial point-of-care billing code expansions and CSA Group standards revision schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Portable Medical and Healthcare Devices Market
Medical Devices
Ultrasonic Dissection Devices Market
Medical Devices
At-Home Vaginal Ph Test Kit Market
Medical Devices
Snoring Control Devices Market
Medical Devices
Australia Spinal Surgery Devices Market
Medical Devices
Global Disposable Medical Sensors Market
Medical Devices
Global Lenses for Myopia Control Market
Medical Devices
Medical Coatings for Implants Market
Medical Devices
Varicose Vein Treatment Devices Market
Medical Devices
Global Hemorrhoid Treatment Devices Market
Medical Devices
Lactate Meter Market
Medical Devices
Brain-On-Chip Model Market
Medical Devices
Tubeless Insulin Pump Market
Medical Devices
Small Bowel Enteroscopes Market
Medical Devices
Injection Practice Pad Market
Medical Devices
Cranial Stabilization Devices Market