
 Global Surgical Robotics Market | 2026-2036
Global Surgical Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Robotics Market Outlook
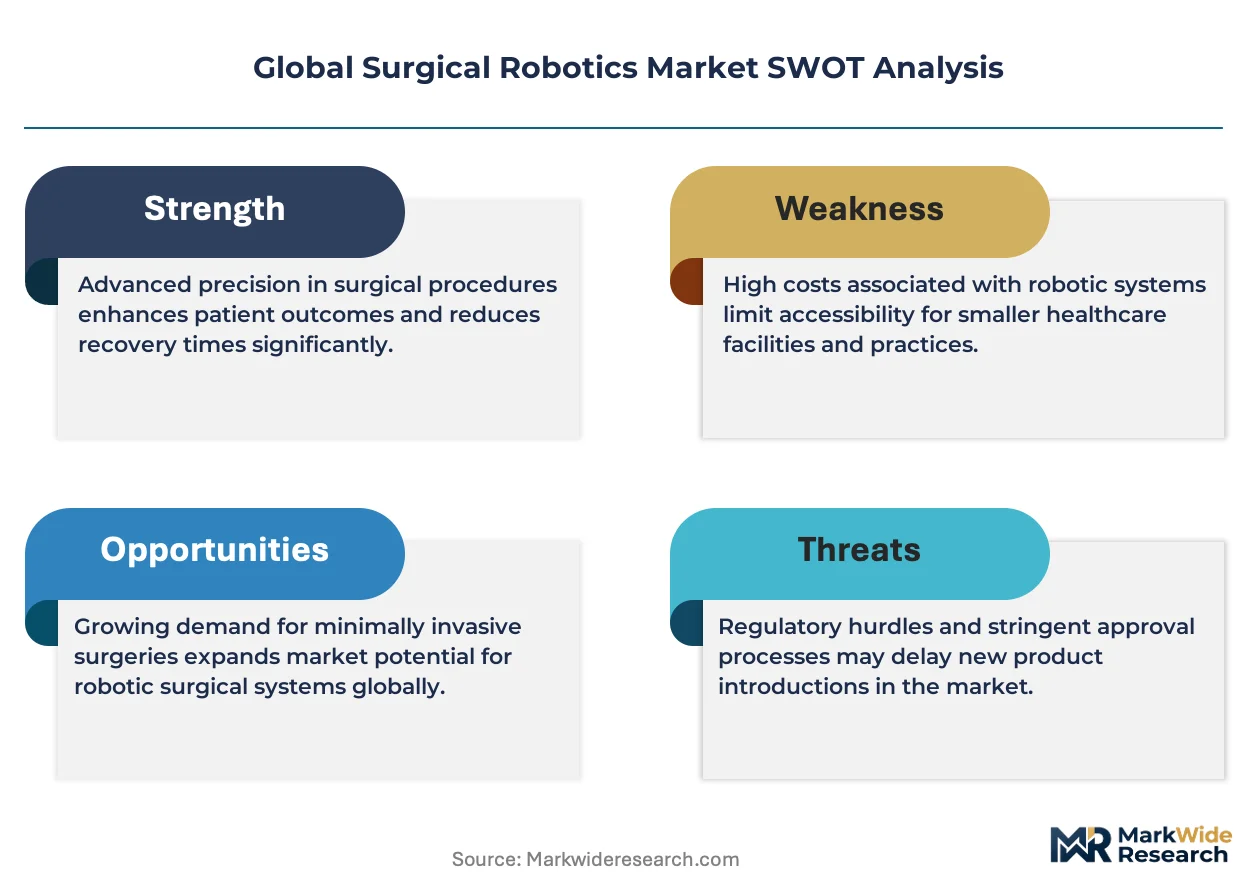
The gap between premium integrated platforms and modular commodity systems is realigning procurement patterns across health systems. Intuitive Surgical dominates the premium tier through captive supply of instruments and software ecosystems. Stryker Corporation competes in orthopedic robotics with specialized milling and navigation platforms. Medtronic anchors the mid-market with flexible capital arrangements that lower hospital entry barriers.
Surgical robotics encompasses electromechanical systems that translate surgeon hand movements into precise instrument articulation, typically operating at sub-millimeter accuracy with force feedback thresholds below 0.5 Newtons, designed to enable minimally invasive procedures through smaller incisions than conventional laparoscopy. Robotic surgical systems command the largest value pool due to capital intensity and recurring instrument revenue, while artificial intelligence represents the fastest-expanding technology layer as computer vision enables autonomous suturing and tissue identification. Hospitals absorb the majority of installed base volume, though ambulatory surgical centers are gaining traction for outpatient orthopedic and urologic applications.
FDA clearance pathways and EMA MDR compliance requirements shape product development timelines and clinical evidence standards for manufacturers seeking market access. ISO 13485 quality management and IEC 60601 electrical safety standards form baseline technical prerequisites for commercial distribution across jurisdictions. Stakeholders must weigh regulatory capital requirements against the pace of AI integration when allocating R&D investment across product generations.
Market Dynamics
The surgical robotics sector is absorbing autonomous capabilities faster than regulatory frameworks can codify safety benchmarks, forcing manufacturers to pre-certify AI modules under FDA's evolving Software as a Medical Device pathway while EMA's MDR recalibration extends clinical evidence timelines.
Growth Catalysts
- FDA's De Novo pathway expansion:Streamlined clearance for novel robotic platforms accelerates commercialization timelines for first-mover systems targeting soft-tissue applications.
- Ambulatory surgical center proliferation:Outpatient migration for orthopedic and urologic procedures expands addressable procedure volume beyond traditional hospital settings.
- Force-feedback haptics integration:Sub-millimeter tactile resolution enables suture automation in microsurgical domains previously resistant to robotic intervention.
Market Restraints
- Capital intensity concentration:Single-platform procurement costs exceed $2 million per installation, constraining adoption to academic medical centers and consolidated health systems with balance sheet capacity.
- Instrument supply oligopoly:Proprietary consumables lock-in concentrates recurring revenue with incumbent manufacturers, elevating total cost of ownership across procedure lifecycles.
- Surgeon training pipeline limitations:Fellowship programs produce insufficient robotic-certified specialists to match installation growth, creating utilization bottlenecks.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives reduce import duty exposure for multinational assemblers establishing regional production nodes.
- EU AI Act compliance premium:Early conformance to high-risk AI system requirements positions vendors for preferential procurement in European public health tenders.
- Telepresence surgery networks:5G-enabled remote procedure capabilities unlock rural and frontier market access without physical platform relocation.
Industry Challenges
- Cybersecurity validation complexity:IEC 62304 software lifecycle compliance for networked surgical systems demands specialized engineering talent scarce in medical device organizations.
- Interoperability standardization gaps:Absence of universal data exchange protocols between robotic platforms and hospital information systems fragments digital surgery ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Robotics Market |
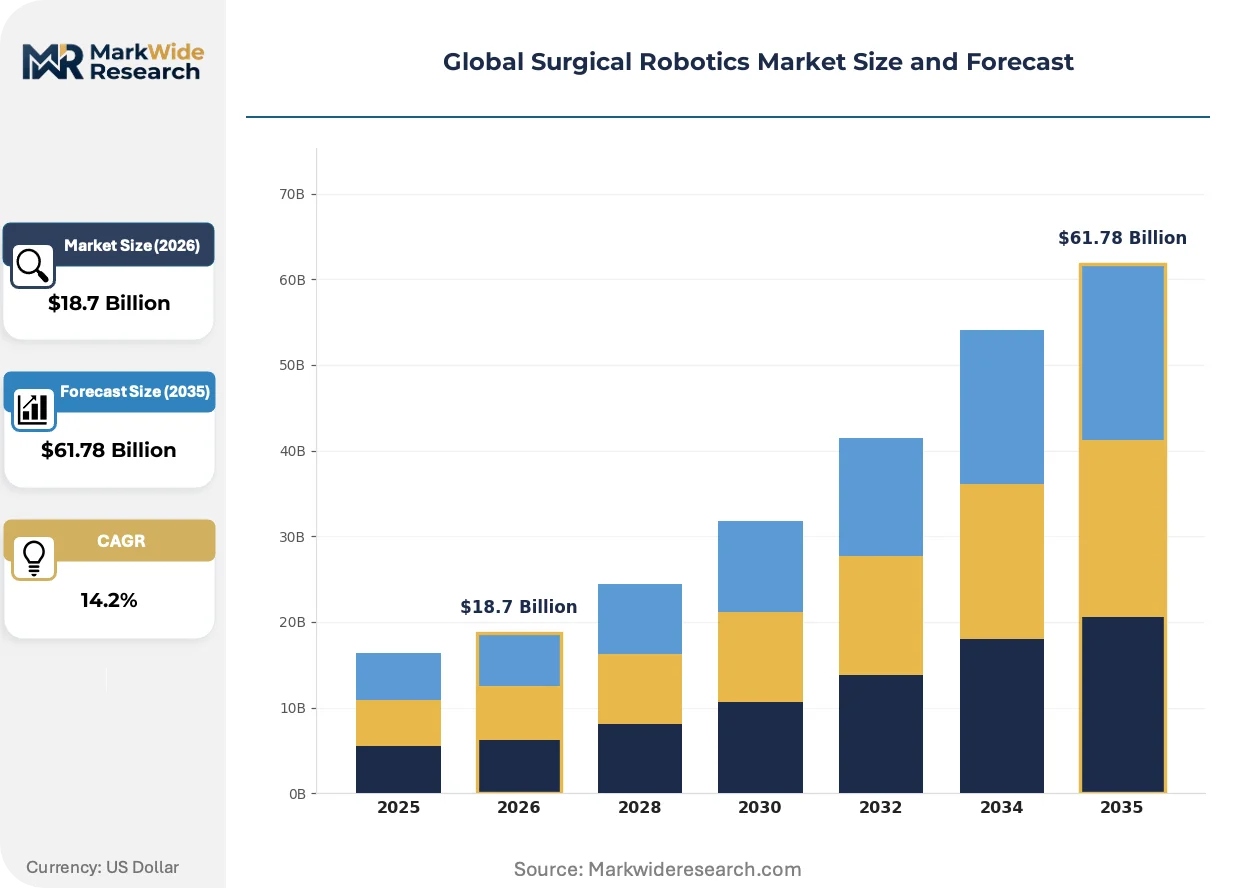
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Surgical Systems, Instrumentation, Accessories, Software End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Application: Orthopedic Surgery, Cardiothoracic Surgery, Neurosurgery, Urologic Surgery Technology: Telemanipulation, Haptic Feedback, Imaging Systems, Artificial Intelligence |
| Companies Covered | Intuitive Surgical, Stryker Corporation, Medtronic, Zimmer Biomet, Smith & Nephew, Asensus Surgical, CMR Surgical, Renishaw, THINK Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Robotics Market Strategic Shifts
Computer vision architectures are displacing conventional navigation paradigms across surgical robotics, with convolutional neural networks now enabling real-time tissue classification that reduces operative variability. Three convergent developments are restructuring competitive advantage.
Autonomous suturing algorithms are absorbing procedural steps previously requiring continuous surgeon manipulation, with microsurgical anastomosis systems now closing vessels below 0.3 millimeters diameter. Academic medical centers in Germany and Japan are piloting these platforms for lymphatic reconstruction, compressing operative time by eliminating hand tremor compensation cycles. The technology is absorbing skilled labor inputs that previously constrained procedure scalability.
EMA's MDR recalibration is elevating clinical evidence requirements for Class III robotic systems, mandating prospective registry data that extends pre-market authorization timelines by 18-24 months. Manufacturers are responding by front-loading post-market surveillance infrastructure during development phases rather than retrofitting compliance. Orthopedic navigation platforms face the steepest evidentiary burden due to long-term implant performance tracking obligations.
Hospital procurement committees are unbundling service contracts from capital purchases, demanding itemized maintenance pricing and third-party servicing rights that erode manufacturer aftermarket capture. This disintermediation is most pronounced in United States integrated delivery networks with centralized supply chain authority, where volume commitments now hinge on total cost transparency rather than bundled financing arrangements.
Global Surgical Robotics Market Segmentation
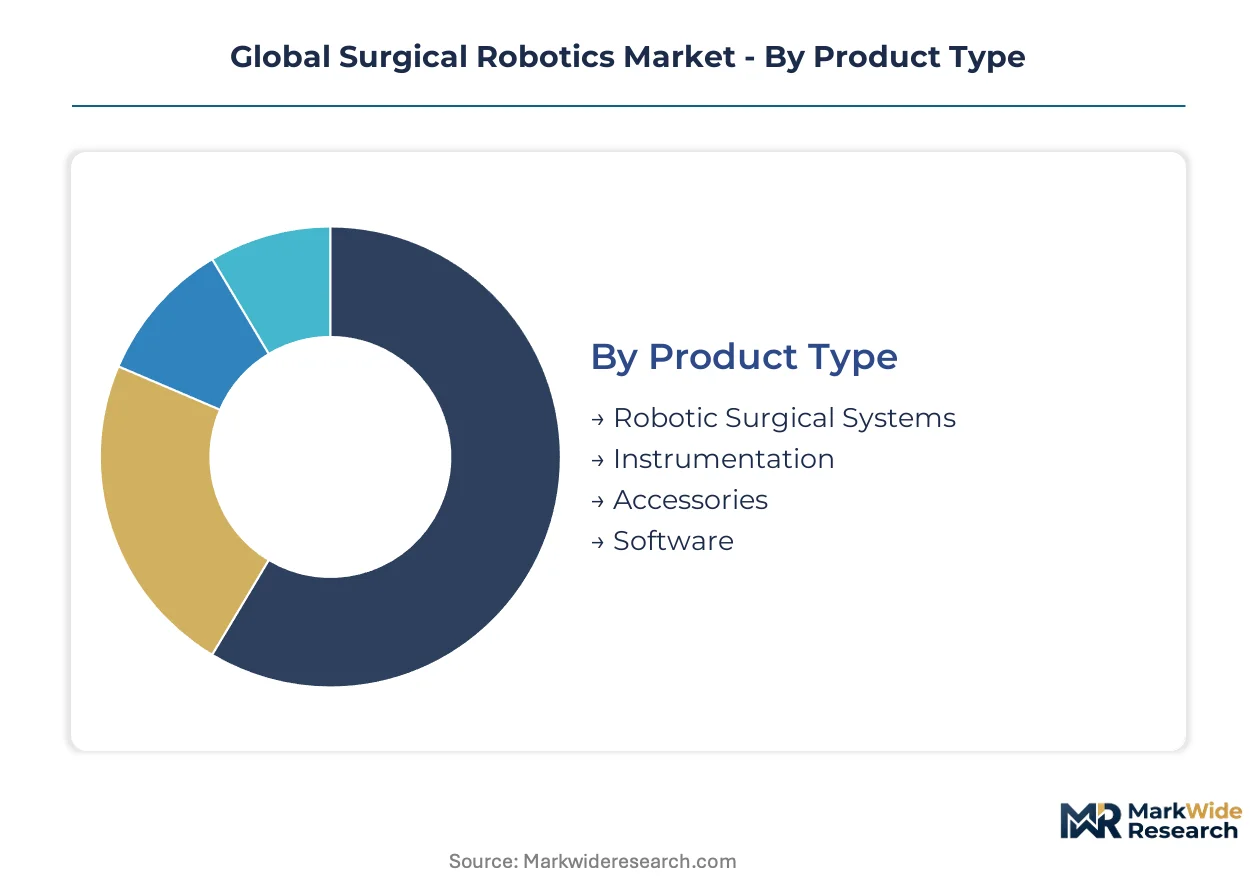
Segmentation in surgical robotics reveals how capital intensity, procedure complexity, and reimbursement pathways concentrate value across distinct product tiers and customer categories. Understanding these divisions clarifies where procurement budgets flow and which technology layers command premium pricing.
Product Type:
Volume deployment favors consumable instrumentation, while premium value pools concentrate in integrated robotic platforms with captive software ecosystems.
- Robotic Surgical Systems:Electromechanical platforms translating surgeon hand movements into sub-millimeter instrument articulation, typically incorporating multi-arm configurations with force feedback below 0.5 Newtons. Academic medical centers in the United States absorb the majority of installations, constrained by capital requirements exceeding $2 million per unit and FDA De Novo pathway timelines.
- Instrumentation:Proprietary single-use or limited-use instruments including graspers, scissors, needle drivers, and energy devices designed for specific platform architectures. Recurring revenue concentration here sustains manufacturer margins, though hospital procurement committees increasingly demand third-party servicing rights and itemized maintenance pricing.
- Accessories:Sterile drapes, trocars, and patient-side cart components enabling procedure-specific configurations.
- Software:Navigation algorithms, pre-operative planning modules, and intraoperative guidance systems enabling autonomous suturing and tissue classification.
Mature deployment sits with Robotic Surgical Systems. Newer deployment is concentrated in Software.
End User:
Reimbursement authority and procedure volume determine customer tiering, with consolidated health systems leveraging balance sheet capacity against outpatient migration trends.
- Hospitals:Integrated delivery networks and academic medical centers commanding robotic surgery programs with fellowship-trained specialists. United States hospital systems drive the majority of telemanipulation installations for urologic and orthopedic procedures, though surgeon training pipeline limitations create utilization bottlenecks.
- Ambulatory Surgical Centers:Outpatient facilities capturing migration of knee arthroplasty and prostatectomy procedures from inpatient settings. Germany and Japan pilot microsurgical anastomosis systems here for lymphatic reconstruction, compressing operative time through tremor elimination.
- Specialty Clinics:Focused urologic and orthopedic practices with lower capital thresholds.
- Research Institutions:Academic centers validating autonomous capabilities and computer vision architectures.
Procurement concentration rests with Hospitals. Volume expansion is climbing the fastest in Ambulatory Surgical Centers.
Application:
Procedure reimbursement codes and clinical evidence requirements shape adoption velocity across surgical specialties.
- Orthopedic Surgery:Robotic milling and navigation platforms for knee and hip arthroplasty, integrating pre-operative imaging with intraoperative bone resection guidance. EMA MDR recalibration imposes the steepest evidentiary burden here due to long-term implant performance tracking obligations, extending pre-market timelines.
- Urologic Surgery:Robotic prostatectomy and partial nephrectomy procedures with established reimbursement pathways.
- Cardiothoracic Surgery:Mitral valve repair and coronary artery bypass grafting via telemanipulation systems.
- Neurosurgery:Stereotactic navigation and tumor resection applications with emerging autonomous capabilities.
Established utilization centers on Urologic Surgery. Steepest expansion trajectory is appearing in Orthopedic Surgery.
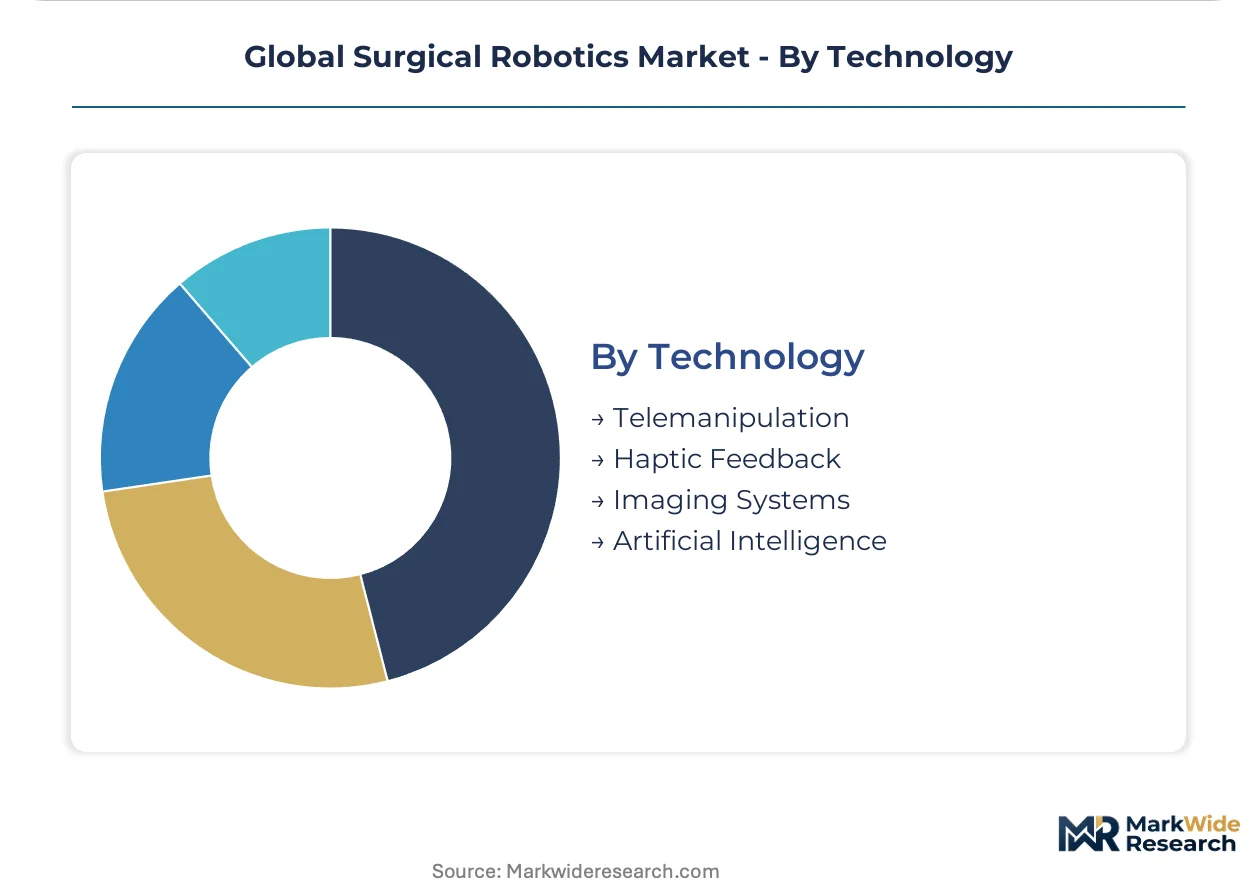
Technology:
Hardware maturity contrasts with software velocity, as regulatory frameworks lag AI integration pace.
- Telemanipulation:Master-slave architectures enabling remote instrument control with motion scaling and tremor filtration. FDA's Software as a Medical Device pathway now governs AI module pre-certification for these systems.
- Artificial Intelligence:Convolutional neural networks enabling real-time tissue classification and autonomous suturing algorithms. Computer vision architectures are displacing conventional navigation paradigms, with microsurgical anastomosis systems now closing vessels below 0.3 millimeters diameter.
- Haptic Feedback:Force-sensing instrumentation providing tactile resolution for suture automation.
- Imaging Systems:Intraoperative fluorescence, optical coherence tomography, and augmented reality overlays.
Commercial maturity resides with Telemanipulation. Capability investment is concentrating most heavily in Artificial Intelligence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Francisco Bay Area anchors global surgical robotics development, hosting Intuitive Surgical's headquarters and the densest concentration of FDA-cleared telemanipulation platforms. Academic medical centers in Baltimore and Houston drive procedure volume validation for autonomous capabilities.
United States
Academic medical centers in Baltimore and Houston absorb the majority of telemanipulation installations for urologic and orthopedic procedures. FDA's De Novo pathway expansion accelerates commercialization timelines for novel soft-tissue platforms. The Texas Medical Center cluster validates force-feedback haptics integration for microsurgical applications.
Germany
University hospitals in Munich and Heidelberg pilot autonomous suturing algorithms for lymphatic reconstruction procedures. EMA's MDR recalibration mandates prospective registry data that extends pre-market authorization timelines. The Baden-Württemberg medical technology corridor concentrates orthopedic navigation platform development.
Japan
Metropolitan hospital systems in Tokyo and Osaka deploy telemanipulation systems for aging-population prostatectomy demand. PMDA compliance requirements align with IEC 60601 electrical safety standards for commercial distribution. The Kobe medical device cluster advances computer vision architectures for intraoperative tissue classification.
India
Corporate hospital chains in Mumbai and Bengaluru expand robotic surgery programs for medical tourism volume. The PLI scheme for medical devices reduces import duty exposure for multinational assemblers establishing regional production nodes. The Hyderabad medical technology corridor attracts contract manufacturing for instrument sterilization accessories.
United Kingdom
NHS trusts in London and Manchester unbundle service contracts from capital purchases for total cost transparency. MHRA convergence with EMA MDR frameworks shapes post-Brexit product development timelines. The Cambridge medical technology cluster validates autonomous capabilities for computer vision-enabled surgical guidance.
Global Surgical Robotics Market Competitive Environment
Premium-margin players sit above commodity-margin players across the instrument supply and software ecosystem dimension. The vendor base concentrates around integrated platform manufacturers with captive consumables revenue and modular system specialists with flexible capital arrangements. Three strategic archetypes dominate: telemanipulation incumbents with proprietary instrument lock-in, orthopedic navigation specialists with milling platform differentiation, and AI-first challengers with computer vision architectures. Competitive moves center on unbundling service contracts for procurement committee transparency and front-loading post-market surveillance infrastructure during development phases.
Within the integrated platform tier, Intuitive Surgical and Stryker Corporation exemplify contrasting approaches to recurring revenue capture. Medtronic occupies a position anchoring mid-market flexibility through capital arrangement innovation. CMR Surgical represents the challenger archetype with modular system architecture.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Stryker Corporation |
| Medtronic |
| Zimmer Biomet |
| Smith & Nephew |
| Asensus Surgical |
| CMR Surgical |
| Renishaw |
| THINK Surgical |
| Others |
Value Chain & Pricing Dynamics
Autonomous suturing algorithm deployment is compressing per-procedure labor costs while concentrating component sourcing with ISO 13485-certified contract manufacturers in Germany and Japan. This technology shift simultaneously elevates software valuation multiples and tightens hardware margin capture as hospitals demand itemized maintenance transparency.
Pricing Analysis
Outcome-based pricing anchors procurement negotiations, with academic medical centers in the United States tying capital commitments to procedure throughput guarantees. Three-tier pricing structure across premium integrated platforms, modular mid-market systems, and commodity navigation tools differentiates by FDA De Novo clearance tier and captive instrument lock-in intensity. Cost compression in the mid-market tier is intensifying because Medtronic's flexible capital arrangements lower entry barriers without proprietary consumables revenue. Ambulatory surgical centers exhibit highest price sensitivity due to balance sheet constraints, while consolidated health systems with centralized supply chain authority leverage volume for total cost transparency.
Supply Chain Analysis
ISO 13485 quality management certification and IEC 60601 electrical safety compliance gate component qualification for electromechanical assemblies. Supply concentrates in the United States for FDA-cleared telemanipulation platforms, Germany for orthopedic navigation milling systems, and Japan for force-feedback haptic instrumentation. Precision servo motors, surgical-grade titanium alloys, and sterilizable sensor arrays constitute critical input dependencies. Single-source vulnerability runs through proprietary instrument architectures that lock hospitals into captive consumables. Distribution runs through direct manufacturer sales forces for capital platforms and GPO-aggregated contracts for recurring instrumentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA's MDR recalibration functions as a cost-of-compliance moat, extending pre-market authorization timelines by 18-24 months and forcing front-loaded post-market surveillance investment that screens out undercapitalized challengers.
For Market Incumbents: Anticipate procurement committee unbundling of service contracts by pre-emptively itemizing maintenance pricing and conceding third-party servicing rights to defend installed base retention. Vertical integration into instrument sterilization accessories buffers margin erosion from transparency demands. The priority lever sits with software ecosystem stickiness through autonomous capability modules that raise switching costs.
For New Entrants and Emerging Players: India's PLI scheme for medical devices opens a window for contract manufacturing establishment that reduces import duty exposure and anchors regional production nodes. Target ambulatory surgical centers in Germany and Japan piloting microsurgical anastomosis systems for lymphatic reconstruction, where tremor elimination justifies premium positioning without academic medical center capital thresholds. A software-first go-to-market angle leveraging convolutional neural networks for tissue classification bypasses hardware certification timelines.
For Investors and Strategic Acquirers: Re-rating potential sits with AI-first challengers possessing computer vision architectures and FDA Software as a Medical Device pathway progress, given autonomous suturing algorithm absorption of skilled labor inputs. Long-term viability over a 5-10 year window favors modular system specialists with flexible capital arrangement capabilities and EU AI Act compliance positioning. The signal to watch is hospital procurement committee adoption of itemized maintenance pricing as a standard evaluation criterion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Pathway Navigation | Streamlined clearance for soft-tissue platforms accelerates commercialization timelines in the United States. |
| EU AI Act Compliance Investment | Early conformance to high-risk AI system requirements secures preferential procurement in European public health tenders. |
| Hospital System Partnership | Integrated delivery network volume commitments hinge on total cost transparency rather than bundled financing. |
| Software Companion Development | Autonomous suturing algorithms absorb procedural steps previously requiring continuous surgeon manipulation. |
| Reimbursement Strategy | Established CPT codes for robotic prostatectomy anchor urologic procedure volume against orthopedic evidentiary burdens. |
Study Parameters
Document review covered FDA 510(k) and De Novo filings, EMA MDR technical documentation, hospital procurement databases, and GPO contract disclosures, complemented by interviews with robotic surgery program directors, biomedical engineers, hospital purchasing committee members, and regulatory affairs leads at device manufacturers. Secondary validation drew from ISO certification registries, CMS Medicare procedure volume data, and academic medical center fellowship program statistics. Bottom-up installation base modeling and top-down procedure volume estimates were triangulated against capital expenditure disclosures from consolidated health systems.
Cross-referencing historical FDA clearance timelines against expert panel input on AI module pre-certification pacing structured the forecast framework across the analysis window. Segmentation dimensions modeled include product architecture tier, end-user facility type, surgical specialty application, technology layer maturity, and regional regulatory cluster. CAGRs were derived from procedure volume elasticity to installed base expansion and recurring instrument revenue per system. Forecast inputs incorporated surgeon training pipeline throughput constraints and ambulatory surgical center migration velocity for orthopedic and urologic procedures.
The model assumes a particular technology adoption path for autonomous capabilities; alternative pathways for fully autonomous suturing without surgeon oversight would alter the outlook substantially. Forecasts reflect assumptions regarding FDA Software as a Medical Device pathway evolution and EMA MDR recalibration stability. A model refresh is warranted upon material change in hospital procurement committee evaluation criteria or cybersecurity validation requirements for networked surgical systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pelvic Floor Electrical Stimulation Devices Market
Medical Devices
Wearable Insulin Pump Market
Medical Devices
Active Implantable Devices Market
Medical Devices
Intelligent Electronic Sphygmomanometers Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Netherlands Artificial Organs and Bionic Implants Market
Medical Devices
Global Radiofrequency Ablation Devices Market
Medical Devices
Artificial Disc Replacement Market
Medical Devices
Single-Use Centrifuge System Market
Medical Devices
Blood Irradiator Device Market
Medical Devices
Foot Ulcer Sensors Market
Medical Devices
Russia Massage Equipment Market
Medical Devices
Tracheostomy Tubes Market
Medical Devices
Brazil Contraceptive Devices Market
Medical Devices
Transcranial Magnetic Stimulation System Market
Medical Devices
Dose Monitoring Devices Market