
 Intraoperative Sensor Market | 2026-2036
Intraoperative Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Intraoperative Sensor Market Analysis
Aftermarket sensor calibration and refurbishment revenue is rewriting margin economics for device OEMs. Medtronic PLC leverages its installed base of neuromonitoring platforms to sustain recurring service contracts across North American hospital networks. GE Healthcare anchors its position through backward integration into imaging-compatible sensor arrays that synchronize with its surgical navigation systems. Analog Devices specializes in MEMS pressure transducer chips that supply multiple OEMs, competing on precision specifications rather than finished-device branding.
Intraoperative sensors are electromechanical or photonic devices designed to measure physiological parameters—tissue oxygenation, nerve impulse conduction, or instrument-tissue contact force—with millisecond latency during active surgical procedures. Fiber optic temperature probes withstand autoclave sterilization cycles while maintaining sub-degree Celsius accuracy in cardiac ablation catheter tips. Pressure sensors dominate current revenue owing to their ubiquity in orthopedic navigation drills and arthroscopic shavers, whereas wireless bioelectrical arrays represent the fastest-expanding technology segment as hospitals phase out tethered EMG cabling in cramped operating theaters. Electromagnetic tracking sensors occupy mature margin pools in image-guided spine surgery, where incremental innovation now centers on miniaturization rather than accuracy breakthroughs.
FDA 510(k) premarket notification requirements govern sensor safety and electromagnetic compatibility for devices used in American surgical suites, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence standards on Class IIa and above intraoperative monitoring equipment sold in Europe. Japan's PMDA mandates localized electrical safety testing that extends approval timelines for wireless sensor platforms. Stakeholders must monitor evolving cybersecurity guidance from FDA and MDR post-market surveillance obligations, as connected surgical sensors become networked endpoints vulnerable to hospital IT infrastructure breaches.
Market Dynamics
Wireless bioelectrical arrays are compressing operating theater footprints while forcing OEMs to abandon tethered EMG architectures, reshaping competitive positioning around electromagnetic compatibility rather than raw signal fidelity.
Growth Catalysts
- FDA 510(k) pathway compression:The FDA's streamlined premarket notification framework for Class II surgical sensors accelerates time-to-market for novel bioelectrical interfaces. Neurosurgical suites in tertiary hospitals exploit this velocity to refresh monitoring platforms on compressed replacement cycles.
- University hospital network integration:German university hospital clusters anchor demand concentration as intraoperative MRI installations drive proprietary sensor ecosystem procurement. These institutions bundle navigation, imaging, and monitoring into single-vendor contracts.
- MEMS precision specifications:Advances in microelectromechanical pressure transducer manufacturing enable sub-millimeter catheter tip integration. Cardiac ablation and orthopedic navigation applications absorb this capability at expanding volume.
Market Restraints
- Japan PMDA electrical safety mandates:Localized testing requirements for wireless sensor platforms extend approval timelines by 8-14 months, freezing early revenue recognition for platforms targeting the Japanese surgical market.
- Silicon foundry concentration:MEMS pressure transducer die production concentrates in Taiwanese and South Korean fabrication facilities, exposing OEMs to geopolitical supply interruption risk.
- Autoclave material degradation:Fiber optic temperature probes face thermal cycling fatigue that limits reusable probe lifespan to 50-75 sterilization cycles, elevating per-procedure consumable costs.
Strategic Opportunities
- Aftermarket calibration services:Recurring refurbishment contracts for installed neuromonitoring platforms generate margin pools detached from hardware shipment volatility. North American hospital networks lock in multi-year service agreements.
- EU MDR Class IIa clinical evidence requirements:Stricter European clinical documentation standards create competitive moats for established players with legacy trial data, disadvantaging new market entrants lacking retrospective cohorts.
- Wireless-EMG convergence:Integration of Bluetooth Low Energy protocols with traditional electromyography arrays eliminates cable clutter in cramped surgical theaters. Ambulatory surgery centers adopt this configuration for space-constrained suites.
Industry Challenges
- Electromagnetic interference mitigation:Surgical teams struggle to isolate wireless sensor arrays from electrosurgical unit noise in hybrid operating rooms, demanding specialized shielding engineering that extends integration timelines.
- Cybersecurity endpoint hardening:Connected intraoperative sensors become network breach vectors as hospital IT infrastructure consolidates, forcing OEMs to absorb FDA cybersecurity guidance compliance costs without pricing recovery mechanisms.
- Legacy navigation system interoperability:Proprietary data protocols from installed electromagnetic tracking platforms block seamless wireless sensor integration, requiring costly middleware development or full-stack replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intraoperative Sensor Market |
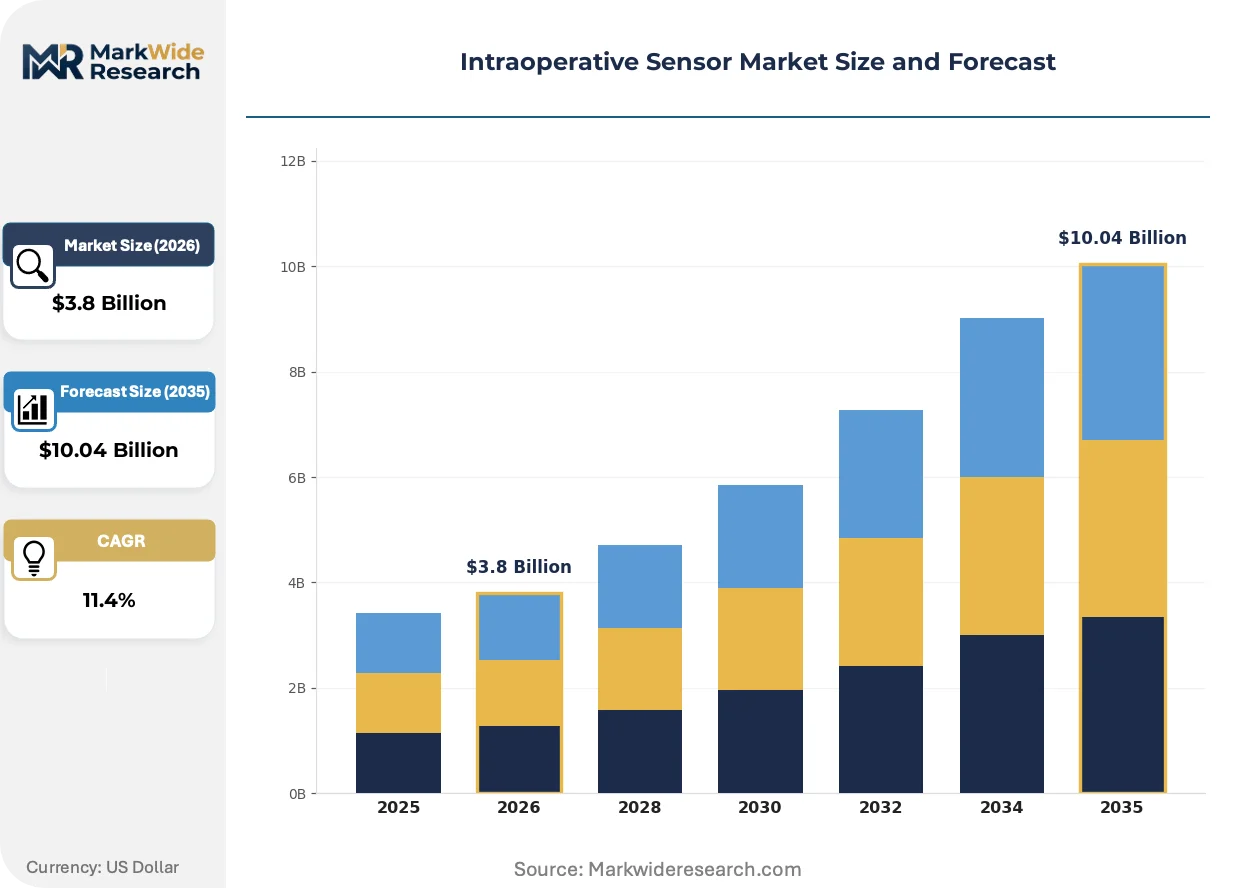
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Sensors, Pressure Sensors, Electromagnetic Sensors, Ultrasonic Sensors Technology: Wireless Technology, Fiber Optics, Imaging Technology, Bioelectrical Technology End User: Hospitals, Surgical Centers, Research Institutions, Medical Training Facilities Application: Cardiac Surgery, Neurological Procedures, Orthopedic Surgeries, Minimally Invasive Surgery |
| Companies Covered | Robert Bosch GmbH, ABB Group, Analog Devices, GE Healthcare, Koninklijke Philips N.V., STMicroelectronics, Medtronic PLC, Honeywell International Inc., Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intraoperative Sensor Market Emerging Trajectories
Real-time neural monitoring architectures are fragmenting around three vectors: wireless connectivity standards, sterilization-compatible materials, and AI-augmented signal interpretation. These shifts compress product lifecycles while elevating R&D intensity.
MEMS pressure sensing is migrating from discrete component supply toward finished-device integration. Orthopedic navigation OEMs now specify custom transducer dies rather than off-the-shelf chips, compressing Analog Devices and similar suppliers into captive component roles. This migration from merchant silicon to embedded subsystem design is forcing semiconductor houses to surrender branding and margin to finished-device manufacturers.
The EU Medical Device Regulation's post-market surveillance obligations are reshaping clinical evidence requirements. Class IIa intraoperative monitoring equipment now demands active implantable-grade follow-up protocols, elevating registry maintenance costs. European notified bodies are responding by consolidating review capacity, extending certificate renewal timelines for wireless bioelectrical arrays.
Hospital procurement departments are unbundling after-sales service from hardware acquisition. Tertiary medical centers now negotiate calibration and refurbishment contracts through separate RFP processes, fragmenting vendor relationships. This unbundling is most visible in German university hospital networks, where imaging-compatible sensor arrays are sourced independently from navigation platform maintenance agreements.
Intraoperative Sensor Market Segmentation
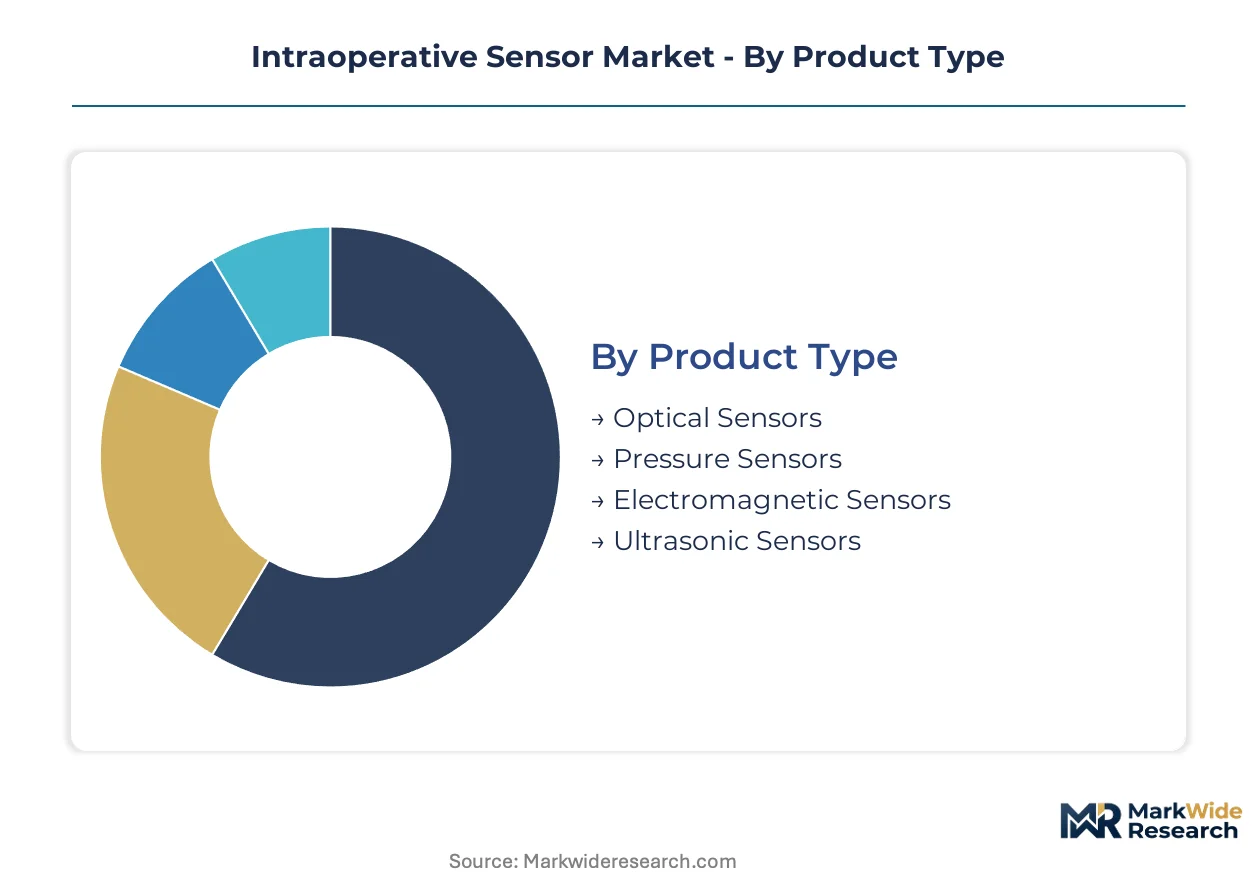
Segmentation in intraoperative sensors reveals divergent technology maturities and procurement patterns across surgical settings. Product type and technology dimensions expose where margin pools concentrate versus where innovation capital flows.
Product Type:
Pressure sensors anchor mature revenue streams while optical platforms accelerate through cardiac ablation adoption.
- Optical Sensors:Fiber optic temperature probes deliver sub-degree Celsius accuracy in catheter tips and withstand repeated autoclave cycles. German university hospital networks bundle these with intraoperative MRI navigation platforms, driving procurement concentration in tertiary cardiac centers.
- Pressure Sensors:MEMS transducer chips integrate into orthopedic navigation drills and arthroscopic shavers with sub-millimeter precision. Demand concentrates in North American hospital networks where instrument-tissue force feedback reduces iatrogenic nerve damage during spine procedures.
- Electromagnetic Sensors:Tracking arrays for image-guided surgery occupy established margin pools with incremental innovation focused on coil miniaturization rather than accuracy gains.
- Ultrasonic Sensors:Piezoelectric arrays enable real-time tissue characterization during tumor resection margins assessment.
Pressure sensors retain volume leadership; optical sensors hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium wireless arrays from commoditized fiber installations.
- Wireless Technology:Bluetooth Low Energy protocols eliminate cable clutter in cramped operating theaters. Ambulatory surgery centers in the United States adopt these configurations for space-constrained suites, though electromagnetic interference from electrosurgical units demands specialized shielding engineering.
- Fiber Optics:Silica-core temperature probes face thermal cycling fatigue limiting reusable lifespan to 50-75 sterilization cycles, elevating per-procedure consumable costs for cardiac ablation programs.
- Imaging Technology:MRI-compatible sensor arrays synchronize with surgical navigation systems in German hospital procurement bundles.
- Bioelectrical Technology:EMG arrays with millisecond latency measure nerve impulse conduction during active dissection.
Fiber optics commands the lowest unit economics; wireless platforms gain share fastest through ASC penetration.
End User:
Customer type determines service contract structures and replacement cycle velocity.
- Hospitals:Tertiary medical centers in Germany and the United States negotiate multi-year calibration agreements separately from hardware acquisition, fragmenting vendor relationships. These institutions drive demand for integrated imaging-compatible sensor ecosystems.
- Surgical Centers:Ambulatory facilities prioritize wireless configurations to maximize procedure throughput in constrained physical footprints.
- Research Institutions:University hospital networks prototype next-generation neural monitoring architectures before commercial scale-up.
- Medical Training Facilities:Simulation labs absorb refurbished sensor platforms from hospital upgrade cycles.
Hospitals dominate installed base value; surgical centers generate the most rapid deployment velocity.
Application:
Procedure invasiveness level correlates with sensor modality complexity and price realization.
- Cardiac Surgery:Ablation catheter tip sensors require fiber optic temperature monitoring with autoclave resilience. FDA 510(k) pathway compression accelerates platform refresh cycles in United States electrophysiology labs.
- Neurological Procedures:Real-time neural monitoring arrays with millisecond latency protect motor pathways during tumor resection. German university hospital clusters anchor demand concentration through intraoperative MRI integration.
- Orthopedic Surgeries:Navigation drill force feedback relies on MEMS pressure transducers specified as custom dies rather than merchant silicon.
- Minimally Invasive Surgery:Laparoscopic instrument-tissue contact sensors demand miniaturized electromagnetic tracking coils.
Cardiac surgery commands premium pricing; neurological applications exhibit the steepest technology refresh intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across surgical settings. Ambulatory surgery centers in the United States demand wireless configurations at aggressive unit economics, while German university hospital networks absorb premium imaging-compatible sensor ecosystems without procurement friction.
United States
FDA 510(k) pathway compression accelerates platform refresh cycles for neuromonitoring arrays in tertiary electrophysiology labs. Ambulatory surgery centers in Texas and Florida prioritize Bluetooth Low Energy configurations to maximize throughput in space-constrained suites. The Southeast corridor absorbs expanding volumes of refurbished sensor platforms from hospital upgrade cycles.
Germany
University hospital clusters in Bavaria and North Rhine-Westphalia anchor European demand concentration through intraoperative MRI integration. EU MDR Class IIa clinical evidence requirements create competitive moats for established players with legacy trial data. The Berlin-Brandenburg corridor prototypes next-generation neural monitoring architectures before commercial scale-up.
Japan
PMDA electrical safety mandates for wireless sensor platforms extend approval timelines by 8-14 months, freezing early revenue recognition. METI funding for smart surgical infrastructure drives adoption in Tokyo and Osaka metropolitan hospital networks. The Kansai region concentrates domestic MEMS foundry partnerships for pressure transducer die supply.
China
NMPA streamlined review pathways for Class II surgical sensors compress domestic time-to-market against import competitors. Yangtze River Delta hospital procurement departments unbundle after-sales service from hardware acquisition, fragmenting vendor relationships. Shanghai tertiary centers drive demand for MRI-compatible sensor arrays synchronized with surgical navigation systems.
South Korea
MFDS electromagnetic compatibility standards for wireless bioelectrical arrays match Japanese stringency, extending validation timelines. Seoul Capital Area hospital networks negotiate multi-year calibration agreements separately from hardware acquisition. The Busan-Ulsan corridor anchors domestic MEMS fabrication capacity for pressure transducer supply to regional OEMs.
Intraoperative Sensor Market Vendor Landscape
Diversified industrial conglomerates and specialized medical device manufacturers split the market along integration depth. Consolidation pressures concentrate around imaging-compatible sensor ecosystems and aftermarket service contract capture. Three archetypes dominate: full-stack surgical navigation integrators, MEMS component suppliers, and refurbished platform service specialists. Competitive moves center on backward integration into sensor fabrication and geographic expansion through university hospital network procurement bundling.
Among diversified industrial conglomerates, Siemens AG and Robert Bosch GmbH exemplify the scale-driven archetype, leveraging captive electronics manufacturing depth to supply imaging-compatible sensor subsystems across European hospital networks. Medtronic PLC occupies a position within the full-stack surgical navigation tier, anchoring North American installed base value through recurring calibration contract structures. Analog Devices represents the merchant silicon specialist archetype, supplying precision MEMS pressure transducer dies to multiple finished-device OEMs without forward integration into branded surgical platforms.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| ABB Group |
| Analog Devices |
| GE Healthcare |
| Koninklijke Philips N.V. |
| STMicroelectronics |
| Medtronic PLC |
| Honeywell International Inc. |
| Siemens AG |
| Others |
Supply Flow & Price Mechanics
Taiwanese foundry concentration for MEMS pressure transducer die production exposes OEMs to geopolitical supply interruption risk that simultaneously compresses standard-tier hardware margins and expands premium-tier spreads for imaging-compatible sensor ecosystems with captive fabrication.
Pricing Analysis
Aftermarket calibration and refurbishment contracts now drive lifetime value, with North American hospital networks locking in multi-year service agreements detached from hardware shipment volatility. Pricing stratifies across premium imaging-compatible arrays, standard tethered EMG platforms, and economy refurbished units. Cost compression in standard-tier pressure sensors intensifies as orthopedic navigation OEMs specify custom MEMS dies rather than merchant silicon. Ambulatory surgery centers exhibit acute price sensitivity, while German university hospital networks absorb premium bundles without procurement friction.
Supply Chain Analysis
US export controls on advanced semiconductor manufacturing equipment to Chinese foundries constrain MEMS fabrication capacity expansion, reshaping regional supply allocation. MEMS pressure transducer die production centers on Taiwanese and South Korean fabrication facilities, drawing from silicon wafers, photoresist chemicals, and precision etching equipment. Single-source vulnerability concentrates in 200mm foundry capacity for medical-grade MEMS. Distribution runs through finished-device OEMs with direct hospital procurement relationships, bypassing traditional medical device distributors for sensor subsystem integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of electromagnetic compatibility engineering talent for wireless bioelectrical arrays in cramped surgical theaters limits competitive replication, anchoring premium capture for early movers with shielding protocol expertise.
For Market Incumbents: Pre-empt wireless-EMG convergence disruption by acquiring Bluetooth Low Energy protocol specialists before ambulatory surgery center procurement shifts lock in alternative vendors. Backward integration into MEMS fabrication insulates margin pools from Taiwanese foundry concentration risk. Hospital network unbundling of after-sales service threatens recurring revenue capture.
For New Entrants and Emerging Players: Japanese PMDA electrical safety testing bottlenecks represent the most penetrable entry point for wireless sensor platforms with pre-validated electromagnetic compatibility documentation. Target ASC configurations in the United States Southeast corridor with refurbished platform refurbishment capabilities. Pursue white-label MEMS die supply to orthopedic navigation OEMs seeking custom transducer specifications.
For Investors and Strategic Acquirers: EU MDR Class IIa clinical evidence requirements reshape the acquisition landscape toward established players with legacy trial data and active implantable-grade follow-up protocols. Long-term viability hinges on aftermarket service contract density rather than hardware shipment velocity. Monitor FDA cybersecurity guidance enforcement intensity as a signal for compliance cost absorption capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Single-vendor contracts with German university hospital networks bundle imaging, navigation, and monitoring into proprietary ecosystems. |
| FDA 510(k) Submission | Streamlined premarket notification pathways compress time-to-market for novel bioelectrical interfaces in electrophysiology labs. |
| Backward Integration into MEMS Fabrication | Captive die production insulates orthopedic navigation OEMs from Taiwanese foundry concentration and geopolitical interruption. |
| Software Companion Development | AI-augmented signal interpretation for real-time neural monitoring elevates R&D intensity while fragmenting product architectures. |
| Reimbursement Strategy | Calibration service contracts generate recurring margin pools detached from hardware shipment volatility in North American networks. |
Methodological Framework
A spread of perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and neuromonitoring platform specialists converged on the working assumptions. Primary interviews with clinicians and regulatory affairs leads at FDA-cleared device manufacturers combined with secondary validation against FDA 510(k) filings, EU MDR notified body certificates, hospital procurement databases, and GPO contract repositories. Bottom-up installed base modeling and top-down market sizing triangulation anchored volume estimates.
Demand-supply balance across the analysis window shaped the analytical framework, with segmentation modeled by product type, technology tier, end-user category, and application invasiveness level. CAGRs derived from procedure volume elasticity, replacement cycle compression, and technology substitution curves. Wireless bioelectrical array penetration rates and MEMS pressure transducer integration intensity served as industry-specific forecast inputs.
Practitioners should monitor FDA cybersecurity guidance enforcement, EU MDR certificate renewal timeline extensions, and Taiwanese foundry utilization rates for early signals. Forecasts reflect assumptions about electromagnetic interference mitigation engineering capacity and autoclave material degradation rates. Material shifts in US export control scope for semiconductor manufacturing equipment or PMDA electrical safety mandate stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Upper Limb Prosthetics Market
Medical Devices
Japan Artificial Organs and Bionic Implants Market
Medical Devices
IV Equipment Market
Medical Devices
Global Stroke Assistive Devices Market
Medical Devices
Tracheostomy Tubes Market
Medical Devices
Italy Artificial Organs and Bionic Implants Market
Medical Devices
Global Artificial Limbs Market
Medical Devices
South Africa Artificial Organs and Bionic Implants Market
Medical Devices
Global Medical Device Contract Manufacturing Market
Medical Devices
Positive Air Pressure Devices Market
Medical Devices
Global Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
Subperiosteal Implants Market
Medical Devices
Organ Care Market
Medical Devices
India Drug Delivery Devices Market
Medical Devices
Contact Lenses Market
Medical Devices
Syringe Scale Magnifiers Market