
 External Nasal Dilator Market | 2026-2036
External Nasal Dilator Market Size, Share, and Industry Trends Forecast 2026-2036
External Nasal Dilator Market Foresight
ISO 13485 certification for medical device quality management is rotating as the primary gating mechanism for manufacturers seeking entry into regulated channels. GlaxoSmithKline Plc leverages its established consumer health infrastructure to sustain pharmacy shelf presence across multiple continents. Rhinomed Limited differentiates through proprietary nasal architecture designs that anchor its position in performance-oriented segments. Splintek Inc competes on manufacturing scale, controlling cost structures that support mass-market over-the-counter distribution.
An external nasal dilator is a mechanical device composed typically of adhesive-backed plastic or spring-steel bands that physically widens the nasal vestibule to reduce airflow resistance during respiration. The device functions by exerting outward tension on the nasal wall, with spring force measured in grams of dilation pressure determining clinical efficacy for snoring reduction or athletic oxygen intake. Single-use adhesive strips still occupy the largest volume position due to low unit cost and convenience, though reusable silicone variants are capturing margin pools among committed athletic users. Custom-fit segments remain nascent but concentrate value where 3D scanning or impression-based fitting commands premium positioning. Material selection splits between plastic substrates for economy positioning and medical-grade silicone for dermatological tolerance and repeated-use durability.
FDA oversight as a Class I medical device in the United States and CE marking requirements under the EU MDR collectively shape product labeling claims, biocompatibility testing obligations, and market access timelines for manufacturers. Health Canada and the TGA in Australia impose parallel pre-market notification structures that filter which companies can deploy direct-to-consumer marketing with therapeutic indications. Stakeholders must monitor how evolving OTC classification debates in major jurisdictions could either expand retail access or trigger prescription-level scrutiny for claims beyond simple mechanical action.
Market Dynamics
Spring-steel band technology is decomposing the traditional single-use adhesive strip segment as athletes and chronic snorers demand reusable, dermatologically tolerant alternatives with measurable dilation pressure consistency.
Growth Catalysts
- ISO 13485 certification pathways:Medical device quality management standards are opening regulated pharmacy channels in Germany, France, and Australia for manufacturers meeting biocompatibility testing protocols.
- Athletic oxygen optimization:Endurance sports participants in cycling and marathon running are adopting dilators with calibrated spring force measured in grams to quantify respiratory efficiency gains during competition.
- FDA Class I clearance efficiency:The streamlined 510(k) exemption pathway for mechanical nasal dilators accelerates market entry timelines compared to drug-based respiratory therapies.
Market Restraints
- Medical-grade silicone cost volatility:Raw material price fluctuations for platinum-cured silicone impact margin structures for reusable dilator manufacturers targeting premium athletic segments.
- Substitution by internal nasal stents:ENT specialists increasingly prescribe internal dilators for severe nasal valve collapse, compressing addressable volume for external mechanical alternatives.
- EU MDR recertification burden:Legacy CE-marked products face biocompatibility retesting and clinical evidence requirements under the 2017/745 Medical Device Regulation, extending compliance timelines.
Strategic Opportunities
- 3D scanning integration:Custom-fit dilators produced through smartphone-based nasal architecture scanning are capturing premium positioning among committed users dissatisfied with one-size designs.
- Direct-to-consumer telehealth bundling:Sleep apnea screening platforms in the United States are incorporating external dilators into subscription diagnostic kits, bypassing traditional pharmacy distribution.
- India PLI scheme leverage:The Production Linked Incentive scheme for medical devices offers tariff advantages for manufacturers establishing domestic silicone molding and adhesive lamination capacity.
Industry Challenges
- Adhesive dermatitis mitigation:Formulation chemists with polymer science specialization remain scarce as manufacturers balance peel strength against skin irritation incidence in sensitive user populations.
- Spring fatigue testing standardization:Absence of unified ISO protocols for measuring dilation pressure degradation over repeated use cycles complicates quality assurance and warranty positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | External Nasal Dilator Market |
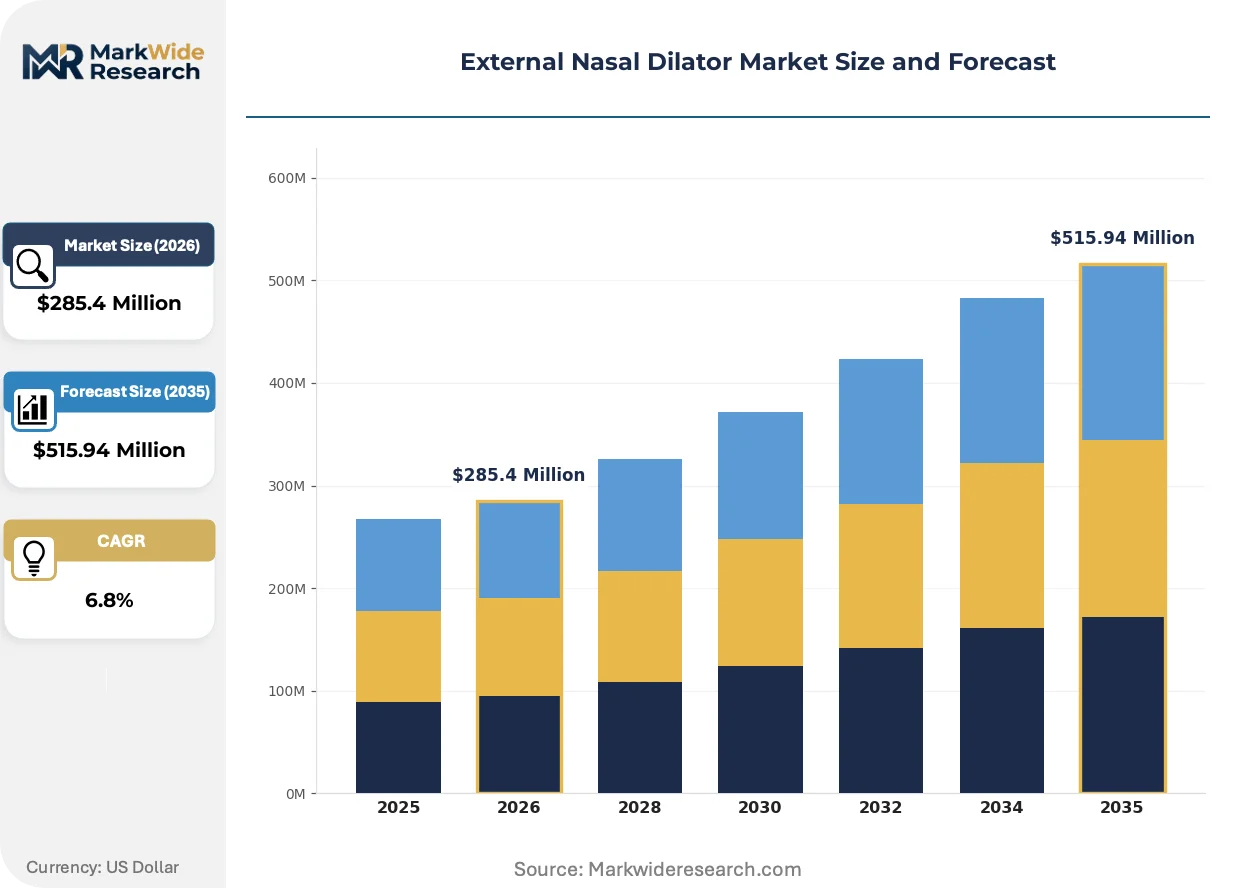
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-use, Reusable, Custom-fit, Over-the-counter End User: Athletes, Patients, Healthcare Professionals, General Consumers Distribution Channel: Pharmacies, Online Stores, Supermarkets, Specialty Stores Material: Silicone, Plastic, Rubber, Foam |
| Companies Covered | GlaxoSmithKline Plc, HealthRight Products LLC, Splintek Inc, Rhinomed Limited, AirWare Labs, Tomed GmbH, Zhongshan Hongze Medical Technology Co., Ltd., McKeon Products Inc., Scandinavian Formulas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
External Nasal Dilator Market Shifts & Advancements
Material science convergence with digital health infrastructure is redefining product architecture and user engagement models across the external nasal dilator category.
Reusable silicone dilators with integrated pressure sensors are decomposing the commodity adhesive strip market by enabling real-time airflow resistance measurement through Bluetooth-connected mobile applications. Professional athletes and sleep clinics are piloting these devices to quantify physiological response. The technology is compressing unit economics for single-use competitors while creating recurring revenue streams through subscription analytics platforms.
REACH compliance deadlines for phthalate-free adhesives are forcing reformulation of legacy pressure-sensitive tapes used in economy-tier strips. Manufacturers sourcing acrylate-based alternatives face extended validation timelines for skin-sensitivity testing. The regulatory pressure falls most heavily on private-label suppliers serving European pharmacy chains, who must absorb retooling costs or exit the market.
Certification-driven purchasing is fragmenting procurement authority within hospital systems and sports medicine clinics. Procurement officers now require ISO 10993 biocompatibility documentation and FDA establishment registration before adding dilators to formulary lists, displacing informal physician preference-based ordering. This behavioral shift concentrates volume with manufacturers maintaining dedicated regulatory affairs functions, visible most acutely in United States integrated delivery networks.
External Nasal Dilator Market Segmentation
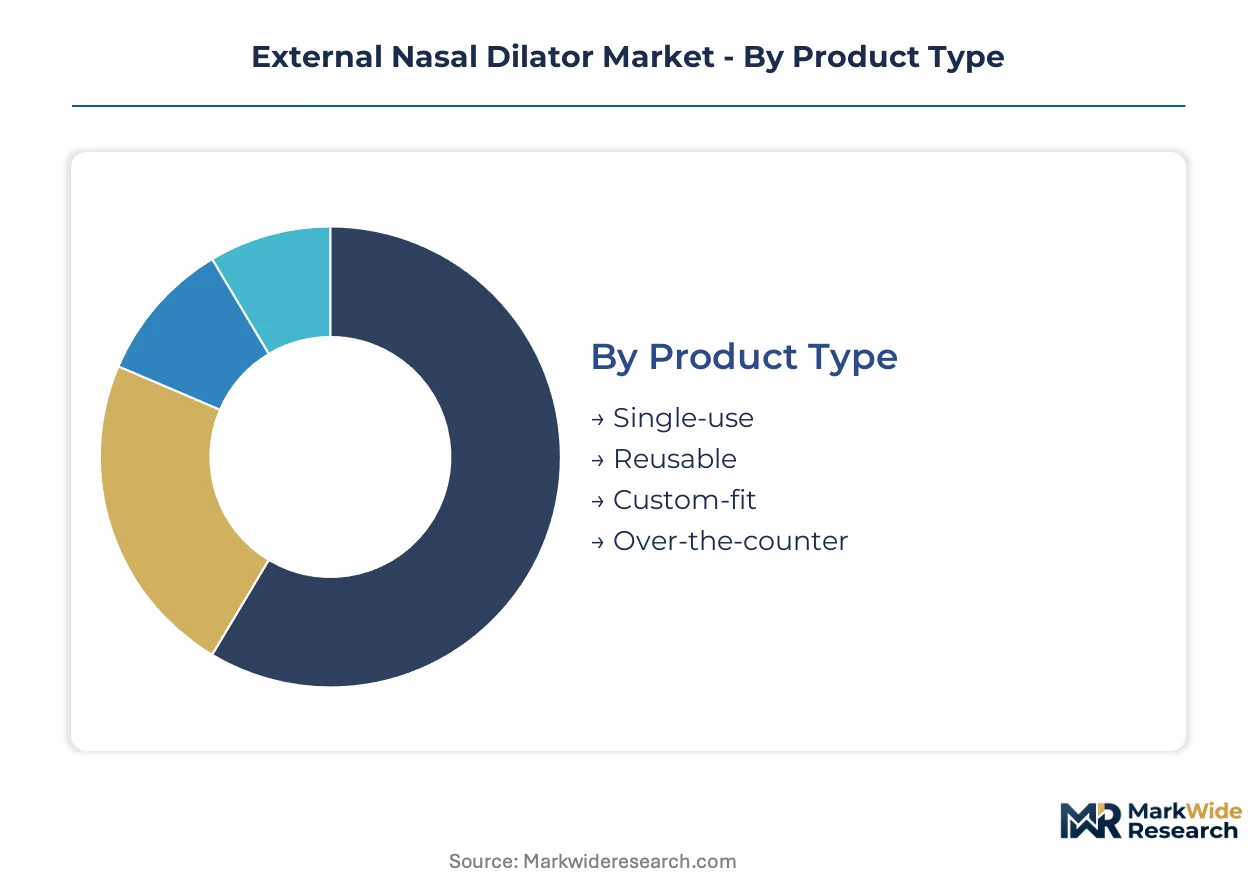
External nasal dilators fragment across four distinct category axes, each commanding different margin profiles and regulatory pathways. Product architecture and material selection determine whether manufacturers pursue FDA Class I clearance or remain in unregulated consumer channels.
Product Type:
FDA Class I designation and CE marking under EU MDR split this category into regulated medical devices versus unregulated consumer goods, with compliance burden directly shaping market access.
- Single-use:Adhesive-backed strips with spring-steel bands dominate pharmacy volume through low unit cost and disposable convenience. Demand concentrates in North American retail chains where consumers prioritize trial accessibility over long-term investment.
- Reusable:Medical-grade silicone dilators with calibrated spring mechanisms target athletic users requiring consistent dilation pressure across training cycles. Adoption climbs fastest among marathon runners and cyclists in Germany and Australia who track respiratory efficiency metrics.
- Custom-fit:Impression-based or 3D-scanned devices command premium positioning through personalized nasal architecture matching. ENT clinics in the United States and sleep medicine practices in France drive prescription-channel volume.
- Over-the-counter:Economy-tier strips bypass medical device classification through mechanical-action-only labeling. Mass-market distribution through supermarkets in the United Kingdom and drugstore chains in Canada sustains volume despite thinner margins.
Established volume favors single-use strips; emerging adoption favors reusable silicone variants with measurable performance metrics.
End User:
Application intensity and clinical oversight requirements segment demand across performance optimization, therapeutic intervention, and casual symptom relief.
- Athletes:Endurance sports participants deploy dilators with gram-specified spring force to quantify oxygen intake gains during competition. Cycling teams in Italy and triathlon clubs in Spain represent concentrated demand pockets.
- Patients:Chronic snorers and mild sleep apnea sufferers seek clinical validation through FDA-cleared or CE-marked devices. Sleep clinics in the Netherlands and respiratory therapy centers in Switzerland drive prescription volume.
- Healthcare Professionals:ENT specialists and sports medicine physicians specify dilators for nasal valve collapse or athletic performance protocols. Procurement through hospital systems in the United States requires ISO 13485 documentation.
- General Consumers:Occasional users responding to seasonal allergies or temporary congestion favor low-commitment adhesive strips. Pharmacy impulse purchases in Japan and convenience store sales in South Korea sustain this segment.
Patient-directed therapeutic use anchors current revenue; athlete-centric performance optimization is climbing the fastest.
Distribution Channel:
Channel selection determines whether manufacturers absorb retail margin compression or invest in direct relationship infrastructure with end users.
- Pharmacies:Regulated medical device positioning requires pharmacist consultation in Germany and France, filtering out unbranded competitors. Boots and CVS chains maintain dedicated respiratory aid sections.
- Online Stores:Direct-to-consumer platforms bypass retail markup while enabling subscription models for reusable dilator consumables. Amazon and specialized athletic equipment sites capture growing share among digitally native users.
- Supermarkets:Economy-tier single-use strips rely on high-visibility placement in health and wellness aisles. Tesco and Walmart distribution demands aggressive slotting fee negotiations.
- Specialty Stores:Running shops and cycling retailers provide educated staff recommendation for performance-oriented reusable variants. REI and Decathlon locations in the United States and Europe concentrate athletic-segment volume.
Pharmacy dominance persists in regulated markets; online expansion is gaining share fastest among reusable product adopters.
Material:
Raw material selection governs biocompatibility certification pathways, dermatological tolerance profiles, and unit economics across manufacturing scales.
- Silicone:Platinum-cured medical-grade formulations enable repeated-use durability and hypoallergenic positioning. FDA and TGA clearance for reusable devices in the United States and Australia mandates this substrate.
- Plastic:Injection-molded substrates with adhesive lamination dominate single-use strip production through cost minimization. REACH compliance for phthalate-free formulations pressures European manufacturers.
- Rubber:Latex and synthetic elastomer variants occupy mid-tier positioning with limited regulatory traction due to allergy concerns. Niche presence in emerging markets with less stringent biocompatibility requirements.
- Foam:Pressure-sensitive adhesive foams serve economy-tier disposable segments with minimal spring-steel integration. Limited clinical validation restricts expansion beyond casual consumer trial.
Plastic substrates anchor mass-market volume; silicone formulations show the steepest expansion trajectory among certified reusable devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentive schemes for medical device manufacturing are redrawing production maps and channel access across major consumption centers. Fiscal support for domestic silicone molding capacity and streamlined regulatory pathways are concentrating investment in select jurisdictions.
United States
FDA Class I 510(k) exemption pathways enable rapid market entry for mechanical nasal dilators compared to pharmaceutical alternatives. Sleep medicine clinics in California and respiratory therapy centers in Massachusetts drive prescription-channel adoption of reusable variants. Telehealth bundling models in Texas and Florida are bypassing traditional pharmacy distribution for direct-to-consumer sales.
Germany
Pharmacy consultation requirements for regulated medical devices filter out unbranded competitors and sustain premium positioning for ISO 13485-certified manufacturers. EU MDR recertification timelines under 2017/745 are compressing legacy product portfolios. Industrial clusters in Bavaria and Baden-Württemberg host specialized adhesive formulation and spring-steel fabrication suppliers serving reusable dilator producers.
Australia
TGA pre-market notification structures parallel FDA oversight and enable therapeutic indication claims for biocompatibility-tested devices. Endurance sports participation rates in Victoria and New South Wales support athletic-segment demand for gram-calibrated spring force dilators. Melbourne-based sleep clinics are piloting sensor-integrated reusable variants with Bluetooth-connected analytics.
India
Production Linked Incentive schemes for medical devices offer tariff advantages for manufacturers establishing domestic silicone molding and adhesive lamination capacity. CDSCO medical device rules are gradually aligning with international quality management standards. Industrial corridors in Maharashtra and Gujarat are attracting contract manufacturing investment from export-oriented dilator brands.
Japan
PMDA oversight maintains stringent biocompatibility documentation requirements that favor established manufacturers with dedicated regulatory affairs functions. METI initiatives for digital health integration are creating pilot opportunities for sensor-equipped reusable dilators. Pharmacy chains in Tokyo and Osaka maintain dedicated respiratory aid sections with pharmacist consultation protocols.
External Nasal Dilator Market Competitive Landscape
Player mix skews toward mid-cap specialists with dedicated regulatory affairs infrastructure and diversified healthcare conglomerates leveraging consumer health distribution networks. Market structure concentrates volume with manufacturers maintaining ISO 13485 certification and FDA establishment registration, displacing informal physician preference-based ordering. Strategic archetypes include quality-certified specialists, consumer health portfolio players, and contract manufacturing scale operators. Competitive moves center on M&A for regulatory asset acquisition and capacity expansion into PLI-advantaged jurisdictions.
Within the quality-certified specialist tier, Rhinomed Limited and Splintek Inc exemplify positioning strategies built on proprietary design differentiation and manufacturing scale control respectively. GlaxoSmithKline Plc anchors the consumer health portfolio archetype, leveraging established pharmacy shelf presence across multiple continents. Tomed GmbH represents European-based fabrication with regulatory alignment to EU MDR requirements. Zhongshan Hongze Medical Technology Co., Ltd. occupies contract manufacturing scale positioning with access to Asia-Pacific production cost structures.
| Leading Market Players |
|---|
| GlaxoSmithKline Plc |
| HealthRight Products LLC |
| Splintek Inc |
| Rhinomed Limited |
| AirWare Labs |
| Tomed GmbH |
| Zhongshan Hongze Medical Technology Co., Ltd. |
| McKeon Products Inc. |
| Scandinavian Formulas |
| Others |
Supply & Pricing Matrix
Platinum-cured medical-grade silicone substitution for acrylate-based adhesives is simultaneously shifting production geography toward India and Germany while compressing margin structures for economy-tier strip manufacturers. This material transition concentrates pricing power with ISO 13485-certified producers capable of absorbing biocompatibility validation costs, while private-label suppliers face exit pressure from REACH compliance deadlines.
Pricing Analysis
Certification level (ISO 13485/FDA establishment registration/CE marking under EU MDR) creates the primary spread between premium reusable dilators and commodity adhesive strips. Three-tier pricing structure separates prescription-channel custom-fit devices from pharmacy-grade reusable variants and supermarket economy strips. Pricing pressure stems from raw material volatility in platinum-cured silicone, with athletic users showing least price sensitivity and general consumers in mass-market channels exhibiting highest elasticity.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are extending lead times for spring-steel band imports and adhesive laminate shipments. Manufacturing concentrates in China for plastic substrate molding, Germany for precision spring fabrication, and India for silicone molding under PLI scheme advantages. Supply chain risk centers on single-source dependency for medical-grade silicone feedstock. Distribution runs through pharmacy chains in regulated markets and direct-to-consumer platforms for athletic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is emerging from a cyclical trough driven by EU MDR recertification completion, with compliance-ready manufacturers positioned to capture displaced legacy volume.
For Market Incumbents: Compound regulatory asset advantages by accelerating ISO 10993 biocompatibility documentation for reusable silicone variants before smaller competitors complete retesting. Prioritize backward integration into platinum-cured silicone compounding to offset raw material volatility threatening margin stability in premium athletic segments. For New Entrants and Emerging Players: Anchor in telehealth bundling opportunities with sleep apnea screening platforms, where direct-to-consumer channels bypass entrenched pharmacy distribution controlled by GlaxoSmithKline and established consumer health portfolios. Target athletic specialty retailers in Australia and Germany with gram-calibrated spring force positioning. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors quality-certified specialists with dedicated regulatory affairs functions over undifferentiated contract manufacturers. Long-term viability hinges on sensor integration and subscription analytics platforms. Watch FDA OTC classification debates as the critical inflection signal for retail access expansion or prescription-level scrutiny.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Opens regulated pharmacy channels in Germany, France, and Australia for therapeutic claims. |
| 3D Scanning Integration | Enables premium custom-fit positioning through smartphone-based nasal architecture capture. |
| Sensor-Equipped Product Development | Creates recurring revenue streams via Bluetooth-connected respiratory analytics subscriptions. |
| India PLI Scheme Manufacturing Footprint | Delivers tariff advantages for domestic silicone molding and adhesive lamination capacity. |
| Telehealth Platform Partnership | Bypasses traditional pharmacy distribution through sleep clinic diagnostic kit bundling. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, and TGA pre-market notification databases. Interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and athletic equipment procurement leads informed demand-side validation. Secondary sources include customs trade records, ISO certification registries, and hospital procurement databases. Bottom-up volume estimates triangulated against top-down market sizing across product architecture segments.
Segmentation dimensions modeled include product type (single-use, reusable, custom-fit, over-the-counter), end user (athletes, patients, healthcare professionals, general consumers), distribution channel, and material substrate. CAGRs derived from regression analysis of historical volume trends against regulatory milestone timing and athletic participation rate projections. Industry-specific inputs incorporated spring-steel fatigue testing protocols and biocompatibility validation timelines.
Decision-makers should treat outputs as directional under assumptions of stable FDA Class I classification and continued EU MDR enforcement without therapeutic indication expansion; material deviation would warrant model refresh. Specific risks include internal nasal stent substitution acceleration, adhesive dermatitis litigation, and REACH reformulation cost absorption failures. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Gynecological Devices Market
Medical Devices
Global Smart Implantable Pumps Market
Medical Devices
Medical Radiation Detectors Market
Medical Devices
Global Healthcare Nanotechnology (Nanomedicine) Market
Medical Devices
Global Ureteroscopes Market
Medical Devices
Auto-Transfusion Systems Market
Medical Devices
GCC Biopsy Devices Market
Medical Devices
Biodegradable Stents Market
Medical Devices
Europe Viscosupplementation Market
Medical Devices
Infertility Devices Market
Medical Devices
Ehealth Devices Market
Medical Devices
Arteriovenous Fistula Devices Market
Medical Devices
Digital Sphygmomanometer Market
Medical Devices
Baby Thermometer Market
Medical Devices
Intravascular Warming Systems Market
Medical Devices
3D Printing for Surgical Procedures Market