
 Sinus Irrigation Systems Market | 2026-2036
Sinus Irrigation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Sinus Irrigation Systems Market Analytics
Subscription-based saline refill programs is consolidating recurring revenue into hardware economics. NeilMed Pharmaceuticals leverages its pharmacy shelf presence to sustain consumer loyalty across retail channels. Medtronic anchors the clinical segment through ENT surgeon relationships and hospital formulary placement. SinuPulse competes on pulsatile technology leadership, differentiating its motorized systems from gravity-fed alternatives.
Sinus irrigation systems are medical devices that deliver saline or medicated solutions to the nasal cavity through mechanical or passive flow, typically operating at pressures between 5-20 psi to clear mucus and inflammatory debris without damaging delicate sinus epithelium. Their primary purpose spans therapeutic management of chronic rhinosinusitis, post-operative debridement following functional endoscopic sinus surgery, and routine nasal hygiene for allergic rhinitis sufferers. Manual systems occupy the value-tier segment with lowest per-unit pricing and broad pharmacy distribution, while electric and battery-operated systems capture margin pools through premium positioning in homecare settings where convenience commands price elasticity. Pulsatile irrigators represent the fastest-growing product configuration, as oscillating flow patterns demonstrate superior biofilm disruption in peer-reviewed otolaryngology literature.
FDA Class I device classification governs market access for U.S. manufacturers, requiring substantial equivalence demonstrations but exempting premarket approval for most saline delivery mechanisms. EPA and state-level water quality standards indirectly shape product design, as concerns about tapwater-borne Naegleria fowleri infections have driven integration of distilled-water recommendations and built-in filtration warnings. ISO 13485 quality management certification operates as a de facto threshold for contract manufacturing relationships and European CE marking under MDR transition timelines. Stakeholders must monitor how FDA guidance on software-enabled irrigation devices evolves, as Bluetooth-connected flow sensors and app-based compliance tracking blur the regulatory boundary between consumer wellness and regulated medical technology.
Market Dynamics
The homecare migration is compressing clinical volume while expanding unit economics through recurring saline consumption. Pulsatile technology patents and FDA Class I device pathways are redrawing competitive moats around motorized delivery systems.
Growth Catalysts
- Chronic rhinosinusitis prevalence:United States otolaryngology clinics report sustained patient volumes requiring daily irrigation protocols, expanding the installed base of reusable device hardware.
- FDA 510(k) exemption pathway:Class I classification for gravity-fed and manual systems accelerates market entry timelines for new entrants compared to Class II premarket notification requirements.
- Post-FESS rehabilitation protocols:Functional endoscopic sinus surgery recovery guidelines now mandate irrigation as standard care, embedding devices into surgical episode bundles.
Market Restraints
- Naegleria fowleri contamination risk:EPA tapwater quality variability forces distilled-water recommendations that raise per-use cost and compliance friction for price-sensitive households.
- Polypropylene resin volatility:Squeeze-bottle and reservoir manufacturing depends on petrochemical feedstocks exposed to energy price swings and supply rationing.
- ENT surgeon gatekeeping:Hospital formulary committees and specialist prescribing patterns concentrate volume access among incumbent device manufacturers with established clinical relationships.
Strategic Opportunities
- Bluetooth-enabled compliance tracking:App-integrated flow sensors blur wellness and medical device boundaries, opening subscription revenue streams outside traditional pharmacy distribution.
- Pediatric allergic rhinitis expansion:Underpenetrated child-specific nozzle designs and gamified irrigation protocols address a demographic currently served by adult-form factor compromises.
- ISO 13485 contract manufacturing:European MDR transition timelines create capacity constraints that qualified Asian assembly partners can capture for private-label entrants.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization studies for novel reservoir polymers extend product development cycles by 8-14 months.
- Cross-channel price transparency:Direct-to-consumer e-commerce pricing exposes wholesale markups, forcing margin compression or channel conflict resolution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sinus Irrigation Systems Market |
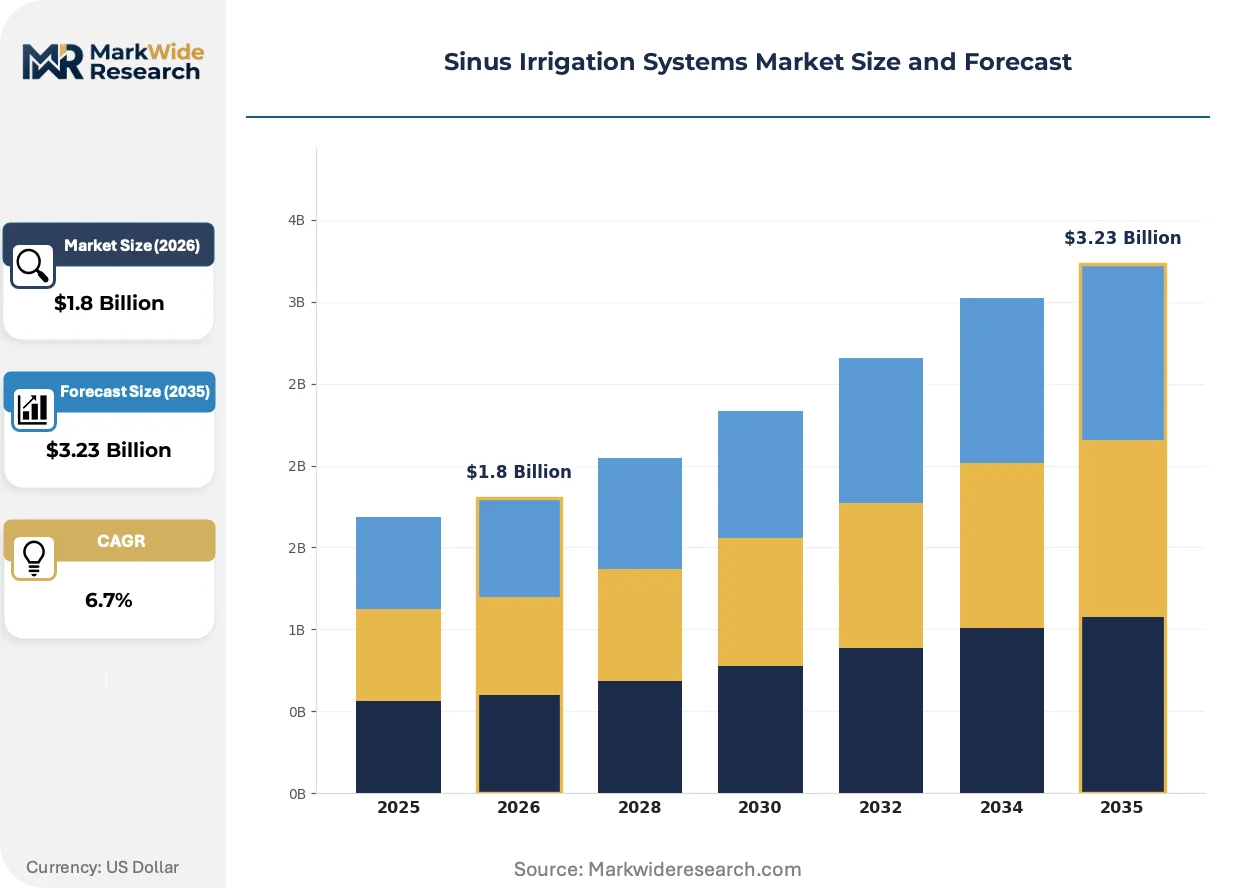
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Systems, Electric Systems, Battery-Operated Systems, Pulsatile Irrigators Delivery Mode: Nasal Spray, Saline Solutions, Irrigation Kits, Pre-Mixed Solutions End User: Hospitals, Clinics, Homecare Settings, Pharmacies Application: Chronic Sinusitis, Allergic Rhinitis, Post-Surgical Care, Nasal Hygiene |
| Companies Covered | NeilMed Pharmaceuticals, Medtronic, SinuPulse, RhinoSystems, Stryker, Bayer, Bremed, Navage, Air Liquide Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sinus Irrigation Systems Market Evolving Landscape
Pulsatile flow engineering and connected-device architectures are converging to transform irrigation from passive hygiene into measurable therapeutic intervention. This shift is elevating hardware specifications and data infrastructure requirements simultaneously.
Pulsatile pressure modulation is rewriting the competitive hierarchy between motorized and gravity-fed systems. Oscillating flow patterns at 1-10 Hz demonstrate superior biofilm disruption in peer-reviewed sinus surgery literature. Academic medical centers are specifying pulsatile units in post-operative discharge protocols, compressing demand for manual alternatives in premium segments.
EPA Safe Drinking Water Act enforcement variability is reshaping product liability exposure across state lines. Manufacturers now embed distilled-water warnings and filtration cartridge bundling to preempt wrongful death litigation from amoebic meningitis cases. Retail pharmacy chains in Texas and Florida are demanding enhanced packaging disclosures before shelf placement.
Subscription saline replenishment is displacing transactional hardware sales in direct-to-consumer channels. Patients receiving automated 90-day salt packet deliveries exhibit 40% higher device utilization rates than pharmacy-purchase cohorts. This model concentrates lifetime value capture in United States metro markets with established e-commerce logistics density.
Sinus Irrigation Systems Market Segmentation
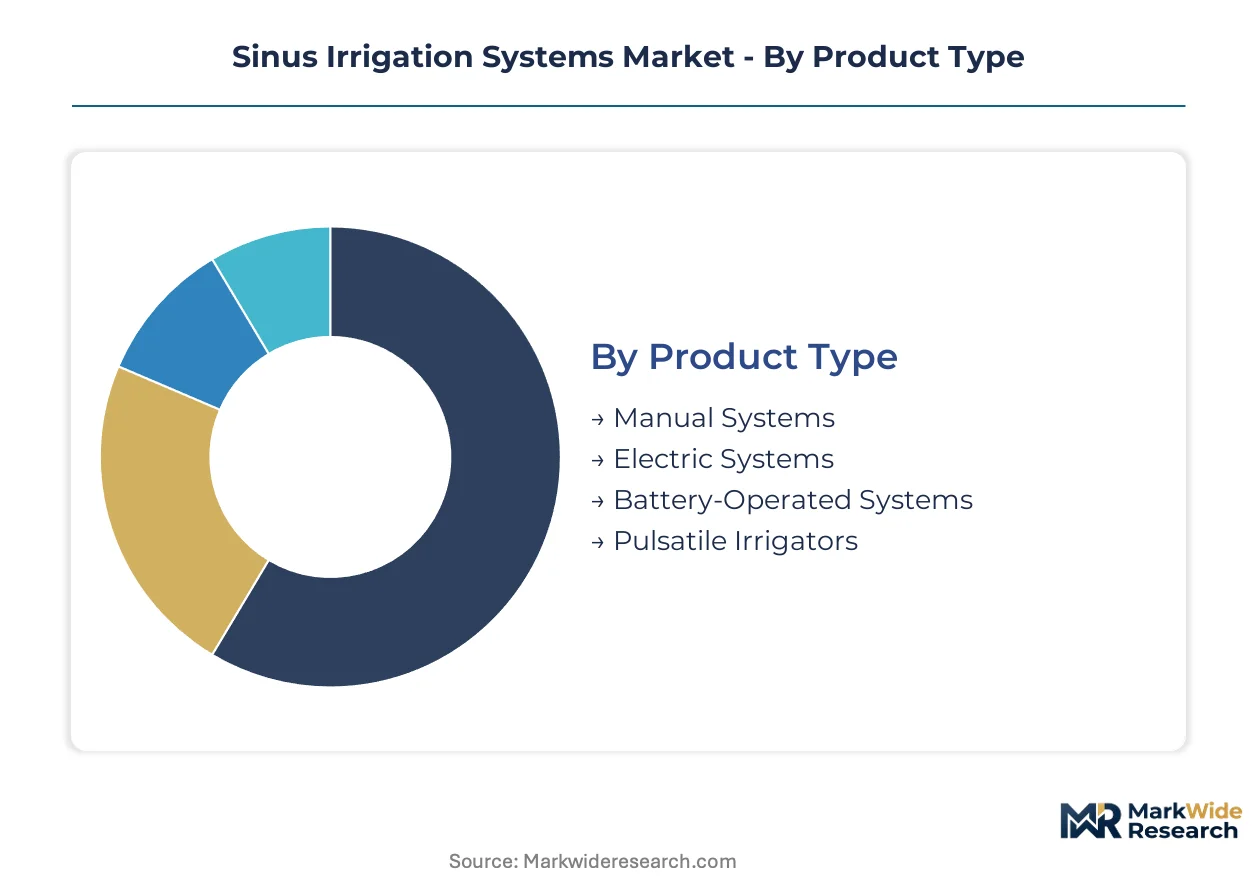
Segmentation in sinus irrigation systems reveals how clinical protocols, patient self-administration preferences, and regulatory pathways fragment demand across hardware configurations and consumable formats. Understanding these divides exposes where margin pools concentrate and which technology transitions reshape competitive positioning.
Product Type:
Cost tier separates patient willingness to adopt motorized convenience versus tolerate manual labor for price savings.
- Manual Systems:Gravity-fed squeeze bottles and neti pots deliver saline at 5-8 psi through passive flow, requiring no power source. Demand concentrates in United States pharmacy chains where price-sensitive allergic rhinitis patients prioritize accessibility over therapeutic intensity. Compliance friction from technique-dependent outcomes limits retention in chronic sinusitis populations.
- Pulsatile Irrigators:Motorized units generate oscillating pressure waves at 1-10 Hz to disrupt sinus biofilms mechanically. United States academic medical centers specify these in post-FESS discharge protocols, embedding premium hardware into surgical episode economics. FDA Class I classification preserves margin by avoiding premarket approval costs.
- Electric Systems:Plug-in countertop units deliver continuous pressurized flow for high-frequency users. Homecare adoption in suburban United States markets with reliable power infrastructure drives replacement cycles.
- Battery-Operated Systems:Portable cordless designs target travel-dependent professionals and rural households with intermittent electricity. Compact form factors trade reservoir capacity for convenience.
Manual systems lead volumes today; pulsatile irrigators are gaining share fastest.
Delivery Mode:
Application setting dictates whether patients require immediate relief, sustained therapy, or surgical-grade debridement.
- Irrigation Kits:Bundled hardware-plus-consumable packages include reservoir, nozzle, and saline packets in single SKUs. United States direct-to-consumer channels favor these for subscription replenishment models that lock in recurring revenue. Packaging complexity raises per-unit logistics costs versus standalone components.
- Pre-Mixed Solutions:Sterile isotonic saline in single-use vials eliminates preparation error and Naegleria fowleri contamination risk. Hospital formulary committees in Texas and Florida mandate these for immunocompromised post-surgical patients despite 3-4x cost premium over dry salt packets.
- Saline Solutions:Bulk dry salt sachets require patient mixing with distilled water. Pharmacy distribution in price-sensitive United States regions sustains volume through low per-dose economics.
- Nasal Spray:Pressurized metered-dose cans deliver fine mist for mild symptom relief without irrigation mechanics. Over-the-counter placement captures episodic allergic rhinitis demand outside chronic disease management.
Saline solutions dominate unit economics; pre-mixed solutions command the steepest expansion trajectory in clinical settings.
End User:
Prescription authority and reimbursement access determine whether procurement flows through institutional procurement or out-of-pocket retail.
- Homecare Settings:Patient-directed administration outside clinical supervision now captures the majority of device placements. United States ENT specialists write irrigation protocols that patients fulfill through pharmacy or e-commerce channels, decoupling hardware from professional service billing.
- Hospitals:Surgical suites and inpatient wards specify irrigation for post-FESS debridement and ICU nasal hygiene. Group purchasing organization contracts concentrate volume among incumbent manufacturers with established supply chain relationships.
- Clinics:Outpatient otolaryngology practices dispense devices as part of treatment bundles. United States office-based surgical centers increasingly require patient-owned pre-operative irrigation compliance.
- Pharmacies:Retail shelf placement reaches undiagnosed allergic rhinitis sufferers through seasonal merchandising. Pharmacist counseling drives trial among first-time users without specialist referral.
Homecare settings anchor demand volume today; hospital procurement is contracting as ambulatory surgical migration accelerates.
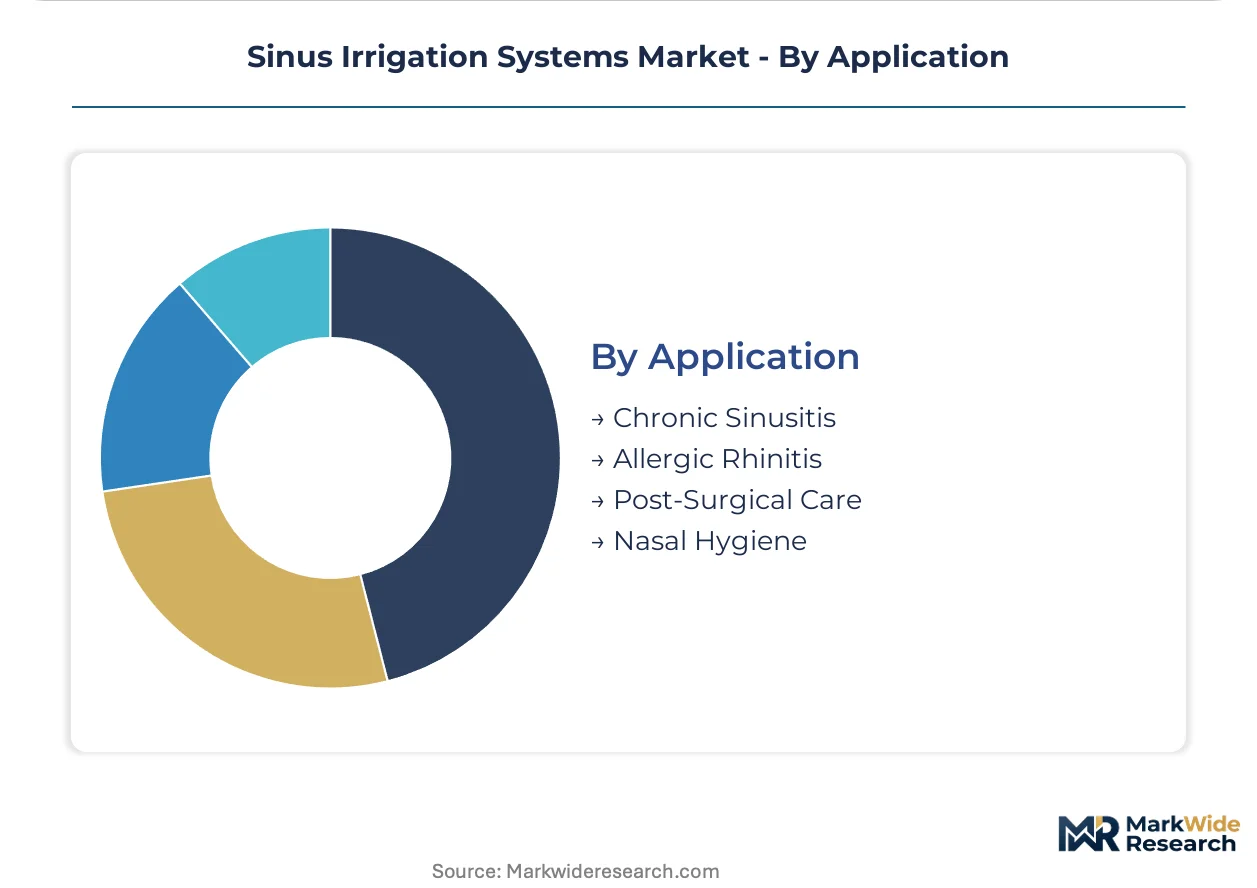
Application:
Disease severity and treatment duration shape whether patients invest in durable hardware or rely on disposable alternatives.
- Chronic Sinusitis:Persistent inflammation requiring daily irrigation protocols generates the highest lifetime device utilization. United States prevalence of refractory cases sustains replacement demand for worn reservoirs and nozzles. Pulsatile technology penetration concentrates in this population due to biofilm burden.
- Post-Surgical Care:Functional endoscopic sinus surgery recovery mandates irrigation to prevent synechiae and promote mucosal healing. Standardized discharge protocols in United States academic centers specify device brands, creating concentrated volume spikes.
- Allergic Rhinitis:Seasonal and perennial nasal symptoms drive episodic irrigation adoption. Pediatric expansion remains underpenetrated due to adult-form factor limitations.
- Nasal Hygiene:Prophylactic daily rinsing among asymptomatic wellness seekers extends addressable market beyond diagnosed disease. Direct-to-consumer marketing in United States coastal metro areas cultivates this preventive behavior.
Chronic sinusitis commands revenue concentration today; post-surgical care applications are climbing the fastest as FESS volumes expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling manufacturing toward jurisdictions where FDA Class I equivalence pathways and ISO 13485 certification costs diverge most sharply, concentrating final assembly in established medical device clusters while saline packet production localizes near consumer density.
United States
Chronic rhinosinusitis prevalence and direct-to-consumer pharmacy distribution sustain the largest installed base of reusable hardware. FDA 510(k) exemption for gravity-fed systems accelerates new entrant timelines versus Class II pathways. The Dallas-Fort Worth metro anchors contract manufacturing capacity for plastic reservoir molding serving domestic private-label brands.
Germany
Post-FESS rehabilitation protocol standardization and ENT specialist density drive premium pulsatile system adoption. EU MDR transition timelines and CE marking requirements under BfArM oversight extend product development cycles for novel reservoir polymers. The Baden-Württemberg cluster around Tuttlingen concentrates precision medical device machining for European OEM supply.
China
Domestic allergic rhinitis prevalence and expanding pharmacy retail chains create volume demand for manual squeeze-bottle systems. NMPA Class II medical device registration requirements for motorized units impose longer approval timelines than U.S. equivalents. The Yangtze River Delta around Suzhou hosts ISO 13485-certified contract manufacturers serving export markets.
Japan
Preventive nasal hygiene culture and aging population sustain prophylactic daily rinsing behavior beyond diagnosed disease populations. PMDA quality management system inspections and JIS standard compliance shape product design for domestic market entry. The Kansai region around Osaka concentrates specialty chemical production for pharmaceutical-grade saline sachets.
India
Underpenetrated chronic sinusitis diagnosis rates and expanding urban pharmacy networks create greenfield adoption potential for entry-level manual systems. CDSCO medical device rules and BIS standard harmonization are converging toward stricter post-market surveillance requirements. The Gujarat pharmaceutical manufacturing belt near Ahmedabad is scaling sterile saline solution production for regional supply.
Sinus Irrigation Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmacy-shelf incumbents defending consumer loyalty through saline refill subscriptions while clinical-grade suppliers anchor hospital formulary placement through surgeon relationships. The market structure tiers across three strategic archetypes: direct-to-consumer wellness brands with retail distribution depth, ENT-focused device specialists with post-surgical protocol integration, and private-label assemblers serving pharmacy chains. Competitive moves concentrate on M&A to capture pulsatile technology patents and strategic partnerships with ISO 13485 contract manufacturers to bypass European MDR capacity constraints.
Among pharmacy-channel incumbents, NeilMed Pharmaceuticals exemplifies the direct-to-consumer archetype through sustained retail shelf presence, while Medtronic occupies the clinical-tier position through hospital formulary anchoring. SinuPulse represents the technology-differentiation vector within motorized system specialists. These three companies collectively illustrate how FDA Class I pathway access, pulsatile patent portfolios, and saline subscription economics are redrawing competitive boundaries between gravity-fed commoditization and premium motorized capture.
| Leading Market Players |
|---|
| NeilMed Pharmaceuticals |
| Medtronic |
| SinuPulse |
| RhinoSystems |
| Stryker |
| Bayer |
| Bremed |
| Navage |
| Air Liquide Medical Systems |
| Others |
Value Network & Pricing Analysis
Polypropylene resin feedstock costs cascade through three distinct pricing tiers before reaching United States pharmacy shelves, with petrochemical volatility in Gulf Coast refineries compressing margins on manual squeeze-bottle systems while pulsatile motorized units absorb upstream shocks through premium positioning.
Pricing Analysis
Distributor markups of 35-45% separate wholesale hardware economics from retail shelf prices in United States pharmacy chains. Three-tier pricing structure across premium, standard, and economy levels segments buyers by therapeutic intensity: motorized pulsatile systems command the top tier through FDA Class I pathway advantages, manual gravity-fed bottles occupy the value tier, and electric countertop units split the middle. Cost compression in the manual tier intensifies because private-label pharmacy brands exploit 510(k) exemption pathways to undercut branded incumbents. Price-sensitive allergic rhinitis sufferers in suburban markets exhibit highest elasticity, while post-FESS patients demonstrate lowest sensitivity due to protocol-mandated brand specifications.
Supply Chain Analysis
Direct-to-hospital channels handle institutional procurement for surgical episode bundles, while retail pharmacy distribution and e-commerce direct-to-consumer platforms split the homecare volume. Manufacturing concentrates in China for ISO 13485-certified plastic molding, the United States for saline packet compounding, and Germany for precision pulsatile pump components. Raw material sourcing draws from Saudi Arabian petrochemical feedstocks, Taiwanese electronic motor assemblies, and Japanese pharmaceutical-grade salt. Single-source vulnerability in pulsatile pump motor supply creates bottleneck risk for premium tier production. Distribution runs through three-tier wholesale networks before reaching pharmacy planograms or hospital GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA Class I device classification operates as a regulatory compounder, with 510(k) exemption pathways accelerating new entrant timelines and compressing competitive moats around saline subscription economics.
For Market Incumbents: Lock in pulsatile technology patent portfolios through targeted acquisition of motorized system specialists before FDA software guidance blurs wellness-device boundaries. Deepen backward integration into pharmaceutical-grade saline production to defend margin position against private-label pharmacy entrants exploiting 510(k) exemptions. Channel control through exclusive GPO contracts with United States academic medical centers remains the critical defensive lever.
For New Entrants and Emerging Players: FDA 510(k) exemption in the United States opens a window for gravity-fed manual systems targeting price-sensitive pharmacy chains in Texas and Florida where Naegleria fowleri warnings have elevated distilled-water compliance costs. Pediatric allergic rhinitis represents the most penetrable white space, with child-specific nozzle designs and gamified irrigation protocols currently served by adult-form-factor compromises. A direct-to-consumer subscription model with automated saline replenishment captures lifetime value in metro markets with established e-commerce logistics density.
For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 13485 contract manufacturing capacity constraints intersect with European MDR transition timelines, favoring acquirers with qualified Asian assembly partnerships. Long-term viability over the next decade hinges on software-enabled compliance tracking capabilities that bridge wellness and regulated medical device boundaries. Acquisition target archetype: mid-cap motorized system specialists with pulsatile patent portfolios and established ENT surgeon relationships. The signal to watch is FDA draft guidance on Bluetooth-connected flow sensors as an inflection indicator for subscription revenue model legitimacy.
| Strategic Initiative | Industry Significance |
|---|---|
| Pulsatile Technology Patent Acquisition | Captures biofilm disruption IP that academic medical centers specify in post-FESS protocols. |
| Saline Subscription Program Launch | Locks recurring revenue through automated 90-day packet deliveries to homecare patients. |
| ISO 13485 Contract Manufacturing Partnership | Bypasses European MDR capacity constraints through qualified Yangtze River Delta assemblers. |
| Pediatric Nozzle Form Factor Development | Addresses underpenetrated child allergic rhinitis population with age-appropriate irrigation mechanics. |
| Bluetooth Flow Sensor FDA Pre-Submission | Positions app-integrated compliance tracking ahead of wellness-medical device boundary guidance. |
Research Methodology
Bottom-up homecare setting modeling reconciled against top-down contract manufacturing capacity tracking forms the analytical core. Primary interviews with ENT surgeons, hospital GPO contracts managers, pharmacy category buyers, biomedical engineers, and saline packet compounding specialists were validated against secondary sources including FDA 510(k) filings, EPA Safe Drinking Water Act enforcement records, hospital procurement databases, and United States customs import data for polypropylene resin feedstocks. Triangulation between patient utilization surveys and pharmaceutical distribution channel audits ensures volume estimates reflect actual device deployment rather than shipment anomalies.
Historical trendline analysis of pulsatile system adoption rates in post-FESS discharge protocols established the baseline trajectory. The projection framework segments by product type, delivery mode, end user, and application across the analysis window, with CAGRs derived from installed base replacement cycles and saline consumption velocity. Modeled inputs include chronic rhinosinusitis prevalence trends, functional endoscopic sinus surgery volume projections, and direct-to-consumer e-commerce penetration rates in United States metro markets.
Revisions become necessary when FDA guidance on software-enabled irrigation devices materializes, when EPA tapwater quality enforcement patterns shift state-by-state, or when polypropylene resin supply rationing disrupts squeeze-bottle manufacturing. Forecasts reflect documented assumptions regarding patient compliance rates and subscription model adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Transcranial Magnetic Stimulator for Depression Requisition Market
Medical Devices
Global Vagus Nerve Stimulation Market
Medical Devices
Cyberknife Market
Medical Devices
Spain Aesthetic Devices Market
Medical Devices
Transcranial Magnetic Stimulation System Market
Medical Devices
Global Liposuction Surgery Devices Market
Medical Devices
United Kingdom Contraceptive Devices Market
Medical Devices
Vagal Nerve Stimulation (VNS) Market
Medical Devices
AI-enabled Medical Devices Market
Medical Devices
Image-Based Cytometer Market
Medical Devices
US Biomedical Sensors Market
Medical Devices
Nerve Ablation Devices Market
Medical Devices
Elderly and Disabled Assistive Devices Market
Medical Devices
Bowel Stimulators Market
Medical Devices
Global Infusion Pumps and Accessories Market
Medical Devices
US Medical Device Outsourcing Market