
 Bone Densitometer Devices Market | 2026-2036
Bone Densitometer Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Densitometer Devices Market Analysis
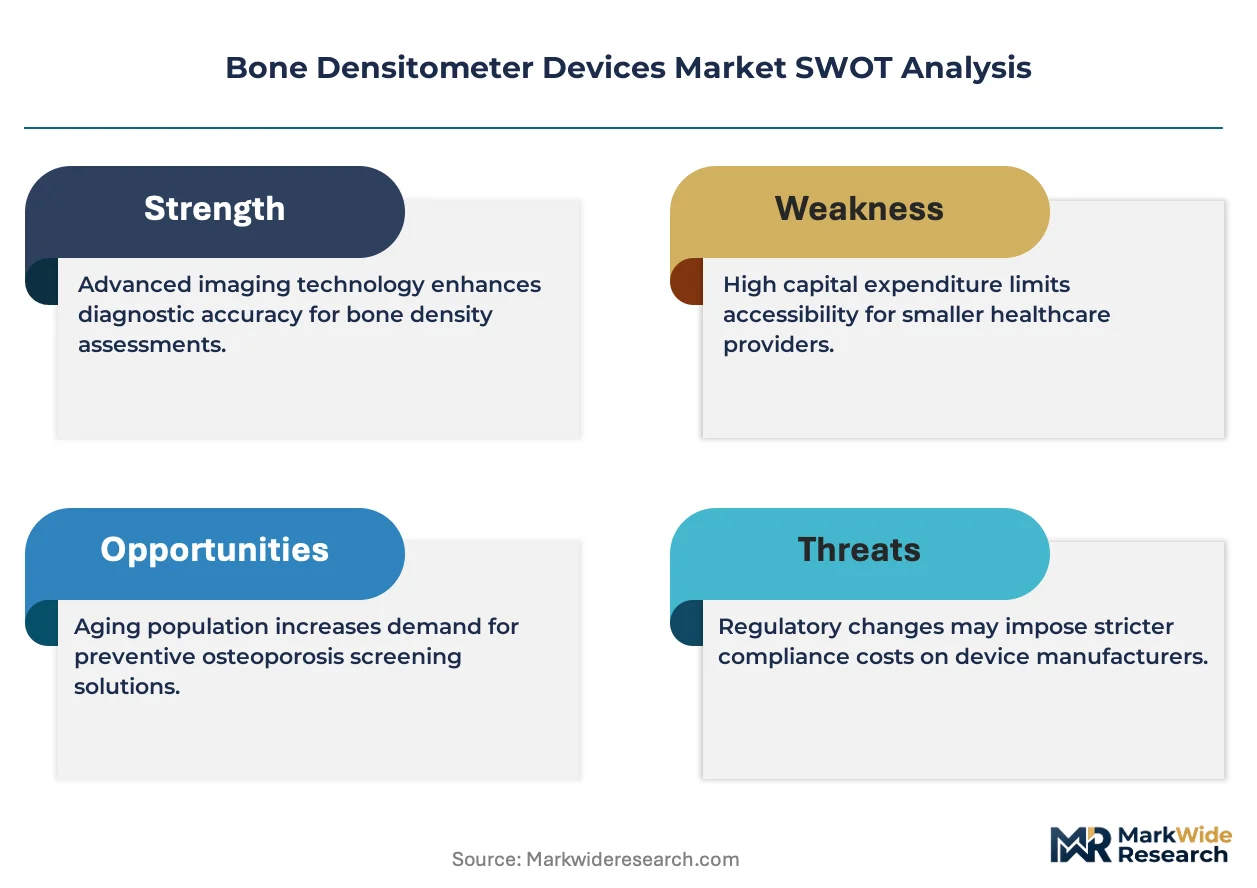
MDR compliance in Europe is recalibrating the cost-of-entry calculus for bone densitometer manufacturers seeking CE marking. Hologic Inc. leverages its installed base of DXA systems to sustain service revenue across North American hospital networks. GE Healthcare anchors its position through integrated imaging platforms that bundle densitometry with broader musculoskeletal diagnostics. Echolight S.p.A. differentiates via radiation-free ultrasound technology that targets outpatient clinic expansion.
Bone densitometer devices quantify bone mineral density using ionizing or acoustic energy to assess skeletal integrity and fracture probability. Dual-energy X-ray absorptiometry systems typically operate at 70-140 kVp with precision errors below 1%, enabling longitudinal tracking of osteoporosis progression. DEXA systems occupy the mature revenue core while software-driven analytics represent the fastest-expanding margin pool as artificial intelligence enhances fracture risk stratification. Ultrasound densitometers compete on portability and capital efficiency for primary care deployment.
FDA 510(k) pathways, MDR technical documentation requirements, and ISO 13485 quality management standards collectively govern market access and post-market surveillance obligations. The EPA regulates radioactive source handling for DXA systems containing sealed sources, adding compliance layers to equipment lifecycle management. Stakeholders must monitor reimbursement coding revisions for bone density testing as payors tighten prior authorization criteria.
Market Dynamics
MDR technical documentation requirements are recalibrating the cost-of-entry calculus for bone densitometer manufacturers seeking CE marking in Europe. The regulatory burden is compressing margins while simultaneously accelerating consolidation among smaller device producers unable to sustain compliance investments.
Growth Catalysts
- Aging demographics in Germany:Reimbursement clarity for bone mineral density testing drives clinical adoption across hospital networks and outpatient clinics. The statutory health insurance framework removes payment uncertainty that previously delayed equipment procurement cycles.
- Dual-energy X-ray absorptiometry technology:DXA systems replace older screening methods in United States hospital networks as precision errors below 1% enable longitudinal osteoporosis tracking. The technology's diagnostic reliability supports expanded screening protocols.
- FDA quality standards:Updated diagnostic imaging equipment requirements reshape manufacturer compliance obligations, elevating barriers for low-quality entrants and protecting established players with robust quality management systems.
Market Restraints
- Sealed source handling costs:EPA regulations governing radioactive source management for DXA systems add compliance layers to equipment lifecycle management, inflating total cost of ownership beyond initial capital expenditure.
- Ultrasound densitometer substitution:Radiation-free acoustic technology competes aggressively on portability and capital efficiency for primary care deployment, pressuring ionizing-radiation system pricing.
- Prior authorization tightening:United States payors constrict reimbursement coding criteria for bone density testing, elongating revenue recognition cycles and dampening replacement demand from cost-sensitive providers.
Strategic Opportunities
- Artificial intelligence analytics:Software-driven fracture risk stratification represents the fastest-expanding margin pool as machine learning enhances diagnostic interpretation beyond raw density measurements.
- Outpatient clinic channel expansion:Echolight's radiation-free ultrasound technology targets ambulatory settings previously inaccessible to X-ray-based systems, unlocking primary care penetration.
- Integrated imaging platforms:Bundling densitometry with broader musculoskeletal diagnostics creates stickier hospital relationships and defends service revenue streams across North American networks.
Industry Challenges
- ISO 13485 quality management implementation:Small manufacturers struggle to document design controls and risk management files sufficient for FDA 510(k) clearance and MDR technical documentation.
- Legacy system integration complexity:Hospital information system connectivity requirements for DXA data exchange demand specialized software engineering capabilities scarce among traditional device engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Densitometer Devices Market |
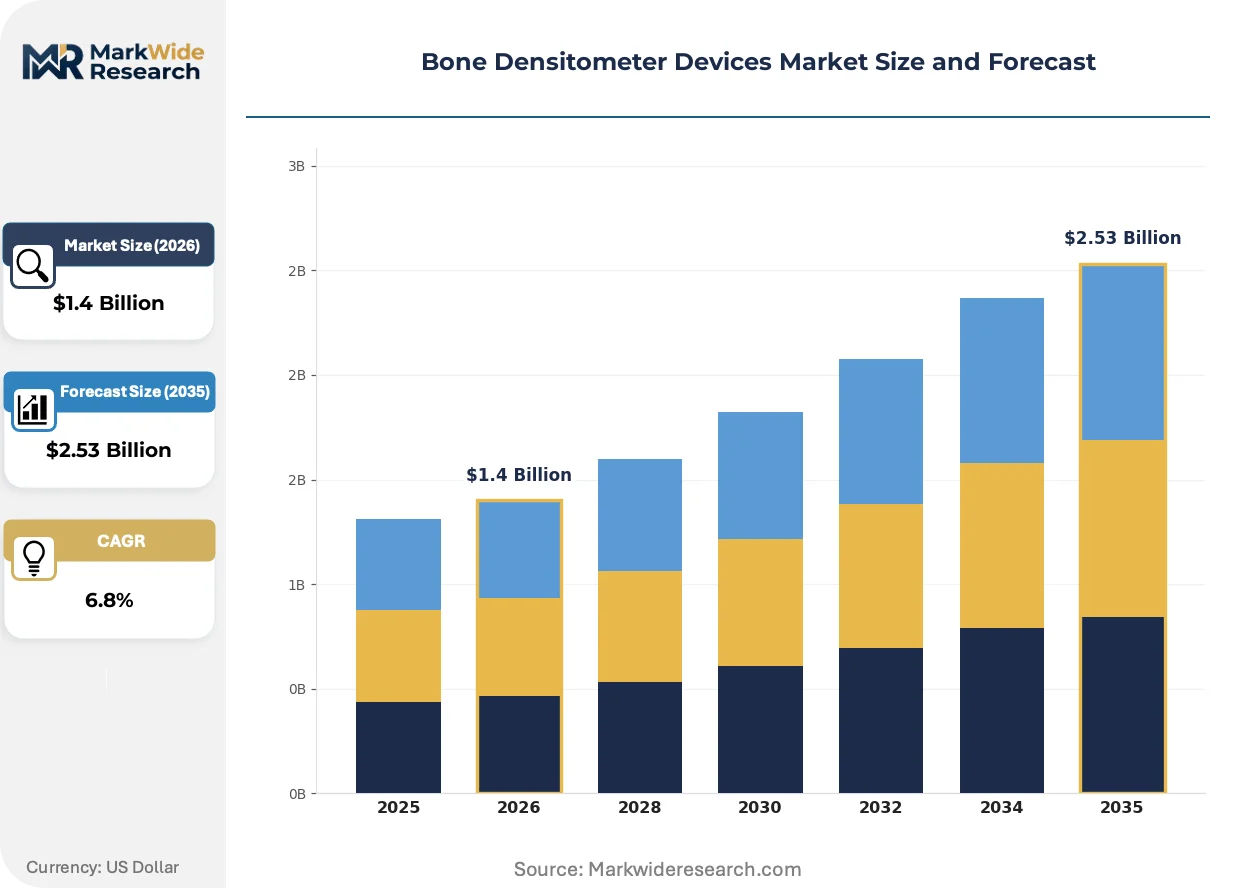
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DEXA, Ultrasound, QCT, Peripheral Technology: High-Resolution, Dual-Energy, 3D Imaging, Software-Driven End User: Hospitals, Clinics, Diagnostic Centers, Research Facilities Application: Osteoporosis Diagnosis, Fracture Risk Assessment, Body Composition Analysis, Clinical Trials |
| Companies Covered | Swissray, Echolight S.p.A., GE Healthcare, Scanflex Healthcare AB, FURUNO Electric Co., Ltd., Hologic Inc., BeamMed Ltd., Trivitron Healthcare, OsteoSys Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Densitometer Devices Market Emerging Trajectories
Artificial intelligence is actively reshaping competitive positioning in bone densitometry, compressing the value chain toward software-enabled diagnostics while hardware commoditization accelerates. The convergence of imaging physics with predictive analytics is redefining what providers purchase and how vendors monetize.
Portable ultrasound densitometry is modularizing point-of-care osteoporosis screening by decoupling bone assessment from centralized radiology departments. Primary care physicians in Germany and the United States adopt handheld systems for immediate fracture risk stratification. This distributed diagnostic model is compressing referral volumes to hospital-based DXA centers while expanding addressable patient populations.
Europe's MDR recasts post-market surveillance obligations for bone densitometer manufacturers, mandating systematic clinical follow-up data collection previously absent from legacy compliance frameworks. Technical documentation requirements now demand proactive evidence generation rather than reactive adverse event reporting. Small and mid-sized device producers face existential documentation burdens that favor scaled competitors with dedicated regulatory affairs infrastructure.
Hospital procurement committees increasingly unbundle after-sales service contracts from initial equipment purchases, treating software maintenance and hardware warranty as separately negotiable line items. This disaggregation pressures vendor margins on long-term revenue streams previously captured through integrated pricing. The practice is most visible in United States health systems consolidating purchasing authority across regional networks.
Bone Densitometer Devices Market Segmentation
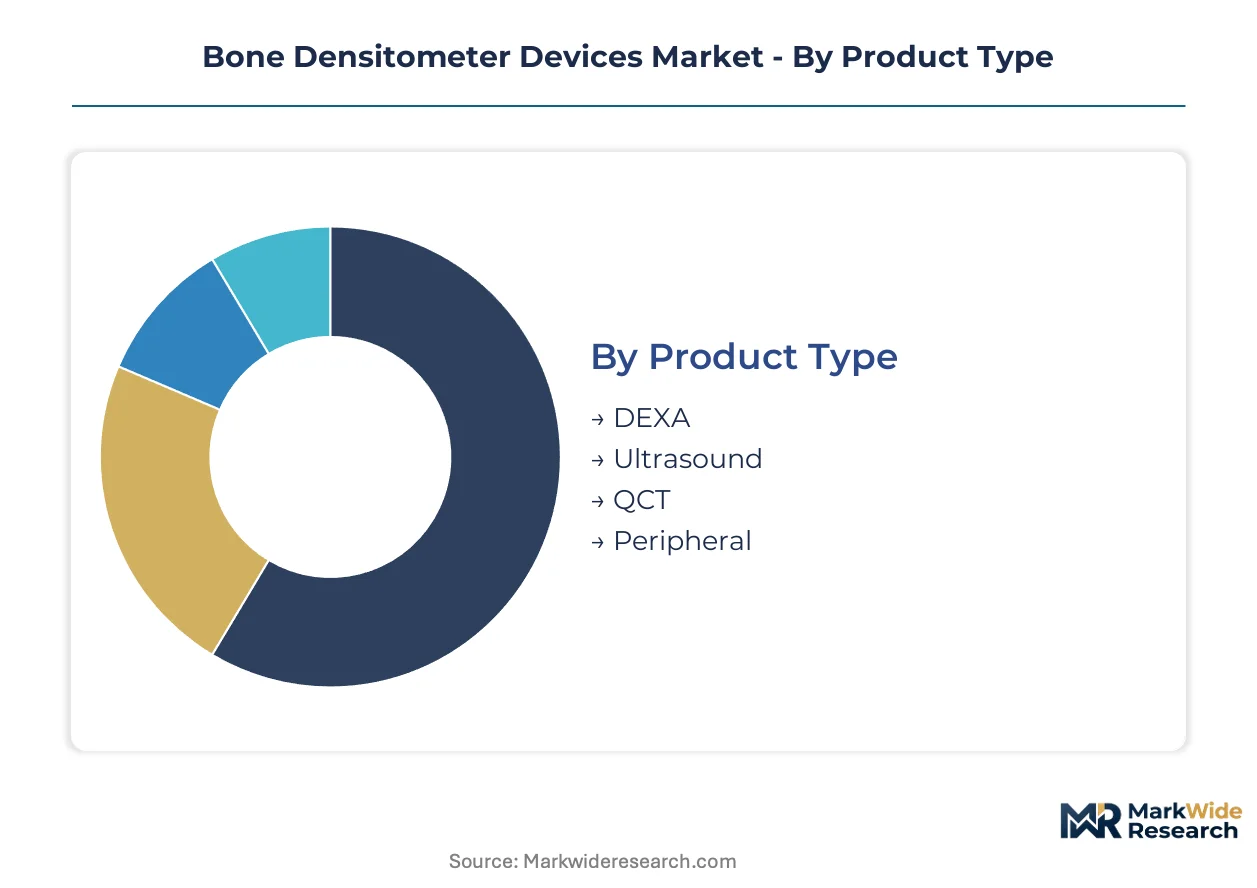
Bone densitometer segmentation reveals divergent commercial architectures between centralized hospital systems and distributed point-of-care networks. Equipment specifications, reimbursement pathways, and regulatory obligations vary sharply across these deployment models, reshaping vendor go-to-market priorities.
Product Type:
Standalone floor systems dominate capital budgets while portable alternatives embed into primary care workflows, fragmenting procurement authority across radiology departments and outpatient networks.
- DEXA:Dual-energy X-ray absorptiometry systems operate at 70-140 kVp with precision errors below 1%, serving as the diagnostic gold standard for longitudinal osteoporosis tracking. Hospital networks in the United States concentrate replacement demand here as FDA quality standards elevate compliance costs that smaller manufacturers cannot absorb.
- Ultrasound:Radiation-free acoustic technology competes on portability and capital efficiency, targeting ambulatory clinics previously inaccessible to ionizing-radiation equipment. German outpatient networks drive clinical adoption where reimbursement clarity for bone mineral density testing removes payment uncertainty.
- QCT:Quantitative computed tomography delivers volumetric bone density assessment with superior three-dimensional resolution for research applications.
- Peripheral:Compact extremity-focused systems enable decentralized screening at reduced capital thresholds for primary care deployment.
DEXA leads volumes today; ultrasound is gaining share fastest.
Technology:
Cost tier stratification separates premium imaging physics from software-augmented interpretation layers, with margin concentration shifting toward analytics modules.
- High-Resolution:Advanced detector arrays capture trabecular microarchitecture detail beyond standard density measurements, commanding premium pricing in academic medical centers. Research facilities in Germany prioritize these specifications for fracture mechanism studies requiring granular skeletal visualization.
- Dual-Energy:The foundational spectral separation technique enables soft-tissue correction and precise bone mineral quantification across axial and appendicular sites. United States hospital networks standardize procurement on this proven modality despite sealed source handling costs from EPA regulations.
- 3D Imaging:Volumetric reconstruction capabilities enhance hip and spine geometric assessments for improved fracture risk prediction.
- Software-Driven:Artificial intelligence modules automate region-of-interest detection and generate automated fracture risk reports.
Dual-energy systems anchor installed bases; software-driven layers are expanding margins most rapidly.
End User:
Customer type determines purchasing committee composition, contract structure, and service attachment rates, with health system consolidation unbundling long-term maintenance agreements.
- Hospitals:Integrated imaging platforms bundle densitometry with broader musculoskeletal diagnostics, creating stickier relationships and defending service revenue streams. North American networks increasingly treat software maintenance and hardware warranty as separately negotiable line items.
- Clinics:Echolight's radiation-free ultrasound technology targets ambulatory settings with reduced regulatory burden and lower total cost of ownership. Primary care physicians in Germany adopt handheld systems for immediate fracture risk stratification.
- Diagnostic Centers:High-throughput operations prioritize throughput optimization and automated reporting workflows.
- Research Facilities:Precision requirements and protocol flexibility drive specification customization and extended validation timelines.
Hospitals retain the largest equipment footprint; clinics are expanding addressable patient populations fastest.
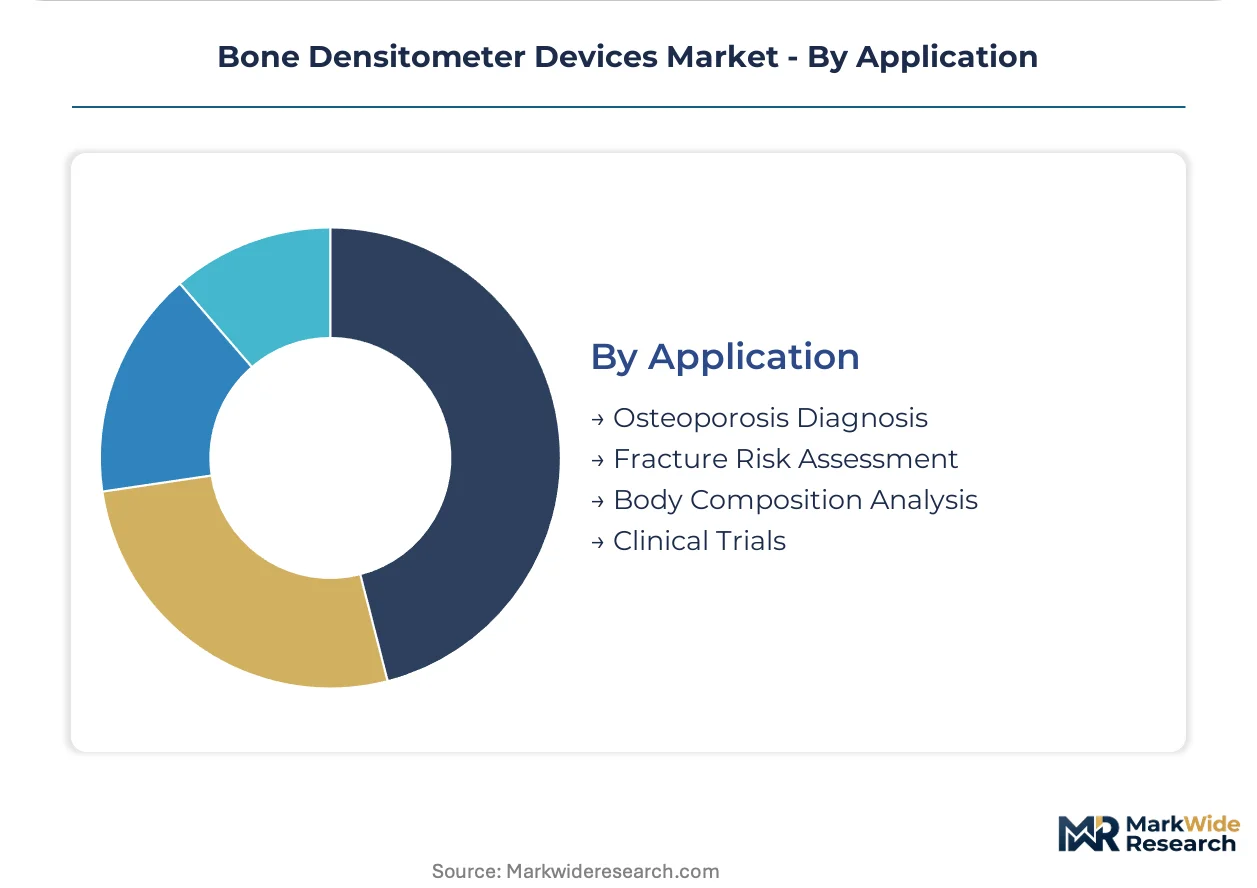
Application:
Maturity gradients separate established diagnostic categories from emerging analytical services, with reimbursement stability varying across clinical versus research indications.
- Osteoporosis Diagnosis:The core clinical indication leverages DXA precision for treatment initiation and therapy monitoring decisions. Statutory health insurance frameworks in Germany remove payment uncertainty that previously delayed equipment procurement cycles.
- Fracture Risk Assessment:Machine learning enhances diagnostic interpretation beyond raw density measurements, representing the fastest-expanding margin pool as predictive analytics redefine provider purchasing criteria. Prior authorization tightening from United States payors elongates revenue recognition cycles for this service line.
- Body Composition Analysis:Athlete monitoring and bariatric surgery planning extend densitometry utility beyond skeletal applications.
- Clinical Trials:Pharmaceutical development demand requires standardized acquisition protocols and centralized data management infrastructure.
Osteoporosis diagnosis commands current procedure volumes; fracture risk assessment is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiology technologists and medical physicists cluster in Germany, the United States, and Japan, anchoring the industry's technical workforce and driving regional equipment deployment patterns.
United States
Hospital network consolidation and Medicare reimbursement stability for DXA procedures sustain equipment replacement cycles. FDA 510(k) pathways govern market entry, with updated quality standards elevating compliance investments. The Boston-to-Washington corridor concentrates densitometer manufacturing and imaging software development.
Germany
Statutory health insurance frameworks remove payment uncertainty for bone mineral density testing, accelerating outpatient clinic procurement. MDR technical documentation requirements recalibrate CE marking costs for European market access. Bavaria's medical technology corridor hosts concentrated device engineering and regulatory affairs expertise.
Japan
Aging demographics and universal health coverage sustain high per-capita screening volumes for osteoporosis diagnosis. PMDA regulatory frameworks align with international standards while maintaining distinct post-market surveillance protocols. The Kanto region around Tokyo anchors hospital system purchasing authority and distributor networks.
China
Expanding tertiary hospital infrastructure and rising osteoporosis awareness drive densitometer installation growth. NMPA medical device registration requirements are harmonizing with international standards under recent regulatory reforms. The Yangtze River Delta medical device cluster concentrates domestic manufacturing and import distribution channels.
Bone Densitometer Devices Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into imaging platform bundlers, radiation-free technology specialists, and regional equipment fabricators. Strategic moves concentrate on M&A for regulatory capabilities and technology licensing for AI-enhanced analytics modules.
Among diversified healthcare conglomerates, GE Healthcare and Hologic Inc. occupy positions as archetypal platform bundlers leveraging installed base density for service revenue. Echolight S.p.A. exemplifies the radiation-free specialist archetype targeting ambulatory channel expansion. These three represent distinct competitive vectors: integrated imaging ecosystems, precision DXA hardware, and portable ultrasound innovation.
| Leading Market Players |
|---|
| Swissray |
| Echolight S.p.A. |
| GE Healthcare |
| Scanflex Healthcare AB |
| FURUNO Electric Co., Ltd. |
| Hologic Inc. |
| BeamMed Ltd. |
| Trivitron Healthcare |
| OsteoSys Corp. |
| Others |
Supply Flow & Price Mechanics
EPA sealed source disposal mandates gate qualified supply and premium-tier pricing access for DXA manufacturers, as compliance infrastructure investments separate certified vendors from gray-market alternatives in United States hospital procurement.
Pricing Analysis
The bundled-versus-unbundled service split now dominates contract negotiations across North American health systems. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status and ISO 13485 certification grade. Pricing pressure stems from ultrasound densitometer substitution in primary care channels, where capital efficiency demands compress ionizing-radiation system margins. Outpatient clinics exhibit highest price sensitivity; academic medical centers with research funding tolerate premium positioning for high-resolution detector arrays.
Supply Chain Analysis
Dual-sourcing requirements for X-ray tube assemblies and solid-state detector arrays now appear in United States hospital procurement specifications, forcing manufacturers to qualify secondary suppliers in Japan and Germany. Component dependencies center on high-voltage generators, precision collimators, and AI-enabled image reconstruction chipsets. Single-source vulnerability concentrates in rare-earth phosphor coatings for scintillation detectors. Distribution runs through specialized medical device distributors with FDA establishment registration, bypassing general industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bone densitometer market functions as a stable compounder, with aging demographics in Germany and Japan delivering predictable replacement cycles regardless of macroeconomic volatility.
For Market Incumbents: Cement installed base retention through predictive maintenance contracts that lock hospital networks into multi-year service agreements. Deepen backward integration into X-ray tube refurbishment capabilities to capture lifecycle revenue streams. Ultrasound densitometer entrants threaten primary care channel displacement; counter with portable DXA variants that maintain radiation-based diagnostic credibility.
For New Entrants and Emerging Players: Distributor partnerships with GPO-authorized medical device suppliers offer the fastest path to United States hospital system access. White-space targets cluster in German outpatient clinics seeking MDR-compliant ultrasound systems and Chinese tertiary hospitals requiring NMPA-registered QCT platforms. Reimbursement strategy development must precede product launch.
For Investors and Strategic Acquirers: Roll-up economics work for regional European device fabricators because MDR technical documentation costs now exceed standalone profitability thresholds. Five-to-ten-year viability favors scaled platforms with dedicated regulatory affairs infrastructure. Monitor FDA 510(k) clearance velocity as inflection indicator for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR technical documentation investments now determine European market access viability. |
| Hospital System Partnership | GPO contract penetration in United States networks defends replacement cycle capture. |
| Software Companion Development | AI fracture risk modules command fastest-expanding margins beyond hardware commoditization. |
| Reimbursement Strategy | Prior authorization pathway clarity in Germany accelerates outpatient clinic procurement decisions. |
| FDX Submission | Updated FDA quality standards elevate compliance barriers protecting established manufacturers. |
Methodological Framework
Coverage spans United States, Germany, Japan, and China, with primary inputs from each market cluster combined with secondary validation. Interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists informed demand-side dynamics. Secondary sources include FDA 510(k) filings, NMPA registration databases, German statutory health insurance reimbursement schedules, and CMS Medicare procedure volume data. Bottom-up equipment installation tracking triangulates against top-down market size estimates.
Granularity-level modeling disaggregates revenue across DEXA, ultrasound, QCT, and peripheral system categories by technology tier and end-user channel. Deployment forecasts incorporate aging demographic trajectories, reimbursement coding revisions, and regulatory pathway timelines across the projection horizon. CAGR derivation weights historical replacement cycles against software-driven analytics penetration curves and outpatient clinic channel expansion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MDR enforcement consistency and United States payor prior authorization tightening. Deviation in FDA quality standard implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
India Artificial Organs and Bionics Market
Medical Devices
Software As a Medical Device Market
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
Peripheral Vascular Guide Wire Market
Medical Devices
Keratoprosthesis (Kpro) Market
Medical Devices
Global Venous Blood Collection Devices Market
Medical Devices
Artificial Implants Market
Medical Devices
Elbow Fixation Systems Market
Medical Devices
Global Ventilators Market
Medical Devices
Intrauterine Devices (IUD) Market
Medical Devices
Inversion Table Market
Medical Devices
Smart Stairlift Market
Medical Devices
Photomedicine Technology Market
Medical Devices
Penile Prosthesis Market
Medical Devices
Canada Digital X-Ray Devices Market
Medical Devices
South Korea Minimally Invasive Surgery Devices Market