
 Ventricular Restoration Systems Market | 2026-2036
Ventricular Restoration Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Ventricular Restoration Systems Market Analysis
Hospital procurement for ventricular restoration systems is tilting toward bundled contracts that pair implantable devices with long-term patient monitoring services. Abbott Laboratories leverages its structural heart portfolio to anchor premium positioning across integrated delivery networks. Medtronic competes through extensive clinical trial infrastructure that sustains regulatory momentum for novel repair technologies. BioVentrix specializes in catheter-based ventricular remodeling systems that occupy a distinct niche in minimally invasive cardiac intervention.
Ventricular restoration systems encompass implantable and percutaneous technologies designed to reconstruct or support damaged left ventricular geometry following myocardial infarction, typically employing synthetic patches, biological scaffolds, or mechanical assist components that restore chamber volume and improve ejection fraction. These systems serve the primary clinical purpose of halting or reversing adverse ventricular remodeling in heart failure patients who remain ineligible for transplant. Mechanical assist devices currently dominate procedural volumes across cardiac surgery centers, while bioengineered solutions within tissue patch systems represent the fastest-expanding segment as regenerative manufacturing processes mature. Minimally invasive techniques are capturing disproportionate investment focus, with margin pools concentrating in catheter-deployable platforms that reduce intensive care utilization.
FDA premarket notification and PMA pathways govern device approval timelines and clinical endpoint requirements for manufacturers seeking U.S. market access, while the EU Medical Device Regulation imposes stricter post-market surveillance and notified body scrutiny across European jurisdictions. Japan's PMDA maintains distinct technical documentation standards that elongate registration timelines for novel implantable cardiac technologies. Stakeholders must monitor evolving reimbursement determinations from Medicare and commercial payers that increasingly predicate coverage on randomized mortality data rather than surrogate hemodynamic endpoints.
Market Dynamics
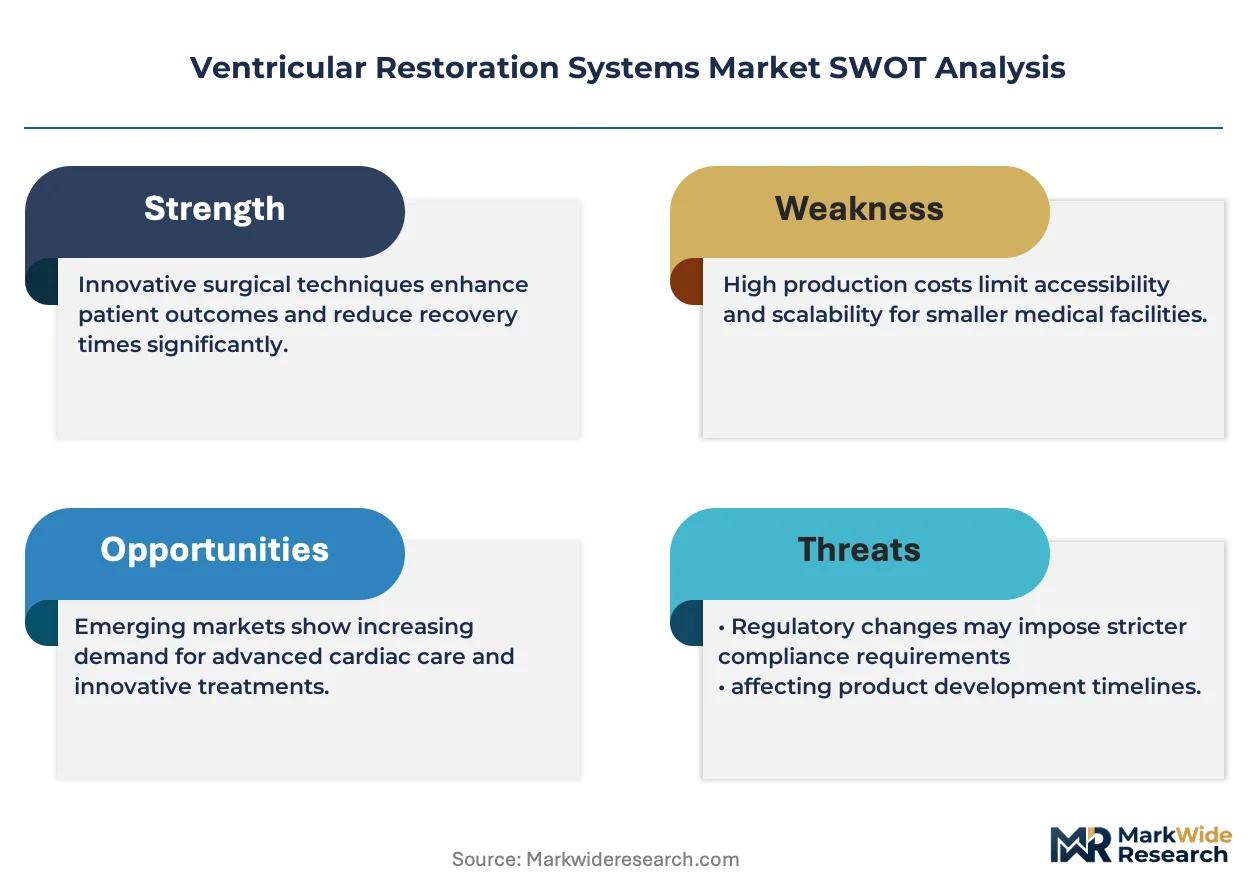
Bundled procurement contracts pairing implantable devices with long-term patient monitoring services are restructuring competitive positioning across cardiac surgery centers, compressing standalone device margins while elevating integrated service providers.
Growth Catalysts
- FDA Premarket Approval Pathways:Tightening clinical evidence requirements for implantable cardiac devices are filtering out marginal competitors and consolidating market access around well-capitalized manufacturers with robust trial infrastructure.
- German Heart Clinic Protocol Integration:Specialized heart clinics across Germany are embedding bioengineered patch systems into standard heart failure treatment pathways, creating template adoption models for neighboring European jurisdictions.
- Catheter-Based Ventricular Remodeling:Minimally invasive catheter-deployable platforms are capturing disproportionate investment focus as cardiac surgery centers seek to reduce intensive care utilization and accelerate patient throughput.
Market Restraints
- Biological Scaffold Input Volatility:Regenerative manufacturing processes for tissue patch systems depend on porcine and bovine-derived extracellular matrix supplies vulnerable to veterinary disease outbreaks and export restrictions.
- EU Medical Device Regulation Friction:Stricter post-market surveillance obligations and notified body capacity constraints are elongating certification timelines and raising compliance costs for novel implantable cardiac technologies.
- Mechanical Assist Device Substitution:Established ventricular assist devices and emerging transcatheter mitral repair technologies compete for the same heart failure patient cohort with more mature clinical evidence bases.
Strategic Opportunities
- Japanese PMDA Registration:Distinct technical documentation standards create first-mover advantages for manufacturers willing to navigate elongated timelines in a market with aging demographics and underpenetrated heart failure intervention rates.
- Regenerative Manufacturing Convergence:Integration of 3D bioprinting with patient-specific imaging workflows enables customized patch geometries that command premium positioning against standardized synthetic alternatives.
- Remote Patient Monitoring Bundling:Medicare reimbursement determinations increasingly predicate coverage on longitudinal outcomes data, creating openings for device manufacturers with captive digital health infrastructure.
Industry Challenges
- Cardiac Surgery Center Credentialing:Minimally invasive ventricular restoration techniques demand specialized hybrid operating room configurations and cross-trained interventional cardiologist-cardiac surgeon teams that remain scarce outside tertiary academic centers.
- Randomized Mortality Endpoint Trials:Commercial payers and Medicare now require hard mortality data rather than surrogate hemodynamic endpoints, extending trial durations and capital requirements for PMA submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ventricular Restoration Systems Market |
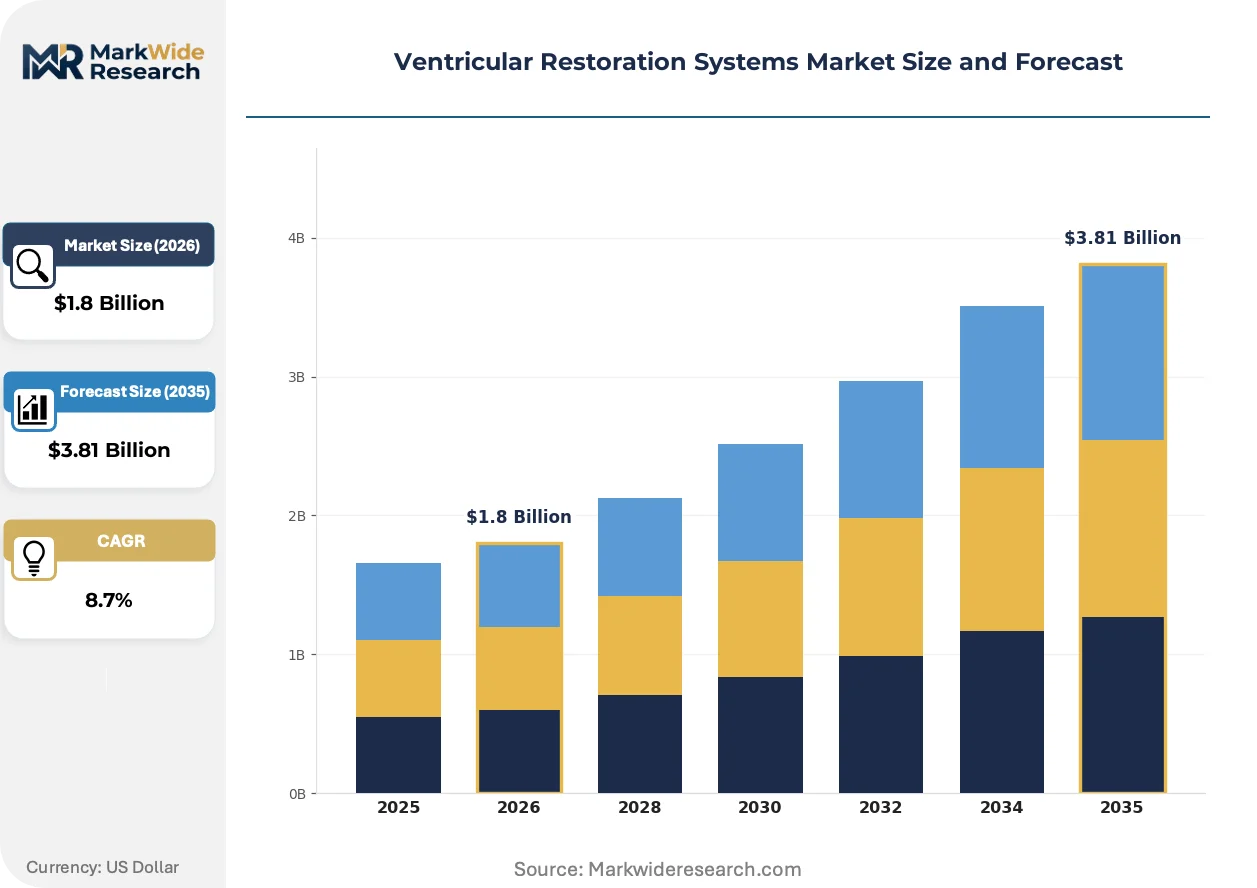
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Assist Devices, Tissue Patch Systems, Patch Repair Systems, Infusion Pumps End User: Cardiac Surgery Centers, Heart Clinics, Hospitals, Specialty Care Facilities Application: Heart Failure Treatment, Surgical Repair, Transplant Preparation, Cardiomyopathy Management Technology: Bioengineered Solutions, Implantable Devices, Minimally Invasive Techniques, Cell Therapy |
| Companies Covered | NeoChord Inc., CardioKinetix Inc., BioVentrix Inc., CryoLife Inc., ON-X Life Technologies Inc., Abbott Laboratories, Medtronic, Artivion Inc., Edwards Lifesciences Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ventricular Restoration Systems Market Emerging Trajectories
Active reshaping in ventricular restoration centers on the compression of procedural invasiveness, the elevation of regenerative biological solutions over mechanical alternatives, and the reconfiguration of procurement around longitudinal patient outcomes rather than device acquisition costs.
Catheter-deployable ventricular restoration systems are collapsing the traditional boundary between surgical and interventional cardiology. Cardiac surgery centers in the United States are accelerating adoption of these platforms to capture heart failure patients previously deemed inoperable. The structural consequence is a redistribution of procedural volume away from open surgical centers toward hybrid catheterization laboratories with lower fixed cost bases.
EU Medical Device Regulation post-market surveillance obligations are tightening evidentiary requirements for implantable cardiac devices across European jurisdictions. Manufacturers must now maintain active safety monitoring systems and periodic safety update reports that were previously voluntary. Tissue patch systems with biological components face the steepest compliance burden due to variability in regenerative material sourcing.
Hospital procurement committees are unbundling device acquisition from implantation services and rebundling with multi-year patient monitoring contracts. Integrated delivery networks in the United States are piloting these arrangements with cardiac surgery centers, displacing traditional fee-for-service device purchasing. Germany's specialized heart clinics represent the most advanced implementation of this model in Europe.
Ventricular Restoration Systems Market Segmentation
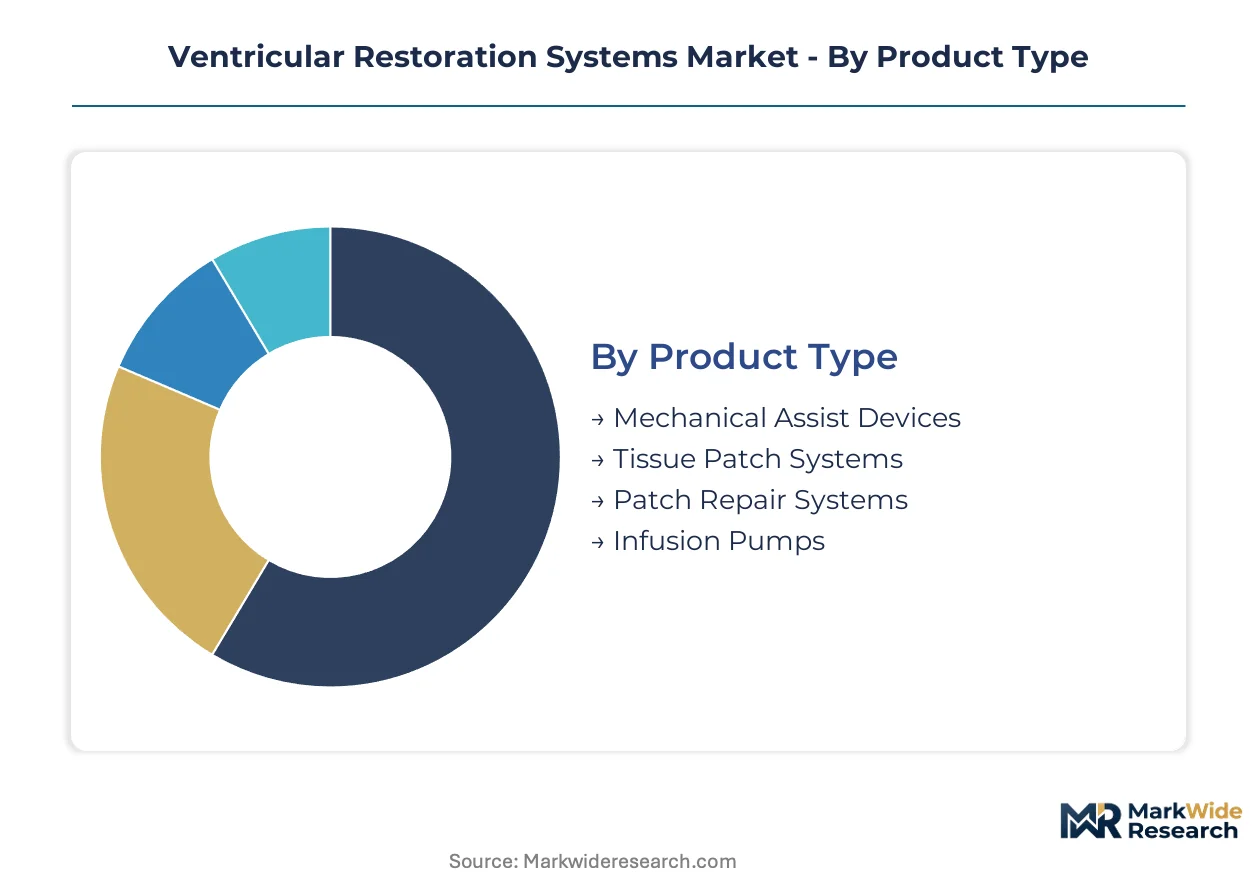
Ventricular restoration systems fragment across four intersecting dimensions that determine procurement patterns, reimbursement pathways, and manufacturer margin structures. Product type and technology choices dictate after-sales service intensity, while end-user configuration and application setting shape clinical evidence requirements and regulatory submission strategies.
Product Type:
After-sales service intensity varies dramatically across product categories, with implantable mechanical systems demanding long-term monitoring infrastructure while patch-based solutions require specialized handling protocols.
- Mechanical Assist Devices:These systems incorporate pumps, cannulae, and control units that provide hemodynamic support to failing ventricles. Demand concentrates in high-volume cardiac surgery centers across the United States where bundled procurement contracts now pair device implantation with multi-year remote monitoring services. FDA PMA pathways for these devices impose rigorous mortality endpoint trials that filter out undercapitalized competitors.
- Tissue Patch Systems:Biological scaffolds derived from extracellular matrix materials reconstruct damaged ventricular geometry through regenerative mechanisms. German heart clinics are embedding these into standard heart failure protocols, creating template adoption models for neighboring European jurisdictions facing EU MDR compliance burdens.
- Patch Repair Systems:Synthetic or hybrid materials reinforce ventricular walls without full mechanical assistance. These occupy mid-tier pricing positions in hospital procurement portfolios.
- Infusion Pumps:Delivery systems for pharmacological or cellular adjunct therapies during restoration procedures. These command lower capital intensity but require precise calibration servicing.
By volume, Mechanical Assist Devices leads. By growth pace, Tissue Patch Systems is climbing the fastest.
End User:
Customer type determines purchasing authority structure, with integrated delivery networks consolidating procurement across multiple facility categories while academic centers retain specialized device selection autonomy.
- Cardiac Surgery Centers:Tertiary facilities performing open surgical ventricular restoration with hybrid operating room configurations. These centers in the United States are expanding adoption of minimally invasive platforms to reduce intensive care utilization.
- Heart Clinics:Specialized cardiovascular facilities focusing on catheter-based interventions and longitudinal patient management. Germany's specialized heart clinics represent the most advanced implementation of bundled device-plus-monitoring procurement models in Europe.
- Hospitals:General acute care facilities with cardiovascular service lines. These face capital budget constraints that favor rental and service-inclusive contracting over outright device purchase.
- Specialty Care Facilities:Post-acute and rehabilitation centers managing heart failure patients after initial restoration procedures. These settings drive demand for portable monitoring technologies that extend manufacturer service relationships.
Cardiac Surgery Centers capture the highest procedure volumes. Heart Clinics are gaining share fastest through catheter-based platform adoption.
Application:
Clinical indication shapes device selection criteria, with transplant bridge applications demanding durability proofs that elective repair settings do not require.
- Heart Failure Treatment:Primary indication for ventricular restoration in patients ineligible for transplant. Medicare reimbursement determinations increasingly predicate coverage on longitudinal outcomes data from these applications.
- Surgical Repair:Direct reconstruction of ventricular geometry following myocardial infarction. These procedures concentrate in cardiac surgery centers with established cardiothoracic programs.
- Transplant Preparation:Bridge-to-transplant applications requiring device reliability over extended durations. These impose the steepest clinical evidence requirements.
- Cardiomyopathy Management:Ongoing therapeutic intervention for chronic ventricular dysfunction. This application segment expands as device durability improves.
Heart Failure Treatment dominates procedure counts. Transplant Preparation shows the steepest expansion trajectory as waiting lists lengthen.
Technology:
Technology maturity determines regulatory pathway complexity, with bioengineered solutions facing biological sourcing variability that mechanical platforms avoid.
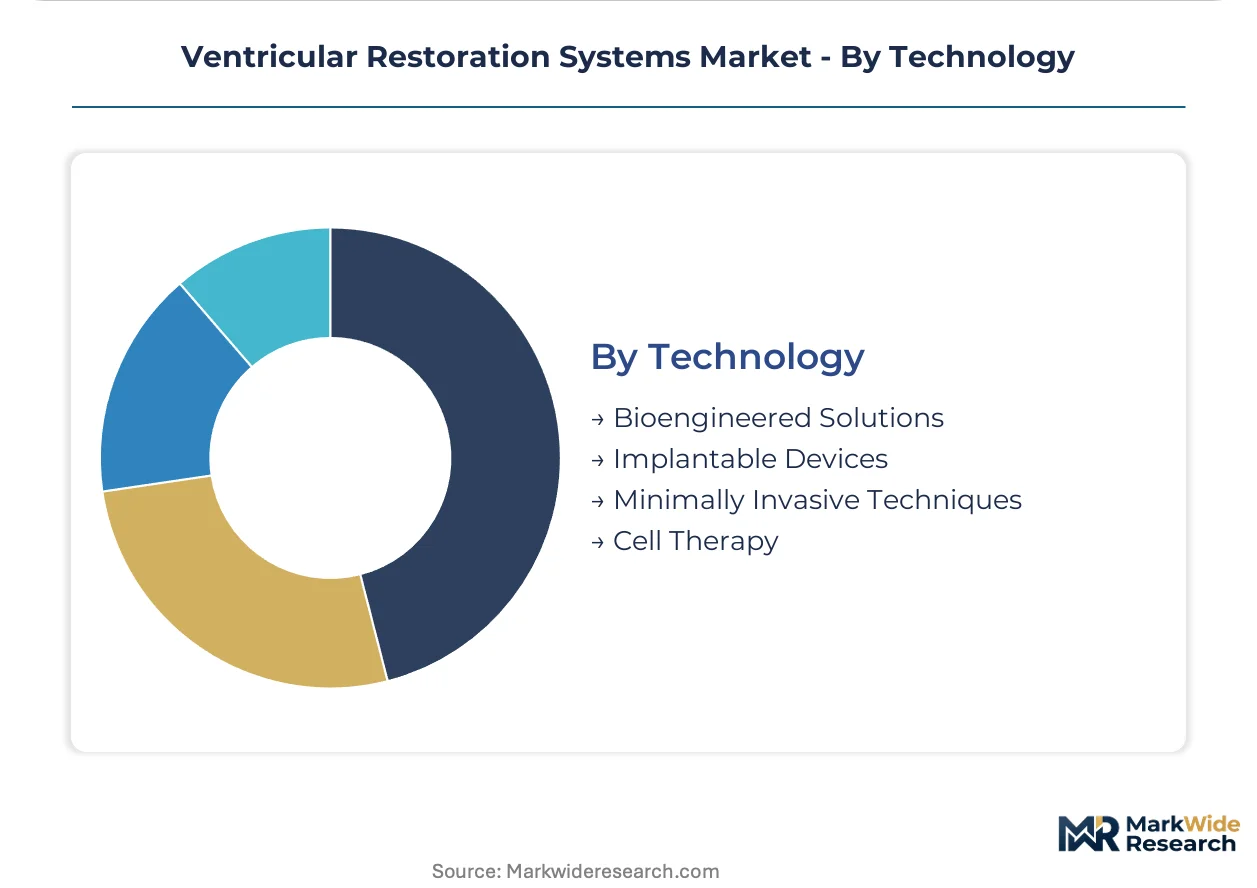
- Bioengineered Solutions:Regenerative approaches employing patient-specific or allogeneic biological materials. Manufacturing depends on porcine and bovine-derived extracellular matrix supplies vulnerable to veterinary disease outbreaks.
- Implantable Devices:Permanent mechanical systems requiring surgical placement. FDA premarket approval pathways for these are tightening clinical evidence requirements.
- Minimally Invasive Techniques:Catheter-deployable platforms that reduce procedural trauma. Cardiac surgery centers are accelerating adoption to capture patients previously deemed inoperable.
- Cell Therapy:Emerging approaches combining structural restoration with regenerative cell delivery. These face elongated PMDA registration timelines in Japan due to distinct technical documentation standards.
Implantable Devices maintains volume leadership. Minimally Invasive Techniques is expanding most quickly through hybrid catheterization laboratory investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cleveland Clinic's cardiac surgical corridor anchors United States ventricular restoration capacity, with its hybrid operating infrastructure underwriting transcatheter platform adoption across the Midwest corridor.
United States
FDA premarket approval pathways tighten clinical evidence requirements for implantable cardiac devices, filtering out marginal competitors. Medicare reimbursement determinations now predicate coverage on randomized mortality data rather than surrogate hemodynamic endpoints. The Texas Medical Center cluster in Houston concentrates mechanical assist device implantation volumes.
Germany
Specialized heart clinics embed bioengineered patch systems into standard heart failure treatment protocols, creating template adoption models for neighboring European jurisdictions. EU Medical Device Regulation post-market surveillance obligations elongate certification timelines for novel implantable technologies. The Heidelberg-Mannheim cardiac cluster drives catheter-based platform integration.
Japan
PMDA maintains distinct technical documentation standards that elongate registration timelines for novel implantable cardiac technologies. METI funding programs support domestic clinical trial infrastructure for regenerative manufacturing processes. The Tokyo-Osaka medical device corridor concentrates hybrid catheterization laboratory investment.
United Kingdom
NHS England bundled procurement contracts pair implantable devices with multi-year patient monitoring services, displacing traditional fee-for-service purchasing. MHRA post-Brexit regulatory divergence creates parallel submission requirements for EU-registered devices. The Oxford-Cambridge-London golden triangle anchors bioengineered scaffold research translation.
Switzerland
Swissmedic maintains streamlined registration pathways for breakthrough cardiac devices with existing FDA or EMA approvals. Federal procurement frameworks favor integrated service contracts over standalone device acquisition. The Basel-Zurich corridor concentrates precision manufacturing for biological scaffold components.
Ventricular Restoration Systems Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying biological scaffolds and catheter delivery mechanisms. Market structure consolidates around three strategic archetypes: diversified cardiovascular conglomerates with structural heart portfolios, mid-cap device specialists with catheter-based platforms, and regenerative manufacturing pure-plays with biological sourcing capabilities. Dominant competitive moves include strategic partnerships bundling device implantation with remote monitoring services, and geographic expansion into Japanese and German markets with elongated regulatory timelines but premium pricing acceptance.
Within the diversified cardiovascular tier, Abbott Laboratories and Medtronic represent platform integrators leveraging extensive clinical trial infrastructure to sustain regulatory momentum. BioVentrix occupies a distinct position among catheter-based specialists, exemplifying the minimally invasive platform archetype that cardiac surgery centers increasingly favor. These three anchors demonstrate how market access now depends on integrated service capabilities rather than device innovation alone.
| Leading Market Players |
|---|
| NeoChord Inc. |
| CardioKinetix Inc. |
| BioVentrix Inc. |
| CryoLife Inc. |
| ON-X Life Technologies Inc. |
| Abbott Laboratories |
| Medtronic |
| Artivion Inc. |
| Edwards Lifesciences Corporation |
| Others |
Supply Flow & Price Mechanics
The Rhine-Alpine freight corridor's cost volatility transmits directly into ventricular restoration system pricing, with cardiac surgery centers in Germany absorbing logistics premiums that compress margins on mechanical assist devices while creating price differentiation between bioengineered patch systems and standardized synthetic alternatives.
Pricing Analysis
Volume-discount tiering structures separate high-throughput integrated delivery networks negotiating bundled device-plus-monitoring contracts from standalone cardiac surgery centers purchasing single-unit implantable devices. Price differentiation rests on FDA PMA certification status and after-sales service bundling intensity. Pricing pressure stems from Medicare reimbursement determinations predicating coverage on longitudinal mortality data rather than hemodynamic endpoints. General acute care hospitals exhibit highest price sensitivity due to capital budget constraints, while German specialized heart clinics accept premium positioning for bioengineered solutions.
Supply Chain Analysis
Extended payment terms from Swiss and German precision manufacturers to biological scaffold suppliers stabilize working capital across regenerative manufacturing networks. Geographic supply concentrates in Switzerland for catheter delivery mechanisms, Germany for extracellular matrix processing, and the United States for mechanical assist device assembly. Raw material dependencies include porcine-derived extracellular matrix, nitinol for catheter frameworks, and biocompatible polymers for synthetic patches. Single-source vulnerability in veterinary-derived biological inputs poses structural risk. Distribution runs through GPO contracts with integrated delivery networks and direct hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of hybrid catheterization laboratory infrastructure and cross-trained interventional cardiologist-cardiac surgeon teams concentrates competitive advantage in a narrow tier of tertiary academic centers, amplifying acquisition premiums for platforms with proven minimally invasive deployment capabilities.
For Market Incumbents: Pre-empt catheter-based platform commoditization by anchoring proprietary remote monitoring ecosystems to device implantation contracts, while consolidating biological scaffold sourcing through captive supply agreements with German extracellular matrix processors to neutralize porcine-derived input volatility from transcatheter mitral repair substitution threats. For New Entrants and Emerging Players: Establish a beachhead in Japanese heart clinics by navigating PMDA's elongated registration timelines with dedicated clinical trial infrastructure, targeting the underpenetrated bridge-to-transplant segment where mechanical assist device durability requirements filter out established competitors, and differentiate through regenerative manufacturing convergence with 3D bioprinting workflows. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified cardiovascular conglomerates divesting non-core structural heart assets amid bundled procurement consolidation, with long-term viability hinging on digital health infrastructure ownership rather than device innovation alone; monitor FDA PMA approval velocity for novel catheter-deployable platforms as inflection indicator for sector repricing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA PMA Submission Acceleration | Expedited mortality endpoint trials consolidate market access around well-capitalized manufacturers with robust clinical infrastructure. |
| Hospital System Partnership | Bundled device-plus-monitoring contracts with integrated delivery networks displace traditional fee-for-service purchasing models. |
| CE Marking Pathway Investment | EU MDR post-market surveillance compliance separates sustainable competitors from marginally capitalized market entrants. |
| Biological Scaffold Sourcing Integration | Captive supply agreements with German extracellular matrix processors neutralize veterinary disease outbreak risks. |
| Software Companion Development | Remote patient monitoring platforms satisfy Medicare reimbursement determinations predicating coverage on longitudinal outcomes data. |
Methodological Framework
A standing panel of cardiac surgeons, interventional cardiologists, hospital purchasing committee chairs, GPO contracts managers, and biomedical engineers provided ongoing calibration across primary interviews combined with secondary validation from FDA PMA filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement determinations. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue attribution.
Scenario-bracketing framed analytical approaches across the analysis window, modeling segmentation dimensions including product type, end-user facility configuration, clinical application indication, and technology maturity tier. CAGRs derived from procedure volume trajectories and average selling price evolution, incorporating regenerative manufacturing scale curves and catheter-based platform adoption rates as industry-specific forecast inputs.
Sensitivities concentrate around FDA PMA approval timeline extensions, EU MDR notified body capacity constraints, and biological scaffold supply disruptions from veterinary disease outbreaks. Forecasts reflect documented assumptions regarding reimbursement determination patterns and hybrid catheterization laboratory investment cycles; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Intraosseous Devices Market
Medical Devices
Oxygen Conservers Market
Medical Devices
Global Digital Dose Inhaler Market
Medical Devices
Intracranial Pressure Monitors Market
Medical Devices
Eye Examination Equipment Market
Medical Devices
Non-Invasive Brain Trauma Monitoring Devices Market
Medical Devices
United Kingdom Anesthesia Devices Market
Medical Devices
Global Gait Analysis System Market
Medical Devices
Polymer-Based Prefilled Syringe Market
Medical Devices
Europe Ablation Technologies Market
Medical Devices
Posterior Chamber Lens Market
Medical Devices
Middle East and Africa Orthotic Devices Market
Medical Devices
Sterile Filtration Module Market
Medical Devices
Absorbable PGLA Surgical Sutures Market
Medical Devices
Flexible and Semi-Rigid Ureteroscopy Market
Medical Devices
Global Glaucoma Surgery Devices Market