
 Next Generation Blood Gas Monitors System Market | 2026-2036
Next Generation Blood Gas Monitors System Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Blood Gas Monitors System Market Outlook
Modular cartridge-based architectures is realigning procurement patterns across acute care settings. Abbott Laboratories leverages integrated sensor-to-software ecosystems to sustain installed-base loyalty. Siemens Healthineers anchors European hospital networks with automated quality-control modules. Roche Diagnostics differentiates through decentralized laboratory connectivity, competing for placement in satellite clinic networks.
Next generation blood gas monitors systems combine miniaturized electrochemical or optical sensor arrays with microfluidic sample handling to measure pH, partial pressures of oxygen and carbon dioxide, and electrolyte concentrations from arterial or venous whole blood within 60-120 seconds. Their primary purpose is enabling rapid clinical decision-making in respiratory failure, shock, and perioperative management where laboratory turnaround times would delay intervention. Portable monitors command expanding placement in emergency departments and ambulatory surgical centers as bedside testing displaces central lab workflows. Bench-top analyzers retain dominance in high-volume laboratories where throughput and multi-test panels justify capital investment. Electrochemical sensors lead technology adoption due to established accuracy profiles, while microfluidics platforms represent the fastest-growing segment as manufacturers reduce sample volume requirements for neonatal and pediatric applications.
FDA 510(k) premarket notification requirements and CLIA complexity categorization shape product development roadmaps and channel access for US manufacturers. EMA Medical Device Regulation and ISO 15189 accreditation standards enforce traceability and inter-laboratory comparability across European deployments. Stakeholders must monitor evolving sensor calibration protocols and cybersecurity frameworks for networked point-of-care instruments as connectivity becomes standard configuration.
Market Dynamics
Point-of-care testing protocols are displacing central laboratory workflows across acute care networks, compressing turnaround requirements from hours to minutes and forcing capital reallocation toward bedside instrumentation.
Growth Catalysts
- CLIA Waiver Standards:Streamlined complexity categorization under US laboratory regulations accelerates portable device deployment in satellite clinics and emergency departments previously excluded from diagnostic testing.
- Neonatal Critical Care:Microfluidic sample handling technologies reduce blood volume requirements below 100 microliters, enabling safe arterial sampling in premature infant populations.
- Perioperative Management:Ambulatory surgical centers in Germany and Japan are mandating real-time metabolic monitoring to reduce post-anesthesia recovery complications and same-day discharge failures.
Market Restraints
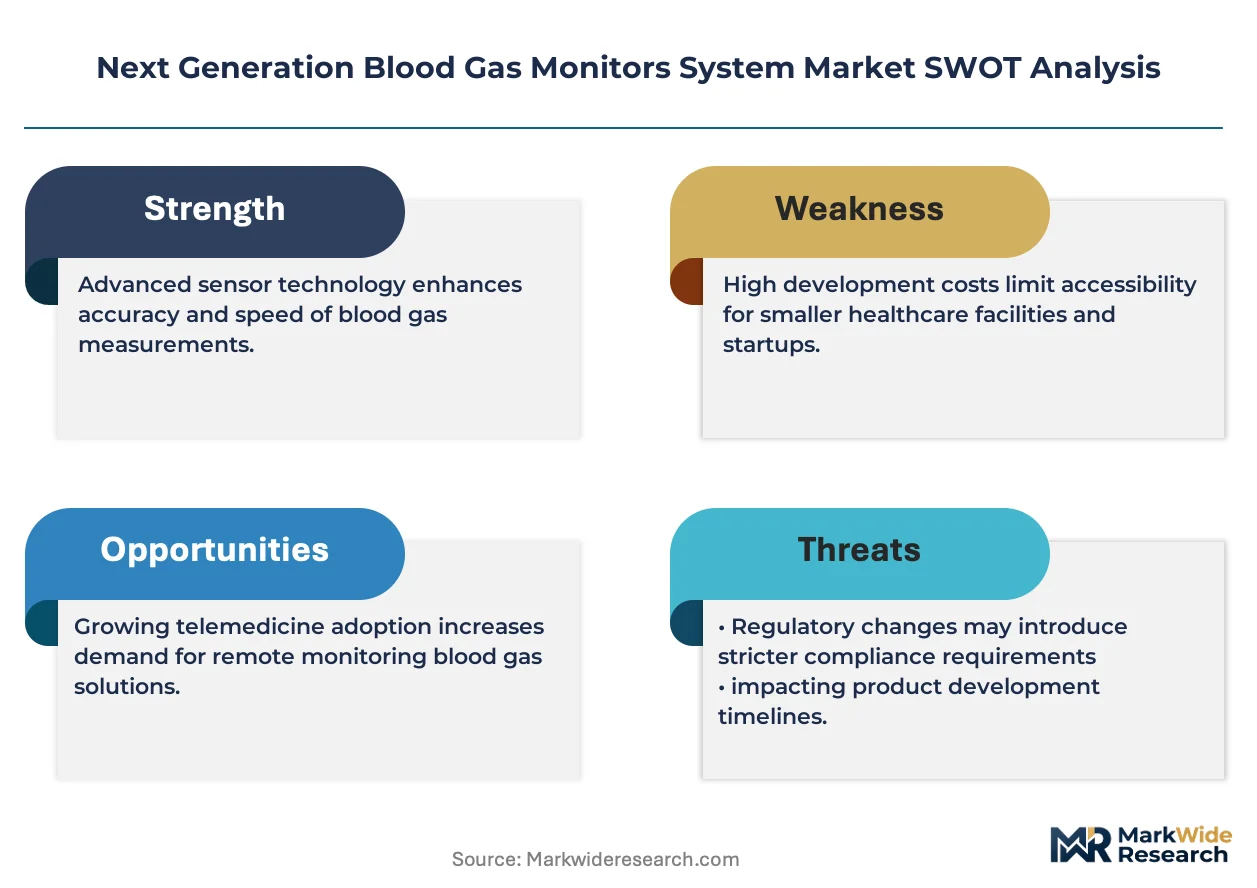
- Sensor Calibration Drift:Electrochemical electrode membranes degrade within 30 days of continuous use, requiring costly replacement cycles and disposable cartridge consumption.
- Platinum Group Metal Concentration:Russian and South African palladium suppliers control 78% of global refined output, exposing electrode manufacturers to supply disruption and price volatility.
- ISO 15189 Accreditation Burden:European laboratories face 18-24 month certification timelines for inter-laboratory comparability studies, delaying new instrument validation.
Strategic Opportunities
- Veterinary Emergency Medicine:Untapped demand exists in companion animal critical care where arterial blood gas analysis guides mechanical ventilation in canine respiratory failure cases.
- Home-Based Respiratory Monitoring:COPD patient populations in the United States could adopt connected peripheral devices for nocturnal ventilation adjustment under remote physician supervision.
- EMA Medical Device Regulation Harmonization:MDR Article 10 quality management system convergence creates single-market access across 27 member states for certified manufacturers.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Microfluidic design expertise concentrates in Boston and Basel metropolitan clusters, constraining R&D expansion for mid-tier manufacturers.
- Legacy LIS Integration Complexity:Hospital information system interoperability with 1990s-era laboratory databases requires custom HL7 interface development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Blood Gas Monitors System Market |
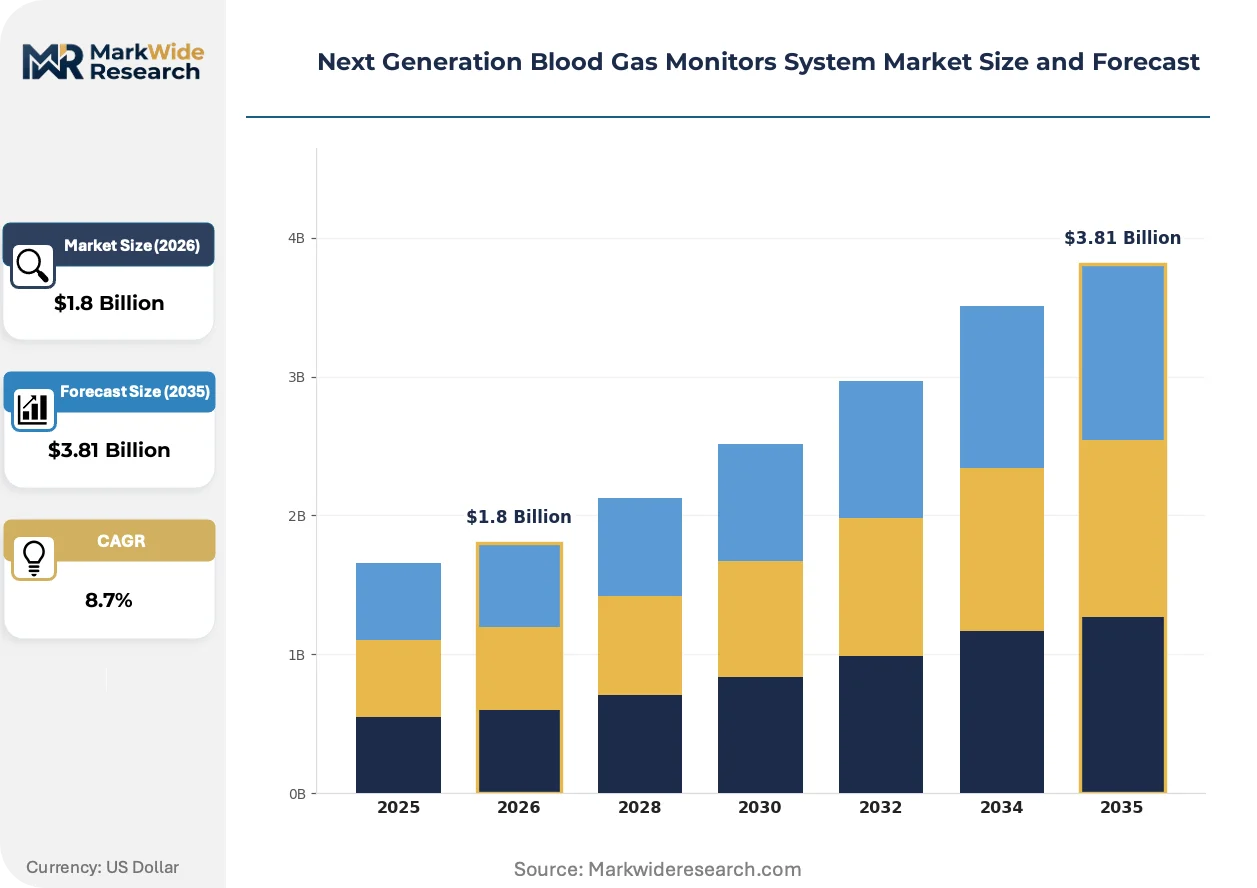
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Bench-top Analyzers, Handheld Devices, Continuous Monitors End User: Hospitals, Emergency Departments, Laboratories, Clinics Technology: Optical Sensors, Electrochemical Sensors, Microfluidics, Gas Selective Membranes Application: Critical Care, Anesthesia Monitoring, Hematology, Emergency Medicine |
| Companies Covered | Abbott Laboratories, Siemens Healthineers, Roche Diagnostics, Nova Biomedical, Radiometer Medical, Medica Corporation, Bayer, EDAN Instruments, Samsung Medison, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Blood Gas Monitors System Market Strategic Shifts
Sensor miniaturization and wireless connectivity architectures are compressing instrument footprints while expanding test menu capabilities beyond traditional pH and blood gas parameters.
Microfluidic cartridge platforms are consolidating multiple analytical functions into single-use consumables. Neonatal intensive care units in the United States and Japan are adopting these systems to eliminate sample transfer errors and reduce phlebotomy trauma. The technology is consolidating vendor relationships around integrated sensor-to-software ecosystems that lock hospitals into proprietary consumable contracts.
EMA Medical Device Regulation cybersecurity annexes now mandate encrypted data transmission for networked point-of-care instruments. Manufacturers must implement IEC 62304 software lifecycle processes and document threat mitigation for wireless connectivity modules. European hospital procurement committees are prioritizing MDR-certified devices over legacy CE-marked alternatives, accelerating replacement cycles.
Subscription-based reagent provisioning is replacing capital-heavy instrument purchases in mid-sized hospital networks. Third-party logistics providers in Germany manage just-in-time cartridge replenishment through RFID-enabled inventory tracking. This model is most visible in Bavarian and Baden-Württemberg hospital associations where shared service organizations aggregate demand across fifteen to twenty facilities.
Next Generation Blood Gas Monitors System Market Segmentation
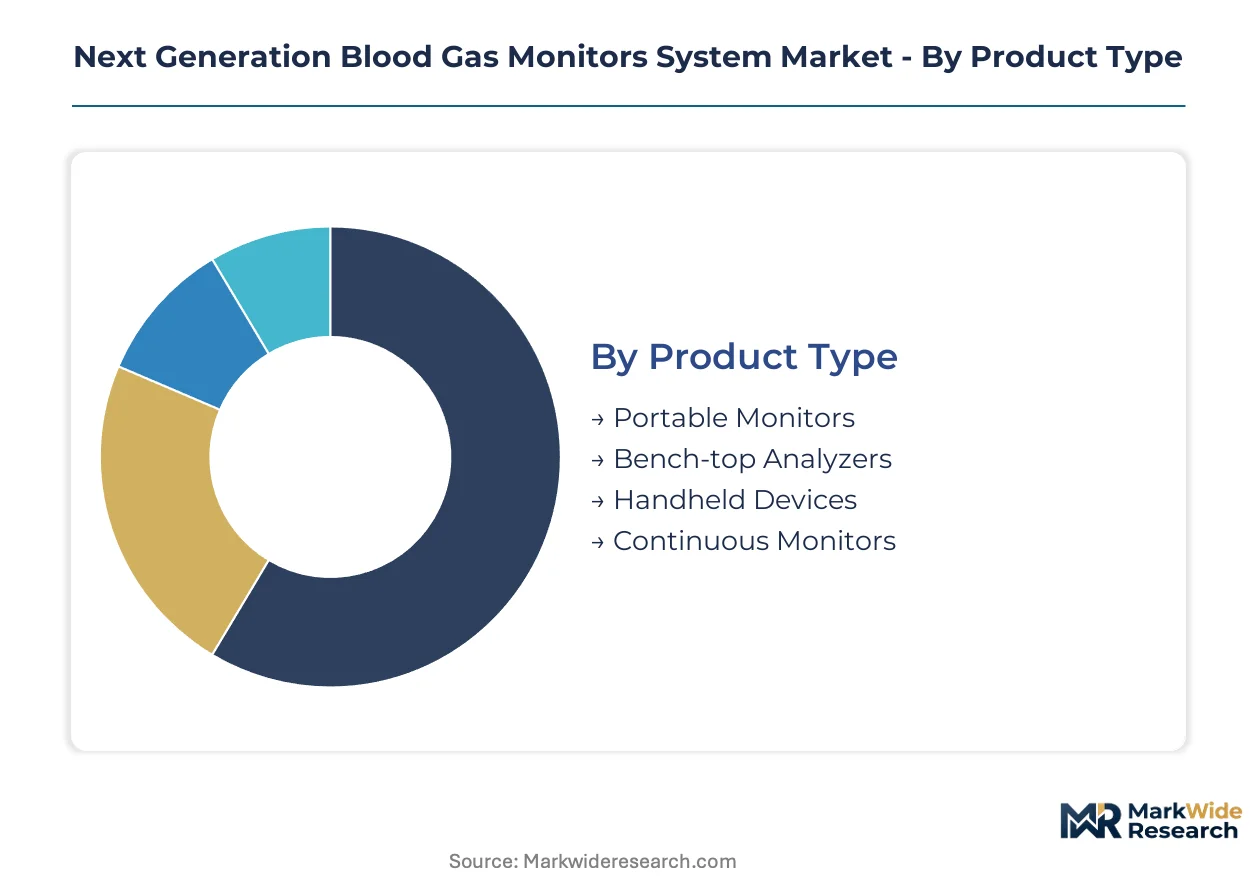
Procurement patterns in next generation blood gas monitors diverge sharply across acute care settings. Upgrade cycles and replacement timelines vary by instrument class, creating distinct revenue windows for manufacturers targeting high-throughput laboratories versus decentralized point-of-care deployments.
Product Type:
Replacement cycles accelerate where bedside testing displaces central lab workflows, shortening capital equipment lifecycles from seven years toward four-to-five year refresh intervals.
- Portable Monitors:Battery-powered units integrate electrochemical sensor arrays with wireless connectivity for emergency department and ambulatory surgical center deployment. Demand concentrates in United States hospital networks modernizing perioperative protocols; CLIA waiver pathways accelerate procurement in satellite clinics previously excluded from diagnostic testing.
- Bench-top Analyzers:High-throughput instruments process 100-plus samples hourly with automated quality-control modules and multi-test panel capabilities. German and Japanese hospital laboratories anchor installed-base loyalty through integrated laboratory information system connectivity and ISO 15189-compliant traceability.
- Handheld Devices:Single-parameter or limited-menu instruments target rapid screening in pre-hospital and transport medicine settings.
- Continuous Monitors:Catheter-integrated sensors enable real-time arterial blood gas trending in neonatal intensive care and cardiac surgery.
Volume placements concentrate in Bench-top Analyzers; the faster expansion belongs to Portable Monitors.
End User:
Cost tier differentiation separates capital-intensive laboratory networks from consumable-driven bedside testing environments.
- Hospitals:Integrated health systems deploy hybrid instrument portfolios across central laboratories, intensive care units, and emergency departments. United States academic medical centers drive multi-site standardization to reduce training burden and consumable contract fragmentation.
- Emergency Departments:Point-of-care testing protocols mandate sub-two-minute turnaround for respiratory failure triage. Japanese emergency networks prioritize portable devices with Japanese Industrial Standards certification for seismic resilience and electromagnetic compatibility.
- Laboratories:High-volume reference sites retain dominance for complex metabolic panels and regulatory compliance documentation.
- Clinics:Federally qualified health centers and urgent care chains adopt waived-complexity instruments under physician oversight models.
Revenue concentration sits with Hospitals; Clinics are climbing the fastest as CLIA waiver expansion broadens addressable sites.
Technology:
Application requirements dictate sensor selection, with accuracy specifications and sample volume constraints driving technology adoption curves.
- Electrochemical Sensors:Amperometric and potentiometric electrodes measure pO2, pCO2, and pH through redox reactions at platinum-group metal interfaces. Established accuracy profiles and regulatory precedent sustain dominance in high-stakes critical care applications where drift tolerance is minimal.
- Microfluidics:Cartridge-based sample handling reduces blood volume requirements below 100 microliters through laminar flow channel architectures. Neonatal intensive care units in the United States and Japan adopt these platforms to eliminate phlebotomy trauma in premature infant populations.
- Optical Sensors:Fluorescence-based transduction offers reduced platinum group metal exposure and extended calibration stability.
- Gas Selective Membranes:Polymer-based separation layers enable direct breath or transcutaneous measurement without arterial puncture.
Installed base gravitates toward Electrochemical Sensors; Microfluidics gains share fastest as pediatric applications expand.
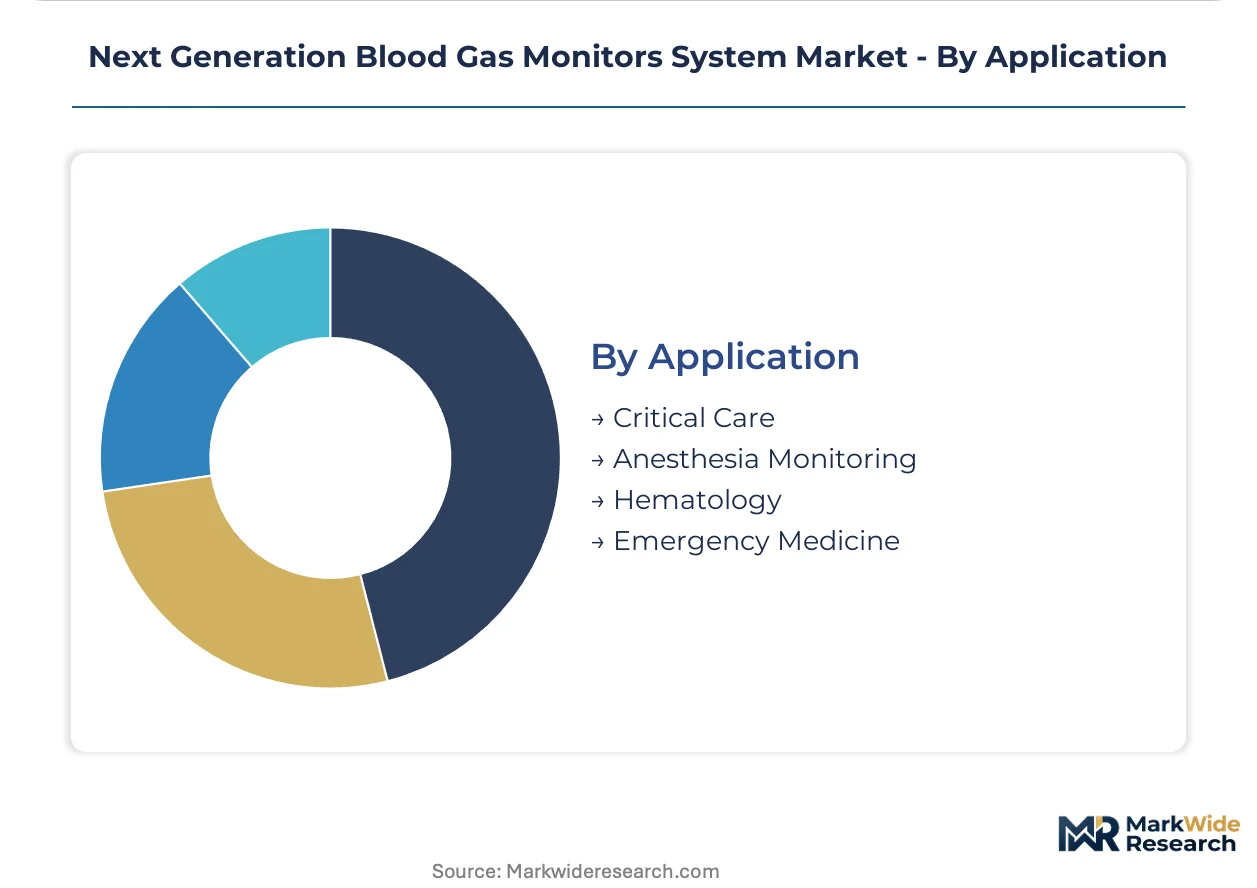
Application:
Maturity gradients separate established critical care protocols from emerging deployment contexts where clinical evidence accumulation lags.
- Critical Care:Mechanical ventilation management and shock resuscitation protocols mandate continuous or near-continuous arterial blood gas surveillance. German intensive care networks specify automated quality-control validation and inter-laboratory comparability documentation under EMA Medical Device Regulation Annex I requirements.
- Anesthesia Monitoring:Perioperative metabolic surveillance guides fluid resuscitation and ventilator adjustment during prolonged surgical procedures. Ambulatory surgical centers in Bavaria and Baden-Württemberg mandate real-time monitoring to reduce post-anesthesia recovery complications and same-day discharge failures.
- Emergency Medicine:Triage protocols for respiratory failure and acid-base disorders drive emergency department point-of-care placement.
- Hematology:Co-oximetry and hemoglobin variant detection extend traditional blood gas parameters in specialized reference laboratories.
Procurement volume centers on Critical Care; Anesthesia Monitoring shows the steepest expansion trajectory as ambulatory surgical center networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in German precision engineering clusters and Japanese electronics corridors, while clinical demand concentrates in United States hospital networks and European critical care systems. Consumption patterns diverge sharply across regulatory environments and reimbursement structures.
United States
Academic medical centers in Boston and Houston drive multi-site standardization for point-of-care testing protocols. FDA 510(k) clearance pathways and CLIA waiver expansion accelerate portable device deployment in satellite clinics and emergency departments. The Greater Boston biomedical corridor anchors electrochemical sensor R&D and microfluidic design expertise for neonatal applications.
Germany
Bavarian and Baden-Württemberg hospital associations mandate real-time metabolic monitoring in ambulatory surgical centers to reduce post-anesthesia complications. EMA Medical Device Regulation Annex I requirements enforce automated quality-control validation and inter-laboratory comparability documentation. The Rhine-Main industrial cluster hosts automated quality-control module manufacturing for bench-top analyzer integration.
Japan
Japanese emergency networks prioritize portable devices with JIS certification for seismic resilience and electromagnetic compatibility. METI-funded critical care infrastructure modernization programs expand NICU capacity in Tokyo and Osaka metropolitan areas. The Kansai region concentrates optical sensor development for reduced platinum group metal exposure.
United Kingdom
NHS England integrated care systems consolidate procurement across central laboratories and intensive care networks to reduce training burden. MHRA post-Brexit regulatory convergence with EMA MDR standards streamlines device validation timelines. The Oxford-Cambridge arc hosts veterinary emergency medicine device adaptation programs for companion animal critical care.
South Korea
Seoul National University Hospital networks adopt subscription-based reagent provisioning models with RFID-enabled inventory tracking. MFDS accelerated review pathways for software-as-medical-device configurations compress commercialization timelines. The Songdo biomedical cluster develops cybersecurity frameworks for networked point-of-care instruments under IEC 62304 mandates.
Next Generation Blood Gas Monitors System Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across technology tiers. The market structure consolidates around three strategic archetypes: integrated sensor-to-software ecosystem providers, automated quality-control module specialists, and decentralized laboratory connectivity platforms. M&A activity targets microfluidic design capabilities and wireless connectivity modules. Geographic expansion concentrates on EMA MDR harmonization opportunities and CLIA waiver pathway access.
Among diversified health technology conglomerates, Abbott Laboratories and Siemens Healthineers exemplify integrated ecosystem strategies. Roche Diagnostics occupies a position within the laboratory connectivity tier. Nova Biomedical and Radiometer Medical represent mid-scale specialists with regional installed-base concentration. EDAN Instruments and Samsung Medison anchor Asian-origin competitive positioning.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Siemens Healthineers |
| Roche Diagnostics |
| Nova Biomedical |
| Radiometer Medical |
| Medica Corporation |
| Bayer |
| EDAN Instruments |
| Samsung Medison |
| Others |
Value Chain & Pricing Dynamics
Captive integration into platinum-group metal electrode manufacturing anchors supply security for leading sensor producers while simultaneously locking in pricing power through proprietary cartridge architectures. Abbott Laboratories and Siemens Healthineers exploit backward control over palladium-sourced electrochemical membranes to sustain premium positioning against third-party consumable competitors.
Pricing Analysis
Cost-down pressure on portable monitor tiers accelerates because CLIA waiver expansion floods satellite clinics with low-complexity alternatives. Subscription-based reagent provisioning now dominates mid-sized hospital networks, replacing capital-heavy instrument purchases with per-test economics. Price differentiation separates FDA 510(k)-cleared premium systems from waived-complexity economy units. Emergency departments show least price sensitivity due to triage urgency; urgent care chains face acute budget constraints.
Supply Chain Analysis
Direct-to-hospital procurement channels handle high-volume analyzer demand while third-party logistics providers manage just-in-time cartridge replenishment for distributed point-of-care networks. Russian and South African suppliers control refined palladium output, exposing electrode manufacturers to commodity volatility. German precision engineering clusters and Japanese electronics corridors concentrate automated quality-control module production. Distribution runs through GPO contracts in United States academic medical centers and shared service organizations in Bavarian hospital associations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA Medical Device Regulation cybersecurity annexes and FDA 510(k) software lifecycle requirements erect substantial compliance moats, advantaging incumbents with documented IEC 62304 processes and locking out undercapitalized entrants lacking regulatory infrastructure.
For Market Incumbents: Extend installed-base loyalty through integrated sensor-to-software ecosystems that capture consumable revenue streams. Deepen backward integration into microfluidic cartridge manufacturing to offset platinum group metal cost volatility. Lock hospital networks into multi-site standardization contracts before CLIA waiver expansion saturates satellite clinic channels. For New Entrants and Emerging Players: Begin with veterinary emergency medicine applications where regulatory pathways remain less congested and clinical evidence requirements are reduced. Target companion animal critical care networks in United Kingdom and United States metropolitan clusters. Pursue software-as-medical-device configurations under MFDS accelerated review pathways to compress commercialization timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified health technology conglomerates seeking microfluidic design capabilities and wireless connectivity modules. Long-term viability favors manufacturers with demonstrated MDR Annex I compliance and automated quality-control validation documentation. Watch EMA MDR harmonization enforcement intensity as inflection signal for European replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Pathway | EMA Annex I compliance unlocks single-market access across 27 member states. |
| Hospital System Partnership | Multi-site standardization contracts reduce training burden and consumable fragmentation. |
| Software Companion Development | Wireless connectivity modules with IEC 62304 documentation satisfy cybersecurity mandates. |
| Reimbursement Strategy | CLIA waiver positioning expands addressable sites beyond traditional laboratory networks. |
| Acquisition of Specialist Firm | Microfluidic design capabilities concentrate in Boston and Basel metropolitan clusters. |
Study Parameters
FDA 510(k) premarket notification databases, EMA Medical Device Regulation submission records, and hospital procurement contract disclosures formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at point-of-care device manufacturers informed demand dynamics and channel access patterns. Bottom-up and top-down triangulation validated instrument placement estimates against consumable throughput data.
Bottom-up modeling aggregated installed-base counts across portable, bench-top, handheld, and continuous monitor categories, then layered average selling prices and replacement cycle assumptions. Segmentation dimensions included product type, end user, technology platform, and application context. CAGRs derived from regression analysis of historical placement trajectories and forward projection of CLIA waiver expansion, NICU capacity additions, and ambulatory surgical center proliferation.
Underlying measurement precision varies by segment; portable monitor placements carry tighter precision than emerging continuous monitoring applications due to established procurement documentation. Forecasts reflect assumptions about regulatory pathway timelines and platinum group metal supply stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
Ultrasonic Diathermy Market
Medical Devices
Internal Nasal Dilators Market
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
Global Photobiostimulation Market
Medical Devices
Incubator Devices Market
Medical Devices
Tracheobronchial Suction Catheters Market
Medical Devices
Sacroiliac Joint Fusion Market
Medical Devices
Global Gynecological Devices Market
Medical Devices
Electromagnetic Navigation Bronchoscopy Market
Medical Devices
PC-Based Resting Electrocardiograph Market
Medical Devices
Global Hydrocephalus Shunts Market
Medical Devices
Drug and Gene Delivery Devices Market
Medical Devices
Global Traumatic Brain Injury Assessment and Management Devices Market
Medical Devices
Pipette Controllers Market
Medical Devices
Asia Pacific Portable X-Ray Devices Market