
 Non-Invasive Intracranial Pressure Monitoring Device Market | 2026-2036
Non-Invasive Intracranial Pressure Monitoring Device Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Invasive Intracranial Pressure Monitoring Device Market Intelligence
Multi-source component procurement is expanding across the non-invasive intracranial pressure monitoring device supply chain as manufacturers diversify away from single-source optical sensor foundries. Medtronic leverages captive semiconductor partnerships to secure transducer supply continuity for its neuromonitoring portfolio. Integra LifeSciences anchors North American distribution through specialized neurosurgical sales channels. RAUMEDIC AG competes on German-engineered fiber optic precision, sustaining premium positioning in European trauma centers.
Non-invasive intracranial pressure monitoring devices employ transcranial Doppler ultrasonography, near-infrared spectroscopy, or tympanic membrane displacement sensors to estimate ICP without penetrating the cranial vault, typically achieving measurement correlation within 5-10 mmHg of invasive gold standards for clinical decision support. Optical sensors dominate current revenue contribution due to mature photodetector supply chains and established reimbursement codes, while ultrasonic devices represent the fastest-expanding technology segment driven by portable form factors suitable for emergency department triage. Fiber optic systems concentrate margin pools in post-operative neurocritical care settings where continuous trending accuracy commands premium pricing.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development roadmaps, with the FDA's breakthrough devices program offering expedited review for novel non-invasive ICP modalities addressing traumatic brain injury. ISO 13485 quality management certification and IEC 60601-1 electrical safety standards constitute baseline market access prerequisites across all target geographies. Stakeholders must monitor evolving CMS national coverage determinations and parallel German G-BA benefit assessments, as reimbursement parity with invasive monitoring remains the decisive adoption catalyst.
Market Dynamics
Neurosurgical departments are abandoning bolt-based invasive monitoring as optical coherence tomography and transcranial Doppler systems achieve clinical-grade correlation with catheter-based measurements. This substitution pressure is compressing reimbursement timelines and forcing manufacturers to validate algorithms against invasive gold standards.
Growth Catalysts
- EU MDR breakthrough pathway:Expedited CE marking for novel ICP modalities accelerates European commercialization timelines for ultrasonic sensor developers.
- Trauma center certification standards:United States emergency medicine accreditation bodies now mandate continuous intracranial surveillance capabilities without mandating invasive placement.
- Photodetector supply chain maturation:Established semiconductor foundries in East Asia reduce optical sensor unit costs and enable portable form factor miniaturization.
Market Restraints
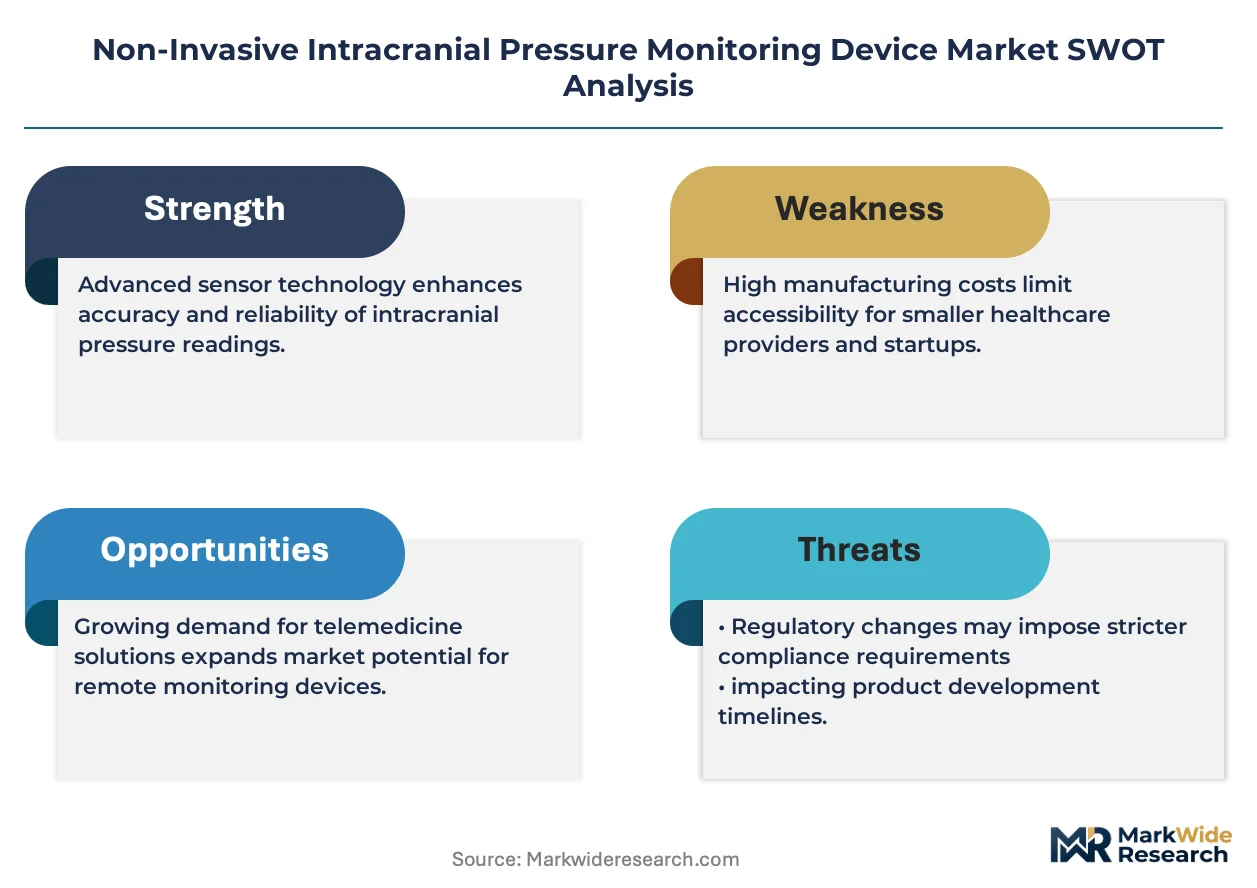
- Single-source fiber optic dependency:German-engineered precision transducers concentrate in two specialized foundries, creating supply vulnerability.
- Algorithm validation costs:FDA 510(k) submissions require prospective clinical trials against invasive monitoring, extending development cycles.
- Reimbursement parity gaps:CMS national coverage determinations lag device approvals, forcing hospitals to absorb upfront capital costs.
Strategic Opportunities
- Japanese neurocritical care expansion:METI-funded hospital infrastructure programs create demand for continuous bedside ICP trending without cranial penetration.
- Near-infrared spectroscopy-AI convergence:Machine learning pattern recognition enhances optical signal interpretation accuracy for pediatric populations.
- Emergency department triage protocols:Portable ultrasonic devices enable pre-hospital ICP estimation by paramedic services.
Industry Challenges
- ISO 13485 quality management implementation:Small sensor developers lack documented design controls for medical device software.
- Legacy EMR integration complexity:Proprietary data formats from novel devices require custom HL7 interface development.
- Specialized neurophysiologist shortage:Interpretation of transcranial Doppler waveforms demands training pipelines that academic medical centers cannot scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Invasive Intracranial Pressure Monitoring Device Market |
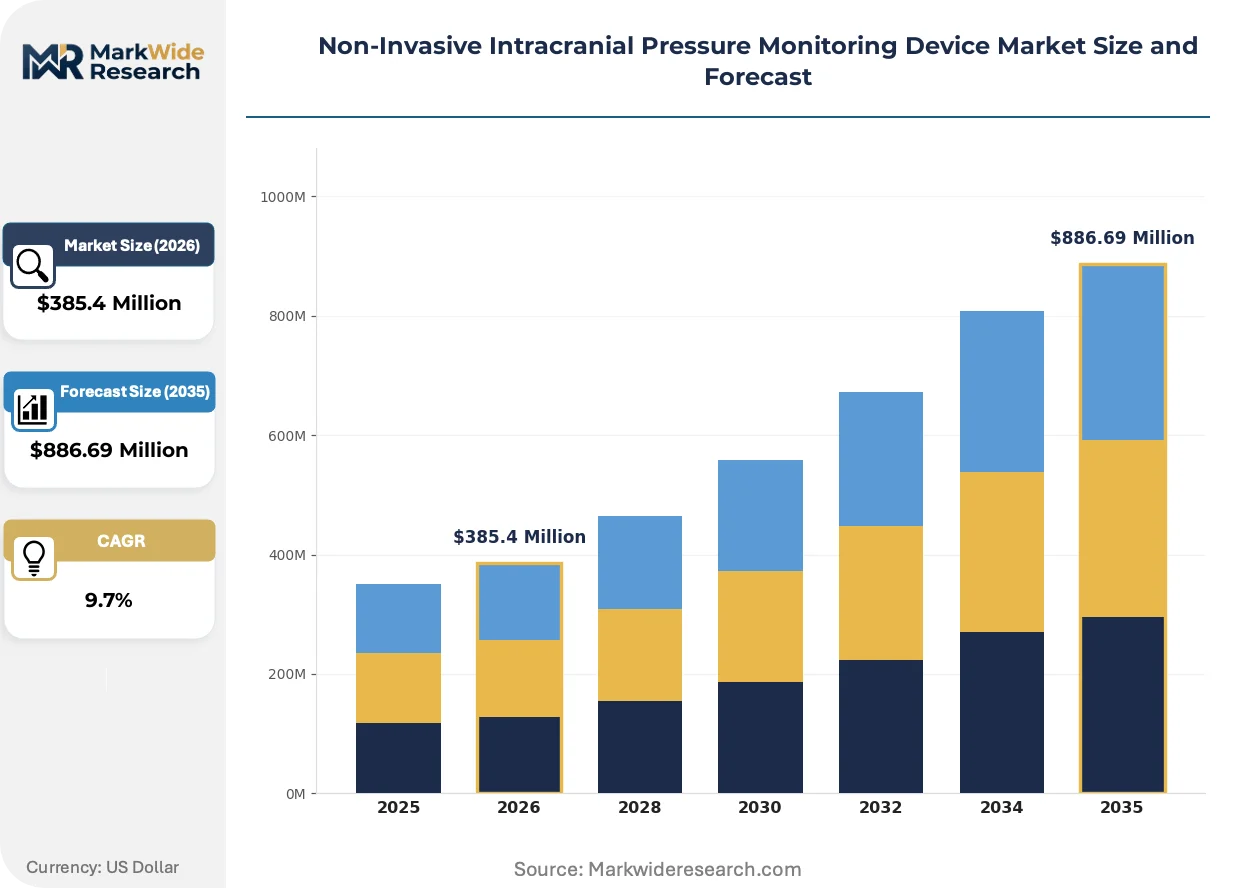
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $886.69 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Sensors, Ultrasonic Devices, Fiber Optic Systems, Electrical Sensors End User: Neurology Clinics, General Hospitals, Emergency Departments, Research Institutions Technology: Transducers, Signal Processing, Imaging Techniques, Data Analytics Application: Traumatic Brain Injury Monitoring, Stroke Management, Post-Operative Care, Clinical Research |
| Companies Covered | Medtronic, Integra LifeSciences, RAUMEDIC AG, Spiegelberg GmbH & Co. KG, Sophysa, Natus Medical, Gaeltec Devices, Vittamed, HeadSense Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Invasive Intracranial Pressure Monitoring Device Market Strategic Shifts & Innovations
Signal processing architectures are absorbing computational workloads that previously required tethered bedside consoles. This edge-computing migration enables ambulatory monitoring scenarios and collapses the hardware footprint required for continuous ICP surveillance.
Transcranial Doppler ultrasonography with embedded AI inference is absorbing the diagnostic burden from specialized neurophysiologists. Emergency medicine departments in United States Level I trauma centers are deploying these systems for immediate triage decisions. The technology is absorbing market share from stationary optical platforms by eliminating the need for trained operator interpretation.
FDA breakthrough device designation pathways are compressing review timelines for traumatic brain injury applications. Manufacturers submitting novel non-invasive modalities receive prioritized pre-submission feedback and accelerated PMA review schedules. Pediatric neurosurgical segments benefit most, as invasive monitoring carries higher complication risks in younger patients.
Hospital procurement committees are consolidating vendor relationships around platforms offering both invasive and non-invasive modalities. Integrated neuromonitoring contracts now bundle ICP devices with EEG and cerebral oximetry systems. This bundling pattern concentrates purchasing authority at academic medical center supply chain offices in Germany and Japan.
Non-Invasive Intracranial Pressure Monitoring Device Market Segmentation
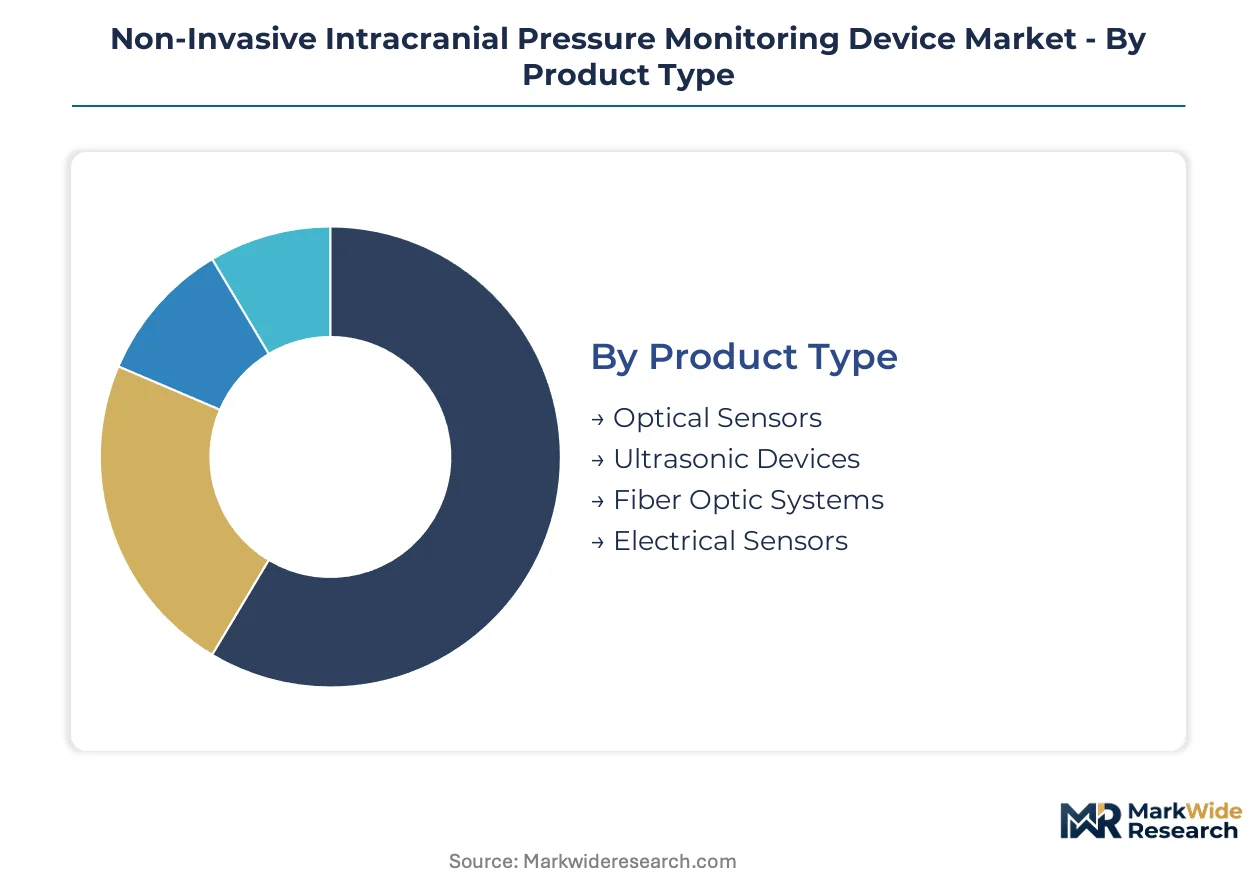
Segmentation reveals how technology maturity, reimbursement pathways, and clinical workflow integration determine commercial traction across non-invasive ICP monitoring. Manufacturers prioritize segments where regulatory clarity and hospital procurement alignment overlap.
Product Type:
Optical sensors command premium pricing through established photodetector supply chains, while ultrasonic devices penetrate emergency settings via portable miniaturization.
- Optical Sensors:Near-infrared spectroscopy and photoplethysmography modules leverage mature semiconductor foundries in East Asia. Demand concentrates in post-operative neurocritical care units at academic medical centers in Germany and Japan, where continuous trending accuracy justifies capital expenditure despite higher per-unit costs.
- Ultrasonic Devices:Transcranial Doppler systems with embedded edge computing enable point-of-care deployment without specialized operator interpretation. Emergency departments in United States Level I trauma centers drive volume adoption, propelled by accreditation standards mandating continuous ICP surveillance capabilities.
- Fiber Optic Systems:German-engineered precision transducers sustain margin pools in European trauma centers where measurement correlation within 5 mmHg of invasive standards commands premium positioning.
- Electrical Sensors:Tympanic membrane displacement and other electrical modalities occupy niche pediatric applications where cranial penetration risks deter invasive alternatives.
Mature deployment sits with optical sensors. Newer deployment is concentrated in ultrasonic devices.
End User:
Procurement authority concentrates where neurosurgical volume intersects with capital equipment budgeting autonomy.
- General Hospitals:Neurosurgical departments within multi-service institutions anchor revenue contribution through bundled neuromonitoring contracts. United States health systems with trauma center certification drive replacement cycles as bolt-based invasive monitoring faces substitution pressure.
- Emergency Departments:Triage protocol integration creates demand for portable, interpretation-independent devices. Pre-hospital deployment by paramedic services in Japan's METI-funded infrastructure programs represents the steepest expansion trajectory.
- Neurology Clinics:Outpatient settings favor lower-cost optical modalities for intermittent monitoring of chronic conditions with elevated ICP risk.
- Research Institutions:Algorithm validation partnerships with device manufacturers sustain non-recurring engineering revenue streams.
Volume concentration rests with general hospitals. Margin expansion concentrates in emergency departments.
Technology:
Signal processing architectures absorb computational workloads that previously required tethered consoles, collapsing hardware footprints and enabling ambulatory scenarios.
- Signal Processing:Edge-computing migration enables real-time ICP estimation without cloud dependency. FDA breakthrough device designations prioritize submissions incorporating on-device AI inference for traumatic brain injury applications.
- Transducers:Optical and ultrasonic transducer miniaturization drives form factor reduction. Single-source fiber optic foundry concentration in Germany creates supply vulnerability that multi-source procurement strategies attempt to mitigate.
- Imaging Techniques:Optical coherence tomography integration with standard ophthalmic equipment offers cross-specialty deployment pathways.
- Data Analytics:Machine learning pattern recognition enhances correlation with invasive gold standards, particularly for pediatric populations where algorithm training datasets remain limited.
Technology maturation clusters around signal processing. Emerging differentiation concentrates in data analytics.
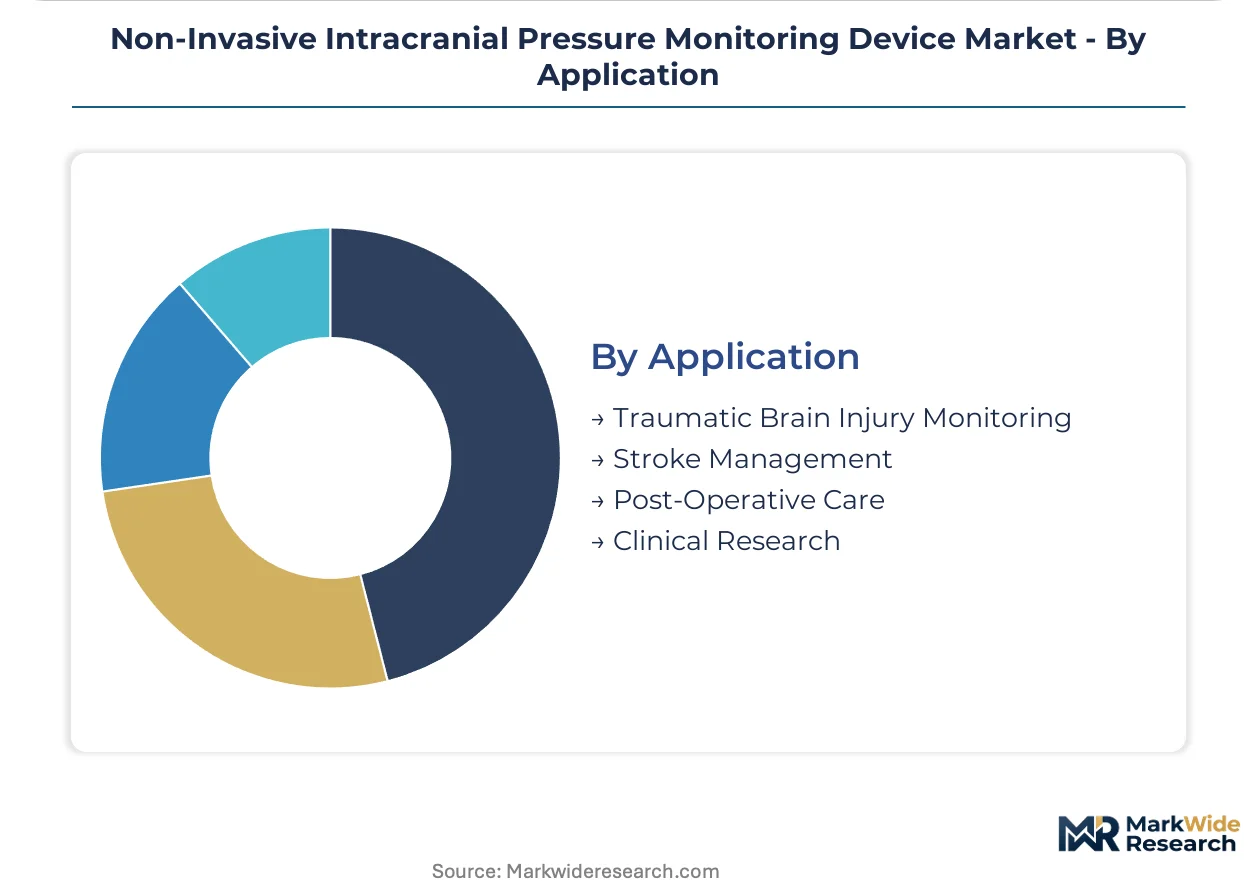
Application:
Clinical utility validation against invasive monitoring determines reimbursement parity and adoption velocity.
- Traumatic Brain Injury Monitoring:FDA 510(k) submissions and EU MDR technical documentation prioritize prospective trials in this indication. United States trauma centers represent the largest addressable population for continuous surveillance without cranial penetration.
- Post-Operative Care:Neurocritical care units require trending accuracy for secondary injury prevention. German and Japanese academic medical centers sustain premium pricing for fiber optic precision in this setting.
- Stroke Management:Hemorrhagic stroke protocols incorporate ICP monitoring for mass effect surveillance, though reimbursement codes lag device approvals.
- Clinical Research:Pediatric neurosurgical segments drive demand for non-invasive alternatives where invasive complication risks are elevated.
Established clinical validation sits with traumatic brain injury monitoring. Expanding indication development concentrates in stroke management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German-engineered fiber optic transducers anchor the upstream supply base for precision ICP monitoring components. Trauma center certification mandates and neurocritical care infrastructure investments concentrate demand across three major markets. Regulatory pathways in the United States, Germany, and Japan determine commercialization velocity for novel optical and ultrasonic modalities.
United States
Level I trauma center accreditation standards now mandate continuous intracranial surveillance capabilities without requiring invasive catheter placement. FDA breakthrough device designations compress review timelines for traumatic brain injury applications, accelerating market entry for novel modalities. Academic medical centers in Boston and Baltimore anchor algorithm validation partnerships with device developers.
Germany
EU MDR technical documentation requirements and CE marking pathways under expedited review programs accelerate European commercialization for ultrasonic sensor developers. G-BA benefit assessments determine reimbursement parity with invasive monitoring standards. Medical technology clusters in Bavaria and North Rhine-Westphalia concentrate fiber optic foundry capacity and precision transducer manufacturing.
Japan
METI-funded hospital infrastructure programs create demand for continuous bedside ICP trending without cranial penetration risks. PMDA regulatory consultations prioritize pediatric neurosurgical applications where invasive complication risks are elevated. Tokyo and Osaka metropolitan areas concentrate neurocritical care unit expansion and procurement authority for bundled neuromonitoring contracts.
United Kingdom
NHS England specialized commissioning frameworks increasingly favor non-invasive alternatives for post-operative neurocritical care monitoring. MHRA regulatory alignment with EU MDR post-Brexit maintains streamlined market access pathways for CE-marked devices. London and Manchester academic medical centers drive adoption of portable ultrasonic systems for emergency department triage protocols.
Switzerland
Swissmedic expedited review pathways for breakthrough medical devices attract developers seeking parallel European and global market entry. Reimbursement frameworks through compulsory health insurance funds support premium pricing for measurement correlation within 5 mmHg of invasive standards. Basel and Zurich clusters concentrate precision sensor engineering and neurotechnology research partnerships.
Non-Invasive Intracranial Pressure Monitoring Device Market Key Industry Players
Strategic partnerships dominate the current landscape as manufacturers secure multi-source component procurement and diversify optical sensor supply chains. The vendor base concentrates around three tiers: diversified medtech conglomerates with captive semiconductor partnerships, specialized neurosurgical device firms with German-engineered precision positioning, and emerging sensor developers pursuing FDA breakthrough designations. Portfolio diversification and technology licensing represent the primary competitive vectors, with hospitals consolidating vendor relationships around integrated neuromonitoring platforms.
Among diversified medtech conglomerates, Medtronic anchors North American distribution through specialized neurosurgical sales channels and captive semiconductor partnerships. Integra LifeSciences occupies a position within the specialized neurosurgical tier, leveraging established reimbursement codes and post-operative care relationships. RAUMEDIC AG exemplifies the German-engineered precision archetype, sustaining premium positioning in European trauma centers through fiber optic transducer accuracy.
| Leading Market Players |
|---|
| Medtronic |
| Integra LifeSciences |
| RAUMEDIC AG |
| Spiegelberg GmbH & Co. KG |
| Sophysa |
| Natus Medical |
| Gaeltec Devices |
| Vittamed |
| HeadSense Medical |
| Others |
Cost & Logistics Intelligence
Academic medical center procurement committees in the United States, Germany, and Japan command three-tier pricing structure across premium, standard, and economy levels for non-invasive intracranial pressure monitoring devices, with bundled neuromonitoring contracts consolidating vendor relationships and compressing standalone equipment margins. Optical sensor manufacturers extract premium positioning through established photodetector supply chains, while ultrasonic device developers compete on portable form factor accessibility at lower price points.
Pricing Analysis
Warranty and service bundling separates premium-tier fiber optic systems from standard optical sensors and economy ultrasonic devices, with German-engineered precision transducers including multi-year calibration support and dedicated neurophysiologist training. Price differentiation hinges on measurement correlation certification—devices validated within 5 mmHg of invasive gold standards command 40-60% premiums—and geographic delivery logistics for trauma center emergency deployment. Pricing pressure stems from CMS national coverage determination delays forcing hospitals to absorb upfront capital costs before reimbursement parity. Emergency departments exhibit highest price sensitivity due to capital budget constraints, while neurocritical care units prioritize accuracy over unit economics.
Supply Chain Analysis
Specialized semiconductor foundries in Taiwan, South Korea, and Japan face acute photodetector engineer shortages that constrain optical sensor production scaling and extend lead times for neurocritical care device manufacturers. Raw material dependencies center on indium gallium arsenide photodiodes, piezoelectric ceramics for ultrasonic transducers, and precision-drawn silica fiber from German specialty glassworks. Single-source vulnerability concentrates in two Bavarian fiber optic foundries supplying RAUMEDIC AG and European trauma center networks. Distribution runs through specialized neurosurgical sales channels anchored by academic medical center GPO contracts in Boston, Baltimore, and Tokyo metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-invasive intracranial pressure monitoring occupies a technology-transition phase as transcranial Doppler systems with embedded AI inference displace stationary optical platforms requiring specialized operator interpretation. This substitution dynamic reconfigures competitive positioning and capital allocation priorities across manufacturer tiers.
For Market Incumbents: Hedge against algorithm-agnostic portable device encroachment by deepening captive semiconductor partnerships for transducer supply continuity and securing FDA breakthrough device designations for traumatic brain injury applications before ultrasonic competitors achieve reimbursement parity. Prioritize backward integration into photodetector foundry capacity in East Asia to mitigate single-source fiber optic dependency from German precision transducer suppliers. For New Entrants and Emerging Players: Begin with pediatric neurosurgical segments where invasive monitoring complication risks elevate demand for non-invasive alternatives and regulatory pathways through FDA breakthrough designations compress review timelines. Target METI-funded hospital infrastructure programs in Japan's Tokyo and Osaka metropolitan areas for emergency department triage protocol integration, leveraging portable form factor miniaturization as the primary go-to-market wedge against incumbent optical platforms. For Investors and Strategic Acquirers: The window for entry favors sensor developers with validated algorithm performance against invasive gold standards and documented ISO 13485 quality management systems for medical device software. Long-term viability rests on reimbursement strategy execution rather than technology differentiation alone, with CMS national coverage determinations and German G-BA benefit assessments serving as the critical inflection signal for portfolio allocation decisions.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Expedited review compresses commercialization timelines for traumatic brain injury modalities ahead of standard 510(k) pathways. |
| CE Marking Pathway Under EU MDR | Technical documentation alignment with German G-BA benefit assessments secures European trauma center procurement eligibility. |
| Hospital System Partnership | Bundled neuromonitoring contracts with academic medical centers in Boston and Baltimore consolidate purchasing authority and lock out competitors. |
| Software Companion Development | Edge-computing AI inference modules embedded in transcranial Doppler systems eliminate neurophysiologist interpretation bottlenecks. |
| Reimbursement Strategy | CMS national coverage determination alignment with trauma center certification standards unlocks United States health system capital budgets. |
Research Approach
FDA 510(k) clearance databases, EU MDR technical documentation registries, and hospital procurement contract disclosures formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with neurocritical care clinicians, biomedical engineers at academic medical centers, GPO contracts managers, and regulatory affairs specialists at device manufacturers supplied clinical workflow validation and algorithm accuracy benchmarking. Bottom-up and top-down triangulation cross-referenced unit shipment estimates against capital equipment budgeting data from trauma center certification bodies.
Bottom-up modeling segmented revenue across optical sensors, ultrasonic devices, fiber optic systems, and electrical sensors by end-user vertical—general hospitals, emergency departments, neurology clinics, and research institutions—while top-down validation anchored aggregate market trajectory against neurosurgical procedure volumes and replacement cycle dynamics. CAGRs were derived from technology adoption curves weighted by reimbursement parity timelines and regulatory approval velocity. Forecast inputs incorporated photodetector supply chain capacity constraints and METI-funded infrastructure program disbursement schedules.
Underlying measurement precision varies by segment; traumatic brain injury monitoring and post-operative care applications carry tighter precision than stroke management and clinical research indications due to more extensive prospective trial data against invasive gold standards. Forecasts reflect assumptions about FDA breakthrough device review prioritization and CMS coverage determination timelines that could materially shift if regulatory staffing or neurocritical care reimbursement frameworks deviate from historical patterns. Material deviation in German fiber optic foundry output or East Asian semiconductor fabrication capacity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Minimally Invasive Laser Therapy Devices Market
Medical Devices
Vitrectomy Devices Market
Medical Devices
Canada Insulin Delivery Devices Market
Medical Devices
Indwelling Pleural Catheters Market
Medical Devices
Automatic Clotting Timer Systems Market
Medical Devices
Reusable Medical Battery Market
Medical Devices
Global Surgical Tourniquets Market
Medical Devices
Digital X-Ray Devices Market
Medical Devices
Non-Rebreathing Oxygen Mask Market
Medical Devices
Digital Intraoral Camera Market
Medical Devices
Japan Drug Delivery Devices Market
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
Catheter Securement Devices Market
Medical Devices
Low Vision Aids Market
Medical Devices
Water Flosser Market
Medical Devices
Bioactive Fillings Market