
 Zoldonat Injection Market | 2026-2036
Zoldonat Injection Market Size, Share, and Industry Trends Forecast 2026-2036
Zoldonat Injection Market Insights
Generic zoledronic acid is consolidating market share from originator formulations as patent cliffs mature and hospital procurement shifts toward cost-equivalent alternatives. Natco Pharma Limited leverages vertically integrated API-to-finished-dose capabilities to control input costs across its oncology injectables portfolio. Sun Pharmaceutical Industries Ltd. anchors its position through dominant distribution networks across Indian hospital chains and emerging African markets. Teva Pharmaceutical Industries competes on regulatory dossier breadth, holding abbreviated new drug applications across multiple reference markets.
Zoldonat Injection refers to the generic zoledronic acid formulation, a nitrogen-containing bisphosphonate administered parenterally at 4 mg/5 mL or 4 mg/100 mL concentrations to inhibit osteoclast-mediated bone resorption in malignancy-associated hypercalcemia, multiple myeloma bone disease, and metastatic bone lesions. The vial segment retains the largest volume share due to institutional preference for flexible dilution protocols in oncology infusion centers, though pre-filled syringes are gaining traction in European day-care units seeking reduced compounding error rates. The hospital end-user channel captures the dominant margin pool given the requirement for intravenous administration with hydration protocols and renal monitoring, while home care remains restricted to subcutaneous reformulation trials.
FDA bioequivalence standards and EMA biosimilar guidance frameworks govern approval pathways for generic zoledronic acid, with India's CDSCO aligning its injectable stability requirements to ICH Q1A(R2) thermal stress protocols. The EU F-Gas Regulation and US EPA emission controls are raising compliance costs for sterilization processes using hydrofluorocarbon propellants in aseptic filling lines. Stakeholders must monitor CDSCO's evolving requirements for complex generic peptide equivalence as India tightens scrutiny on parenteral oncology copies.
Market Dynamics
Hospital procurement consolidation is compressing margins for generic zoledronic acid suppliers while simultaneously raising the threshold for contract eligibility through mandatory stability data and bioequivalence documentation. This concentration of purchasing power is forcing manufacturers to absorb sterilization compliance costs and invest in automated aseptic filling lines to remain on tender lists.
Growth Catalysts
- CDSCO's ICH-aligned stability protocols:India's alignment with ICH Q1A(R2) thermal stress standards is accelerating approval timelines for domestic manufacturers seeking to export complex injectables to regulated markets.
- Oncology infusion center expansion:Hospital-based cancer treatment protocols are standardizing zoledronic acid administration alongside chemotherapy regimens, embedding the therapy into institutional purchasing agreements.
- PLI scheme for pharmaceuticals:India's production-linked incentive program is subsidizing capital investment in bisphosphonate API manufacturing, reducing import dependency for key starting materials.
Market Restraints
- EU F-Gas Regulation compliance costs:Sterilization processes using hydrofluorocarbon propellants face escalating environmental levies, raising per-unit manufacturing overhead for aseptic filling operations.
- API supply concentration in China:Domestic zoledronic acid API production remains limited, exposing finished dose manufacturers to freight volatility and customs processing delays.
- Renal monitoring requirements:Intravenous administration mandates creatinine clearance screening and hydration protocols, restricting administration to institutional settings with nursing capacity.
Strategic Opportunities
- Subcutaneous reformulation trials:Alternative delivery routes enabling outpatient administration could unlock home care channels currently blocked by infusion requirements.
- African hospital chain procurement:Emerging market health systems are consolidating oncology purchasing through regional distributors seeking cost-equivalent bisphosphonate sources.
- Pre-filled syringe adoption in European day-care units:Reduced compounding error liability is driving preference shift away from multi-dose vials in ambulatory oncology settings.
Industry Challenges
- Complex generic peptide equivalence scrutiny:CDSCO's tightening standards for parenteral oncology copies require expanded clinical endpoint studies, extending development timelines.
- Aseptic filling line qualification:Media fill validation and isolator technology upgrades demand capital deployment that mid-scale manufacturers struggle to finance.
- Cross-referencing dossier maintenance:Multiple abbreviated new drug applications across FDA, EMA, and emerging market regulators create ongoing pharmacovigilance reporting burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zoldonat Injection Market |
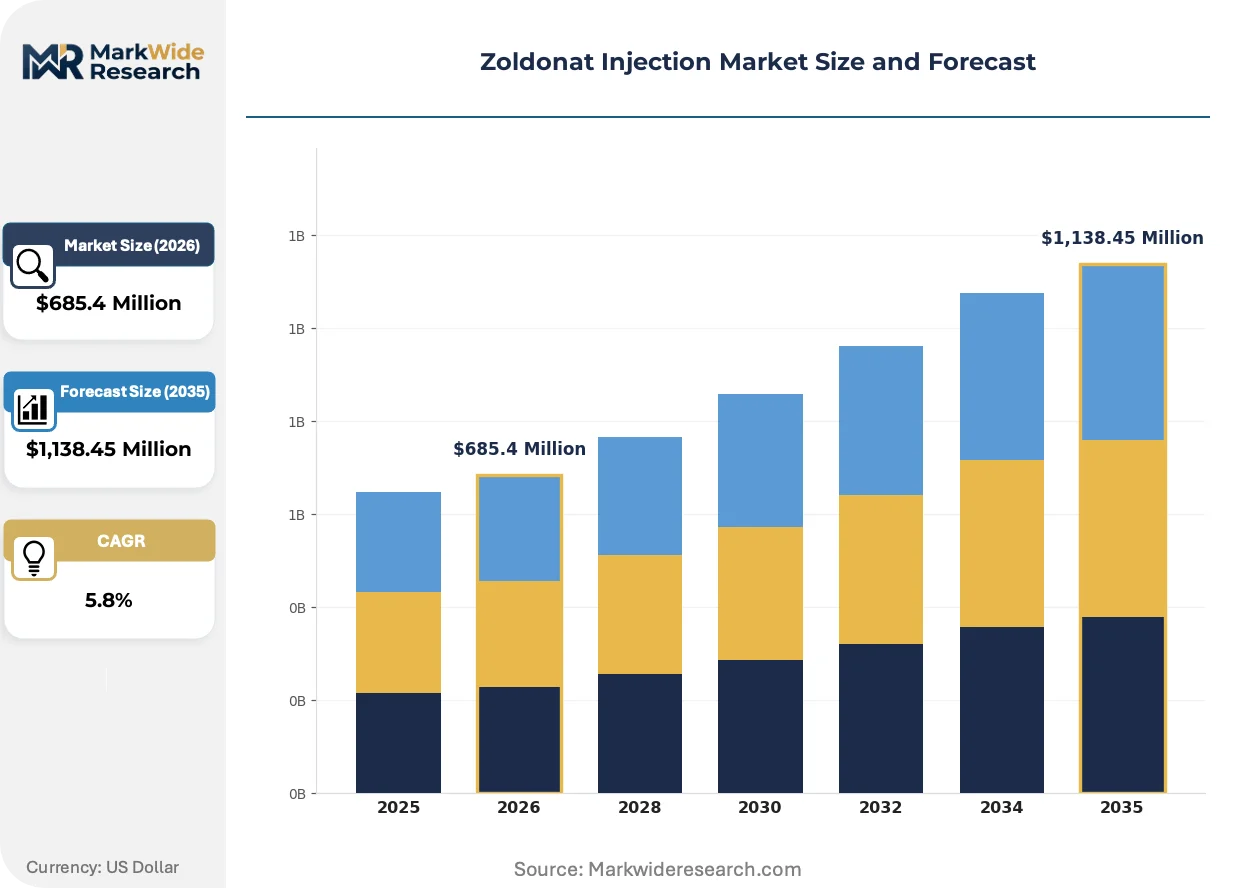
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-filled Syringes, Vials, Infusion Bags, Ampoules Application: Oncology, Osteoporosis, Pain Management, Other End User: Hospitals, Clinics, Home Care, Pharmacies Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral |
| Companies Covered | Natco Pharma Limited, Intas Pharmaceuticals Ltd., Sun Pharmaceutical Industries Ltd., Mylan N.V., Novartis AG, Teva Pharmaceutical Industries, Cipla Limited, Zydus Cadila, Dr. Reddy’s Laboratories Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zoldonat Injection Market Trends and Innovations
Automation and regulatory stringency are converging to reshape manufacturing economics and competitive positioning in generic zoledronic acid supply. The following developments are actively restructuring how products reach end-users.
Closed-system transfer devices (CSTDs) are automating hazardous drug compounding in oncology pharmacies, reducing operator exposure to cytotoxic agents during zoledronic acid preparation. Hospital systems in the United States are mandating CSTD adoption for all antineoplastic and supportive care injectables, with compliance deadlines tightening through 2025. This technology is automating manual dilution steps previously performed by pharmacy technicians, compressing preparation time while expanding documentation requirements for batch records.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in pharmaceutical manufacturing, forcing sterilization equipment retrofits or alternative technology adoption. Aseptic filling line operators face capital allocation decisions between propellant substitution and steam sterilization infrastructure conversion. European contract manufacturers serving oncology injectable markets are prioritizing nitrogen-based sterilization alternatives to maintain production continuity under tightening emission quotas.
Hospital group purchasing organizations are consolidating oncology drug tenders into multi-year sole-source agreements, displacing fragmented spot purchasing. This concentration is compressing supplier margins while demanding extended stability data and dedicated safety stock commitments. The shift is most visible in Indian hospital chains expanding into tier-2 cities, where procurement centralization is standardizing formulary decisions across previously autonomous facilities.
Zoldonat Injection Market Segmentation
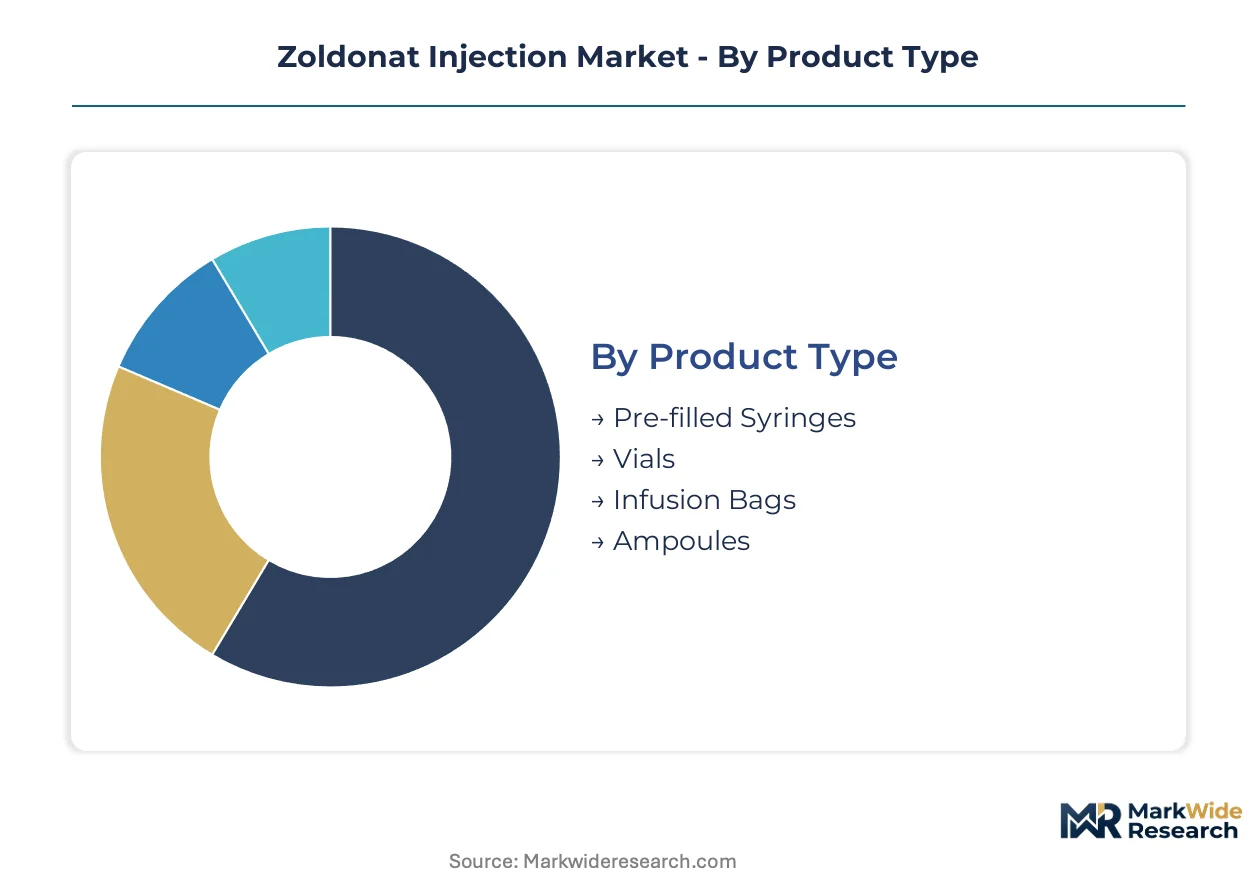
Zoldonat Injection supply chains segment sharply across container formats, clinical applications, and care settings. Each axis shapes procurement economics, regulatory dossier requirements, and competitive positioning for generic zoledronic acid manufacturers.
Product Type:
Standardization dominates high-volume oncology procurement, while customization prevails in European ambulatory settings seeking compounding risk reduction.
- Vials:Multi-dose glass containers at 4 mg/5 mL or 4 mg/100 mL concentrations enable flexible dilution protocols in hospital infusion centers. Indian hospital chains and African regional distributors specify vial formats for centralized pharmacy compounding, where batch preparation economies offset per-dose labor costs.
- Pre-filled Syringes:Single-unit presentations with pre-mixed diluent eliminate admixture steps and reduce medication error liability. European day-care oncology units in Germany and France are migrating toward this format, trading higher unit cost against reduced pharmacy technician time and closed-system transfer device compatibility.
- Infusion Bags:Large-volume parenteral containers with pre-incorporated zoledronic acid suit high-throughput chemotherapy day units seeking minimal handling steps.
- Ampoules:Break-seal glass containers serve cost-sensitive institutional tenders where single-dose integrity outweighs convenience features.
Leading the category by volume: Vials. Growing fastest: Pre-filled Syringes.
Application:
Clinical indication determines dosing frequency, reimbursement tier, and site-of-care requirements for zoledronic acid administration.
- Oncology:Malignancy-associated hypercalcemia, multiple myeloma bone disease, and metastatic bone lesions require 4 mg intravenous doses every 3-4 weeks alongside chemotherapy cycles. Hospital oncology departments in India and South Africa embed zoledronic acid into bundled cancer care protocols, creating institutional purchasing lock-in.
- Osteoporosis:Annual 5 mg dosing for postmenopausal bone density loss shifts reimbursement toward outpatient endocrinology clinics with lower per-visit infrastructure costs than infusion centers.
- Pain Management:Adjunctive use in bone metastasis palliation follows variable protocols across hospice and acute care settings.
- Other:Paget's disease and hyperparathyroidism applications represent niche prescriber segments with limited protocol standardization.
Revenue concentration peaks in Oncology. Steepest expansion trajectory: Osteoporosis as population aging extends treatable prevalence.
End User:
Care setting dictates regulatory compliance burden, cold chain requirements, and nursing supervision intensity for bisphosphonate administration.
- Hospitals:Tertiary oncology centers with on-site infusion suites, renal monitoring capacity, and hydration protocols capture the dominant procedure volume for intravenous zoledronic acid. Indian hospital chains expanding into tier-2 cities centralize procurement through group purchasing organizations.
- Clinics:Ambulatory oncology day units and infusion centers handle stabilized patients requiring shorter observation windows, with CDSCO and state pharmacy boards governing compounding standards.
- Home Care:Subcutaneous reformulation trials could eventually unlock this channel, currently blocked by intravenous administration requirements and renal safety monitoring.
- Pharmacies:Retail dispensing remains minimal given parenteral administration constraints and oncology protocol embedding.
Margin pool concentrates in Hospitals. Channel gaining share fastest: Clinics as ambulatory oncology capacity expands.
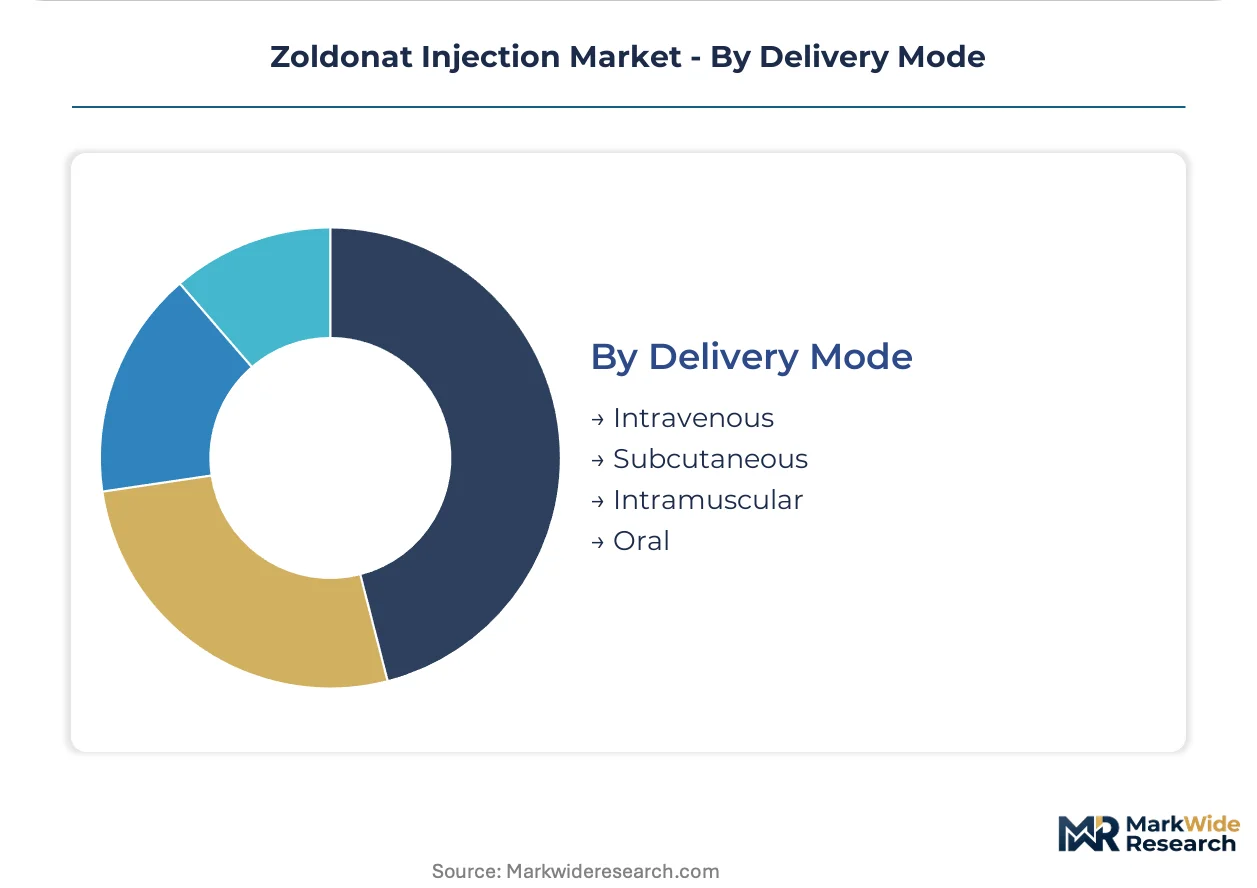
Delivery Mode:
Route of administration determines patient eligibility, site-of-care flexibility, and development pipeline priorities for formulation innovation.
- Intravenous:15-minute infusion with pre- and post-hydration remains the standard of care across all approved indications, mandating institutional settings with creatinine clearance monitoring capability.
- Subcutaneous:Investigational reformulations targeting outpatient administration could displace infusion requirements if renal safety profiles align with existing protocols.
- Intramuscular:No approved zoledronic acid products utilize this route; preclinical work explores depot formulations with extended release kinetics.
- Oral:Bioavailability limitations prevent effective oral delivery of bisphosphonate compounds due to gastrointestinal absorption barriers.
Intravenous dominates current utilization. Subcutaneous represents the most significant channel-opening opportunity if clinical trials succeed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates the dominant share of zoledronic acid demand through its expanding hospital-based oncology networks and government-backed manufacturing incentives. Hospital procurement centralization and production-linked subsidies are reshaping supply geography across four critical markets.
India
Hospital oncology departments in Mumbai, Delhi, and Bangalore drive volume through bundled cancer care protocols embedding bisphosphonate administration. CDSCO's ICH-aligned stability protocols accelerate export approvals for domestic manufacturers. The Hyderabad-Visakhapatnam pharmaceutical corridor hosts concentrated API-to-finished-dose facilities scaling capacity under the PLI scheme.
United States
Oncology group purchasing organizations consolidate tenders into multi-year agreements mandating closed-system transfer device compatibility. FDA bioequivalence standards govern abbreviated new drug application pathways for generic zoledronic acid. The Boston-Cambridge biopharma cluster influences hospital formulary standards that cascade to regional infusion networks.
Germany
Ambulatory oncology day units in Munich and Hamburg migrate toward pre-filled syringe formats to reduce compounding liability. The EU F-Gas Regulation phases down hydrofluorocarbon propellants in sterilization equipment, raising compliance costs for aseptic filling lines. The Rhine-Main pharmaceutical manufacturing belt adapts nitrogen-based sterilization alternatives to maintain production continuity.
South Africa
Regional hospital chains in Johannesburg and Cape Town consolidate oncology purchasing through distributors seeking cost-equivalent bisphosphonate sources. The national health department's centralized tender system prioritizes suppliers with WHO prequalification status. The Durban-Pinetown pharmaceutical logistics hub handles import distribution for southern African markets.
Zoldonat Injection Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with originator formulations defending oncology hospital contracts while generic suppliers capture tender-driven volume. The vendor base organizes into three tiers: vertically integrated API producers, regional hospital distributors, and multinational dossier holders. Dominant competitive moves include backward integration into bisphosphonate API manufacturing and automated aseptic filling line qualification for regulatory maintenance.
Among Indian pharmaceutical conglomerates, Natco Pharma Limited and Sun Pharmaceutical Industries Ltd. occupy positions reflecting vertically integrated production architectures, while Teva Pharmaceutical Industries exemplifies the multinational generic dossier holder archetype with abbreviated new drug application breadth across reference markets.
| Leading Market Players |
|---|
| Natco Pharma Limited |
| Intas Pharmaceuticals Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Mylan N.V. |
| Novartis AG |
| Teva Pharmaceutical Industries |
| Cipla Limited |
| Zydus Cadila |
| Dr. Reddy's Laboratories Ltd. |
| Others |
Pricing and Supply Chain Analysis
The EU F-Gas Regulation gates qualified supply for European contract manufacturers and anchors premium-tier pricing access for compliant aseptic filling operators, while Indian PLI scheme beneficiaries capture standard-tier volume through subsidized API production.
Pricing Analysis
High-volume vial formats for Indian hospital chains trade margin for procurement scale, while pre-filled syringe premiums in German ambulatory units reflect compounding liability reduction. Price differentiation hinges on CDSCO certification tier and closed-system transfer device compatibility. Cost compression in standard vial tiers intensifies as group purchasing organizations consolidate oncology tenders. Tender-driven hospital chains in South Africa exhibit highest price sensitivity; European day-care units seeking medication error reduction show lowest.
Supply Chain Analysis
Freight volatility from API supply concentration in China exposes finished dose manufacturers to customs processing delays and working capital strain. Zoledronic acid API production draws from China, India, and limited European sources. Key inputs encompass bisphosphonate starting materials, glass vial components, and sterilization-grade nitrogen. Single-source vulnerability in Chinese API intermediates threatens continuity. Distribution runs through regional hospital distributors and group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation creates a barrier-to-entry moat for compliant aseptic filling operators, justifying premium positioning for sterilization-capitalized incumbents while excluding mid-scale challengers from European tender eligibility.
For Market Incumbents: Acquire automated isolator technology and nitrogen-based sterilization infrastructure to defend European market access against regulatory exclusion. Backward integration into zoledronic acid API manufacturing through the Indian PLI scheme reduces Chinese import dependency. Prioritize CDSCO stability data investment to maintain tender eligibility as complex generic scrutiny tightens.
For New Entrants and Emerging Players: Subcutaneous reformulation platforms offer the most penetrable wedge for home care channel entry currently blocked by intravenous requirements. Target African regional distributors consolidating oncology purchasing through WHO prequalification pathways. Lead with bioequivalence dossier breadth rather than manufacturing scale to secure reference market approvals.
For Investors and Strategic Acquirers: CDSCO approval timeline acceleration for ICH-aligned domestic manufacturers is the leading indicator that vertically integrated Indian producers will capture export share. Five-to-ten year viability favors API-to-finished-dose operators with captive sterilization capacity. Monitor EU F-Gas Regulation compliance deadline adherence as inflection signal for European contract manufacturer consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | CDSCO ICH alignment accelerates export eligibility for Indian manufacturers into EMA reference markets. |
| Manufacturing Scale-Up | PLI-subsidized API capacity in Hyderabad-Visakhapatnam corridor reduces import dependency for bisphosphonate starting materials. |
| Green Manufacturing Transition | Nitrogen-based sterilization retrofits preserve European production continuity under tightening F-Gas emission quotas. |
| Long-term Supply Agreement | Multi-year oncology tender commitments with Indian hospital chains lock in volume against spot purchasing volatility. |
| Pipeline Diversification | Subcutaneous reformulation trials unlock home care channels currently restricted to institutional infusion settings. |
Research Methodology
Multi-period observation of CDSCO approval timelines, PLI scheme disbursement patterns, and EU F-Gas Regulation compliance deadlines anchored the trend analysis, supplemented by interviews with regulatory affairs leads at Indian pharmaceutical conglomerates, oncology formulary directors at Mumbai and Delhi hospital chains, aseptic filling operations managers in the Rhine-Main manufacturing belt, and procurement officers at South African regional distributors. Secondary validation drew from FDA ANDA filings, EMA centralized procedure outcomes, CDSCO injectable stability guidance documents, and Indian Ministry of Chemicals PLI scheme progress reports. Bottom-up demand modeling across hospital, clinic, and ambulatory channels triangulated against top-down API production capacity assessments.
Segment-weighting applied product type, clinical application, end-user channel, and delivery mode dimensions across the projection horizon, with regional regulatory clusters treated as distinct growth corridors. CAGRs derived from patient volume projections tied to oncology protocol penetration rates, dosing frequency by indication, and reimbursement tier evolution. Forecast inputs incorporated hospital procurement consolidation velocity, sterilization technology substitution costs, and subcutaneous reformulation clinical trial milestones.
Forecast precision tightens around the base case; tail outcomes carry wider variance under CDSCO enforcement escalation, Chinese API export restriction scenarios, or accelerated EU F-Gas phase-down schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
United Kingdom OTC Drugs Market
Pharmaceuticals
Pharmaceutical Elixir Market
Pharmaceuticals
Anti-Viral Therapeutics Market
Pharmaceuticals
Asia-Pacific GLP 1 Agonist Market
Pharmaceuticals
Bendamustin Market
Pharmaceuticals
Soft Capsules Drugs Market
Pharmaceuticals
Adenosine Market
Pharmaceuticals
Oxaliplatin Market
Pharmaceuticals
TNF Inhibitors Market
Pharmaceuticals
Asia-Pacific Vaccines Market
Pharmaceuticals
Injectable Targeted Therapy Market
Pharmaceuticals
Leukotriene Modifiers Market
Pharmaceuticals
Global Pericarditis Drugs Market
Pharmaceuticals
Zoledronic Acid Market
Pharmaceuticals
Global Doxorubicin Market