
 Cholesterol Monitors Market | 2026-2036
Cholesterol Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Cholesterol Monitors Market Outlook
Clinical-grade accuracy tiers is rotating toward the center of competitive strategy as home users and physicians demand laboratory-correlated results from portable formats. Abbott Laboratories leverages dual-wavelength optical detection to sustain precision leadership in self-testing segments. Roche Diagnostics anchors professional laboratory workflows with enzymatic assay platforms that dominate hospital lipid panel throughput. Siemens Healthineers competes on integrated health informatics, connecting cholesterol data directly to electronic medical records for care coordination.
Cholesterol monitors are analytical instruments that quantify total cholesterol, HDL, LDL, and triglyceride concentrations in whole blood, serum, or plasma through enzymatic or electrochemical reactions, typically requiring sample volumes between five and forty microliters and delivering results within sixty to one hundred eighty seconds for point-of-care applications. Their primary commercial purpose is enabling cardiovascular risk stratification outside centralized laboratories, reducing time-to-treatment decisions for dyslipidemia management. Portable devices lead volume shipments due to pharmacy and direct-to-consumer channels, while wearable monitors represent the fastest-growing category as continuous metabolite tracking integrates with fitness ecosystems. Electrochemical sensors capture the largest installed base because of strip-based cost structures, yet biosensor platforms attract margin concentration through multi-analyte expansion into glucose and ketone combination testing.
FDA 510(k) pathways and CLIA waiver classifications determine market access speed for cholesterol monitors in the United States, with waived status enabling operation in pharmacies, elder care centers, and retail clinics without laboratory director oversight. ISO 15197 and IEC 61010 standards govern European and international electrical safety and analytical performance benchmarks, creating compliance cost barriers for emerging manufacturers. Stakeholders must monitor evolving remote patient monitoring reimbursement codes and integrated diagnostic platform strategies that bundle cholesterol testing with broader metabolic panels.
Market Dynamics
The cholesterol monitors market is pivoting toward clinical-grade accuracy in portable formats as home users and physicians demand laboratory-correlated results from handheld devices, compressing the traditional performance gap between point-of-care and central laboratory systems.
Growth Catalysts
- CLIA-waived device standards:FDA clearance pathways in the United States enable pharmacy-based screening without laboratory director oversight, accelerating retail clinic deployment and expanding accessible testing locations for cardiovascular risk management.
- Enzymatic assay miniaturization:Strip-based electrochemical sensors now achieve precision thresholds previously requiring benchtop equipment, driving replacement cycles in elder care centers and home health settings managing chronic dyslipidemia.
- Germany's preventive care reimbursement:Pharmacy-based lipid screening programs create sustained institutional demand for point-of-care systems, with statutory health insurance coverage removing cost barriers for routine cardiovascular monitoring.
Market Restraints
- Enzyme reagent stability:Temperature-sensitive biosensor strips degrade in distribution channels lacking cold-chain infrastructure, constraining market penetration in tropical climates and remote geographies with intermittent supply logistics.
- Optical component concentration:Precision photodiodes and interference filters for dual-wavelength detection concentrate among Japanese and German component suppliers, creating input bottlenecks for manufacturers outside established electronics supply networks.
- Substitution by laboratory panels:Centralized laboratories offer comprehensive lipid profiles at lower per-test cost for insured populations, limiting price elasticity in segments where reimbursement favors traditional diagnostic workflows over self-monitoring.
Strategic Opportunities
- Continuous metabolite wearables:Integration of cholesterol sensing with fitness ecosystems creates white space for devices tracking lipid fluctuations during exercise and dietary interventions, targeting wellness-oriented consumers outside traditional medical channels.
- Remote patient monitoring reimbursement:Evolving CPT codes for integrated diagnostic platforms bundle cholesterol testing with broader metabolic panels, enabling subscription revenue models for connected monitoring services in United States Medicare populations.
- Multi-analyte biosensor expansion:Combination testing for glucose, ketones, and lipids on single-strip platforms captures margin concentration from diabetic patients requiring comprehensive metabolic surveillance, consolidating device ecosystems for chronic disease management.
Industry Challenges
- ISO 15197 correlation studies:Manufacturers must demonstrate laboratory-grade accuracy across hematocrit ranges and interfering substances, extending certification timelines and requiring substantial clinical validation investment before market entry.
- Legacy EMR integration:Point-of-care devices face technical friction connecting cholesterol data to fragmented electronic medical record systems, complicating care coordination and reducing physician adoption of portable testing workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cholesterol Monitors Market |
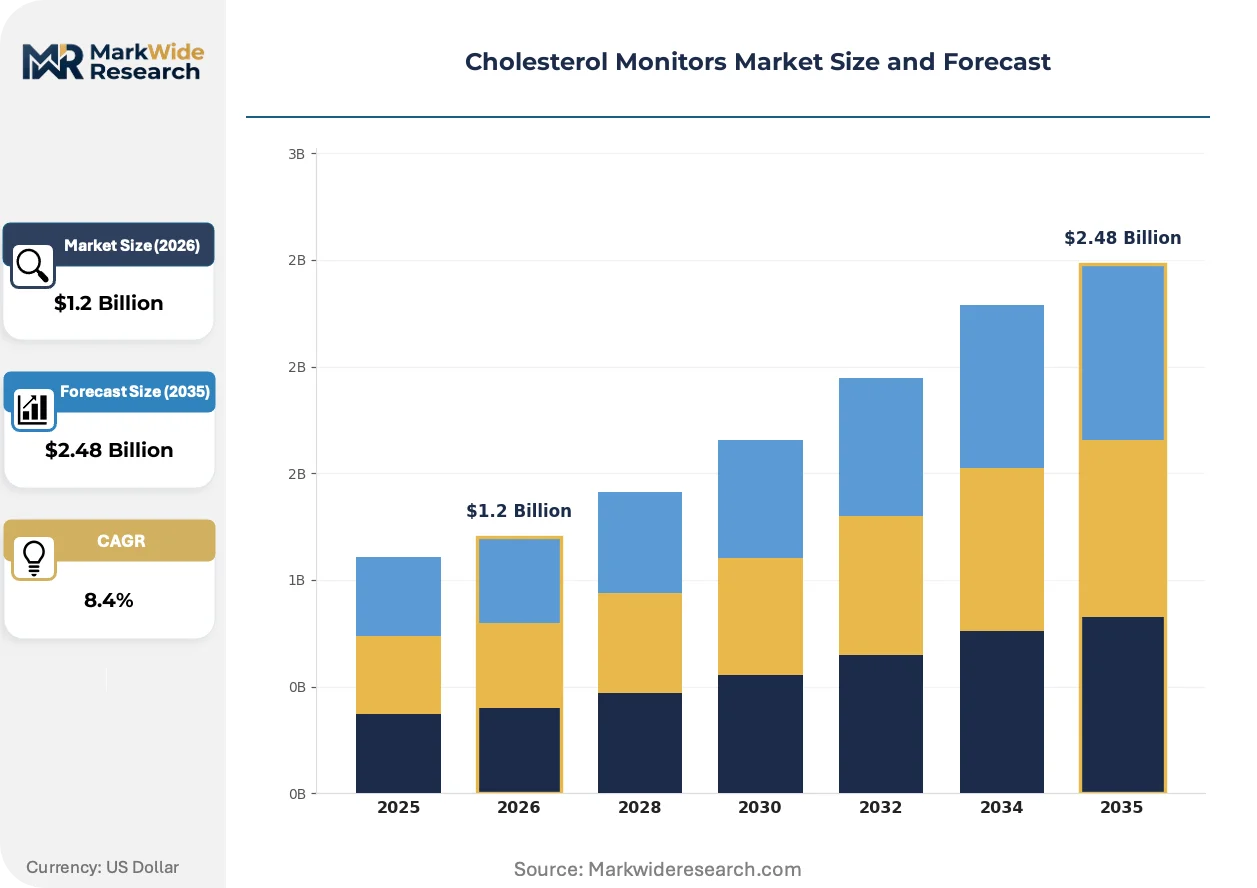
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Desktop Analyzers, Wearable Monitors, Test Strips Kits Technology: Electrochemical Sensors, Optical Sensors, Biosensor Platforms, Enzymatic Assays Application: Home Testing, Clinical Diagnostics, Remote Patient Monitoring, Fitness Tracking End User: Diagnostic Laboratories, Healthcare Practitioners, Pharmacies, Elder Care Centers |
| Companies Covered | Abbott Laboratories, Roche Diagnostics, PTS Diagnostics, ACON Laboratories, Inc., ARKRAY Inc., Siemens Healthineers, Thermo Fisher Scientific, Randox Laboratories, Omron Healthcare, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cholesterol Monitors Market Strategic Shifts
Portable cholesterol monitoring is fragmenting into divergent performance tiers as clinical accuracy demands collide with consumer convenience expectations, reshaping how manufacturers segment their development roadmaps and distribution partnerships.
Electrochemical biosensor technology is bifurcating between premium enzymatic platforms achieving laboratory correlation and economy strip formats sacrificing precision for cost reduction. Hospital outpatient departments and cardiology clinics adopt the former for treatment decisions, while direct-to-consumer channels absorb the latter for wellness screening. This split is compressing mid-tier positioning and forcing manufacturers to commit explicitly to clinical or consumer positioning.
Europe's MDR implementation tightens analytical performance documentation for in-vitro diagnostic devices, extending conformity assessment timelines for cholesterol monitors seeking CE marking. Manufacturers must submit expanded clinical evidence packages demonstrating traceability to reference methods. Professional laboratory segments face the steepest compliance burden, while self-testing categories navigate notified body capacity constraints through early engagement strategies.
Pharmacy channel consolidation is displacing traditional medical device distribution for point-of-care lipid testing. Large retail health chains in Germany and the United States negotiate direct procurement relationships with manufacturers, extracting volume discounts and private-label arrangements that bypass independent distributor margins. This concentration is most visible in pharmacy-based screening programs where formulary decisions centralize across national retail networks rather than individual clinic purchasing.
Cholesterol Monitors Market Segmentation
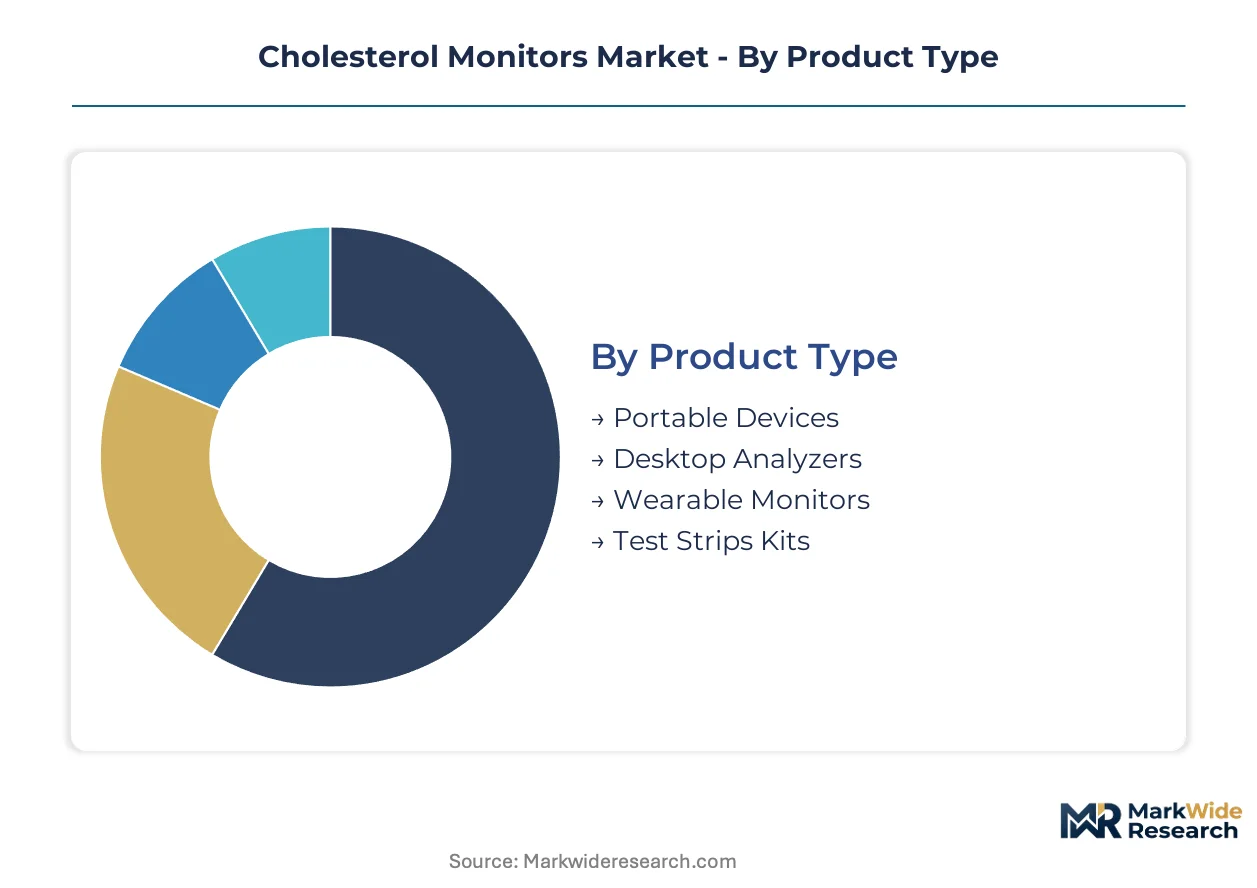
Cholesterol monitors fragment across four intersecting dimensions that determine pricing power, regulatory pathway, and channel strategy. Product format dictates whether manufacturers pursue FDA 510(k) clearance or wellness-device positioning. Technology choice separates laboratory-correlated precision from consumer-accessible convenience tiers.
Product Type:
Domestic demand concentrates in portable formats for pharmacy and elder care deployment, while export markets absorb specialized laboratory equipment and emerging wearable categories.
- Portable Devices:Handheld units employing strip-based electrochemical detection dominate pharmacy-based screening programs in Germany and retail clinic networks across the United States. Elder care centers in Japan favor these for bedside lipid monitoring without laboratory infrastructure.
- Desktop Analyzers:Benchtop systems with automated sample handling and integrated quality control serve hospital outpatient departments requiring throughput for cardiology clinics. Demand clusters in tertiary care centers across France and Italy where centralized lipid panels remain standard.
- Wearable Monitors:Continuous metabolite tracking devices integrate with fitness ecosystems for wellness-oriented consumers.
- Test Strips Kits:Disposable consumables drive recurring revenue in home testing segments across direct-to-consumer channels.
Portable devices command the established base. The steepest expansion runs through wearable monitors.
Technology:
Cost tier stratification separates premium enzymatic platforms achieving laboratory correlation from economy electrochemical formats sacrificing precision for accessibility.
- Electrochemical Sensors:Strip-based amperometric detection captures the largest installed base through cost-engineered manufacturing in East Asian electronics clusters. German pharmacy screening programs and United States retail clinics absorb volume shipments for point-of-care lipid testing.
- Enzymatic Assays:Reference-method traceability distinguishes professional laboratory platforms requiring cold-chain reagent stability. Hospital systems in Switzerland and Austria specify these for treatment decisions in dyslipidemia management.
- Optical Sensors:Dual-wavelength photometry enables reflectance-based measurement in compact formats.
- Biosensor Platforms:Multi-analyte expansion into glucose and ketone combination testing attracts margin concentration from diabetic patient populations.
Electrochemical sensors anchor volume deployment. Enzymatic assays capture premium positioning in clinical settings.
Application:
Customer type divergence separates medical-channel reimbursement dependence from wellness-market direct payment models.
- Home Testing:Self-monitoring by elderly patients managing chronic cardiovascular conditions accelerates through pharmacy distribution and direct-to-consumer e-commerce. German statutory health insurance reimbursement removes cost barriers for routine testing.
- Clinical Diagnostics:Physician-directed lipid panel testing in cardiology and primary care settings demands laboratory-correlated accuracy for treatment decisions. United States hospital outpatient departments specify CLIA-waived devices for workflow efficiency.
- Remote Patient Monitoring:Connected devices transmitting cholesterol data to care teams enable subscription revenue models.
- Fitness Tracking:Wellness-oriented consumers outside medical channels pursue lipid fluctuation visibility during dietary interventions.
Clinical diagnostics retains the revenue concentration. Fitness tracking gains share fastest among wellness-integrated applications.
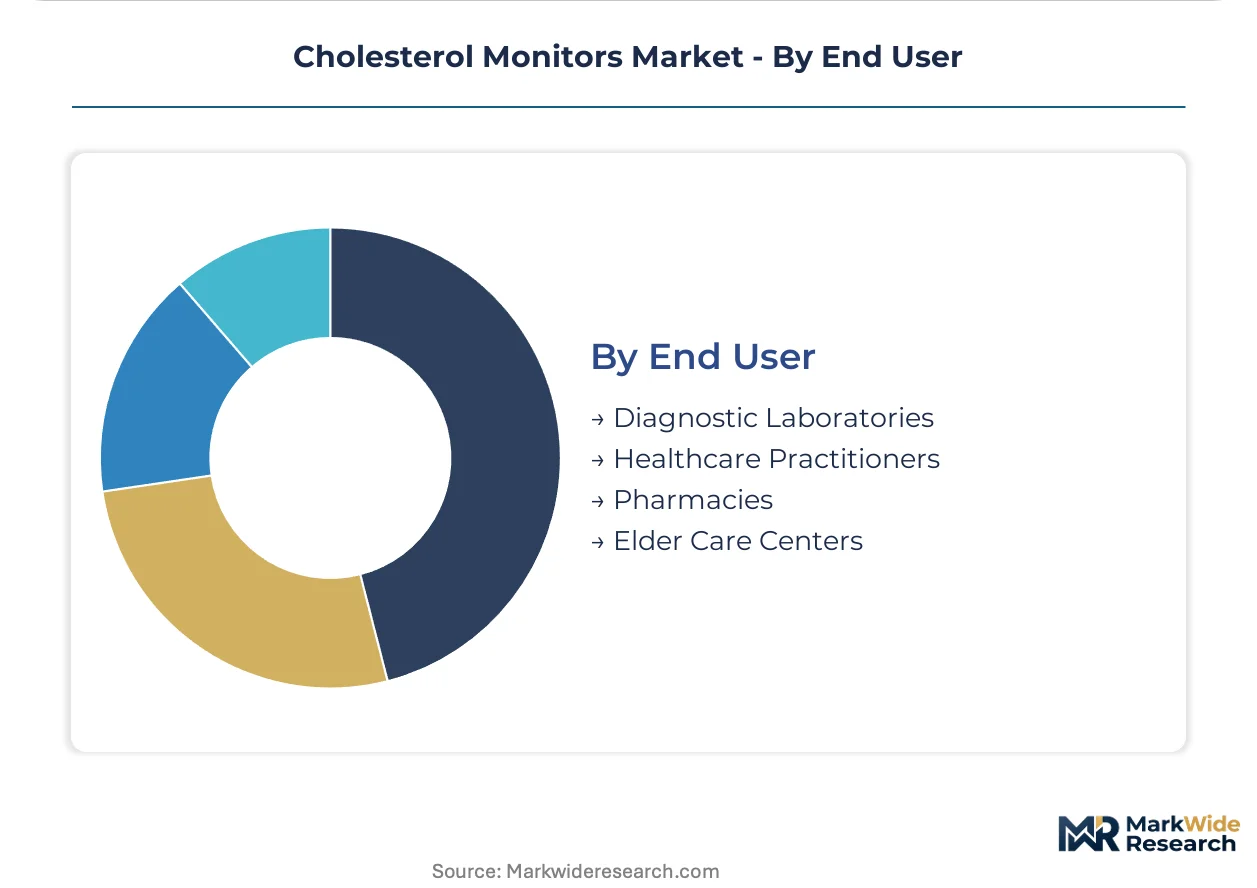
End User:
Procurement authority is shifting toward consolidated retail health chains that negotiate direct manufacturer relationships, displacing independent distributor networks.
- Diagnostic Laboratories:Centralized facilities with automated analyzers and reference method traceability dominate throughput volume in hospital systems across France and Italy.
- Healthcare Practitioners:Physician offices and cardiology clinics adopt portable devices for immediate treatment decisions, particularly in United States Medicare populations where time-to-diagnosis affects reimbursement.
- Pharmacies:Retail health chains in Germany and the United States centralize formulary decisions for point-of-care lipid screening programs.
- Elder Care Centers:Long-term care facilities managing chronic dyslipidemia prioritize ease-of-use and minimal training requirements.
Diagnostic laboratories maintain the equipment base. Pharmacies drive the steepest volume expansion through screening program deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports point-of-care lipid testing systems to pharmacy networks across Central Europe, while the United States supplies CLIA-waived devices to retail clinic chains in Canada and Mexico. Japan ships compact optical detection components to manufacturers in South Korea and Taiwan.
United States
Retail health chains and elder care centers drive procurement of portable cholesterol monitors for cardiovascular risk management. FDA 510(k) pathways and CLIA waiver classifications enable pharmacy-based screening without laboratory director oversight. Minneapolis and Boston host development clusters for dual-wavelength optical detection systems.
Germany
Statutory health insurance reimbursement for preventive lipid screening sustains institutional demand from pharmacy networks. MDR implementation tightens analytical performance documentation for in-vitro diagnostic devices seeking CE marking. Frankfurt and Munich concentrate manufacturing of enzymatic assay platforms for professional laboratory segments.
Japan
Elder care facilities prioritize bedside lipid monitoring devices requiring minimal training and infrastructure. PMDA regulatory frameworks govern approval timelines for electrochemical biosensor technologies. Osaka and Nagoya anchor precision photodiode and interference filter production for dual-wavelength detection systems.
China
Domestic manufacturing clusters supply cost-engineered electrochemical sensor strips to Southeast Asian and African markets. NMPA standards and GB technical regulations shape product registration requirements for imported diagnostic equipment. Shenzhen and Shanghai concentrate strip-based manufacturing for economy-tier wellness devices.
India
Cardiology clinics in tier-2 cities adopt portable monitors to reduce time-to-treatment for dyslipidemia patients. CDSCO regulates import and manufacture of in-vitro diagnostic devices under the Medical Devices Rules framework. Hyderabad and Bengaluru host diagnostic technology development centers serving domestic and export markets.
Cholesterol Monitors Market Competitive Environment
Listed leaders compete with private specialists across technology licensing and distribution channel control. The vendor base spans three tiers: multinational conglomerates with integrated health informatics platforms, mid-scale diagnostic specialists with enzymatic assay expertise, and regional manufacturers focused on cost-optimized strip production. Strategic archetypes include precision-technology leaders, multi-analyte platform integrators, and pharmacy-channel consolidators. Dominant competitive moves encompass direct procurement relationships with retail health chains and portfolio expansion into continuous metabolite wearables.
Among precision-technology leaders, Abbott Laboratories and Roche Diagnostics exemplify the dual-wavelength optical detection and enzymatic assay platform archetypes respectively. Siemens Healthineers occupies a position within the integrated health informatics tier. These three entities represent contrasting strategic commitments: optical precision leadership, laboratory workflow dominance, and care coordination connectivity.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Diagnostics |
| PTS Diagnostics |
| ACON Laboratories, Inc. |
| ARKRAY Inc. |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Randox Laboratories |
| Omron Healthcare, Inc. |
| Others |
Value Chain & Pricing Dynamics
Strip manufacturing scale economies in East Asian electronics clusters compress unit economics for electrochemical sensor production, concentrating cost leadership among high-volume producers while forcing smaller manufacturers toward premium enzymatic assay positioning or exit. This scale asymmetry anchors price floors for economy-tier wellness devices and amplifies margin pressure on mid-tier portable monitors lacking differentiation.
Pricing Analysis
Next-generation biosensor platforms command substantial premiums over mature electrochemical strip formats, while prior-generation optical reflectance systems face accelerated price erosion. Three-tier pricing structure across premium enzymatic, standard electrochemical, and economy optical tiers reflects certification-grade differentiation, with FDA 510(k) clearance and CLIA waiver status driving substantial price premiums. Pricing pressure stems from pharmacy chain consolidation extracting volume discounts through direct procurement. Home testing segments exhibit highest price sensitivity, while hospital outpatient departments prioritize accuracy over cost.
Supply Chain Analysis
Precision photodiode and interference filter supply concentrates among Japanese and German component manufacturers, creating input bottlenecks for dual-wavelength detection systems. Strip-based electrochemical production draws from Chinese and South Korean electronics manufacturing, while enzymatic reagent formulation rests on Swiss and Austrian cold-chain logistics. Single-source vulnerability in optical component supply threatens production continuity for clinical-grade portable devices. Distribution runs through consolidated retail health chains in Germany and the United States, displacing independent medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing capability for laboratory-correlated accuracy in portable formats remains scarce, with enzymatic assay miniaturization expertise and dual-wavelength optical engineering talent concentrated among a handful of established players. This skill gap constrains competitive entry and sustains premium positioning for incumbents mastering both precision and portability.
For Market Incumbents: Secure CLIA-waived certification portfolios to defend pharmacy channel access against emerging multi-analyte competitors. Deepen backward integration into precision optical component supply through captive production or long-term offtake agreements with Japanese photodiode manufacturers, mitigating single-source exposure that threatens dual-wavelength detection platforms. For New Entrants and Emerging Players: Remote patient monitoring data integration services present an underserved layer where established device manufacturers lack software-native capabilities. Fitness-tracking wellness segments offer the most penetrable entry point, with direct-to-consumer e-commerce enabling bypass of consolidated pharmacy procurement. Lead with subscription-based metabolite tracking platforms rather than hardware-first positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors multi-analyte biosensor platforms combining glucose, ketone, and lipid sensing on single-strip architectures. Long-term viability hinges on regulatory clearance velocity and EMR integration depth rather than hardware cost alone. Watch for CPT code expansion for integrated diagnostic platforms as the inflection signal validating subscription revenue models.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Waiver Pathway Acceleration | FDA clearance velocity determines pharmacy channel access speed against competitors. |
| Multi-Analyte Strip Development | Combination glucose-ketone-lipid testing captures diabetic patient wallet share consolidation. |
| EMR Integration Partnership | Direct data connectivity to hospital systems reduces physician workflow friction substantially. |
| Retail Health Chain Direct Procurement | Volume discount extraction bypasses distributor margins and locks formulary positioning. |
| Continuous Metabolite Wearable Investment | Fitness ecosystem integration opens wellness consumer segments outside medical reimbursement. |
Study Parameters
Cross-validation between primary interviews with regulatory affairs specialists and secondary analysis of FDA 510(k) filings anchors the qualitative findings on clearance pathway dynamics. Conversations with hospital purchasing committee members, pharmacy procurement directors, biomedical engineers at elder care centers, and GPO contracts managers combined with CMS Medicare reimbursement data, hospital procurement databases, and CLIA waiver registries. Bottom-up shipment estimates and top-down epidemiological demand modeling triangulate market sizing across the analysis window.
Sensitivity analysis on reimbursement policy scenarios and technology substitution rates frames the forecast uncertainty. Segmentation modeling spans product format, detection technology, application setting, and end-user procurement authority, with regional regulatory clusters capturing FDA, MDR, PMDA, and NMPA pathway differences. CAGRs derive from installed base replacement cycles and expansion coefficients applied to chronic disease prevalence trends, with enzymatic assay miniaturization timelines and wearable sensor maturation curves as key technology inputs.
Underlying assumptions cover stable CLIA waiver reimbursement codes and continued pharmacy channel consolidation, with deviation risk concentrated in remote patient monitoring CPT code expansion delays and optical component supply disruptions. Practitioners should keep alternative scenarios live as MDR implementation timelines and fitness ecosystem partnership structures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ultrasound Probe Market
Medical Devices
Europe Sperm Separation Devices Market
Medical Devices
ePTFE Vascular Prosthesis Market
Medical Devices
Tubal Obstruction Devices Market
Medical Devices
Implantable Pulse Generator Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Global Digital Pathology Systems Market
Medical Devices
Fracture Fixation Products Market
Medical Devices
Table-Top Autorefractor Market
Medical Devices
Global Medical Composite Market
Medical Devices
Low Vision Aids Market
Medical Devices
Smart Vision Aids Market
Medical Devices
Global Blood Transfusion Devices Market
Medical Devices
Australia Spinal Surgery Devices Market
Medical Devices
Echogenic Catheters Market
Medical Devices
Platelet Concentration Systems Market