
 Double-Lumen Biliary Catheters Market | 2026-2036
Double-Lumen Biliary Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Double-Lumen Biliary Catheters Market Analysis
Software-defined pressure monitoring and embedded sensor subscriptions is shifting the value proposition from disposable hardware to procedure-integrated platforms. Boston Scientific Corporation leverages its endoscopy ecosystem to bundle catheter placement with real-time analytics services. Cook Medical anchors its competitive stance through deep specialization in biliary access devices and physician training infrastructure. Merit Medical Systems competes on manufacturing scale, operating high-volume catheter production lines that sustain cost positions across hospital procurement channels.
Double-lumen biliary catheters are dual-channel flexible tubes engineered from silicone or polyurethane with distinct lumens for simultaneous drainage and guidewire access, typically ranging 7-12 Fr in diameter and designed to maintain patency during percutaneous transhepatic cholangiography or endoscopic biliary procedures. Hydrophilic coated material variants command attention where tortuous anatomy demands enhanced trackability, while silicone constructions dominate long-term indwelling applications due to superior biocompatibility and reduced encrustation. Among end users, hospitals absorb the majority of catheter volumes through centralized interventional radiology and gastroenterology departments, whereas ambulatory surgical centers represent the fastest structural expansion as same-day biliary procedures migrate from inpatient settings.
FDA 510(k) clearance requirements and the EU Medical Device Regulation shape product development cycles, with both frameworks mandating enhanced biocompatibility testing and clinical performance documentation for permanent implant contact devices. The EPA and OSHA additionally govern sterilization byproduct handling and ethylene oxide exposure limits at manufacturing facilities, influencing plant location and compliance cost structures. Stakeholders must monitor how reimbursement shifts toward bundled episode payments reshape catheter selection criteria across hospital purchasing committees.
Market Dynamics
The migration of biliary procedures from inpatient to ambulatory settings is compressing catheter utilization cycles and forcing manufacturers to redesign products for same-day discharge protocols.
Growth Catalysts
- Endoscopic Retrograde Cholangiopancreatography (ERCP) Volume Expansion:Hospital systems in the United States, Germany, and Japan are expanding dedicated interventional gastroenterology suites to accommodate rising procedural demand for biliary obstruction management.
- FDA 510(k) Pathway Modernization:Enhanced premarket validation requirements for permanent implant contact devices are accelerating biocompatibility testing investments among manufacturers seeking durable competitive positioning.
- Silicone Material Advancement:Superior biocompatibility and reduced encrustation properties in silicone constructions are extending indwelling durations and reducing replacement frequency in long-term biliary drainage applications.
Market Restraints
- Ethylene Oxide Sterilization Constraints:EPA and OSHA exposure limits at manufacturing facilities are restricting plant capacity expansion and elevating compliance cost structures for catheter producers.
- Single-Source Polyurethane Supply Concentration:Medical-grade polymer feedstock availability remains concentrated among specialty chemical suppliers in Germany and the United States, creating input cost volatility.
- Technical Limitation in Tortuous Anatomy Navigation:Standard catheter constructions face trackability constraints in complex biliary tree anatomies, limiting procedural success rates without hydrophilic coated variants.
Strategic Opportunities
- Ambulatory Surgical Center Channel Penetration:Same-day biliary procedure migration creates demand for simplified catheter delivery systems optimized for outpatient interventional radiology workflows.
- Software-Defined Pressure Monitoring Convergence:Integration of embedded sensor subscriptions with catheter hardware enables recurring revenue models and procedure-integrated analytics platforms.
- EU Medical Device Regulation (MDR) Compliance Differentiation:Enhanced clinical performance documentation requirements create competitive separation for manufacturers with robust post-market surveillance infrastructure.
Industry Challenges
- Interventional Gastroenterologist Training Pipeline Constraints:Specialized ERCP procedural expertise remains concentrated among aging physician cohorts, limiting procedure volume scalability.
- FDA 510(k) Clearance Timeline Compression:Premarket submission preparation for biocompatibility testing and clinical validation documentation extends product development cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Double-Lumen Biliary Catheters Market |
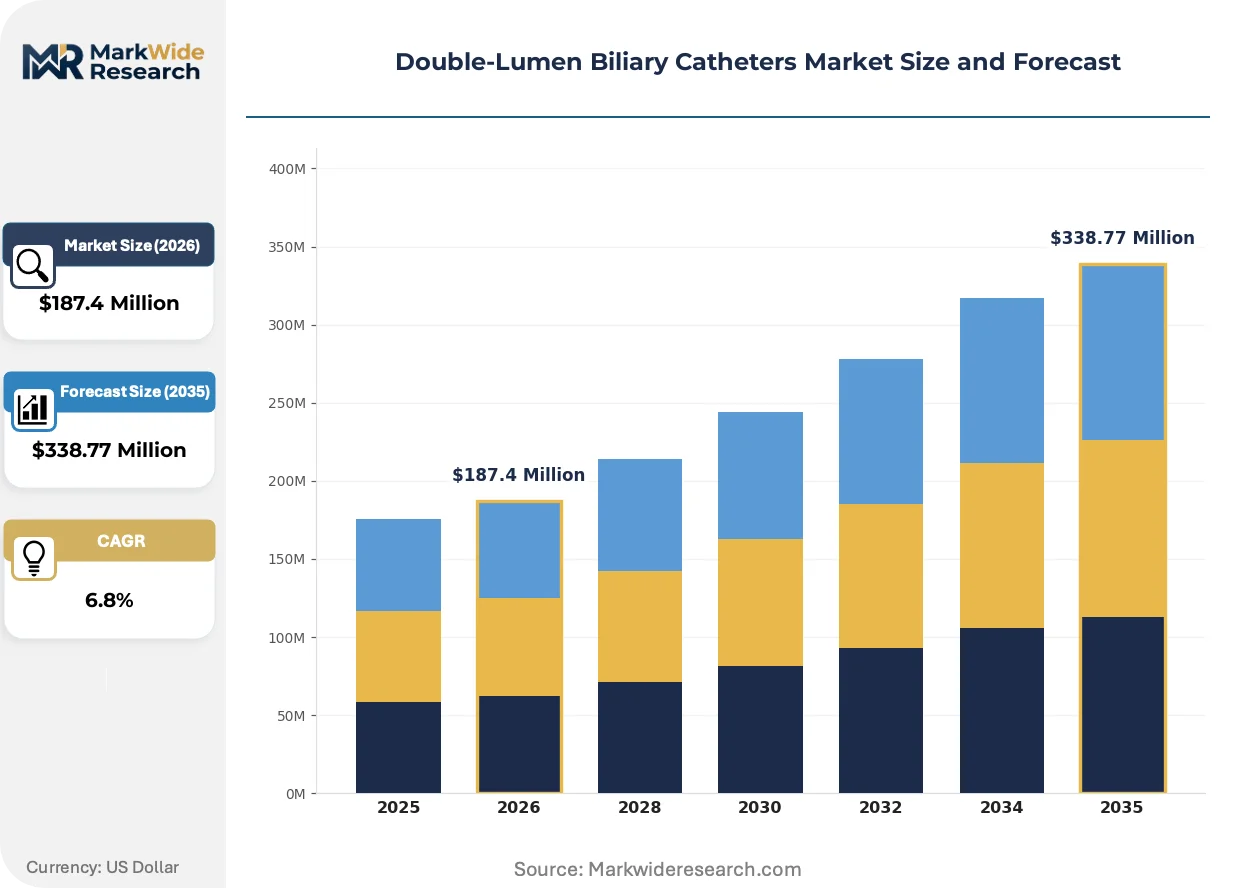
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drainage Catheters, Guide Catheters, Balloon Catheters, Biliary Stents End User: Hospitals, Outpatient Clinics, Ambulatory Surgical Centers, Specialty Clinics Material: Silicone, Polyurethane, Hydrophilic Coated Material, PVC Application: Therapeutic Interventions, Diagnostic Procedures, Fluid Drainage, Bile Duct Obstruction |
| Companies Covered | Boston Scientific Corporation, Cook Medical, Medtronic plc, Olympus Corporation, Conmed Corporation, Teleflex Incorporated, Merit Medical Systems, B. Braun, AngioDynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Double-Lumen Biliary Catheters Market Emerging Trajectories
Sensor-embedded catheter platforms are displacing passive drainage hardware as the central value proposition, while regulatory frameworks on both sides of the Atlantic accelerate documentation burdens.
Embedded pressure transducer arrays within double-lumen biliary catheters is decentralizing real-time patency monitoring from centralized telemetry stations to point-of-care decision support. Interventional radiology departments at tertiary hospitals in the United States and Japan are piloting these connected devices for post-procedure remote surveillance. This architecture compresses emergency re-intervention rates by enabling earlier occlusion detection before clinical decompensation.
EU Medical Device Regulation (MDR) Article 10 technical documentation requirements are mandating expanded clinical evidence packages for Class IIb implantable devices. Manufacturers must now submit post-market clinical follow-up protocols alongside premarket submissions, extending validation timelines. Small-to-mid catheter producers without dedicated regulatory affairs infrastructure are outsourcing compliance to specialized consultants in Ireland and Switzerland.
Hospital purchasing committees are consolidating catheter procurement through integrated delivery networks rather than department-level spot buying. This concentration shifts vendor selection criteria toward total episode cost and supply chain reliability metrics rather than unit price. The United States exhibits the most pronounced consolidation, with regional health systems standardizing on two-to-three approved catheter suppliers across all affiliated facilities.
Double-Lumen Biliary Catheters Market Segmentation
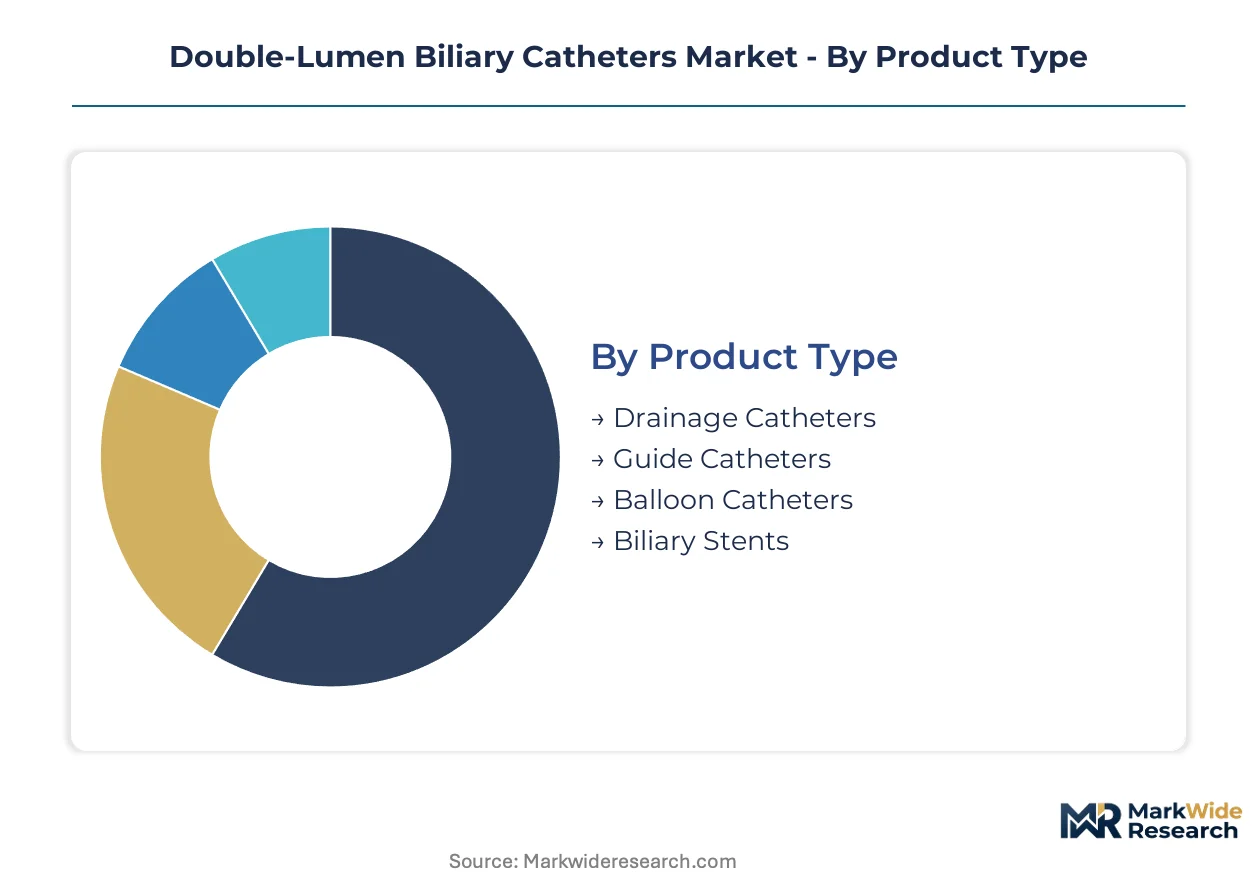
Catheter selection in biliary interventions hinges on procedure complexity, indwelling duration, and anatomical constraints. Manufacturers calibrate material formulations and lumen architectures to match distinct clinical workflows across inpatient and ambulatory settings.
Product Type:
Procurement committees prioritize total episode cost and supply chain reliability when selecting among catheter architectures.
- Drainage Catheters:Dual-lumen silicone or polyurethane constructions enable simultaneous bile evacuation and guidewire manipulation during percutaneous transhepatic cholangiography. Hospital interventional radiology departments in the United States and Germany absorb the majority of volumes for malignant obstruction management.
- Guide Catheters:Engineered with reinforced torque response for selective cannulation of the common bile duct during endoscopic retrograde cholangiopancreatography. Demand concentrates in tertiary centers where complex biliary anatomy requires enhanced trackability beyond standard drainage designs.
- Balloon Catheters:Integrate inflation lumens with drainage channels for stricture dilation combined with stent deployment.
- Biliary Stents:Permanent or temporary implantable scaffolds maintaining ductal patency in benign and malignant strictures.
Volume sits with drainage catheters; growth tilts toward guide catheters as ERCP complexity escalates.
End User:
Site-of-care migration is compressing utilization cycles and reshaping delivery system requirements.
- Hospitals:Centralized interventional radiology and gastroenterology suites at academic medical centers handle high-acuity biliary interventions requiring overnight monitoring. The United States, Germany, and Japan exhibit the highest procedural densities for complex malignant obstruction cases.
- Ambulatory Surgical Centers:Same-day discharge protocols for diagnostic ERCP and uncomplicated drainage procedures are expanding catheter demand in outpatient settings. These facilities require simplified delivery systems optimized for rapid turnover workflows.
- Outpatient Clinics:Physician office-based laboratories performing scheduled catheter exchanges and surveillance cholangiography.
- Specialty Clinics:Dedicated hepatobiliary centers managing chronic biliary diseases through longitudinal catheter care.
Procurement concentration favors hospitals; ambulatory surgical centers are climbing the fastest.
Material:
Biocompatibility profiles and encrustation resistance dictate material selection for short-term versus long-term indwelling applications.
- Silicone:Superior biocompatibility and reduced protein adhesion extend indwelling durations beyond 90 days in percutaneous biliary drainage. Long-term palliative care applications in the United States and Japan favor silicone for minimized replacement frequency.
- Hydrophilic Coated Material:Surface-activated polymers reduce friction coefficients by 60-80 percent, enabling navigation through tortuous biliary strictures. Complex anatomical variants and recurrent benign strictures drive adoption in specialized interventional centers.
- Polyurethane:Higher tensile strength permits thinner wall constructions at equivalent French sizes, maximizing internal lumen diameter.
- PVC:Cost-positioned for short-term diagnostic procedures where indwelling duration remains under 48 hours.
Silicone commands long-term volume; hydrophilic coatings are gaining share fastest in complex anatomy segments.
Application:
Reimbursement bundling and clinical outcomes data are shifting preference toward integrated therapeutic platforms over discrete diagnostic hardware.
- Therapeutic Interventions:Combined drainage, dilation, and stent deployment procedures generate the highest catheter consumption per case. Malignant biliary obstruction management in tertiary hospitals drives recurring device utilization.
- Diagnostic Procedures:Cholangiography and manometry applications require precise contrast injection lumens with minimal dead space. Outpatient clinic volumes are expanding for surveillance of post-surgical biliary anatomy.
- Fluid Drainage:External biliary decompression for acute cholangitis or preoperative biliary optimization.
- Bile Duct Obstruction:Targeted catheterization for stone extraction or stricture traversal in choledocholithiasis.
Therapeutic applications anchor volume; diagnostic procedures show the steepest expansion trajectory in ambulatory migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American catheter manufacturing through dense medical device industrial corridors. The metropolitan cluster concentrates precision polymer processing and sterilization infrastructure for interventional biliary hardware.
United States
Academic medical centers in Boston and Baltimore drive ERCP procedural volume expansion for malignant obstruction management. FDA 510(k) pathway modernization tightens biocompatibility documentation requirements for permanent implant contact devices. The Twin Cities corridor sustains high-volume catheter production lines serving integrated delivery network procurement consolidation.
Germany
Tertiary hospitals in Munich and Heidelberg maintain Europe's highest procedural densities for complex biliary interventions. EU Medical Device Regulation Article 10 mandates expanded clinical evidence packages for Class IIb implantable devices. The Rhine-Main industrial cluster concentrates medical-grade polyurethane feedstock production for catheter material supply.
Japan
Aging demographics accelerate palliative biliary drainage demand in Tokyo and Osaka metropolitan hospitals. PMDA regulatory frameworks align with enhanced clinical performance documentation for long-term indwelling devices. The Kansai region hosts specialized interventional gastroenterology training centers addressing physician pipeline constraints.
United Kingdom
NHS bundled payment reforms shift catheter selection criteria toward total episode cost metrics in London and Manchester hospital systems. MHRA post-Brexit regulatory divergence creates parallel compliance pathways for EU MDR and UKCA marking. The Oxford-Cambridge arc develops sensor-embedded catheter platforms for remote patency monitoring.
India
Private hospital chains in Mumbai and Delhi expand interventional gastroenterology suites for domestic biliary procedure demand. CDSCO medical device rules strengthen import registration requirements for implantable drainage hardware. The Hyderabad medical technology corridor attracts contract manufacturing for silicone catheter components.
Double-Lumen Biliary Catheters Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the catheter value chain. The market structure consolidates around three tiers: diversified medtech conglomerates with endoscopy ecosystems, specialized biliary access device manufacturers, and high-volume contract producers. Strategic moves center on sensor-platform integration for recurring revenue models and ambulatory surgical center channel penetration for same-day procedure workflows.
Within the diversified medtech tier, Boston Scientific Corporation and Medtronic plc exemplify endoscopy ecosystem bundling strategies. Cook Medical occupies a specialist position in biliary access devices and physician training infrastructure. Merit Medical Systems represents scale-driven manufacturing archetypes with high-volume production lines serving hospital procurement channels.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Cook Medical |
| Medtronic plc |
| Olympus Corporation |
| Conmed Corporation |
| Teleflex Incorporated |
| Merit Medical Systems |
| B. Braun |
| AngioDynamics |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap catheter specialists in Germany and the United States anchor supply-side discipline through multi-generational control of silicone compounding and sterilization assets, translating into pricing power that resists commoditization despite hospital procurement consolidation.
Pricing Analysis
Value-based pricing anchored to procedural throughput metrics governs catheter economics in integrated delivery networks. Three-tier pricing structure across premium sensor-embedded, standard hydrophilic-coated, and economy uncoated configurations differentiates by clinical outcome documentation and indwelling duration performance. Cost compression in economy tiers is intensifying because ambulatory surgical centers prioritize disposable unit economics over durability specifications. Hospital purchasing committees exhibit lowest price sensitivity for silicone constructions in malignant obstruction cases where replacement frequency drives total episode cost.
Supply Chain Analysis
ISO 13485 and FDA Quality System Regulation certifications gate entry for component suppliers, concentrating qualified feedstock sources among established polymer processors. Medical-grade silicone production clusters in Germany, the United States, and Japan supply catheter manufacturers, while specialty hydrophilic coating chemistries draw from Swiss and American chemical firms. Single-source vulnerability in platinum-cured silicone formulations creates exposure to pharmaceutical-grade raw material allocation priorities. Distribution runs through group purchasing organizations and regional health system warehouses rather than direct hospital delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Double-Lumen Biliary Catheters Market operates as a cost-of-compliance story where EU MDR Article 10 clinical evidence requirements erect barrier-to-entry moats favoring manufacturers with dedicated regulatory infrastructure and post-market surveillance capabilities.
For Market Incumbents: Anticipate sensor-platform commoditization by accelerating software companion development for remote patency monitoring before integrated delivery networks standardize on analytics-embedded contracts. Defensive consolidation through captive supply of hydrophilic coating capacity insulates against specialty chemical supplier allocation shifts. Priority investment in physician training infrastructure addresses interventional gastroenterologist pipeline constraints threatening procedure volume scalability.
For New Entrants and Emerging Players: Ambulatory surgical center distribution partnerships offer the most penetrable channel wedge for simplified catheter delivery systems optimized for same-day discharge workflows. White-space exists in diagnostic ERCP applications migrating to outpatient settings where established players underinvest in rapid-turnover product configurations. Reimbursement strategy development targeting bundled episode payment structures differentiates new market entries against incumbent spot-price competitors.
For Investors and Strategic Acquirers: FDA 510(k) clearance timeline compression for biocompatibility testing is the leading indicator that regulatory affairs infrastructure scarcity will drive acquisition premiums for compliant mid-cap manufacturers. Long-term viability favors asset-light designers with sensor-platform IP over capital-heavy sterilization-dependent producers facing ethylene oxide capacity constraints. Watch for integrated delivery network standardization announcements signaling procurement consolidation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Integrated delivery network contracts lock in multi-year catheter procurement across affiliated facilities. |
| Software Companion Development | Embedded sensor subscriptions transform hardware margins into recurring platform revenue streams. |
| CE Marking Pathway | EU MDR compliance differentiation separates viable competitors from regulatory-excluded suppliers. |
| Backward Integration into Coating | Captive hydrophilic polymer supply insulates against specialty chemical feedstock volatility. |
| Reimbursement Strategy | Bundled episode payment alignment shapes catheter selection criteria at purchasing committees. |
Methodological Framework
FDA 510(k) premarket notification databases, EU MDR technical documentation filings, and hospital procurement contract records formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with interventional gastroenterologists, biomedical engineers, GPO contracts managers, and regulatory affairs directors at catheter manufacturers validated demand drivers and pricing dynamics. Bottom-up and top-down triangulation cross-checked unit volume estimates against procedure volume data from CMS Medicare claims and Japanese Ministry of Health procedural registries.
Bottom-up modeling segmented the market by product architecture, material formulation, and site-of-care delivery setting across the analysis window. Top-down validation referenced medical device trade flows and sterilization capacity utilization metrics from EPA facility reporting. CAGRs derived from procedure volume elasticity to aging demographics, ERCP suite expansion announcements, and ambulatory migration trends. Forecast inputs incorporated biocompatibility testing timeline assumptions and integrated delivery network consolidation trajectories.
Caveats apply where EPA ethylene oxide sterilization rulemaking or EU MDR notified body capacity constraints could materially shift the outlook for manufacturer compliance costs and product launch timelines. Forecasts reflect assumptions about physician training pipeline throughput and ambulatory reimbursement stability. A model refresh is warranted upon material change in FDA premarket validation requirements or integrated delivery network procurement standardization announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Angiography Catheters Market
Medical Devices
Lactation Massager Market
Medical Devices
Global Breast Pumps Market
Medical Devices
Global Orthopedic Surgical Robots Market
Medical Devices
MRI Motion Tracking Systems Market
Medical Devices
Adsorption Apheresis Devices Market
Medical Devices
Ultrasonic Skin Care Devices Market
Medical Devices
Pelvic Electro-Stimulators Market
Medical Devices
Silastic Implant Market
Medical Devices
Global Tracheal Tube and Airway Products Market
Medical Devices
Brachytherapy Market
Medical Devices
Pulmonology Devices Market
Medical Devices
South Africa Digital X-Ray Devices Market
Medical Devices
Asia-Pacific Vagus Nerve Stimulation Market
Medical Devices
Spine Bone Stimulators Market
Medical Devices
Dual Balloon Angioplasty Catheter Market