
 Lithuania Pharmaceutical Market | 2026-2036
Lithuania Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Lithuania Pharmaceutical Market Insights
The gap between premium biologics and commodity generics is shifting as Lithuanian hospitals consolidate formularies and push volume toward lower-cost alternatives. Pfizer leverages its established oncology portfolio to sustain institutional contracts with major Vilnius hospitals. Teva Lithuania competes aggressively on generic substitution, while Biomapas UAB anchors the clinical services segment through its regional trial management capabilities.
Pharmaceuticals encompass chemically synthesized or biologically derived substances formulated for disease prevention, diagnosis, or treatment, with specifications ranging from small-molecule purity thresholds exceeding 99.5% to biologics requiring cold-chain maintenance at 2-8°C throughout distribution. Their primary commercial purpose centers on restoring or modifying physiological functions through precise molecular targeting. Prescription drugs generate the deepest margin pools due to reimbursement-backed oncology and cardiology demand, while biologics represent the fastest-expanding category as infusion capacity expands in Lithuanian tertiary centers. Generic drugs occupy a mature, price-compressed tier where pharmacy-level substitution mandates determine volume allocation.
The State Medicines Control Agency and Ministry of Health regulate market access through reimbursement lists and Good Manufacturing Practice audits aligned with EU directives. The EU AI Act and GDPR shape how patient data flows into pharmacovigilance systems and real-world evidence platforms. Stakeholders must monitor how Lithuania's adoption of EU-wide health technology assessment standards will reshape formulary negotiations for novel therapies.
Market Dynamics
Hospital formulary consolidation in Vilnius is compressing margins for originator biologics while channeling volume toward lower-cost alternatives, reshaping how manufacturers negotiate institutional access.
Growth Catalysts
- Oncology Biologics Reimbursement:Lithuania's Ministry of Health is tightening criteria for high-cost therapies, expanding hospital procurement of oncology biologics through centralized tender mechanisms.
- Clinical Trial Infrastructure:Specialized infusion centers in Vilnius are attracting regional Phase II-III oncology studies, positioning Lithuania as a Baltic hub for patient recruitment.
- EU HTA Alignment:Adoption of EU-wide health technology assessment standards is streamlining formulary negotiations for novel therapies entering the Lithuanian market.
Market Restraints
- Reimbursement Lag:The State Medicines Control Agency maintains a compressed positive list, delaying market access for innovative therapies by 18-24 months versus Western EU benchmarks.
- Pharmacy Substitution Mandates:Generic substitution rules at the retail level cap pricing power for branded small-molecule drugs across chronic therapy categories.
- Cold-Chain Infrastructure Gaps:Regional hospitals outside Vilnius lack validated 2-8°C distribution capacity, limiting biologics penetration to tertiary centers.
Strategic Opportunities
- Real-World Evidence Platforms:GDPR-compliant patient data integration is enabling pharmacovigilance systems that support accelerated reimbursement negotiations with the Ministry of Health.
- Kaunas Regional Expansion:Secondary cities are developing ambulatory infusion capacity, creating whitespace for biosimilar volume capture outside the saturated Vilnius cluster.
- EU AI Act Compliance:Automated adverse event reporting tools are opening regulatory technology partnerships for clinical services providers serving multinational sponsors.
Industry Challenges
- Specialized Oncology Nursing Shortage:Vilnius hospitals face recruitment constraints for certified infusion nurses, capping expansion of biologics administration capacity.
- Legacy ERP Integration:Hospital procurement systems require manual bridging to EU tender platforms, delaying contract execution and payment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithuania Pharmaceutical Market |
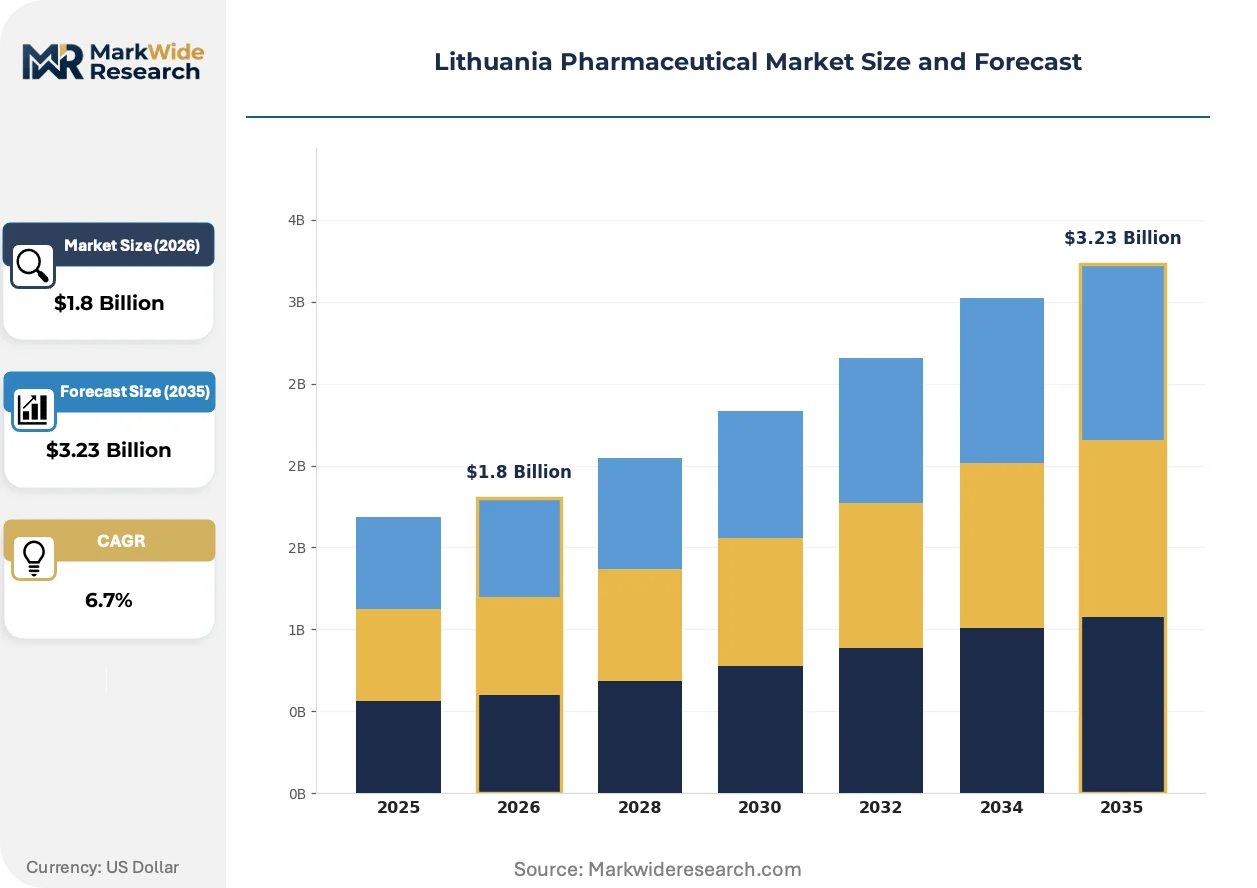
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, OTC Medications, Generic Drugs, Biologics End User: Hospitals, Clinics, Pharmacies, Homecare Therapy Area: Oncology, Cardiology, Neurology, Immunology Form: Tablets, Injectables, Topicals, Inhalables |
| Companies Covered | Johnson & Johnson, Novartis International AG, Merck & Co., Inc., Pfizer Inc., Bayer AG, Rivopharm, Teva Lithuania, Berin Chemie, Biomapas UAB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithuania Pharmaceutical Market Trends and Innovations
Digital health infrastructure and regulatory technology are converging to reshape how pharmaceutical stakeholders access the Lithuanian market, with data governance becoming as critical as clinical evidence.
Blockchain-enabled temperature logging is integrating cold-chain verification across biologics distribution. Vilnius-based hospital pharmacies are piloting distributed ledger systems to satisfy EMA Good Distribution Practice requirements. This technology is integrating audit trails directly into reimbursement documentation, compressing dispute resolution timelines with the State Medicines Control Agency.
GDPR Article 89 research exemptions are enabling broader secondary use of patient data for outcomes research. The Ministry of Health is interpreting these provisions to support real-world evidence submissions for oncology drug pricing negotiations. Hospital networks in Kaunas and Klaipeda are responding by establishing dedicated data governance offices to manage research partnerships.
Centralized procurement consortia are consolidating purchasing power across Lithuania's five largest hospital networks. Vilnius University Hospital is leading tender aggregation for oncology biologics, displacing individual hospital negotiations. This concentration is most visible in cardiology and immunology categories, where annual contract values now exceed threshold levels for EU-wide tender publication.
Lithuania Pharmaceutical Market Segmentation
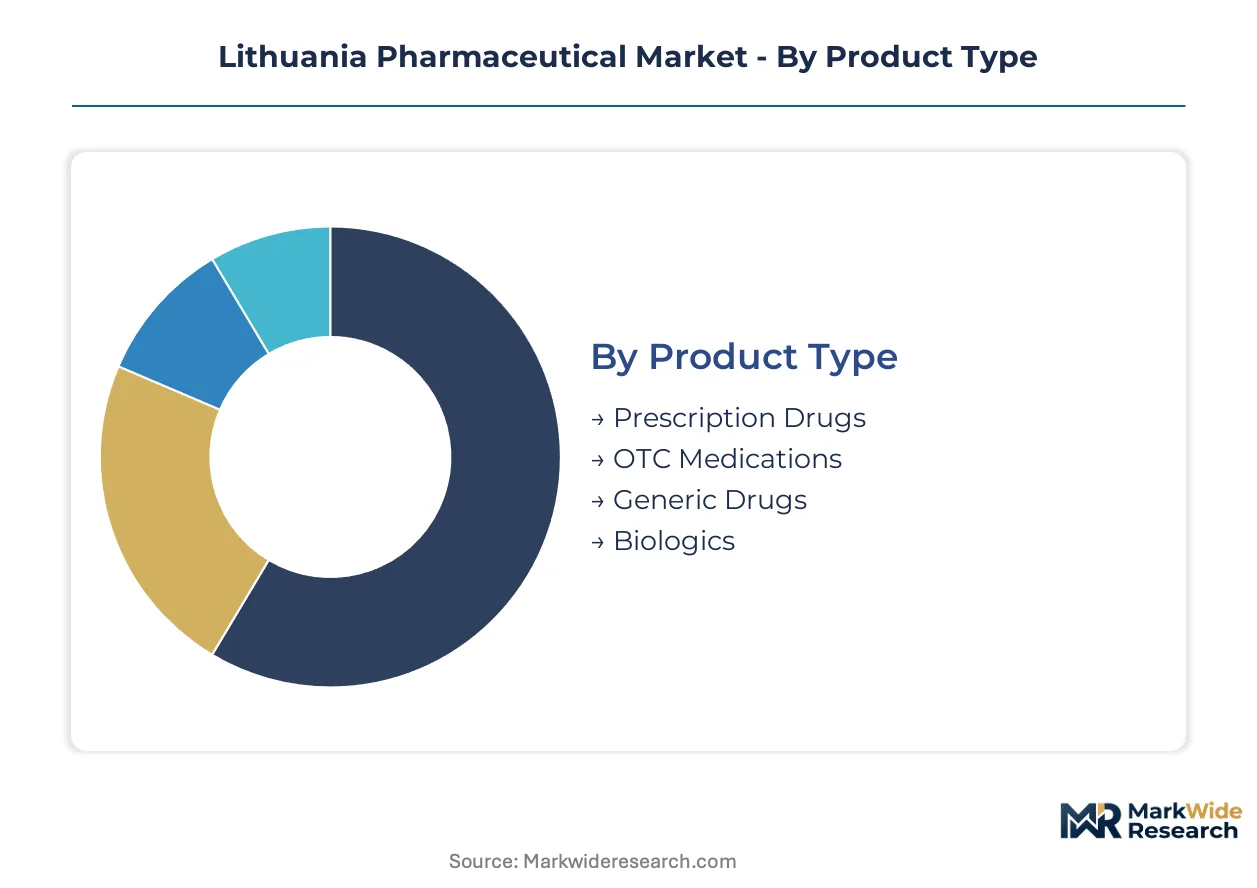
Segmentation in Lithuania's pharmaceutical market reveals how reimbursement policy and infrastructure constraints reshape demand patterns. Understanding these divisions exposes where procurement power concentrates and where access barriers persist.
Product Type:
Capital intensity varies sharply across product categories, with cold-chain biologics requiring multimillion-euro distribution investments while generics operate on lean manufacturing economics.
- Prescription Drugs:Chemically synthesized therapeutics requiring physician authorization and State Medicines Control Agency reimbursement listing. Hospital formularies in Vilnius concentrate procurement for oncology and cardiology prescriptions through centralized tender mechanisms.
- Biologics:Temperature-sensitive large-molecule therapies demanding validated 2-8°C distribution infrastructure. Tertiary centers in Vilnius absorb the majority of infusion-administered biologics as regional hospitals lack cold-chain capacity.
- Generic Drugs:Bioequivalent small-molecule copies operating under pharmacy substitution mandates that compress pricing power. Volume flows toward retail channels where automatic interchange rules govern dispensing decisions.
- OTC Medications:Self-administered remedies distributed through pharmacy networks without prescription requirements. Consumer brands compete on shelf visibility and pharmacist recommendation programs.
Prescription drugs absorb the bulk of installed capacity; biologics is expanding most quickly.
End User:
Customer concentration determines contract negotiation leverage, with hospital networks commanding volume discounts that fragment pharmacy purchasing power.
- Hospitals:Institutional purchasers managing formularies for acute and chronic therapy administration. Vilnius University Hospital anchors procurement consortia that aggregate demand across Lithuania's five largest networks.
- Clinics:Outpatient facilities delivering specialist consultations and limited procedural care. Ambulatory oncology clinics in Kaunas are developing infusion capacity to capture biosimilar volume outside the capital.
- Pharmacies:Retail dispensaries operating under generic substitution rules that override physician brand preferences. Independent operators face margin pressure from chain consolidation and reimbursement clawbacks.
- Homecare:Patient-directed administration of self-injectable and oral therapies outside clinical settings. Growth depends on nursing support infrastructure and patient education program availability.
Hospitals command the deepest procurement relationships; homecare climbs the fastest as chronic disease management shifts beyond institutional walls.
Therapy Area:
Reimbursement generosity and unmet medical need create divergent margin profiles across therapeutic categories.
- Oncology:High-cost cytotoxic and targeted therapies dominating hospital pharmacy budgets. The Ministry of Health's tightened criteria for novel agents are reshaping how manufacturers approach centralized tenders.
- Cardiology:Chronic cardiovascular medications representing stable volume through retail and institutional channels. Generic substitution has largely commoditized the small-molecule segment.
- Neurology:Central nervous system therapies including antiepileptics and disease-modifying treatments for neurodegenerative conditions. Patient adherence challenges and complex titration protocols favor specialist oversight.
- Immunology:Autoimmune and inflammatory condition management through biologic and small-molecule immunosuppressants. Infusion center capacity constraints in regional cities limit penetration outside Vilnius.
Oncology absorbs the bulk of reimbursement expenditure; immunology gains share fastest as diagnostic recognition improves.
Form:
Delivery technology requirements segment manufacturing capabilities and distribution economics.
- Injectables:Parenteral formulations including intravenous infusions and subcutaneous administrations. Aseptic manufacturing standards and cold-chain validation concentrate production among specialized contract manufacturers.
- Tablets:Oral solid dosage forms dominating chronic therapy compliance and retail pharmacy volume. High-speed compression equipment and coating technologies define manufacturing scale advantages.
- Topicals:Dermal and mucosal applications for localized therapeutic effect. Semi-solid formulation expertise and preservative stability testing create entry barriers for new market participants.
- Inhalables:Pulmonary delivery systems for respiratory disease management. Device-drug combination complexity and patient technique training requirements limit generic substitution pressure.
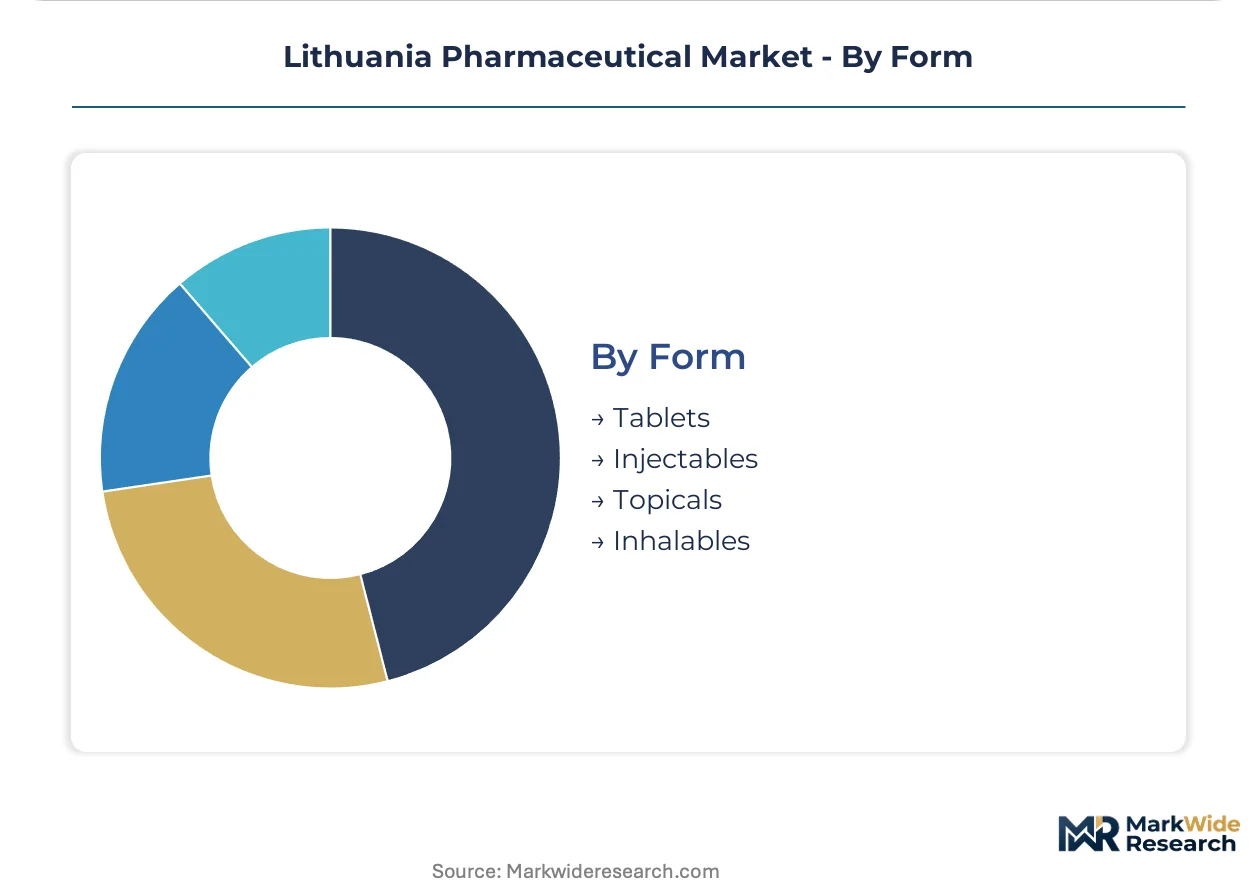
Tablets retain the largest installed manufacturing base; injectables show the steepest expansion trajectory as biologics volume rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vilnius commands the dominant share of pharmaceutical activity, anchoring procurement consortia and specialized infusion infrastructure that channels biologics volume through tertiary centers.
Vilnius
The capital's hospital networks aggregate oncology biologics demand through centralized tender mechanisms led by Vilnius University Hospital. State Medicines Control Agency reimbursement audits concentrate here, accelerating formulary decisions for novel therapies. Infusion center capacity expansion in Santaros Klinikos and other tertiary sites is drawing regional Phase II-III clinical trials.
Kaunas
Ambulatory oncology clinics in Lithuania's second city are developing independent infusion capacity to capture biosimilar volume outside the capital's saturated cluster. The Ministry of Health's regional health administration allocates separate procurement budgets for Kaunas University Hospital network facilities. Secondary city infrastructure investment is creating whitespace for cold-chain biologics distribution beyond Vilnius.
Klaipeda
The port city's hospital networks serve as a distribution gateway for temperature-sensitive therapeutics entering from EU supply hubs. Regional procurement offices here negotiate separate framework agreements for immunology and cardiology categories. Cold-chain validation gaps persist in surrounding coastal municipalities, limiting biologics penetration to the central hospital pharmacy.
Siauliai
Northern Lithuania's regional hospital network operates under consolidated formulary management from Vilnius-based procurement consortia. Pharmacy substitution mandates at the retail level govern chronic therapy dispensing across this catchment area. Limited specialized nursing capacity constrains expansion of infusion-administered therapies beyond oral solid dosage forms.
Lithuania Pharmaceutical Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Lithuanian pharmaceutical sector, with originator biologics manufacturers maintaining deep institutional relationships while generic specialists exploit pharmacy-level substitution rules. The market structure concentrates procurement leverage within five hospital networks that aggregate volume for tender negotiations. Three archetypes dominate: global innovators with oncology portfolios, regional generic distributors with retail pharmacy penetration, and clinical services providers anchoring trial infrastructure. Competitive moves center on formulary consolidation through tender aggregation and real-world evidence partnerships that accelerate reimbursement timelines with the Ministry of Health.
Among global innovators with established institutional presence, Pfizer Inc. and Novartis International AG occupy positions anchoring oncology biologics procurement in Vilnius tertiary centers. Teva Lithuania exemplifies the regional generic archetype competing on pharmacy substitution mandates, while Biomapas UAB represents clinical services specialists managing regional trial operations for multinational sponsors.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Novartis International AG |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Bayer AG |
| Rivopharm |
| Teva Lithuania |
| Berin Chemie |
| Biomapas UAB |
| Others |
Pricing and Supply Chain Analysis
Centralized tender aggregation by Vilnius University Hospital and four major networks is forcing manufacturers to accept volume-discounted contracts that compress originator margins and redirect supply toward lower-cost alternatives. This procurement consolidation reshapes how distributors configure cold-chain logistics and where they invest temperature-validated capacity.
Pricing Analysis
Outcome-based reimbursement anchors from the Ministry of Health's tightened criteria for oncology biologics, tying hospital payment to patient response thresholds rather than administered dose. Pricing stratifies across originator biologics, authorized biosimilars, and commodity generics, with differentiation driven by cold-chain certification grade and infusion center accreditation status. Cost compression in the generic tier is intensifying because pharmacy substitution mandates override physician brand preferences. Retail pharmacies show the deepest price sensitivity due to reimbursement clawbacks, while tertiary hospital networks command leverage through tender aggregation.
Supply Chain Analysis
Dual-sourcing requirements embedded in EU Good Distribution Practice audits compel Lithuanian distributors to qualify secondary cold-chain providers for biologics, fragmenting procurement volumes across validated networks. Active pharmaceutical ingredients draw from India, China, and Switzerland, while finished biologics feed from Belgian and German manufacturing hubs. Single-source vulnerability concentrates in temperature-controlled last-mile delivery, where validated 2-8°C capacity is tethered to Vilnius-based tertiary centers. Distribution runs through hospital pharmacy consortia for institutional volume and retail chains for generic substitution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled temperature logging and automated adverse event reporting are displacing legacy paper-based pharmacovigilance systems, creating compliance gaps for distributors lacking regulatory technology infrastructure.
For Market Incumbents: To counter biosimilar substitution pressure in oncology tenders, Pfizer and Novartis should deepen backward integration into cold-chain distribution partnerships with Vilnius-based logistics providers. Securing exclusive infusion center capacity at Santaros Klinikos and Kaunas University Hospital anchors formulary position against lower-cost rivals. For New Entrants and Emerging Players: Capture ambulatory infusion whitespace in Kaunas and Klaipeda by establishing GDPR-compliant real-world evidence partnerships with regional hospital data governance offices. Position biosimilar portfolios through tender participation in the Ministry of Health's centralized procurement frameworks rather than fragmented pharmacy channels. For Investors and Strategic Acquirers: The window for entry favors clinical services specialists with EU AI Act-compliant pharmacovigilance platforms and established Baltic trial management infrastructure. Watch for inflection signals in reimbursement lag reduction as the State Medicines Control Agency accelerates HTA alignment with EU standards.| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Partnership | GDPR-compliant patient data integration accelerates Ministry of Health reimbursement negotiations for novel oncology therapies. |
| Cold-Chain Infrastructure Expansion | Validated 2-8°C distribution capacity in Kaunas and Klaipeda captures biosimilar volume outside saturated Vilnius clusters. |
| EU HTA Alignment Preparation | Early adoption of EU-wide health technology assessment standards streamlines formulary access for innovative biologics. |
| Regulatory Technology Investment | Automated adverse event reporting tools satisfy EU AI Act requirements for multinational clinical trial sponsors. |
| Centralized Tender Aggregation | Hospital network consortium participation secures volume contracts exceeding threshold levels for EU-wide publication. |
Research Methodology
EMA submissions, ClinicalTrials.gov records, and Lithuanian Ministry of Health reimbursement databases formed the secondary backbone, cross-referenced against primary interviews with formulary directors at Vilnius University Hospital, regulatory affairs leads at the State Medicines Control Agency, hospital procurement managers across five major networks, and payer access specialists. Bottom-up segmentation modeling triangulated with top-down macroeconomic validation anchored the quantitative framework.
Historical trendline analysis of oncology biologics procurement volumes and generic substitution rates informed the projection methodology across the analysis window. Segmentation dimensions encompassed therapy area, product type, end-user channel, and regional regulatory cluster. CAGRs derived from regression analysis of tender award values and reimbursement list expansion timelines, incorporating cold-chain capacity buildout schedules and EU HTA adoption pace as industry-specific inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Ministry of Health reimbursement policy shifts and EU AI Act enforcement granularity. Deviation in centralized tender aggregation pace or GDPR research exemption interpretation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Europe Pharmaceutical Warehousing Market
Pharmaceuticals
Global Testosterone Replacement Therapy Market
Pharmaceuticals
Mitochondrial-Based Therapeutics Market
Pharmaceuticals
Global DNA Repair Drugs Market
Pharmaceuticals
Spain Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Zoldonat Injection Market
Pharmaceuticals
Prothrombin Complex Concentrate (PCC) Market
Pharmaceuticals
Oral Anticoagulant Market
Pharmaceuticals
Global Lidocaine Market
Pharmaceuticals
Loxoprofen Market
Pharmaceuticals
Anti-Platelet Agents Market
Pharmaceuticals
Empty Capsules Market
Pharmaceuticals
Etoricoxib Market
Pharmaceuticals
Antidiuretic Drugs Market
Pharmaceuticals
Angiopoietin Inhibitors Therapeutic Market
Pharmaceuticals
Dyslipidemia Therapeutics Market