
 GCC Solar Microinverter Market | 2026-2036
GCC Solar Microinverter Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Solar Microinverter Market Intelligence
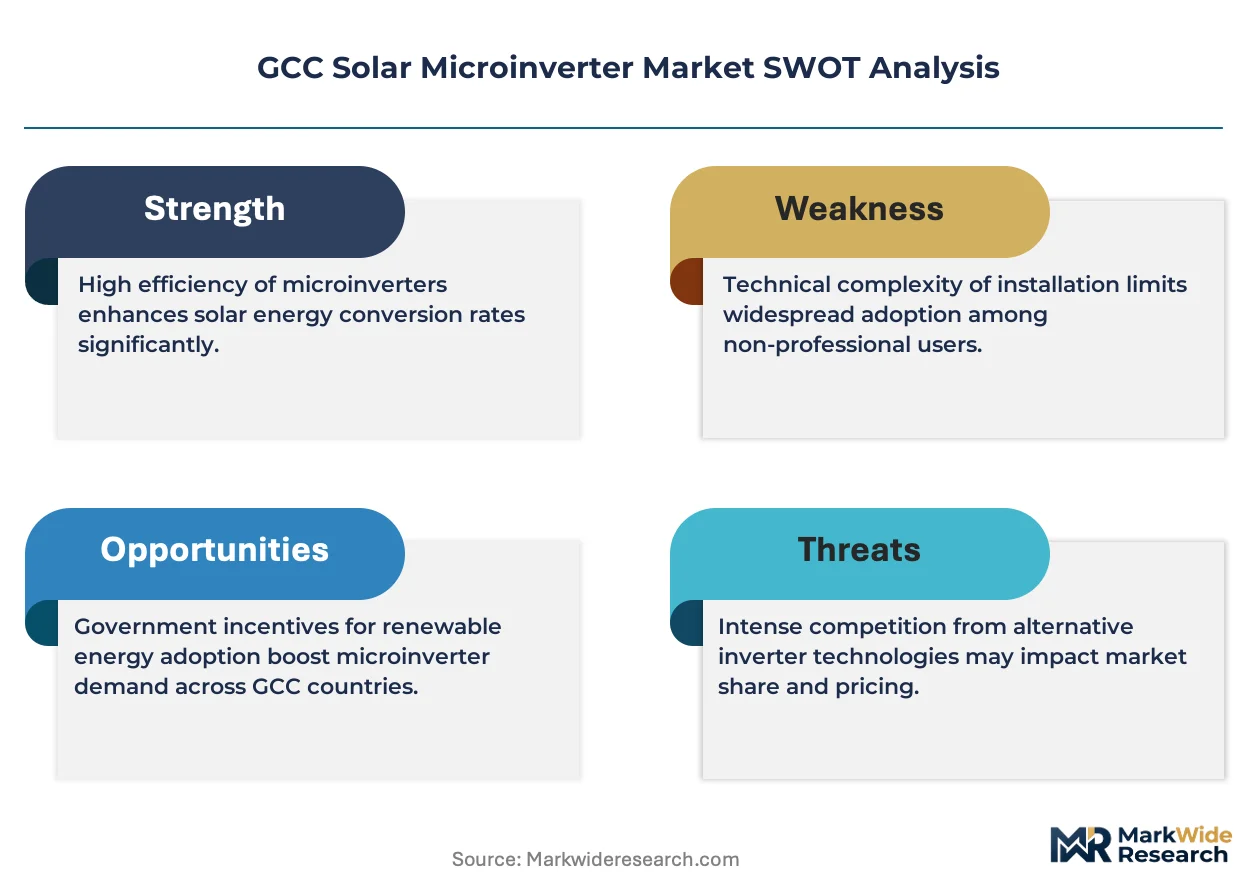
IEC 62109 certification for photovoltaic power converters is redrawing competitive boundaries in the GCC. Enphase Energy leverages its UL 1741-SA certified architecture to anchor premium residential positioning across Saudi Arabia and the UAE. SMA Solar Technology competes through its decentralized inverter portfolio optimized for high-temperature desert climates. SolarEdge Technologies differentiates via power optimizers paired with string inverters, occupying a hybrid niche between string and microinverter architectures.
A solar microinverter converts direct current from individual photovoltaic modules into grid-compliant alternating current at the panel level, typically operating at 95-97% peak efficiency with maximum power point tracking per module. This device architecture eliminates single-point failure risks inherent to string topologies while enabling granular production monitoring across distributed arrays. Residential installations command the dominant share of unit volume as villa owners and small businesses pursue self-consumption models under Gulf net metering frameworks. Smart microinverters represent the fastest-expanding technology segment, integrating module-level electronics with grid-responsive communication protocols demanded by Saudi Electricity Company interconnection standards.
Gulf Standardization Organization (GSO) conformity requirements and Saudi Standards, Metrology and Quality Organization (SASO) technical regulations govern product entry, with SASO IEC 62109-1 compliance now mandatory for inverter certification in the Kingdom. The Emirates Authority for Standardization and Metrology (ESMA) enforces equivalent protocols across the UAE, creating a dual-track compliance burden for manufacturers targeting both markets. Stakeholders must monitor evolving grid code harmonization between GCC member states, as regulatory divergence threatens to fragment procurement specifications and complicate regional scale strategies.
Market Dynamics
Module-level power electronics are concentrating procurement specifications across Saudi Arabia and the UAE as net metering frameworks reward granular production visibility. EPC contractors now embed microinverter compatibility into residential tender documents, locking out string-only architectures from government-backed villa solar programs.
Growth Catalysts
- SASO IEC 62109-1 Mandate:Saudi Arabia's mandatory inverter certification accelerates product standardization, filtering uncertified imports and concentrating demand among pre-qualified suppliers.
- Villa Self-Consumption Models:Residential rooftop owners across Dubai and Riyadh pursue behind-the-meter solar economics under revised net metering buyback rates.
- Al Dhafra Solar Cluster Procurement:The UAE's concentrated utility-scale development creates spillover demand for distributed residential systems as EPCs build installation capacity.
Market Restraints
- Dual-Track Compliance Burden:GSO conformity requirements and separate ESMA protocols in the UAE force manufacturers to maintain parallel certification streams for Saudi and Emirati entry.
- Silicon Carbide Supply Concentration:Power semiconductor sourcing for high-efficiency conversion electronics remains concentrated among East Asian foundries, exposing margins to input volatility.
- String Inverter Substitution:SolarEdge's power optimizer architecture offers module-level monitoring at lower per-watt cost, capturing price-sensitive residential segments.
Strategic Opportunities
- Kuwait and Oman Penetration:These markets lag Saudi Arabia and the UAE in net metering implementation, offering first-mover positioning as regulations mature.
- Grid-Responsive Smart Microinverters:Saudi Electricity Company interconnection standards now demand reactive power capability, creating premium tier for communication-enabled units.
- EPC Direct Procurement Channels:Bypassing traditional distribution, manufacturers are cultivating direct relationships with contractors serving government renewable auctions.
Industry Challenges
- Desert Climate Certification Timelines:Extended thermal cycling and sand ingress testing for SASO compliance stretches product launch schedules.
- Grid Code Harmonization Delays:Divergent technical regulations between GCC member states complicate regional inventory pooling and service network economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Solar Microinverter Market |
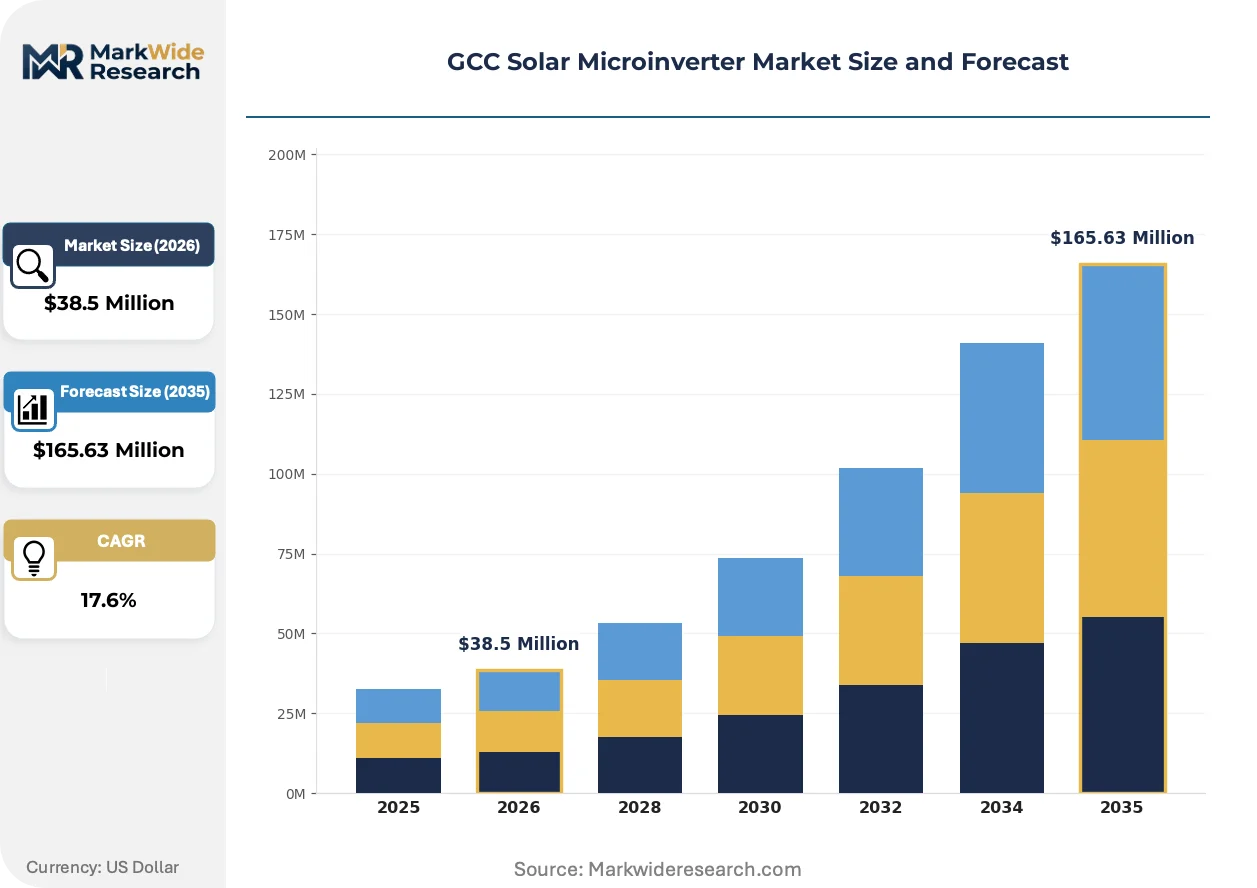
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $165.63 Million |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Microinverters, Enphase Microinverters, SolarEdge Microinverters, Customized Microinverters Installation Type: Residential Installations, Commercial Installations, Industrial Installations, Off-Grid Systems End User: Homeowners, Small Businesses, Large Enterprises, Government Projects Technology: Grid-Tied Systems, Battery Storage Systems, Hybrid Systems, Smart Microinverters |
| Companies Covered | Enphase Energy, Inc., SMA Solar Technology AG, SolarEdge Technologies Inc., APsystems, Chilicon Power LLC, Darfon, Delta Electronics, Inc., Sungrow, Canadian Solar, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Solar Microinverter Market Strategic Shifts & Innovations
Power electronics architecture is bifurcating across the Gulf as module-level granularity becomes a procurement requirement rather than a premium feature. This shift compresses margins for centralized inverter portfolios while rewarding integrated software-hardware platforms.
GaN-based switching topologies are displacing conventional silicon IGBTs in next-generation microinverter designs. Saudi EPCs serving premium villa segments specify these units for their superior heat tolerance in ambient temperatures exceeding 50°C. The technology is displacing mid-efficiency string inverters from residential tenders where thermal derating previously favored centralized architectures.
Saudi Standards, Metrology and Quality Organization technical regulations now embed grid support functionality into inverter certification criteria. This policy compresses the addressable market to suppliers capable of voltage ride-through and frequency-watt control. Residential installations above 10kW face the strictest compliance timelines, forcing distributors to clear legacy inventory ahead of enforcement windows.
Buyer concentration among state-linked EPCs is compressing vendor negotiation leverage. Contractors serving Saudi Arabia's renewable auctions now demand extended warranty terms and localized spare parts holding as standard contract riders. This behavioral shift is most visible in Riyadh and Jeddah metropolitan procurement, where aggregator platforms consolidate villa owner demand into volume tenders.
GCC Solar Microinverter Market Segmentation
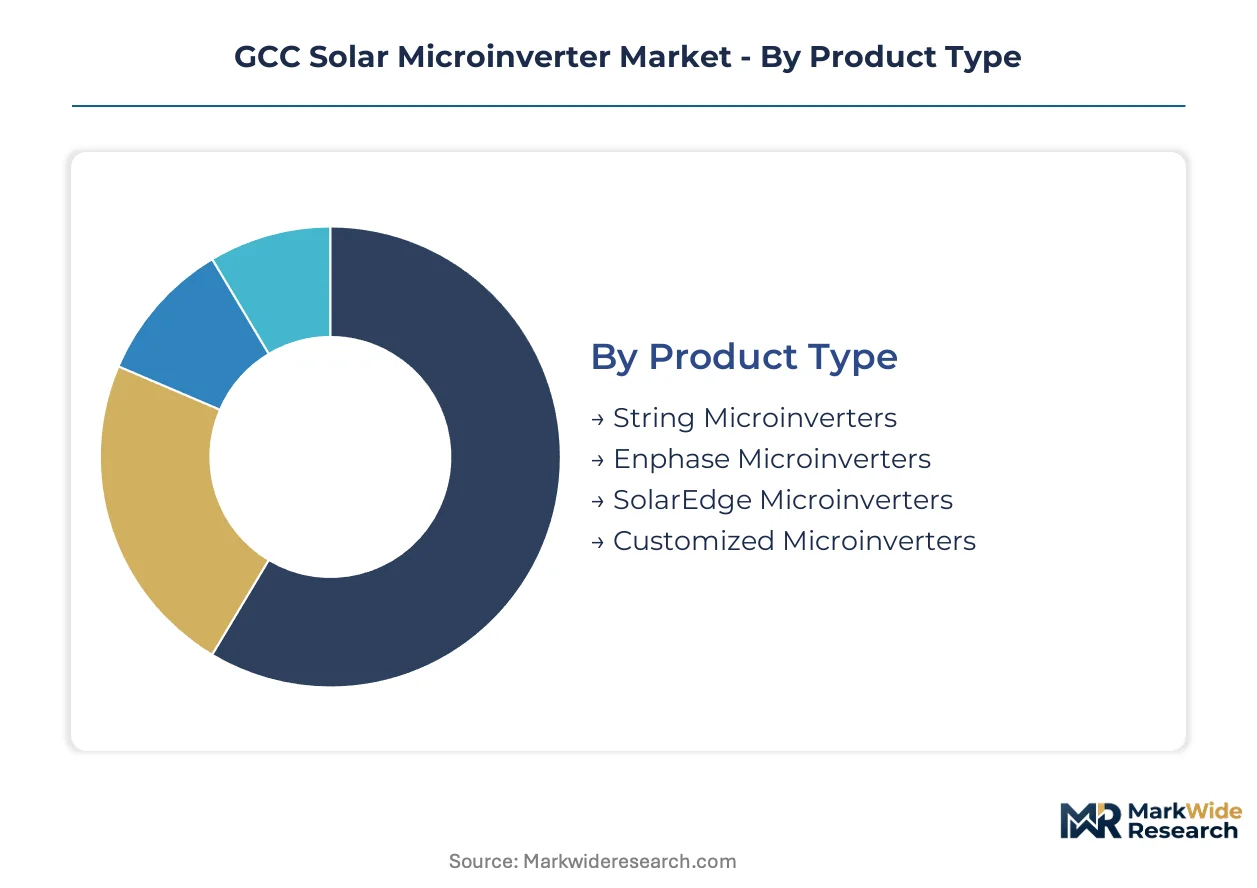
Segmentation in the GCC solar microinverter market reveals how regulatory frameworks and climate conditions reshape procurement priorities across product architectures. Saudi Arabia's SASO IEC 62109-1 mandate and the UAE's ESMA protocols create divergent compliance pathways that segment demand by certification tier and thermal performance rating.
Product Type:
SASO and ESMA certification requirements split the product landscape into pre-qualified and pending-certification tiers, with thermal cycling resilience becoming the decisive filter for Gulf market entry.
- String Microinverters:These centralized architectures manage DC-to-AC conversion at the string level rather than panel level. Demand concentrates in price-sensitive commercial installations across Dubai's industrial zones where module-level granularity is not specified in tender documents.
- Enphase Microinverters:Panel-level conversion electronics with integrated maximum power point tracking and UL 1741-SA certification anchor premium residential positioning. Procurement concentrates among EPC contractors serving Saudi Arabia's government-backed villa solar programs where granular monitoring is mandatory.
- SolarEdge Microinverters:Power optimizer-string inverter hybrid architectures occupy a mid-tier positioning. These units capture residential segments in the UAE where cost pressure from string alternatives moderates module-level electronics adoption.
- Customized Microinverters:Bespoke units engineered for extreme desert thermal profiles and sand ingress protection. Saudi EPCs commission these for Al Dhafra-scale project spillover and specialized industrial applications.
Established volume favors string architectures in commercial procurement; emerging adoption favors Enphase-equivalent panel-level systems in Riyadh and Dubai residential tenders.
Installation Type:
Net metering buyback rates and interconnection standards segment demand by system scale, with behind-the-meter economics driving divergent technology choices across residential, commercial, and off-grid applications.
- Residential Installations:Rooftop systems below 10kW dominate unit volume across Saudi villa compounds and Dubai's gated communities. Self-consumption models under revised net metering frameworks accelerate module-level electronics specification.
- Commercial Installations:Mid-scale rooftop and carport arrays serving retail and logistics facilities. Procurement favors string or hybrid architectures where production monitoring granularity is traded against per-watt capital cost.
- Industrial Installations:Large rooftop and ground-mount systems above 100kW serving manufacturing and desalination facilities. These installations face the strictest Saudi Electricity Company grid support compliance timelines.
- Off-Grid Systems:Standalone microinverter configurations for remote agricultural pumping and telecom tower electrification. Demand clusters in Oman's interior and Kuwait's northern oil field periphery where grid extension is uneconomical.
Unit economics favor residential scale in Saudi Arabia and the UAE; margin concentration favors industrial installations with extended warranty and service contract attachments.
End User:
Buyer sophistication and procurement channel structure segment the market, with state-linked aggregators consolidating demand from dispersed villa owners while direct EPC relationships serve enterprise and government accounts.
- Homeowners:Individual villa owners across Riyadh, Jeddah, and Dubai pursuing electricity bill reduction. These buyers access microinverter systems through EPC aggregator platforms that consolidate demand into volume tenders.
- Small Businesses:Retail, hospitality, and light manufacturing operators with rooftop solar potential. Procurement concentrates in Dubai's SME free zones where net metering registration is streamlined.
- Large Enterprises:Industrial conglomerates and logistics operators with multi-site portfolio deployment. These buyers demand centralized monitoring platforms and 20-year performance warranties as standard.
- Government Projects:State-backed renewable auctions and public building solarization programs. Saudi Arabia's renewable energy project development office and UAE's Masdar procurement set technical specifications that cascade to private EPCs.
Volume aggregates through homeowner platforms; margin protection concentrates in government direct procurement with localized spare parts requirements.
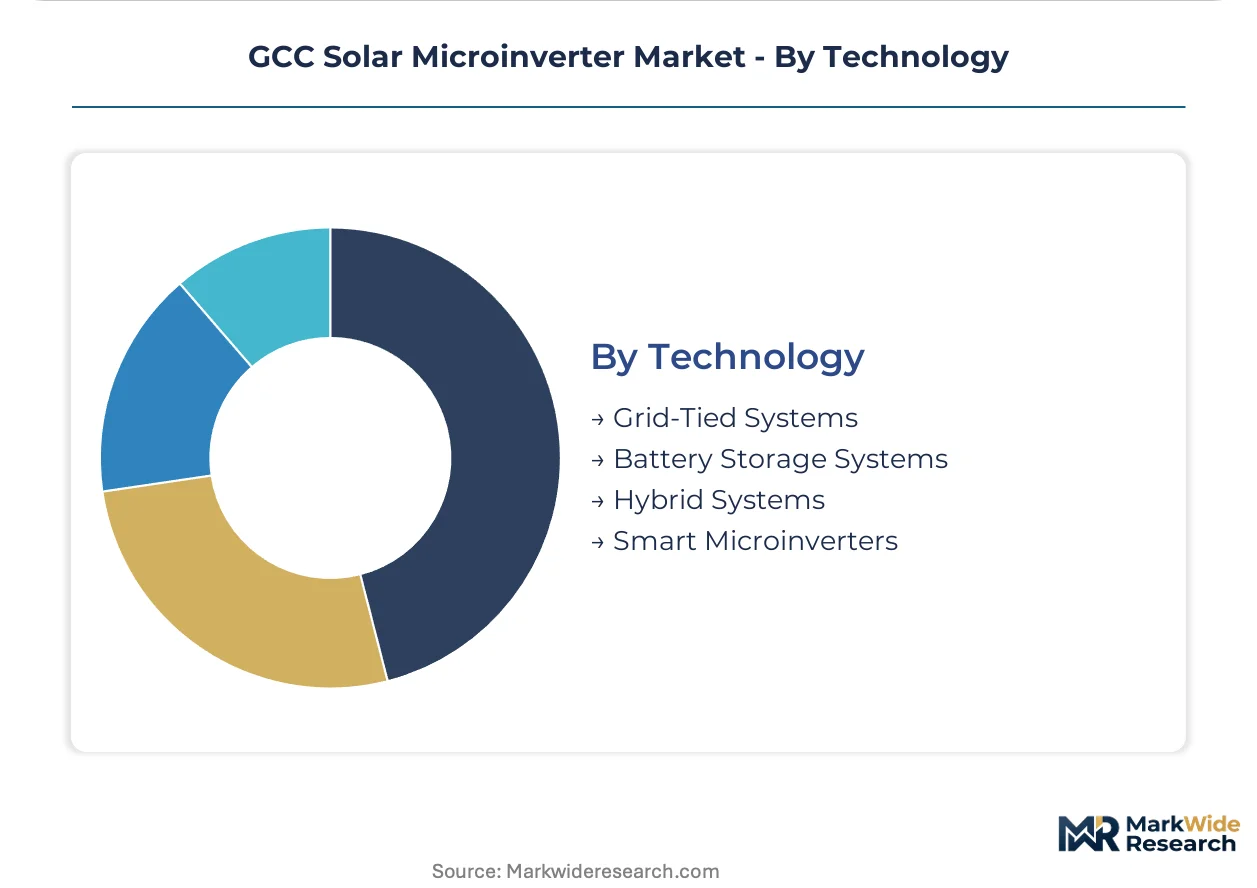
Technology:
Grid code evolution and storage integration mandates segment technology adoption, with Saudi Electricity Company reactive power requirements and Dubai's storage incentives creating divergent specification pathways.
- Grid-Tied Systems:Standard microinverter configurations exporting surplus generation to the distribution network. These systems dominate where net metering buyback rates remain economically attractive.
- Battery Storage Systems:DC-coupled or AC-coupled storage integration enabling time-of-use arbitrage and backup power. Demand accelerates in Dubai where DEWA storage incentives offset peak demand charges.
- Hybrid Systems:Configurations supporting both grid-tied and islanded operation. These units capture premium positioning in Saudi commercial segments where grid reliability varies by region.
- Smart Microinverters:Communication-enabled units with voltage ride-through, frequency-watt control, and remote firmware update capability. Saudi interconnection standards mandate these features for systems above 10kW, creating the steepest expansion trajectory among technology segments.
Regulatory baseline favors conventional grid-tied architectures; premium tier expansion favors smart microinverters as SASO enforcement windows tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net metering revisions and government-backed renewable auctions are concentrating procurement activity across Gulf Cooperation Council member states. Saudi Arabia's SASO certification mandates and the UAE's ESMA protocols create divergent compliance pathways that segment supplier access. Each jurisdiction's grid code evolution determines technology specification timelines and warranty requirements.
Saudi Arabia
Villa solar programs and industrial rooftop mandates drive residential microinverter demand in Riyadh and Jeddah. SASO IEC 62109-1 certification filters supplier entry, concentrating procurement among pre-qualified vendors. The Kingdom's renewable energy project development office sets technical specifications that cascade through EPC contractor networks.
United Arab Emirates
Al Dhafra solar cluster development creates spillover demand for distributed residential systems as contractors build installation capacity. ESMA protocols enforce equivalent standards to Saudi certification, forcing parallel compliance streams. Dubai's net metering buyback rates accelerate self-consumption models in gated communities.
Kuwait
Lagging net metering implementation leaves residential solar penetration below regional peers, offering first-mover positioning as regulations mature. The Ministry of Electricity and Water's interconnection standards remain under development. Northern oil field periphery applications concentrate off-grid demand for remote pumping and telecom electrification.
Oman
Interior agricultural and industrial electrification needs drive standalone microinverter configurations where grid extension is uneconomical. The Authority for Electricity Regulation's distributed generation framework is advancing toward implementation. Dhofar and Al Batinah regions host early commercial rooftop pilots serving manufacturing facilities.
Qatar
Utility-scale solar commitments under the national renewable energy strategy create contractor capacity that spills into commercial distributed generation. Kahramaa interconnection standards emphasize grid stability requirements for inverter certification. Lusail and Msheireb developments incorporate building-integrated solar specifications.
GCC Solar Microinverter Market Key Industry Players
Listed leaders compete with private specialists across certification tier and thermal performance positioning. The vendor base concentrates among three to five suppliers holding dual SASO-ESMA compliance, with tiered differentiation by warranty duration and localized service capability. Strategic archetypes include integrated power electronics platforms, desert-optimized thermal specialists, and hybrid optimizer-inverter hybrids. Capacity expansion into regional distribution hubs and backward integration into power semiconductor sourcing represent dominant competitive vectors.
Within the certification-premium tier, Enphase Energy, Inc. and SMA Solar Technology AG exemplify divergent architectural approaches to Gulf market entry. SolarEdge Technologies Inc. occupies a hybrid positioning between panel-level and string-level conversion. Chilicon Power LLC and APsystems represent private specialists competing through price-accessible module-level electronics. Darfon and Delta Electronics, Inc. anchor East Asian manufacturing scale advantages. Sungrow and Canadian Solar leverage upstream module integration to bundle inverter procurement.
| Leading Market Players |
|---|
| Enphase Energy, Inc. |
| SMA Solar Technology AG |
| SolarEdge Technologies Inc. |
| APsystems |
| Chilicon Power LLC |
| Darfon |
| Delta Electronics, Inc. |
| Sungrow |
| Canadian Solar |
| Others |
Cost & Logistics Intelligence
East Asian foundry scale economies in silicon carbide wafer production anchor cost structures across the GCC microinverter value chain, compressing price floors for tier-two suppliers while concentrating margin capture among vertically integrated power semiconductor manufacturers. This scale dynamic filters through to Riyadh and Dubai procurement, where SASO and ESMA certification costs create divergent entry barriers that reshape competitive pricing tiers.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with UL 1741-SA and SASO IEC 62109-1 compliance commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium certified, standard certified, and economy pending-certification levels segments buyer access. Cost compression in the economy tier is intensifying because EPC contractors consolidate volume tenders and demand extended warranty bundling. Small businesses in Dubai's SME free zones exhibit the highest price sensitivity, while government-linked aggregators prioritize certification grade over per-watt cost.
Supply Chain Analysis
Inventory lead times for GaN and silicon carbide power semiconductors stretch certification-to-delivery windows, forcing distributors to pre-position stock ahead of SASO enforcement dates. Manufacturing concentrates in Taiwan, China, and South Korea, with backend assembly and testing migrating to Vietnam and Malaysia. Raw material dependencies center on rare earth substrates, copper interconnects, and aluminum thermal management housings. Single-source vulnerability in 200mm silicon carbide wafer supply exposes margin stability. Distribution runs through EPC direct procurement channels that bypass traditional electrical wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart microinverter adoption represents a high-growth disruption as Saudi Electricity Company interconnection standards mandate reactive power capability, compressing the addressable market to communication-enabled suppliers and accelerating replacement cycles for legacy inventory.
For Market Incumbents: Fortify certification moats by accelerating SASO IEC 62109-1 and ESMA dual-track compliance ahead of enforcement windows, while securing captive supply agreements with Taiwan-based GaN foundries to hedge silicon carbide concentration risk. SolarEdge's power optimizer architecture threatens panel-level microinverter positioning in price-sensitive UAE residential segments. For New Entrants and Emerging Players: Differentiate on thermal resilience specifications engineered for ambient temperatures exceeding 50°C, targeting Kuwait and Oman where net metering implementation lags and first-mover positioning remains available. Bypass established distribution by cultivating direct EPC relationships serving northern Saudi villa compounds. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors smart microinverter specialists with software-hardware integration capability and existing SASO compliance. Long-term viability hinges on grid code harmonization across GCC member states enabling regional scale. Watch for Saudi-Emirati regulatory convergence as the inflection signal for inventory pooling economics.| Strategic Initiative | Industry Significance |
|---|---|
| Dual SASO-ESMA Certification Investment | Unlocks simultaneous access to Saudi and UAE procurement channels without parallel compliance redundancy. |
| GaN-Based Switching Topology Migration | Captures premium positioning in Riyadh and Jeddah villa segments demanding superior heat tolerance. |
| EPC Direct Procurement Channel Development | Bypasses distributor margin extraction while embedding products into government-backed renewable auction specifications. |
| Localized Spare Parts Holding Requirements | Satisfies state-linked aggregator contract riders that now mandate 20-year performance warranty support. |
| Kuwait and Oman Market Pre-Positioning | Establishes brand presence ahead of net metering framework finalization in lagging GCC jurisdictions. |
Research Approach
Initial hypotheses were tested against primary input from EPC contractors, utility interconnection planners, and inverter procurement leads at state-linked aggregators, then refined through secondary validation against customs import records, SASO certification registries, and DEWA net metering registration databases. Bottom-up installation forecasts triangulated with top-down renewable auction capacity allocations derived from Saudi renewable energy project development office disclosures and Masdar procurement announcements.
Variance decomposition across product architecture, installation scale, and certification tier shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include panel-level versus string-level conversion electronics, residential versus commercial versus industrial system scale, and smart versus conventional grid-tie functionality. CAGRs were synthesized from installation volume trajectories and per-unit value erosion curves, with specific inputs drawn from thermal cycling test duration requirements and grid code evolution timelines.
Decision-makers should treat outputs as directional under assumptions of continued SASO enforcement and stable net metering buyback rates; material deviation in regulatory timelines or semiconductor supply availability would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Vegetable Dryer Market
Solar Power Systems
Non-Concentrating Solar Collector Market
Solar Power Systems
Solar Thermal Power Market
Solar Power Systems
Tubular Solar Collector Market
Solar Power Systems
Solar Fuel Market
Solar Power Systems
Flexible Parylene-Based Solar Cells Market
Solar Power Systems
United Arab Emirates Solar Photovoltaic (PV) Market
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
Solar Sunlight Control System Market
Solar Power Systems
Smart Solar Power Market
Solar Power Systems
United States Solar Energy Market
Solar Power Systems
United Kingdom Solar Power Market
Solar Power Systems
UV Solar Simulators Market
Solar Power Systems
Off-Grid Solar Power Market
Solar Power Systems
South America Solar Tracker Market
Solar Power Systems
Crystalline Silicon Solar PV Market