
 Saudi Arabia Chemical Logistics Market | 2026-2036
Saudi Arabia Chemical Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Chemical Logistics Market Insights
Specialty chemical manufacturers are unwinding legacy bulk-shipping contracts in favor of temperature-controlled, batch-specific logistics arrangements. Bahri Chemicals anchors deep-sea chemical tanker capacity through its dedicated fleet serving Red Sea and Arabian Gulf corridors. Almajdouie Logistics dominates overland heavy-lift transport for oversized reactor components and pressurized containers. DHL Supply Chain Saudi Arabia extends value-added services including inventory management and customs brokerage for multinational chemical entrants.
Chemical logistics encompasses the specialized transportation, storage, and handling of hazardous and non-hazardous chemical products requiring compliance with temperature thresholds, pressure ratings, and material compatibility specifications such as stainless-steel tank classifications or nitrogen-blanketing protocols. Petrochemicals sustain the largest volume footprint given Saudi Arabia's feedstock abundance and downstream derivative capacity, while specialty chemicals command premium margins due to smaller batch sizes, stricter handling protocols, and higher insurance requirements. Warehousing services within the service-type dimension are concentrating around bonded zones near King Fahd Industrial Port as exporters seek duty-deferral advantages and faster customs clearance.
SFDA oversight governs pharmaceutical-grade chemical imports and establishes cold-chain integrity mandates that reshape last-mile requirements. The General Authority of Civil Aviation and Saudi Customs coordinate hazardous-material air-freight protocols and cross-border documentation standards that determine market access speed. Stakeholders must weigh capital deployment between automated tank-farm infrastructure and flexible multi-modal hubs as project pipelines shift between commodity and specialty chemical dominance.
Market Dynamics
The Saudi chemical logistics sector is reconfiguring around Aramco's downstream megaprojects at Jubail and Yanbu, where specialty chemical output is displacing commodity bulk flows and demanding precision-handling infrastructure.
Growth Catalysts
- SFDA Cold-Chain Mandates:Pharmaceutical-grade chemical imports now require validated temperature-controlled corridors, expanding demand for qualified warehousing near King Fahd Industrial Port.
- Aramco Downstream Diversification:Crude-to-chemicals investments at Yanbu are generating specialized logistics needs for catalysts and process chemicals that resist bulk handling.
- Red Sea Transit Positioning:Saudi Arabia's geographic control over Bab-el-Mandeb alternatives is attracting transshipment flows for East African and Levantine chemical markets.
Market Restraints
- Stainless-Steel Tank Scarcity:Specialized ISO tank containers for corrosive chemicals face 14-18 month procurement lead times from Asian fabricators, constraining fleet expansion.
- SFDA Import Licensing Friction:Pharmaceutical chemical registrations require 90-120 day validation cycles that delay commercial launches and tie up working capital.
- Jubail-Yanbu Corridor Concentration:Over 70 percent of chemical warehousing capacity clusters within 50 kilometers of these two cities, creating single-point vulnerability.
Strategic Opportunities
- NEOM Industrial City Development:The northwestern giga-project's planned advanced materials cluster will require greenfield logistics infrastructure with no incumbent competition.
- Hydrogen Carrier Logistics:Ammonia and liquid organic hydrogen carrier flows for export to European offtakers under EU Green Deal import rules represent an emerging cargo category.
- Drone-Based Hazmat Inspection:General Authority of Civil Aviation pilot programs for unmanned aerial surveillance of tank farms could reduce manual inspection costs by half.
Industry Challenges
- Dangerous Goods Certification Gap:IMDG and ADR-certified drivers and warehouse operators remain scarce relative to fleet expansion targets, inflating recruitment premiums.
- Multi-Modal Integration Complexity:Port-to-plant chemical movements require seamless handoffs between Bahri deep-sea tankers, Almajdouie heavy-lift units, and last-mile tank trucks with incompatible scheduling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Chemical Logistics Market |
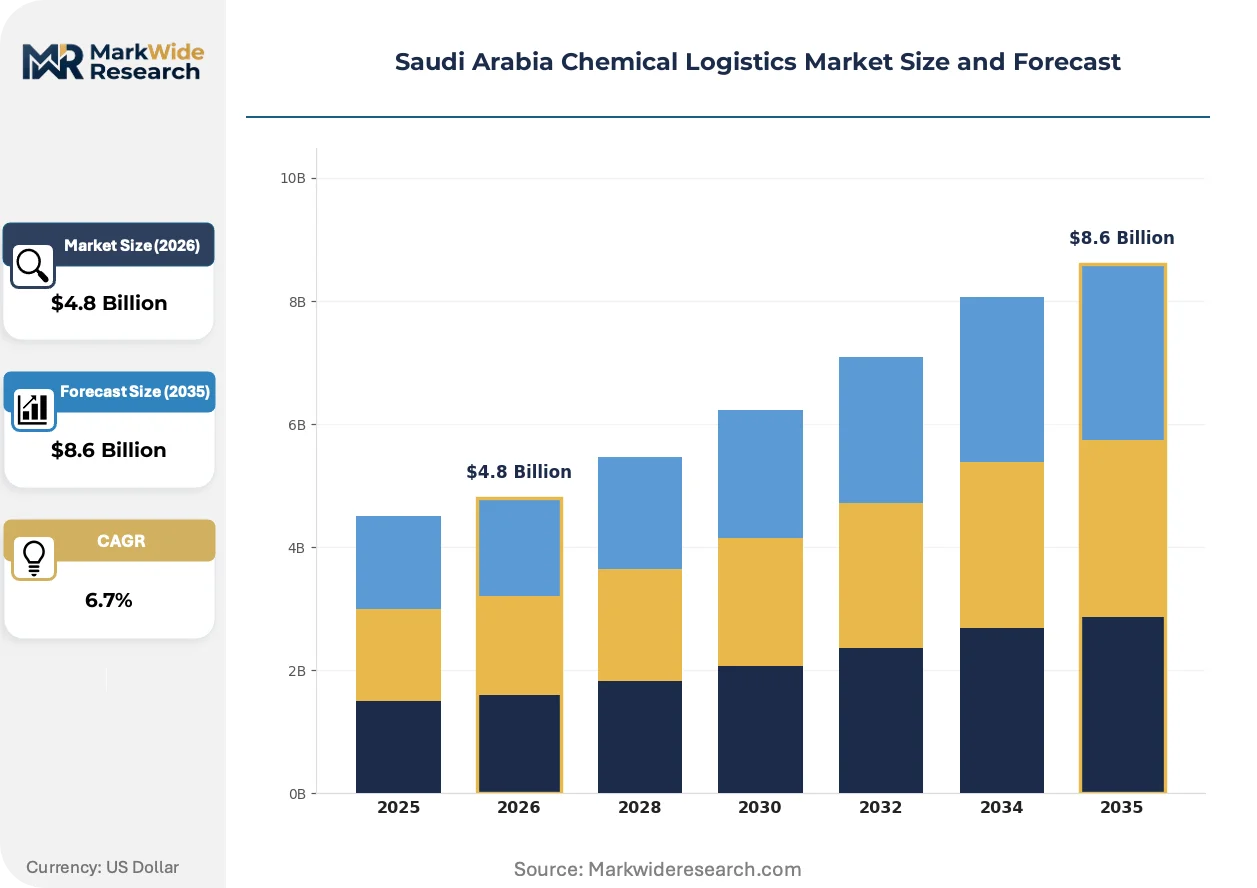
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk Chemicals, Specialty Chemicals, Fine Chemicals, Petrochemicals Application: Agriculture, Pharmaceuticals, Construction, Food & Beverage Service Type: Transportation, Warehousing, Distribution, Waste Management End User: Chemical Manufacturers, Oil & Gas Companies, Retailers, Exporters |
| Companies Covered | Bahri Chemicals, Saudi Transport & Investment Co. (Mubarrad), Almajdouie Logistics, Arabian Chemical Terminals, DHL Supply Chain Saudi Arabia, Agility Logistics, CEVA Logistics Saudi Arabia, Al-Futtaim Logistics, Bertschi Saudi Arabia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Chemical Logistics Market Trends and Innovations
Digital traceability and autonomous handling systems are displacing paper-based chain-of-custody methods across Saudi chemical logistics, with SFDA compliance deadlines accelerating vendor selection cycles.
Blockchain-enabled batch documentation is fragmenting traditional freight-forwarding value capture. Specialty chemical exporters to European REACH jurisdictions now demand immutable custody records from Saudi loading terminals through Rotterdam discharge. Maersk and local freight operators are deploying shared ledger infrastructure that bypasses document-checking intermediaries. This compression is forcing established customs brokers to reposition as compliance consultants rather than transaction processors.
SFDA's 2024 serialization requirements for imported pharmaceutical chemicals are mandating unit-level tracking from manufacturer through hospital pharmacy. The regulation requires temperature loggers with 15-minute interval reporting and blockchain-anchored certificates of analysis. Cold-chain operators serving Riyadh's medical district are retrofitting warehouse management systems to accommodate this data payload. European and Indian generic API suppliers are selecting logistics partners based on SFDA audit readiness rather than rate competitiveness.
Buyers of specialty chemicals are consolidating vendor panels and demanding integrated inventory management from logistics providers. Multinational pharmaceutical manufacturers in King Abdullah Economic City now contract DHL Supply Chain for vendor-managed inventory of GMP-grade solvents, displacing traditional spot procurement from multiple freight operators. This bundling concentrates purchasing power with integrators capable of SFDA-compliant warehousing and customs brokerage under single accountability. The shift is most pronounced among US and European pharmaceutical entrants lacking established Saudi distribution infrastructure.
Saudi Arabia Chemical Logistics Market Segmentation
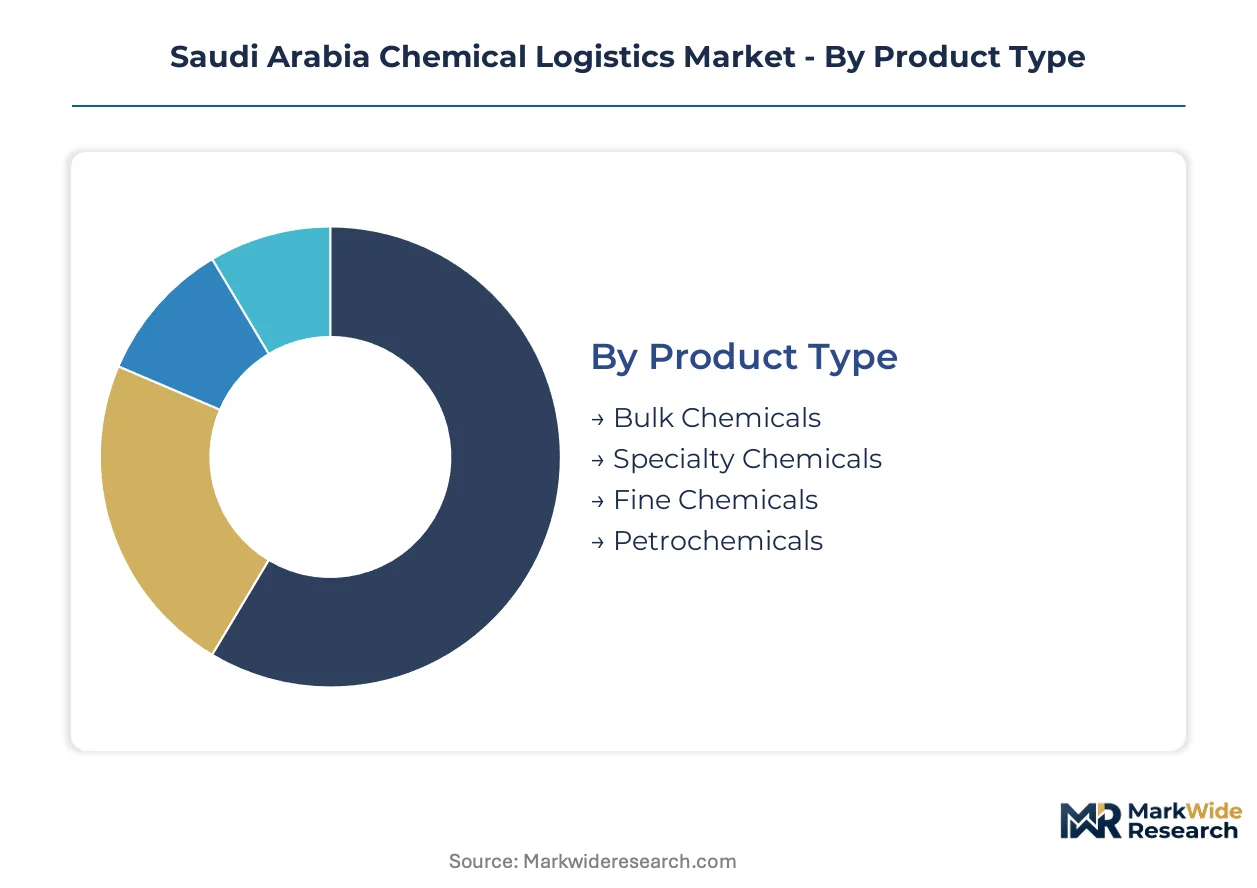
Chemical logistics segmentation in Saudi Arabia reflects divergent handling protocols across product hazard classes and end-use regulatory stringency. SFDA oversight, Aramco downstream integration, and Jubail-Yanbu corridor concentration create distinct service requirements that reshape provider specialization.
Product Type:
SFDA cold-chain mandates and ADR/IMDG certification thresholds split logistics capabilities across corrosive, flammable, and inert chemical classifications.
- Petrochemicals:Ethylene, propylene, and aromatics derivatives move through dedicated pipeline networks and stainless-steel ISO tanks with nitrogen-blanketing protocols. Jubail Industrial City hosts the dominant storage capacity, where Aramco SABIC joint ventures generate feedstock flows requiring minimal modal handoffs.
- Specialty Chemicals:Catalysts, process additives, and performance materials demand temperature-controlled corridors and batch-specific documentation. Pharmaceutical-grade imports under SFDA serialization rules are concentrating demand around King Fahd Industrial Port bonded warehousing.
- Bulk Chemicals:Sulfuric acid, caustic soda, and ammonia move via deep-sea tankers and heavy-lift rail with corrosion-resistant handling equipment.
- Fine Chemicals:High-purity intermediates for agrochemical and electronic applications require dedicated clean-room loading and contamination-segregated transport.
Established volume favors petrochemicals; emerging adoption favors specialty chemicals.
Application:
End-use regulatory intensity determines margin capture, with pharmaceutical and food-grade corridors commanding premium handling fees over industrial bulk.
- Pharmaceuticals:API imports and excipient distribution fall under SFDA serialization mandates with 15-minute temperature logging and blockchain-anchored certificates of analysis. Cold-chain operators serving Riyadh's medical district retrofit warehouse management systems for compliance.
- Agriculture:Fertilizer and agrochemical movements peak seasonally around planting cycles, requiring flexible fleet scaling and Yanbu port access for urea and phosphate exports.
- Construction:Admixtures, sealants, and coatings move through less stringent handling protocols with standard tank-truck and flatbed distribution.
- Food & Beverage:Food-grade solvents and packaging materials require HACCP-aligned warehousing with segregation from hazardous chemical zones.
Margin compression hits construction; compliance premiums expand pharmaceuticals.
Service Type:
Capital deployment tension separates fixed tank-farm infrastructure from flexible multi-modal hubs as project pipelines shift between commodity and specialty dominance.
- Transportation:Deep-sea chemical tankers, heavy-lift overland units, and last-mile tank trucks form the modal stack. Bahri Chemicals anchors Red Sea and Arabian Gulf corridor capacity through owned fleet deployment.
- Warehousing:Bonded zones near King Fahd Industrial Port concentrate temperature-controlled and hazardous-material storage as exporters seek duty-deferral advantages.
- Distribution:Vendor-managed inventory and integrated customs brokerage consolidate purchasing power with DHL Supply Chain and similar integrators.
- Waste Management:Spent catalysts, contaminated packaging, and process residuals require licensed disposal tracking under Saudi Environmental Protection Authority guidelines.
Tank-farm lock-in threatens transportation; value-added bundling favors distribution.
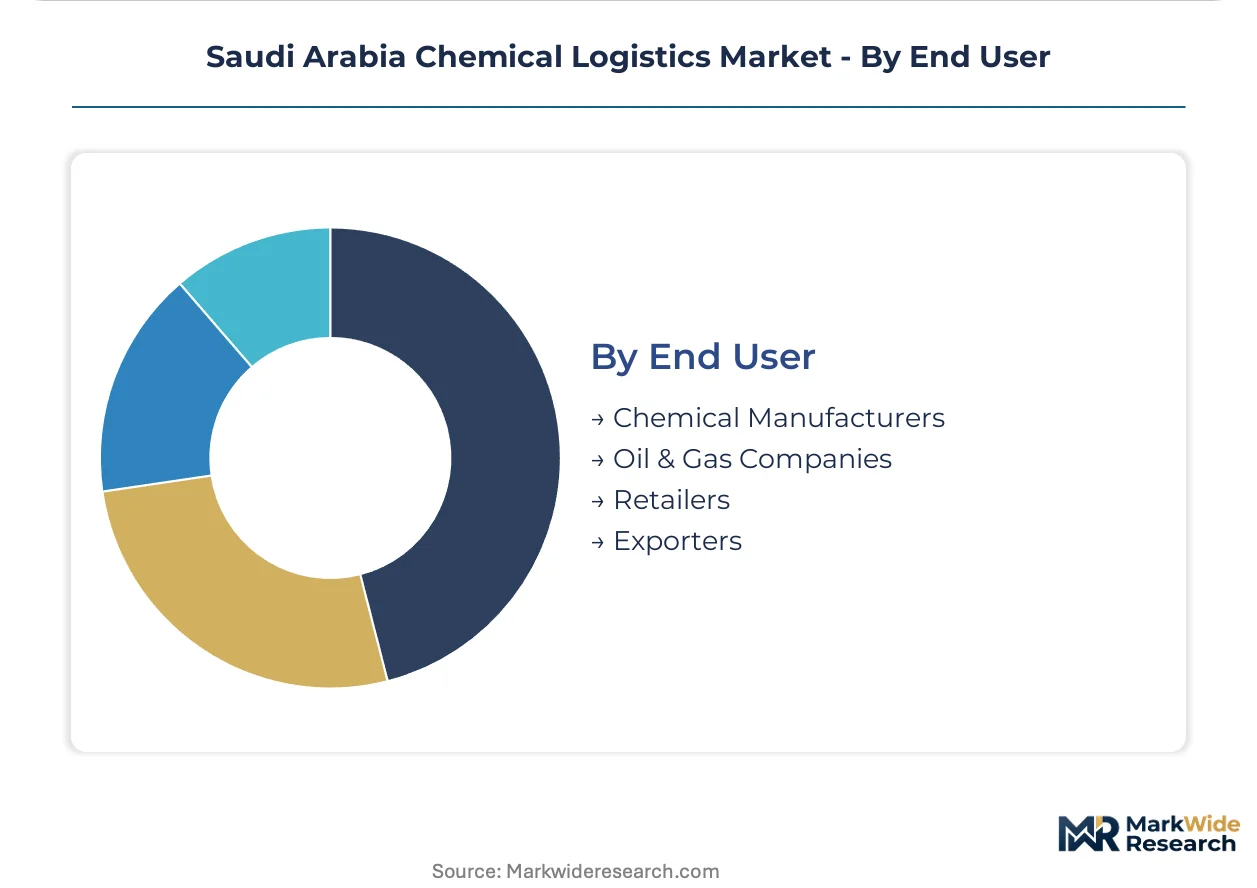
End User:
Procurement sophistication gaps separate multinational entrants seeking single-accountability logistics from domestic producers with fragmented spot arrangements.
- Chemical Manufacturers:SABIC and specialty chemical joint ventures demand integrated inbound feedstock and outbound derivative logistics with synchronized production scheduling.
- Oil & Gas Companies:Aramco downstream projects at Yanbu generate catalyst and process chemical requirements that resist bulk handling and demand precision delivery windows.
- Retailers:Agricultural supply and construction material distributors require seasonal surge capacity and regional distribution center access.
- Exporters:European REACH jurisdiction shipments demand immutable custody records from Saudi loading terminals through Rotterdam discharge, favoring blockchain-enabled operators.
Contract consolidation favors chemical manufacturers; spot fragmentation persists among retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's chemical logistics corridors channel specialty and bulk flows toward European REACH jurisdictions and East African markets, with domestic infrastructure concentrated around Aramco's downstream clusters.
Eastern Province
Jubail Industrial City hosts the densest concentration of petrochemical storage and pipeline networks, where Aramco SABIC joint ventures generate feedstock flows requiring minimal modal handoffs. SFDA bonded warehousing near King Fahd Industrial Port serves pharmaceutical-grade chemical exporters seeking duty-deferral advantages. The Jubail-Yanbu corridor anchors over 70 percent of national chemical warehousing capacity within a 50-kilometer radius.
Western Region
Yanbu's crude-to-chemicals investments generate specialized logistics needs for catalysts and process chemicals that resist bulk handling. Red Sea transit positioning attracts transshipment flows for East African and Levantine chemical markets through Bab-el-Mandeb alternatives. Almajdouie Logistics dominates overland heavy-lift transport for oversized reactor components moving between Yanbu port and inland industrial zones.
Riyadh
The capital's medical district drives cold-chain demand for SFDA-compliant pharmaceutical chemical distribution, requiring 15-minute temperature logging and blockchain-anchored certificates of analysis. DHL Supply Chain Saudi Arabia extends vendor-managed inventory services to multinational pharmaceutical manufacturers lacking established Saudi distribution infrastructure. Last-mile logistics retrofit warehouse management systems to accommodate serialization data payloads.
NEOM Northwest
The giga-project's planned advanced materials cluster will require greenfield logistics infrastructure with no incumbent competition. Hydrogen carrier logistics for ammonia and liquid organic hydrogen carrier exports to European offtakers represent an emerging cargo category under EU Green Deal import rules. Drone-based hazmat inspection pilot programs through the General Authority of Civil Aviation could reduce manual tank farm surveillance costs.
Saudi Arabia Chemical Logistics Market Competitive Landscape
Listed leaders compete with private specialists across fleet ownership and service integration, producing a tiered structure where scale-driven tanker operators, heavy-lift overland specialists, and multinational integrators occupy distinct competitive positions. Three strategic archetypes dominate: state-linked maritime carriers with captive fleet capacity, domestic heavy-lift operators with project cargo expertise, and global 3PLs with SFDA compliance infrastructure. Competitive moves concentrate on automated tank-farm deployment and multi-modal hub integration as project pipelines shift between commodity and specialty chemical dominance.
Within the maritime carrier archetype, Bahri Chemicals anchors deep-sea chemical tanker capacity through Red Sea and Arabian Gulf corridors. Among domestic heavy-lift specialists, Almajdouie Logistics exemplifies project-cargo positioning for pressurized containers and reactor components. On the integrator tier, DHL Supply Chain Saudi Arabia represents bundled service models combining warehousing, customs brokerage, and inventory management for multinational entrants.
| Leading Market Players |
|---|
| Bahri Chemicals |
| Saudi Transport & Investment Co. (Mubarrad) |
| Almajdouie Logistics |
| Arabian Chemical Terminals |
| DHL Supply Chain Saudi Arabia |
| Agility Logistics |
| CEVA Logistics Saudi Arabia |
| Al-Futtaim Logistics |
| Bertschi Saudi Arabia |
| Others |
Pricing and Supply Chain Analysis
SFDA cold-chain certification gates both supplier qualification and price differentiation simultaneously, as pharmaceutical-grade logistics providers command handling premiums that commodity chemical transporters cannot access without validated temperature-controlled infrastructure and serialized tracking systems.
Pricing Analysis
Current-generation ISO tank container fleets with nitrogen-blanketing protocols price at premiums against prior-generation bulk-shipping contracts, while next-generation blockchain-anchored custody systems are reshaping rate structures for European REACH-bound exports. Three-tier pricing structure across premium cold-chain, standard hazardous-material, and economy bulk-chemical levels stratifies the market. Price differentiation hinges on ADR/IMDG certification tier and stainless-steel tank classification. Cost compression in standard hazardous-material tiers is intensifying because Asian fabricator lead times stretch fleet expansion timelines. Construction chemical buyers exhibit highest price sensitivity; pharmaceutical manufacturers show lowest.
Supply Chain Analysis
Inventory lead times for specialized ISO tank containers now stretch 14-18 months from Asian fabricators, constraining fleet deployment and inflating working capital requirements for logistics operators. Supply concentrates in South Korea, China, and Japan for stainless-steel tank fabrication. Raw material dependencies include specialty steel alloys, temperature logger electronics, and nitrogen supply systems. Single-source vulnerability runs through Jubail-Yanbu corridor concentration where over 70 percent of warehousing capacity clusters within 50 kilometers. Distribution runs through Bahri deep-sea tankers feeding bonded zones near King Fahd Industrial Port.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA serialization mandates are disrupting competitive positioning, as pharmaceutical-grade compliance infrastructure becomes the decisive barrier between premium logistics capture and commodity margin erosion.
For Market Incumbents: Shield core tank-farm assets through automated infrastructure deployment at Jubail and Yanbu corridors before NEOM greenfield competition materializes. Backward integration into captive stainless-steel tank procurement from Korean fabricators reduces lead-time exposure. Certification investment in drone-based hazmat inspection pilots through General Authority of Civil Aviation programs secures regulatory preference. For New Entrants and Emerging Players: Differentiate on SFDA audit readiness rather than rate competitiveness, targeting European and Indian generic API suppliers lacking established Saudi distribution infrastructure. The most penetrable white-space sits in NEOM's planned advanced materials cluster where no incumbent logistics presence exists. A vendor-managed inventory go-to-market angle bundled with customs brokerage displaces fragmented spot procurement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated tank-farm infrastructure as project pipelines shift from commodity bulk toward specialty chemical dominance. Long-term viability favors operators with integrated multi-modal hubs spanning deep-sea, heavy-lift, and last-mile capabilities. Acquisition targets should display SFDA-compliant warehousing and blockchain-enabled custody systems. The signal to watch is hydrogen carrier logistics pilot contracts for ammonia exports under EU Green Deal import rules.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Tank-Farm Deployment | Reduces manual inspection costs through drone-based hazmat surveillance piloted by General Authority of Civil Aviation. |
| Backward Integration into Tank Fabrication | Mitigates 14-18 month procurement lead times from Korean and Chinese stainless-steel ISO tank suppliers. |
| SFDA Compliance Infrastructure Buildout | Captures pharmaceutical-grade premiums through validated cold-chain corridors with 15-minute temperature logging. |
| Multi-Modal Hub Integration | Synchronizes Bahri deep-sea tankers with Almajdouie heavy-lift and last-mile tank trucks under single accountability. |
| Hydrogen Carrier Logistics Development | Positions for ammonia and liquid organic hydrogen carrier exports to European offtakers under EU Green Deal rules. |
Research Methodology
Operator-level perspectives from logistics fleet managers, pharmaceutical procurement directors, chemical plant operators, and customs brokerage heads anchored the qualitative base. Primary interviews combined with secondary validation from Saudi Customs trade data, SFDA regulatory filings, SEC 10-K disclosures of listed chemical logistics operators, and Aramco downstream project announcements. Bottom-up tank-farm capacity counts and top-down petrochemical throughput estimates were triangulated to anchor volume assumptions.
Sensitivity analysis tested forecast robustness across stainless-steel tank procurement lead-time scenarios and SFDA serialization compliance penetration rates. Segmentation dimensions modeled include product hazard classification, end-use regulatory intensity, service-type capital structure, and regional corridor concentration. CAGRs were derived from installed base expansion rates and project pipeline conversion probabilities. Industry-specific inputs incorporated Aramco downstream megaproject timelines and bonded warehousing capacity additions near King Fahd Industrial Port.
Forecasts assume regulatory continuity in SFDA pharmaceutical oversight and Saudi Environmental Protection Authority waste management regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
China Bunker Fuel Market
Fuels
Global Chemical Logistics Market
Fuels
Wood Pellet Market
Fuels
Tire Derived Fuel Market
Fuels
Middle-East and Africa Commercial Aircraft Aviation Fuel Market
Fuels
LPG Vaporizer Market
Fuels
Coal Intelligent Dry Separators Market
Fuels
LNG Fueling Station Market
Fuels
Iso-Octane Market
Fuels
Europe Gas Market
Fuels
India Bunker Fuel Market
Fuels
Gas Hydrates Market
Fuels
United Arab Emirates Fuel Station Market
Fuels
Gasoline As a Fuel Market
Fuels
Fuel Grinder Market
Fuels
Catalytic Hydrothermolysis Jet [CHJ] Fuel Market