
 Solar Thermal Power Market | 2026-2036
Solar Thermal Power Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Thermal Power Market Outlook
Aftermarket service revenue for molten salt storage systems is reshaping margin distribution across the solar thermal value chain. BrightSource Energy leverages its tower technology leadership to capture recurring maintenance contracts in utility-scale installations. Abengoa Solar anchors its position through backward integration into receiver tube manufacturing and thermal oil supply chains. Siemens competes on turbine-generator integration, extending its power island expertise from fossil into concentrated solar applications.
Solar thermal power harnesses concentrated sunlight to heat a working fluid—typically synthetic oil, molten salt, or water—driving steam or gas turbines for electricity generation at temperatures exceeding 550°C in tower configurations. The technology serves baseload and dispatchable power needs where photovoltaic intermittency creates grid stability constraints. Parabolic trough installations occupy the largest installed base due to decades of commercial operation, though solar tower configurations represent the fastest-growing segment as higher operating temperatures improve steam cycle efficiency. Industrial process heat applications are gaining traction as cement and chemical producers seek to decarbonize thermal loads below 400°C.
Spain's Ministry for Ecological Transition enforces renewable energy auction mechanisms that favor dispatchable solar thermal with storage over intermittent sources. The EU Green Deal and F-Gas Regulation are tightening heat transfer fluid specifications, pushing operators toward lower-global-warming-potential alternatives. China's National Energy Administration and MIIT coordinate molten salt chemistry standards with domestic supply chain localization targets. Stakeholders must monitor regulatory treatment of long-duration storage eligibility in capacity markets and carbon border adjustment mechanisms affecting project finance structures.
Market Dynamics
Molten salt storage integration is restructuring project economics across the solar thermal value chain, compressing levelized cost differentials between dispatchable solar thermal and combined-cycle gas plants in high-insolation corridors.
Growth Catalysts
- Spain's renewable auction mechanisms:Dispatchability premiums favor concentrated solar power with thermal storage over photovoltaic installations. Developers secure 15-25 year power purchase agreements through competitive bidding.
- China's dual carbon policy framework:Feed-in tariff structures and MIIT localization mandates accelerate molten salt chemistry standardization. Domestic supply chain buildout reduces receiver tube import dependency.
- Industrial process heat decarbonization:Cement and chemical producers below 400°C thermal loads are piloting parabolic trough integration. Saudi Aramco and UAE cement consortia lead procurement trials.
Market Restraints
- Synthetic oil price volatility:Diphenyl oxide/biphenyl eutectic mixtures fluctuate with benzene feedstock costs. Operators face working capital pressure during procurement cycles.
- Heliostat manufacturing concentration:Chinese and Spanish suppliers control precision glass mirror and steel frame production. Project developers encounter single-source risk for tower configurations.
- Grid interconnection queues:Transmission upgrade timelines in the US Southwest and North Africa delay commercial operation dates by 18-36 months. FERC interconnection reforms have not cleared backlogs.
Strategic Opportunities
- Green hydrogen co-production:Solar towers operating above 800°C can drive high-temperature electrolysis or thermochemical water splitting. Australian and Chilean project pipelines integrate hydrogen offtake contracts.
- EU F-Gas Regulation phase-down:Heat transfer fluid specifications tighten global warming potential thresholds. Operators must retrofit or replace synthetic oil circuits with lower-emission alternatives by 2030.
- Desalination-thermal hybrid plants:Multi-effect distillation pairs with parabolic trough waste heat in Saudi Arabia and Oman. Water scarcity drives dual-purpose infrastructure investment.
Industry Challenges
- Molten salt chemistry expertise scarcity:Nitrate salt mixture corrosion management and freeze recovery protocols require specialized O&M crews. Training pipelines have not scaled with installation growth.
- Receiver tube degradation monitoring:Vacuum seal failure detection and selective coating performance tracking demand predictive maintenance systems. Asset operators struggle to standardize inspection intervals across trough and tower geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Thermal Power Market |
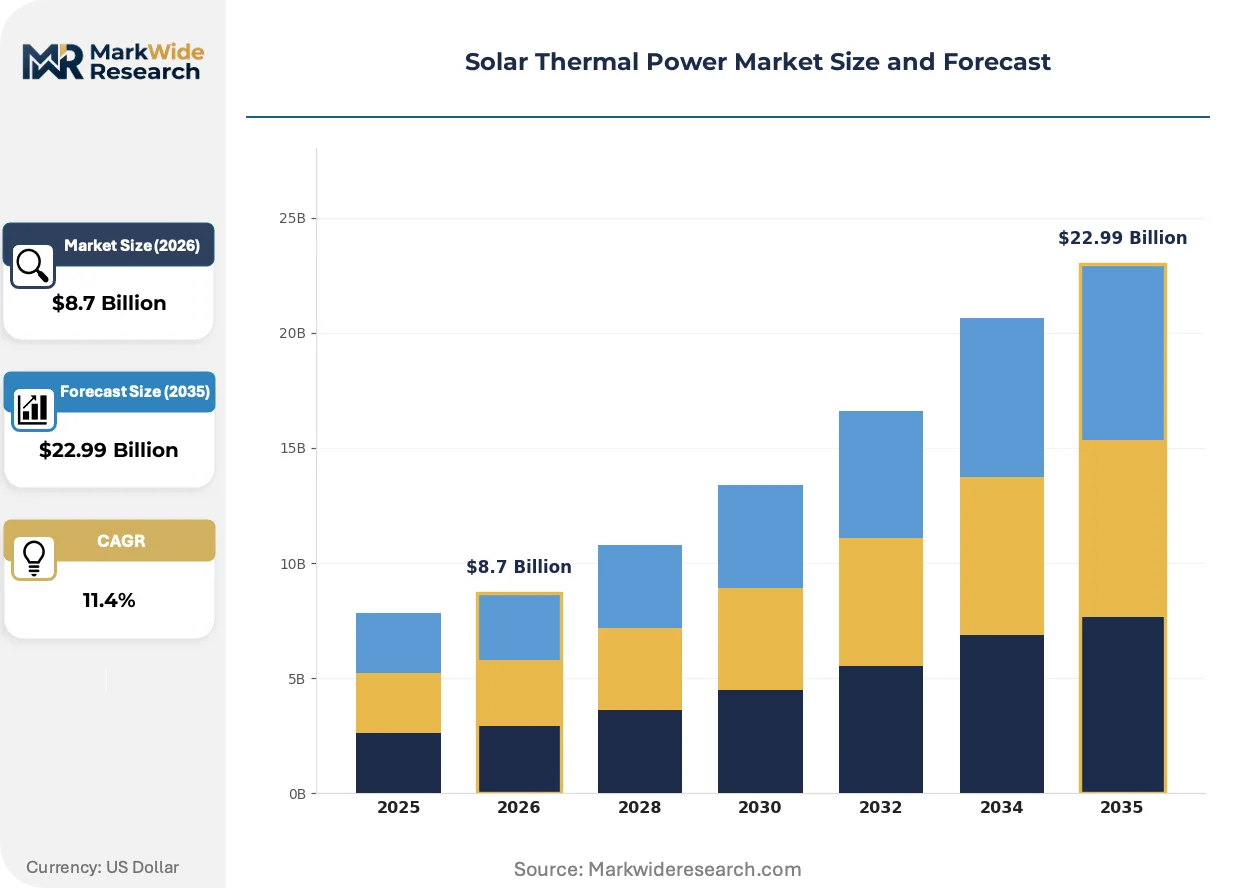
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Parabolic Trough, Solar Tower, Fresnel Collector, Dish-Stirling Application: Power Generation, Water Heating, Industrial Processes, Desalination End User: Utilities, Industrial, Commercial, Residential Installation: On-Grid, Off-Grid, Hybrid, Centralized |
| Companies Covered | BrightSource Energy, Abengoa Solar, Siemens, Acciona, SolarReserve, SENER, Aalborg CSP, GlassPoint Solar, Torresol Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Thermal Power Market Strategic Shifts
Advanced receiver designs and solid-state thermal storage media are compressing the cost-performance frontier for high-temperature solar thermal applications. These innovations reshape competitive positioning between incumbent parabolic trough architectures and emerging tower configurations.
Solid particle receiver technology circulating ceramic granules instead of liquid heat transfer fluids is rendering obsolete the temperature limitations of molten salt systems. Sandia National Laboratories and German Aerospace Center pilot plants demonstrate 900°C+ particle temperatures enabling supercritical CO2 power cycles. Utility developers in Australia and South Africa evaluate particle-to-fluid heat exchanger integration for hybrid storage configurations.
The EU F-Gas Regulation mandates progressive hydrofluorocarbon phase-down affecting heat transfer fluid specifications across concentrated solar power installations. REACH compliance costs for synthetic oil disposal and replacement are redirecting operator capital toward lower-global-warming-potential alternatives. Spanish and Italian operators accelerate thermal oil circuit retrofits ahead of 2027 restriction milestones.
Aftermarket service unbundling separates long-term O&M contracts from initial EPC agreements in utility-scale procurement. Saudi ACWA Power and Moroccan MASEN tender discrete maintenance packages for heliostat cleaning, salt chemistry management, and turbine overhaul. This procurement model shift compresses vendor margins while extending contract visibility for specialized service providers across Middle East and North Africa project portfolios.
Solar Thermal Power Market Segmentation
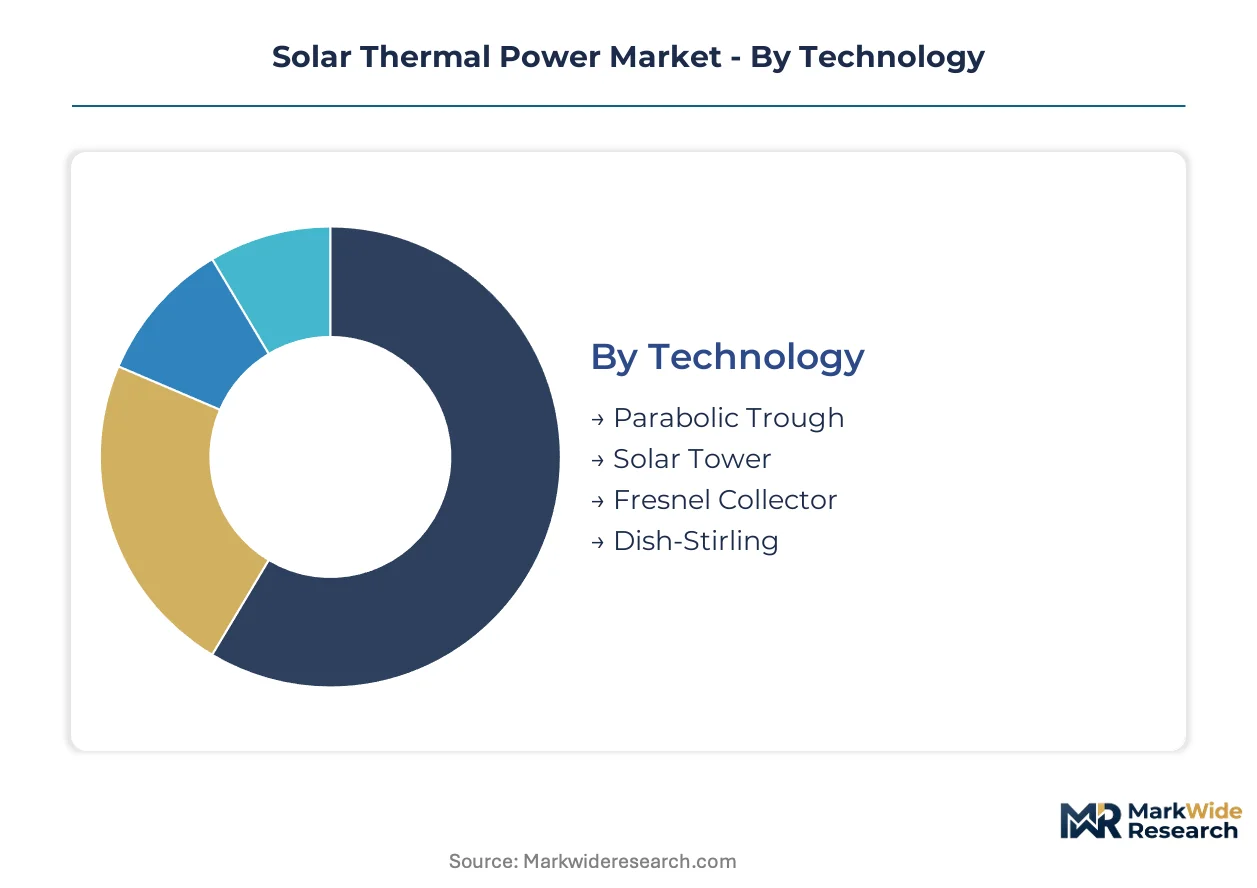
Solar thermal power segmentation reveals distinct technology-performance tradeoffs across temperature ranges, storage integration, and grid services. Each dimension carries implications for project finance structures, O&M specialization, and regulatory eligibility in renewable energy auctions.
Technology:
Parabolic trough systems anchor the installed base through decades of commercial operation, while solar towers capture developer attention for next-generation high-temperature applications.
- Parabolic Trough:Curved mirrors concentrate sunlight onto receiver tubes containing synthetic oil, achieving operating temperatures around 400°C. Spain's Extremadura corridor and Morocco's Noor complex concentrate procurement for utility-scale plants with molten salt storage hybrids. Developers favor the technology for its bankable performance history and established supply chains.
- Solar Tower:Heliostat fields redirect sunlight to a central receiver atop a tower, enabling temperatures exceeding 550°C and superior steam cycle efficiency. China's Qinghai province and South Africa's Northern Cape host the fastest-expanding project pipelines as operators chase higher capacity factors through advanced receiver designs.
- Fresnel Collector:Flat mirror arrays achieve linear concentration at lower capital cost, suited to industrial process heat below 300°C.
- Dish-Stirling:Parabolic dishes drive Stirling engines at high efficiency in distributed configurations, finding niche applications in remote off-grid installations.
The dominant share belongs to Parabolic Trough, while Solar Tower is closing the gap fastest.
Application:
Cost tiers separate bulk electricity supply from premium thermal services where fossil fuel displacement commands price premiums.
- Power Generation:Utility-scale plants feed electricity into transmission networks, competing directly with combined-cycle gas on levelized cost where storage enables dispatchability. Saudi ACWA Power and Moroccan MASEN tender multi-hundred-megawatt installations with 15-25 year offtake contracts.
- Industrial Processes:Cement kilns, chemical reactors, and food processing facilities below 400°C thermal loads pilot solar thermal integration. Saudi Aramco and UAE cement consortia lead procurement trials as carbon border adjustments reshape fuel economics.
- Water Heating:Residential and commercial buildings deploy evacuated tube collectors for domestic hot water, particularly in Mediterranean climates with high solar irradiance.
- Desalination:Multi-effect distillation pairs with parabolic trough waste heat in Saudi Arabia and Oman, addressing water scarcity through dual-purpose infrastructure.
Power Generation commands the largest project scale, though Industrial Processes is expanding most quickly as manufacturing decarbonization accelerates.
End User:
Customer type dictates financing structures, with utilities accessing sovereign-backed debt unavailable to commercial or residential buyers.
- Utilities:State-owned and independent power producers dominate procurement of utility-scale concentrated solar power with integrated storage, leveraging long-term power purchase agreements and renewable auction mechanisms.
- Industrial:Energy-intensive manufacturers seek to hedge volatile natural gas prices through captive solar thermal installations, particularly in chemicals and mining sectors.
- Commercial:Hotels, hospitals, and district heating networks deploy mid-scale systems for predictable thermal cost structures.
- Residential:Single-family homes and small multi-unit buildings install evacuated tube or flat-plate collectors for water heating, constrained by rooftop space and capital availability.
Utilities retain the dominant installation share, while Industrial end users are gaining share fastest as process heat electrification advances.
Installation:
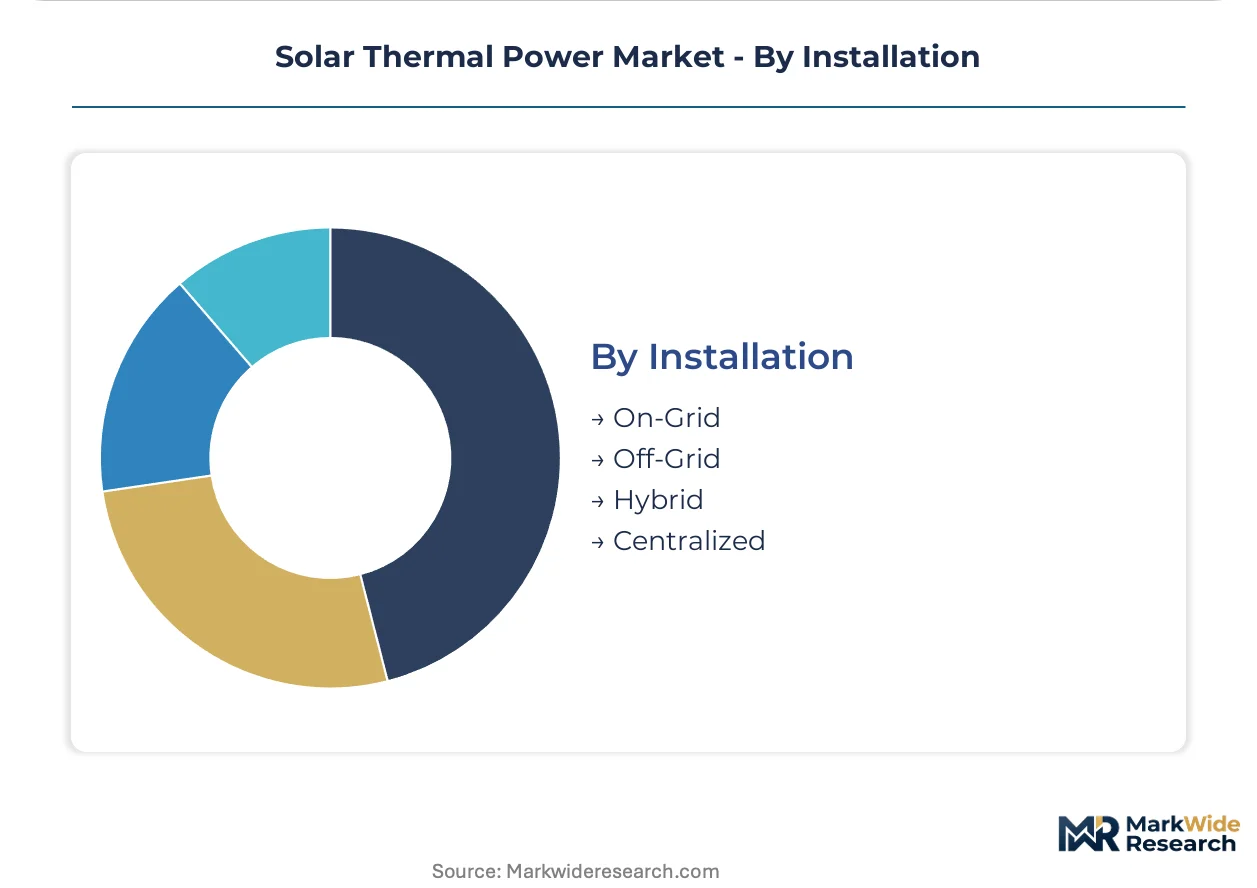
Grid connectivity determines revenue streams, with on-grid installations capturing capacity payments and renewable energy certificates unavailable to isolated systems.
- On-Grid:Plants interconnect with transmission infrastructure to sell electricity into wholesale markets or bilateral contracts, requiring FERC interconnection approval in the US and equivalent grid codes elsewhere.
- Off-Grid:Remote mining camps, island communities, and agricultural operations deploy standalone systems without transmission dependency, absorbing higher levelized costs for energy autonomy.
- Hybrid:Solar thermal integrates with photovoltaic, wind, or battery storage to optimize capacity utilization and grid services, particularly in Chilean and Australian project pipelines.
- Centralized:Large single-site installations achieve economies of scale in heliostat manufacturing and salt storage, dominating utility procurement.
On-Grid configurations hold the dominant share, while Hybrid installations are climbing the fastest as developers optimize multi-technology portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Spain and the Middle East accept premium pricing for dispatchable capacity, while Chinese utilities drive hard bargains on molten salt system costs. Price elasticity varies sharply by grid stability requirements and auction design.
Spain
Extremadura and Andalusia solar corridors concentrate developer activity around parabolic trough and tower configurations. The Ministry for Ecological Transition enforces renewable auction mechanisms that award dispatchability premiums to concentrated solar power with thermal storage over photovoltaic installations. Noor-Ouarzazate style project pipelines anchor procurement timelines through 2030.
China
Qinghai province hosts the fastest-expanding solar tower pipeline as developers chase higher capacity factors. The National Energy Administration coordinates with MIIT on molten salt chemistry standards and domestic supply chain localization targets. Dual carbon policy frameworks accelerate feed-in tariff structures that favor integrated storage systems.
Morocco
MASEN tenders multi-hundred-megawatt installations with 15-25 year offtake contracts through competitive bidding. The national renewable energy agency structures procurement to favor dispatchable solar thermal over intermittent sources. Ouarzazate and Midelt solar complexes anchor North African project concentration.
Saudi Arabia
ACWA Power leads utility-scale procurement with integrated desalination-thermal hybrid configurations. The national renewable energy program and water ministry coordinate dual-purpose infrastructure investment. NEOM and Riyadh industrial corridors concentrate pilot trials for cement and chemical process heat applications.
United States
Southwest utilities face 18-36 month grid interconnection queue delays that compress commercial operation timelines. FERC interconnection reforms have not cleared backlogs in high-insolation corridors. California and Arizona project developers absorb working capital pressure during transmission upgrade cycles.
Solar Thermal Power Market Competitive Environment
Capability concentration sits with tower technology specialists and molten salt system integrators; scale advantage sits with turbine-generator manufacturers and precision heliostat fabricators. The market structures around three tiers: technology licensors with proprietary receiver designs, EPC contractors with backward integration into thermal oil supply chains, and component suppliers competing on manufacturing throughput. Dominant competitive moves include aftermarket service unbundling from initial EPC agreements and strategic partnerships for solid-state thermal storage pilot programs.
Among US-based technology developers, BrightSource Energy and SolarReserve exemplify the tower configuration archetype with proprietary heliostat field control systems. Siemens anchors the turbine-generator integration tier, extending power island expertise from fossil fuel into concentrated solar applications. Spanish specialists including Abengoa Solar and SENER occupy positions between technology licensing and EPC execution, with backward integration into receiver tube manufacturing.
| Leading Market Players |
|---|
| BrightSource Energy |
| Abengoa Solar |
| Siemens |
| Acciona |
| SolarReserve |
| SENER |
| Aalborg CSP |
| GlassPoint Solar |
| Torresol Energy |
| Others |
Value Chain & Pricing Dynamics
Chinese precision glass mirror and steel frame manufacturers control heliostat production capacity, concentrating margin capture in the upstream fabrication tier while project developers downstream absorb single-source risk premiums in tower configuration procurement.
Pricing Analysis
Aftermarket service contracts for molten salt chemistry management and receiver tube replacement drive lifetime value capture across utility-scale installations. Pricing stratifies across premium, standard, and economy tiers based on storage integration depth and dispatchability guarantees. Cost compression in synthetic oil procurement is intensifying because benzene feedstock volatility pressures working capital cycles. Industrial process heat buyers exhibit highest price sensitivity, while Middle Eastern utilities accepting long-term offtake structures show lowest.
Supply Chain Analysis
Heliostat contract manufacturing concentrates in China and Spain, with domestic content mandates reshaping procurement patterns. The supply chain draws from nitrate salt deposits in Chile, synthetic oil refineries in Germany, and selective coating specialists in the United States. Single-source vulnerability runs through precision mirror glass supply. Distribution feeds from EPC contractors through to sovereign-backed utilities and industrial offtakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar thermal incumbents must navigate photovoltaic-plus-battery substitution threats that erode dispatchability premiums in renewable energy auctions.
For Market Incumbents: Insulate tower technology margins through captive receiver tube manufacturing and molten salt chemistry IP. Backward integration into thermal oil supply chains defends against benzene cost volatility. Anchor long-term O&M contracts before EPC handoff to lock recurring revenue streams. For New Entrants and Emerging Players: Industrial cement and chemical facilities below 400°C thermal loads in Saudi Arabia and the UAE represent the most penetrable entry point for parabolic trough pilots. Partner with national oil companies on process heat decarbonization trials to bypass utility-scale development barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed EPC contractors holding Spanish and Moroccan project pipelines. Five-to-ten year viability hinges on storage eligibility in capacity market designs. Watch for carbon border adjustment mechanism implementation as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Molten Salt Storage Integration | Enables dispatchability premiums in Spain's renewable auction mechanisms. |
| Backward Integration into Receiver Manufacturing | Captures margin pools currently held by Chinese and Spanish suppliers. |
| Industrial Process Heat Partnerships | Opens cement and chemical decarbonization revenue streams with Saudi Aramco. |
| Green Hydrogen Co-production Licensing | Extends solar tower economics into Australian and Chilean hydrogen offtake contracts. |
| F-Gas Regulation Compliance Retrofit | Mandatory thermal oil replacement creates aftermarket service demand in EU installations. |
Study Parameters
The analysis maps parabolic trough, solar tower, Fresnel collector, and dish-Stirling configurations, each validated through utility planning officers, IPP project developers, EPC contractors, and molten salt system integrators. Primary interview findings triangulate against EIA data, IEA reports, FERC filings, and project development databases. Bottom-up capacity installation tracking reconciles with top-down addressable market sizing.
Assumptions held fixed include China's dual carbon policy framework and Spain's dispatchability auction premiums, while feed-in tariff levels and synthetic oil price trajectories varied across scenarios. The projection horizon models technology type, storage integration depth, application segment, and regional regulatory cluster. CAGRs derive from segmented demand build-up and technology cost curves. Forecast inputs include heliostat manufacturing capacity expansion and molten salt chemistry standardization timelines.
Practitioners should monitor grid interconnection queue clearance rates and carbon border adjustment implementation for early signals of demand revision. Forecasts reflect assumptions about sovereign-backed procurement continuity and thermal storage eligibility in capacity markets. Quarterly review of auction mechanism design changes and synthetic oil price volatility is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Photovoltaics Wafer Market
Solar Power Systems
Solar PV Carport Market
Solar Power Systems
Global Ultra Efficient Solar Power Market
Solar Power Systems
IBC Solar Cells Market
Solar Power Systems
Solar Vegetable Dryer Market
Solar Power Systems
GCC Solar Microinverter Market
Solar Power Systems
Grid-Connected Solar Microinverter Market
Solar Power Systems
Printable Solar Cells Market
Solar Power Systems
Building Integrated Photovoltaics Module Market
Solar Power Systems
Non-Concentrating Solar Collector Market
Solar Power Systems
On-Grid Solar Inverter Market
Solar Power Systems
Off-Grid Solar Generator Market
Solar Power Systems
Solar Interconnect Ribbon Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
India Solar Inverter Market
Solar Power Systems
Tubular Solar Collector Market