
 Solar Fuel Market | 2026-2036
Solar Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Fuel Market Analytics
Project finance structures with long-term power purchase agreements are reshaping competitive entry in solar fuel production. ACWA Power leverages integrated development models that pair gigawatt-scale solar parks with electrolyzer assets in desert climates. NextEra Energy sustains capital discipline through regulated utility returns while expanding into green hydrogen pilot projects. LONGi Green Energy Technology anchors its position through in-house wafer-to-module manufacturing that feeds directly into solar-to-hydrogen system integration.
Solar fuel denotes energy carriers synthesized using solar-derived electricity or thermal energy to drive water splitting, carbon dioxide reduction, or biomass conversion processes, typically yielding hydrogen with purity exceeding 99.9 percent or liquid fuels with energy densities comparable to conventional gasoline. Its primary purpose is to decarbonize sectors where direct electrification proves technically prohibitive, including long-haul aviation, maritime shipping, and high-temperature industrial heat. Photovoltaics dominates installed capacity for electrolytic hydrogen production due to precipitous module cost declines, while concentrated solar power retains structural importance in regions with exceptional direct normal irradiance where thermal storage enables round-the-clock fuel synthesis. Hydrogen captures the deepest margin pools among product types as offtake premiums for certified green molecules widen across European and Asian industrial clusters.
The EU Green Deal and its delegated acts on renewable fuels of non-biological origin are tightening product certification requirements and reshaping import eligibility for solar-derived hydrogen into European ports. Japan's METI hydrogen strategy and Australia's renewable energy export frameworks are creating bilateral standards alignment that facilitates cross-border offtake contracting. The US IRA production tax credits for clean hydrogen are altering project economics across Texas and California solar corridors. Stakeholders must monitor how carbon border adjustment mechanisms and evolving lifecycle accounting rules determine which solar fuel pathways secure premium market access.
Market Dynamics
Carbon border adjustment mechanisms are compressing import eligibility for solar-derived hydrogen into European ports, forcing project developers to reconfigure supply chains around certified lifecycle accounting. This regulatory tightening is virtualizing competitive entry requirements across electrolyzer deployment corridors.
Growth Catalysts
- EU Green Deal delegated acts:Renewable fuels of non-biological origin certification is tightening product standards for transport fuels, pulling industrial offtake toward electrolytic hydrogen pathways.
- Japan-Australia bilateral frameworks:METI hydrogen strategy alignment with Australian renewable energy export frameworks is accelerating cross-border offtake contracting for Pilbara export hubs.
- Concentrated solar power thermal storage:Exceptional direct normal irradiance regions are enabling round-the-clock fuel synthesis, opening margin pools unavailable to intermittent photovoltaic-electrolyzer configurations.
Market Restraints
- Electrolyzer supply concentration:Stack manufacturing capacity clusters in European and Chinese industrial zones, exposing project timelines to single-source procurement risk.
- Grid interconnection queues:Utility-scale solar park permitting delays in Texas and California corridors are stretching project development cycles beyond investor return thresholds.
- Natural hydrogen geological discoveries:Subsurface hydrogen extraction in Mali and France is emerging as a lower-capex substitute for synthetic solar fuel in select industrial applications.
Strategic Opportunities
- US IRA production tax credits:Clean hydrogen incentives are restructuring project economics across southwestern solar corridors, attracting capital toward integrated development models.
- Maritime fuel bunkering:Singapore and Rotterdam port authorities are mandating low-carbon marine fuel standards, creating first-mover slots for solar-derived ammonia and methanol.
- Photovoltaic-electrolyzer system integration:Direct coupling architectures are eliminating power conversion losses, compressing levelized hydrogen costs in high-irradiance desert climates.
Industry Challenges
- Electrolyzer stack degradation modeling:Thin-film catalyst stability under variable renewable input remains poorly characterized, forcing conservative warranty terms that inflate project financing costs.
- Green hydrogen certification lag:Lifecycle accounting methodologies lack harmonization between EU delegated acts and Japanese METI standards, creating compliance duplication for export-oriented projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Fuel Market |
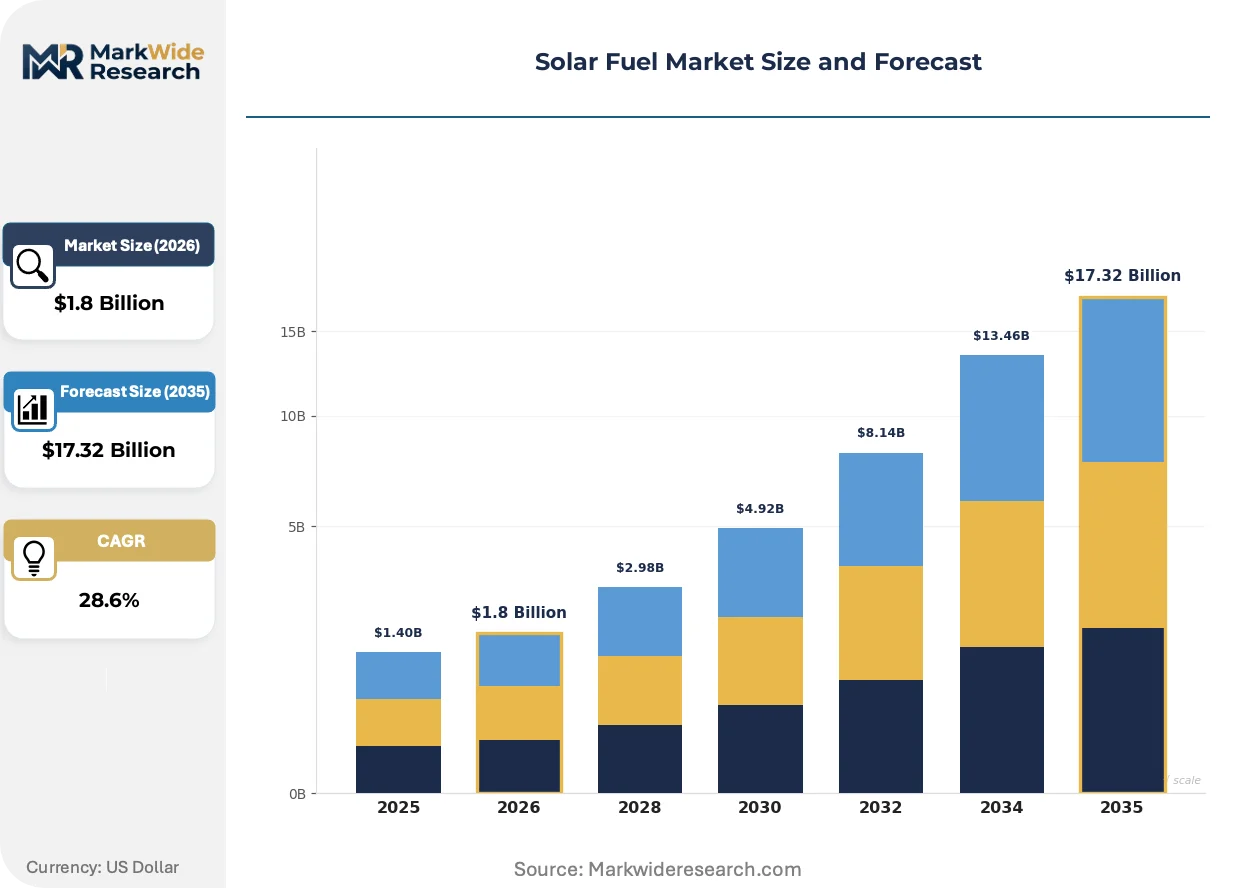
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photovoltaics, Concentrated Solar Power, Solar Thermal, Biofuels Product Type: Hydrogen, Ethanol, Methanol, Biogas End User: Automotive, Residential, Commercial, Industrial Application: Electricity Generation, Heating, Transportation, Energy Storage |
| Companies Covered | NextEra Energy, LONGi Green Energy Technology, JinkoSolar Holding, Sungrow Power Supply, First Solar, Canadian Solar, ACWA Power, Trina Solar, JA Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Fuel Market Evolving Landscape
Technology convergence between photovoltaic architectures and electrolyzer stack designs is compressing system integration costs. Regulatory frameworks are hardening around carbon intensity thresholds. Buyer procurement patterns are rotating toward long-term offtake structures that transfer volume risk to producers.
Solid oxide electrolysis is virtualizing efficiency benchmarks for high-temperature fuel synthesis. Industrial clusters in Germany's Ruhr region and Japan's Keihin corridor are piloting pressurized steam electrolysis for steel decarbonization. This thermal integration pathway is compressing electricity requirements per kilogram of hydrogen output, enabling cost parity with steam methane reforming in carbon-priced jurisdictions.
EU delegated acts on renewable fuels of non-biological origin are tightening lifecycle carbon intensity thresholds for import eligibility. The delegated act methodology excludes grid-connected electrolysis unless hourly matching with renewable generation is demonstrated. Project developers in Spain's Extremadura region and Morocco's Ouarzazate corridor are reconfiguring toward behind-the-meter solar architectures to secure certification compliance.
Long-term offtake contracting is displacing merchant market exposure for solar fuel producers. Japanese trading houses and Korean steel conglomerates are securing fifteen-year hydrogen supply agreements with Australian export hub developers. This procurement rotation is compressing developer equity requirements while transferring volume and price risk to balance sheet-backed buyers, most visible in the Pilbara-Korea shipping corridor.
Solar Fuel Market Segmentation
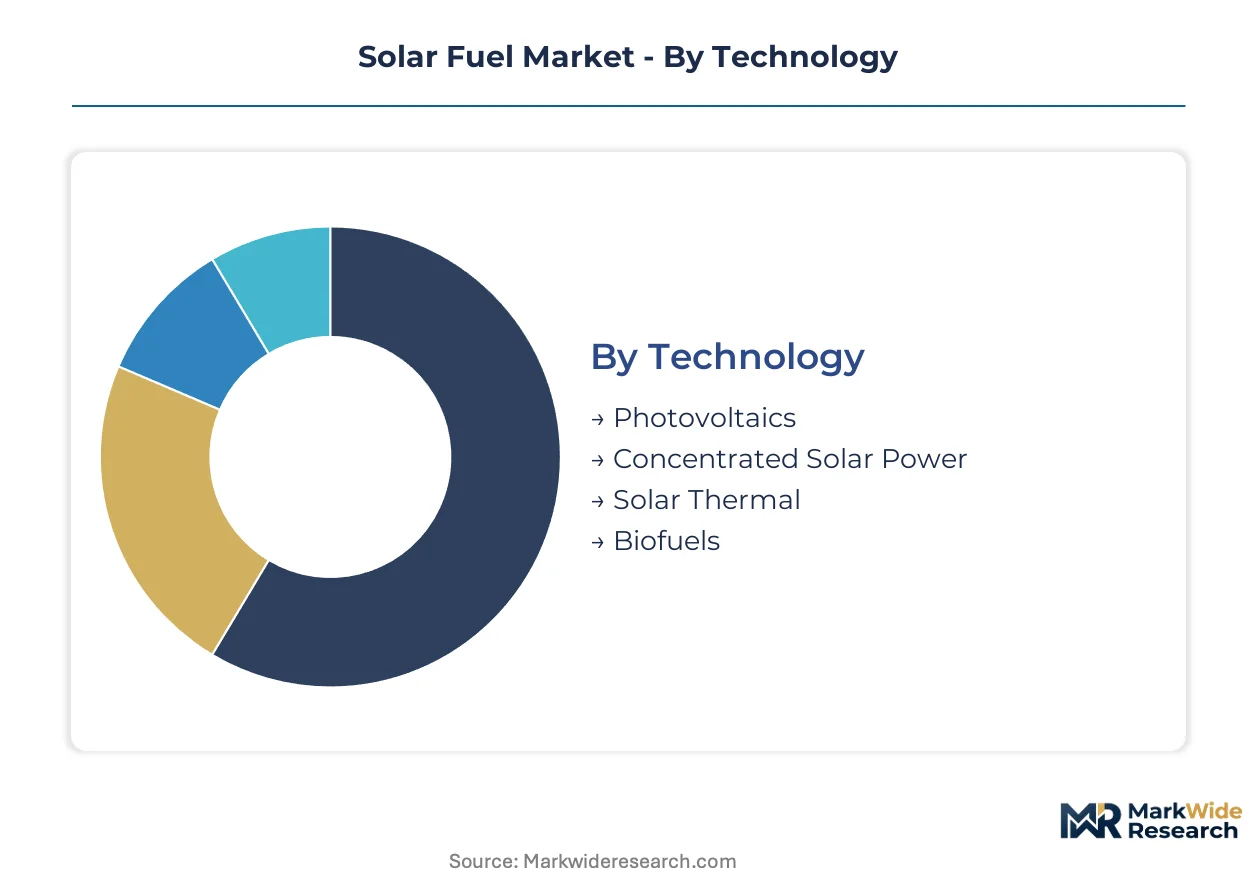
Technology pathways and product chemistry determine project economics and offtake eligibility in solar fuel production. Segmentation reveals where capital is concentrating and which configurations capture premium pricing under tightening certification standards.
Technology:
Photovoltaic architectures dominate electrolytic hydrogen deployment due to precipitous module cost compression and modular scalability across irradiance gradients.
- Photovoltaics:Silicon and thin-film modules convert sunlight to electricity for alkaline and PEM electrolyzer stacks. Demand clusters in Australia's Pilbara and Saudi Arabia's NEOM where gigawatt-scale parks pair directly with hydrogen export infrastructure.
- Concentrated Solar Power:Parabolic trough and power tower systems with molten salt storage enable round-the-clock thermal fuel synthesis. Spain's Extremadura and Morocco's Ouarzazate corridors exploit exceptional direct normal irradiance for continuous operation unavailable to intermittent PV configurations.
- Solar Thermal:Low-temperature collectors drive thermochemical water splitting and biomass drying processes. Industrial heat applications in Germany's chemical corridor leverage evacuated tube arrays for process steam integration.
- Biofuels:Algae cultivation and agricultural residue conversion using solar-thermal processing yields liquid transport fuels. California's Central Valley hosts pilot facilities targeting aviation sector offtake specifications.
The dominant share belongs to Photovoltaics, while Concentrated Solar Power is closing the gap fastest through thermal storage integration.
Product Type:
Carbon intensity thresholds and energy density requirements pull production toward molecules with established transport infrastructure and certification methodologies.
- Hydrogen:Electrolytic production yields purity exceeding 99.9 percent for ammonia synthesis, steel reduction, and fuel cell mobility. Japan's METI procurement standards and EU delegated acts on renewable fuels of non-biological origin are tightening lifecycle accounting requirements for import eligibility.
- Methanol:Solar-derived syngas conversion produces liquid fuel compatible with existing chemical shipping and marine bunkering infrastructure. Singapore port authority mandates are accelerating offtake contracting for low-carbon methanol in container shipping corridors.
- Ethanol:Cellulosic fermentation using solar-thermal pretreatment serves blending mandates in transport fuel markets. Brazilian ANVISA certification alignment with EU sustainability criteria is opening export pathways for certified production.
- Biogas:Anaerobic digestion of organic feedstocks upgraded to biomethane feeds industrial heat and grid injection applications. Germany's KBA vehicle certification framework recognizes biomethane for compressed natural gas mobility.
Hydrogen commands the deepest margin pools, while Methanol is expanding most quickly through maritime fuel substitution.
End User:
Carbon border exposure and electrification constraints determine which sectors absorb solar fuel premiums at scale.
- Industrial:Steel, ammonia, and refining operations purchase electrolytic hydrogen to satisfy EU carbon border adjustment mechanism liabilities. German Ruhr region clusters and Korea's POSCO facilities are securing fifteen-year supply agreements with Australian export hub developers.
- Transportation:Aviation and maritime sectors lacking direct electrification pathways drive demand for solar-derived synthetic fuels. Rotterdam port authority low-carbon marine fuel standards are mandating ammonia and methanol bunkering infrastructure.
- Automotive:Fuel cell electric vehicle fleets in Japan and Korea consume compressed hydrogen through METI-subsidized refueling networks. California's LCFS credit market supports retail hydrogen pricing parity with gasoline.
- Residential:Micro-cogeneration and heating applications utilize solar-derived biomethane injection into distribution grids. Netherlands grid operators are piloting renewable gas certificates for household thermal decarbonization.
Industrial offtake holds the largest contract volumes, while Transportation is climbing the fastest through International Maritime Organization compliance deadlines.
Application:
Dispatch requirements and storage duration specifications segment solar fuel deployment across electricity system services.
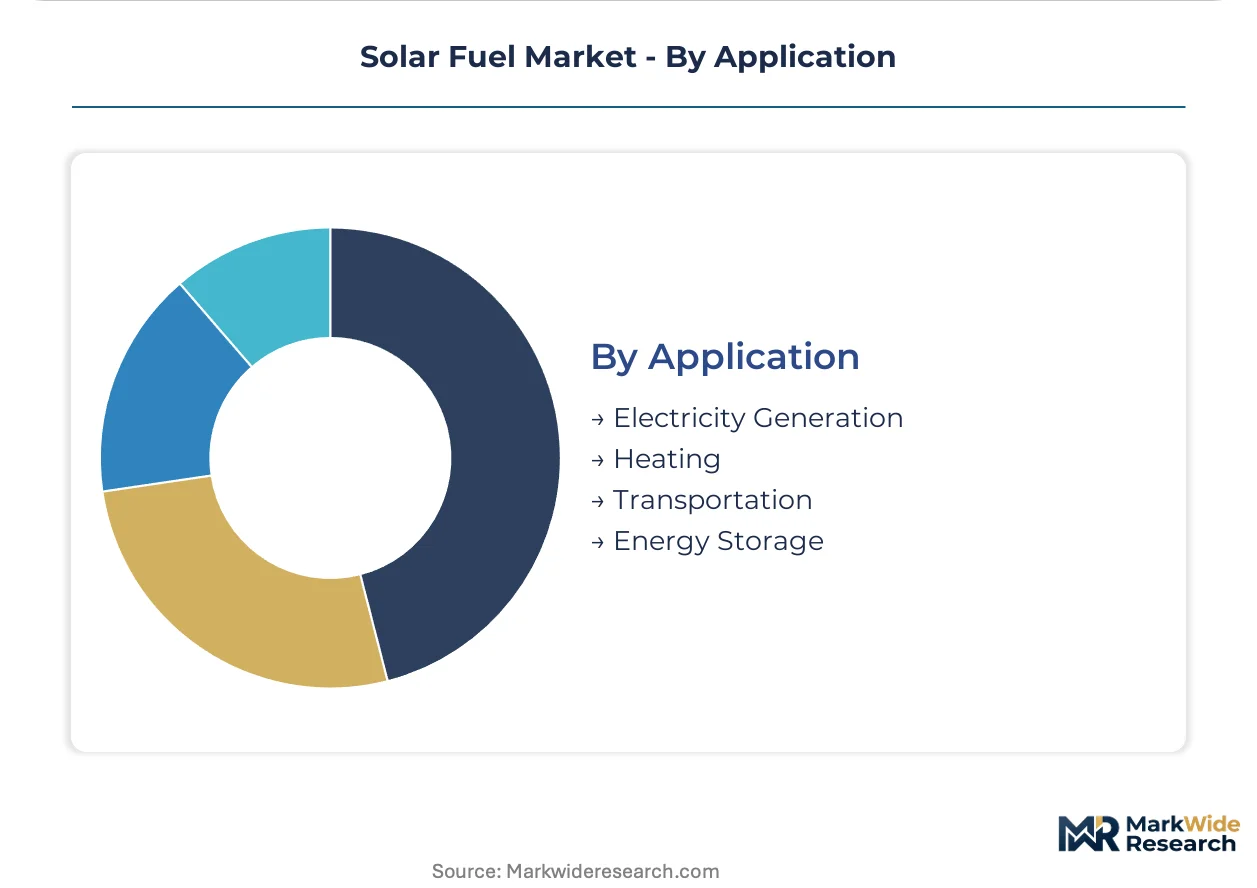
- Transportation:Long-haul aviation and maritime shipping require liquid and gaseous fuels with energy densities exceeding battery storage limitations. Asian trading houses are contracting Pilbara hydrogen for conversion to ammonia marine fuel.
- Energy Storage:Power-to-gas and power-to-liquid systems convert surplus solar generation into storable molecules for seasonal discharge. Texas ERCOT market participants are evaluating green hydrogen salt cavern storage for renewable curtailment arbitrage.
- Heating:Industrial process heat and district heating networks substitute solar-derived biomethane and hydrogen for natural gas. Denmark's district heating cooperatives are blending renewable hydrogen into existing pipeline infrastructure.
- Electricity Generation:Fuel cells and gas turbines reconvert stored hydrogen to grid power during renewable drought periods. Japan's METI hydrogen power generation roadmap targets gas turbine co-firing commercialization.
Transportation applications absorb the highest absolute volumes, while Energy Storage is gaining share fastest through power system flexibility contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pilbara export hubs command premium pricing leverage against European industrial buyers, while Texas solar corridors undercut on production economics but face interconnection bottlenecks.
Australia
Iron ore miners and Asian trading houses anchor hydrogen offtake demand across the Pilbara region. The country's renewable energy export frameworks align with Japan's METI hydrogen strategy for bilateral certification. Port Hedland and Karratha clusters are securing fifteen-year supply agreements with Korean steel conglomerates.
Germany
Ruhr industrial clusters purchase electrolytic hydrogen to satisfy EU carbon border adjustment mechanism liabilities. The EU Green Deal delegated acts on renewable fuels of non-biological origin tighten import eligibility standards. Extremadura-linked project developers are reconfiguring toward behind-the-meter solar architectures to secure certification compliance.
United States
ERCOT market participants evaluate green hydrogen salt cavern storage for renewable curtailment arbitrage. The IRA production tax credits for clean hydrogen restructure project economics across southwestern solar corridors. Texas and California developers face utility-scale solar park permitting delays stretching project timelines.
Japan
Fuel cell electric vehicle fleets consume compressed hydrogen through METI-subsidized refueling networks. The country's hydrogen strategy alignment with Australian export frameworks accelerates cross-border offtake contracting. Keihin corridor steelmakers pilot pressurized steam electrolysis for decarbonization.
Saudi Arabia
NEOM gigawatt-scale solar parks pair directly with hydrogen export infrastructure under integrated development models. ACWA Power leverages desert climate advantages for direct coupling architectures that eliminate power conversion losses. The kingdom's positioning targets Asian buyer procurement rotations toward long-term offtake structures.
Solar Fuel Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream capturing margin from electrolyzer stack and module supply. Market structure concentrates around vertically integrated developers pairing generation assets with fuel synthesis infrastructure. Three archetypes dominate: utility-backed project developers, solar manufacturers extending into hydrogen integration, and independent power producers diversifying from conventional generation. Competitive moves center on securing long-term power purchase agreements and locking electrolyzer manufacturing capacity through strategic offtake arrangements.
Among utility-backed developers, NextEra Energy exemplifies the regulated-utility-return model expanding into green hydrogen pilot projects. Chinese solar manufacturers occupy the integration tier, with LONGi Green Energy Technology anchoring in-house wafer-to-module manufacturing that feeds solar-to-hydrogen system deployment. Saudi Arabia-based ACWA Power represents the desert-climate platform integrator pairing gigawatt-scale solar parks with electrolyzer assets.
| Leading Market Players |
|---|
| NextEra Energy |
| LONGi Green Energy Technology |
| JinkoSolar Holding |
| Sungrow Power Supply |
| First Solar |
| Canadian Solar |
| ACWA Power |
| Trina Solar |
| JA Solar |
| Others |
Value Network & Pricing Analysis
Electrolyzer stack manufacturing concentrates in Germany and China, anchoring margin capture upstream while project developers downstream absorb financing cost inflation from extended equipment procurement timelines. This geographic clustering of proton-exchange membrane and alkaline stack production shapes where pricing power accumulates across solar-to-hydrogen value chains.
Pricing Analysis
Configured-to-order electrolyzer systems command premiums exceeding standard modular configurations by capturing certification-grade hydrogen output and integrated thermal management. Project-based long-term offtake contracting dominates, with price differentiation driven by carbon-intensity certification tier and volume scale commitment. Pricing pressure stems from Chinese stack manufacturers compressing alkaline system costs through scaled wafer processing. Industrial offtakers in steel and ammonia exhibit lowest price sensitivity due to carbon border exposure, while merchant hydrogen traders face acute margin compression.
Supply Chain Analysis
Extended payment terms from Korean trading houses and supply-chain finance facilities arranged through Singaporean port authorities are restructuring working capital requirements for Pilbara export hub developers. Manufacturing draws from Germany for precision stack components, China for silicon wafer and membrane production, and Japan for catalyst coatings. Iridium and platinum group metal dependencies create single-source vulnerability from South African mining concentration. Distribution runs through integrated development models pairing ACWA Power-style gigawatt parks with captive electrolyzer assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar fuel penetration sits at early-cycle expansion, justified by EU carbon border adjustment mechanisms activating compliance-driven industrial procurement across German Ruhr and Korean steel corridors.
For Market Incumbents: Harden electrolyzer manufacturing capacity reservations through multi-year stack procurement agreements before Chinese alkaline producers consolidate pricing control. Defend margin position by accelerating behind-the-meter solar architectures that satisfy EU delegated act hourly matching requirements, neutralizing grid-connected certification risk. For New Entrants and Emerging Players: Build out direct-coupling photovoltaic-electrolyzer system integration capabilities targeting Texas ERCOT curtailment arbitrage and Australian Pilbara export hub EPC contracts. Maritime fuel bunkering in Singapore and Rotterdam offers the most penetrable near-term segment through port authority low-carbon mandates. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed project developers holding Australian renewable energy export framework approvals but lacking electrolyzer integration execution capability. Five-to-ten year viability hinges on certification methodology harmonization between EU delegated acts and Japanese METI standards. Watch for bilateral Australia-Japan contracting velocity as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer Manufacturing Scale-Up | Chinese alkaline stack producers compress costs through wafer processing automation, reshaping project economics. |
| Long-term Hydrogen Supply Agreement | Fifteen-year offtake contracts with Korean POSCO transfer volume risk to balance sheet-backed industrial buyers. |
| Behind-the-Meter Solar Architecture | Spain's Extremadura developers reconfigure projects to satisfy EU delegated act hourly matching certification. |
| Maritime Fuel Bunkering Partnership | Rotterdam port authority mandates create first-mover slots for solar-derived ammonia in container shipping. |
| Green Certification Program | EU renewable fuels of non-biological origin delegated acts tighten lifecycle carbon intensity import thresholds. |
Research Methodology
Desk research of IEA hydrogen project databases, EIA solar generation statistics, and EU delegated act regulatory filings preceded structured interviews with electrolyzer stack manufacturers, utility planning officers at NextEra Energy and ACWA Power, EPC contractors in Australian Pilbara corridors, and fuel supply specialists at Japanese trading houses. Bottom-up project economics modeling triangulated against top-down market sizing from trade flow analysis.
Assumptions held electrolyzer capital cost decline trajectories and carbon border adjustment mechanism coverage fixed while varying renewable energy export framework adoption rates and bilateral certification alignment timelines. Segmentation dimensions modeled include technology pathway, product chemistry, end-use sector, and regional regulatory cluster. CAGRs derived from project pipeline aggregation and offtake contract velocity analysis, with inputs from salt cavern storage economics and maritime fuel substitution elasticities.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed alkaline stack producers or accelerated EU carbon border phase-in would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Hairy Solar Panels Market
Solar Power Systems
Rooftop Solar Photovoltaic (PV) Installation Market
Solar Power Systems
Solar Bench Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Skylights Market
Solar Power Systems
Asia-Pacific Solar Concentrator Market
Solar Power Systems
United States Solar Microinverter Market
Solar Power Systems
Solar Laminator Market
Solar Power Systems
Solar Interconnect Ribbon Market
Solar Power Systems
Off-Grid Solar Lighting Market
Solar Power Systems
Malaysia Solar Energy Market
Solar Power Systems
Flat Plate Solar Collector Market
Solar Power Systems
Portugal Distributed Solar Energy Market
Solar Power Systems
Solar Updraft Tower Market
Solar Power Systems
Solar Rack Market
Solar Power Systems
Israel Solar Energy Market
Solar Power Systems
Biohybrid Solar Cell Market