
 Solar Sunlight Control System Market | 2026-2036
Solar Sunlight Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Sunlight Control System Market Intelligence
China is rewriting supply dynamics for electrochromic film and motorized drive components as domestic manufacturers expand wafer-coating capacity for smart glass substrates. Hunter Douglas leverages vertical integration across fabric sourcing and automated assembly to sustain margin control in premium motorized shades. Lutron Electronics anchors North American commercial specification through deep channel relationships with lighting designers and building automation integrators. WAREMA competes in European facade systems with specialized engineering for climate-responsive exterior shading.
A solar sunlight control system integrates electrochromic, thermochromic, or photochromic materials with mechanical or automated actuation to modulate solar heat gain and visible light transmission through building envelopes. These systems typically operate within 3-5 volt DC circuits, switching between transparent and opaque states in 2-10 minutes depending on film chemistry and panel size, primarily serving to reduce HVAC loads and enhance occupant comfort. Motorized shades and smart glass command the deepest margin pools as building owners prioritize automated daylight harvesting over manual blind retrofits. The commercial end-user segment leads volume absorption, while institutional installations in healthcare and education settings represent the fastest-growing demand category due to stringent indoor environmental quality mandates.
The EU Green Deal and F-Gas Regulation restrict fluorinated gas use in insulating glass manufacturing, forcing suppliers to reformulate gas fills and coating chemistries. The U.S. Department of Energy and California Energy Commission enforce Title 24 performance thresholds that effectively mandate dynamic glazing or advanced exterior shading in new commercial construction above four stories. Stakeholders must monitor how rapidly evolving IECC model codes migrate into state-level amendments, as this trajectory determines whether electrochromic retrofits or prefabricated shading modules capture the larger share of replacement-cycle spending.
Market Dynamics
Building energy codes across North America and Europe are compressing design timelines for facade systems, forcing developers to specify dynamic glazing and automated shading before architectural finalization rather than as value-engineering alternatives.
Growth Catalysts
- Title 24 mandates:California's energy code requires automated daylight harvesting in commercial buildings above four stories, creating specification pull for motorized shades and electrochromic glass.
- Healthcare IEQ standards:Patient recovery protocols in hospital construction now mandate precise circadian lighting control, accelerating institutional adoption of tunable glazing systems.
- Tungsten oxide deposition:Advances in sputtering chemistry for electrochromic films have reduced switching latency from minutes to under 90 seconds, expanding addressable applications.
Market Restraints
- Indium tin oxide volatility:Transparent conductor pricing swings of 40% annually compress margins for smart glass laminators dependent on sputtered coatings.
- F-Gas reformulation costs:EU regulations banning sulfur hexafluoride in insulating glass units force gas fill substitutions that degrade thermal performance unless paired with triple glazing.
- Facade contractor concentration:North American installation capacity clusters among 12 regional glazing subcontractors, creating bottlenecks for complex electrochromic retrofits.
Strategic Opportunities
- Indian commercial construction:Bureau of Energy Efficiency codes for large office buildings lack enforcement infrastructure, creating first-mover advantage for suppliers establishing specification relationships.
- Aviation cabin glazing:Boeing and Airbus retrofit programs are evaluating electrochromic dimming as a weight-saving alternative to mechanical window shades.
- Performance contracting:Energy Service Companies in Germany are bundling dynamic facade upgrades with HVAC retrofits, shifting procurement from capital expenditure to guaranteed savings models.
Industry Challenges
- Building automation integration:BACnet and KNX protocol fragmentation forces custom middleware development for each major controls vendor, extending commissioning timelines.
- Facade engineer scarcity:North American universities graduated fewer than 200 specialized building envelope engineers in 2023, constraining project execution capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Sunlight Control System Market |
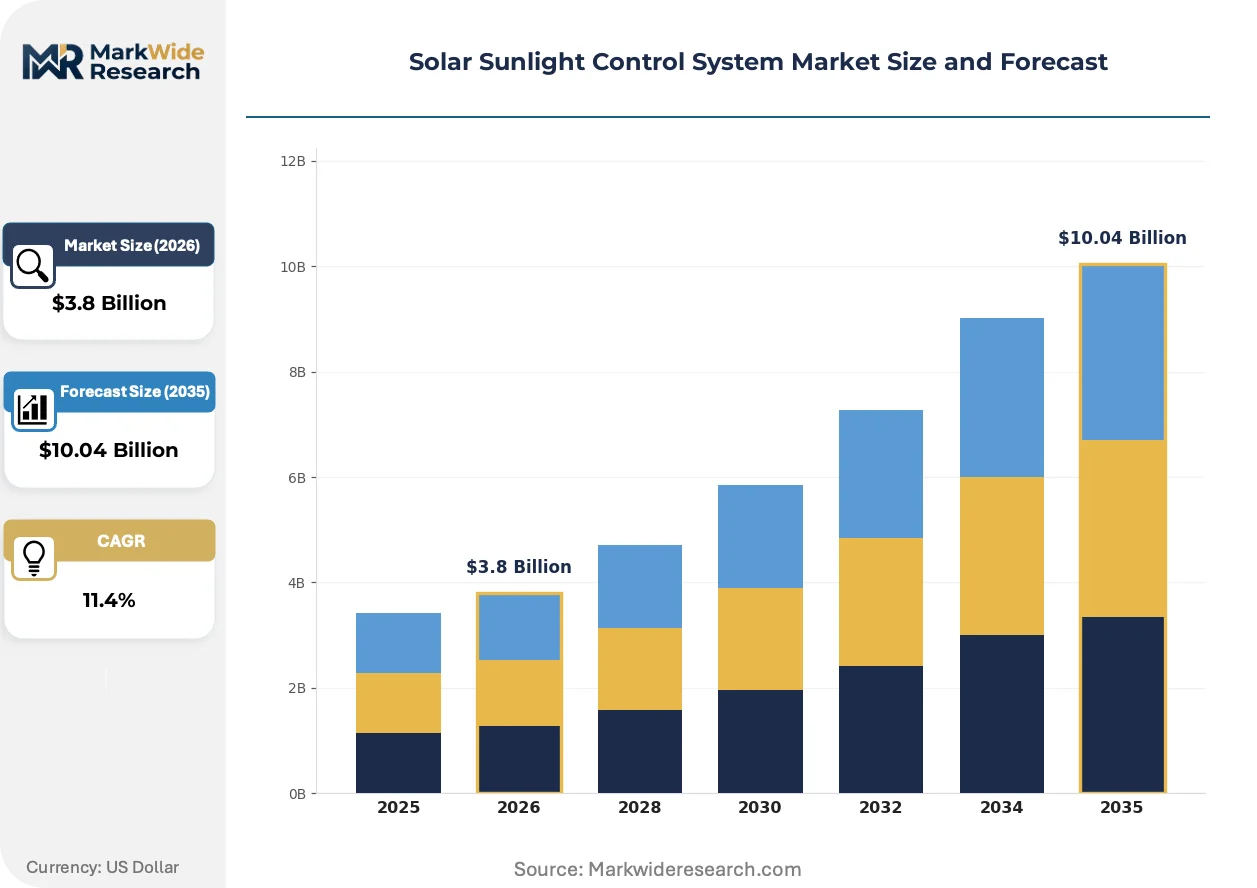
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Blinds, Motorized Shades, Smart Glass, Exterior Awnings Technology: Electrochromic, Thermochromic, Photochromic, Manual End User: Residential, Commercial, Institutional, Industrial Installation Type: New Construction, Retrofits, Custom Installations, Prefabricated |
| Companies Covered | Hunter Douglas, Lutron Electronics, Kawneer Company, WAREMA, Somfy Systems, Skyco Shading Systems, Draper, EFCO Corporation, QMotion Advanced Shading Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Sunlight Control System Market Strategic Shifts & Innovations
Computational facade design tools are collapsing the traditional sequence where architects specify static systems and engineers retrofit performance, enabling real-time solar optimization from schematic design through occupancy.
Electrochromic thin-film deposition is virtualizing the physical switching layer that once required liquid crystal or suspended particle assemblies. Healthcare and laboratory developers in Germany and Switzerland are specifying these solid-state systems for contamination-sensitive environments where mechanical failure modes pose operational risk. The technology is virtualizing maintenance schedules and compressing total cost of ownership calculations that previously favored conventional blinds.
EU F-Gas Regulation amendments will prohibit hydrofluorocarbon use in insulating glass manufacturing by 2026, forcing suppliers to certify krypton and xenon fill alternatives under revised CE marking protocols. German facade engineers report 18-month lead times for validated gas barrier coatings that maintain thermal performance without fluorinated components. Commercial retrofit projects in France and the Netherlands are accelerating procurement to lock in grandfathered material certifications.
Building owners now require lifecycle performance guarantees rather than equipment warranties, shifting risk to manufacturers and integrators. Real estate investment trusts in California and New York are inserting liquidated damages clauses for daylight autonomy failures, displacing traditional specification-based procurement. This contractual evolution is most visible in Class A office developments where LEED Zero and WELL certification requirements create enforceable indoor environmental quality thresholds.
Solar Sunlight Control System Market Segmentation
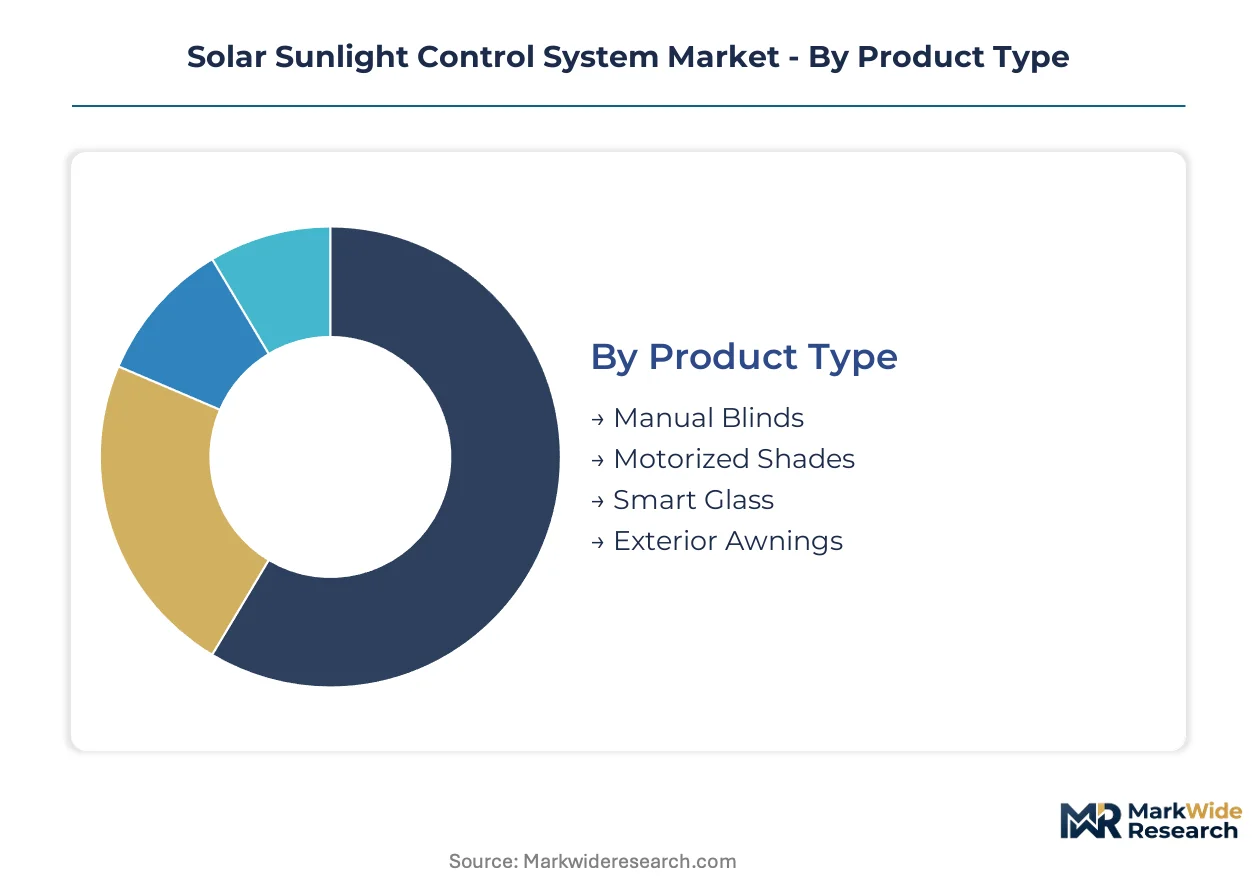
Solar sunlight control systems span four distinct segmentation axes that determine procurement patterns, margin structures, and specification timelines. Product type and technology segmentation reveal the deepest strategic fault lines, as electrochromic glass and motorized shades command premium positioning against manual alternatives while serving fundamentally different construction workflows.
Product Type:
Replacement cycles vary dramatically across this category, with motorized components requiring 10-15 year refresh intervals while manual systems often persist for 25-plus years in commercial installations.
- Manual Blinds:Fabric or slat-based systems dependent on occupant operation for daylight modulation. Demand concentrates in residential retrofits and budget-constrained commercial projects where automated controls cannot be justified.
- Motorized Shades:Tubular motor-driven roller or pleated systems integrated with building automation protocols. Specification pull from California Title 24 compliance mandates drives volume in new commercial construction above four stories.
- Smart Glass:Laminated electrochromic or suspended particle device assemblies that switch optical states through electrical excitation. Healthcare and laboratory developers in Germany and Switzerland specify these for contamination-sensitive environments where mechanical failure modes pose unacceptable operational risk.
- Exterior Awnings:Fixed or retractable fabric or metal projections mounted outside the building envelope. Mediterranean climate zones and heritage building retrofits sustain demand despite longer procurement cycles.
Manual blinds dominate installed base across all geographies. Smart glass is where expansion concentrates as lifecycle performance guarantees displace traditional specification-based procurement.
Technology:
Cost tiers separate solid-state thin-film systems from mechanical alternatives, with electrochromic deposition requiring capital-intensive sputtering equipment that constrains supplier entry.
- Electrochromic:Tungsten oxide thin-film deposition on glass substrates enables voltage-driven switching between transparent and opaque states. Advances in sputtering chemistry have reduced switching latency from minutes to under 90 seconds, expanding addressable applications in aviation and healthcare.
- Thermochromic:Vanadium dioxide coatings that respond passively to temperature thresholds without electrical input. Building envelope engineers specify these for remote installations where power infrastructure is unreliable or maintenance access is restricted.
- Photochromic:Silver halide or organic dye systems that darken under ultraviolet exposure. Eyewear and automotive applications absorb most production volume, leaving limited supply for architectural glazing.
- Manual:No active switching mechanism; reliance on occupant adjustment or fixed geometry. Persistent demand in developing markets and residential replacement cycles sustains manufacturing scale.
Manual technology anchors volume shipments. Electrochromic systems are climbing the fastest as real estate investment trusts insert liquidated damages clauses for daylight autonomy failures.
End User:
Customer type determines specification authority and procurement channel, with institutional buyers demanding extended warranties and performance contracting structures unavailable to residential purchasers.
- Residential:Single-family and multifamily housing where purchasing decisions rest with individual owners or developers. Smart home integration compatibility increasingly filters specification choices.
- Commercial:Office, retail, and hospitality properties where facilities managers or sustainability officers control procurement. Class A office developments in New York and California drive premium segment absorption.
- Institutional:Healthcare, education, and government facilities subject to stringent indoor environmental quality mandates. Patient recovery protocols in hospital construction now mandate precise circadian lighting control.
- Industrial:Manufacturing and warehouse facilities where glare reduction serves safety and productivity objectives rather than aesthetic or comfort goals.
Commercial end users command the deepest margin pools. Institutional installations are gaining share fastest due to healthcare IEQ standards and laboratory contamination control requirements.
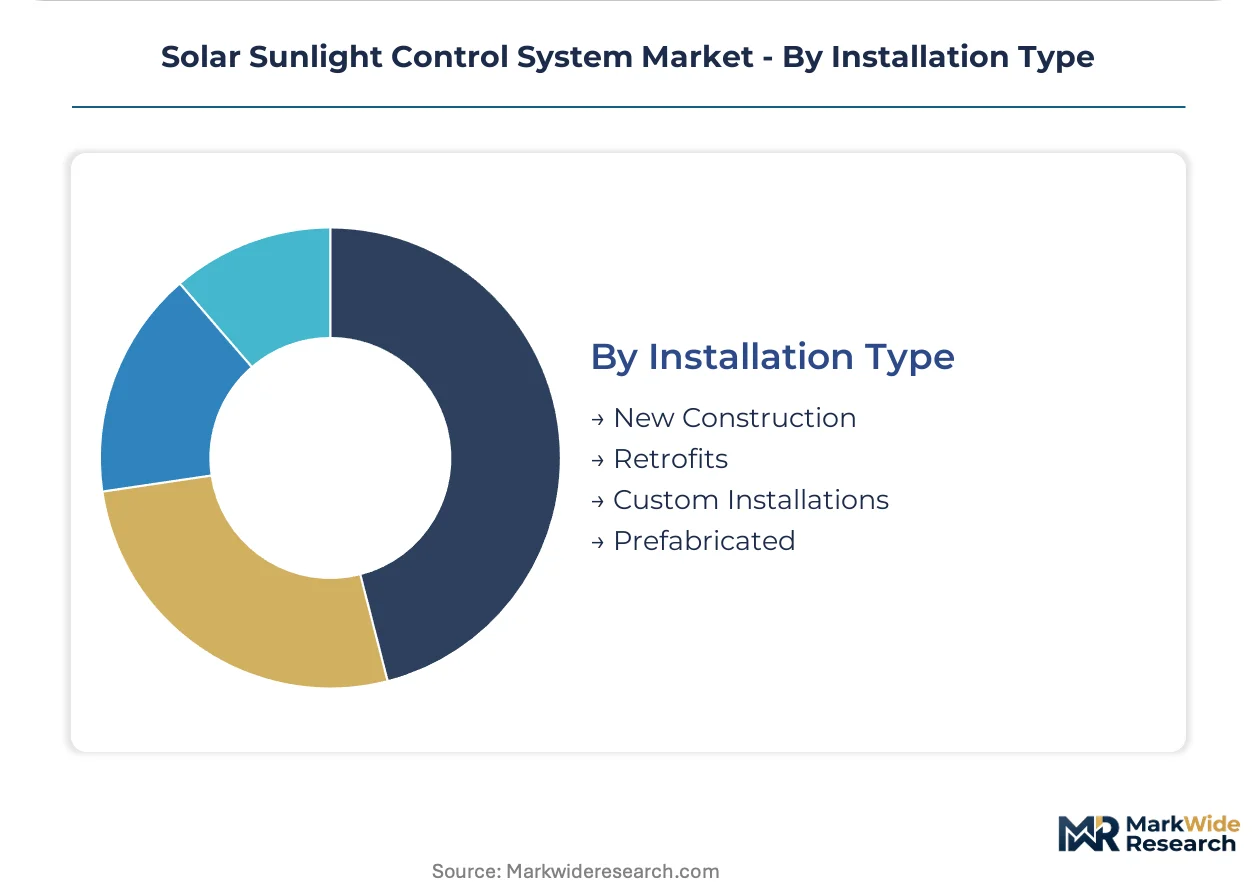
Installation Type:
Supply concentration among regional glazing subcontractors creates execution bottlenecks for complex retrofits, while prefabricated modules compress on-site labor requirements.
- New Construction:Systems specified during architectural design and installed before building occupancy. Facade contractors in North America report 18-month lead times for validated gas barrier coatings required under EU F-Gas Regulation amendments.
- Retrofits:Replacement or upgrade of existing envelope systems in occupied buildings. French and Dutch commercial projects are accelerating procurement to lock in grandfathered material certifications before regulatory deadlines.
- Custom Installations:Bespoke engineering for irregular geometries or heritage building constraints. Limited supplier base and extended design timelines compress margins.
- Prefabricated:Factory-assembled facade modules incorporating integrated shading or switching systems. Offsite construction methods reduce on-site labor and weather dependency.
New construction dominates specification volume. Retrofits are where expansion concentrates as energy service companies in Germany bundle dynamic facade upgrades with HVAC retrofits under guaranteed savings models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wafer-coating capacity for smart glass substrates concentrates in China, while specification authority for commercial projects remains anchored in California and New York regulatory jurisdictions. Motorized shade assembly clusters in the Netherlands and Germany serve European facade retrofit demand.
United States
California Title 24 mandates automated daylight harvesting in commercial buildings above four stories, pulling specification for motorized shades and electrochromic glass. The EPA and Department of Energy enforce building envelope performance thresholds that compress facade design timelines. Los Angeles and San Francisco development pipelines account for concentrated procurement volume as developers lock in grandfathered certifications ahead of code amendments.
Germany
F-Gas Regulation amendments prohibit hydrofluorocarbon use in insulating glass manufacturing by 2026, forcing gas fill substitutions and coating reformulations. The EU Green Deal accelerates material shifts away from high-global-warming-potential components in glazing assemblies. Stuttgart and Munich facade engineering clusters report 18-month lead times for validated gas barrier coatings that maintain thermal performance without fluorinated components.
China
Domestic manufacturers expand sputtering capacity for electrochromic film deposition, rewriting supply dynamics for smart glass substrates. MIIT dual carbon goals pressure industrial glazing suppliers to reduce embodied carbon in manufacturing processes. Yangtze River Delta industrial zones concentrate wafer-coating facilities serving both domestic commercial construction and export markets for aviation cabin glazing.
France
Commercial retrofit projects accelerate procurement to lock in grandfathered material certifications before EU regulatory deadlines. The country's national building energy regulator enforces performance thresholds that mandate dynamic glazing or advanced exterior shading in new construction. Paris and Lyon commercial development pipelines concentrate specification activity as real estate investment trusts insert liquidated damages clauses for daylight autonomy failures.
Netherlands
Energy Service Companies bundle dynamic facade upgrades with HVAC retrofits under guaranteed savings models, shifting procurement from capital expenditure to performance contracting. CE marking protocols for krypton and xenon fill alternatives create compliance bottlenecks for insulating glass suppliers. Randstad metropolitan construction activity drives concentrated demand for prefabricated facade modules incorporating integrated shading systems.
Solar Sunlight Control System Market Key Industry Players
Vertically integrated fabricators and specialized controls integrators split the market between premium specification channels and volume retrofit deployment. The structure favors players with captive supply of core materials—electrochromic films, tubular motors, automation protocols—over pure assembly operations. Three archetypes dominate: window covering manufacturers with backward integration into fabric sourcing, building automation specialists with deep channel relationships, and facade engineering firms with climate-responsive exterior shading expertise. Competitive moves concentrate on vertical integration into film deposition and sputtering capacity, plus strategic partnerships with real estate investment trusts for lifecycle performance contracting.
Among North American specification anchors, Hunter Douglas and Lutron Electronics exemplify divergent integration strategies. Hunter Douglas leverages in-house production of fabric and automated assembly to sustain margin control in premium motorized shades. Lutron Electronics anchors commercial specification through embedded relationships with lighting designers and building automation integrators. European competition centers on WAREMA, which occupies a position in climate-responsive exterior shading systems engineered for facade integration.
| Leading Market Players |
|---|
| Hunter Douglas |
| Lutron Electronics |
| Kawneer Company |
| WAREMA |
| Somfy Systems |
| Skyco Shading Systems |
| Draper |
| EFCO Corporation |
| QMotion Advanced Shading Systems |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta wafer-coating clusters concentrate electrochromic film deposition capacity, granting Chinese substrate suppliers outsized leverage in contract negotiations with European and North American glazing laminators. This geographic concentration compresses margins for downstream integrators while amplifying pricing power for sputtering equipment operators and indium tin oxide feedstock providers.
Pricing Analysis
California Title 24 dictates the pricing tier structure across the solar sunlight control system market, separating premium electrochromic assemblies with automated daylight harvesting compliance from standard motorized shades and economy manual blind alternatives. Price differentiation rests on certification grade—CE-marked krypton-filled units command premiums over grandfathered hydrofluorocarbon systems—and volume scale, with real estate investment trusts extracting bulk discounts through lifecycle performance contracting. Pricing pressure intensifies in the motorized shade segment as fabric sourcing costs fluctuate and European F-Gas reformulation expenses propagate downstream. Commercial developers in New York and California exhibit lowest price sensitivity due to Local Law 97 and Title 24 compliance mandates, while residential retrofits in secondary markets remain highly cost-conscious.
Supply Chain Analysis
Export control regimes restricting advanced sputtering equipment shipments to certain jurisdictions fragment electrochromic film manufacturing capacity between China, Germany, and the United States. Raw material dependencies center on tungsten oxide precursors, indium tin oxide transparent conductors, and specialized gas barrier coatings required under EU F-Gas amendments. Supply chain risk concentrates in single-source vulnerability for validated gas barrier formulations, where German facade engineers report extended procurement timelines for fluorinated-gas-free alternatives. Distribution runs through regional glazing subcontractors in North America and specialized facade engineering clusters in Europe, with prefabricated module channels gaining share in Dutch and French retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar sunlight control system market sits at an inflection point where electrochromic switching latency compression below 90 seconds and EU F-Gas prohibitions on hydrofluorocarbon gas fills are simultaneously reshaping competitive positioning and procurement economics.
For Market Incumbents: Pre-empt margin erosion in motorized shades by securing captive fabric sourcing through backward integration into textile manufacturing or exclusive supply agreements with Yangtze River Delta weavers. Anchor specification relationships with California and New York real estate investment trusts through bundled lifecycle performance guarantees that shift operational risk from building owners to system integrators, neutralizing emerging threats from energy service companies offering guaranteed savings contracting structures. For New Entrants and Emerging Players: Establish a beachhead in Indian commercial construction by cultivating specification relationships with Bureau of Energy Efficiency code consultants before enforcement infrastructure matures. Aviation cabin glazing retrofits for Boeing and Airbus fleets represent a second penetrable white-space, where electrochromic weight savings against mechanical shades justify premium positioning. A go-to-market angle emphasizing solid-state thin-film reliability for contamination-sensitive healthcare and laboratory environments bypasses incumbent channel saturation in conventional commercial construction. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated fabricators with in-house sputtering capacity and established building automation protocol integration capabilities over pure assembly operations. Long-term viability through the next decade hinges on securing gas barrier coating alternatives validated under revised CE marking protocols before EU regulatory deadlines eliminate grandfathered material certifications. The signal to watch is acceleration in prefabricated facade module procurement by Dutch and German energy service companies, indicating whether performance contracting models displace traditional capital expenditure channels.| Strategic Initiative | Industry Significance |
|---|---|
| Sputtering Capacity Expansion | Captive electrochromic film deposition secures margin control against indium tin oxide price volatility. |
| Building Automation Protocol Integration | Embedded BACnet and KNX compatibility reduces commissioning friction with lighting designer specifications. |
| Performance Contracting Partnership | Lifecycle guarantees align procurement incentives with real estate investment trust sustainability mandates. |
| F-Gas Compliant Coating Certification | Validated krypton and xenon barrier formulations unlock EU commercial retrofit procurement before regulatory deadlines. |
| Prefabricated Facade Module Development | Factory-integrated shading systems compress on-site labor requirements and weather dependency for Dutch contractors. |
Research Approach
Cross-validation between primary interviews with facade engineers, building automation integrators, glazing subcontractors, and real estate sustainability officers and secondary validation through California Energy Commission Title 24 filings, EU F-Gas Regulation amendment texts, and Bureau of Energy Efficiency code documentation anchors the qualitative findings. Bottom-up triangulation against customs records for electrochromic film imports and top-down reconciliation with commercial construction permit databases in Los Angeles, San Francisco, New York, Stuttgart, and Paris complete the demand estimation framework.
Calibration against historical adoption curves for dynamic glazing in healthcare and laboratory construction informs the projection methodology across product type, technology, end user, and installation type segmentation dimensions. CAGRs derive from slope-matching to regulatory mandate implementation timelines and energy code amendment cycles rather than extrapolation of recent growth rates. Key inputs include tungsten oxide deposition yield improvements, indium tin oxide price series, and F-Gas compliance cost pass-through elasticities observed in German and French facade engineering markets.
Stress conditions across indium tin oxide price volatility, EU F-Gas enforcement timing, and California Title 24 amendment stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding sputtering chemistry advancement rates and building automation protocol standardization progress. Material shifts in electrochromic switching speed breakthroughs below 60 seconds or unexpected delays in CE marking protocol finalization for gas barrier alternatives would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Europe Solar Microinverter Market
Solar Power Systems
Solar Updraft Tower Market
Solar Power Systems
Indonesia Solar Energy Market
Solar Power Systems
Venezuela Solar Energy Market
Solar Power Systems
US Solar Carport Market
Solar Power Systems
Middle-East Solar Power Market
Solar Power Systems
Residential Solar Energy Market
Solar Power Systems
Residential Solar Shading System Market
Solar Power Systems
Solar Concentrator Market
Solar Power Systems
Solar Microinverter and Power Optimizer Market
Solar Power Systems
United Kingdom Solar Power Market
Solar Power Systems
Global Photovoltaic Glass Market
Solar Power Systems
Solar Grid-Tied Systems Market
Solar Power Systems
Ground Mount PV Utility Market
Solar Power Systems
Colombia Solar Energy Market
Solar Power Systems
Solar Panel Bracket Market