
 Global Airport Solar Power Market | 2026-2036
Global Airport Solar Power Market Size, Share, and Industry Trends Forecast 2026-2036
Global Airport Solar Power Market Analysis
The EU Green Deal is expanding the cost-of-entry calculus for airport energy infrastructure across Europe, forcing operators to embed photovoltaic generation into master planning or face carbon border exposure. JinkoSolar leverages its vertically integrated cell-to-module production to dominate utility-scale airport tenders in Asia and the Middle East. First Solar anchors the thin-film segment with cadmium telluride technology optimized for high-temperature airfield environments where silicon degradation accelerates. LONGi Green Energy Technology specializes in mono-crystalline PERC architectures that maximize output per square meter on congested terminal rooftops.
Airport solar power denotes photovoltaic electricity generation systems sited on airport property, typically comprising monocrystalline or thin-film panels rated between 300W and 700W per module, integrated with string or central inverters and DC-coupled battery storage to buffer ramp-rate constraints during cloud transients. These installations serve dual commercial purposes: reducing scope-two emissions for airport operators and hedging against volatile grid tariffs that distort long-term concession economics. Solar panels and inverters together capture the dominant share of hardware value, though battery storage is widening fastest as regulators tighten resilience requirements for critical infrastructure. Roof-top installations lead deployment volume where land constraints prevent ground-mounted arrays, while hybrid systems that blend grid-tie with islanding capability command premium pricing from operators seeking operational continuity guarantees.
The FAA mandates hazard assessments for glare and radar interference, shaping system design and vendor qualification pathways for US airport projects. EASA coordinates with national aviation regulators under the EU Green Deal framework to standardize permitting for airfield-integrated photovoltaics, while India's CEA enforces grid-code compliance for captive solar at airports under the national renewable purchase obligation. Stakeholders must monitor how evolving electromagnetic compatibility standards and carbon accounting rules reshape equipment selection and financing structures across jurisdictions.
Market Dynamics
Binding decarbonization mandates from the EU Green Deal and India's renewable purchase obligation are forcing airport operators to integrate photovoltaics into capital planning or face stranded asset risk and carbon border exposure.
Growth Catalysts
- EU Green Deal transport infrastructure targets:Binding 2030 emissions reduction requirements for aviation hubs are mandating renewable energy quotas that photovoltaic systems directly satisfy.
- India's airport modernization mandate:The Airports Authority of India enforces captive renewable obligations for major hubs, creating immediate procurement pull for ground-mounted and rooftop arrays.
- Jet fuel price volatility:Scope-two electricity cost hedging through solar generation protects concession economics against grid tariff instability that distorts long-term operator returns.
Market Restraints
- Silicon supply concentration:Polysilicon refining capacity clusters in Xinjiang and Inner Mongolia, exposing project developers to forced labor scrutiny and trade restriction cascades.
- FAA glare assessment mandates:Hazard evaluations for pilot visual interference and radar electromagnetic compatibility extend permitting timelines and disqualify marginal sites.
- Cadmium telluride thin-film scarcity:Tellurium extraction dependence on copper anode slimes limits First Solar's technology diffusion outside pre-qualified high-temperature airfield environments.
Strategic Opportunities
- Battery-buffered ramp-rate systems:DC-coupled storage integration with string inverters addresses cloud transient volatility that degrades grid stability at islanded airport microgrids.
- Ground support electrification:Electric baggage tractors and preconditioned air units create synchronized demand profiles that maximize solar self-consumption ratios.
- EASA standardization harmonization:Coordinated permitting frameworks across Germany, France, and the Netherlands reduce regulatory fragmentation that currently fragments vendor qualification pathways.
Industry Challenges
- Aviation-electrical engineering skill scarcity:Cross-functional expertise spanning FAA hazard assessment, photovoltaic system design, and airfield operations safety remains concentrated among a handful of specialized EPC contractors.
- Legacy SCADA integration complexity:Terminal building management systems require protocol translation layers to ingest solar generation telemetry, inflating commissioning costs and failure modes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Airport Solar Power Market |
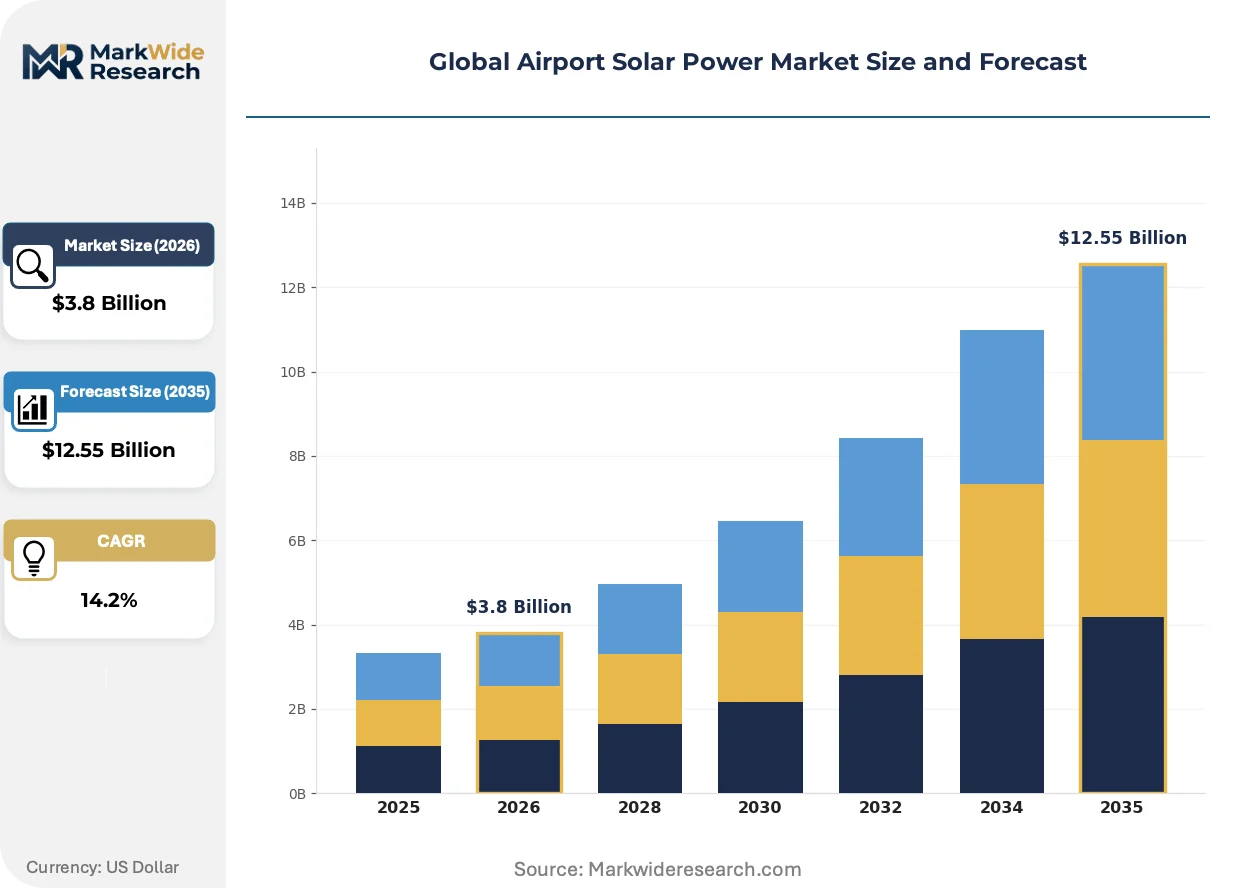
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Panels, Inverters, Battery Storage, Power Management Systems Application: Terminal Buildings, Runway Lighting, Ground Support Equipment, Taxiway Illumination Installation: On-Grid Systems, Off-Grid Systems, Hybrid Systems, Roof-Top Installations End User: Airport Authorities, Airlines, Maintenance Providers, Energy Suppliers |
| Companies Covered | JinkoSolar, Yingli Solar, First Solar, LONGi Green Energy Technology, SMA Solar Technology, Canadian Solar, SunPower Corporation, Envision Solar, Trina Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Airport Solar Power Market Emerging Trajectories
Photovoltaic technology trajectories and procurement model evolution are compressing deployment timelines while expanding the addressable surface area for airport-sited generation beyond conventional rooftop constraints.
Bifacial panel architectures with tracking mounts are decentralizing generation geography across airport properties. Ground handlers and fixed-base operators in the United States and United Arab Emirates are deploying these systems on airfield margins previously excluded from solar consideration. The technology is decentralizing project ownership from centralized utility procurement toward distributed captive power models that terminal concessionaires and cargo handlers operate independently.
The EU Green Deal's CSRD disclosure requirements are mandating granular scope-two emissions reporting that photovoltaic generation certificates must satisfy. Airport operators in Germany and the Netherlands face audit scrutiny that forces module-level monitoring and blockchain-tracked renewable energy attribute verification. European hub operators are responding by specifying IEC 62446-1 compliant testing protocols that disqualify vendors lacking documented electroluminescence inspection capabilities.
Power purchase agreement structures are fragmenting across ownership models that separate hardware capital from energy offtake risk. Indian airport authorities increasingly procure solar-as-a-service through energy service companies that retain asset ownership, displacing traditional EPC-transfer arrangements that burden operator balance sheets. This unbundling concentrates most visibly at Bangalore and Delhi hubs where concession terms prohibit long-term capital commitments.
Global Airport Solar Power Market Segmentation
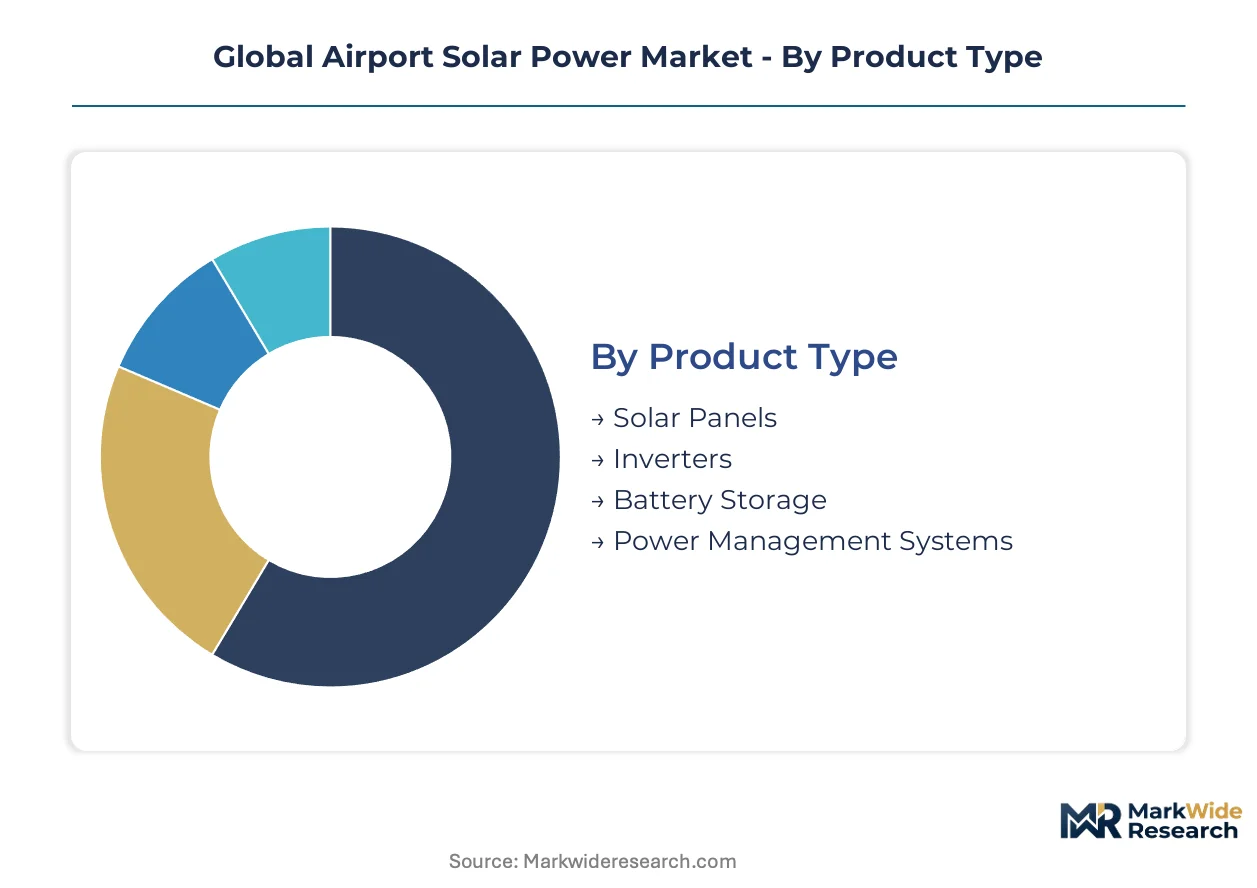
Airport solar procurement patterns diverge sharply across hardware categories, operational applications, and ownership structures. Equipment specifications, installation constraints, and counterparty risk appetites create distinct commercial segments that vendors must navigate separately.
Product Type:
Capital allocation intensity and replacement cycles separate buyers across the hardware stack.
- Solar Panels:Monocrystalline PERC and cadmium telluride thin-film modules rated 300W-700W dominate procurement. Indian airport authorities under CEA renewable purchase obligations favor high-efficiency monocrystalline units for congested terminal rooftops where space constraints bite hardest.
- Inverters:String and central inverter architectures convert DC generation to grid-synchronous AC output. German hub operators specify IEC 62446-1 compliant units with protocol translation capability for legacy SCADA integration, extending vendor qualification timelines.
- Battery Storage:DC-coupled lithium-ion systems buffer ramp-rate volatility during cloud transients.
- Power Management Systems:Integrated control platforms orchestrate generation, storage, and load dispatch.
Solar panels lead volumes today; battery storage is gaining share fastest.
Application:
Regulatory visibility and safety certification requirements determine project economics across use cases.
- Terminal Buildings:Rooftop and facade-integrated photovoltaics serve scope-two emissions reduction mandates. EU Green Deal CSRD disclosure requirements force German and Dutch operators toward module-level monitoring with blockchain-tracked attribute verification.
- Ground Support Equipment:Solar-charged electric baggage tractors and preconditioned air units synchronize demand with generation profiles. Dubai and Abu Dhabi fixed-base operators deploy bifacial tracking arrays to power GSE fleets independently of terminal concessions.
- Runway Lighting:FAA-mandated hazard assessments for glare interference constrain system placement on airfield margins.
- Taxiway Illumination:Electrified guidance systems create distributed low-voltage demand suitable for islanded microgrids.
Terminal buildings anchor procurement today; ground support equipment is expanding most quickly.
Installation:
Grid interconnection architecture and resilience guarantees shape contract structures.
- Roof-Top Installations:Space-constrained arrays on terminal structures maximize output per square meter through high-efficiency monocrystalline panels. India's Airports Authority mandates these for major hubs where land availability prevents ground-mounted deployment.
- Hybrid Systems:Grid-tie configurations with islanding capability command premium pricing from operators seeking operational continuity guarantees during grid outages. EASA-coordinated permitting across Germany, France, and the Netherlands is standardizing qualification pathways for these resilient architectures.
- On-Grid Systems:Standard grid-tie installations without storage buffer export tariffs against volatile electricity markets.
- Off-Grid Systems:Fully autonomous microgrids serve remote airfield facilities without utility interconnection.
Roof-top installations dominate deployment today; hybrid systems show the steepest expansion trajectory.
End User:
Balance sheet capacity and concession term structures fragment procurement authority.
- Airport Authorities:Sovereign and quasi-sovereign entities with long-dated asset ownership horizons deploy capital directly. Indian authorities at Bangalore and Delhi hubs increasingly procure solar-as-a-service through energy service companies to circumvent concession prohibitions on long-term capital commitments.
- Airlines:Carriers with terminal concessions and fixed-base operations seek captive generation to hedge scope-two exposure. US legacy carriers specify FAA-compliant glare assessments as a vendor qualification gate.
- Maintenance Providers:Third-party contractors with short-dated service contracts favor leased equipment without asset ownership.
- Energy Suppliers:Utility and independent power producers develop airport-sited generation under power purchase agreement structures.
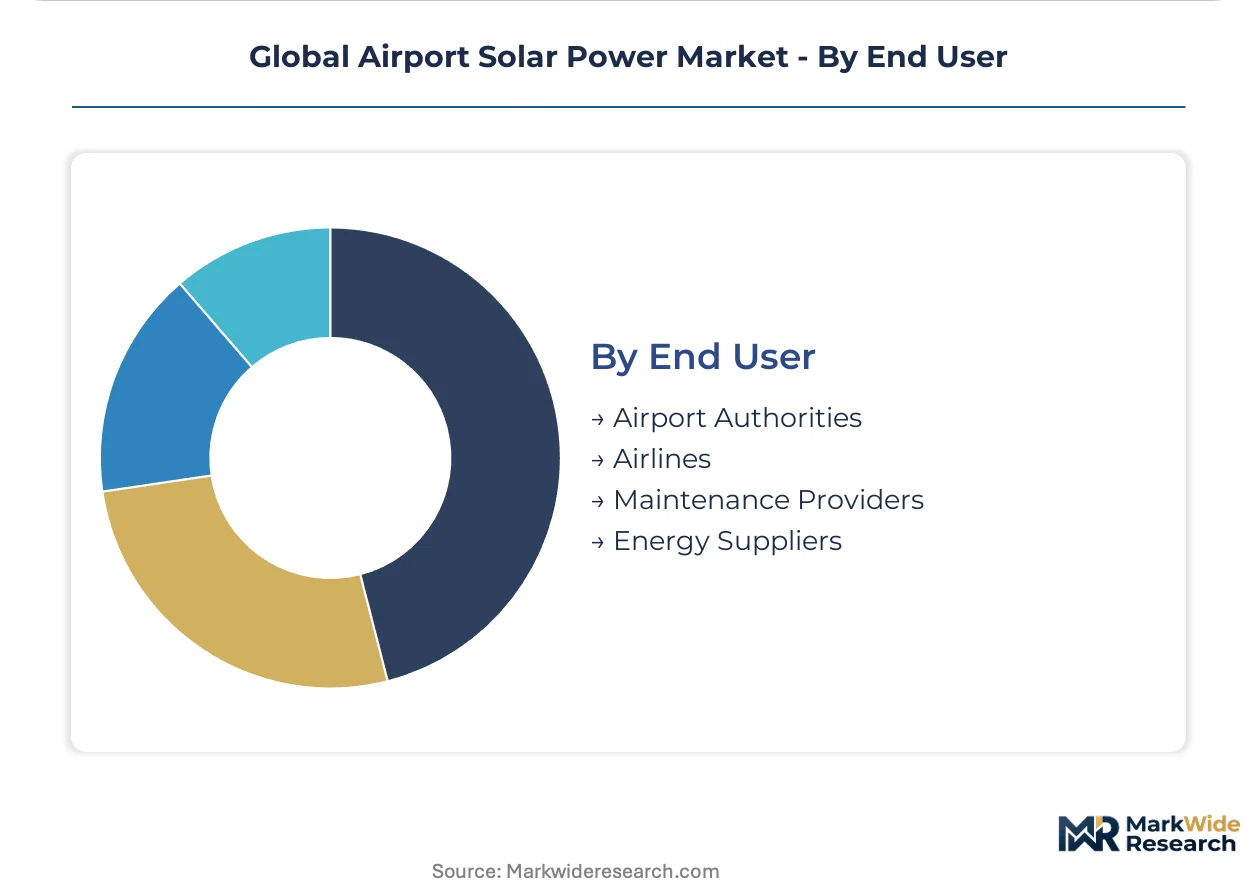
Airport authorities control the largest procurement volumes today; airlines are capturing share fastest through distributed captive models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Germany's industrial belt and India's renewable energy corridor anchor deployment capacity for airport photovoltaic systems. Project developers with cross-functional expertise spanning aviation safety certification and electrical infrastructure design concentrate in these jurisdictions. Procurement authority fragments across sovereign airport authorities, energy service companies, and terminal concessionaires with divergent balance sheet capacities.
United States
Legacy carrier fleet decarbonization commitments drive scope-two hedging demand at Atlanta, Dallas-Fort Worth, and Denver hubs. The FAA mandates hazard assessments for glare interference and radar electromagnetic compatibility, extending permitting timelines and shaping vendor qualification pathways. Ground handlers at Phoenix Sky Harbor deploy bifacial tracking arrays on airfield margins to power electric baggage tractor fleets independently of terminal infrastructure.
Germany
Frankfurt and Munich airport operators face binding EU Green Deal emissions reduction targets that photovoltaic generation directly satisfies. The CSRD mandates granular scope-two emissions reporting with blockchain-tracked renewable energy attribute verification, forcing module-level monitoring specifications. EASA coordination with Germany's national aviation regulator standardizes permitting frameworks for hybrid grid-tie systems with islanding capability.
India
The Airports Authority of India enforces captive renewable purchase obligations for Bangalore, Delhi, and Mumbai hubs where land constraints favor rooftop deployment. The CEA grid-code compliance requirements shape equipment selection for on-site solar integration. Gujarat and Rajasthan-based engineering, procurement, and construction contractors concentrate specialized expertise in aviation-electrical cross-functional system design.
United Arab Emirates
Dubai and Abu Dhabi fixed-base operators seek operational autonomy from grid-dependent terminal concessions through distributed captive generation models. The country's national renewable energy program accelerates procurement timelines for ground-mounted arrays on airfield peripheries. Emirates Group engineering subsidiaries develop in-house photovoltaic integration capabilities for Al Maktoum International expansion phases.
Australia
Remote mining-town airport operators deploy fully autonomous off-grid microgrids where utility interconnection proves economically unviable. The national renewable energy target framework supports capital allocation for resilience-critical infrastructure at Queensland and Western Australia regional hubs. Perth-based specialized contractors concentrate expertise in islanded system design for isolated airfield facilities.
Global Airport Solar Power Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment supply and project development segments. The vendor base stratifies into three tiers: vertically integrated cell-to-module manufacturers with captive polysilicon supply, regional engineering-procurement-construction contractors with aviation certification expertise, and energy service companies offering solar-as-a-service ownership models. Competitive dynamics center on strategic partnerships between module suppliers and specialized airport EPC contractors, plus geographic expansion into jurisdictions with binding renewable purchase obligations.
Within the vertically integrated tier, JinkoSolar and LONGi Green Energy Technology exemplify manufacturers with backward integration into polysilicon refining and wafer production. First Solar occupies a distinct position in the thin-film segment with cadmium telluride technology. These three companies anchor the equipment supply layer that feeds specialized airport project developers across Germany, India, and the United States.
| Leading Market Players |
|---|
| JinkoSolar |
| Yingli Solar |
| First Solar |
| LONGi Green Energy Technology |
| SMA Solar Technology |
| Canadian Solar |
| SunPower Corporation |
| Envision Solar |
| Trina Solar |
| Others |
Supply Flow & Price Mechanics
Backward integration into polysilicon refining and wafer production anchors both supply security and pricing power for airport solar module manufacturers. JinkoSolar and LONGi Green Energy Technology leverage captive upstream capacity to buffer margin erosion from volatile raw material costs, while First Solar's thin-film cadmium telluride technology sidesteps silicon supply chains entirely through specialized tellurium sourcing arrangements.
Pricing Analysis
The bundled-vs-unbundled service split separates capital-intensive EPC-transfer arrangements from solar-as-a-service subscription models. Price differentiation hinges on module efficiency tiers and FAA or EASA certification compliance levels. Cost compression in standard monocrystalline panels is intensifying because Chinese capacity expansions flood procurement tenders. Airport authorities with concession prohibitions on long-term capital commitments exhibit highest price sensitivity, while sovereign operators with direct asset ownership show lowest.
Supply Chain Analysis
Workforce availability constraints in Xinjiang and Inner Mongolia polysilicon refining clusters tether module output to labor scrutiny risks. The supply chain draws from Chinese wafer slicing, Malaysian cell fabrication, and Vietnamese module assembly. Tellurium extraction dependence on copper anode slimes creates single-source vulnerability for thin-film technology. Distribution runs through specialized EPC contractors with aviation-electrical cross-functional certification rather than commodity hardware channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Airport Solar Power Market functions as a stable compounder, with binding decarbonization mandates from the EU Green Deal and India's renewable purchase obligation ensuring steady procurement pull regardless of cyclical aviation traffic fluctuations.
For Market Incumbents: To counter forced labor scrutiny disrupting Xinjiang polysilicon supply, JinkoSolar and LONGi should accelerate Southeast Asian wafer capacity expansion. EASA standardization harmonization across Germany, France, and the Netherlands offers a certification lever to lock in preferred vendor status before competitors qualify. For New Entrants and Emerging Players: Direct-to-airport-authority digital procurement platforms bypass incumbent EPC relationships that dominate traditional tender channels. White-space concentrates in battery-buffered ramp-rate systems for islanded microgrids and ground support equipment electrification at Dubai and Abu Dhabi fixed-base operations. A solar-as-a-service ownership model with energy service company structuring penetrates Indian airport authorities fastest. For Investors and Strategic Acquirers: Roll-up economics work for specialized aviation-electrical EPC contractors because cross-functional expertise scarcity concentrates among a handful of qualified firms. Five-to-ten year viability rests on regulatory tightening accelerating rather than plateauing. Watch EASA electromagnetic compatibility standard evolution as the inflection signal for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Captive Xinjiang and Inner Mongolia refining capacity insulates JinkoSolar and LONGi from trade restriction cascades. |
| Aviation-Electrical Certification Investment | FAA glare assessment and EASA electromagnetic compatibility expertise concentrates project developer market share. |
| Battery-Buffered Ramp-Rate Deployment | DC-coupled lithium-ion integration addresses cloud transient volatility that degrades grid stability at islanded airport microgrids. |
| Solar-as-a-Service Ownership Model | Energy service company structures circumvent Indian airport authority concession prohibitions on long-term capital commitments. |
| EASA Permitting Harmonization | Coordinated frameworks across Germany, France, and the Netherlands reduce regulatory fragmentation for hybrid system vendors. |
Methodological Framework
Coverage spans Germany, India, the United States, and the United Arab Emirates, with primary inputs from each market cluster. The analysis combines structured interviews with airport authority engineering directors, EPC contractor project managers, module manufacturer sales executives, and aviation regulator compliance officers with secondary validation from IEA renewable energy reports, EIA airport energy consumption databases, FERC interconnection filings, and EU Green Deal implementation tracking documents. Bottom-up project pipeline aggregation triangulates against top-down regulatory mandate quantification.
Rate-of-change decomposition separates hardware cost trajectories from deployment velocity shifts across the projection horizon. The analytical framework models product type segmentation by module technology and inverter architecture, application segmentation by terminal building versus ground support equipment, installation segmentation by rooftop versus hybrid system, and end-user segmentation by airport authority versus airline versus energy supplier. CAGRs derive from equipment replacement cycles, regulatory compliance deadlines, and concession term structures. Forecast inputs incorporate FAA hazard assessment timeline distributions and EASA standardization rollout schedules.
The model assumes a particular technology adoption path; alternative pathways for bifacial tracking mounts or thin-film cadmium telluride diffusion would alter the outlook. Forecasts reflect assumptions regarding EU Green Deal enforcement intensity, Indian renewable purchase obligation adherence rates, and polysilicon supply chain reshoring feasibility. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Europe Solar Photovoltaic (PV) Market
Solar Power Systems
Concentrated Photovoltaic System Market
Solar Power Systems
Solar Photovoltaic Glass Market
Solar Power Systems
Slovakia Renewable Energy Market
Solar Power Systems
Chile Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Updraft Tower Market
Solar Power Systems
Middle-East Solar Power Market
Solar Power Systems
Europe Solar Charging Station Market
Solar Power Systems
India Solar Tracker Market
Solar Power Systems
Europe Bifacial Solar Market
Solar Power Systems
Perovskite Solar Cell Market
Solar Power Systems
Agriculture Solar Water Pumps Market
Solar Power Systems
Belgium Solar Energy Market
Solar Power Systems
Middle East and Africa Solar Photovoltaic (PV) Market
Solar Power Systems
PV Solar Data Logger Market
Solar Power Systems
Thin-Film Photovoltaic Market