
 United States Solar Microinverter Market | 2026-2036
United States Solar Microinverter Market Size, Share, and Industry Trends Forecast 2026-2036
United States Solar Microinverter Market Intelligence
Module-level power electronics with 240V split-phase output and UL 1741-SA certification is rotating through the residential channel as installers trade up from string-based architectures. Enphase leverages its integrated AC battery ecosystem to anchor recurring service revenue. SolarEdge competes through power optimizer pairing with centralized inversion for commercial rooftops. APsystems differentiates via dual-module microinverter designs that reduce balance-of-system labor.
A solar microinverter is a compact DC-to-AC power conversion device mounted behind individual photovoltaic modules, typically rated between 250W and 500W with maximum power point tracking performed at the panel level to optimize energy harvest under partial shading or mismatch conditions. Its primary commercial purpose is to eliminate single-point failure risk in string architectures while enabling granular production monitoring and simplified rooftop expansion. Single-phase units dominate residential attachment rates, though three-phase variants are gaining traction in small commercial installations where 208V service prevails. Roof-mounted deployments generate the deepest installer familiarity and fastest permitting turnaround, while ground-mounted utility applications favor power optimizer architectures for centralized inversion economies. Hybrid microinverters with DC-coupled battery integration command premium positioning as storage attachment rates climb.
FERC Order 2222 and state-level interconnection standards governed by public utility commissions are accelerating grid-forming inverter requirements that favor advanced microinverter compliance paths. California's Title 24 building code mandates solar readiness on new construction, embedding module-level electronics into baseline residential design. EPA portfolio standards and state renewable portfolio standards in Texas and Arizona create procurement pull-through for distributed generation with production visibility. Stakeholders must monitor NEM 3.0 export compensation structures and evolving IEEE 1547-2018 certification timelines as these determine retrofit economics and new build attachment rates.
Market Dynamics
FERC Order 2222 compliance deadlines and IEEE 1547-2018 certification requirements are restructuring procurement priorities for distributed generation assets. Installers now face binary equipment choices between legacy string architectures and module-level power electronics with grid-forming capabilities.
Growth Catalysts
- Inflation Reduction Act Investment Tax Credits:Residential and commercial solar deployments in sun-belt states now capture 30% federal incentives that improve project IRRs and accelerate payback periods for module-level electronics.
- California Title 24 Building Code:New construction mandates for solar readiness embed microinverter-compatible electrical infrastructure into baseline residential design, front-loading attachment rates.
- Module-level monitoring platforms:Granular production visibility at the panel level is displacing coarse string-level data, driving homeowner demand for fault isolation and performance optimization.
Market Restraints
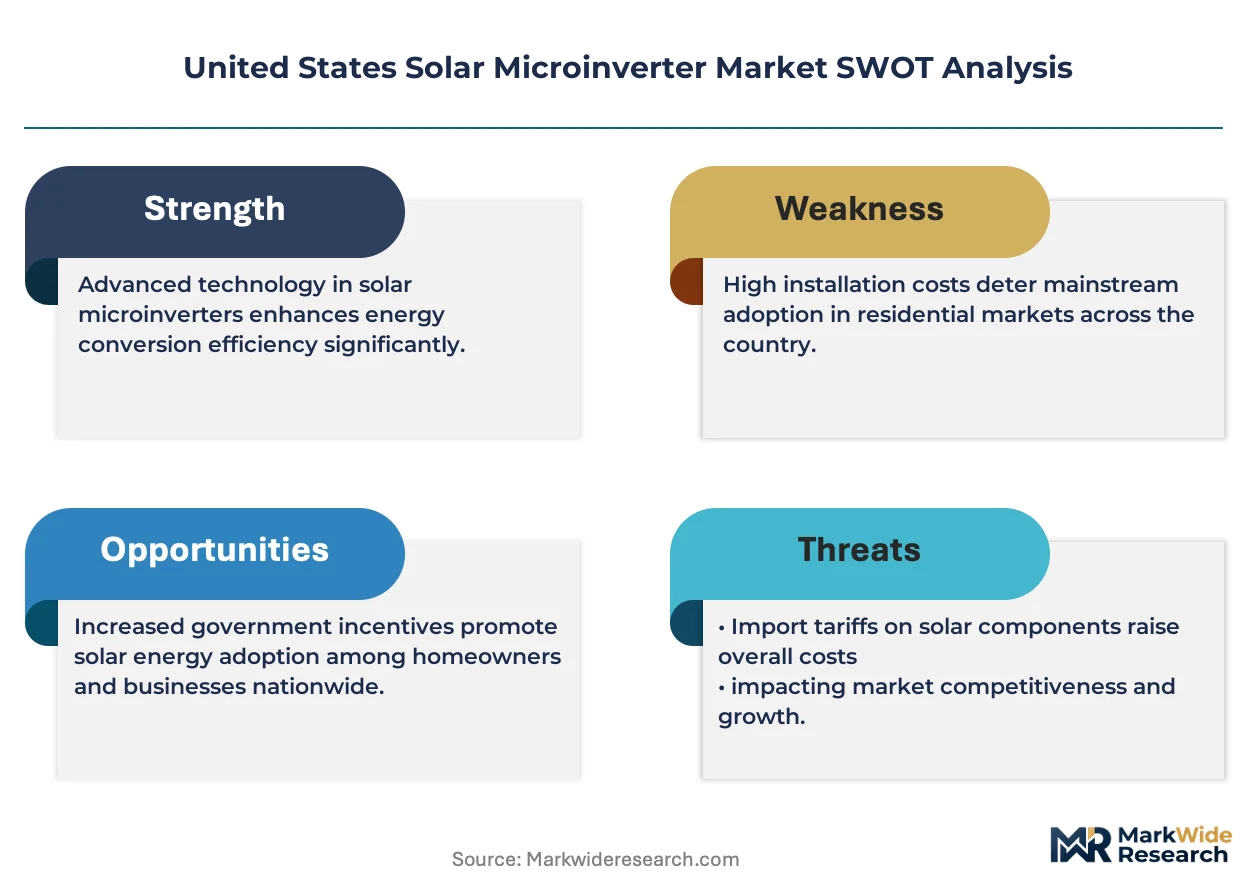
- Semiconductor supply concentration:Power MOSFET and gate driver sourcing from East Asian foundries creates lead time volatility for 250W-500W residential units.
- NEM 3.0 export compensation compression:California's revised net metering structure reduces avoided-cost rates for rooftop solar, extending payback horizons and dampening retrofit economics.
- String inverter cost parity:Centralized inversion with power optimizers delivers comparable monitoring at lower per-watt installed cost for unshaded commercial rooftops.
Strategic Opportunities
- Texas ERCOT grid instability:Rolling blackouts and wholesale price spikes are driving residential storage attachment, favoring hybrid microinverters with DC-coupled battery integration.
- Florida net metering preservation:Favorable export compensation policies in the Sunshine State sustain retrofit economics absent federal incentive cliffs.
- Installer certification programs:NABCEP credentialing requirements are creating channel captivity for training-integrated microinverter vendors with dedicated field support.
Industry Challenges
- UL 1741-SA certification timelines:Grid-forming inverter testing protocols extend product validation cycles, delaying revenue recognition for new hardware releases.
- Electrical contractor labor scarcity:Skilled residential solar electricians in California and Arizona command premium wages, compressing installer margins on labor-intensive module-level deployments.
- Legacy string system interoperability:Retrofit customers face stranded asset risk when expanding existing arrays, complicating sales conversations and design flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Solar Microinverter Market |
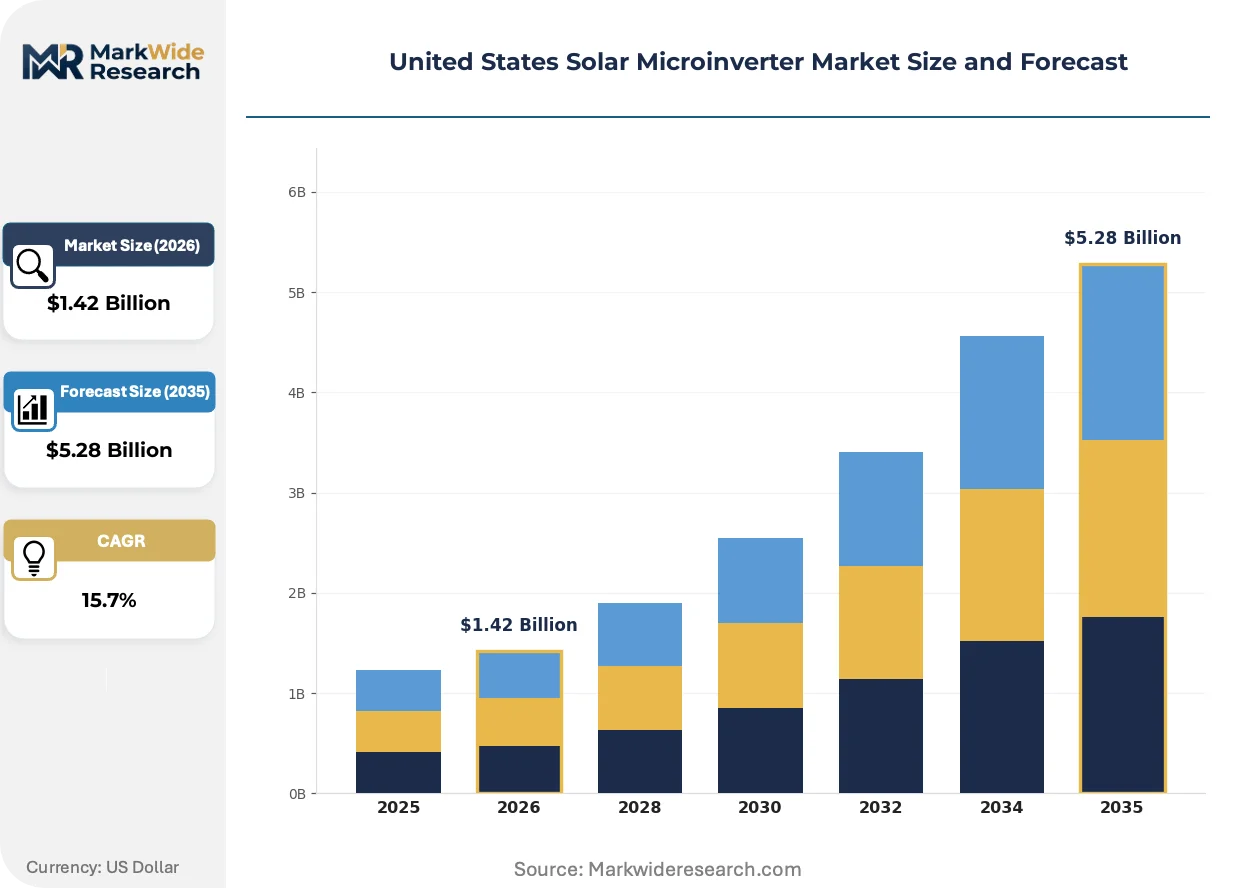
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $5.28 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Hybrid, Power Optimizer Installation Type: Roof-Mounted, Ground-Mounted, Building-Integrated, Off-Grid End User: Residential, Commercial, Industrial, Utility Technology: String Inverter, Central Inverter, Microinverter, DC Optimizer |
| Companies Covered | Hoymiles, Solectria, Enphase, Canadian Solar, SMA, SolarEdge, Chilicon Power, Qcells, APsystems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Solar Microinverter Market Strategic Shifts & Innovations
Module-level power electronics are converging with energy storage and grid services functionality, transforming microinverters from passive conversion devices into active grid assets. This architectural shift is redrawing competitive boundaries between hardware vendors and software platforms.
Quad-mode microinverters with reactive power control and frequency-watt response are displacing conventional UL 1741-SA certified units in California and Hawaii markets. Residential installers in NEM 3.0 territories are specifying these capabilities to maximize self-consumption and participate in virtual power plant programs. The added semiconductor content is compressing gross margins but creating recurring software revenue streams through grid services aggregation.
IEEE 1547-2018 implementation timelines enforced by state public utility commissions are mandating ride-through capabilities and voltage regulation functions that favor advanced microinverter architectures. Texas and Arizona regulators have adopted the standard with 2024-2025 effective dates, forcing equipment upgrades across distribution interconnection queues. Commercial rooftop segments in these states are responding by consolidating procurement around vendors with certified three-phase product lines.
Homebuyer preference for solar-ready electrical panels is rotating demand toward new construction channels in Florida and Texas. Production builders in these states are pre-wiring for module-level electronics to accelerate closing timelines and meet HERS rating requirements. This channel shift is most visible in master-planned communities where solar is bundled into mortgage financing rather than sold as a post-purchase upgrade.
United States Solar Microinverter Market Segmentation
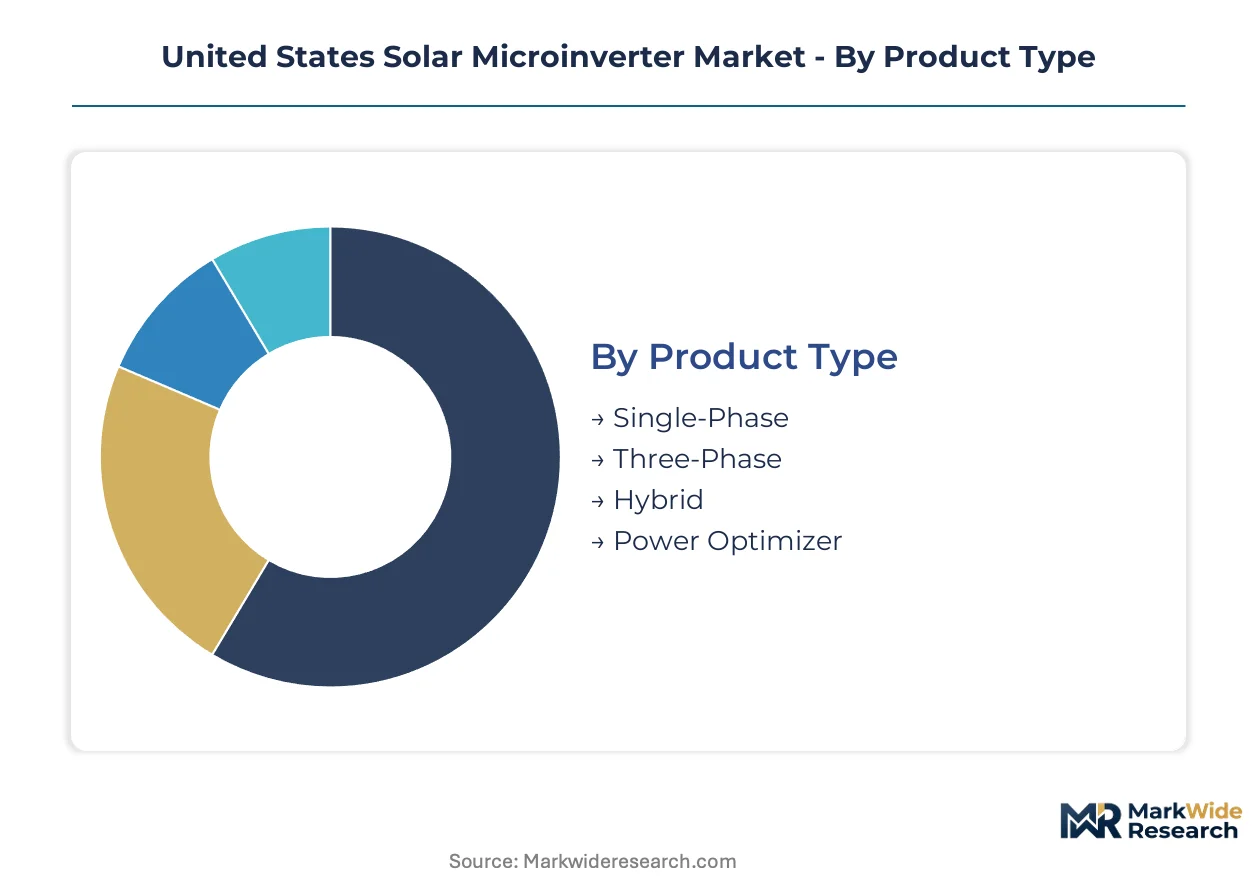
Segmentation in the United States solar microinverter market reveals how technology choices cascade through installation economics and regulatory compliance. Each dimension exposes different vulnerability to substitute architectures and shifting policy incentives across state markets.
Product Type:
Power optimizers and string inverters exert the strongest substitution pressure on traditional microinverter segments, particularly in unshaded commercial applications where module-level monitoring is desired without per-panel conversion costs.
- Single-Phase:These 240V split-phase units dominate behind-the-module residential deployments, integrating maximum power point tracking with UL 1741-SA grid support functions. California rooftop retrofits concentrate demand here as NEM 3.0 self-consumption economics favor panel-level optimization over string alternatives.
- Three-Phase:Engineered for 208V commercial service entrances, these variants enable balanced load distribution across small business rooftops. Texas and Arizona small commercial installations are rotating toward this format as IEEE 1547-2018 compliance deadlines approach.
- Hybrid:DC-coupled battery integration positions these units for storage attachment in ERCOT territories experiencing grid instability.
- Power Optimizer:Panel-level DC conditioning with centralized inversion offers cost-competitive monitoring for unshaded arrays.
Single-phase units anchor the volume base while hybrid configurations gain share at the steepest rate.
Installation Type:
Cost tier differentiation separates premium roof-integrated systems from economy ground-mounted alternatives, with labor intensity and permitting complexity driving the wedge.
- Roof-Mounted:Behind-the-rail attachment dominates residential channel economics, leveraging existing electrical infrastructure and accelerated municipal permitting pathways. Florida and Texas production builders specify this format for solar-ready new construction under streamlined HERS compliance.
- Ground-Mounted:Racking systems for utility-scale and agricultural applications favor power optimizer architectures over microinverters due to centralized inversion economies at scale.
- Building-Integrated:Aesthetic solar roofing and facade applications demand compact form factors.
- Off-Grid:Remote cabin and rural electrification deployments prioritize DC-coupled storage integration.
Roof-mounted deployments capture the deepest installer familiarity while building-integrated formats expand most quickly in premium new construction segments.
End User:
Customer type maturity varies sharply, with residential channels exhibiting the highest technology turnover and utility procurement favoring proven centralized architectures.
- Residential:Homeowner demand concentrates in California, Texas, and Florida where high irradiance coincides with favorable financing or net metering structures. Module-level monitoring drives attachment as solar becomes a standard home improvement category.
- Commercial:Small business rooftops in sun-belt states balance production visibility against per-watt installed cost, often selecting power optimizer hybrids.
- Industrial:Large flat-roof facilities with unshaded exposure favor string or central inversion.
- Utility:Ground-mounted solar farms at transmission scale deploy centralized inversion exclusively.
Residential channels anchor current volume while commercial retrofits climb the fastest as NEM 3.0 export compression forces self-consumption optimization.
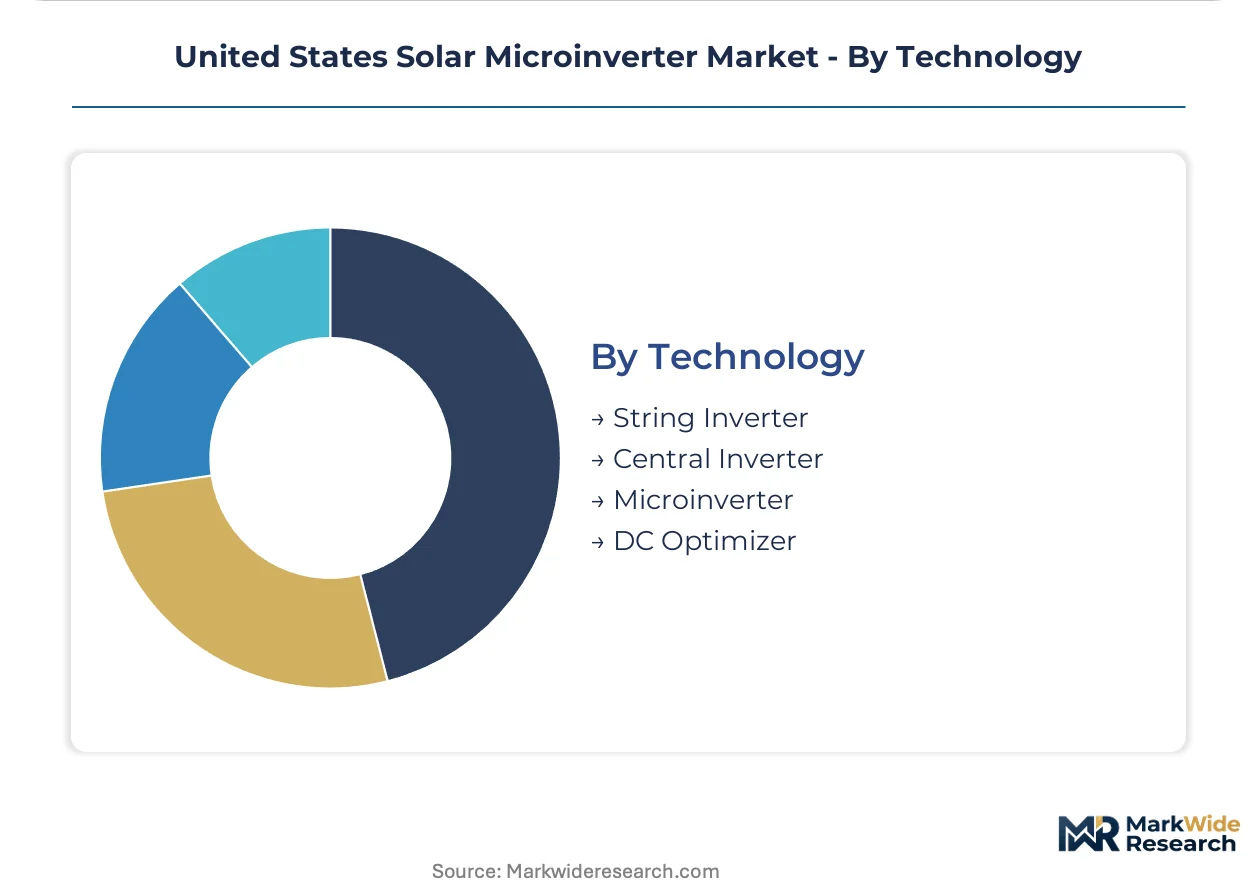
Technology:
Supply concentration in semiconductor sourcing creates divergent availability constraints across conversion architectures, with microinverter production facing tighter component lead times than centralized alternatives.
- Microinverter:Per-panel AC conversion with integrated MPPT eliminates single-point failure risk and enables granular monitoring. California Title 24 solar readiness mandates embed this architecture into baseline electrical design for new residential construction.
- DC Optimizer:Panel-level conditioning with string inverter pairing captures monitoring benefits at reduced semiconductor content.
- String Inverter:Centralized DC-to-AC conversion for series-wired arrays dominates economy segments.
- Central Inverter:Utility-scale conversion at the megawatt level serves ground-mounted projects exclusively.
String inverter architectures anchor the installed cost floor while microinverter penetration climbs fastest in retrofit markets requiring shade tolerance and monitoring granularity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian semiconductor foundries concentrate critical power MOSFET and gate driver supply for residential microinverter production. California, Texas, and Florida absorb the majority of domestic module-level electronics deployment as irradiance and policy incentives align. State-level interconnection standards and building codes now determine equipment specification across distinct regional markets.
California
Residential rooftop retrofits concentrate in Los Angeles, San Diego, and Bay Area metro corridors where NEM 3.0 export compression forces self-consumption optimization. Title 24 solar readiness mandates embed microinverter-compatible electrical infrastructure into new construction permits. The California Energy Commission enforces IEEE 1547-2018 compliance timelines that accelerate grid-forming inverter procurement.
Texas
ERCOT grid instability and rolling blackout events drive storage attachment rates in Houston and Dallas-Fort Worth residential channels. Favorable interconnection standards under the Public Utility Commission of Texas support rapid distributed generation deployment. Austin and San Antonio production builders specify solar-ready electrical panels to accelerate HERS compliance and mortgage bundling.
Florida
The Sunshine State preserves net metering export compensation that sustains retrofit economics absent federal incentive cliffs. Miami, Tampa, and Orlando metro areas exhibit the fastest permitting turnaround for roof-mounted residential systems. Florida Building Code solar readiness provisions align with module-level electronics specification in master-planned communities.
Arizona
Phoenix and Tucson markets combine high irradiance with Renewable Energy Standard tariff structures that pull through distributed generation assets. The Arizona Corporation Commission adopted IEEE 1547-2018 with 2024 effective dates, forcing equipment upgrades across interconnection queues. Navajo County and Coconino County ground-mounted utility projects favor power optimizer architectures for centralized inversion economies.
United States Solar Microinverter Market Key Industry Players
Concentration sits with vertically integrated hardware-software platforms and specialized power electronics fabricators. The vendor base separates into three distinct tiers: integrated ecosystem providers with battery coupling capabilities, standalone microinverter specialists with dual-module designs, and power optimizer vendors competing through centralized inversion pairing. Strategic moves center on UL 1741-SA certification acceleration and installer certification program capture to secure channel captivity.
Among North American-integrated ecosystem providers, Enphase and SolarEdge exemplify the hardware-software platform archetype, each anchoring distinct competitive vectors through recurring service revenue models and power optimizer pairing strategies respectively. APsystems represents the dual-module specialist tier with reduced balance-of-system labor positioning. SMA and Qcells occupy positions within the European and Korean industrial conglomerate fabricator categories, leveraging scale advantages in three-phase commercial segments.
| Leading Market Players |
|---|
| Hoymiles |
| Solectria |
| Enphase |
| Canadian Solar |
| SMA |
| SolarEdge |
| Chilicon Power |
| Qcells |
| APsystems |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation agreements with East Asian foundries lock in semiconductor access for US microinverter vendors while capping price volatility on power MOSFET and gate driver components. These contractual structures anchor procurement economics for residential 250W-500W units where module-level electronics compete against string alternatives.
Pricing Analysis
UL 1741-SA certification dictates the pricing tier structure across residential and commercial segments. Three-tier pricing structure across premium grid-forming, standard grid-following, and economy retrofit tiers separates vendors by IEEE 1547-2018 compliance depth. California NEM 3.0 export compression is intensifying price competition in the retrofit channel as payback period extension drives buyer sensitivity toward per-watt installed cost. Residential homeowners in sun-belt states exhibit highest price sensitivity, while commercial EPC contractors prioritize certification reliability over unit economics.
Supply Chain Analysis
Taiwan Strait shipping lanes concentrate risk for power semiconductor delivery to North American assembly facilities. Taiwan, South Korea, and Japan anchor wafer fabrication for silicon carbide MOSFETs and isolated gate drivers that feed US microinverter production. Tariff exposure on Chinese-sourced magnetic components and capacitors rests on Section 301 duty classifications. Distribution runs through authorized distributor networks serving NABCEP-certified installer channels, with direct OEM relationships capturing utility-scale procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States solar microinverter market builds defensive moats through regulatory entrenchment: IEEE 1547-2018 and UL 1741-SA certification timelines create switching costs that lock installers into training-integrated vendor ecosystems.
For Market Incumbents: Compound channel captivity through NABCEP certification program expansion and field service network density in California, Texas, and Florida. Counter power optimizer substitution threat in unshaded commercial segments by accelerating three-phase product line certification. Prioritize backward integration into power semiconductor sourcing to reduce foundry lead time vulnerability. For New Entrants and Emerging Players: Lead with Texas ERCOT territory storage attachment as the most penetrable white space, where hybrid microinverter demand outpaces incumbent supply. Target Florida master-planned community production builders specifying solar-ready electrical panels under streamlined HERS compliance. Deploy installer training subsidies as the primary go-to-market mechanism to overcome certification barrier. For Investors and Strategic Acquirers: Specialist dual-module microinverter fabricators with reduced balance-of-system labor positioning represent the most attractive acquisition archetype for platform consolidation. Long-term viability hinges on DC-coupled battery integration capabilities and virtual power plant software revenue attachment. Watch NEM 3.0 export compensation adoption across additional states as the inflection signal for retrofit market compression.| Strategic Initiative | Industry Significance |
|---|---|
| UL 1741-SA Certification Acceleration | FERC Order 2222 compliance deadlines force grid-forming capability into baseline product specifications. |
| Installer Certification Program Expansion | NABCEP credentialing requirements create channel captivity and reduce customer acquisition costs. |
| DC-Coupled Battery Integration | ERCOT grid instability drives residential storage attachment rates favoring hybrid architectures. |
| Backward Integration into Semiconductors | East Asian foundry concentration creates supply risk that captive sourcing mitigates. |
| Virtual Power Plant Software Platform | California NEM 3.0 self-consumption economics enable recurring grid services revenue streams. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with residential solar installers, commercial EPC contractors, utility interconnection planners, and power electronics procurement leads. Secondary validation drew from FERC interconnection filings, EIA generation capacity databases, state public utility commission dockets, and NABCEP certification records. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across the analysis window.
Across the projection horizon, the analytical framework modeled volume and value outputs by product type, installation format, end-user segment, and state regulatory cluster. CAGRs were derived from regression analysis of historical attachment rates against policy incentive trajectories. Forecast inputs incorporated IEEE 1547-2018 adoption timelines, NEM 3.0 export compensation structures, and semiconductor availability constraints.
The analysis sits within stated boundaries; outcomes outside IRA incentive continuity or East Asian supply stability would require recalibration. Forecasts reflect documented assumptions regarding interconnection queue processing speeds and installer labor availability. Practitioners should keep alternative scenarios live as state-level net metering structures and federal tax credit phase-down schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Argentina Solar Energy Market
Solar Power Systems
US Solar Carport Market
Solar Power Systems
Building Integrated Photovoltaics Module Market
Solar Power Systems
Europe Concentrated Solar Power Market
Solar Power Systems
Asia-Pacific Rooftop Solar Market
Solar Power Systems
Solar PV Panels Market
Solar Power Systems
Thin Film Photovoltaic Sales Market
Solar Power Systems
Bulgaria Solar Energy Market
Solar Power Systems
Solar PV Tracker Market
Solar Power Systems
Off-Grid Solar Energy Market
Solar Power Systems
Floating Photovoltaics (FPV) Market
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
Off-Grid Solar Lighting Market
Solar Power Systems
Smart Solar Tracker Market
Solar Power Systems
Smart Solar Power Market
Solar Power Systems
China Distributed Solar Power Generation Market