
 United States Solar Energy Market | 2026-2036
United States Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
United States Solar Energy Market Analytics
Domestic thin-film manufacturing capacity in Ohio and Alabama is shifting toward cadmium telluride and perovskite tandem architectures. First Solar leverages vertical integration from semiconductor deposition through module assembly to control cost curves. NextEra Energy sustains the nation's largest renewable development pipeline through utility-scale origination and long-term power purchase agreements. Sunrun anchors residential market share with leased and loaned rooftop systems across deregulated state markets.
United States solar energy encompasses photovoltaic and concentrated thermal systems that convert electromagnetic radiation into electrical current or process heat, with crystalline silicon modules achieving commercial efficiencies above twenty-one percent and utility installations requiring direct current to alternating current inversion at grid-frequency synchronization. The technology dimension shows bifacial panels capturing reflected irradiance from ground surfaces to boost yield per watt in ground-mounted configurations, while thin-film alternatives compete in utility procurement where temperature coefficients and shading tolerance offset lower conversion efficiency. Rooftop installation dominates residential end-user economics where net metering policies and behind-the-meter storage integration reshape customer value propositions.
FERC Order 2023 and state-level renewable portfolio standards in California, New York, and Illinois mandate interconnection reform and clean electricity procurement timelines that reshape developer capital allocation. The EPA's greenhouse gas standards for power plants and OSHA's fall protection requirements for elevated work further constrain project execution methods and equipment specifications. Stakeholders must monitor interconnection queue reform implementation and battery storage pairing economics as determinants of project bankability and regional deployment sequencing.
Market Dynamics
The Investment Tax Credit extension compresses project payback periods while interconnection queue reforms under FERC Order 2023 accelerate utility-scale deployment timelines across deregulated state markets.
Growth Catalysts
- Renewable Portfolio Standards:California, New York, and Illinois mandate clean electricity procurement timelines that force utilities into long-term solar power purchase agreements.
- Behind-the-meter storage integration:Residential customers pair rooftop photovoltaic systems with lithium-ion batteries to maximize net metering value and grid independence.
- Cadmium telluride thin-film advances:Domestic manufacturing in Ohio and Alabama reduces module cost curves and supply chain exposure to polysilicon price volatility.
Market Restraints
- Polysilicon supply concentration:Raw material refining clusters in Xinjiang and Inner Mongolia create tariff exposure and forced labor compliance risks for crystalline silicon module assemblers.
- Interconnection queue congestion:Regional transmission organizations in Texas and California impose multi-year study timelines that delay project energization and tie up developer capital.
- Alternating current infrastructure gaps:Rural substations and distribution feeders lack capacity to absorb utility-scale photovoltaic injection without voltage regulation upgrades.
Strategic Opportunities
- Agrivoltaic dual-use development:Ground-mounted arrays elevate panels above row crops or grazing land, generating lease revenue for farmers while preserving agricultural output in the Midwest.
- Perovskite tandem commercialization:Laboratory efficiencies exceeding thirty-three percent promise to disrupt incumbent silicon architectures if manufacturing yields stabilize.
- Community solar subscription models:Virtual net metering statutes in Colorado, Minnesota, and Massachusetts enable renters and shaded property owners to access off-site generation credits.
Industry Challenges
- Electrical trades labor scarcity:Journeyman electricians and NABCEP-certified installers command wage premiums that compress installer margins in high-demand states.
- Module-level power electronics certification:Rapid shutdown compliance with NEC Article 690.12 requires component-level listing that fragments supplier bases and extends procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Solar Energy Market |
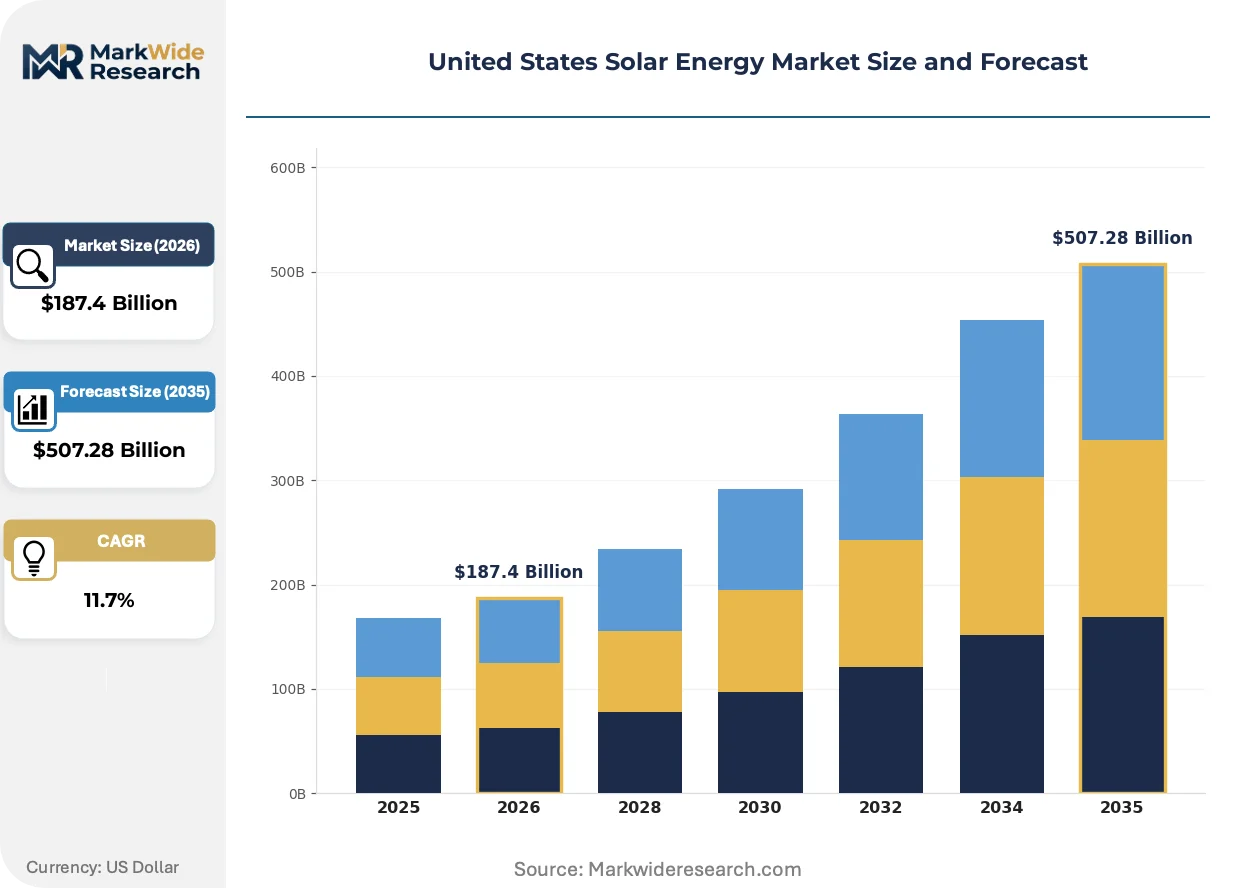
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Systems, Concentrated Solar Power, Solar Modules, Inverters End User: Residential, Commercial, Industrial, Utility Technology: Thin-Film, Crystalline Silicon, Bifacial, Building-Integrated Installation: Ground-Mounted, Rooftop, Off-Grid, Hybrid Systems |
| Companies Covered | First Solar, NextEra Energy, Sunrun, Invenergy, EDF Renewables North America, Cypress Creek Renewables, Qcells, Tesla, Constellation Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Solar Energy Market Evolving Landscape
Bifacial panel architectures and perovskite tandems are compressing levelized cost thresholds while interconnection automation and procurement platforms reshape how projects reach financial close.
Bifacial photovoltaic modules capture reflected irradiance from ground surfaces and snow cover to boost yield per watt. Utility-scale developers in the Southwest deploy these panels on single-axis trackers to maximize energy density per acre. This technology is expanding into floating solar installations on reservoirs and quarry ponds where albedo effects amplify rear-side generation.
FERC Order 2023 mandates cluster study reforms and standardized interconnection procedures across regional transmission organizations. The rule compresses study timelines from years to months for projects with clear site control and permitting. Texas and California grid operators are restructuring queue management to penalize speculative applications and prioritize ready-to-build projects.
Corporate offtakers now procure renewable energy through virtual power purchase agreements rather than direct physical delivery. Data center operators and semiconductor fabs in Arizona and Nevada anchor this demand as they seek hourly carbon-free energy matching. This behavior concentrates contract origination with developers who can pair solar with battery storage to shape output to load profiles.
United States Solar Energy Market Segmentation
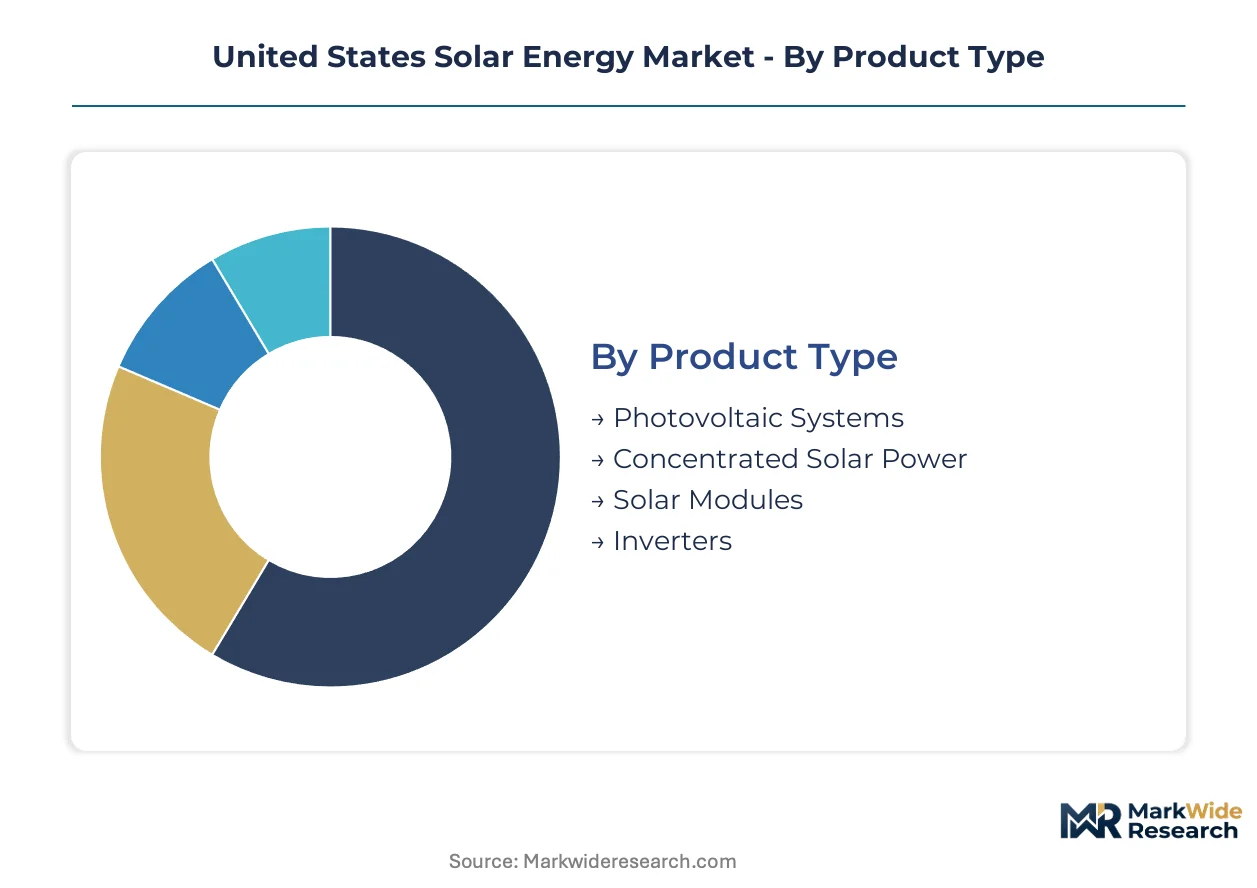
United States solar deployment fragments across technology architectures, customer scale, and grid-connection strategies that each carry distinct capital intensity, permitting pathways, and policy exposure. Understanding these divisions clarifies where module supply bottlenecks, interconnection delays, and tax credit optimization concentrate risk and return.
Product Type:
Technology specification determines manufacturing origin, balance-of-system requirements, and project bankability thresholds across the value chain.
- Photovoltaic Systems:Direct-conversion semiconductor arrays dominate capacity additions, with crystalline silicon and cadmium telluride architectures competing on temperature coefficients and supply chain provenance. Texas and California utilities procure multi-hundred-megawatt installations where DC-to-AC inversion and tracker mechanics add complexity to EPC contracts.
- Concentrated Solar Power:Parabolic trough and power-tower systems with molten-salt thermal storage deliver dispatchable capacity in the Southwest where direct normal irradiance exceeds thresholds for economic operation. Nevada and Arizona host the remaining commercial deployments as photovoltaic cost compression sidelines greenfield development.
- Solar Modules:Individual panel assemblies—framed glass-laminate units rated by wattage and efficiency tier—constitute the tradeable commodity layer where domestic content bonuses under the Inflation Reduction Act reshape procurement geography.
- Inverters:Power electronics that synchronize direct current output with grid-frequency alternating current, with string and central configurations selected based on array size and shading topology.
Photovoltaic Systems lead on scale; Solar Modules lead on momentum as domestic manufacturing incentives accelerate factory commitments in Ohio, Alabama, and Georgia.
End User:
Customer scale determines financing structure, offtake contract type, and regulatory jurisdiction.
- Residential:Behind-the-meter rooftop installations leased or loaned to homeowners, concentrated in deregulated state markets where net metering policies and property-assessed clean energy financing drive adoption.
- Commercial:On-site generation for retail, warehouse, and office facilities where power purchase agreements offset retail electricity rates and sustainability commitments shape procurement.
- Industrial:Large-load manufacturing facilities with predictable demand profiles that anchor corporate renewable energy procurement through virtual power purchase agreements.
- Utility:Independent power producers and regulated utilities deploying transmission-connected capacity where FERC interconnection queues and state renewable portfolio standards govern deployment sequencing.
Utility leads on scale; Residential leads on momentum as battery storage pairing and rate reform reshape customer economics.
Technology:
Cell architecture and module form factor determine efficiency curves, manufacturing location, and application suitability.
- Thin-Film:Cadmium telluride and copper indium gallium selenide semiconductors deposited on glass substrates, produced at scale by First Solar in Ohio and Alabama where vertical integration controls cost and avoids polysilicon supply chains.
- Crystalline Silicon:Monocrystalline and polycrystalline wafers sliced from ingots, dominating global module supply with PERC and TOPCon cell architectures pushing commercial efficiencies above twenty-one percent.
- Bifacial:Double-glass modules capturing rear-side irradiance reflected from ground surfaces or snow cover, deployed on single-axis trackers in utility-scale configurations to boost yield per watt.
- Building-Integrated:Photovoltaic cells embedded in roofing membranes, curtain walls, and skylights where aesthetic and structural integration commands premium pricing in commercial and high-end residential segments.
Crystalline Silicon leads on scale; Bifacial leads on momentum as albedo capture and tracker pairing expand addressable project returns.
Installation:
Mounting configuration and grid-connection status shape land use, permitting complexity, and revenue streams.
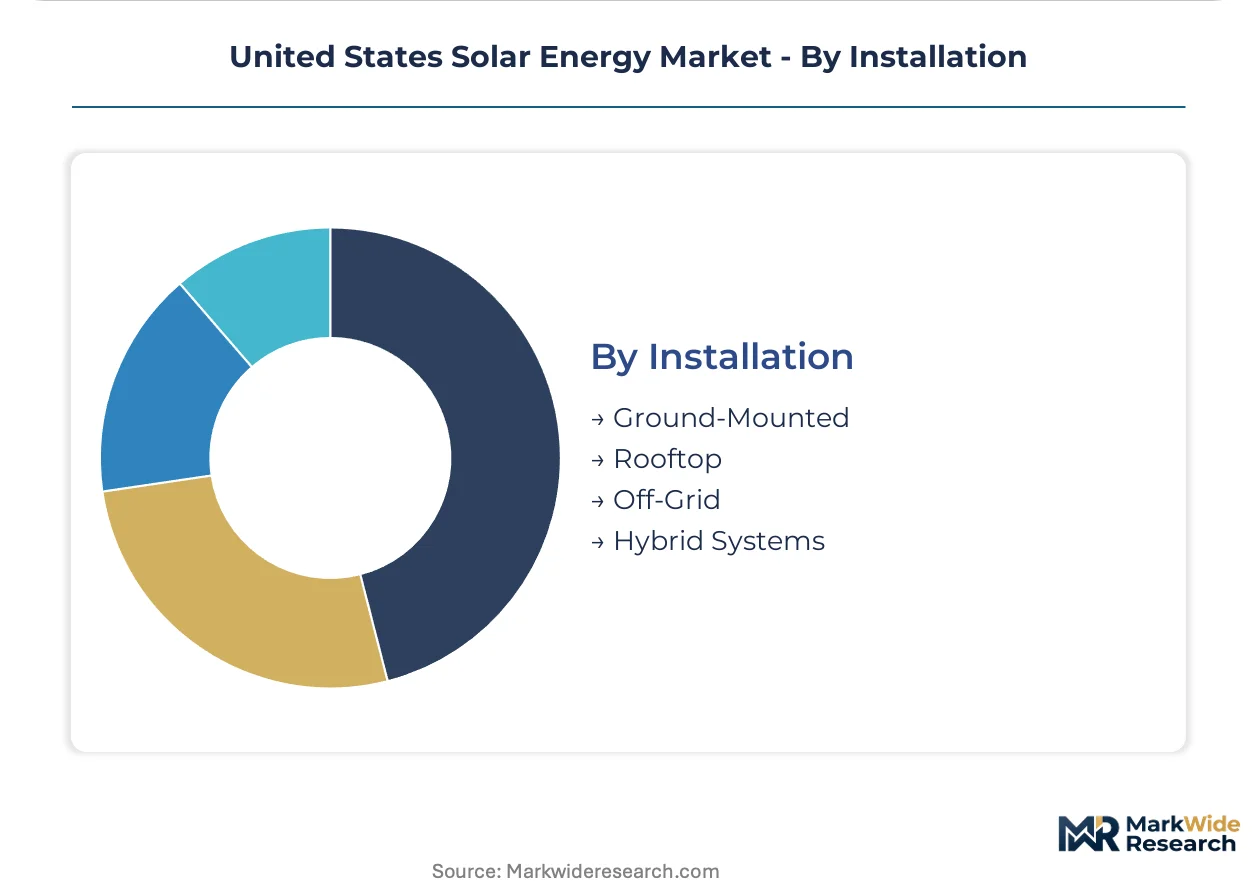
- Ground-Mounted:Fixed-tilt or tracking arrays on open land, dominating utility-scale deployment where agrivoltaic dual-use configurations generate lease revenue for Midwest farmers while preserving agricultural output.
- Rooftop:Residential and commercial systems attached to existing structures, concentrated in California, Texas, and Florida where solar resource and electricity rates align customer payback periods.
- Off-Grid:Standalone systems with battery storage serving remote structures and telecommunications infrastructure where distribution grid extension is uneconomic.
- Hybrid Systems:Solar paired with battery storage, diesel backup, or other generation assets to shape output profiles and ensure reliability in microgrid and resilience applications.
Ground-Mounted leads on scale; Hybrid Systems lead on momentum as storage cost declines and grid reliability concerns accelerate pairing economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic content bonuses under the Inflation Reduction Act are pulling module assembly toward states with lower labor costs and weaker state environmental review requirements, creating a compliance-cost arbitrage that favors Ohio and Alabama over California and New York.
Texas
ERCOT's interconnection queues swell with utility-scale photovoltaic proposals as corporate data centers and hydrogen electrolyzer projects drive procurement. The Public Utility Commission of Texas approved $7.8 billion in transmission expansion to relieve congestion between West Texas solar zones and Gulf Coast load centers. Developers concentrate in the Permian Basin and South Texas where land availability and irradiance profiles support gigawatt-scale project clusters.
California
The California Public Utilities Commission's net metering reforms and CPUC-mandated storage pairing requirements reshape residential and commercial deployment economics. The California Independent System Operator manages interconnection backlogs for transmission-connected projects in the Central Valley and Imperial Valley. Sacramento and Fresno anchor distributed solar deployment as municipal utilities maintain more favorable rate structures than investor-owned counterparts.
Arizona
Direct normal irradiance exceeding 2,500 kWh per square meter annually supports concentrated solar power retention and utility-scale photovoltaic expansion. The Arizona Corporation Commission maintains renewable energy standards that require regulated utilities to procure clean capacity. Phoenix and Tucson metropolitan areas concentrate rooftop installation activity where summer peak demand and time-of-use rates improve customer payback calculations.
Florida
The Sunshine State prohibits third-party power purchase agreements but sustains utility-owned solar expansion through Florida Power & Light's SolarTogether program and Duke Energy Florida's clean energy commitments. The Florida Public Service Commission approved rate-basing for utility solar investments that bypass customer acquisition costs endemic to deregulated markets. Orlando and Tampa anchor commercial deployment where behind-the-meter systems offset high commercial electricity tariffs.
Ohio
First Solar's cadmium telluride manufacturing complex in Perrysburg represents the largest domestic thin-film production footprint, capitalizing on Inflation Reduction Act domestic content bonuses and avoiding polysilicon supply chain exposure. The Ohio Power Siting Board streamlined approval timelines for utility-scale projects on reclaimed industrial land. Toledo and Columbus anchor manufacturing and distributed deployment clusters respectively.
United States Solar Energy Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue agrivoltaic dual-use configurations and community solar subscription models to bypass interconnection queue congestion. The vendor base separates into three archetypes: vertically integrated thin-film manufacturers controlling semiconductor deposition through module assembly, independent power producers aggregating development pipelines through long-term power purchase agreements, and residential installers leasing rooftop systems through tax equity partnerships. Competitive moves concentrate on manufacturing capacity expansion in domestic content bonus-eligible states and strategic partnerships with corporate offtakers seeking hourly carbon-free energy matching.
Among domestic thin-film specialists, First Solar exemplifies vertical integration from semiconductor deposition through module assembly. NextEra Energy occupies a position as the nation's largest renewable development pipeline holder through utility-scale origination. Sunrun anchors residential market representation with leased and loaned rooftop systems across deregulated state markets.
| Leading Market Players |
|---|
| First Solar |
| NextEra Energy |
| Sunrun |
| Invenergy |
| EDF Renewables North America |
| Cypress Creek Renewables |
| Qcells |
| Tesla |
| Constellation Energy |
| Others |
Value Network & Pricing Analysis
FERC Order 2023 compliance deadlines gate access to premium interconnection pricing tiers for developers with site control and permitting secured, compressing margins for speculative queue positions while rewarding ready-to-build projects with faster study timelines and lower cost of capital.
Pricing Analysis
Direct-to-utility EPC contracting eliminates distributor markups for multi-hundred-megawatt installations, while residential channels absorb retailer margins through third-party ownership structures. Pricing stratifies across premium domestic-content modules, standard imported crystalline silicon, and economy-tier thin-film alternatives based on Inflation Reduction Act bonus eligibility and supply chain provenance. Cost compression in imported polysilicon modules is intensifying because tariff exposure and forced labor compliance documentation raise landed costs. Utility-scale offtakers demonstrate lowest price sensitivity due to long-term power purchase agreement anchoring, while residential lease customers face elevated monthly payments that amplify sensitivity to interest rate shifts.
Supply Chain Analysis
Journeyman electrician scarcity in Ohio and Alabama constrains module assembly line expansion and installation crew deployment despite factory capital commitments. Manufacturing draws from cadmium telluride semiconductor deposition, glass substrate forming, and aluminum frame extrusion as primary inputs. Raw material refining clusters in Xinjiang and Inner Mongolia create tariff exposure and forced labor compliance risks for crystalline silicon supply chains. Distribution runs through vertically integrated thin-film manufacturers, independent power producer procurement teams, and residential installer networks serving deregulated state markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States solar energy market has entered a late-cycle quality phase where hourly carbon-free energy matching requirements from corporate data center operators displace pure capacity-based procurement, rewarding developers with storage pairing capabilities and domestic content compliance.
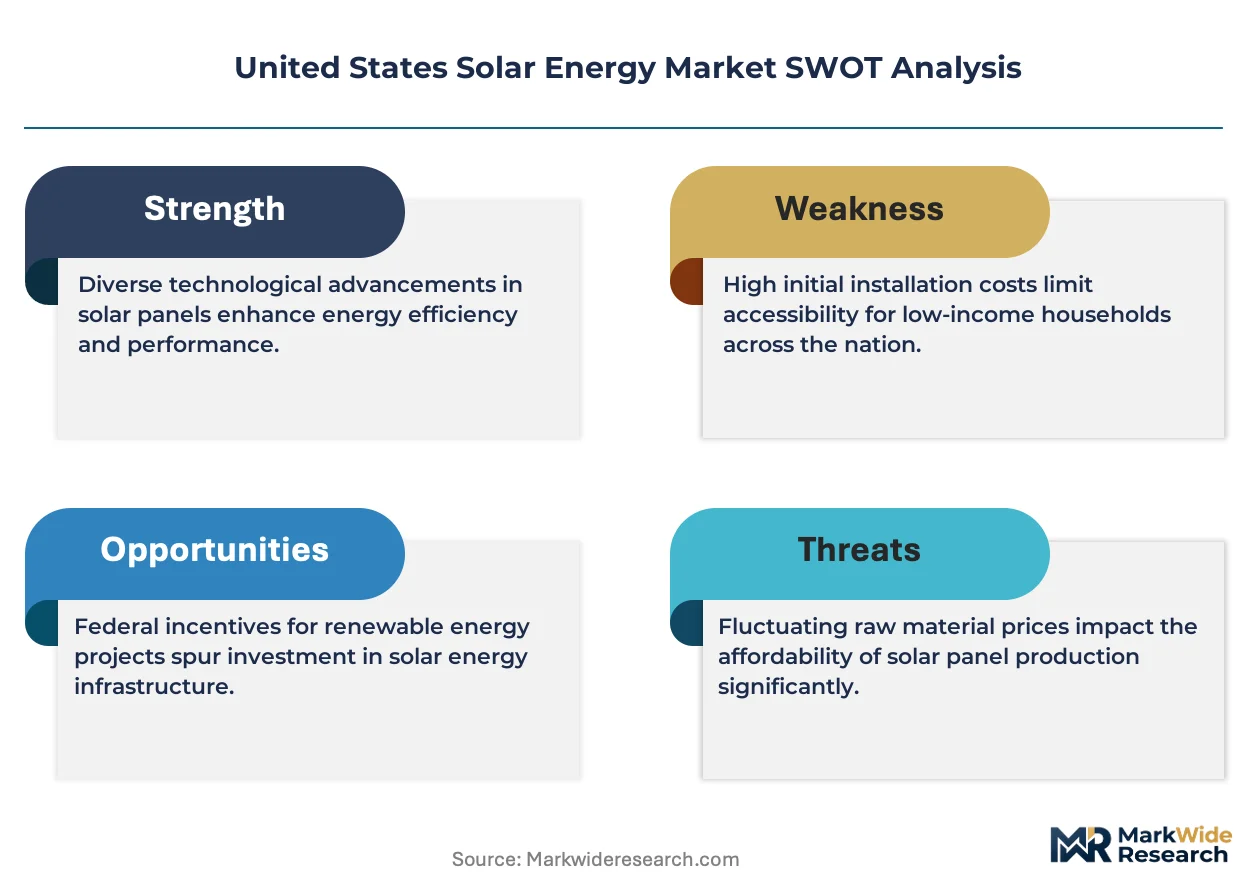
For Market Incumbents: Deepen backward integration into cadmium telluride semiconductor deposition to secure Inflation Reduction Act domestic content bonuses and insulate against polysilicon price volatility. Expand manufacturing capacity in Ohio and Alabama where streamlined state environmental review reduces compliance timelines. Control balance-of-system procurement through captive inverter and tracker production to defend margins against emerging thin-film competitors.
For New Entrants and Emerging Players: Enter via agrivoltaic dual-use development in Midwest states where agricultural lease revenue streams bypass interconnection queue congestion and preserve project bankability. Target community solar subscription models in Colorado, Minnesota, and Massachusetts where virtual net metering statutes enable rapid customer acquisition without rooftop installation complexity. Pursue strategic partnerships with agricultural land managers to secure long-term site control.
For Investors and Strategic Acquirers: Roll-up economics work for regional residential installers with established tax equity partnerships because customer acquisition costs in deregulated markets create scale advantages for consolidated platforms. Long-term viability hinges on storage pairing capabilities and software-enabled fleet management. Monitor FERC interconnection queue reform implementation velocity as the primary signal for deployment timing inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Scale-Up | First Solar's Ohio and Alabama expansion captures Inflation Reduction Act domestic content bonuses for utility procurement. |
| Storage Pairing Integration | Battery co-location with photovoltaic arrays satisfies corporate offtaker hourly carbon-free energy matching requirements. |
| Agrivoltaic Site Development | Dual-use configurations in Midwest states generate agricultural lease revenue while preserving crop production. |
| Interconnection Automation Investment | FERC Order 2023 compliance accelerates study timelines for developers with clear site control and permitting. |
| Community Solar Platform Buildout | Virtual net metering statutes in Colorado and Massachusetts expand addressable customer base beyond property owners. |
Research Methodology
Coverage spans Texas, California, Arizona, Florida, and Ohio, with primary inputs from each regional market through structured interviews with utility planning officers, independent power producer project developers, EPC contractors, grid operators, and module supply specialists. Secondary validation draws from EIA generation statistics, FERC interconnection filings, IEA renewable energy reports, and state renewable portfolio standard compliance databases. Bottom-up project-level capacity aggregation and top-down regulatory scenario modeling were triangulated to reconcile deployment timelines.
Granularity-level framing applied technology architecture, end-user scale, installation configuration, and regional regulatory cluster as primary segmentation dimensions across the analysis window. CAGRs were derived from project pipeline visibility, interconnection queue progression rates, and policy incentive phase-out schedules. Forecast inputs incorporated module cost curve trajectories, battery storage pairing economics, and labor availability constraints in manufacturing geographies.
Inputs from FERC and state public utility commissions were available through the study window; gaps in real-time interconnection queue progression data introduce uncertainty bands around energization date assumptions. Forecasts reflect documented assumptions regarding Inflation Reduction Act domestic content bonus continuity, tariff exposure on imported polysilicon, and regional transmission organization study timeline compliance. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
United Arab Emirates Solar Photovoltaic (PV) Market
Solar Power Systems
Ghana Solar Energy Market
Solar Power Systems
Bifacial Solar Module Market
Solar Power Systems
Marine Solar Panel Market
Solar Power Systems
Germany Distributed Solar Power Generation Market
Solar Power Systems
Hybrid Solar Panel Market
Solar Power Systems
Solar Photovoltaic (PV) Panel Market
Solar Power Systems
North America Concentrated Solar Power (CSP) Market
Solar Power Systems
Solar Pontoon Market
Solar Power Systems
Solar Tracker Installation Market
Solar Power Systems
Global Thin Film Solar Cells Market
Solar Power Systems
Solar Phone Chargers Market
Solar Power Systems
Distributed Solar Power Generation System Market
Solar Power Systems
Plastic Solar Cell Market
Solar Power Systems
Residential Solar Shading System Market
Solar Power Systems
Middle-East and Africa Distributed Solar Power Generation Market