
 Crystalline Silicon Solar PV Market | 2026-2036
Crystalline Silicon Solar PV Market Size, Share, and Industry Trends Forecast 2026-2036
Crystalline Silicon Solar PV Market Outlook
Utility-scale procurement is broadening faster than residential deployment as grid operators prioritize firm renewable capacity. LONGi Green Energy Technology anchors monocrystalline wafer supply through in-house ingot production. Tongwei Solar dominates polysilicon manufacturing and extends cost leadership through chemical-grade silicon integration. JA Solar competes aggressively on module efficiency ratings across bifacial and PERC product lines.
Crystalline silicon solar PV refers to photovoltaic cells manufactured from silicon ingots sliced into wafers, typically achieving conversion efficiencies between twenty-one and twenty-four percent for monocrystalline architectures and serving as the dominant technology for grid-connected electricity generation. Polysilicon purification via the Siemens process establishes material purity thresholds that directly constrain cell performance. Monocrystalline modules command premium pricing in utility-scale tenders where energy yield per hectare determines project returns. Heterojunction cell architectures represent the fastest-growing technology segment as manufacturers seek to displace incumbent PERC lines before equipment depreciation cycles conclude.
The EU Green Deal and its attendant Carbon Border Adjustment Mechanism reshape import competitiveness for Chinese-manufactured modules entering European markets. The United States Inflation Reduction Act's domestic content bonus credits redirect supply chain geography toward Southeast Asian and North American cell assembly. India's PLI scheme for solar manufacturing accelerates local polysilicon-to-module investments as developers face basic customs duty exposure on imported cells. Stakeholders must monitor how trade remedy expansions and technology-specific subsidy tiers alter competitive positioning between integrated polysilicon producers and module-only assemblers.
Market Dynamics
N-type cell architectures are rewriting cost-performance tradeoffs as manufacturers accelerate equipment upgrades ahead of PERC line depreciation cycles. This technology transition concentrates capital deployment in polysilicon purification and wafer thinning capabilities.
Growth Catalysts
- EU Green Deal domestic content mandates:European module buyers now prioritize locally assembled products, redirecting investment toward PERC and heterojunction cell manufacturing within EU member states.
- Utility-scale procurement expansion:Grid operators in India and the United States seek firm renewable capacity through long-term power purchase agreements that favor high-efficiency monocrystalline modules.
- Polysilicon-to-module integration:Chemical-grade silicon integration through the Siemens process enables producers to capture margin across the value chain from feedstock to finished cells.
Market Restraints
- Polysilicon price volatility:Feedstock cost swings constrain project developer margins and complicate long-term contract pricing for module procurement.
- Chinese supply concentration:Jiangsu and Anhui provinces control critical polysilicon and wafer capacity, creating geographic risk exposure for buyers seeking supply diversification.
- PERC equipment lock-in:Sunk capital in incumbent cell lines delays heterojunction adoption timelines for manufacturers with recent depreciation cycles.
Strategic Opportunities
- India PLI scheme acceleration:Production-linked incentives for solar manufacturing attract integrated polysilicon-to-module investments as developers face basic customs duty exposure on imported cells.
- United States IRA domestic content bonus:Tax credit adders for North American cell assembly redirect supply chain geography toward Southeast Asian and domestic manufacturing partners.
- Heterojunction-PERC technology convergence:Hybrid cell architectures combine established passivation techniques with advanced junction designs to bridge equipment transition gaps.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell manufacturing expansion outpaces skilled workforce availability for Czochralski crystal growth and thin-film deposition operations.
- Module certification timeline compression:IEC 61215 and IEC 61730 testing protocols create bottlenecks as new cell architectures require extended bankability validation cycles.
- Supply chain reconfiguration friction:Redirecting polysilicon logistics from Chinese coastal ports to alternative assembly locations in Vietnam and Thailand strains just-in-time wafer delivery systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crystalline Silicon Solar PV Market |
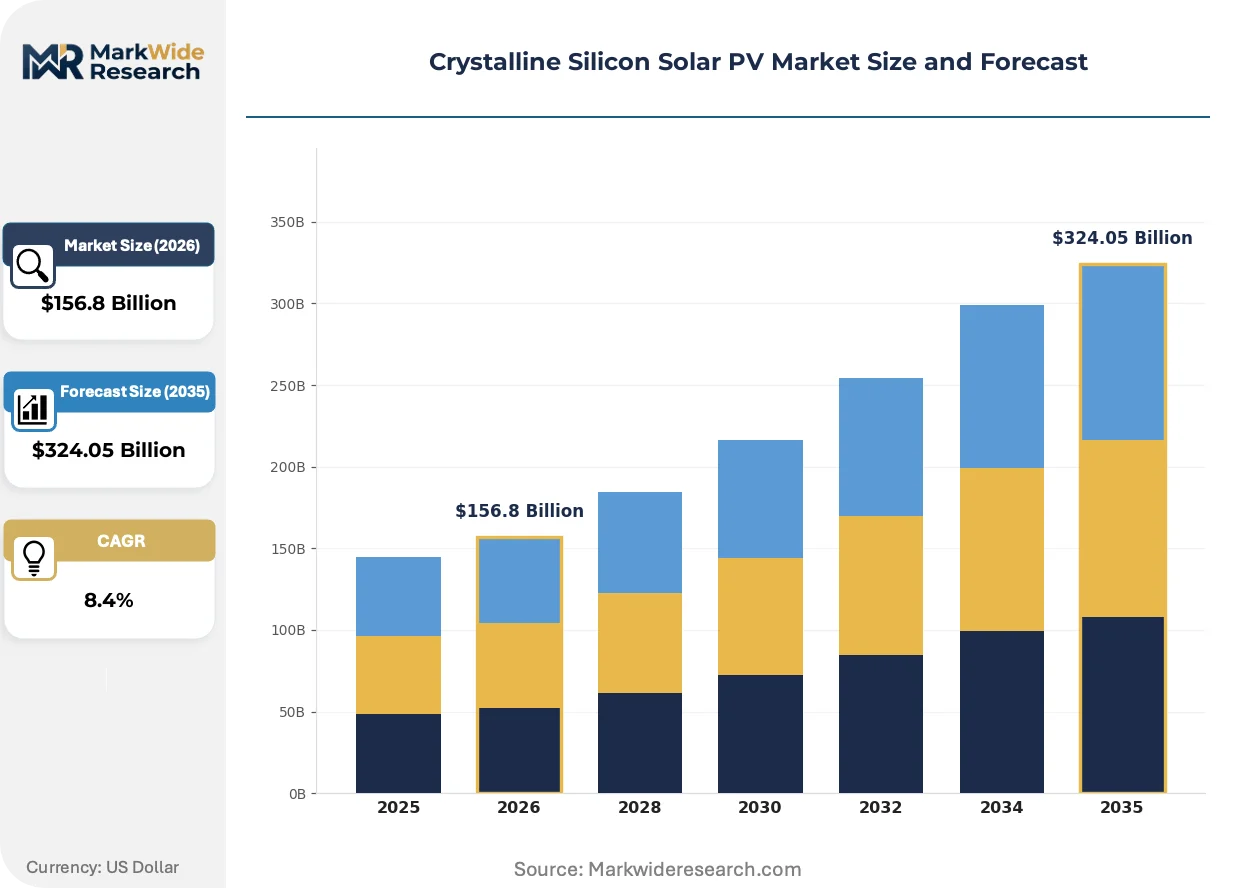
| Market Size in 2026 | $156.8 Billion |
| Market Size in 2035 | $324.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Bifacial, Thin-Film Application: Residential, Commercial, Utility-Scale, Off-Grid End User: Utilities, OEMs, Contractors, Distributors Technology: Temperature Coefficient, PERC, Half-Cut, Heterojunction |
| Companies Covered | JA Solar, Canadian Solar, JinkoSolar, GCL-Poly Energy Holdings, Hanwha Q CELLS, LONGi Green Energy Technology, Tongwei Solar, Risen Energy, Trina Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crystalline Silicon Solar PV Market Strategic Shifts
Heterojunction cell architectures and n-type wafer platforms are compressing efficiency gaps between laboratory demonstrations and mass-produced modules. These advances reshape capital allocation priorities across ingot pulling, wafer slicing, and cell fabrication equipment.
TOPCon and heterojunction cell structures is rewriting the competitive landscape for high-efficiency modules. Utility-scale developers in the United States and European utility tenders now specify n-type bifacial products for new projects. This specification shift compresses pricing premiums for PERC capacity and accelerates equipment retirement decisions.
The EU Carbon Border Adjustment Mechanism imposes embodied carbon reporting requirements on imported Chinese-manufactured modules entering European markets. Module assemblers must document polysilicon provenance and electricity sources for cell fabrication. European project developers increasingly source from Southeast Asian cell assembly to reduce carbon intensity scores and avoid border levy exposure.
Long-term power purchase agreements with fixed escalation clauses now dominate utility-scale procurement in India and the United States. Independent power producers negotiate directly with module manufacturers, bypassing traditional distributor channels. This disintermediation concentrates volume with integrated polysilicon producers and squeezes margin for module-only assemblers lacking captive wafer supply.
Crystalline Silicon Solar PV Market Segmentation
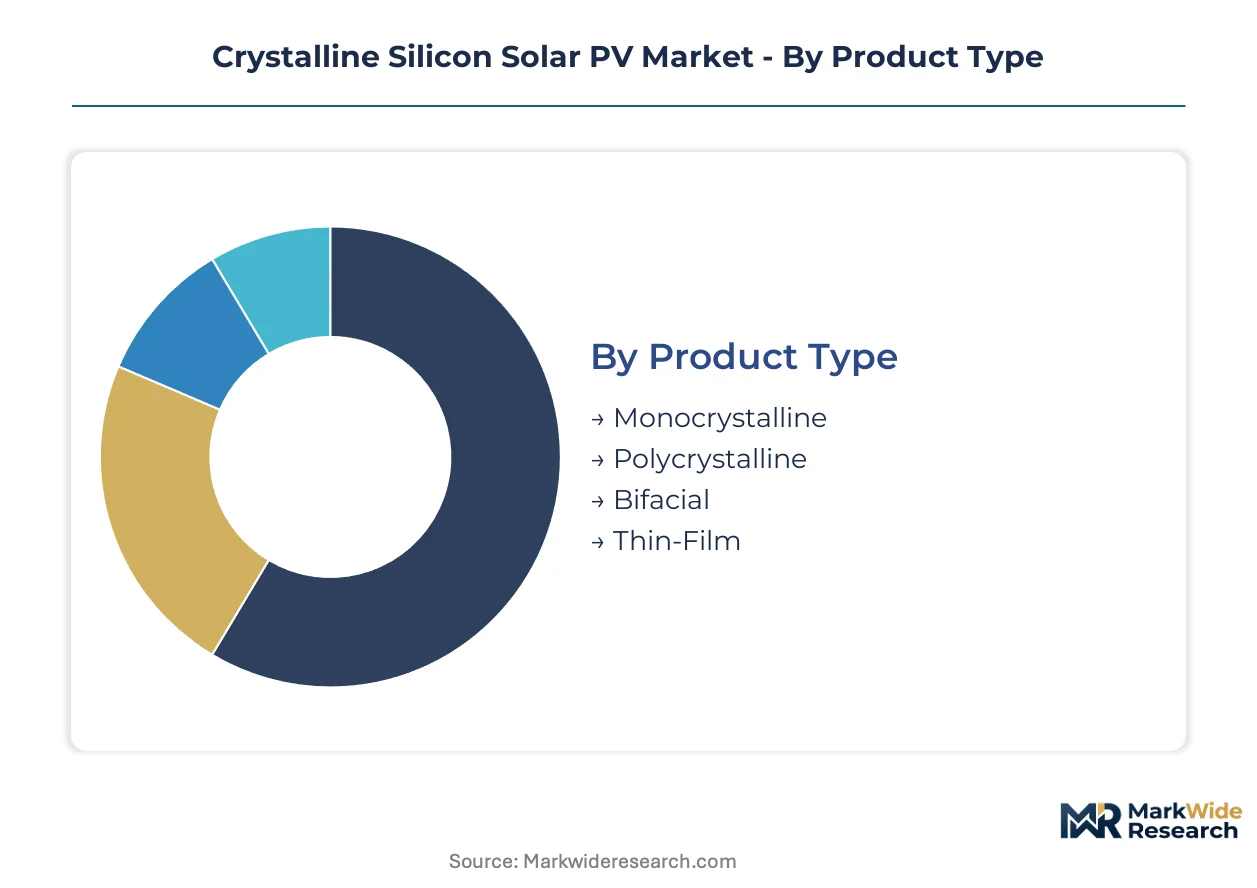
Crystalline silicon solar PV segmentation reflects divergent capital requirements across manufacturing stages and customer procurement patterns. Equipment depreciation cycles and polysilicon purity thresholds create distinct margin profiles that shape strategic positioning for integrated producers and module assemblers alike.
Product Type:
Capital intensity peaks at the polysilicon purification and ingot pulling stages, with monocrystalline production demanding the highest upfront equipment investment.
- Monocrystalline:Czochralski crystal growth produces uniform silicon lattice structures yielding conversion efficiencies above twenty-one percent. Utility-scale tenders in India and the United States specify monocrystalline modules for projects where energy yield per hectare determines returns, though ingot production requires substantial furnace and crucible investment.
- Bifacial:Dual-sided cell architectures capture reflected and diffuse light from rear surfaces, boosting energy harvest in high-albedo environments. Demand concentrates in Middle Eastern and North African utility installations where desert sand reflectance maximizes bifacial gain coefficients.
- Polycrystalline:Directional solidification furnaces produce lower-purity ingots at reduced capital cost, serving price-sensitive distributed generation segments.
- Thin-Film:Non-silicon alternatives occupy niche applications where weight constraints or flexible form factors outweigh efficiency considerations.
Most installed capacity flows through monocrystalline lines. Expansion is steepest in bifacial products.
Application:
Customer procurement scale determines contract structure, with utility-scale buyers negotiating directly with manufacturers while residential channels rely on distributor networks.
- Utility-Scale:Grid-connected projects above five megawatts deploy high-efficiency modules under long-term power purchase agreements with fixed escalation clauses. India's Central Electricity Authority and United States FERC-jurisdictional interconnection queues drive procurement volume, though project finance requirements demand extended bankability validation.
- Residential:Rooftop installations below twenty kilowatts prioritize aesthetic integration and simplified permitting over absolute efficiency metrics. Net metering policies in California and Germany shape demand concentration, with local installer networks capturing significant margin.
- Commercial:Behind-the-meter installations for industrial facilities balance peak demand reduction with available roof space.
- Off-Grid:Remote power systems combine solar generation with battery storage for unelectrified regions.
Utility-scale procurement commands the largest absolute volume. Residential deployment is climbing fastest as financing mechanisms mature.
End User:
Supply chain position dictates margin capture, with integrated producers serving utilities directly while contractors and distributors intermediate fragmented downstream segments.
- Utilities:Vertically integrated power generators procure modules through competitive tenders specifying efficiency, degradation rates, and warranty terms. State-owned distribution companies in India and investor-owned utilities in Texas anchor procurement volume, with domestic content requirements from the EU Green Deal and United States IRA reshaping supplier qualification.
- Contractors:Engineering-procurement-construction firms specify module brands based on installation labor efficiency and local inventory availability.
- OEMs:System integrators and balance-of-plant manufacturers incorporate modules into pre-engineered solar solutions.
- Distributors:Wholesale channels stock inventory for residential and commercial installer networks.
Direct utility procurement captures the highest volume concentration. Contractor channel expansion is accelerating most quickly as distributed generation scales.
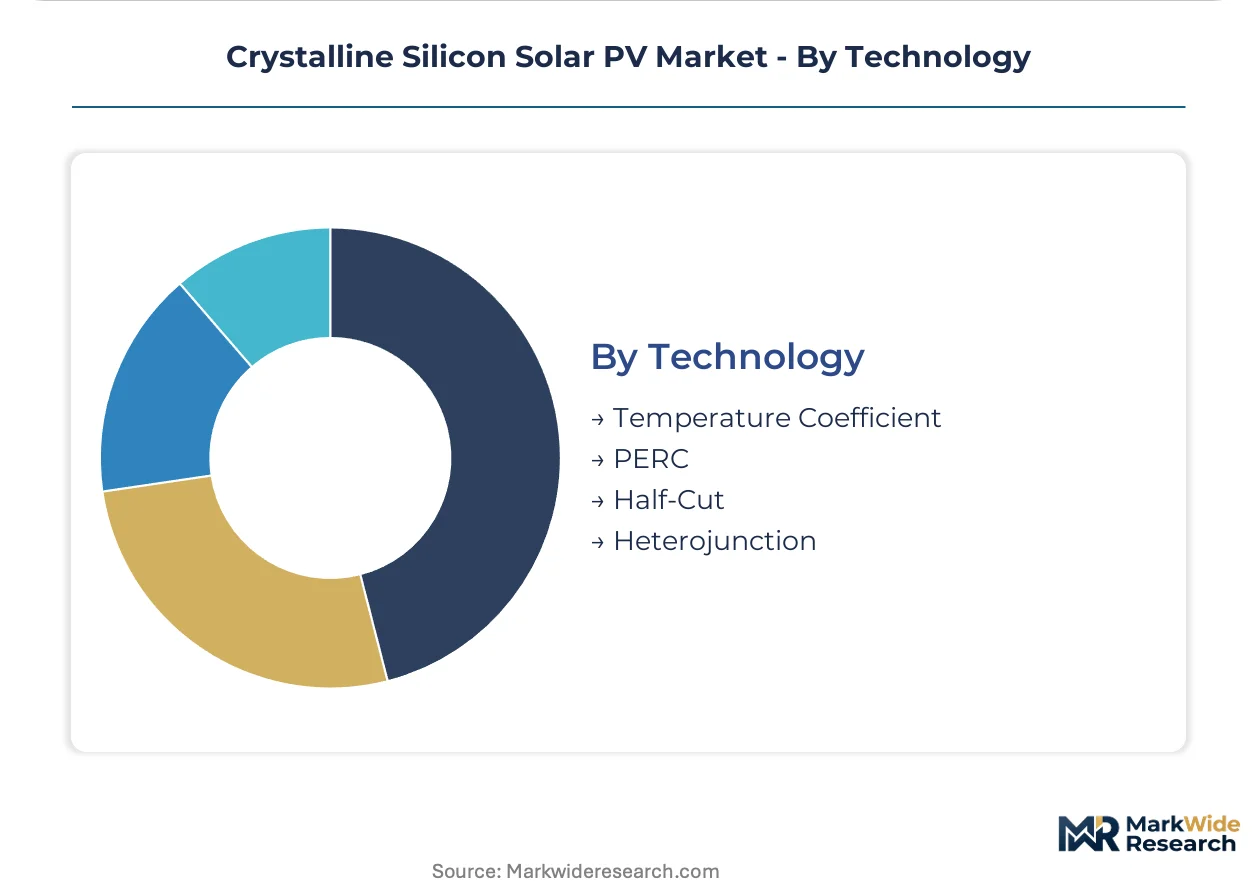
Technology:
Cell architecture selection locks in equipment depreciation schedules, with heterojunction lines requiring the newest capital deployment while PERC assets face accelerated obsolescence.
- Heterojunction:Amorphous silicon layers deposited on crystalline wafers achieve superior temperature coefficients and bifaciality ratios. Equipment suppliers in Japan and Germany anchor tool provision, though capital costs per gigawatt exceed PERC lines substantially.
- PERC:Passivated emitter and rear contact structures dominate incumbent capacity, with Chinese manufacturers in Jiangsu and Anhui provinces operating the largest installed base.
- Half-Cut:Laser-scribed wafer division reduces resistive losses and enables higher string voltages.
- Temperature Coefficient:Performance optimization for high-temperature environments drives module selection in desert climates.
PERC technology retains the largest operational footprint. Heterojunction capacity is scaling fastest as manufacturers replace deprecated equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting polysilicon-to-module production toward jurisdictions where IRA domestic content credits and EU carbon border levies create compliance-cost gaps. Manufacturers now site cell assembly in Vietnam and Thailand to preserve US market access while European buyers seek Southeast Asian provenance to reduce embodied carbon scores.
China
Jiangsu and Anhui provinces concentrate over half of global polysilicon and wafer capacity through Tongwei Solar and LONGi Green Energy Technology operations. The country's dual carbon goals under MIIT accelerate n-type cell transitions while restricting new coal-powered smelter permits. Chemical-grade silicon integration in Xuzhou and Hefei captures margin from feedstock through finished cells.
United States
Texas and Arizona utility-scale queues drive module procurement through FERC-jurisdictional interconnection backlogs exceeding three years. The IRA's domestic content bonus credits redirect supply chain geography toward North American cell assembly partnerships. Georgia and Ohio manufacturing investments target Southeast Asian wafer imports to qualify for tax credit adders.
India
Gujarat and Rajasthan anchor utility-scale deployment through CEA-mandated renewable purchase obligations. The PLI scheme for solar manufacturing attracts integrated polysilicon-to-module investments as developers face basic customs duty exposure on imported cells. Andhra Pradesh's Mundra port cluster hosts emerging cell fabrication for Middle Eastern export markets.
Vietnam
Bac Ninh and Hai Phong industrial zones absorb Chinese wafer supply for US-bound module assembly. Manufacturers leverage origin-flexible production to circumvent anti-dumping duties while preserving IRA eligibility. The northern provinces' proximity to Ha Long Bay shipping lanes compresses logistics costs for Pacific container routes.
Germany
Saxony and Brandenburg host heterojunction equipment suppliers serving EU Green Deal domestic content mandates. The Carbon Border Adjustment Mechanism imposes embodied carbon reporting on imported Chinese modules, favoring Southeast Asian cell provenance. Thuringia's legacy solar research infrastructure supports pilot lines for next-generation deposition tools.
Crystalline Silicon Solar PV Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated polysilicon producers commanding utility-scale tenders while module-only assemblers serve distributed channels. The market structures around three tiers: captive-feedstock giants, technology-licensing specialists, and regional contract fabricators. Consolidation pressures favor backward integration into polysilicon purification and wafer pulling capabilities. Strategic moves center on equipment upgrade cycles for n-type cell transitions and Southeast Asian assembly partnerships to preserve US and EU market access.
Among China-based integrated producers, LONGi Green Energy Technology and Tongwei Solar exemplify the captive-feedstock archetype through in-house polysilicon-to-module control. JA Solar occupies a position within the technology-licensing tier, competing on module efficiency specifications across bifacial product lines. These three companies represent divergent strategic postures: one anchors monocrystalline wafer supply, another dominates chemical-grade silicon integration, and the third pursues aggressive efficiency differentiation.
| Leading Market Players |
|---|
| JA Solar |
| Canadian Solar |
| JinkoSolar |
| GCL-Poly Energy Holdings |
| Hanwha Q CELLS |
| LONGi Green Energy Technology |
| Tongwei Solar |
| Risen Energy |
| Trina Solar |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers in China and India anchor supply discipline through state-coordinated capacity planning, while private-equity-rolled-up module assemblers in Southeast Asia face compressed margins as IRA domestic content bonuses and EU carbon border levies reshape procurement economics. This ownership fragmentation concentrates pricing power upstream with polysilicon purifiers and wafer pullers, while downstream assemblers compete on thin spreads.
Pricing Analysis
Distributor margin compression dominates channel economics as utility-scale developers in India and the United States negotiate direct long-term offtake contracts with integrated manufacturers. Project-based contract pricing with fixed escalation clauses separates premium monocrystalline bifacial modules from standard PERC products, while cost compression in economy-tier polycrystalline lines intensifies due to Chinese oversupply. Independent power producers exhibit lowest price sensitivity given bankability requirements, while residential installers through distributor networks face highest margin pressure.
Supply Chain Analysis
The United States IRA domestic content bonus and EU Green Deal domestic content mandates are redirecting wafer sourcing from Chinese coastal ports toward Southeast Asian assembly hubs. Polysilicon purification draws from chemical-grade silicon feedstock concentrated in China, metallurgical-grade silicon from Norway and Brazil, and crucible quartz from the United States. Single-source vulnerability concentrates in Jiangsu and Anhui province polysilicon capacity. Distribution runs through direct manufacturer-to-utility procurement for large projects and wholesale distributor networks for residential channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The crystalline silicon solar PV market functions as a geographic-arbitrage play where Southeast Asian cell assembly captures margin spreads between Chinese wafer costs and US/EU compliance premiums. Regulatory cost differentials between IRA-eligible North American content and carbon-adjusted European imports create relocation incentives.
For Market Incumbents: Lock in polysilicon-to-module integration through captive Siemens-process purification and Czochralski ingot capacity before heterojunction equipment depreciation cycles conclude. Defend against n-type technology displacement by accelerating PERC line retrofits and securing Southeast Asian assembly partnerships for US market access. Prioritize chemical-grade silicon integration to capture upstream margin. For New Entrants and Emerging Players: The price-point gap between premium heterojunction modules and economy-tier polycrystalline products creates entry space for mid-efficiency bifacial specialists. Target India's PLI scheme manufacturing incentives as the most penetrable geography given basic customs duty exposure on imported cells. Pursue engineering-procurement-construction contractor relationships as the primary go-to-market channel. For Investors and Strategic Acquirers: Valuations sit cheapest among module-only assemblers lacking captive wafer supply, presenting acquisition targets for backward integration plays. Long-term viability centers on equipment upgrade cycles and domestic content qualification across multiple jurisdictions. Watch heterojunction capacity expansion rates as the inflection signal for PERC asset obsolescence timing.| Strategic Initiative | Industry Significance |
|---|---|
| N-Type Cell Capacity Buildout | Heterojunction and TOPCon lines displace incumbent PERC capacity before depreciation cycles conclude. |
| Domestic Content Supply Chain Reconfiguration | IRA bonus credits and EU carbon border levies redirect assembly toward Vietnam, Thailand, and North America. |
| Polysilicon-to-Module Integration | Captive Siemens-process purification captures margin from chemical-grade silicon through finished cells. |
| Long-Term Power Purchase Agreement Structuring | Fixed-escalation contracts with Indian CEA and US FERC-jurisdictional utilities secure offtake volume. |
| Carbon Intensity Certification Program | Documented polysilicon provenance and renewable electricity sourcing qualifies modules for EU Green Deal compliance. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with polysilicon plant managers, utility procurement officers, EPC contractors, and heterojunction equipment suppliers with secondary validation. Bottom-up and top-down triangulation drew from customs and trade data, SEC filings of listed manufacturers, IEA and EIA energy deployment statistics, FERC interconnection queue filings, and IEC certification databases.
Historical reference periods anchored the projection horizon through verified capacity installation records and module shipment volumes across the analysis window. The analytical framework modeled segmentation across cell architecture, module form factor, application scale, and regional regulatory cluster. CAGRs derived from polynomial trend fitting of deployment trajectories, incorporating polysilicon price volatility indices and equipment depreciation schedules as industry-specific forecast inputs.
Caveats apply where trade remedy expansions, technology subsidy tier revisions, or electrochemical engineering talent scarcity could materially shift the outlook. Forecasts reflect assumptions about n-type transition timelines, domestic content qualification thresholds, and carbon border levy implementation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Slovakia Renewable Energy Market
Solar Power Systems
Fixed Tilt Solar PV Market
Solar Power Systems
Netherlands Solar Energy Market
Solar Power Systems
Chile Solar Photovoltaic (PV) Market
Solar Power Systems
India Residential Solar Inverter Market
Solar Power Systems
Asia-Pacific Solar Photovoltaic (PV) Market
Solar Power Systems
Bifacial Solar Market
Solar Power Systems
Alternative Solar Photovoltaic Technologies Market
Solar Power Systems
Portugal Solar Energy Market
Solar Power Systems
3D Printed Solar Energy Trees Market
Solar Power Systems
Solar Powered Elevator Market
Solar Power Systems
Floating Photovoltaics (FPV) Market
Solar Power Systems
Floating Solar System Market
Solar Power Systems
Boat Solar Panel Market
Solar Power Systems
Solar Cells Market
Solar Power Systems
Global Photovoltaic Glass Market