
 South America Solar Tracker Market | 2026-2036
South America Solar Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
South America Solar Tracker Market Insights
Brazilian steel fabricators and aluminum extruders is restructuring supply chains to serve tracker OEMs building localized production footprints. Nextracker Inc. anchors its regional position through high-volume manufacturing partnerships in São Paulo state. Soltec Power Holdings SA differentiates via dedicated R&D facilities in Spain that feed technology into its Brazilian assembly operations. Array Technologies Inc. competes on structural steel cost engineering tailored to Cerrado wind-load conditions.
A solar tracker is a mechanical racking system that orients photovoltaic modules toward the sun using single or dual rotational axes, typically achieving 20-45% additional energy yield versus fixed-tilt configurations through precise angular positioning algorithms. The primary commercial purpose is maximizing kilowatt-hour output per hectare in utility-scale installations where land and interconnection costs dominate project economics. Single axis systems dominate current procurement volumes across South America due to lower capex per megawatt and proven reliability in high-irradiance climates. Smart trackers incorporating sensor fusion and predictive algorithms represent the fastest-expanding technology segment as operators prioritize plant-level optimization software. Ground mounted installations command the structural margin pool given their scale economies and compatibility with the region's dominant utility procurement model.
ANEEL in Brazil enforces grid connection standards and local content thresholds that directly shape tracker sourcing decisions for projects accessing national development bank financing. INMETRO certification requirements for structural components create compliance barriers that favor established suppliers with testing infrastructure in-country. Chile's environmental impact assessment framework under the SEA regulates utility-scale solar siting and drives tracker specification toward minimal land-disturbance designs. Stakeholders must monitor evolving local content mandates and grid-code harmonization across Mercosur jurisdictions to anticipate procurement qualification shifts.
Market Dynamics
Brazil's ANEEL local content mandates are forcing tracker OEMs to reconfigure supply chains around domestic steel fabrication and aluminum extrusion capacity, compressing delivery timelines for utility-scale projects accessing BNDES financing.
Growth Catalysts
- ANEEL Local Content Thresholds:Brazil's national development bank financing rules require escalating domestic manufacturing shares, pulling tracker assembly into São Paulo state industrial corridors.
- Single-Axis Tracker Reliability:Proven performance in high-irradiance Cerrado and Atacama conditions reduces perceived technology risk for utility procurement teams.
- Net Metering Expansion:Distributed generation regulatory frameworks across Brazil's Northeast region accelerate commercial and industrial rooftop tracker adoption.
Market Restraints
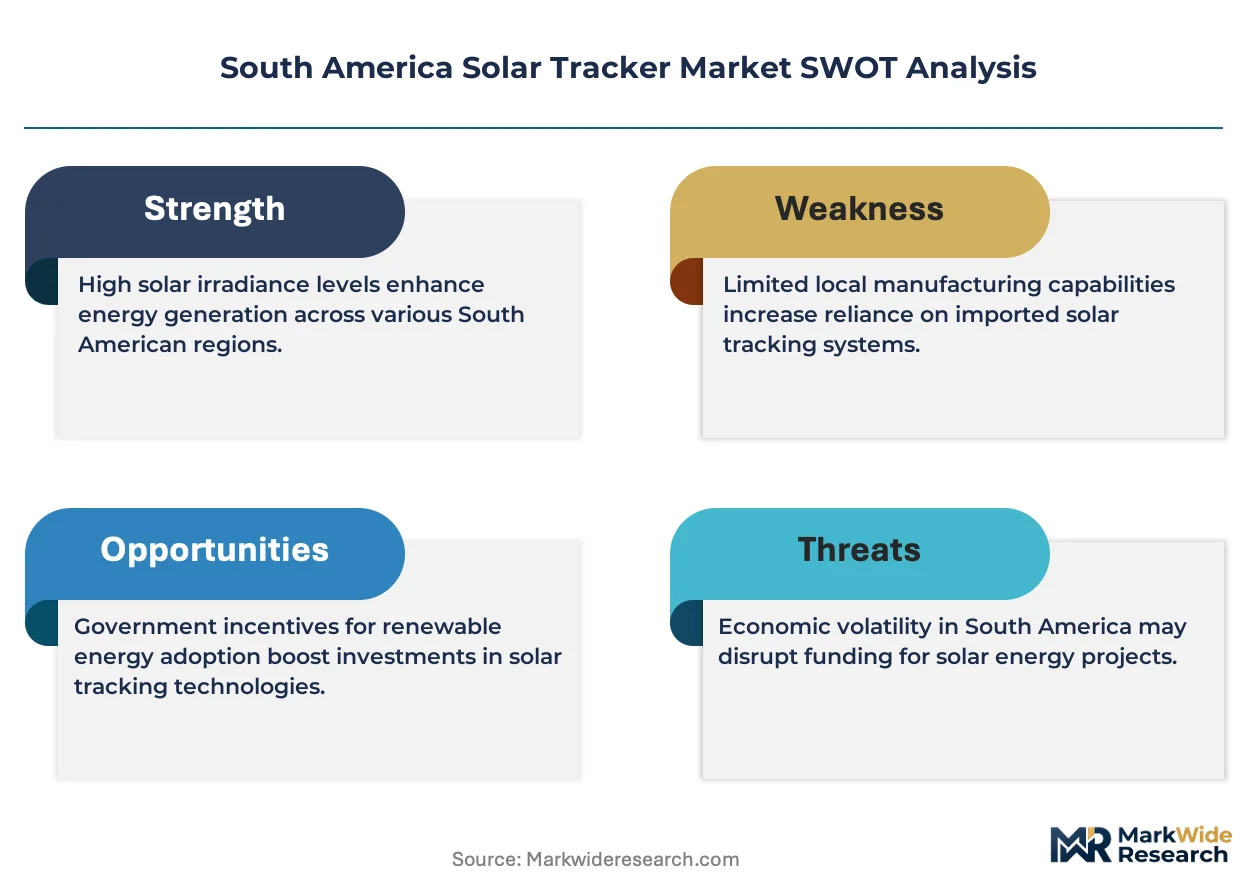
- Steel Price Volatility:Structural steel input costs fluctuate with Brazilian domestic mill capacity and import tariff cycles, squeezing tracker OEM margin structures.
- INMETRO Certification Bottlenecks:Limited in-country testing infrastructure for structural wind-load validation creates 4-6 month qualification delays for new market entrants.
- Fixed-Tilt Substitution:Low-cost fixed-racking systems from Chinese suppliers capture price-sensitive segments in Peru and Argentina where local content rules are absent.
Strategic Opportunities
- Chilean Environmental Fast-Track:SEA regulatory streamlining for low-disturbance tracker designs accelerates Atacama Desert utility project permitting timelines.
- Smart Tracker Convergence:Sensor fusion and predictive positioning algorithms create software-margin pools beyond hardware sales for plant-level optimization contracts.
- Colombian Grid Parity:Untapped solar irradiance in La Guajira and Atlántico departments awaits transmission infrastructure completion for tracker deployment.
Industry Challenges
- Wind-Load Engineering Talent Scarcity:Specialized structural analysis capabilities for Cerrado gust conditions concentrate among São Paulo and Belo Horizonte engineering consultancies.
- Supply Chain Reconfiguration Friction:Aluminum extrusion qualification with new Brazilian Tier-2 suppliers demands 12-18 month quality assurance cycles for tracker OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Solar Tracker Market |
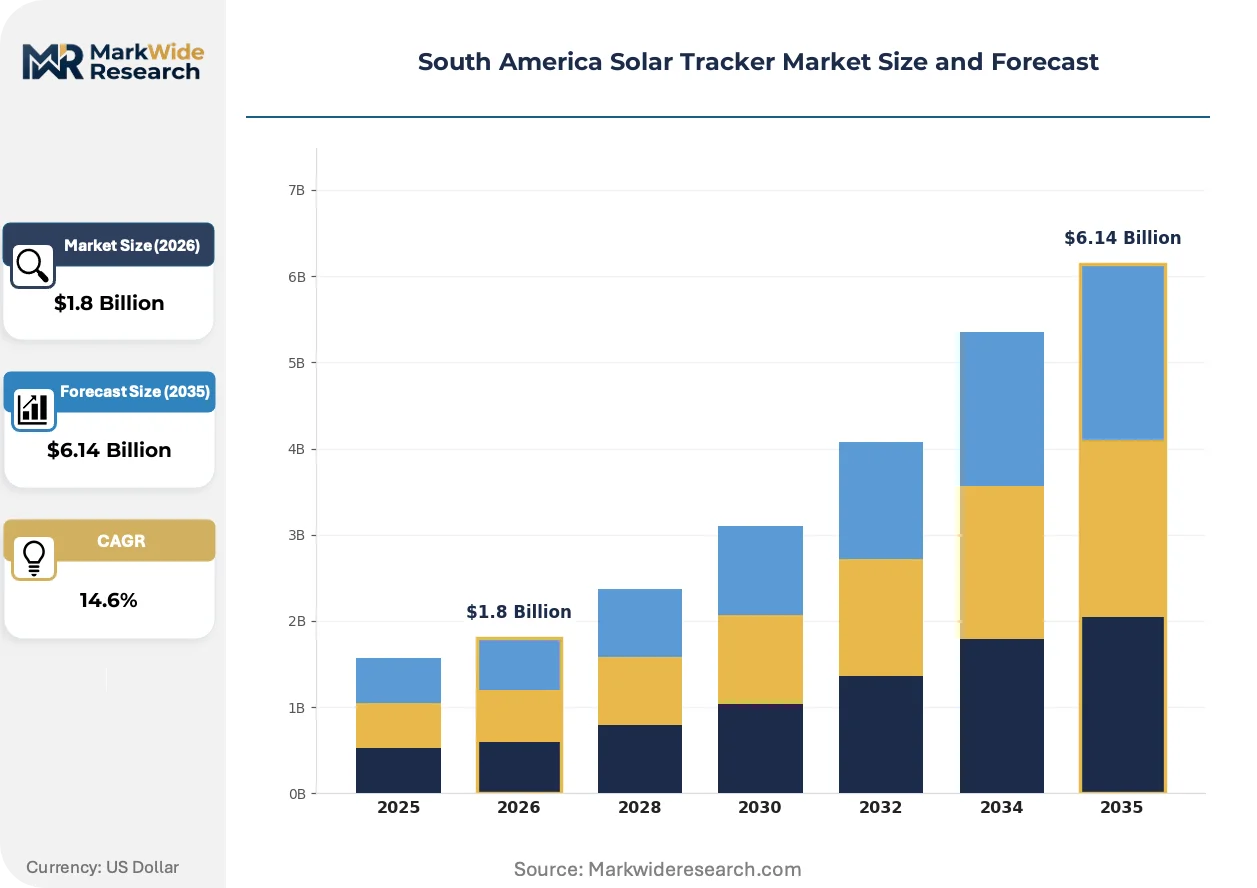
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Axis, Dual Axis, Bifacial, Fixed Tilt End User: Utilities, Commercial, Residential, Industrial Technology: Active Tracking, Passive Tracking, Hybrid Systems, Smart Trackers Installation Type: Ground Mounted, Rooftop, Carport, Floating |
| Companies Covered | Arctech Solar Holding Co. Ltd, Nextracker Inc., Soltec Power Holdings SA, Ideematec Deutschland GmbH, MecaSolar, Solar Steel, Array Technologies Inc., PV Hardware, GameChange Solar, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Solar Tracker Market Trends and Innovations
Tracker technology is converging with plant-level digital infrastructure, creating new value capture mechanisms beyond mechanical hardware. Software-defined optimization and regulatory compliance automation are reshaping competitive differentiation.
Self-calibrating tracker arrays using machine vision and edge computing is integrating predictive maintenance protocols directly into control firmware. Brazilian utility-scale developers operating in remote Cerrado locations deploy these systems to minimize technician dispatch frequency. The technology is integrating operational expenditure compression into long-term power purchase agreement economics.
Chile's SEA environmental impact assessment framework is tightening land-use efficiency standards for utility-scale solar siting. Developers must now demonstrate minimal soil disturbance and reversible foundation designs to secure construction permits. Tracker OEMs are responding with low-pile-count structural systems and modular ballast configurations for rocky Atacama terrain.
Utility procurement teams in Brazil's Northeast are unbundling tracker hardware from engineering-procurement-construction contracts to negotiate direct OEM relationships. This disintermediation compresses distributor margins while accelerating technical specification alignment between tracker suppliers and project developers. The pattern is most pronounced in Pernambuco and Ceará states where major IPPs maintain dedicated sourcing teams.
South America Solar Tracker Market Segmentation
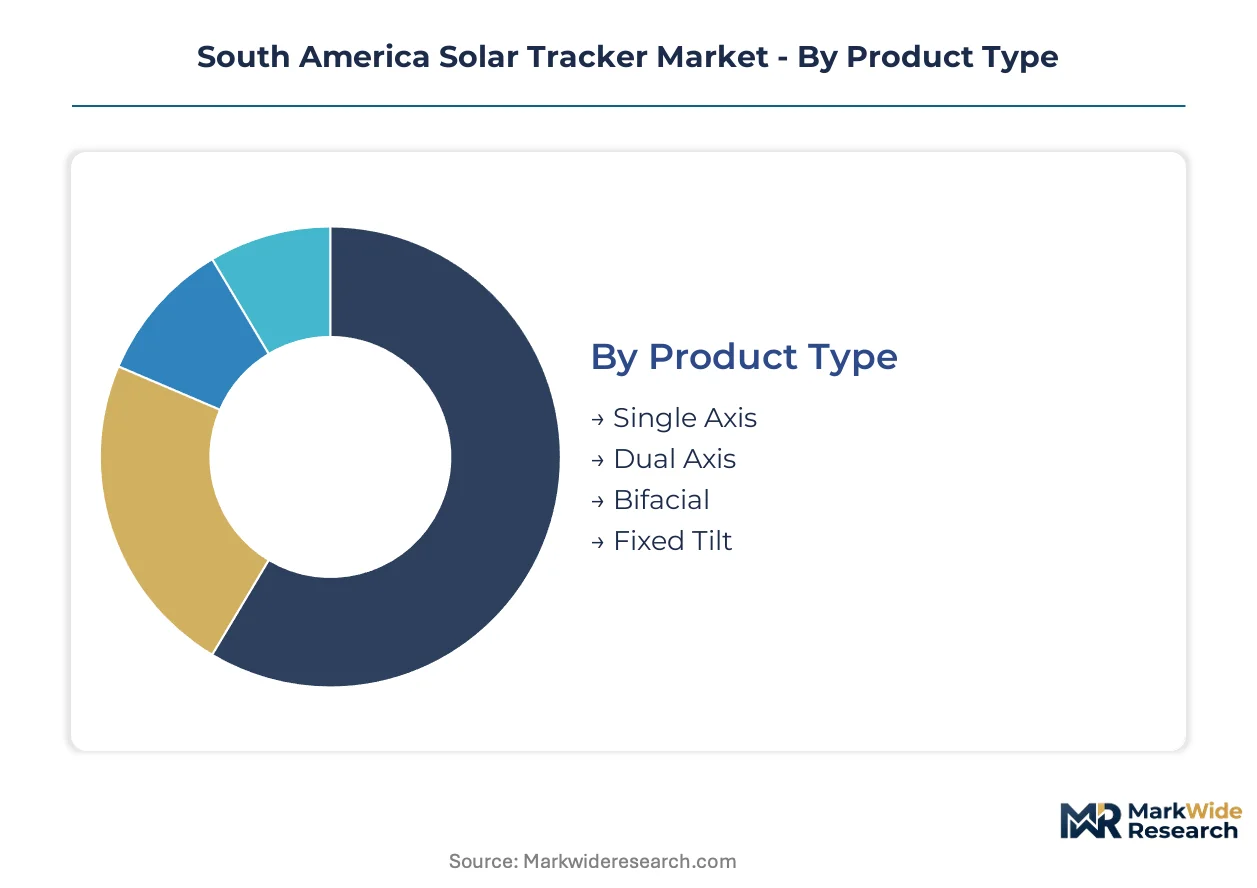
Segmentation reveals how tracker OEMs allocate engineering resources across divergent technical requirements and procurement economics. Product architecture choices cascade through installation logistics, maintenance protocols, and financing structures.
Product Type:
Supply concentration in São Paulo state steel fabrication corridors favors designs that minimize custom extrusion requirements.
- Single Axis:One rotational degree of freedom tracks east-west solar azimuth through torque tube and bearing assemblies. Brazilian Northeast utilities in Pernambuco and Ceará specify these for 100+ MW plants where proven reliability under Cerrado wind loads outweighs marginal yield gains from more complex architectures.
- Dual Axis:Azimuth-elevation tracking maximizes direct normal irradiance capture through independent rotational motors. Atacama Desert developers in Chile deploy these where land constraints and premium PPA pricing justify higher capex per megawatt.
- Bifacial:Tracker structures optimized for rear-side irradiance capture through elevated ground clearance and reflective ground cover compatibility.
- Fixed Tilt:Stationary racking without tracking mechanics captures price-sensitive demand in Peru and Argentina where local content mandates are absent.
Today's leader: Single Axis. Tomorrow's challenger: Bifacial.
End User:
Procurement scale and financing sophistication create distinct specification patterns across customer categories.
- Utilities:Centralized procurement teams at Brazilian IPPs negotiate direct OEM relationships for multi-hundred-megawatt portfolios. ANEEL local content thresholds and BNDES financing access dominate sourcing criteria.
- Commercial:Distributed generation operators in Brazil's Northeast net metering framework prioritize rapid installation and minimal shading footprint on constrained rooftop and ground-mount sites.
- Residential:Individual system owners rarely specify trackers given structural load concerns and maintenance access limitations on single-family installations.
- Industrial:Self-consumption projects at mining and manufacturing facilities in Minas Gerais and São Paulo states balance yield optimization against production continuity risks.
Procurement gravity centers on Utilities. Commercial is expanding most quickly under net metering expansion.
Technology:
Control system architecture determines software margin capture potential beyond mechanical hardware sales.
- Active Tracking:Motor-driven positioning via GPS-synchronized astronomical algorithms dominates utility-scale deployments for precision and predictability.
- Passive Tracking:Thermal or hydraulic actuation without electrical control suits off-grid and remote applications with limited maintenance access.
- Hybrid Systems:Combined astronomical and sensor-feedback positioning balances computational efficiency with real-time irradiance optimization.
- Smart Trackers:Machine vision and edge computing enable predictive maintenance and autonomous calibration. These are gaining share fastest as Brazilian Cerrado operators minimize technician dispatch frequency.
Active Tracking anchors current volume. Smart Trackers represent the steepest expansion trajectory.
Installation Type:
Foundation engineering and labor mobilization requirements vary sharply across mounting configurations.
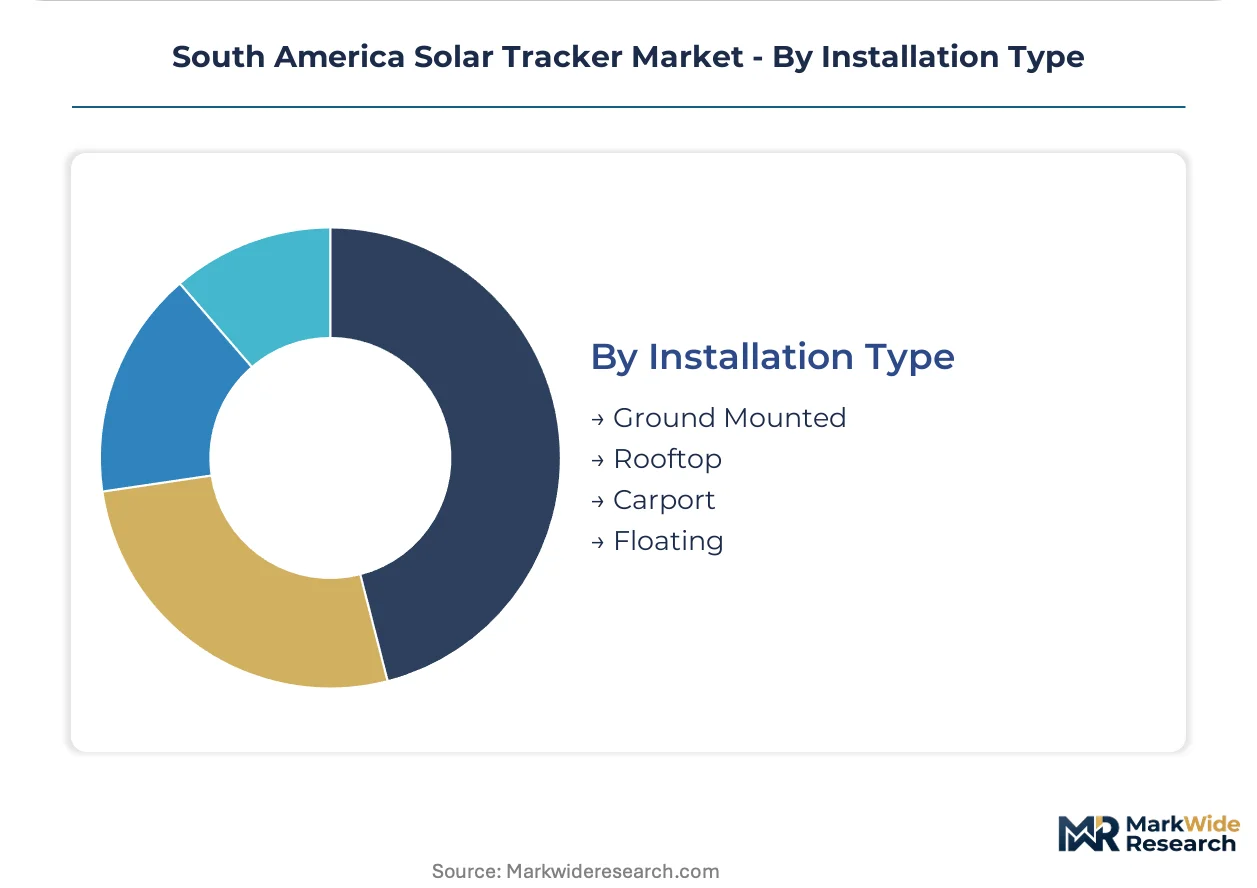
- Ground Mounted:Pile-driven or ballasted foundations for utility-scale arrays command the structural margin pool through scale economies and compatibility with dominant procurement models in Brazil and Chile.
- Rooftop:Ballasted or attached systems for commercial and industrial buildings face load-bearing constraints and shading complexity that limit tracker applicability.
- Carport:Dual-purpose canopy structures over parking areas integrate solar generation with shade provision in urban commercial settings.
- Floating:Pontoon-mounted arrays for hydropower reservoir and mining tailings pond applications remain nascent in South America pending specialized structural validation.
Ground Mounted defines current economics. Floating awaits transmission infrastructure completion in Colombian and Brazilian hydroelectric zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tracker OEMs face divergent compliance costs across South American jurisdictions. Brazil's local content mandates pull assembly capacity into São Paulo industrial corridors, while Chile's environmental fast-track creates permitting arbitrage for low-disturbance designs.
Brazil
ANEEL net metering expansion and BNDES financing access drive procurement in Pernambuco and Ceará states. The regulator enforces escalating domestic manufacturing thresholds for development bank loans. São Paulo state hosts steel fabrication partnerships serving multi-hundred-megawatt utility portfolios.
Chile
Atacama Desert irradiance and premium PPA pricing justify dual-axis tracker capex premiums. SEA environmental impact assessments mandate minimal soil disturbance and reversible foundations. Antofagasta and Calama sub-regions concentrate project development activity.
Colombia
La Guajira and Atlántico departments hold untapped solar resource potential awaiting transmission completion. The national mining and energy planning unit regulates grid interconnection queues. Barranquilla industrial zones position for tracker assembly once infrastructure matures.
Argentina
Absence of local content mandates exposes the market to fixed-tilt substitution from Chinese suppliers. Jujuy and Salta provinces in the Northwest concentrate early-stage solar development. Mendoza's wine industry clusters explore commercial self-consumption with minimal tracker penetration.
Peru
Price-sensitive procurement in Arequipa and Moquegua regions favors low-cost fixed-racking over tracking systems. The Ministry of Energy and Mines oversees distributed generation regulations. Mining sector self-supply projects in the southern corridor represent niche tracker demand.
South America Solar Tracker Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bifacial-optimized structural designs. The market exhibits moderate concentration with three to five dominant assembly footprints serving Brazil and Chile. Archetypes include integrated steel-and-control OEMs, specialized structural fabricators, and software-centric smart tracker specialists. Competitive moves center on São Paulo state manufacturing partnerships and predictive maintenance software licensing.
Among the named players, Nextracker Inc. and Soltec Power Holdings SA exemplify scale-driven OEMs with regional assembly presence, while Array Technologies Inc. occupies a position emphasizing structural cost engineering for high-wind applications. Arctech Solar Holding Co. Ltd represents Chinese-origin fabricators competing on capital efficiency. Ideematec Deutschland GmbH anchors European-engineered precision positioning systems. GameChange Solar and PV Hardware sit within the mid-tier specialist category serving project-specific procurement channels.
| Leading Market Players |
|---|
| Arctech Solar Holding Co. Ltd |
| Nextracker Inc. |
| Soltec Power Holdings SA |
| Ideematec Deutschland GmbH |
| MecaSolar |
| Solar Steel |
| Array Technologies Inc. |
| PV Hardware |
| GameChange Solar |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed development bank financing through BNDES has concentrated tracker procurement among Brazilian utilities with stringent ANEEL local content thresholds, compressing distributor margins while elevating steel fabrication partnerships to strategic pricing leverage points for assembly-scale OEMs.
Pricing Analysis
Distributor margin compression dominates channel economics as Brazilian IPPs in Pernambuco and Ceará states unbundle tracker hardware from EPC contracts to negotiate direct OEM relationships. Project-based transactional pricing anchored to steel input cost indices stratifies across premium smart-tracker configurations, standard single-axis torque-tube assemblies, and economy fixed-tilt alternatives. Cost compression in the standard tier intensifies as Chinese-origin fabricators without local content compliance capture price-sensitive Argentine and Peruvian demand. Commercial net-metering operators exhibit highest price sensitivity due to constrained rooftop footprints and rapid payback requirements, while Atacama Desert utilities absorbing dual-axis premiums demonstrate lowest sensitivity.
Supply Chain Analysis
ANEEL escalating domestic manufacturing thresholds are restructuring sourcing around São Paulo state steel fabrication corridors and emerging aluminum extrusion partnerships. Structural steel and control electronics draw from Brazilian domestic mill capacity and East Asian semiconductor supply chains respectively. Single-source vulnerability concentrates in torque-tube bearing assemblies qualified for Cerrado wind-load conditions. Distribution runs through direct OEM relationships with utility procurement teams, bypassing traditional distributor networks in Brazil's Northeast.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's solar tracker market represents a late-cycle quality story as utility procurement shifts toward smart-tracker configurations with predictive maintenance software and sensor-fusion positioning algorithms commanding premium pricing over commodity hardware.
For Market Incumbents: Acquire specialized wind-load engineering consultancies in São Paulo and Belo Horizonte to internalize scarce structural analysis capabilities for Cerrado gust conditions. Consolidate aluminum extrusion partnerships through equity stakes in Tier-2 Brazilian suppliers, compressing 12-18 month qualification cycles that currently constrain assembly capacity expansion. Fixed-tilt substitution from Chinese fabricators in Argentina and Peru threatens margin structures in price-sensitive segments. For New Entrants and Emerging Players: Machine vision-enabled self-calibrating arrays offer a technology-first wedge into Brazilian Cerrado utility portfolios where technician dispatch frequency drives operational expenditure compression. Target Colombian La Guajira and Atlántico departments ahead of transmission infrastructure completion, positioning for first-mover tracker deployment once grid interconnection queues clear. Pursue software-licensing partnerships with established EPC contractors lacking in-house plant-level optimization capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier structural fabricators without smart-tracker software stacks but with established INMETRO certification infrastructure. Long-term viability across the analysis window hinges on convergence between mechanical hardware margins and recurring software revenue streams. Watch ANEEL local content threshold escalations as the inflection signal determining which assembly footprints qualify for BNDES financing access.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Tracker Software Licensing | Predictive maintenance algorithms create recurring revenue beyond hardware sales for Brazilian Cerrado operators. |
| Backward Integration into Steel Fabrication | São Paulo state manufacturing partnerships secure ANEEL compliance and compress delivery timelines for utility portfolios. |
| INMETRO Certification Infrastructure Investment | In-country testing capacity eliminates 4-6 month qualification delays that currently barrier new market entrants. |
| Low-Disturbance Foundation System Development | Modular ballast configurations accelerate Chile SEA permitting timelines for Atacama Desert rocky terrain. |
| Direct OEM-Utility Procurement Relationships | Disintermediation of EPC distributors captures margin compression while aligning technical specifications with IPP requirements. |
Research Methodology
Bottom-up utility procurement modeling reconciled against top-down tracker assembly capacity tracking forms the analytical core of this study. Primary interviews with Brazilian IPP project developers, EPC contract managers, ANEEL regulatory affairs officers, and São Paulo state steel fabrication plant directors combined with secondary validation from BNDES financing disclosure databases, ANEEL distributed generation interconnection records, and Chile SEA environmental impact assessment filings. Cross-referencing bottom-up project pipeline data against top-down OEM production footprints triangulates volume estimates.
Input-output matrices map tracker deployment capacity against steel fabrication throughput, aluminum extrusion qualification cycles, and control system electronics supply. Segmentation dimensions span product architecture, end-user procurement scale, control technology sophistication, and installation foundation type. CAGRs derive from regression analysis across historical deployment trajectories and projected utility-scale procurement schedules. Forecast inputs incorporate ANEEL local content threshold escalation timelines and Chile SEA regulatory streamlining protocols.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Brazilian steel price volatility cycles and transmission infrastructure completion delays in Colombian departments. Projections reflect assumptions around ANEEL regulatory continuity and BNDES financing availability without anticipating Mercosur grid-code harmonization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Global Concentrating Solar Power Market
Solar Power Systems
Solar Appliances Market
Solar Power Systems
Denmark Solar Energy Market
Solar Power Systems
Europe Solar Photovoltaic (PV) Market
Solar Power Systems
United States Fixed-Tilt Solar PV Market
Solar Power Systems
Portugal Distributed Solar Energy Market
Solar Power Systems
United Arab Emirates Solar Energy Market
Solar Power Systems
Switzerland Solar Energy Market
Solar Power Systems
Smart Solar Tracker Market
Solar Power Systems
Solar Skin Market
Solar Power Systems
France Solar Energy Market
Solar Power Systems
India Residential Solar Inverter Market
Solar Power Systems
Solar Module Racking Market
Solar Power Systems
Global Rooftop Solar Photovoltaic Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Skylights Market
Solar Power Systems
New Zealand Solar Energy Market