
 Flexible Parylene-Based Solar Cells Market | 2026-2036
Flexible Parylene-Based Solar Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Parylene-Based Solar Cells Market Foresight
Poland is narrowing its thin-film manufacturing gap through Saule Technologies' perovskite-parylene pilot lines in Wrocław. Heliatek GmbH leverages organic photovoltaic expertise to sustain Dresden's position in tandem cell development. Ascent Solar Technologies anchors US defense supply chains with flexible CIGS-parylene modules for unmanned aerial systems.
Flexible parylene-based solar cells integrate vapor-deposited poly-para-xylylene films as conformal barrier layers atop photovoltaic active stacks, achieving sub-10-micron encapsulation with water vapor transmission rates below 10^-6 g/m²/day for moisture-sensitive perovskite and organic chemistries. Their primary purpose is to deliver bendable, lightweight power generation for surfaces incompatible with rigid glass-glass modules. Thin-film product architecture leads commercial shipments due to inherent compatibility with roll-to-roll parylene deposition, while tandem cells represent the fastest-growing segment as efficiency stacking justifies higher coating costs. Aerospace applications command premium positioning because orbital radiation hardness requirements favor parylene's atomic oxygen resistance over polymer alternatives.
REACH compliance in Europe restricts halogenated encapsulants, accelerating parylene substitution in export-bound modules. The EU AI Act and CSRD reporting obligations are forcing photovoltaic OEMs to document supply chain carbon intensity, favoring localized parylene deposition over imported fluoropolymer films. Stakeholders must monitor how ECHA substance evaluation timelines affect parylene dimer purity standards and whether FDA device-grade coating certifications open wearable electronics pathways beyond consumer markets.
Market Dynamics
REACH compliance deadlines and the EU F-Gas Regulation are structurally displacing fluoropolymer encapsulants, forcing photovoltaic OEMs to requalify supply chains around parylene chemistry before the 2027 substance evaluation window closes.
Growth Catalysts
- Orbital weight mandates:Aerospace procurement specifications now penalize every gram of solar array mass, driving satellite operators toward sub-10-micron parylene barriers that glass cannot match.
- Perovskite moisture sensitivity:Water vapor transmission rates below 10^-6 g/m²/day are becoming non-negotiable for next-generation active layers, and only vapor-deposited poly-para-xylylene achieves this without thermal damage.
- EU Green Deal manufacturing incentives:Production tax credits for low-carbon photovoltaic assembly in Germany and Poland are concentrating thin-film capacity where localized parylene deposition reduces transport emissions.
Market Restraints
- Dimer feedstock oligopoly:Specialty chemical production of parylene precursor monomers concentrates in two US and Japanese suppliers, exposing coaters to allocation risk during semiconductor demand spikes.
- Batch deposition throughput ceilings:Vacuum chamber cycling limits roll-to-roll coating speeds to fractions of fluoropolymer lamination lines, constraining unit economics at gigawatt-scale module demand.
- Atomic oxygen test standard gaps:Absence of IEC-qualified accelerated aging protocols for orbital radiation hardness forces satellite prime contractors to fund proprietary qualification campaigns that extend sales cycles.
Strategic Opportunities
- Wearable electronics power integration:FDA device-grade coating certifications for parylene biocompatibility could unlock medical patches and continuous glucose monitors as addressable demand beyond aerospace and building-integrated photovoltaics.
- Tandem cell architecture penetration:Efficiency stacking of perovskite-silicon and organic-inorganic junctions justifies premium encapsulation costs that single-junction modules cannot bear.
- Defense unmanned systems procurement:US FAA and DoD specifications for flexible power on small unmanned aerial vehicles are creating sole-source pathways for domestic parylene-coated CIGS suppliers.
Industry Challenges
- Vacuum coating technician scarcity:Specialized vapor deposition expertise resides in semiconductor and optical coating industries, forcing photovoltaic entrants to poach talent or fund 18-month training programs.
- Multi-standard certification stacking:Modules must sequentially qualify under REACH substance restrictions, CE marking electromagnetic compatibility, and customer-specific orbital outgassing tests, extending time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Parylene-Based Solar Cells Market |
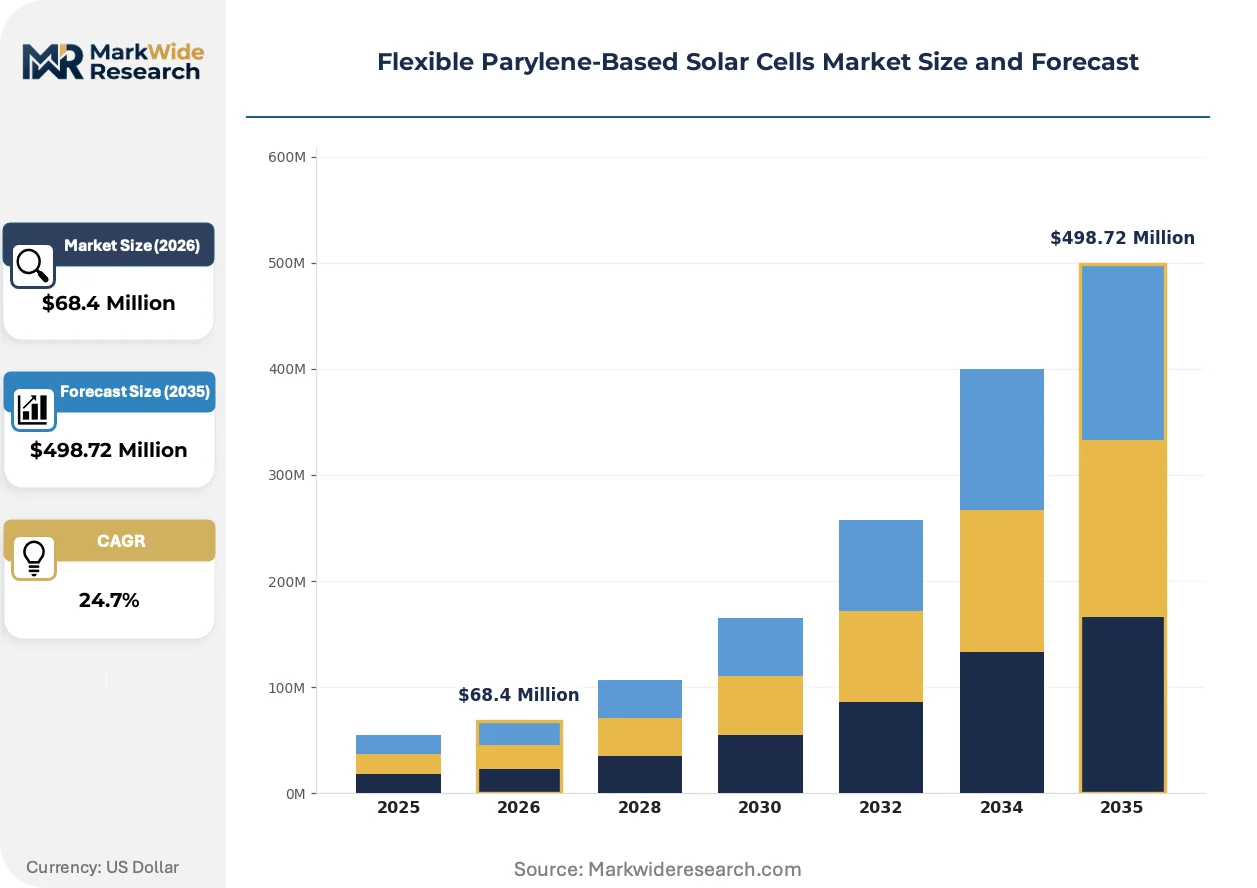
| Market Size in 2026 | $68.4 Million |
| Market Size in 2035 | $498.72 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Tandem Cells, Perovskite, Amorphous Silicon Technology: Parylene Coating, Organic Photovoltaic, Dye-Sensitized, Copper Indium Gallium Selenide, Quantum Dot, Multi-Junction Application: Wearable Electronics, Aerospace Power, Portable Chargers, Building-Integrated Systems, Consumer Devices, Military Equipment End User: Electronics Manufacturers, Defense Contractors, Consumer Electronics, Aerospace Firms, Telecommunications Providers, Research Institutions |
| Companies Covered | Saule Technologies, Heliatek GmbH, Oxford PV, Ascent Solar Technologies, Hanergy, MiaSolé, Flisom AG, Fab Solar, Swift Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Parylene-Based Solar Cells Market Shifts & Advancements
Atomic layer deposition hybridization and roll-to-roll chamber redesigns are compressing the cost gap between parylene barriers and incumbent fluoropolymer films, while regulatory carbon accounting forces supply chain regionalization.
Roll-to-roll parylene deposition is collapsing the historical throughput disadvantage against batch vacuum processing. Satellite solar array manufacturers in Germany and the US are adopting continuous-coating pilot lines that halve chamber idle time. This equipment transition is collapsing the capital cost per square meter of barrier film, enabling parylene to compete on price with ethylene-tetrafluoroethylene laminates in terrestrial building-integrated applications.
The EU F-Gas Regulation phasedown of hydrofluorocarbon blowing agents and perfluorinated polymer feedstocks is restricting fluoropolymer film availability for export-bound photovoltaic modules. European OEMs are responding by qualifying parylene encapsulation for their entire product portfolios ahead of the 2030 quota tightening. This regulatory displacement is most acute in Germany, where Heliatek and Flisom AG anchor thin-film production clusters dependent on EU-sourced materials.
Buyer concentration among satellite prime contractors is compressing vendor qualification timelines from 36 months to 18 months. Lockheed Martin and Airbus Defence and Space are unbundling solar array procurement from satellite platform contracts, creating direct purchasing relationships with parylene coaters. This disintermediation is most visible in the US defense supply chain, where Ascent Solar Technologies has secured sole-source status for flexible CIGS-parylene modules on classified unmanned aerial programs.
Flexible Parylene-Based Solar Cells Market Segmentation
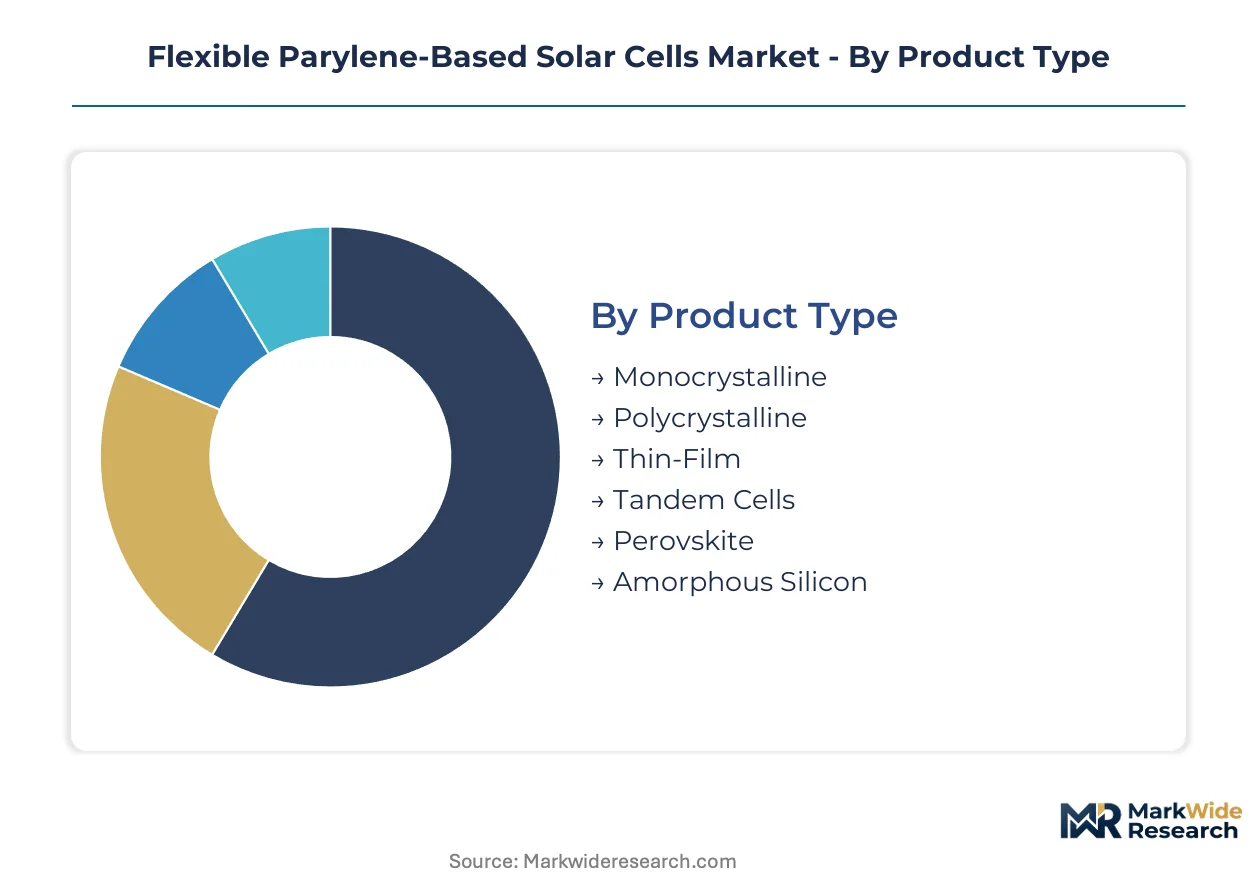
Segmentation in flexible parylene-based solar cells reveals how encapsulation chemistry aligns with distinct performance requirements across photovoltaic architectures. Each dimension—product type, technology, application, and end user—exposes different tolerance thresholds for barrier thickness, bending radius, and moisture protection that determine coating process selection.
Product Type:
Mature crystalline formats coexist with emerging thin-film stacks in this segmentation, revealing a technology transition where parylene deposition economics favor certain active layer chemistries over others.
- Monocrystalline:Silicon wafers with parylene edge-sealing achieve bendability through kerfless slicing, though efficiency premiums concentrate demand in German building-integrated installations where aesthetic constraints override cost sensitivity.
- Thin-Film:Roll-to-roll compatibility makes this the dominant commercial format; cadmium telluride and copper indium gallium selenide stacks accept conformal parylene barriers without thermal degradation, anchoring production clusters in Dresden and Wrocław.
- Tandem Cells:Efficiency stacking justifies premium encapsulation costs in aerospace procurement.
- Perovskite:Moisture sensitivity below 10^-6 g/m²/day water vapor transmission mandates parylene chemistry.
- Polycrystalline:Cost-sensitive terrestrial applications favor thicker polymer alternatives.
- Amorphous Silicon:Low-temperature deposition compatibility suits portable charger formats.
Thin-Film retains volume leadership; Tandem Cells holds the steepest expansion curve.
Technology:
Cost tier differentiation separates vapor-deposited barrier approaches from solution-processed alternatives, with parylene chemistry occupying the premium qualification tier for mission-critical deployments.
- Parylene Coating:Vapor-deposited poly-para-xylylene films achieve sub-10-micron conformal coverage with atomic oxygen resistance; satellite prime contractors in Germany and the US specify this chemistry for orbital radiation hardness requirements that fluoropolymers cannot satisfy.
- Copper Indium Gallium Selenide:CIGS active layers pair with parylene encapsulation in defense unmanned aerial systems; Ascent Solar Technologies anchors US supply chains with sole-source status for flexible modules meeting FAA and DoD specifications.
- Multi-Junction:III-V semiconductor stacks command highest efficiency premiums in aerospace.
- Organic Photovoltaic:Heliatek GmbH leverages Dresden manufacturing for tandem organic-parylene development.
- Dye-Sensitized:Niche research applications dominate commercial traction.
- Quantum Dot:Emerging active layer chemistry pending barrier qualification protocols.
Parylene Coating captures the premium tier; Multi-Junction is expanding most quickly in defense procurement.
Application:
Customer type concentration varies sharply across application segments, with aerospace procurement specifications driving qualification investments that later cascade into consumer electronics adaptations.
- Aerospace Power:Orbital weight mandates penalize every gram of solar array mass; sub-10-micron parylene barriers from German and US coaters displace glass-glass modules in Lockheed Martin and Airbus Defence and Space procurement.
- Wearable Electronics:FDA device-grade coating certifications for parylene biocompatibility unlock medical patches and continuous glucose monitors; conformal encapsulation accommodates skin-contact bending radii incompatible with rigid barriers.
- Military Equipment:Classified unmanned aerial programs specify domestic parylene-coated CIGS supply chains.
- Building-Integrated Systems:EU F-Gas Regulation phasedown accelerates parylene substitution for fluoropolymer films in German and Polish installations.
- Portable Chargers:Consumer price sensitivity limits parylene adoption to premium outdoor formats.
- Consumer Devices:Volume scale favors faster polymer lamination throughput.
Aerospace Power dominates revenue concentration; Wearable Electronics is gaining share fastest through medical device certifications.
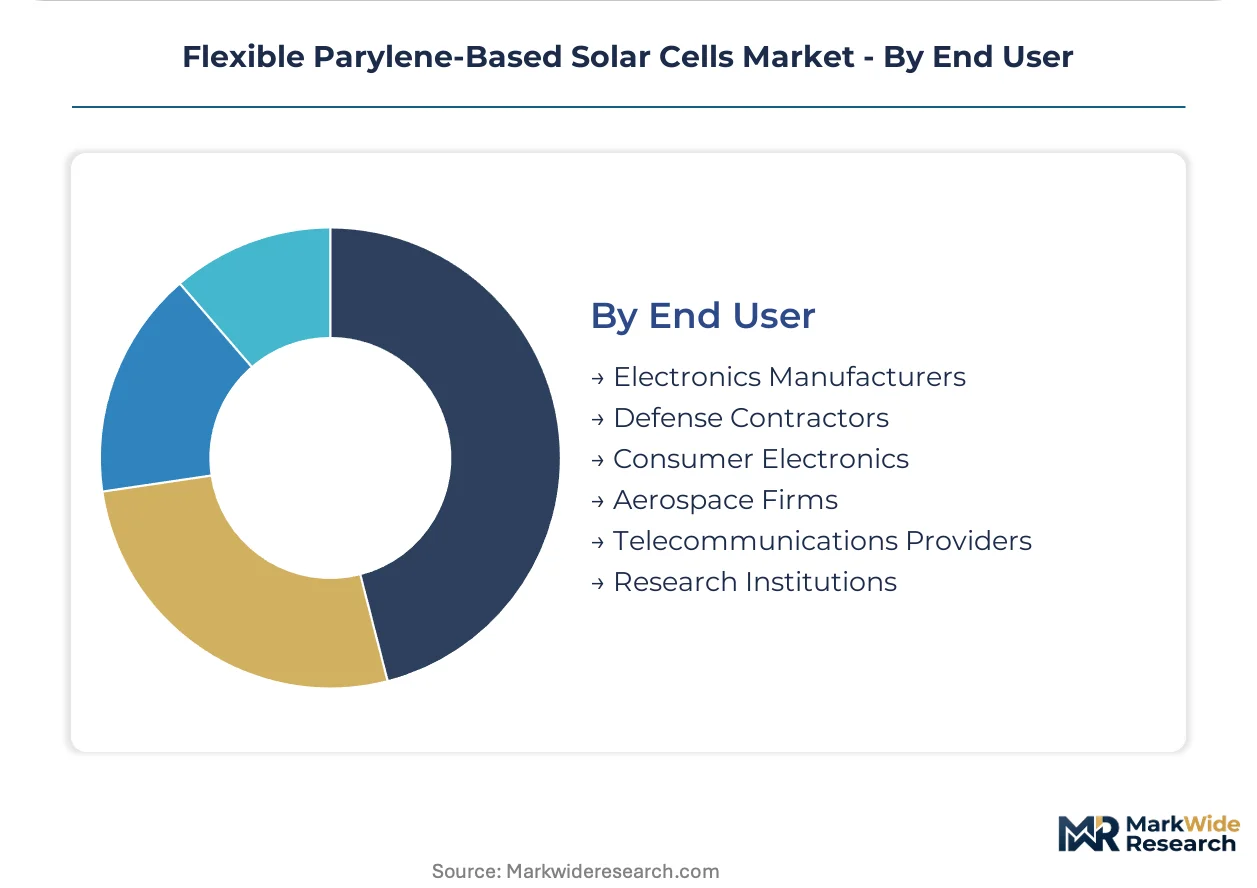
End User:
Supply concentration patterns reveal how defense and aerospace procurement unbundling is creating direct purchasing relationships that bypass traditional module integrators.
- Defense Contractors:US DoD specifications for flexible power on small unmanned aerial vehicles concentrate demand with domestic coaters meeting ITAR compliance; sole-source pathways favor Ascent Solar Technologies for CIGS-parylene modules.
- Aerospace Firms:Satellite prime contractors compress vendor qualification timelines from 36 months to 18 months; disintermediation of solar array procurement from platform contracts creates direct relationships with parylene deposition specialists.
- Electronics Manufacturers:REACH compliance deadlines force requalification around parylene chemistry.
- Consumer Electronics:Price pressure maintains fluoropolymer dominance in high-volume formats.
- Telecommunications Providers:Remote power applications favor established glass-glass reliability.
- Research Institutions:Perovskite-parylene pilot lines in Polish facilities supply experimental volumes.
Defense Contractors anchor premium pricing; Aerospace Firms show the steepest procurement reform trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH and the EU F-Gas Regulation anchor European regulatory gravity, while US defense procurement and Asian manufacturing scale create complementary demand poles. Satellite weight mandates and perovskite moisture sensitivity concentrate investment in Germany, the United States, Poland, Japan, and China.
United States
Defense procurement specifications for unmanned aerial systems drive flexible module demand. FAA and DoD requirements for ITAR-compliant domestic supply chains favor localized parylene deposition. Ascent Solar Technologies anchors Colorado-based production for classified military programs.
Germany
EU Green Deal production tax credits concentrate thin-film capacity in Saxony. Heliatek GmbH leverages Dresden manufacturing clusters for organic photovoltaic-parylene tandem development. ECHA substance evaluation timelines force coaters to requalify dimer purity standards ahead of 2027 deadlines.
Poland
Saule Technologies operates perovskite-parylene pilot lines in Wrocław, narrowing the thin-film manufacturing gap with Western Europe. EU F-Gas Regulation phasedown accelerates substitution away from fluoropolymer encapsulants. Regional funding from the European Regional Development Bank supports deposition equipment upgrades.
Japan
METI technology roadmaps prioritize lightweight space power systems for lunar exploration missions. Japanese satellite prime contractors specify atomic oxygen-resistant barriers for low-earth orbit constellations. Specialized chemical suppliers in Osaka and Tokyo prefectures control parylene dimer precursor production.
China
Dual carbon goals and GB standards for building-integrated photovoltaics create terrestrial demand for conformal encapsulation. Domestic deposition equipment manufacturers in Jiangsu and Zhejiang provinces compress coating cost curves. State-backed aerospace programs test parylene barriers for satellite export competitiveness.
Flexible Parylene-Based Solar Cells Market Competitive Landscape
Capability concentration sits with specialty coaters possessing vapor deposition expertise; scale advantage sits with thin-film module integrators with roll-to-roll infrastructure. The market structures around three archetypes: aerospace-qualified deposition specialists, organic photovoltaic technology developers, and defense-anchored CIGS suppliers. Competitive moves center on sole-source procurement pathway capture and tandem cell architecture qualification ahead of efficiency stacking adoption.
Among European technology developers, Heliatek GmbH and Saule Technologies occupy positions within the organic and perovskite-parylene integration tier. Ascent Solar Technologies represents the defense-anchored archetype with US-based flexible CIGS production. These three companies exemplify how geographic regulatory alignment—REACH compliance in Europe, ITAR requirements in the United States—shapes competitive positioning without requiring identical technical approaches.
| Leading Market Players |
|---|
| Saule Technologies |
| Heliatek GmbH |
| Oxford PV |
| Ascent Solar Technologies |
| Hanergy |
| MiaSolé |
| Flisom AG |
| Fab Solar |
| Swift Solar |
| Others |
Supply & Pricing Matrix
Undercapacity in Japanese parylene dimer production is forcing German and US coaters to accept allocation-based pricing terms, compressing margins for thin-film module integrators while concentrating bargaining power with Osaka and Tokyo specialty chemical suppliers.
Pricing Analysis
German aerospace procurement commands premiums exceeding Polish building-integrated installations by substantial margins. Pricing stratifies across orbital qualification tiers, with ITAR-compliant US defense contracts at the apex and terrestrial consumer formats at the base. Cost compression in standard-grade tandem cells is intensifying because roll-to-roll deposition equipment spreads fixed costs across widening output volumes. Satellite prime contractors exhibit the lowest price sensitivity; portable charger OEMs face acute margin pressure from fluoropolymer laminate competition.
Supply Chain Analysis
Parylene dimer feedstock production concentrates in Japan and the United States, with specialty chemical suppliers in Osaka and Tokyo prefectures controlling precursor purity standards. Coaters draw from semiconductor-grade deposition equipment manufacturers in Germany and China, while thin-film active layers source from CIGS and perovskite specialists in Poland and the US. Single-source vulnerability in dimer supply exposes coaters to allocation risk during semiconductor demand spikes. Distribution runs through direct procurement relationships with satellite prime contractors and defense OEMs, bypassing traditional module integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluoropolymer encapsulation chemistry represents the immediate substitute threat that parylene coaters must displace through regulatory alignment and performance qualification ahead of EU F-Gas quota tightening.
For Market Incumbents: Pre-empt fluoropolymer requalification campaigns by accelerating tandem cell architecture certification with Airbus Defence and Space and Lockheed Martin procurement teams. Secure backward integration into parylene dimer precursor production through offtake agreements with Japanese specialty chemical suppliers, reducing exposure to allocation risk during semiconductor demand cycles. For New Entrants and Emerging Players: Wearable electronics medical device certifications in the United States represent the most penetrable entry point, with FDA device-grade parylene biocompatibility pathways creating addressable demand beyond aerospace procurement. Polish perovskite-parylene pilot lines offer equipment access partnerships for deposition capability acquisition without greenfield vacuum chamber investment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across roll-to-roll parylene deposition as continuous-coating equipment spreads fixed costs across widening output volumes. Acquisition targets should center on aerospace-qualified deposition specialists with sole-source procurement relationships and tandem cell qualification timelines. Monitor ECHA substance evaluation outcomes for parylene dimer purity standard revisions as inflection indicators for regulatory compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Tandem Cell Architecture Qualification | Efficiency stacking with perovskite-silicon junctions justifies premium encapsulation costs for aerospace procurement. |
| Backward Integration into Dimer Feedstock | Captive supply of parylene precursor monomers reduces allocation risk exposure to Japanese specialty chemical suppliers. |
| FDA Device-Grade Coating Certification | Biocompatibility pathway unlocks medical patch and continuous glucose monitor applications beyond building-integrated photovoltaics. |
| Roll-to-Roll Deposition Equipment Upgrade | Continuous-coating pilot lines halve chamber idle time and collapse capital cost per square meter of barrier film. |
| ITAR-Compliant Domestic Supply Chain | US DoD specifications for unmanned aerial systems create sole-source procurement pathways for flexible CIGS-parylene modules. |
Research Methodology
A spread of perspectives from satellite procurement officers at Lockheed Martin and Airbus Defence and Space, thin-film module engineering directors at Heliatek GmbH and Saule Technologies, parylene deposition equipment specialists, and ECHA regulatory affairs consultants converged on the working assumptions. Primary interview insights were cross-validated against secondary sources including SEC filings from US defense suppliers, ECHA substance evaluation documentation, EU F-Gas Regulation implementation reports, and METI technology roadmaps for space power systems. Bottom-up capacity estimates from deposition equipment installations were triangulated with top-down demand projections from aerospace procurement specifications.
Demand-supply balance modeling across the projection horizon incorporated photovoltaic active layer chemistry transitions, orbital weight mandate adoption curves, and REACH compliance deadline effects. Segmentation dimensions included product architecture, encapsulation technology tier, application vertical, and end-user procurement type. CAGRs were derived from installed base growth rates and replacement cycle analysis rather than extrapolated point estimates. Industry-specific forecast inputs encompassed perovskite moisture sensitivity thresholds and atomic oxygen test standard development timelines.
Practitioners should monitor ECHA substance evaluation outcomes, ITAR compliance requirement revisions, and roll-to-roll deposition equipment yield improvements for early signals of forecast revision. Cross-checking against IEA photovoltaic technology roadmaps and satellite industry procurement database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Mirror Market
Solar Power Systems
Residential Solar Energy Market
Solar Power Systems
South America Solar Photovoltaic Market
Solar Power Systems
Global Solar Power Windows Market
Solar Power Systems
North America Single Axis Solar Tracker Market
Solar Power Systems
Kuwait Solar Energy Market
Solar Power Systems
Solar PV Tracker Market
Solar Power Systems
Residential Solar Shading System Market
Solar Power Systems
Europe Solar Concentrator Market
Solar Power Systems
India Residential Solar Inverter Market
Solar Power Systems
Asia-Pacific Distributed Solar Power Generation Market
Solar Power Systems
Perovskite Solar Module Market
Solar Power Systems
Parabolic Solar Cookers Market
Solar Power Systems
Mexico Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Cells Market
Solar Power Systems
Bifacial Solar Module Market