
 Off-Grid Solar Power Market | 2026-2036
Off-Grid Solar Power Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Grid Solar Power Market Analysis
Buyer concentration among rural electrification agencies and development finance institutions is hardening across East and West Africa. ENGIE SA leverages its pay-as-you-go platform to sustain last-mile distribution networks in Kenya and Nigeria. Schneider Electric SE anchors commercial and industrial microgrid deployments through integrated energy management architectures. Azuri Technologies Ltd. specializes in small-scale home systems for households beyond centralized grid reach.
Off-grid solar power denotes photovoltaic electricity generation and storage systems operating independently from utility grid infrastructure, typically incorporating solar panels, charge controllers, battery banks, and inverters with DC-to-AC conversion efficiencies between 85% and 98%. These systems deliver primary or supplementary power to locations where grid extension remains economically unviable. Battery and storage solutions command the deepest margin pools as lithium-ion chemistries displace legacy lead-acid alternatives across residential and commercial installations. Photovoltaic technology dominates unit economics while hybrid systems integrating diesel backup or wind generation represent the fastest-growing configuration for agricultural and industrial end users requiring uninterrupted baseload supply.
FDA oversight governs battery safety certifications for lithium-based storage imported into the United States, while Kenya's Energy Regulatory Authority mandates quality standards for imported solar products through its Solar Water Heating and Photovoltaic Regulations. REACH compliance within Europe restricts hazardous substances in electronic components, directly shaping supplier qualification criteria for module and inverter manufacturers. Stakeholders must monitor evolving storage chemistry regulations and local content requirements as procurement frameworks shift from grant-based development assistance toward commercial debt financing and private capital structures.
Market Dynamics
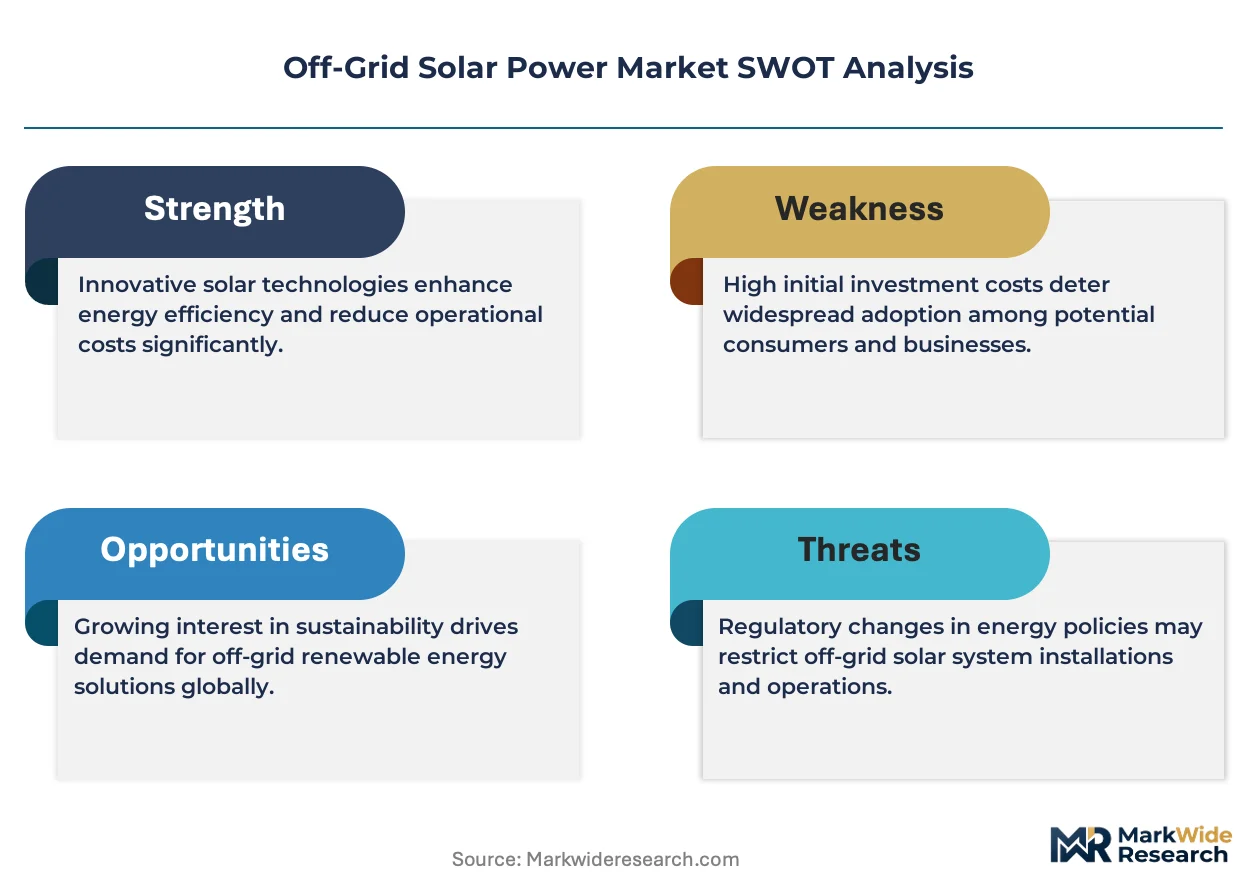
The lithium iron phosphate transition is compressing battery replacement cycles while elevating system lifetime value propositions for rural electrification programs across sub-Saharan Africa.
Growth Catalysts
- Kenya's Solar Water Heating and Photovoltaic Regulations:Quality mandates for imported solar products are filtering out substandard equipment and accelerating formal channel penetration.
- Agricultural irrigation pumping:Diesel displacement in smallholder farming clusters is creating steady demand for hybrid solar-diesel configurations with uninterrupted baseload.
- Development finance institutions:Capital deployment through commercial debt structures is replacing grant-based procurement and expanding addressable household segments.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings compress margin pools for battery-integrated system assemblers.
- East African port concentration:Mombasa and Dar es Salaam handling the majority of module imports creates single-point logistics vulnerability.
- Lead-acid stranded asset risk:Existing dealer networks with legacy inventory face technical obsolescence before depreciation cycles complete.
Strategic Opportunities
- Nigeria's underserved northern states:Grid extension economics remain unfavorable across Kano, Kaduna, and Borno corridors.
- Pay-as-you-go platform convergence with mobile money:Digital payment rails are unlocking remote customer credit scoring for asset financing.
- EU Green Deal carbon border adjustments:Embedded emissions accounting favors African-manufactured modules over Asian imports into European offtake markets.
Industry Challenges
- Certification timeline compression:Kenya's Energy Regulatory Authority testing protocols create six-to-nine month product approval delays.
- Field technician scarcity:Distributed maintenance networks require skilled labor for lithium battery diagnostics that existing lead-acid service pools lack.
- Interoperability fragmentation:Inverter communication protocols vary across charge controller manufacturers, complicating system integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Grid Solar Power Market |
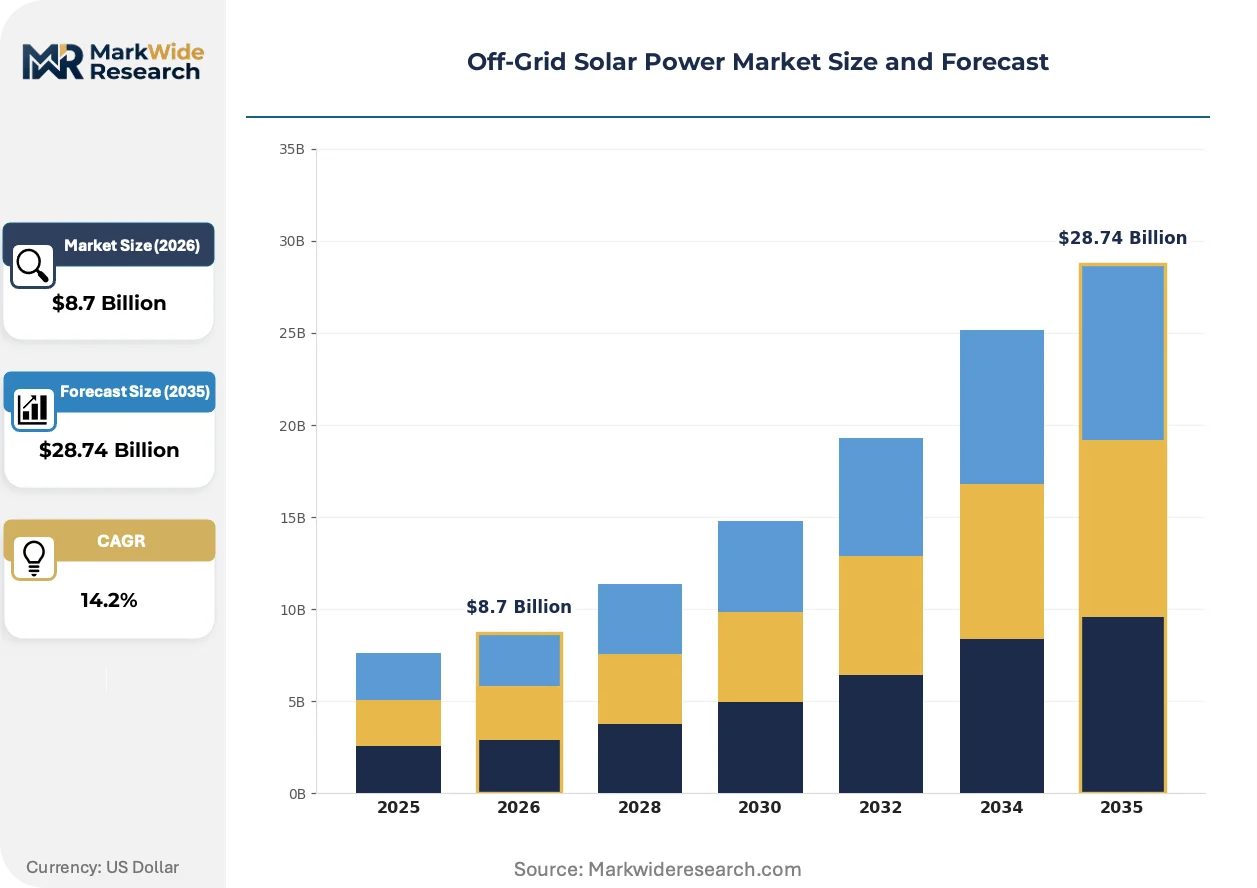
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Panels, Inverters, Batteries, Charge Controllers Application: Residential, Commercial, Industrial, Agricultural End User: Households, Businesses, Farms, Remote Communities Technology: Photovoltaic, Concentrated Solar Power, Hybrid Systems, Storage Solutions |
| Companies Covered | ABB Ltd., Canadian Solar, JinkoSolar Holding Co. Ltd., Schneider Electric SE, SMA Solar Technology AG, ENGIE SA, SunPower Corporation, Hanwha Group, Azuri Technologies Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Grid Solar Power Market Emerging Trajectories
Technology convergence between photovoltaic generation and digital financing platforms is restructuring how last-mile energy access reaches households beyond centralized infrastructure reach.
Lithium iron phosphate chemistry is rewriting rural electrification economics through extended cycle life and thermal stability. Small-scale home system providers are adopting these batteries for households in Tanzania's Lake Zone and Nigeria's Niger Delta. The chemistry is compressing total cost of ownership calculations and enabling longer-term consumer credit structures.
REACH compliance within Europe is restricting hazardous substances in electronic components and reshaping supplier qualification criteria for module and inverter manufacturers. Kenyan assembly operations serving regional export markets must now document substance compliance across their component supply bases. Photovoltaic module categories destined for European offtake face the most stringent documentation requirements.
After-sales service unbundling is separating hardware supply from maintenance contracts in commercial and industrial microgrid deployments. Agricultural processors in Kenya's Rift Valley now contract specialized technicians rather than relying on original equipment vendors. This pattern is most visible among tea cooperatives and cold storage operators requiring guaranteed uptime clauses.
Off-Grid Solar Power Market Segmentation
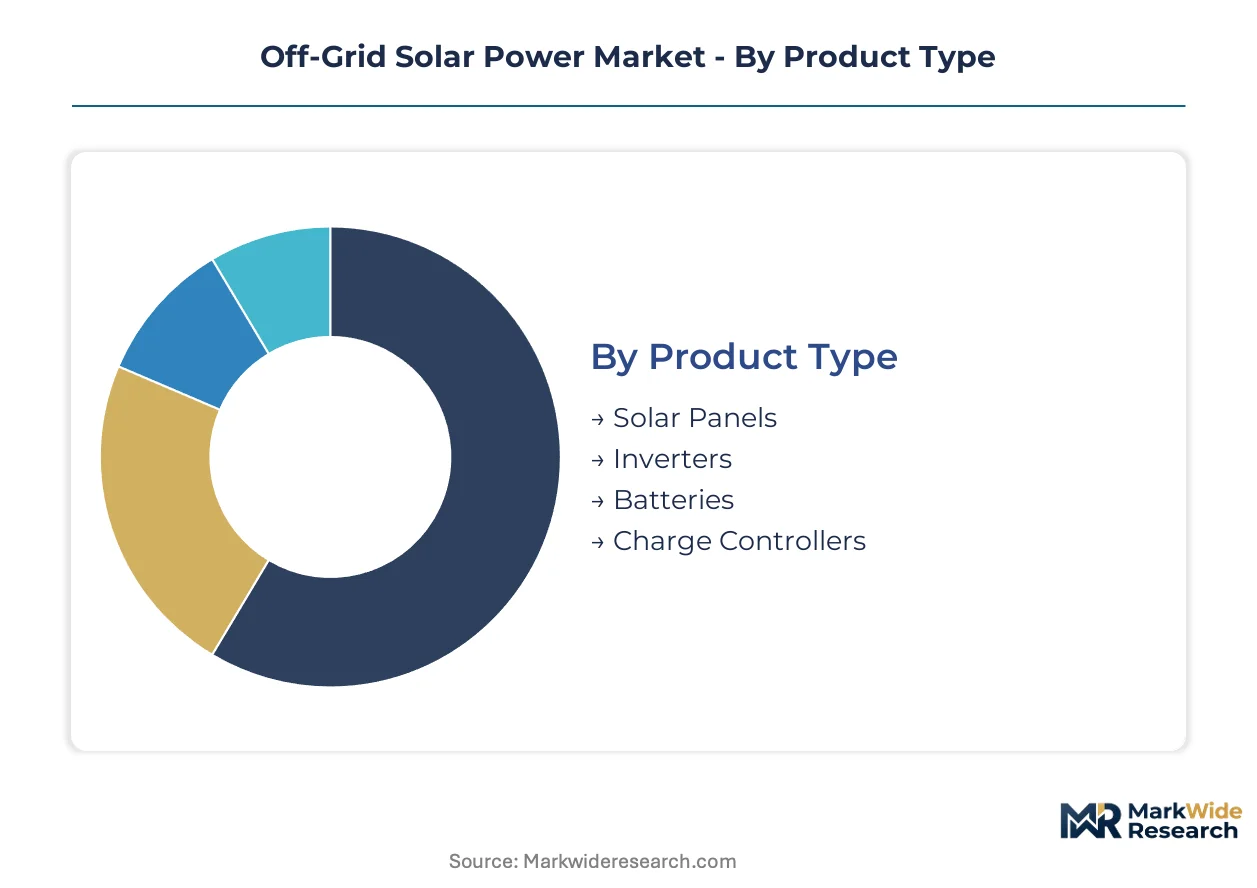
Off-grid solar power markets fragment across hardware categories, deployment scales, and financing mechanisms that determine channel economics. Each segmentation dimension reveals distinct margin structures, customer acquisition costs, and service intensity requirements that shape competitive positioning.
Product Type:
Volume concentrates in commodity hardware while premium capture sits with integrated storage systems requiring technical integration expertise.
- Solar Panels:Crystalline silicon modules dominate unit shipments with conversion efficiencies between 18% and 22%. Demand clusters around rural electrification programs in Kenya and Tanzania where procurement bulk purchases compress per-watt pricing. Panel sourcing from Asian manufacturers creates working capital intensity for African distributors.
- Batteries:Lithium iron phosphate cells are displacing lead-acid storage across residential installations through extended cycle life and thermal stability. Kenyan assembly operations now source cells directly from Chinese suppliers to bypass finished-goods import duties. Battery-integrated systems command the deepest margin pools in product mix.
- Inverters:DC-to-AC conversion hardware with 85% to 98% efficiency ratings enables household appliance compatibility.
- Charge Controllers:MPPT and PWM variants regulate voltage flow between panels and storage banks.
Mature deployment sits with Solar Panels. Newer deployment is concentrated in Batteries.
Application:
Customer scale determines system sizing, with agricultural and industrial segments driving hybrid configuration adoption.
- Residential:Small-scale home systems typically range from 50W to 200W capacity for lighting and mobile phone charging. Pay-as-you-go financing platforms in Nigeria's Niger Delta and Tanzania's Lake Zone unlock credit-constrained household segments. These installations prioritize affordability over performance optimization.
- Commercial:Microgrid deployments serving retail clusters and small enterprises require 5kW to 50kW capacity with guaranteed uptime provisions. Cold storage operators in Kenya's Rift Valley now contract specialized maintenance providers separate from hardware vendors. Commercial segments generate recurring service revenue streams.
- Industrial:Processing facilities and manufacturing sites demand uninterrupted baseload supply.
- Agricultural:Irrigation pumping and post-harvest processing create diesel displacement opportunities.
Residential captures volume leadership. Agricultural applications are expanding most quickly through irrigation mechanization programs.
End User:
Buyer concentration varies sharply between dispersed household demand and concentrated institutional procurement.
- Remote Communities:Mini-grid developers target settlements beyond centralized grid reach with shared infrastructure models. Development finance institutions in sub-Saharan Africa channel capital through rural electrification agencies that aggregate demand across hundreds of villages. Community-scale procurement enables standardized system designs.
- Households:Individual family units purchase entry-level solar home systems through mobile money-enabled installment plans. Kenya's M-Pesa integration with pay-as-you-go platforms reduces default rates through automated payment collection. Household segments require dense last-mile distribution networks.
- Businesses:Urban and peri-urban enterprises seek cost savings versus diesel generator operation.
- Farms:Smallholder and commercial agricultural operations prioritize irrigation and processing loads.
Remote Communities anchor institutional procurement volumes. Households represent the steepest expansion trajectory through digital financing penetration.
Technology:
System architecture choices determine capital intensity, operational complexity, and revenue model flexibility.
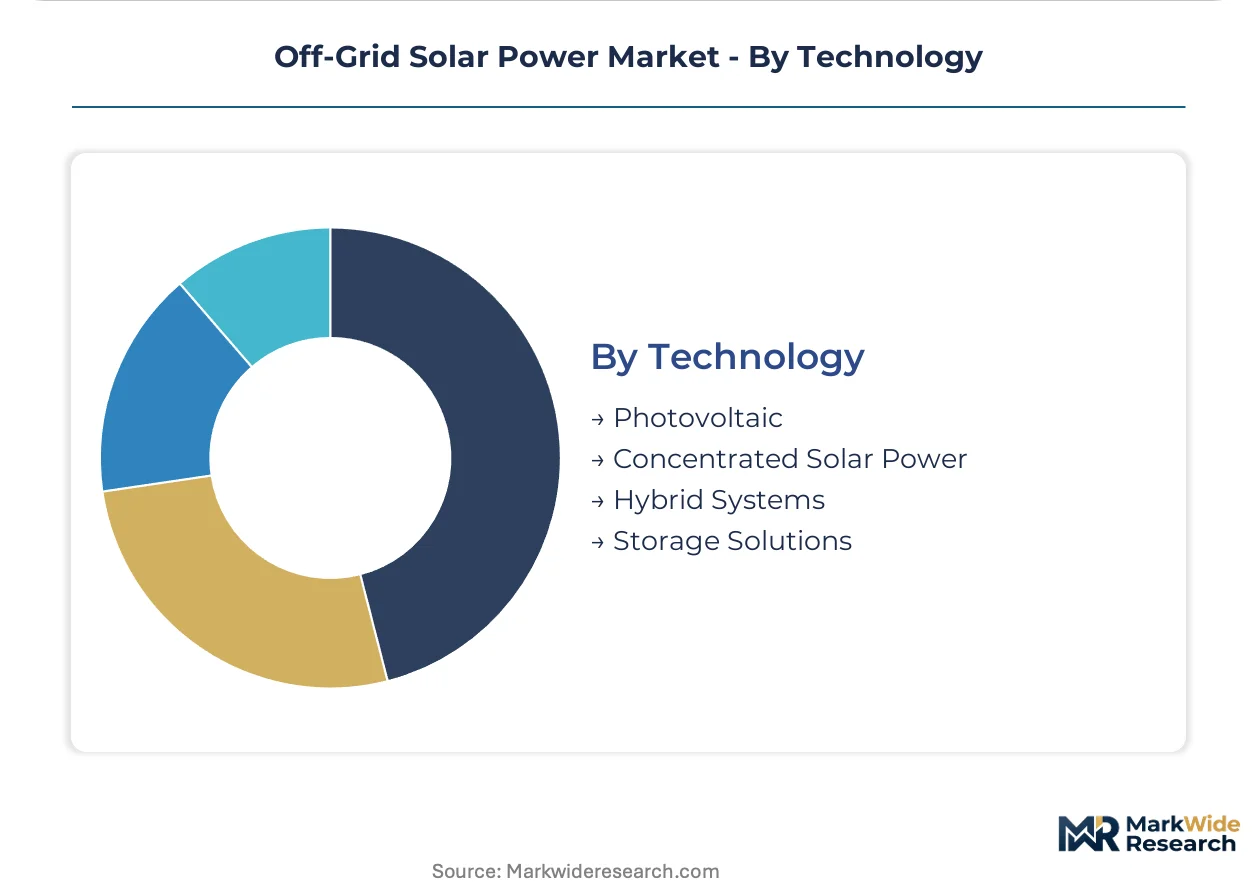
- Photovoltaic:Direct solar-to-electricity conversion technology dominates installed capacity through modular scalability and declining module costs. Kenyan and Nigerian markets prioritize photovoltaic solutions for rapid deployment without fuel supply logistics. This technology anchors unit economics across all application segments.
- Hybrid Systems:Configurations integrating diesel backup or wind generation address agricultural and industrial baseload requirements. Tea cooperatives in Kenya's highlands deploy solar-diesel hybrids to guarantee processing uptime during harvest windows. Hybrid architectures command premium pricing for reliability assurance.
- Storage Solutions:Battery-integrated systems enable load shifting and nighttime operation.
- Concentrated Solar Power:Thermal concentration technology remains limited to utility-scale applications.
Photovoltaic technology anchors mature deployment. Hybrid Systems are gaining share fastest through industrial reliability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in sub-Saharan Africa where rural electrification agencies aggregate procurement across remote settlements. Kenya, Nigeria, and Tanzania anchor installation volumes through development finance capital deployment.
Kenya
Rural electrification programs drive mini-grid development across the Rift Valley and Lake Zone regions. The Energy Regulatory Authority enforces Solar Water Heating and Photovoltaic Regulations that filter substandard imports through mandatory quality testing. Mombasa port handles the majority of module imports, creating logistics concentration for distributors serving East African markets.
Nigeria
Pay-as-you-go platforms unlock credit-constrained households in the Niger Delta and northern states including Kano and Kaduna. The Rural Electrification Agency channels World Bank and AfDB capital toward off-grid solar deployments. Lagos anchors commercial and industrial microgrid demand from manufacturing clusters seeking diesel displacement.
Tanzania
Smallholder irrigation programs create agricultural demand for hybrid solar-diesel configurations in the Lake Zone. The Energy and Water Utilities Regulatory Authority oversees quality standards for imported photovoltaic equipment. Dar es Salaam port concentration creates single-point vulnerability for module supply chains serving domestic and regional markets.
India
Saubhagya scheme extensions and distributed renewable energy programs target unelectrified settlements in Bihar, Uttar Pradesh, and Rajasthan. The Ministry of New and Renewable Energy mandates BIS certification for solar photovoltaic modules through quality control orders. Gujarat's manufacturing clusters produce domestically assembled systems reducing import dependence for rural electrification agencies.
United States
Remote tribal lands and rural Alaska communities drive demand for resilient off-grid installations beyond utility infrastructure reach. The Investment Tax Credit and Inflation Reduction Act provisions reduce capital costs for residential and commercial solar-plus-storage systems. California's backup power regulations accelerate battery-integrated system adoption in wildfire-prone northern counties.
Off-Grid Solar Power Market Vendor Landscape
European energy majors anchor one tier through integrated electrification platforms; Chinese module manufacturers hold cost-competitive supply positions. The vendor base stratifies across three tiers: multinational conglomerates with pay-as-you-go financing capabilities, regional assemblers serving procurement tenders, and specialist providers of small-scale home systems. Strategic moves center on backward integration into battery cell sourcing and geographic expansion through mobile money-enabled last-mile distribution partnerships.
Among the integrated energy majors, ENGIE SA exemplifies the financing-platform archetype through its African pay-as-you-go operations. Schneider Electric SE occupies a position in commercial microgrid deployment through energy management system integration. Azuri Technologies Ltd. represents the specialist tier focused on household-scale systems beyond grid reach. These three players illustrate the competitive spectrum from capital-intensive platform operators to focused rural electrification specialists.
| Leading Market Players |
|---|
| ABB Ltd. |
| Canadian Solar |
| JinkoSolar Holding Co. Ltd. |
| Schneider Electric SE |
| SMA Solar Technology AG |
| ENGIE SA |
| SunPower Corporation |
| Hanwha Group |
| Azuri Technologies Ltd. |
| Others |
Supply Flow & Price Mechanics
Field technician scarcity in Kenya's Rift Valley and Nigeria's northern states widens labor-cost differentials between premium service-bundled systems and economy-tier hardware-only sales. This workforce compression stratifies pricing tiers as after-sales capability becomes the scarcest margin component.
Pricing Analysis
Volume concentrates in commodity solar panels while margin capture sits with battery-integrated systems requiring technical certification. Price differentiation separates REACH-compliant European-export modules from standard-grade imports through documentation burden and testing protocols. Pricing pressure stems from lithium carbonate input volatility compressing assembler margins in battery-integrated configurations. Households in Tanzania's Lake Zone exhibit highest price sensitivity through pay-as-you-go financing constraints, while commercial tea cooperatives in Kenya accept premium pricing for guaranteed uptime clauses.
Supply Chain Analysis
Photovoltaic cell supply rests on Chinese manufacturers, with lithium iron phosphate cell production anchored in China and South Korea. Module assembly draws from Vietnamese and Indian operations to bypass tariff exposure into African markets. Raw material dependencies span polysilicon feedstock, lithium carbonate, and cobalt-free cathode formulations. Single-point logistics vulnerability concentrates at Mombasa and Dar es Salaam ports handling East African module imports. Distribution runs through pay-as-you-go platform networks and rural electrification agency procurement tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell supply scarcity props system pricing as lithium iron phosphate chemistry transitions displace legacy lead-acid inventory faster than manufacturing capacity expands.
For Market Incumbents: Lock in backward integration into Chinese cell sourcing to bypass finished-goods import duties and secure thermal-stable battery supply for Kenyan assembly operations. Defend channel position by certifying products early under Kenya's Energy Regulatory Authority protocols before six-to-nine month approval timelines harden competitive moats. Prioritize technician training partnerships to address field diagnostic scarcity threatening service revenue streams.
For New Entrants and Emerging Players: Mobile money-enabled pay-as-you-go platforms offer the lowest-friction route to credit-constrained households in Nigeria's Niger Delta and northern state corridors. Target agricultural irrigation clusters in Tanzania's Lake Zone where diesel displacement creates immediate total-cost-of-ownership advantages. Pursue white-label assembly partnerships with existing Kenyan distributors to bypass port logistics concentration.
For Investors and Strategic Acquirers: Re-rating potential sits with regional assemblers possessing captive cell supply relationships given lithium chemistry transition acceleration. Long-term viability centers on platforms combining hardware financing with mobile money integration across sub-Saharan Africa. Watch lithium carbonate price stabilization as the inflection signal for margin recovery in battery-integrated system providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Sourcing | Kenyan assemblers bypass import duties by sourcing lithium iron phosphate cells directly from Chinese suppliers. |
| Pay-as-you-go Platform Expansion | Digital payment rails unlock credit scoring for households beyond traditional banking reach in Nigeria and Tanzania. |
| Quality Certification Investment | Kenya's Energy Regulatory Authority mandates filter substandard imports and accelerate formal channel penetration. |
| Technician Training Network Buildout | Distributed maintenance capabilities address lithium battery diagnostic scarcity threatening service revenue. |
| Hybrid System Configuration Development | Solar-diesel integrations guarantee baseload for tea cooperatives and cold storage operators requiring uptime assurance. |
Methodological Framework
Regulatory filings from Kenya's Energy Regulatory Authority, Tanzania's Energy and Water Utilities Regulatory Authority, and Nigeria's Rural Electrification Agency formed the secondary backbone for compliance framework mapping. Primary interviews with pay-as-you-go platform operators, rural electrification procurement officers, and lithium battery assemblers in Nairobi and Lagos triangulated against customs data and development finance institution capital deployment records. Bottom-up unit economics modeling and top-down market sizing converged through crystalline silicon module pricing benchmarks and pay-as-you-go customer default rate databases.
Bottom-up modeling tracked individual system configurations across residential, commercial, and agricultural segments while top-down analysis validated against aggregated rural electrification agency procurement volumes. The analytical framework projected technology transitions, financing mechanism penetration, and regulatory compliance costs across the projection horizon. Segmentation dimensions spanned product type, application scale, end-user concentration, and hybrid system architecture. CAGRs derived from installed base growth rates, replacement cycle compression, and credit access expansion curves.
The model holds under stable lithium carbonate supply and continued mobile money penetration; deviation in raw material price spikes or regulatory approval timeline extensions would shift volume trajectories. Forecasts reflect assumptions on chemistry transition speed, technician training pipeline development, and port logistics reliability. A small set of named triggers—lithium price volatility, Kenya certification backlog, Mombasa port congestion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Thermal Market
Solar Power Systems
Optical Solar Reflectors Market
Solar Power Systems
DSC Solar Technologies Market
Solar Power Systems
Single Axis Solar PV Tracker Market
Solar Power Systems
Global EV Solar Modules Market
Solar Power Systems
Australia Solar Power Market
Solar Power Systems
Global Ultra Efficient Solar Power Market
Solar Power Systems
Global Concentrating Solar Power Market
Solar Power Systems
United States Distributed Solar Power Generation Market
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
Solar Microinverter and Power Optimizer Market
Solar Power Systems
Solar Metal Roof Market
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
Solar Panel Cleaning Equipment Market
Solar Power Systems
Global Photovoltaic Glass Market
Solar Power Systems
Residential Solar Market