
 Tubular Solar Collector Market | 2026-2036
Tubular Solar Collector Market Size, Share, and Industry Trends Forecast 2026-2036
Tubular Solar Collector Market Insights
ISO 9806 thermal performance certification is collapsing the field of qualified suppliers across Europe and Asia. Viessmann Group leverages its testing infrastructure to sustain premium positioning in German-speaking markets. Sunrain Solar Energy anchors volume production through integrated glass-tube manufacturing in eastern China. GREENoneTEC Solarindustrie GmbH differentiates via specialized absorber coatings that compete on optical efficiency metrics.
Tubular solar collectors employ concentric glass tubes with vacuum insulation between layers, typically achieving stagnation temperatures above 200°C while minimizing convective heat loss; this architecture serves commercial water heating and industrial process heat applications where flat-plate designs underperform. Evacuated tube systems lead installed capacity in cold-climate zones due to superior freeze resistance and lower heat loss coefficients. Concentrated solar configurations capture emerging demand from district heating networks seeking temperatures above 120°C. Hybrid designs occupy a niche growth corridor where facilities require simultaneous thermal output and limited photovoltaic generation.
CE marking under the EU Solar Keymark scheme and China's GB/T 19775 national standard collectively shape product eligibility across the two largest demand basins, with compliance costs filtering smaller fabricators from tender participation. The EPA's Energy Star thermal certification and India's BIS solar thermal standards extend this regulatory architecture to additional procurement pools. Stakeholders must monitor evolving efficiency thresholds in national building codes as these determine which collector technologies qualify for subsidy-linked installation contracts.
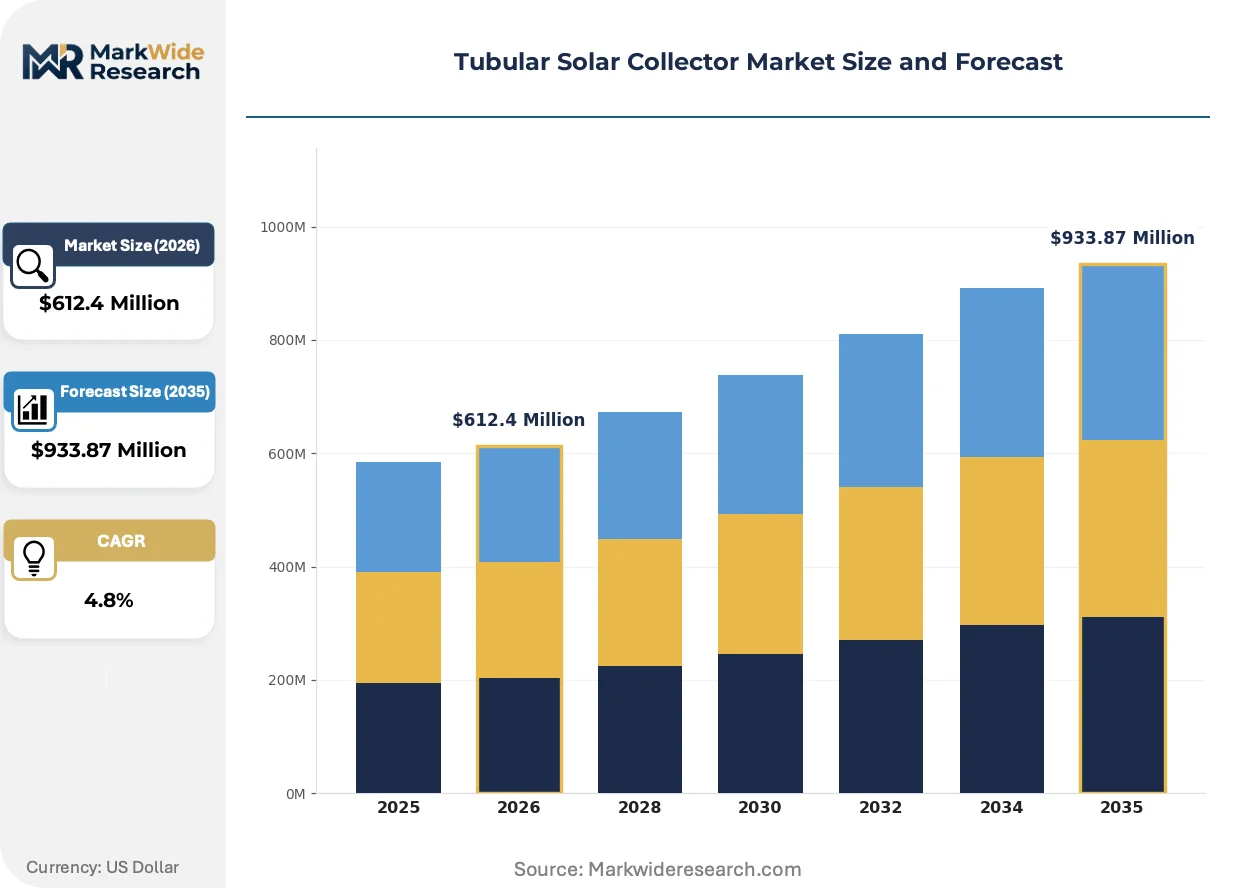
Market Dynamics
ISO 9806 thermal performance certification is consolidating supplier participation across Europe and Asia, eliminating marginal fabricators unable to sustain testing infrastructure investments while concentrating procurement authority among certified tier-one manufacturers.
Growth Catalysts
- German building energy codes:Tightened efficiency mandates for residential heating retrofit are accelerating specification of evacuated tube collectors in new construction and renovation tenders.
- Industrial process heat demand:Food processing and textile manufacturers in cold-climate zones are adopting concentrated solar configurations to displace natural gas for temperatures above 120°C.
- Hybrid system architecture:Facilities requiring simultaneous thermal output and limited photovoltaic generation are driving niche demand for integrated thermal-electric collectors.
Market Restraints
- Borosilicate glass supply concentration:Eastern China dominates specialized glass-tube manufacturing, creating input vulnerability for fabricators outside this production cluster.
- CE marking compliance costs:EU Solar Keymark certification expenses filter smaller European fabricators from public procurement participation.
- Flat-plate collector substitution:Mature flat-plate designs retain cost advantage in mild-climate residential segments, constraining tubular collector penetration in price-sensitive markets.
Strategic Opportunities
- District heating network expansion:Scandinavian and German municipal utilities are piloting concentrated solar configurations for centralized thermal generation above 120°C.
- India BIS solar thermal standards:Formalized national certification is opening subsidy-linked installation contracts for compliant evacuated tube suppliers.
- Selective absorber coating advancement:Optical efficiency improvements via sputtered multi-layer coatings are creating premium positioning against commodity glass-tube alternatives.
Industry Challenges
- Vacuum seal integrity testing:Quality assurance protocols for concentric tube vacuum insulation require specialized equipment and technician training that constrain production scaling.
- Legacy system integration:Retrofit installations face hydraulic compatibility complications with existing boiler infrastructure, extending project timelines and contractor certification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tubular Solar Collector Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $933.87 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Plate, Evacuated Tube, Concentrated Solar, Hybrid Application: Residential Heating, Industrial Processes, Water Heating, Power Generation End User: Households, Commercial Buildings, Manufacturing Facilities, Agricultural Operations Technology: Thermal, Photovoltaic, Thermodynamic, Passive |
| Companies Covered | Viessmann Group, GREENoneTEC Solarindustrie GmbH, Sunrain Solar Energy, Solimpeks Solar Energy Corp., Schott AG, Apricus Solar Co. Ltd., Himin Solar Energy, Bosch Thermotechnology, TVP Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tubular Solar Collector Market Trends and Innovations
Evacuated tube architecture is advancing through materials science improvements and manufacturing automation while regulatory pressure on building efficiency accelerates specification in new construction.
Selective absorber coatings with enhanced spectral selectivity are displacing baseline black-chrome surfaces in premium collector segments. German and Austrian district heating operators are specifying these coatings for high-temperature applications. The technology is displacing commodity-grade collectors in efficiency-sensitive procurement.
China's GB/T 19775 national standard revision is tightening thermal performance thresholds for domestic market eligibility. Manufacturers must retest product lines against elevated efficiency benchmarks. Eastern Chinese fabricators with captive testing infrastructure are accelerating certification cycles while smaller competitors face exclusion.
Engineering-procurement-construction firms are consolidating solar thermal specification authority previously dispersed among mechanical contractors. Large-scale commercial and industrial projects now route through specialized EPCs with in-house thermal engineering capability. Germany and Austria exhibit the most pronounced channel concentration.
Tubular Solar Collector Market Segmentation
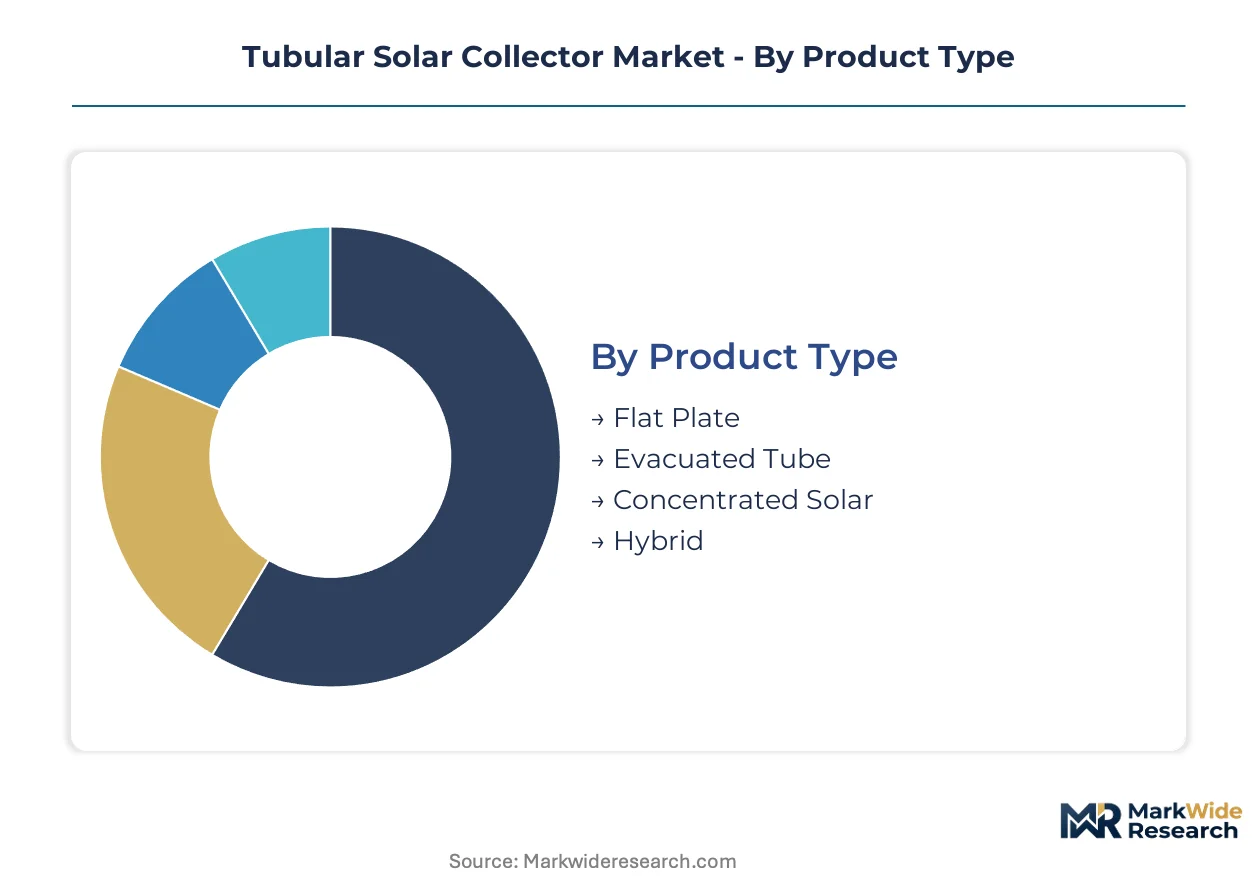
Collector architecture determines compliance pathways and subsidy eligibility across regulatory regimes. Product certification requirements vary sharply by segment, with vacuum-insulated designs facing distinct testing protocols from flat-plate alternatives.
Product Type:
CE marking under the EU Solar Keymark scheme and China's GB/T 19775 standard create divergent qualification burdens across collector architectures.
- Evacuated Tube:Concentric borosilicate glass tubes with vacuum insulation between layers achieve stagnation temperatures above 200°C. German residential heating retrofits under tightened building energy codes are accelerating specification of these systems for freeze-resistant performance in cold-climate zones.
- Concentrated Solar:Parabolic or compound parabolic concentrators focus solar radiation onto absorber tubes for temperatures exceeding 120°C. Scandinavian and German district heating networks are piloting these configurations for centralized industrial process heat generation.
- Flat Plate:Metallic absorber sheets with selective coatings in insulated glazed boxes serve cost-sensitive mild-climate markets.
- Hybrid:Integrated thermal-electric collectors deliver simultaneous heat output and limited photovoltaic generation for facilities with dual energy requirements.
Evacuated tube systems handle the majority of throughput; concentrated solar configurations are expanding most quickly on share.
Application:
End-use temperature requirements and project scale reshape procurement channel structures across installation categories.
- Residential Heating:Space heating and domestic hot water systems in single-family and multi-family buildings. German-speaking markets dominate demand as building energy codes mandate efficiency thresholds that vacuum-insulated collectors satisfy.
- Industrial Processes:Process heat for food processing, textile manufacturing, and chemical operations above 80°C. Cold-climate manufacturers are adopting concentrated solar to displace natural gas combustion.
- Water Heating:Commercial and institutional domestic hot water systems in hotels, hospitals, and athletic facilities.
- Power Generation:Organic Rankine cycle and other thermal-to-electric conversion systems for remote or off-grid installations.
Residential heating commands the largest installed base; industrial process heat is gaining share fastest as fuel substitution economics improve.
End User:
Customer scale and technical sophistication determine specification authority and service requirements.
- Manufacturing Facilities:Industrial plants with continuous thermal demand and in-house engineering capability. Food processors and textile manufacturers in Germany and Austria are specifying high-temperature concentrated solar arrays.
- Commercial Buildings:Hotels, hospitals, schools, and office complexes with predictable hot water loads. Engineering-procurement-construction firms are consolidating specification authority previously held by mechanical contractors.
- Households:Single-family and multi-family residential installations driven by subsidy-linked retrofit programs.
- Agricultural Operations:Greenhouse heating, livestock facility climate control, and crop drying applications with seasonal demand patterns.
Manufacturing facilities drive the highest average project value; commercial buildings are climbing the fastest as EPC channel concentration accelerates.
Technology:
Energy conversion mechanism determines integration complexity and hybrid system compatibility.
- Thermal:Direct heat transfer via water-glycol mixtures or steam generation in absorber tubes. This architecture dominates evacuated tube and concentrated solar installations for temperatures above 80°C.
- Photovoltaic:Semiconductor-based electricity generation integrated into hybrid collector designs for facilities requiring limited electrical output alongside thermal service.
- Thermodynamic:Heat engine cycles including organic Rankine systems for power generation from moderate-temperature thermal sources.
- Passive:Thermosiphon and direct circulation systems without active pumping for simple residential water heating in frost-free climates.
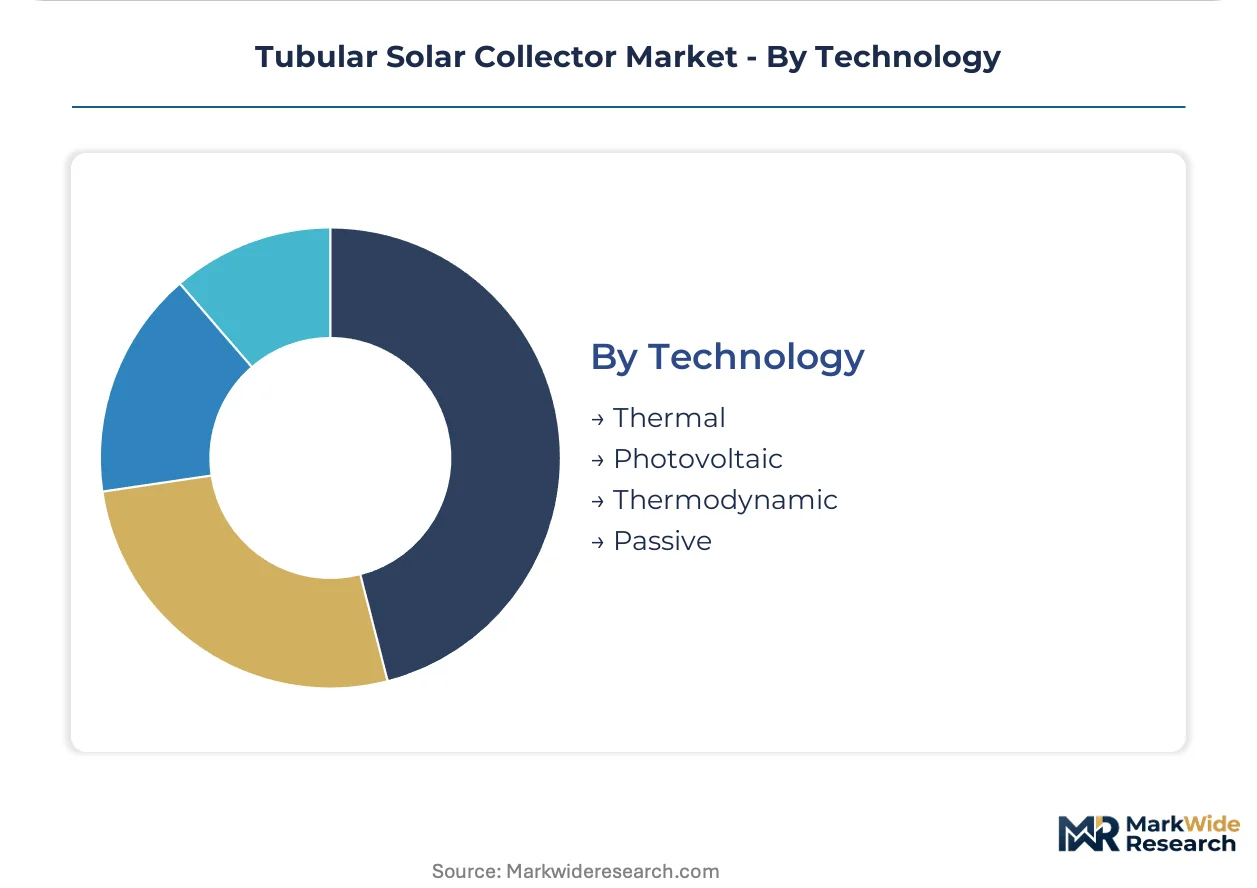
Thermal conversion handles the majority of collector deployments; hybrid thermal-photovoltaic systems are showing the steepest expansion trajectory as facilities seek dual-output solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Subsidy-linked installation contracts in Germany and China's GB/T 19775 standard revision are redirecting procurement toward certified manufacturers. Building energy codes across multiple jurisdictions are tightening thermal performance thresholds for residential and commercial heating systems.
Germany
Residential heating retrofits and new construction tenders are accelerating evacuated tube collector specification as the Building Energy Act tightens efficiency mandates. CE marking under the EU Solar Keymark scheme filters smaller fabricators from public procurement participation. Manufacturing clusters in Bavaria and Baden-Württemberg host testing infrastructure investments by tier-one suppliers.
China
Domestic market eligibility requirements under GB/T 19775 are forcing retesting of product lines against elevated efficiency benchmarks. Eastern Chinese fabricators with captive testing infrastructure are accelerating certification cycles. Glass-tube manufacturing concentrates in Shandong and Jiangsu provinces, creating input supply advantages for integrated producers.
India
BIS solar thermal standards are formalizing national certification pathways for evacuated tube suppliers seeking subsidy-linked contracts. Commercial and institutional water heating projects in Maharashtra and Gujarat are specifying compliant systems. The western industrial corridor is emerging as a distribution hub for cold-climate collector variants.
Austria
District heating network operators are piloting concentrated solar configurations for centralized thermal generation above 120°C. National building codes mandate renewable heat shares in new municipal construction. Engineering-procurement-construction firms in Vienna and Graz are consolidating specification authority for large-scale commercial installations.
United States
EPA Energy Star thermal certification is extending procurement eligibility for commercial water heating applications. Food processing facilities in California and the Pacific Northwest are evaluating concentrated solar for industrial process heat displacement. State-level renewable portfolio standards in the Northeast are creating incentive structures for hybrid thermal-electric collector adoption.
Tubular Solar Collector Market Competitive Landscape
Listed leaders compete with private specialists across certification infrastructure and manufacturing scale. The supplier base concentrates among tier-one fabricators with ISO 9806 testing capabilities, while smaller regional players face exclusion from tender participation. Three archetypes dominate: integrated glass-tube manufacturers with captive raw material supply, specialized coating developers competing on optical efficiency metrics, and diversified heating equipment conglomerates leveraging distribution networks. Competitive moves center on testing infrastructure expansion and selective absorber coating R&D partnerships.
Among German-speaking fabricators, Viessmann Group and GREENoneTEC Solarindustrie GmbH exemplify the premium-tier positioning anchored by certification infrastructure investments. Sunrain Solar Energy represents the scale-driven archetype with integrated manufacturing in eastern China. These three occupy positions across the quality-volume spectrum, with each archetype serving distinct procurement channel structures.
| Leading Market Players |
|---|
| Viessmann Group |
| GREENoneTEC Solarindustrie GmbH |
| Sunrain Solar Energy |
| Solimpeks Solar Energy Corp. |
| Schott AG |
| Apricus Solar Co. Ltd. |
| Himin Solar Energy |
| Bosch Thermotechnology |
| TVP Solar |
| Others |
Pricing and Supply Chain Analysis
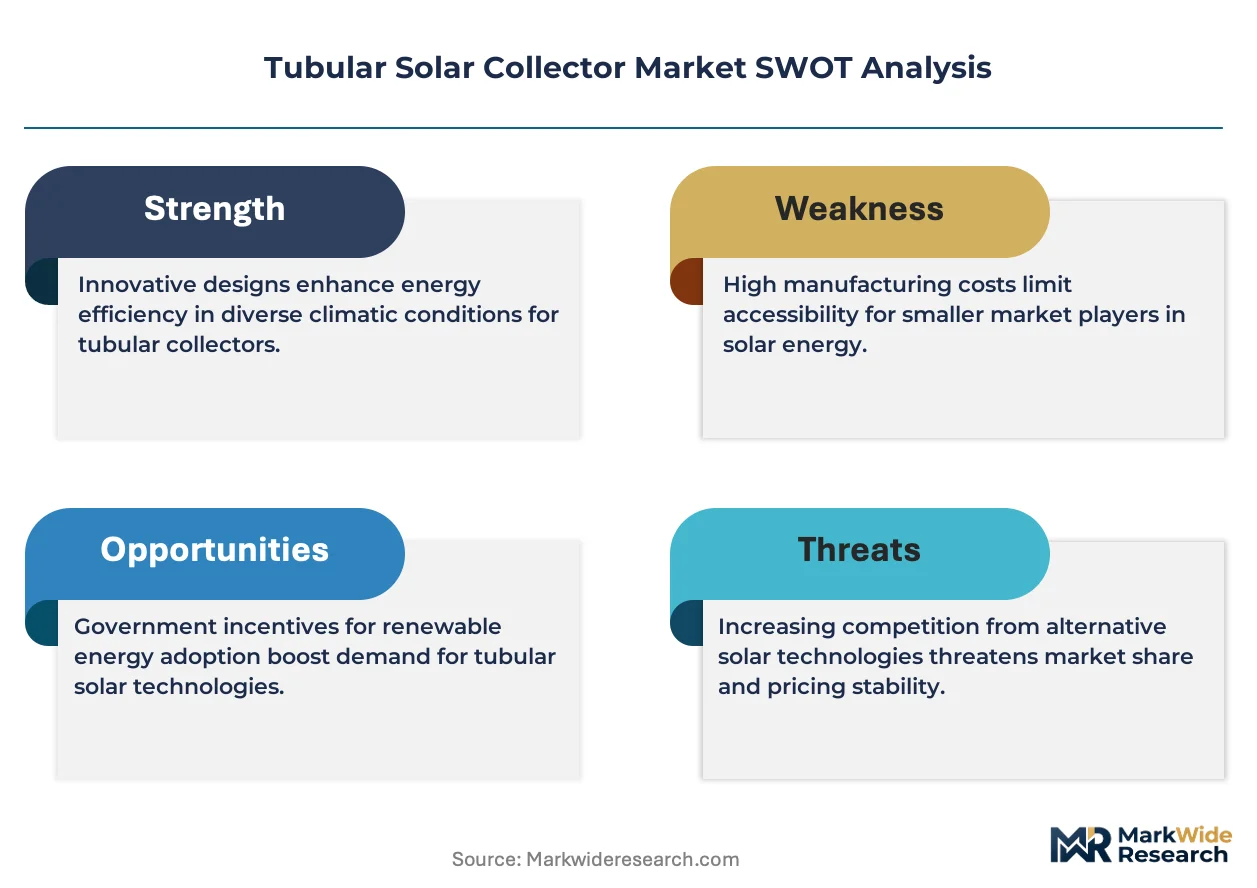
Ninety-day inventory cycles for borosilicate glass tubes in Shandong province concentrate pricing leverage among integrated eastern Chinese manufacturers while tier-one European fabricators absorb premium logistics costs to sustain CE-marked product positioning.
Pricing Analysis
Certification level creates the primary spread between premium and commodity tiers, with ISO 9806 and EU Solar Keymark compliance adding substantial testing overhead that filters smaller competitors. Pricing stratifies across premium certified, standard compliant, and economy non-certified tiers. Cost compression in the economy tier intensifies as flat-plate collectors capture price-sensitive residential segments in mild climates. Manufacturing facilities with continuous thermal demand exhibit the lowest price sensitivity, while household retrofit buyers drive aggressive procurement negotiations.
Supply Chain Analysis
Extended lead times for specialized borosilicate glass—stretching to sixteen weeks during peak demand—expose fabricators without captive tube production to scheduling risk. Supply concentrates in Shandong and Jiangsu provinces of China, with secondary glass-tube capacity in Germany and Austria. Raw material dependencies center on high-purity silica sand, boron oxide, and selective absorber coating chemicals. Single-source vulnerability runs through eastern China's glass-tube manufacturing cluster, where environmental compliance inspections periodically constrain output. Distribution runs through engineering-procurement-construction firms for commercial and industrial projects, while residential channels rely on regional heating contractors and specialized solar installers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tubular solar collector market is entering a cyclical recovery phase as building energy code tightening across German-speaking jurisdictions restarts stalled retrofit demand.
For Market Incumbents: Shield premium positioning by accelerating selective absorber coating R&D partnerships that widen optical efficiency gaps against commodity glass-tube alternatives. Secure captive borosilicate glass supply through backward integration into eastern Chinese manufacturing or long-term offtake agreements with Shandong-based tube producers. Flat-plate collector substitution in mild-climate residential segments represents the most pressing share threat requiring defensive specification support for mechanical contractors. For New Entrants and Emerging Players: Aftermarket vacuum seal integrity testing services present an underserved layer where incumbents under-serve legacy installation bases. Target India's western industrial corridor as the most penetrable geography, where BIS certification formalization is opening subsidy-linked contracts ahead of established European supplier presence. A technical service-led go-to-market angle—offering hydraulic compatibility assessment and boiler integration support—differentiates against product-only competitors. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because building code efficiency thresholds and certification requirements continuously filter marginal competitors while concentrating procurement authority among tested tier-one suppliers. Acquisition candidates should display integrated glass-tube manufacturing or captive selective coating capability rather than pure assembly operations. The signal to watch is GB/T 19775 standard revision implementation velocity in China, which will accelerate consolidation timelines and reveal which eastern fabricators can sustain elevated efficiency benchmarks.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 9806 Testing Infrastructure Expansion | Viessmann Group and GREENoneTEC sustain premium positioning through captive thermal performance certification capability. |
| Selective Absorber Coating R&D Partnership | Sputtered multi-layer optical efficiency advances displace black-chrome surfaces in German district heating specifications. |
| Backward Integration into Glass-Tube Manufacturing | Sunrain Solar Energy anchors cost position through captive borosilicate supply in Shandong province. |
| Engineering-Procurement-Construction Channel Capture | Large-scale commercial project authority consolidates among thermal-engineering-capable EPCs in Germany and Austria. |
| Hybrid Thermal-Electric Collector Platform Launch | Facilities requiring simultaneous heat and limited photovoltaic output drive niche expansion in California and Pacific Northwest markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with EPC contractors, solar thermal system installers, plant engineers at food processing facilities, and procurement officers at district heating utilities; and secondary validation through customs trade data, GB/T 19775 certification registries, EU Solar Keymark databases, and SEC filings of listed heating equipment conglomerates. Bottom-up installation volume estimates triangulated against top-down addressable market sizing across residential heating, industrial process heat, and commercial water heating segments.
Across the analysis window, the forecast framework modeled demand by collector architecture, application temperature threshold, end-user scale, and conversion technology type. CAGRs derived from segment-level growth rate blending weighted by current installed base shares. Key inputs included building energy code revision timelines, natural gas price substitution economics, and subsidy program eligibility criteria across German, Chinese, and Indian procurement pools.
Underlying assumptions cover regulatory enforcement continuity, borosilicate glass supply stability, and flat-plate collector price parity trends, with deviation risk concentrated in China's environmental compliance inspection intensity and EU Solar Keymark efficiency threshold evolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Distributed Solar Energy Market
Solar Power Systems
Middle-East Solar Power Market
Solar Power Systems
Italy Solar Energy Market
Solar Power Systems
Solar Thermal Collector Market
Solar Power Systems
Solar Shed Light Market
Solar Power Systems
US Solar Market
Solar Power Systems
Solar Panels for Home Market
Solar Power Systems
Perovskite Solar Cell Market
Solar Power Systems
Solar Panel Bracket Market
Solar Power Systems
Residential Solar Shading System Market
Solar Power Systems
North America Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Tracker for Power Generation Market
Solar Power Systems
High-Efficiency Solar Modules Market
Solar Power Systems
Solar Thermal Power Market
Solar Power Systems
North America Concentrated Solar Power (CSP) Market
Solar Power Systems
Asia Pacific Solar Backsheet Market