
 Smart Solar Power Market | 2026-2036
Smart Solar Power Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Solar Power Market Outlook
A shortage of certified solar technicians and grid-integration engineers is unwinding project timelines across multiple continents. NextEra Energy Resources leverages its vertically integrated development platform to secure long-term power purchase agreements. SolarEdge Technologies anchors its position through module-level power electronics that reduce balance-of-system costs. Enphase Energy differentiates via microinverter architectures optimized for residential retrofit applications.
Smart solar power integrates photovoltaic generation with digital monitoring, predictive analytics, and automated grid interaction to maximize yield and stabilize intermittency. Systems typically incorporate maximum power point tracking algorithms, cloud-based performance dashboards, and bidirectional communication protocols that enable real-time curtailment or storage dispatch. Photovoltaic cells and inverters command the largest value share, though energy management systems are expanding fastest as building electrification intensifies. Rooftop installations lead in deployment volume, while floating systems are gaining traction where land scarcity constrains ground-mounted expansion.
The US IRA production credits, EU Green Deal taxonomy requirements, and China's dual carbon targets collectively steer capital toward domestic manufacturing and certified component sourcing. EMA and FDA frameworks indirectly shape demand by establishing clinical-grade power reliability standards for healthcare microgrids. Stakeholders must weigh technology lock-in risks against the flexibility premium of interoperable software architectures as procurement standards fragment across jurisdictions.
Market Dynamics
Grid modernization mandates and manufacturing tax incentives are restructuring competitive economics across the smart solar power value chain, compressing project development timelines while amplifying capital requirements for domestic production scale-up.
Growth Catalysts
- US Inflation Reduction Act production credits:Domestic manufacturing incentives are reshoring inverter and module assembly capacity, reducing tariff exposure for utility-scale developers.
- Building electrification mandates:California and New York building codes are accelerating residential solar-plus-storage attachment rates as heat pump penetration rises.
- Dual carbon targets:China's MEE enforcement mechanisms are compelling provincial grid operators to prioritize dispatchable renewable capacity in interconnection queues.
Market Restraints
- Polysilicon supply concentration:Xinjiang-sourced metallurgical-grade silicon creates forced labor due diligence burdens under EU Green Deal taxonomy requirements.
- Interconnection queue delays:FERC Order 2023 implementation gaps extend project energization timelines by 18-36 months in ERCOT and PJM territories.
- Grid-forming inverter technical limits:Current silicon carbide switching frequencies constrain fault ride-through performance below 50% renewable penetration thresholds.
Strategic Opportunities
- Floating photovoltaic deployment:Reservoir-constrained markets in Japan and South Korea are tendering 500MW+ projects where land scarcity blocks ground-mount alternatives.
- Healthcare microgrid certification:EMA clinical-grade power reliability standards are creating premium pricing tiers for solar-plus-storage configurations serving hospital campuses.
- Vehicle-to-grid convergence:Bidirectional EV charging protocols are enabling residential solar owners to monetize battery capacity through frequency regulation markets.
Industry Challenges
- Certified technician scarcity:NEC 2020 rapid shutdown compliance requirements have outpaced electrician training pipeline capacity across US Sun Belt states.
- Interoperability standard fragmentation:IEEE 2030.5, SunSpec Modbus, and proprietary OEM protocols create integration friction for multi-vendor fleet management platforms.
- CAPEX intensity for grid-forming assets:Utility-scale battery inverters require 40% higher capital commitments than conventional string inverters for equivalent AC capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Solar Power Market |
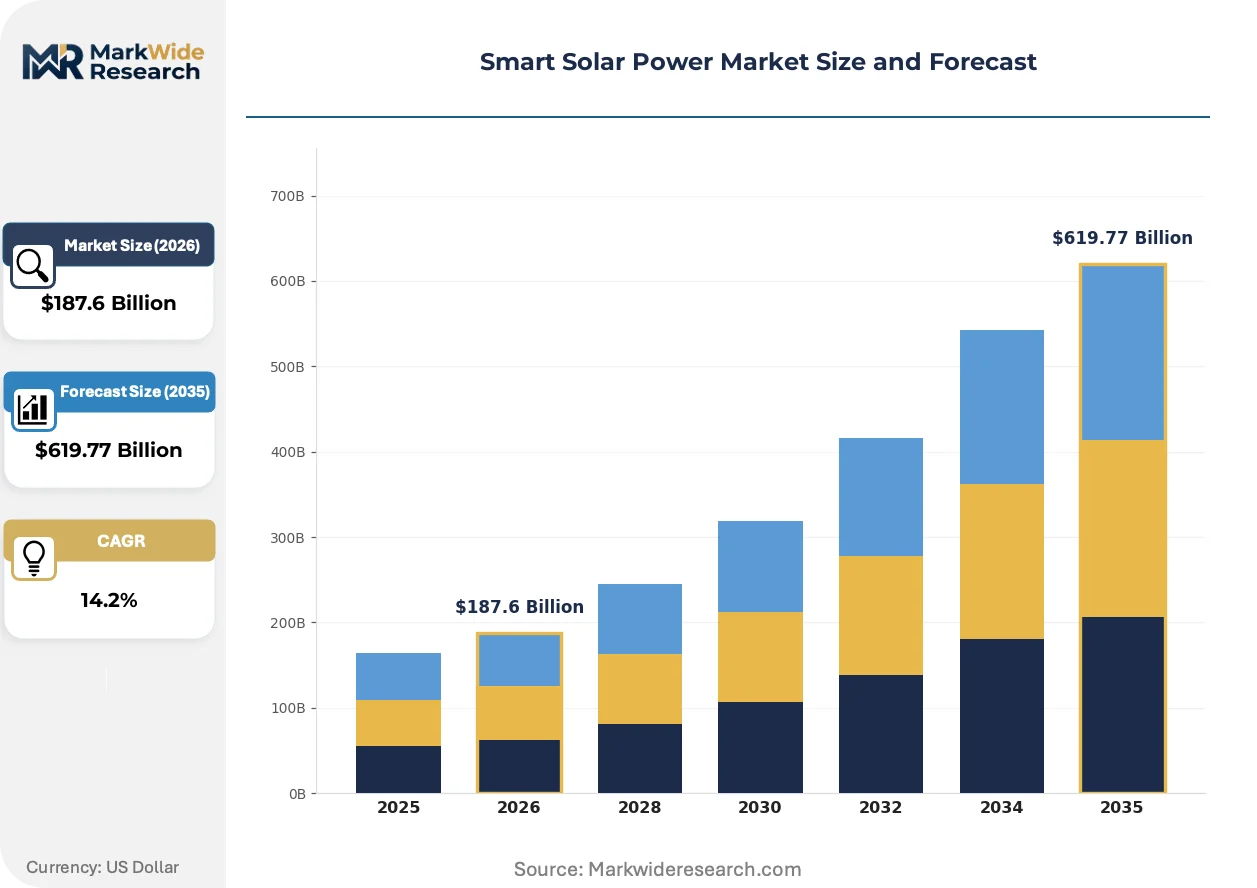
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $619.77 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Cells, Inverters, Energy Management Systems, Smart Meters End User: Residential Buildings, Commercial Buildings, Utility Providers, Industrial Facilities Installation Type: Ground-Mounted, Rooftop, BIPV, Floating Systems Technology: Thin-Film, Monocrystalline, Polycrystalline, Concentrated PV |
| Companies Covered | NextEra Energy Resources, SolarEdge Technologies, First Solar, Lightsource bp US, Recurrent Energy, Sunrun, Cypress Creek Renewables, Avantus, Enphase Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Solar Power Market Strategic Shifts
Digital intelligence layers are migrating from centralized control rooms to module-level electronics, compressing response latencies while fragmenting vendor competitive positions across hardware-software boundaries.
Module-level power electronics is miniaturizing maximum power point tracking circuits onto individual panel backsheets. Commercial rooftop installers in Germany and Australia are specifying these configurations to reduce string mismatch losses below 2%. The technology is miniaturizing balance-of-system component footprints by 60% while enabling granular performance telemetry that undermines traditional string inverter value propositions.
EU Green Deal taxonomy disclosure requirements are mandating supply chain carbon intensity documentation for all renewable energy assets seeking green bond financing. Project developers must now procure modules and inverters from manufacturers with verified Scope 3 emissions audits. Italian and Spanish utility-scale pipelines are experiencing 4-6 month procurement delays as Tier-1 suppliers build ISO 14064 certification capacity.
Corporate offtakers are demanding 15-20 year service performance guarantees with liquidated damages clauses rather than traditional equipment warranties. This shifts risk retention from EPC contractors to inverter and storage OEMs with balance sheet capacity to underwrite long-tail degradation exposure. The practice is most visible in Texas and California where C&I buyers negotiate direct with asset owners, bypassing traditional utility intermediaries.
Smart Solar Power Market Segmentation
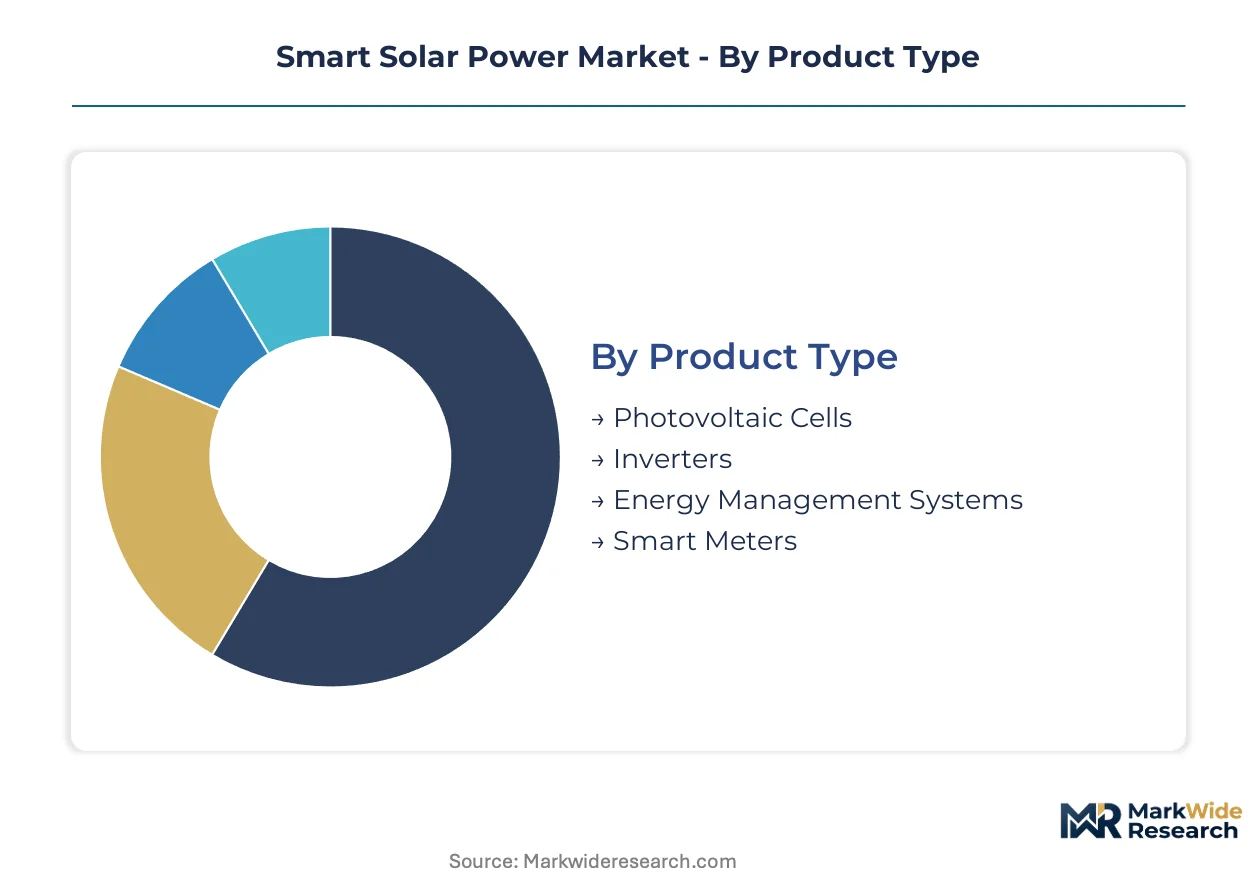
Smart solar power segmentation reveals how hardware commoditization pressures and software value capture reshape vendor economics across the value chain. Component-level differentiation determines margin retention as module prices collapse and intelligence migrates toward edge devices.
Product Type:
Photovoltaic cells face the most acute substitution pressure from next-generation tandem architectures and perovskite alternatives, while energy management systems defend position through data network effects and customer switching costs.
- Photovoltaic Cells:Silicon-based p-n junction devices convert incident photons to direct current through the photovoltaic effect. Utility-scale procurement in China and India concentrates demand for monocrystalline passivated emitter and rear contact (PERC) and tunnel oxide passivated contact (TOPCon) architectures as grid operators prioritize conversion efficiency above 22%.
- Inverters:Power electronics modules transform DC photovoltaic output to grid-synchronous alternating current through pulse-width modulation switching. Residential retrofit markets in Germany and Australia specify module-level power electronics to eliminate string mismatch losses and enable rapid shutdown NEC 2020 compliance without additional hardware.
- Energy Management Systems:Cloud-native software platforms orchestrate generation forecasting, storage dispatch, and demand response through machine learning algorithms. Building electrification mandates in California and New York accelerate attachment rates as heat pump and EV charger coordination requires sub-second load balancing.
- Smart Meters:Bidirectional communication devices measure real-time energy flow and enable net metering settlement through IEEE 2030.5 protocols. EU member states deploying smart grid infrastructure drive replacement cycles as legacy electromechanical meters reach end-of-life.
Photovoltaic cells anchor the volume base while energy management systems gain share at the steepest rate.
End User:
Cost tier stratification separates premium reliability requirements from price-sensitive mass deployment, with industrial facilities and utility providers occupying opposite ends of the specification spectrum.
- Residential Buildings:Single-family and multi-family dwellings deploy rooftop arrays with battery storage to maximize net metering value and backup power resilience. California Title 24 building codes mandate solar readiness for new construction, while NEM 3.0 rate restructuring pushes existing owners toward battery attachment.
- Commercial Buildings:Office, retail, and warehouse properties install solar-plus-storage to reduce demand charges and achieve corporate sustainability commitments. C&I offtakers in Texas and California negotiate direct power purchase agreements with asset owners, bypassing traditional utility intermediaries.
- Utility Providers:Centralized generation entities procure gigawatt-scale projects through competitive tenders and regulated rate-base mechanisms. Grid operators in PJM and ERCOT territories face interconnection queue delays extending energization timelines.
- Industrial Facilities:Manufacturing campuses and data centers require clinical-grade power reliability for continuous operations. EMA standards for healthcare microgrids create premium pricing tiers for solar-plus-storage configurations serving hospital campuses.
Utility providers command the largest absolute capacity additions while commercial buildings expand most quickly behind-the-meter.
Installation Type:
Application-driven geometry constraints determine competitive dynamics, with land availability and structural load limits filtering viable technologies.
- Ground-Mounted:Large-scale arrays on dedicated land parcels optimize tracking systems and economies of scale for utility-scale output. China and India dominate deployment volume as provincial grid operators prioritize dispatchable renewable capacity.
- Rooftop:Building-integrated and building-applied systems leverage existing structural surfaces without land acquisition. Germany and Australia lead commercial rooftop adoption where retail electricity rates exceed levelized solar costs.
- BIPV:Building-integrated photovoltaics replace conventional construction materials with power-generating surfaces. Architectural mandates in European cities accelerate facade and skylight applications.
- Floating Systems:Pontoon-mounted arrays deploy on reservoirs and quarry lakes where land scarcity blocks ground-mount alternatives. Japan and South Korea tender 500MW+ projects as reservoir-constrained markets seek capacity expansion.
Ground-mounted installations retain volume leadership while floating systems climb the fastest as land-constrained geographies exhaust terrestrial sites.
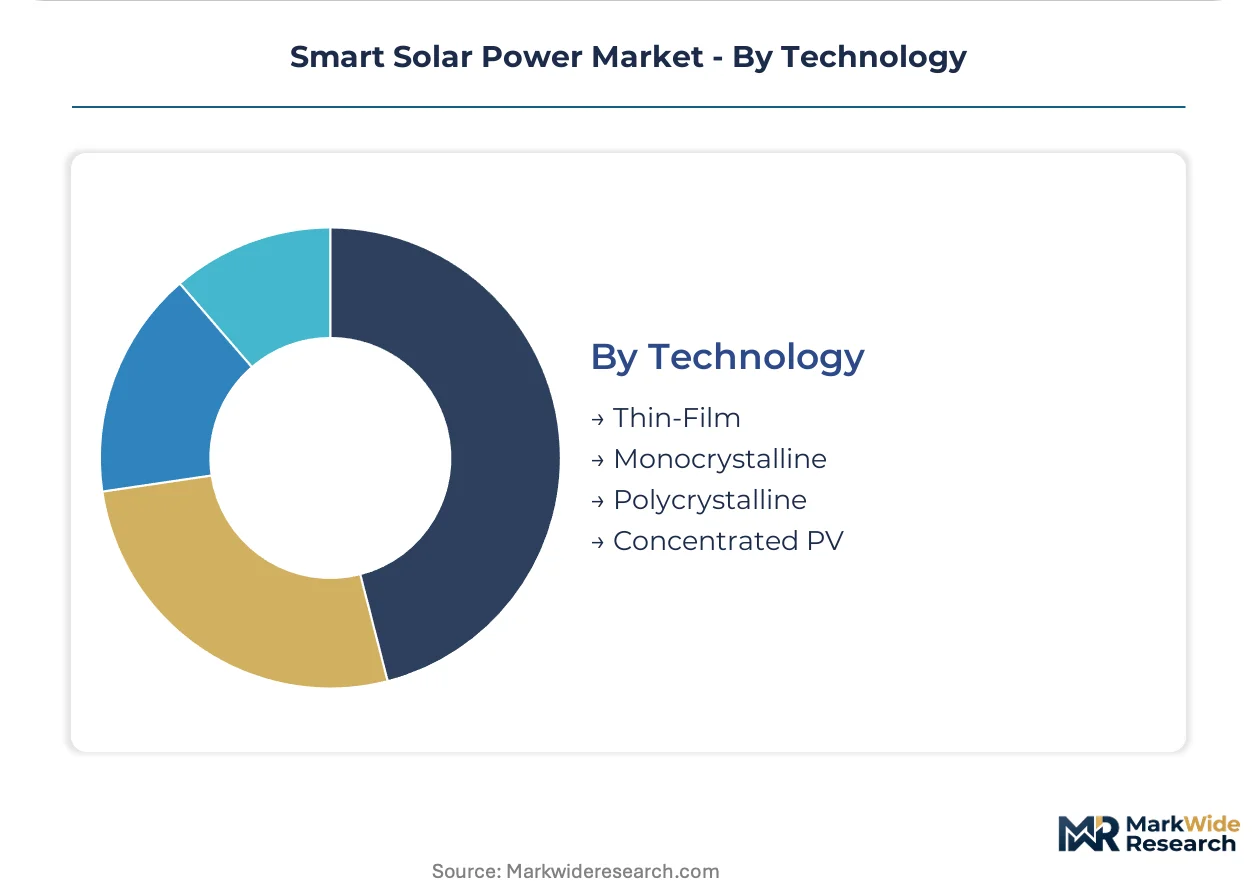
Technology:
Maturity gradients separate proven volume manufacturing from emerging laboratory performance, with crystalline silicon defending incumbent position against thin-film and concentrated alternatives.
- Monocrystalline:Single-crystal silicon wafers deliver the highest commercial conversion efficiencies through uniform electron mobility. Tier-1 manufacturers in China and Southeast Asia achieve 24%+ cell efficiencies through TOPCon and heterojunction architectures.
- Polycrystalline:Multi-crystal silicon ingots offer lower capital intensity and manufacturing energy consumption at reduced efficiency. Cost-sensitive utility markets in India and Brazil specify polycrystalline modules where land availability offsets lower output per watt.
- Thin-Film:Cadmium telluride and copper indium gallium selenide absorber layers enable flexible substrates and low-light performance. First Solar dominates utility-scale thin-film deployment in the US Southwest.
- Concentrated PV:Optical concentrators focus sunlight onto high-efficiency multi-junction cells for specialized high-DNI applications. Desert installations in Saudi Arabia and the UAE leverage direct normal irradiance advantages.
Monocrystalline technology holds the dominant share position while thin-film architectures gain ground in utility-scale procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE enforcement mechanisms in China are compelling provincial grid operators to prioritize dispatchable renewable capacity, while the US IRA production credits are reshoring inverter and module assembly capacity. Germany's EU Green Deal taxonomy requirements are mandating supply chain carbon intensity documentation.
United States
Utility-scale developers in Texas and California negotiate direct power purchase agreements with corporate offtakers, bypassing traditional utility intermediaries. FERC Order 2023 implementation gaps extend project energization timelines by 18-36 months in ERCOT and PJM territories. The Sun Belt states face NEC 2020 rapid shutdown compliance requirements that have outpaced electrician training pipeline capacity.
China
Provincial grid operators prioritize dispatchable renewable capacity in interconnection queues under dual carbon targets enforced by MEE. Xinjiang-sourced metallurgical-grade silicon creates forced labor due diligence burdens under EU Green Deal taxonomy requirements. Yangtze River Delta manufacturers are building ISO 14064 certification capacity to meet disclosure requirements.
Germany
Commercial rooftop installers specify module-level power electronics to reduce string mismatch losses below 2% as retail electricity rates exceed levelized solar costs. EU Green Deal taxonomy disclosure requirements mandate supply chain carbon intensity documentation for green bond financing. Bavarian and North Rhine-Westphalian utility-scale pipelines are experiencing 4-6 month procurement delays.
India
Grid operators prioritize conversion efficiency above 22% for monocrystalline PERC and TOPCon architectures in utility-scale procurement. State-level renewable procurement mandates are expanding across Maharashtra, Gujarat, and Karnataka. Land availability in Rajasthan and Gujarat offsets lower output per watt for cost-sensitive polycrystalline module specifications.
Japan
Reservoir-constrained markets are tendering 500MW+ floating photovoltaic projects where land scarcity blocks ground-mount alternatives. METI grid modernization mandates are accelerating smart meter replacement cycles. Kyushu and Chubu regional utilities are deploying pontoon-mounted arrays on existing hydropower reservoirs.
Smart Solar Power Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the former commanding balance sheet capacity for long-term service guarantees and the latter defending margin position through hardware-software differentiation. The market structure rewards vertical control over development, manufacturing, and asset management functions. Three archetypes dominate: utility-scale developers with captive project pipelines, power electronics specialists with module-level optimization technologies, and residential retrofit platforms with financing integration. Competitive moves concentrate on strategic partnerships for grid-forming inverter deployment and geographic expansion into floating solar markets.
Among US-based integrated developers, NextEra Energy Resources exemplifies the utility-scale archetype through its vertically integrated development platform. SolarEdge Technologies and Enphase Energy occupy positions within the power electronics specialist tier, with the former anchoring module-level optimization and the latter representing microinverter architectures. These three entities collectively illustrate how competitive positioning fragments across hardware-software boundaries as intelligence migrates toward edge devices.
| Leading Market Players |
|---|
| NextEra Energy Resources |
| SolarEdge Technologies |
| First Solar |
| Lightsource bp US |
| Recurrent Energy |
| Sunrun |
| Cypress Creek Renewables |
| Avantus |
| Enphase Energy |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal taxonomy requirements gate both supply qualification and price differentiation simultaneously, forcing manufacturers to absorb ISO 14064 certification costs that stratify module sourcing tiers while developers face 4-6 month procurement delays for compliant components.
Pricing Analysis
Geographic price spreads separate premium European markets from cost-sensitive Asian procurement, with German rooftop installers paying module-level power electronics premiums that Indian utility-scale developers avoid through string inverter specifications. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales bundling, with clinical-grade healthcare microgrid configurations commanding the widest margins. Cost compression in standard-tier residential systems intensifies as Chinese manufacturers expand PERC and TOPCon capacity. Utility-scale offtakers in Texas and California exhibit lowest price sensitivity through long-term power purchase agreements, while residential retrofit buyers in Australia face highest sensitivity to upfront hardware costs.
Supply Chain Analysis
Inventory buffers for silicon carbide switching components and grid-forming inverter assemblies currently stretch lead times beyond traditional string inverter procurement cycles. Manufacturing concentrates in China, Vietnam, and Malaysia for module assembly, with inverter production reshoring to the US under IRA production credits. Polysilicon draws from Xinjiang-sourced metallurgical-grade silicon, silicon wafers, and silver paste metallization inputs. Single-source vulnerability concentrates in Xinjiang polysilicon refining under forced labor due diligence burdens. Distribution runs through vertically integrated developers with captive EPC capabilities and independent distributors serving residential retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among corporate offtakers negotiating direct power purchase agreements, fragmenting traditional utility intermediaries and compressing developer margins across multiple continents.
For Market Incumbents: Compound module-level power electronics differentiation through firmware-locked performance optimization that raises switching costs for commercial rooftop installers. Deepen backward integration into silicon carbide substrate sourcing to secure grid-forming inverter supply against emerging power electronics specialists. Prioritize captive development pipelines in floating solar markets where land scarcity blocks ground-mount alternatives.
For New Entrants and Emerging Players: ISO 14064 certification fast-track unlocks green bond-financed project developer procurement in Germany and Spain where Tier-1 supplier capacity constraints create entry windows. Target floating photovoltaic deployment in Japan and South Korea where reservoir-constrained markets tender 500MW+ projects without established incumbent relationships. Pursue vehicle-to-grid convergence partnerships with bidirectional EV charging protocol developers to monetize residential battery capacity through frequency regulation markets.
For Investors and Strategic Acquirers: FERC Order 2023 implementation reshapes the acquisition landscape by extending energization timelines 18-36 months in ERCOT and PJM territories, favoring developers with interconnection queue management expertise. Long-term viability centers on balance sheet capacity to underwrite 15-20 year service performance guarantees with liquidated damages clauses. Acquisition target archetype: power electronics specialists with module-level optimization IP and software-integrated fleet management platforms. Signal to watch: NEC 2020 rapid shutdown compliance training pipeline expansion indicating technician scarcity resolution.
| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Forming Inverter Deployment | Enables fault ride-through performance above 50% renewable penetration thresholds in ERCOT and PJM territories. |
| Floating Solar Capacity Buildout | Addresses land scarcity constraints in Japan and South Korea through pontoon-mounted reservoir installations. |
| Supply Chain Carbon Certification | Unlocks EU Green Deal taxonomy-compliant green bond financing for Italian and Spanish utility-scale pipelines. |
| Healthcare Microgrid Certification | Captures EMA clinical-grade power reliability premium pricing for hospital campus solar-plus-storage configurations. |
| Vehicle-to-Grid Protocol Integration | Monetizes residential battery capacity through frequency regulation markets using bidirectional EV charging standards. |
Study Parameters
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and grid operators and refined through secondary validation across EIA data, IEA reports, FERC filings, and project development databases. Bottom-up capacity and deployment estimates were triangulated against top-down regulatory mandate analysis across the US IRA, EU Green Deal, and China's dual carbon targets.
Variance decomposition across technology, installation type, and end-user segments shaped the analytical framework over the projection horizon. Modeled dimensions include generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs were derived from segment-level deployment trajectories and policy incentive durability assessments, with inputs from interconnection queue depth, manufacturing tax credit utilization rates, and building electrification mandate compliance timelines.
Decision-makers should treat outputs as directional under sustained IRA production credit authorization and EU taxonomy disclosure enforcement; material deviation in either would warrant model refresh. Specific risk factors include FERC Order 2023 implementation gaps, polysilicon supply chain disruption under forced labor scrutiny, and grid-forming inverter technical limits below high-renewable penetration thresholds. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Boat Solar Panel Market
Solar Power Systems
Southeast Asia Solar Energy Market
Solar Power Systems
North America Rooftop Solar Market
Solar Power Systems
Slovakia Solar Energy Market
Solar Power Systems
Solar Photovoltaic Modules Market
Solar Power Systems
Poland Solar Energy Market
Solar Power Systems
Smart Solar Tracker Market
Solar Power Systems
Building Integrated Photovoltaics Module Market
Solar Power Systems
Solar Shed Light Market
Solar Power Systems
Global Concentrating Solar Power Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
Global Photovoltaic Glass Market
Solar Power Systems
Solar Cullet Market
Solar Power Systems
Europe Solar Photovoltaic (PV) Market
Solar Power Systems
Global Dye-Sensitized Solar Cells (Dssc) Market
Solar Power Systems
Austria Solar Energy Market