
 Coal Fired Power Generation Market | 2026-2036
Coal Fired Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Coal Fired Power Generation Market Intelligence
Buyer concentration among data center operators is realigning procurement priorities across the coal power value chain. General Electric sustains technology leadership in ultra-supercritical turbine systems through deep R&D investment. Mitsubishi Heavy Industries anchors Asian project development with integrated boiler-turbine-generator packages. Siemens Energy competes on efficiency benchmarks in European retrofit markets.
Coal fired power generation converts solid fossil fuel combustion into electricity through steam-driven turbine generators, typically operating at steam temperatures exceeding 540°C and pressures above 24 megapascals in supercritical configurations. The process relies on pulverized coal injection, controlled combustion air ratios, and multi-stage steam expansion to maximize thermal efficiency while managing sulfur oxide and particulate emissions. Ultra-supercritical technology leads capital deployment for new builds due to higher efficiency and lower carbon intensity per megawatt-hour. Subcritical units retain substantial installed base but face accelerated retirement pressure under tightening emission standards. Combined heat and power applications command premium margins where district heating infrastructure exists.
The US EPA enforces Mercury and Air Toxics Standards that compel costly scrubber retrofits or unit shutdowns. China's MEE imposes ultra-low emission limits requiring continuous monitoring and selective catalytic reduction systems. India's CEA mandates phased efficiency upgrades under national capacity addition programs. Stakeholders must weigh stranded asset risk against baseload reliability value as carbon pricing mechanisms expand.
Market Dynamics
Ultra-supercritical turbine retrofits are compressing the economic viability window for subcritical coal assets, forcing operators to choose between capital-intensive upgrades and accelerated decommissioning timelines under tightening emission ceilings.
Growth Catalysts
- Data Center Baseload Demand:Hyperscale facility operators in Southeast Asia are contracting long-term power purchase agreements with coal generators to guarantee grid stability where renewable intermittency risks operational uptime.
- India's FGD Mandate:The Ministry of Environment's flue-gas desulfurization retrofit requirement on older units is creating a captive equipment market for pollution control systems and engineering services.
- Ultra-Low Emission Standards:China's MEE continuous monitoring requirements are driving replacement cycles for selective catalytic reduction catalysts and electrostatic precipitator components.
Market Restraints
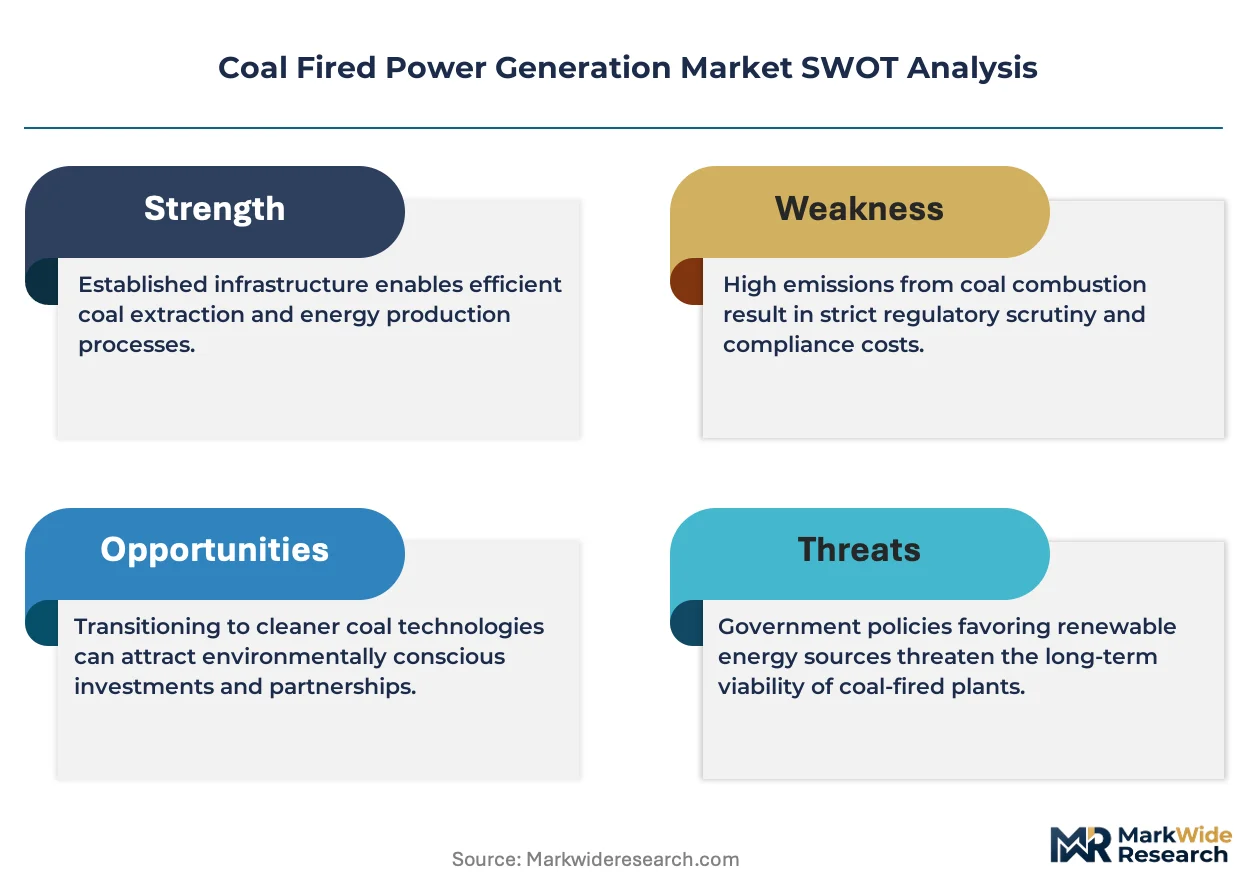
- Carbon Pricing Mechanisms:Expanding emissions trading schemes in the European Union and emerging Asian markets are eroding the marginal cost advantage of coal-fired generation against combined-cycle gas turbines.
- Stranded Asset Risk:Early retirement pressure on subcritical units in North America and Western Europe is compressing residual value recovery periods for project financiers and utility balance sheets.
- Renewable Substitution:Utility-scale solar-plus-storage configurations in India and Vietnam are capturing peak demand hours that previously sustained coal plant load factors.
Strategic Opportunities
- Biomass Co-Firing Retrofits:Existing pulverized coal infrastructure in Poland and the Czech Republic offers conversion pathways to reduce carbon intensity without greenfield capital deployment.
- District Heating Integration:Combined heat and power configurations in Northeast China and Eastern Europe command premium tariffs where municipal heating networks require baseload thermal input.
- Carbon Capture Readiness:New ultra-supercritical builds in Indonesia and Vietnam are incorporating post-combustion capture equipment footprints to future-proof against prospective emission performance standards.
Industry Challenges
- Specialized Welding Expertise:Advanced austenitic steel fabrication for 620°C steam conditions faces a contracting skilled labor pool in mature coal markets where vocational training programs have pivoted toward renewable technologies.
- Legacy Control System Integration:Digital turbine governor retrofits on 1980s-vintage units require bespoke protocol translation layers that extend commissioning timelines and escalate project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coal Fired Power Generation Market |
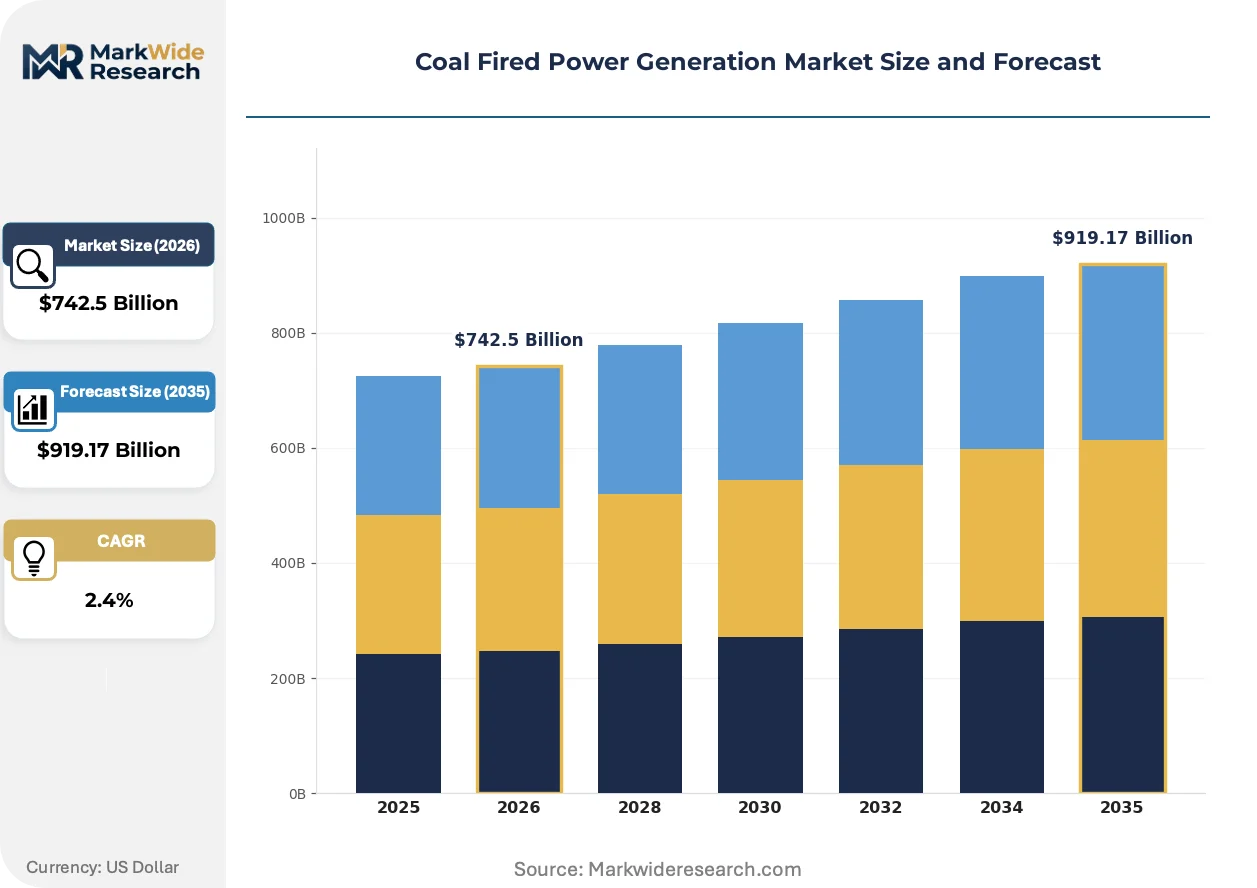
| Market Size in 2026 | $742.5 Billion |
| Market Size in 2035 | $919.17 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Supercritical, Ultra-Supercritical, Subcritical, Circulating Fluidized Bed, Integrated Gasification Combined Cycle Application: Electricity Generation, Industrial Power Supply, Combined Heat & Power, Desalination, District Heating End User Sector: Public Utilities, Manufacturing Plants, Mining Operations, Chemical Processing, Data Centers Fuel Type: Bituminous Coal, Anthracite Coal, Lignite Coal, Subbituminous Coal, Biomass Co-Firing |
| Companies Covered | Mitsubishi Heavy Industries, Harbin Electric Corporation, Dongturbo Electric Company Ltd, Georgia Power, Hitachi, General Electric, Bharat Heavy Electricals Limited, CHN Energy, Siemens Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coal Fired Power Generation Market Strategic Shifts & Innovations
Advanced materials and digital monitoring systems are compressing maintenance intervals while extending operational lifespans for high-pressure steam components. Equipment suppliers are repositioning around efficiency benchmarking and emission compliance rather than pure capacity expansion.
Advanced nickel-based superalloys for ultra-supercritical boiler tubing are expanding into markets where 700°C steam conditions promise efficiency gains above 50 percent. Chinese equipment manufacturers are adopting these materials for domestic retrofit programs. The technology is expanding into Southeast Asian project pipelines as EPC contractors seek performance guarantees that offset carbon intensity concerns.
The US EPA Mercury and Air Toxics Standards enforcement trajectory is compelling scrubber installations or unit retirements across the remaining subcritical fleet. Industrial consequence includes accelerated depreciation schedules and balance sheet write-downs for merchant generators. The PJM and ERCOT interconnection regions are responding with capacity market reforms that partially compensate reliability attributes.
Long-term service agreements are displacing transactional spare parts procurement among European and Asian utility operators. The aftermarket channel faces margin compression as OEMs capture lifecycle value through predictive maintenance subscriptions. This pattern is most visible in Germany and Japan where aging unit populations concentrate maintenance spend with original turbine suppliers.
Coal Fired Power Generation Market Segmentation
Technology choices in coal power directly determine emission compliance costs and residual asset value. Segment-level procurement patterns reveal where operators prioritize efficiency upgrades over retirement, and where regulatory pressure is reshaping fuel and application mixes.
Technology:
Upgrade cycles and replacement timelines vary sharply across thermal efficiency tiers, with newer supercritical configurations commanding extended operational horizons.
- Ultra-Supercritical:Steam conditions exceed 600°C and 30 megapascals, pushing thermal efficiency above 45 percent while minimizing coal consumption per megawatt-hour. Demand concentrates in Vietnam and Indonesia where new builds must satisfy prospective carbon capture readiness standards.
- Supercritical:Operating at 540-600°C and 24-28 megapascals, these units balance capital efficiency with performance gains over subcritical designs. India's Central Electricity Authority mandates efficiency retrofits that favor supercritical conversions for mid-life assets.
- Subcritical:Legacy units below 540°C face accelerated retirement pressure under tightening emission ceilings.
- Circulating Fluidized Bed:Lower combustion temperatures enable fuel flexibility including high-ash domestic coals.
- Integrated Gasification Combined Cycle:Syngas production pathways suit polygeneration applications with carbon capture integration.
Volume placements concentrate in Supercritical; the faster expansion belongs to Ultra-Supercritical.
Application:
End-use diversification determines capacity factor stability and tariff structures across diverging thermal demand profiles.
- Electricity Generation:Baseload grid supply remains the dominant deployment mode, with dispatch priority tied to reliability metrics in Southeast Asian power pools. Data center operators in Singapore and Malaysia are contracting dedicated coal capacity to offset renewable intermittency risks.
- Combined Heat & Power:Simultaneous electricity and thermal output captures efficiency premiums where district heating infrastructure exists. Northeast China and Poland anchor demand as municipal networks require baseload thermal input.
- Industrial Power Supply:Captive generation serves energy-intensive manufacturing with cost predictability.
- Desalination:Thermal desalination co-location suits water-scarce coastal markets in the Middle East.
- District Heating:Seasonal load concentration in Eastern European markets.
Electricity Generation retains the dominant share; Combined Heat & Power is climbing the fastest on efficiency regulation.
End User Sector:
Customer concentration patterns shape contracting structures, with reliability premiums varying across regulated utilities and private offtakers.
- Public Utilities:State-owned generators dominate procurement volumes under national capacity addition programs, particularly in India and Indonesia. India's Ministry of Environment flue-gas desulfurization mandates are concentrating retrofit spending within this segment.
- Data Centers:Hyperscale facility operators are emerging as high-margin offtakers, contracting baseload capacity with uptime guarantees that renewable portfolios cannot match. Southeast Asian markets show the steepest demand trajectory.
- Manufacturing Plants:Captive power needs anchor industrial cluster developments.
- Mining Operations:Remote site generation favors fuel logistics integration.
- Chemical Processing:Process steam requirements sustain combined heat and power economics.
Public Utilities dominate installed capacity; Data Centers are gaining share fastest on reliability premiums.
Fuel Type:
Calorific value and sulfur content specifications determine emission control capital requirements and transport economics.
- Bituminous Coal:High calorific value and moderate sulfur content balance combustion efficiency with scrubber investment needs. Indian power plants favor domestic bituminous blends under import substitution mandates.
- Biomass Co-Firing:Partial substitution of coal with agricultural residues or wood pellets reduces carbon intensity without greenfield capital deployment. Poland and the Czech Republic are retrofitting existing pulverized coal infrastructure for co-firing compliance.
- Lignite Coal:Low energy density requires higher feed rates and enlarged boiler footprints.
- Anthracite Coal:High carbon content suits metallurgical applications over power generation.
- Subbituminous Coal:Lower sulfur profiles reduce emission control burdens in Western US markets.
Bituminous Coal dominates procurement volumes; Biomass Co-Firing shows the steepest expansion trajectory on carbon intensity regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center operators in Singapore and Malaysia are contracting dedicated coal baseload capacity to offset renewable intermittency risks, while India's retrofit mandates concentrate equipment demand domestically.
China
Ultra-supercritical builds in Jiangsu and Zhejiang provinces incorporate post-combustion carbon capture footprints to satisfy prospective emission standards. The Ministry of Ecology and Environment enforces continuous monitoring requirements that drive replacement cycles for selective catalytic reduction catalysts. The Yangtze River Delta anchors domestic equipment manufacturing clusters serving Southeast Asian export markets.
India
The Central Electricity Authority mandates efficiency retrofits favoring supercritical conversions for mid-life assets across Maharashtra and Gujarat. The Ministry of Environment's flue-gas desulfurization retrofit requirement concentrates pollution control equipment procurement within state-owned generation fleets. The National Capital Region and surrounding industrial corridors face accelerated scrubber deployment timelines under regional air quality directives.
Indonesia
New ultra-supercritical capacity additions on Java island target prospective carbon capture readiness standards for future emission compliance. PLN's procurement programs favor integrated boiler-turbine-generator packages from Japanese and Chinese equipment suppliers. The Jakarta-Bandung industrial corridor sustains captive power demand from energy-intensive manufacturing clusters.
Vietnam
Utility-scale solar-plus-storage configurations in the Mekong Delta are capturing peak demand hours that previously sustained coal plant load factors. The national power development plan nonetheless sanctions ultra-supercritical builds in northern provinces to guarantee grid stability where renewable buildout lags demand growth. The Red River Delta concentrates foreign EPC contractor activity around efficiency benchmarking guarantees.
Poland
Existing pulverized coal infrastructure in the Silesian and Łódź voivodeships offers biomass co-firing conversion pathways to reduce carbon intensity without greenfield capital deployment. EU emission trading scheme compliance costs are eroding marginal cost advantages against combined-cycle gas turbines. The Upper Silesian industrial basin sustains combined heat and power economics through municipal district heating network integration.
Coal Fired Power Generation Market Key Industry Players
Japanese producers anchor one tier; German specialists hold efficiency benchmarking positions in European retrofit markets. The vendor base stratifies across integrated turbine-generator OEMs, regional boiler fabricators, and pollution control subsystem suppliers. Three archetypes dominate: technology licensors pursuing long-term service agreements, EPC contractors bundling equipment packages, and aftermarket specialists capturing predictive maintenance subscriptions. Competitive moves concentrate on strategic partnerships for carbon capture integration and geographic expansion into Southeast Asian project pipelines.
Among Japanese integrated heavy industrial conglomerates, Mitsubishi Heavy Industries occupies a position exemplifying the full-system package archetype. Chinese state-affiliated electrical equipment groups, represented by Harbin Electric Corporation and Dongturbo Electric Company Ltd, anchor domestic retrofit programs and regional export positioning. These entities represent scale-driven fabrication capacity serving national capacity addition mandates across Asia-Pacific markets.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| Harbin Electric Corporation |
| Dongturbo Electric Company Ltd |
| Georgia Power |
| Hitachi |
| General Electric |
| Bharat Heavy Electricals Limited |
| CHN Energy |
| Siemens Energy |
| Others |
Cost & Logistics Intelligence
Captive integration into advanced nickel-based superalloy production anchors both supply security and pricing power for ultra-supercritical turbine OEMs serving Southeast Asian project pipelines. Japanese and Chinese equipment manufacturers maintain in-house forging capacity for 620°C steam condition components, insulating against raw material volatility while commanding performance-guarantee premiums.
Pricing Analysis
Volume placements concentrate in supercritical retrofit packages where scale economies compress unit margins, while ultra-supercritical new builds capture efficiency premiums through performance-linked contracting. Price differentiation hinges on steam condition certification tiers and bundled long-term service agreements that lock in aftermarket revenue streams. Cost compression in subcritical equipment markets is intensifying because stranded asset risk accelerates depreciation schedules for merchant generators. Public utilities in India and Indonesia exhibit lowest price sensitivity due to national capacity mandates, whereas independent power producers in Vietnam face acute margin pressure from renewable substitution.
Supply Chain Analysis
Dual-sourcing requirements for advanced austenitic steel boiler tubing mandate qualification of both Japanese and Chinese forging suppliers, extending procurement timelines but mitigating single-source vulnerability. Geographic supply concentration centers on China, Japan, and Germany for ultra-supercritical pressure components, with India emerging for pollution control subsystem fabrication. Raw material dependencies include nickel-chromium superalloys, high-purity steel billets, and specialized welding consumables. Tariff exposure on Chinese steel inputs threatens margin stability for European EPC contractors. Distribution runs through integrated boiler-turbine-generator packages contracted directly to state-owned generation fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coal fired power generation market occupies a technology-transition phase where ultra-supercritical steam conditions displace subcritical baseload capacity under tightening emission ceilings. This shift compresses viable operational horizons for legacy assets while concentrating capital deployment in efficiency-upgraded configurations.
For Market Incumbents: Lock in long-term service agreements with state-owned utilities in India and Indonesia before aftermarket channels face margin compression from predictive maintenance subscriptions. Prioritize backward integration into advanced alloy forging capacity to secure supply positions for 700°C steam condition components. Carbon pricing mechanisms in emerging Asian markets threaten residual value recovery; defend against stranded asset risk by embedding carbon capture readiness footprints in new build specifications. For New Entrants and Emerging Players: Begin with biomass co-firing retrofit opportunities in Poland and the Czech Republic where existing pulverized coal infrastructure offers conversion pathways without greenfield capital deployment. Target district heating integration projects in Northeast China and Eastern Europe where municipal networks require baseload thermal input and command premium tariffs. Pursue equipment leasing models bundled with emission compliance guarantees to penetrate state-owned utility procurement channels. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated heavy industrial conglomerates seeking Southeast Asian project pipelines. Five-to-ten year viability hinges on carbon capture technology maturation and regional emission trading scheme expansion. Acquisition targets should display captive superalloy fabrication capacity and established relationships with PLN or NTPC procurement programs. The signal to watch is FGD retrofit mandate acceleration in India's National Capital Region, which would concentrate equipment demand domestically and validate pollution control subsystem valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Ultra-Supercritical Capacity Buildout | New builds in Vietnam and Indonesia satisfy prospective carbon capture readiness standards under MEE monitoring protocols. |
| Flue-Gas Desulfurization Retrofit Programs | India's Ministry of Environment mandates concentrate pollution control equipment procurement within state-owned generation fleets. |
| Biomass Co-Firing Conversion | Poland and Czech Republic pulverized coal infrastructure reduces carbon intensity without greenfield capital deployment. |
| Long-Term Service Agreement Expansion | Predictive maintenance subscriptions capture lifecycle value from aging unit populations in Germany and Japan. |
| District Heating Integration | Combined heat and power configurations in Northeast China command premium tariffs through municipal network baseload requirements. |
Research Approach
Independent corroboration across EPC contractor project databases, utility procurement disclosures, and equipment supplier order backlogs underwrites the qualitative findings in this study. Primary interviews with IPP project developers, state utility planning officers, and aftermarket service heads were combined with secondary validation from EIA generation statistics, IEA power sector reports, and FERC interconnection queue data. Bottom-up capacity addition tracking and top-down regulatory impact assessment were triangulated to establish market sizing boundaries.
Comparable-period anchoring to historical capacity commissioning rates and retrofit cycle frequencies established the forecast window baseline. The analytical framework models segmentation across technology efficiency tiers, application modes, end-user sector concentration, and fuel type specifications throughout the projection horizon. CAGRs were derived from unit-by-unit retirement probability modeling weighted by emission compliance cost trajectories. Forecast inputs include national power development plan targets, carbon pricing mechanism adoption schedules, and data center load growth projections for Southeast Asian markets.
Regulatory mandate acceleration, carbon capture technology cost curves, and renewable-plus-storage substitution rates are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding FGD retrofit timelines, ultra-supercritical equipment import tariffs, and state-owned utility procurement budget allocations. A model refresh is warranted upon material change in India's Ministry of Environment enforcement trajectory or Vietnam's solar-plus-storage deployment pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Algeria Power Market
Power Generation
Temporary Power Generation & Power Rental Market
Power Generation
Peaking Power Plant Market
Power Generation
North America Distributed Power Generation Market
Power Generation
Distributed Generation Market
Power Generation
India Gensets Market
Power Generation
India Thermal Power Plant Market
Power Generation
Power Sector North America Gas Turbine MRO Market
Power Generation
Micro CHP Market
Power Generation
Gas Turbines in Thermal Power Market
Power Generation
Oman Power Market
Power Generation
Global Natural Gas Fired Electricity Generation Market
Power Generation
East Africa Power Market
Power Generation
Thermal Power Market
Power Generation
Power Generation Technologies Market
Power Generation
Philippines Power Generation EPC Market