
 GCC Induction Motor Market | 2026-2036
GCC Induction Motor Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Induction Motor Market Intelligence
Direct procurement channels between original equipment manufacturers and large oil and gas operators is reshaping how induction motors flow into GCC industrial projects. Siemens AG leverages its long-standing service infrastructure across Saudi Arabia and the UAE to sustain aftermarket revenue streams. ABB Ltd. anchors its regional position through localized manufacturing and technical support centers. WEG Industries competes aggressively on cost efficiency for mid-tier pump applications in water and wastewater projects.
An induction motor converts electrical energy into mechanical rotation through electromagnetic induction between stator windings and a conductive rotor, typically operating at fixed speeds determined by supply frequency and pole count; squirrel cage designs dominate industrial installations due to their rugged construction and minimal maintenance requirements. Three-phase configurations occupy the largest share of GCC demand, driven by heavy-duty applications in oil extraction and petrochemical processing. Single-phase units retain relevance in smaller HVAC and commercial pumping installations across the Gulf states. The wound rotor segment serves specialized high-torque starting requirements in mining and crusher applications where speed control matters.
Saudi Standards, Metrology and Quality Organization and the UAE's Emirates Authority for Standardization and Metrology enforce efficiency classifications that filter substandard equipment from Gulf markets. IEC efficiency standards and ISO mechanical vibration limits further define product eligibility for regional tenders. Stakeholders must track how carbon intensity requirements for industrial facilities reshape motor specification criteria in upcoming project cycles.
Market Dynamics
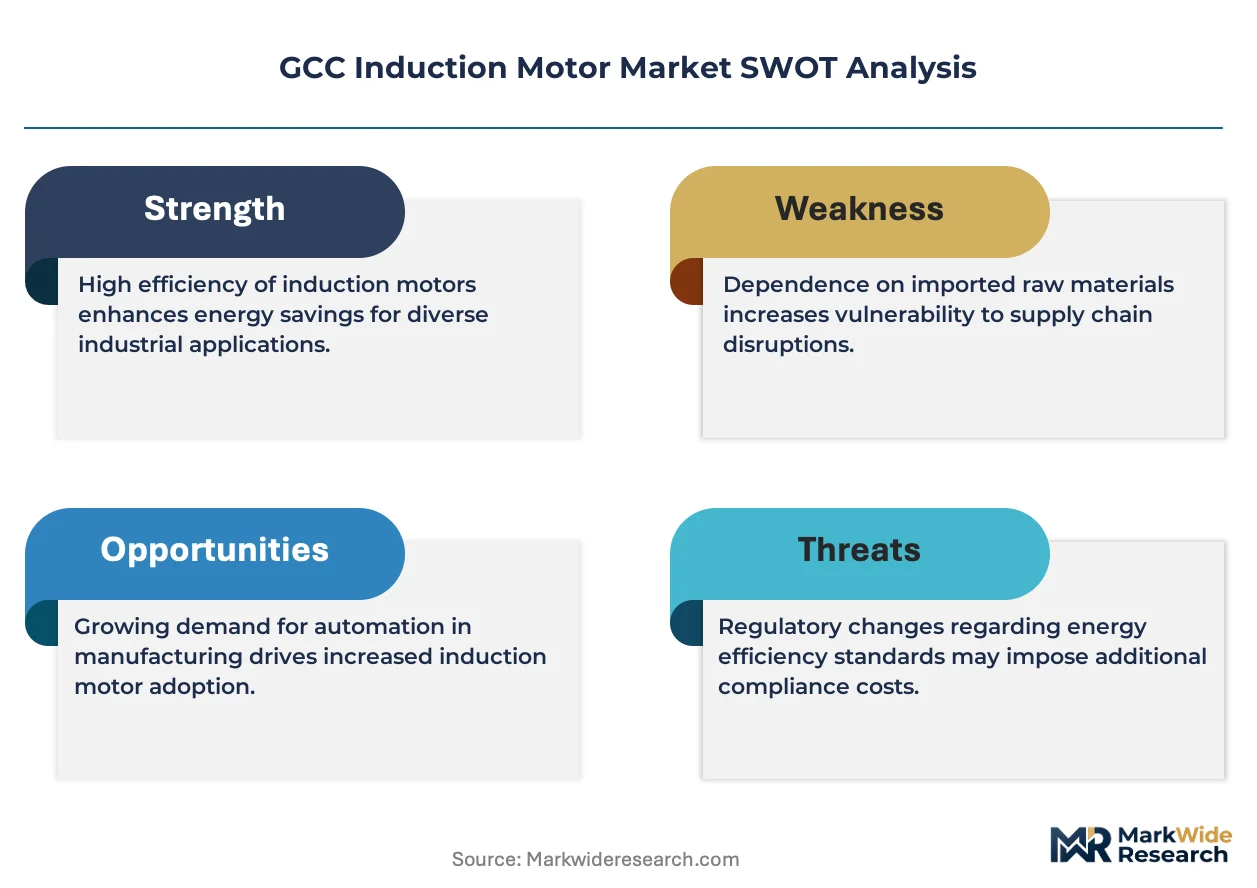
Efficiency mandates from Saudi Standards, Metrology and Quality Organization and the UAE's Emirates Authority for Standardization and Metrology are compressing replacement cycles across Gulf industrial corridors. These regulations filter substandard equipment from regional tenders while accelerating demand for premium-efficiency motor classes.
Growth Catalysts
- IE3 Efficiency Mandates:Saudi Standards, Metrology and Quality Organization and the UAE's Emirates Authority for Standardization and Metrology now require minimum IE3 classifications for motors above specified power thresholds. This forces replacement of aging IE1 and IE2 installed bases across petrochemical and desalination facilities.
- Petrochemical Capacity Expansion:Saudi Arabia's Eastern Province industrial corridor hosts concentrated greenfield and brownfield projects requiring heavy-duty three-phase induction motors for pump and compressor duty. Operators specify premium efficiency classes to meet carbon intensity benchmarks.
- Desalination Infrastructure Buildout:Reverse osmosis and thermal desalination plants across Kuwait, Qatar, and the UAE deploy high-reliability squirrel cage motors for continuous pumping operations. Water security priorities sustain procurement momentum regardless of oil price cycles.
Market Restraints
- Copper and Electrical Steel Volatility:Raw material input costs for stator windings and laminated cores fluctuate with commodity markets. Manufacturers struggle to pass through price swings to long-term frame contract customers in oil and gas.
- Consolidated OEM Supply Base:Regional production concentrates among a limited set of manufacturers with localized assembly facilities. This geographic concentration creates vulnerability to logistics disruptions and limits price competition at the premium tier.
- Permanent Magnet Motor Substitution:Rare-earth permanent magnet synchronous motors offer superior efficiency and power density for variable-speed applications. These systems displace induction technology in new HVAC and some pump installations where electronic drives are standard.
Strategic Opportunities
- Retrofit Services for Aging Installed Base:Thousands of IE1 and IE2 motors operate across Saudi Aramco and ADNOC facilities. Specialized rewinding and efficiency upgrade services capture margin from operators seeking compliance without full replacement.
- Digital Condition Monitoring Integration:Vibration sensors and thermal monitoring systems converge with induction motor hardware. Predictive maintenance contracts create recurring revenue streams and lock in aftermarket relationships with large operators.
- Kuwait and Qatar Water Infrastructure:These markets show lower motor penetration per capita of desalination capacity compared to Saudi Arabia and the UAE. Planned capacity additions through 2035 represent white space for mid-tier suppliers.
Industry Challenges
- Certification Timeline Compression:IEC efficiency testing and regional homologation requirements add months to product qualification. Manufacturers must pre-certify broad product ranges to participate in fast-track tender processes.
- Legacy Control System Integration:Many Gulf petrochemical facilities operate 20-30 year old distributed control systems. New high-efficiency motors with advanced electronic protection create interfacing complexity that delays procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Induction Motor Market |
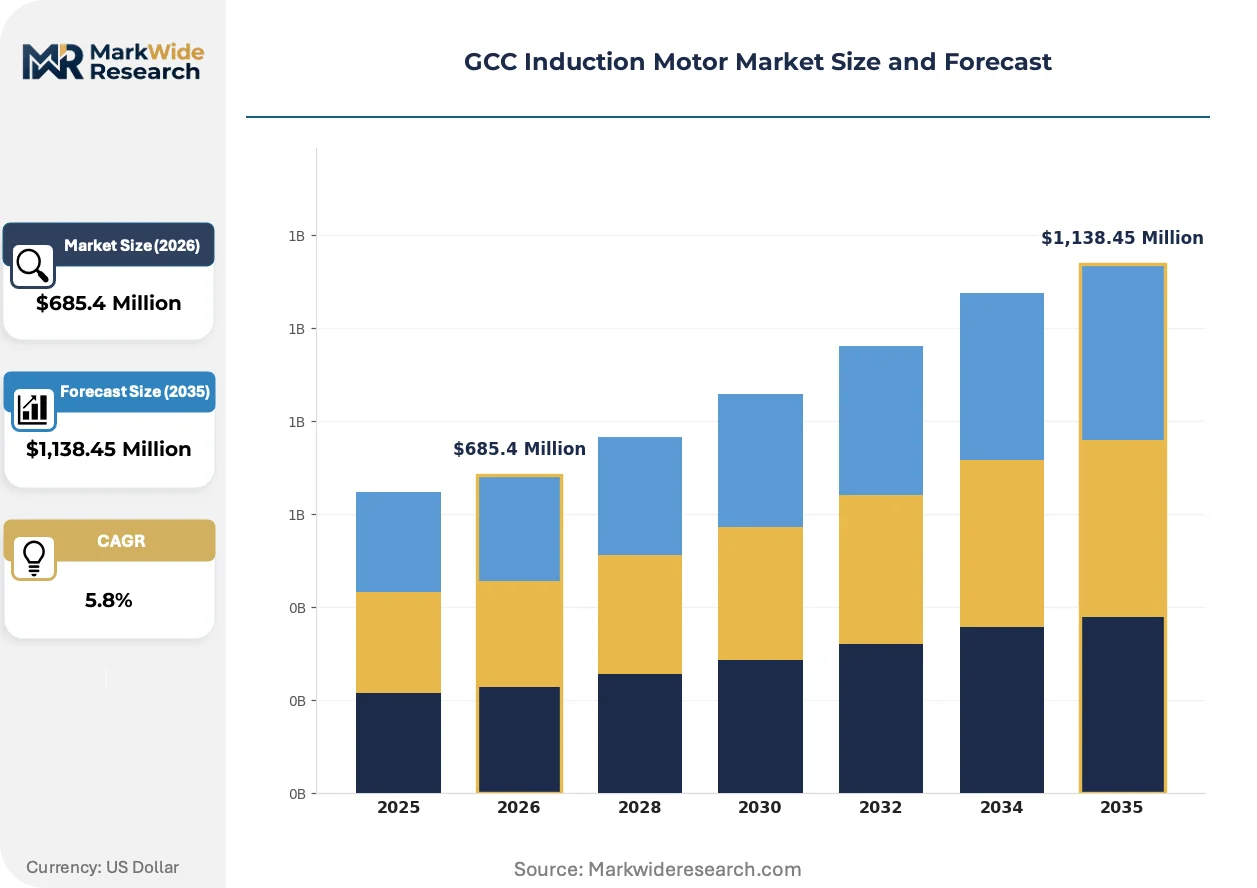
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: Squirrel Cage, Wound Rotor, Single Phase, Three Phase End User: Manufacturing, Oil & Gas, HVAC, Mining Application: Pumps, Fans, Crushers, Conveyors Installation Type: Indoor, Outdoor, Portable, Integrated |
| Companies Covered | ABB Ltd., Siemens AG, General Electric, WEG Industries, Nidec Corporation, Schneider Electric, Regal Beloit Corporation, Emerson Electric, Rockwell Automation, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Induction Motor Market Strategic Shifts & Innovations
Digital twin technology and condition-based maintenance protocols are redefining how Gulf operators manage rotating equipment. These innovations compress downtime costs while reshaping supplier-customer relationships around uptime guarantees rather than hardware transactions.
Variable frequency drive integration is virtualizing the traditional fixed-speed induction motor paradigm. Drive manufacturers now bundle optimized motor-drive packages where the power electronics actively compensate for motor thermal and magnetic characteristics. Saudi petrochemical operators specify these integrated systems for new pump stations, collapsing the historical separation between motor procurement and control system selection.
Saudi Standards, Metrology and Quality Organization is aligning its motor efficiency roadmap with EU Ecodesign regulations and IEC 60034-30-1 standards. This regulatory convergence eliminates the historical Gulf-specific efficiency tiers that created product fragmentation. Manufacturers now design single global product families covering European and Middle Eastern requirements, simplifying inventory but intensifying price competition on standardized platforms.
Direct procurement relationships between end-users and OEMs are displacing traditional distributor channels for large project volumes. Saudi Aramco and ADNOC now maintain approved vendor lists with frame agreements covering multi-year motor supply. This channel consolidation squeezes regional distributors toward smaller commercial and maintenance-replacement volumes while rewarding OEMs with service infrastructure and localized technical support capabilities.
GCC Induction Motor Market Segmentation
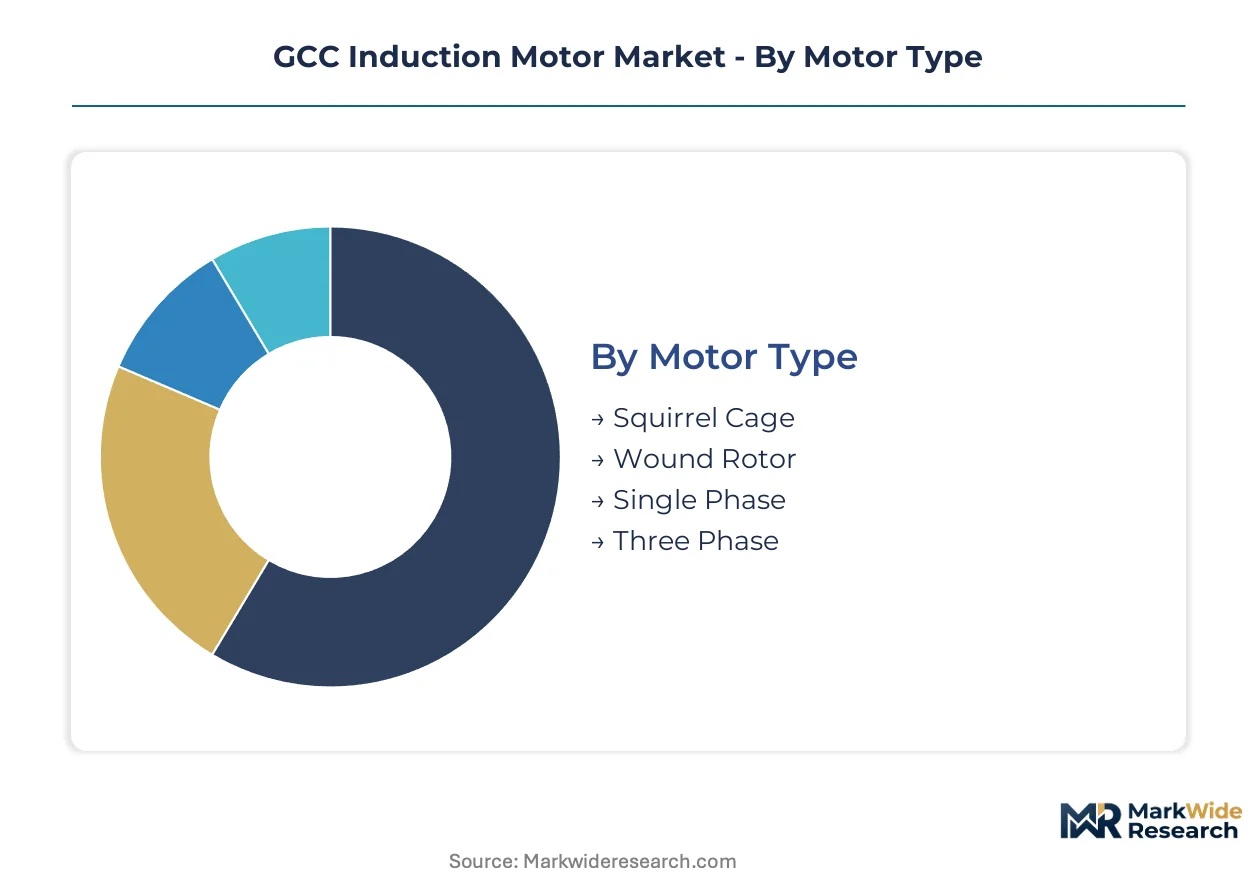
Segmentation in the GCC induction motor market reveals how technical specifications align with the region's industrial infrastructure. Oil and gas operators, desalination utilities, and petrochemical complexes each impose distinct performance requirements that shape procurement patterns across motor categories.
Motor Type:
Use-case spectrum spans fixed-speed heavy-duty installations to specialized variable-torque applications across Gulf industrial corridors.
- Three Phase:Polyphase alternating current configuration delivers constant power output with high starting torque. Concentrated demand flows to Saudi Arabia's Eastern Province petrochemical complexes and UAE desalination facilities where continuous pump duty dominates. IE3 efficiency mandates from Saudi Standards, Metrology and Quality Organization and Emirates Authority for Standardization and Metrology accelerate replacement of aging lower-efficiency units.
- Squirrel Cage:Cast aluminum or copper rotor bars embedded in laminated steel cores create rugged, maintenance-minimal designs. Desalination plants across Kuwait, Qatar, and the UAE specify these for reverse osmosis high-pressure pump duty where reliability outweighs speed control needs.
- Wound Rotor:External resistance control enables high-torque starting for mining crushers and material handling equipment.
- Single Phase:Split-phase or capacitor-start designs serve smaller HVAC and commercial pumping installations in Gulf commercial buildings.
Established volume favors Three Phase; emerging adoption favors Wound Rotor where speed control requirements expand.
End User:
Customer concentration mirrors the GCC's economic structure, with hydrocarbon and water infrastructure commanding premium procurement volumes.
- Oil & Gas:Upstream extraction and downstream refining operations deploy explosion-proof and premium-efficiency motors for pump and compressor duty. Saudi Aramco and ADNOC frame agreements concentrate procurement through direct OEM channels.
- Manufacturing:Petrochemical derivatives production and basic materials processing require continuous-duty motors with predictive maintenance integration.
- HVAC:Commercial building cooling loads sustain demand for smaller single-phase and three-phase units across Gulf urban centers.
- Mining:Quarrying and mineral processing in Oman and Saudi Arabia drives specialized high-torque wound rotor applications.
Procurement scale concentrates with Oil & Gas; service contract innovation concentrates with Manufacturing.
Application:
Mechanical load characteristics determine motor specification priority, from constant-torque pumping to variable-torque material handling.
- Pumps:Centrifugal and positive displacement pumping dominates motor deployment across desalination, oil transfer, and water distribution. Saudi Arabia's Jubail and Yanbu industrial cities host concentrated procurement for high-pressure reverse osmosis and crude oil pipeline applications.
- Fans:Axial and centrifugal ventilation systems serve cooling towers and process air handling in petrochemical facilities.
- Crushers:Jaw and cone crushing equipment in mining and quarrying requires high starting torque wound rotor designs.
- Conveyors:Bulk material handling systems integrate across port terminals and processing plants.
Operational criticality elevates Pumps; maintenance intensity elevates Crushers.
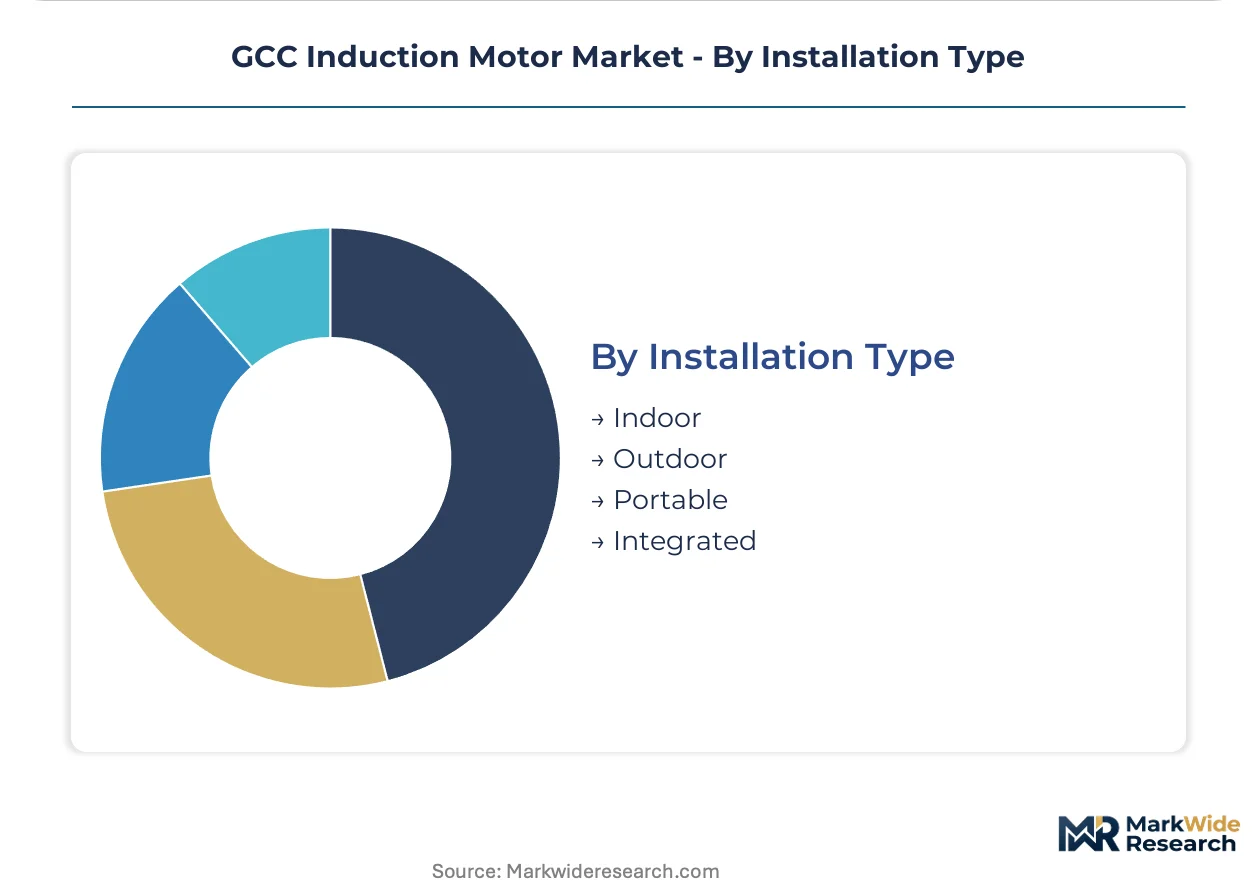
Installation Type:
Environmental exposure and mobility requirements segment motor housing and protection specifications.
- Outdoor:Totally enclosed fan-cooled and weather-protected designs withstand Gulf coastal humidity, sand, and temperature extremes. Desalination intake stations and oil field wellhead installations specify these across Saudi Arabia's Eastern Province and UAE coastal zones.
- Indoor:Open drip-proof and standard enclosed designs serve climate-controlled process buildings and substations.
- Portable:Skid-mounted and trailer-based configurations support temporary dewatering and construction applications.
- Integrated:Motor-pump and motor-compressor packages from OEMs collapse procurement complexity for large project tenders.
Reliability engineering focuses on Outdoor; procurement simplification favors Integrated.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The GCC Interconnection Authority's 400-kilovolt grid network underwrites regional electricity trade and stabilizes industrial power quality for motor-intensive operations across member states.
Saudi Arabia
Saudi Aramco's Marjan and Zuluf offshore expansions drive three-phase motor procurement for crude oil pumping and gas compression. Saudi Standards, Metrology and Quality Organization mandates IE3 efficiency minimums for motors above 0.75 kilowatts. Jubail Industrial City hosts concentrated petrochemical complexes where operators specify premium-efficiency squirrel cage designs for continuous process duty.
United Arab Emirates
ADNOC's Ruwais Derivatives Complex and Al Yasat offshore developments sustain heavy-duty motor demand for pump and compressor applications. Emirates Authority for Standardization and Metrology enforces efficiency classifications aligned with IEC 60034-30-1 standards. Jebel Ali Industrial Zone clusters manufacturing and logistics facilities requiring mid-tier three-phase motors for material handling and HVAC systems.
Kuwait
The Al-Zour Refinery and Northern Oil Field expansion projects require explosion-proof motors for hazardous area pump duty. The Ministry of Electricity and Water oversees efficiency compliance for desalination infrastructure. Doha West and Shuaiba power and water stations deploy high-reliability squirrel cage motors for reverse osmosis high-pressure pump operations.
Qatar
North Field East expansion and Ras Laffan Petrochemical Complex developments concentrate motor procurement for gas processing and LNG train compression. Qatar General Electricity and Water Corporation specifications emphasize reliability metrics for rotating equipment. Ras Laffan Industrial City integrates motor-intensive operations across hydrocarbon export terminals and downstream processing units.
Oman
Duqm Refinery and Special Economic Zone projects generate demand for process motors in greenfield industrial installations. Oman Authority for Academic Accreditation and Quality Assurance of Education extends to industrial equipment standards through technical workforce certification requirements. Sohar Port and Freezone clusters aluminum smelting and polypropylene production requiring continuous-duty motor systems.
GCC Induction Motor Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying standardized frames and windings to regional assembly operations. The supplier base concentrates among multinational OEMs with localized production facilities and established service networks. Two strategic archetypes dominate: full-system integrators bundling motors with drives and controls, and component-focused manufacturers competing on frame cost and delivery speed. Capacity expansion and strategic partnerships represent the primary competitive vectors as firms seek to anchor long-term frame agreements with national oil companies.
Among European-headquartered industrial conglomerates, ABB Ltd. and Siemens AG exemplify the integrated-system archetype through established Middle East technical centers and aftermarket service infrastructure. WEG Industries occupies a position within the cost-optimized component tier, supplying mid-range squirrel cage designs for water infrastructure and commercial applications. These three anchors illustrate the competitive spectrum from premium system integration to volume-focused component supply.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| General Electric |
| WEG Industries |
| Nidec Corporation |
| Schneider Electric |
| Regal Beloit Corporation |
| Emerson Electric |
| Rockwell Automation |
| Others |
Cost & Logistics Intelligence
Jebel Ali Port freight corridors channel copper and electrical steel from Far East mills into GCC assembly plants, concentrating inbound logistics costs among Dubai-based distributors while fragmentating price negotiation leverage for smaller Omani and Qatari buyers.
Pricing Analysis
Volume-discount tiering structures separate frame-contract pricing for Saudi Aramco and ADNOC from spot-market transactions serving maintenance replacements. IE3 certification premiums and localized technical support bundling differentiate premium-tier suppliers from mid-market competitors. Pricing pressure stems from rare-earth permanent magnet motor substitution in variable-speed HVAC applications. Small commercial contractors exhibit highest price sensitivity; national oil companies prioritize lifecycle efficiency over upfront capital cost.
Supply Chain Analysis
Contract manufacturing concentrates among ABB's Jeddah facility, Siemens' Dammam technical center, and WEG's Dubai assembly operations. Laminated electrical steel draws from Japanese and Korean mills; copper windings source from Chilean and Zambian smelters. Single-source vulnerability in rare-earth magnet supply chains for competing permanent magnet technologies threatens induction motor cost positioning. Distribution runs through direct OEM channels for large projects and electrical wholesalers for commercial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Saudi Aramco and ADNOC frame agreements that displace distributor intermediaries, compressing margin capture for suppliers lacking localized service infrastructure.
For Market Incumbents: Insulate aftermarket revenue through predictive maintenance platform deployment and rewinding service capacity expansion. Permanent magnet motor substitution in pump applications threatens induction motor volume; backward integration into copper winding fabrication secures margin against commodity volatility.
For New Entrants and Emerging Players: Establish a beachhead in Kuwait and Qatar desalination infrastructure where motor penetration per capita lags Saudi Arabia and the UAE. Mid-tier squirrel cage designs for reverse osmosis pump duty offer lowest competitive density; partner with European component suppliers for rapid IEC certification.
For Investors and Strategic Acquirers: IE4 efficiency roadmap alignment by Saudi Standards, Metrology and Quality Organization reshapes the acquisition landscape toward rewind-service specialists with upgrade engineering capabilities. Long-term viability hinges on digital condition monitoring integration; target firms with installed-base data access. Watch for carbon intensity benchmarking in petrochemical tenders as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Localized Manufacturing Scale-Up | Jeddah and Dammam facilities anchor Saudi Aramco frame agreement eligibility. |
| Aftermarket Service Network Expansion | Predictive maintenance contracts lock in ADNOC rotating equipment relationships. |
| Efficiency Certification Pre-Investment | IE4-ready designs anticipate Saudi Standards, Metrology and Quality Organization roadmap. |
| Digital Twin Integration Partnership | Condition monitoring bundling collapses hardware-transaction pricing models. |
| Rewind and Upgrade Service Acquisition | Installed-base access captures IE1-to-IE3 retrofit demand without full replacement. |
Research Approach
Operator-level perspectives from maintenance directors at Saudi Aramco and ADNOC facilities, plant engineers at Jubail petrochemical complexes, and procurement leads at Kuwait's Ministry of Electricity and Water anchored the qualitative base. Secondary validation drew from Saudi Standards, Metrology and Quality Organization efficiency filings, Emirates Authority for Standardization and Metrology regulatory updates, IEC 60034 test reports, and customs trade data for copper and electrical steel imports. Bottom-up project pipeline enumeration triangulated against top-down industrial capacity forecasts.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated efficiency mandate trajectories. Segmentation dimensions modeled motor type, end-use industry, application load characteristic, and installation environment across the projection horizon. CAGRs derived from unit deployment rates tied to named project developments and replacement cycle compression under regulatory pressure.
Stress conditions across copper price volatility, rare-earth magnet cost trajectories, and efficiency mandate implementation timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about industrial project sanctioning rates and regulatory enforcement consistency. Quarterly review of tender award patterns and efficiency standard draft releases is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Composite Insulators Market
Electrical Power Equipment
Domestic Hot Water (DHW) Tanks Market
Electrical Power Equipment
Global Explosion-Proof Electric Motors and Actuators Market
Electrical Power Equipment
US Electric Towers and Poles Market
Electrical Power Equipment
Global Duct Heaters Market
Electrical Power Equipment
Hollow Core Insulator Market
Electrical Power Equipment
Portable Space Heater Market
Electrical Power Equipment
Subsea Cables Equipment Market
Electrical Power Equipment
Packaged Substation Market
Electrical Power Equipment
Substation Market
Electrical Power Equipment
Power Line Filters Market
Electrical Power Equipment
Electrical Steel for Electric Vehicle Market
Electrical Power Equipment
Overhead Power Cables Market
Electrical Power Equipment
Immersion Heater Market
Electrical Power Equipment
Alternating Current (AC) Electric Drives Market
Electrical Power Equipment
Carbon Brush Market