
 Hollow Core Insulator Market | 2026-2036
Hollow Core Insulator Market Size, Share, and Industry Trends Forecast 2026-2036
Hollow Core Insulator Market Outlook
The capital-intensity divergence between in-house filament winding capabilities and outsourced composite fabrication is unwinding competitive hierarchies across the supplier base. Hitachi Energy leverages vertically integrated manufacturing of silicone-housing composite insulators to secure utility tenders in high-voltage corridors. NGK Insulators anchors its position through sustained dominance in ceramic-based hollow core designs for established Asian grid operators. MacLean Power Systems competes by specializing in polymer-core transmission products tailored to North American utility specifications.
A hollow core insulator is a cylindrical electrical insulation device with an internal void structure, typically manufactured from porcelain, silicone rubber composites, or glass-reinforced polymers, designed to support conductors while withstanding mechanical loads and environmental stress in high-voltage systems. The composite insulator segment commands expanding share as silicone rubber housing technology displaces traditional porcelain in contamination-prone environments. Multi-core insulators retain structural importance in ultra-high voltage direct current applications where mechanical redundancy proves critical. Railway electrification represents the fastest-growing application dimension as European and Asian networks electrify trunk lines at accelerated pace.
IEC 61462 standards for composite hollow core insulators, combined with CIGRE technical brochures on long-term performance assessment, establish baseline qualification protocols that shape vendor eligibility in international tenders. China's GB standards and the State Grid Corporation's material certification requirements create additional compliance layers for suppliers targeting domestic procurement cycles. Stakeholders must monitor evolving polymer formulation durability data and emerging national testing regimes before committing capital to capacity expansion.
Market Dynamics
Silicone rubber composite technology is compressing replacement cycles for porcelain-based hollow core insulators as grid operators prioritize contamination resistance and reduced maintenance burden in high-voltage corridors.
Growth Catalysts
- Railway Electrification Mandates:European trunk line electrification programs under the EU Green Deal are accelerating orders for polymer-core insulators rated to 25 kV AC catenary systems.
- GB Standard Harmonization:China's State Grid Corporation certification requirements for composite insulators are consolidating domestic supplier qualification protocols and streamlining procurement.
- Contamination-Prone Environments:Silicone rubber housing technology with hydrophobic surface properties is displacing porcelain in coastal and industrial zones where flashover incidents concentrate.
Market Restraints
- Raw Material Concentration:High-purity silicone rubber feedstock supply concentrates among specialty chemical producers in Germany and Japan, exposing fabricators to input cost volatility.
- Ceramic Inertia:Established Asian grid operators with sunk investment in porcelain inspection infrastructure exhibit prolonged replacement cycles despite composite performance advantages.
- IEC 61462 Qualification Burden:Multi-year type-testing protocols for composite hollow core designs create regulatory friction for new market entrants lacking historical performance data.
Strategic Opportunities
- Ultra-High Voltage DC Buildout:China's ±800 kV and ±1100 kV transmission corridors require multi-core insulator configurations with mechanical redundancy specifications that command premium positioning.
- Service Unbundling:Predictive maintenance contracts using distributed fiber optic monitoring of composite insulator housing degradation represent emerging recurring revenue streams.
- North American Retrofit Cycles:Aging porcelain inventory in US transmission networks approaching end-of-design-life creates replacement demand for polymer-core alternatives meeting ANSI C29.11 standards.
Industry Challenges
- Filament Winding Talent Scarcity:Composite core manufacturing requires specialized polymer processing expertise that utilities and traditional ceramic insulator suppliers lack in-house.
- Long-Term Performance Data Gaps:CIGRE technical brochure recommendations for 30-year service life assessment exceed available field validation for silicone rubber formulations deployed since the 2000s.
- Legacy Grid Integration:Composite insulator interface hardware compatibility with existing porcelain socket-and-cap fittings demands custom engineering for each retrofit project.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hollow Core Insulator Market |
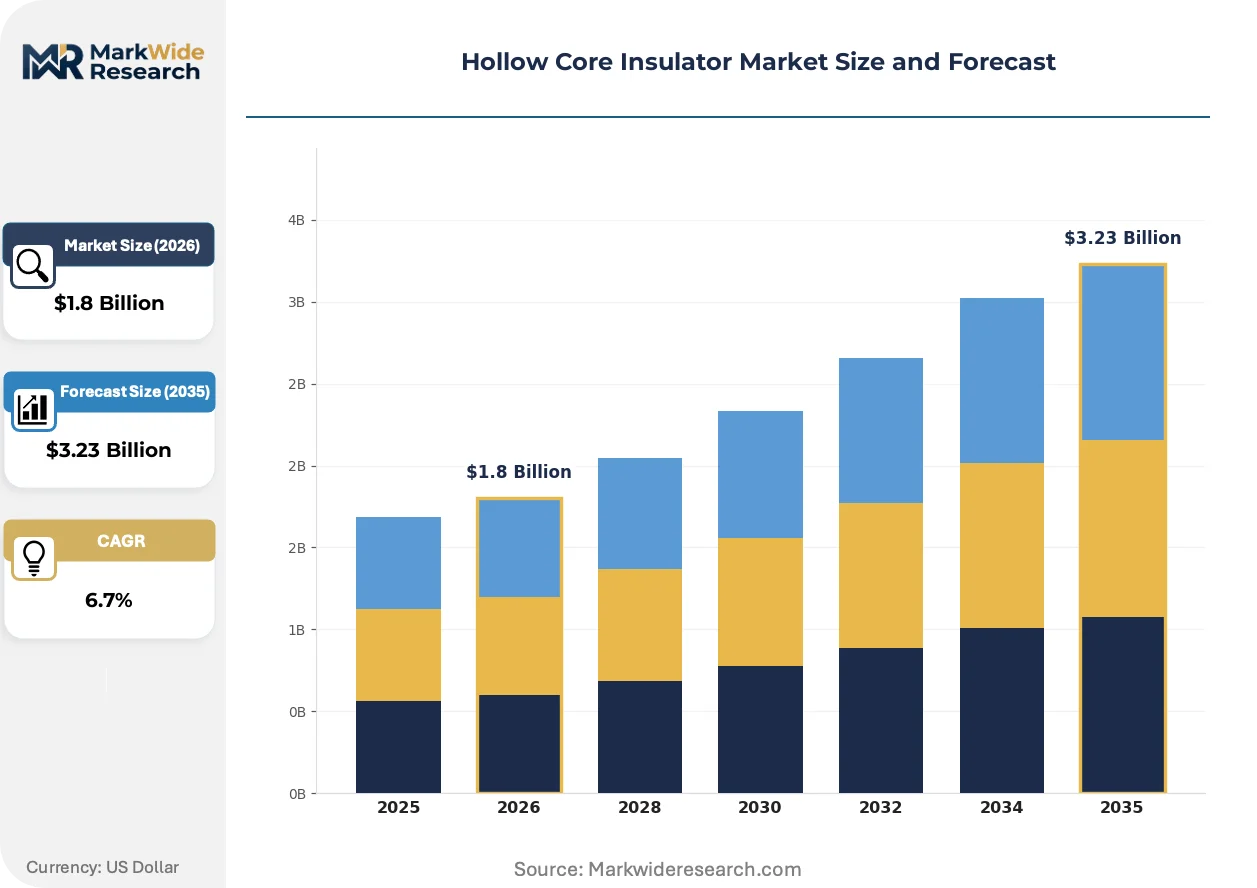
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-core Insulators, Multi-core Insulators, Composite Insulators, Glass Insulators Application: Power Transmission, Railway Electrification, Renewable Energy, Industrial Applications End User: Utilities, Railways, Manufacturing, Telecommunication Material: Ceramics, Polymer, Glass Fiber, Others |
| Companies Covered | Hitachi Energy, MacLean Power Systems, NGK Insulators, Saver SpA, TE Connectivity, Seves Group, Pfisterer, Reinhausen, LAPP Insulators, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hollow Core Insulator Market Strategic Shifts
Material science advances and procurement model evolution are restructuring competitive advantage in hollow core insulator supply, with performance validation protocols and service integration emerging as differentiation axes beyond unit cost.
Silicone rubber housing with integrated zinc oxide varistor elements functions as combined insulation and surge protection in compact substation designs. German transmission operators are piloting these hybrid configurations in 420 kV gas-insulated switchgear retrofits. The convergence of insulation and protection functions is decomposing traditional procurement categories that separated these components.
REACH regulation amendments targeting perfluorinated compound restrictions in industrial applications are extending scrutiny to fluoropolymer coatings used on some composite insulator housings. Suppliers are reformulating surface treatments to maintain hydrophobicity without restricted chemistries. European manufacturers face accelerated R&D timelines to maintain CE marking eligibility for export tenders.
Utility procurement departments are consolidating insulator purchasing into multi-year framework agreements with integrated logistics and field installation services. Equipment OEMs and EPC contractors are ceding direct supplier relationships to centralized utility supply chain functions. This concentration is most visible in China's State Grid Corporation procurement platforms that aggregate demand across provincial operating subsidiaries.
Hollow Core Insulator Market Segmentation
Segmentation in hollow core insulators reveals how material science breakthroughs and infrastructure investment patterns reshape procurement across voltage classes and end-use environments. Understanding these divisions exposes where composite technologies displace legacy ceramics and which customer segments drive premium pricing.
Product Type:
Domestic procurement concentrates on composite and multi-core designs for grid modernization, while export demand tilts toward standardized single-core units for developing market transmission buildouts.
- Composite Insulators:Silicone rubber housing bonded to glass-fiber reinforced polymer cores delivers hydrophobic surface properties and reduced weight versus porcelain. Demand clusters in China's State Grid ultra-high voltage corridors and German offshore wind grid connections where contamination resistance commands specification priority.
- Multi-core Insulators:Redundant internal structures provide mechanical fail-safety for ±800 kV and ±1100 kV DC transmission towers. Procurement localizes to Chinese domestic suppliers meeting GB standard certification for State Grid Corporation tenders.
- Single-core Insulators:Conventional cylindrical designs dominate utility maintenance cycles and emerging market transmission expansion.
- Glass Insulators:Tempered glass disc assemblies persist in legacy European networks with established inspection protocols.
Composite Insulators holds the largest share; momentum sits with Multi-core Insulators.
Application:
Cost tier differentiation separates capital-intensive greenfield transmission from maintenance-budget retrofit cycles.
- Railway Electrification:25 kV AC catenary systems across France, Germany, and Italy require polymer-core insulators with vibration resistance and compact form factors. EU Green Deal trunk line mandates accelerate replacement of porcelain in tunnel and coastal sections.
- Power Transmission:Ultra-high voltage corridors in China and aging US grid infrastructure sustain volume demand across material categories.
- Renewable Energy:Offshore wind collector platforms and solar farm substations specify composite designs for salt-fog environments.
- Industrial Applications:Heavy manufacturing facilities and petrochemical complexes drive contamination-resistant specification in coastal zones.
Power Transmission anchors volume procurement; Railway Electrification is expanding most quickly.
End User:
Customer type determines contract structure, with centralized utility procurement contrasting fragmented industrial purchasing.
- Utilities:State Grid Corporation, Électricité de France, and Italian transmission system operators aggregate demand through multi-year framework agreements with integrated logistics requirements.
- Railways:Deutsche Bahn, SNCF, and Trenitalia specify catenary insulators through rolling stock and infrastructure procurement divisions.
- Manufacturing:Industrial facility operators purchase through EPC contractors with project-specific technical specifications.
- Telecommunication:Tower operators and fiber optic network deployers represent emerging specification demand for compact insulation solutions.
Utilities command the largest procurement volumes; Railways are gaining share fastest.
Material:
Supply concentration shapes competitive access, with polymer feedstock dependencies contrasting ceramic raw material dispersion.
- Polymer:Silicone rubber formulations from German and Japanese specialty chemical producers enable hydrophobic housing performance. Glass-fiber reinforced cores fabricated through filament winding provide mechanical strength at reduced weight versus traditional materials.
- Ceramics:Porcelain and alumina-based designs retain installed base dominance in established Asian grids with sunk inspection infrastructure investment.
- Glass Fiber:E-glass and S-glass reinforcement materials concentrate among composite core manufacturers with captive filament winding capability.
- Others:Epoxy resin and hybrid material experiments occupy niche applications in gas-insulated switchgear and compact substation designs.
Ceramics retains the largest installed base; Polymer shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys hollow core insulators at ultra-high voltage scale for greenfield transmission corridors, while Germany and the United States concentrate procurement on retrofit cycles and railway electrification. This consumption-mix differential separates volume-driven utility expansion from premium-priced replacement demand.
China
State Grid Corporation drives demand through ±800 kV and ±1100 kV DC transmission buildouts across western provinces. GB standards certification requirements filter supplier eligibility for domestic tenders. Manufacturing clusters in Shandong and Jiangsu provinces host composite core fabrication facilities serving State Grid procurement platforms.
Germany
Deutsche Bahn's trunk line electrification under EU Green Deal mandates accelerates 25 kV AC catenary insulator orders. REACH regulation amendments pressure reformulation of fluoropolymer surface coatings. Industrial concentration in Bavaria and North Rhine-Westphalia anchors silicone rubber compounding and filament winding operations.
United States
Aging porcelain inventory in ERCOT and PJM interconnection territories approaches end-of-design-life replacement cycles. FERC Order 1920 grid reliability directives incentivize contamination-resistant composite alternatives. Transmission OEM procurement in Texas and the Midwest targets ANSI C29.11-compliant polymer-core designs.
Japan
Established grid operators with sunk investment in porcelain inspection infrastructure exhibit prolonged replacement cycles despite composite performance advantages. METI carbon neutrality roadmaps pressure eventual material transition. Manufacturing capabilities concentrate in Nagoya and Osaka industrial corridors with ceramic heritage.
Italy
Trenitalia and Terna coordinate railway and transmission electrification procurement under National Recovery and Resilience Facility funding. CE marking and IEC 61462 qualification protocols shape vendor eligibility. Northern industrial districts in Lombardy and Piedmont host insulator assembly operations serving Mediterranean export markets.
Hollow Core Insulator Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in hollow core insulator supply. Tier-one positions concentrate among energy infrastructure conglomerates with captive silicone rubber compounding and filament winding capabilities. Specialist fabricators compete through railway-specific certifications and regional utility relationships. Dominant competitive moves include backward integration into polymer core manufacturing and multi-year framework agreements with centralized utility procurement functions.
Among Japan-based ceramic specialists, NGK Insulators anchors the legacy infrastructure tier with established relationships to Asian grid operators. Hitachi Energy occupies the integrated systems position, leveraging energy infrastructure breadth to secure high-voltage corridor tenders. MacLean Power Systems represents the regional specialist archetype, concentrating on North American utility specifications and ANSI-compliant product configurations.
| Leading Market Players |
|---|
| Hitachi Energy |
| MacLean Power Systems |
| NGK Insulators |
| Saver SpA |
| TE Connectivity |
| Seves Group |
| Pfisterer |
| Reinhausen |
| LAPP Insulators |
| Others |
Value Chain & Pricing Dynamics
Multi-year framework agreements with integrated logistics and field installation services lock in supply access for utilities while anchoring price visibility across volatile silicone rubber feedstock markets. State Grid Corporation procurement platforms aggregate demand across provincial operating subsidiaries, compressing spot market exposure for qualified vendors.
Pricing Analysis
Long-term offtake contracts dominate utility procurement, with pricing stratifying across IEC 61462 certification tier, volume scale, and after-sales service bundling. Premium positioning commands composite designs with GB standard compliance for Chinese ultra-high voltage corridors, while standard tiers serve North American ANSI C29.11 retrofit cycles. Cost compression in the standard tier intensifies as filament winding capacity expands in Shandong province. Industrial EPC contractors exhibit highest price sensitivity; State Grid Corporation tenders show lowest sensitivity due to reliability-weighted scoring.
Supply Chain Analysis
Inbound logistics costs from German and Japanese specialty chemical producers concentrate raw material risk along Asia-Europe trade lanes. High-purity silicone rubber feedstock draws from German chemical clusters and Japanese polymer specialists, while glass-fiber reinforcement centers on Chinese filament winding operations. Single-source vulnerability in specialty silicone formulations exposes fabricators to input cost volatility. Distribution runs through centralized utility procurement platforms and EPC contractor specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hollow core insulator market sits in early-cycle expansion as railway electrification mandates and ultra-high voltage transmission buildouts accelerate composite adoption ahead of porcelain replacement curves.
For Market Incumbents: Consolidate backward integration into silicone rubber compounding to defend margin position against feedstock volatility from German and Japanese specialty chemical suppliers. Expand filament winding capacity in Shandong and Jiangsu provinces to capture State Grid Corporation tender volumes. Prioritize IEC 61462 qualification maintenance as regulatory friction against emerging entrants. For New Entrants and Emerging Players: Lead with predictive maintenance contracts using distributed fiber optic monitoring as a service wedge into utility procurement cycles. Target North American retrofit demand for ANSI C29.11-compliant polymer-core designs where established Asian suppliers lack localized service infrastructure. Penetrate through EPC contractor relationships rather than direct utility engagement. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors integrated manufacturers with captive polymer processing capabilities over pure-play assemblers. Five-to-ten year viability hinges on GB standard certification access and State Grid Corporation supplier status. Watch State Grid procurement platform qualification list expansions as the inflection signal for competitive entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Rubber Compounding | Captive supply of high-purity feedstock insulates margins from German and Japanese chemical producer pricing volatility. |
| GB Standard Certification Investment | State Grid Corporation tender eligibility requires domestic certification protocols that filter foreign supplier access. |
| Predictive Maintenance Service Launch | Fiber optic monitoring contracts create recurring revenue streams beyond unit sales in utility procurement cycles. |
| Filament Winding Capacity Expansion | Shandong and Jiangsu manufacturing clusters serve State Grid ultra-high voltage corridor demand with localized production. |
| Railway Electrification Product Line Development | Deutsche Bahn and SNCF 25 kV AC specifications open premium positioning in EU Green Deal trunk line mandates. |
Study Parameters
Desk research of IEC technical committee publications, CIGRE working group reports, and State Grid Corporation procurement disclosure records preceded structured interviews with utility planning officers, EPC contractor procurement leads, composite insulator plant managers, and railway infrastructure engineers. Primary fieldwork across Shandong manufacturing clusters and German silicone rubber compounding facilities combined with secondary validation from customs trade data and utility capital expenditure filings. Bottom-up unit demand estimates triangulated against top-down transmission investment forecasts.
Variance decomposition across voltage class, material category, and end-use application shaped the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product type, application environment, end-user procurement structure, and regional regulatory cluster. CAGRs derived from regression analysis of historical procurement volumes against grid modernization spending and electrification policy intensity. Forecast inputs incorporated railway electrification mileage targets and ultra-high voltage transmission corridor commissioning schedules.
The analysis sits within stated boundaries; outcomes outside sustained State Grid Corporation capital expenditure levels and EU Green Deal funding continuity would require recalibration. Forecasts reflect assumptions on silicone rubber formulation durability validation timelines and GB standard harmonization trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
North America Surge Arresters Market
Electrical Power Equipment
Global Magnetic Circuit Breaker Market
Electrical Power Equipment
Europe Electric Space Heaters Market
Electrical Power Equipment
South America Medium Voltage Switchgear Market
Electrical Power Equipment
Electric Vehicle Charging Cables Market
Electrical Power Equipment
Global Lightning Arrester Market
Electrical Power Equipment
Digital Fault Recorder (DFR) Market
Electrical Power Equipment
Substation Testing Equipment Market
Electrical Power Equipment
Solid Vacuum Reclosers Market
Electrical Power Equipment
Electric Substation Market
Electrical Power Equipment
India Instrument Transformer Market
Electrical Power Equipment
Global Switchgear Monitoring Market
Electrical Power Equipment
Low Voltage Protection Control Market
Electrical Power Equipment
Battery Charger Market
Electrical Power Equipment
Canada Electric Space Heater Market
Electrical Power Equipment
Load Bank Market