
 Portable Space Heater Market | 2026-2036
Portable Space Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Space Heater Market Insights
Chinese contract manufacturers is recalibrating component sourcing for ceramic heating elements after Southeast Asian labor costs shifted assembly economics. Vornado leverages its domestic engineering base to sustain premium airflow design leadership. Dreo competes aggressively through direct-to-consumer channel control and rapid IoT feature integration.
Portable space heaters are self-contained thermal units typically rated between 750 and 1,500 watts, employing resistive coils, infrared quartz tubes, or diathermic oil reservoirs to convert electrical or fuel energy into radiant or convective warmth for enclosed spaces. Electric fan heaters dominate residential volume due to low first-cost and instant heat delivery, while oil-filled convection models retain margin strength in European commercial settings where silent operation commands premium positioning. Smart thermostatic control interfaces represent the fastest-expanding segment as Wi-Fi-enabled scheduling and voice integration migrate from luxury to standard expectation.
The US Consumer Product Safety Commission enforces tip-over shutoff and overheat protection mandates that elevate baseline safety engineering costs for all entrants. EU Ecodesign regulations under the F-Gas framework restrict refrigerant-adjacent heating technologies and push manufacturers toward heat-pump-compatible electric architectures. Stakeholders must monitor whether emerging battery-buffered cordless designs trigger new UL certification categories before committing capital to portable powertrain development.
Market Dynamics
The US EPA's tightened emissions standards for gas-powered appliances are redirecting procurement toward electric alternatives, while residential retrofitting in aging urban housing accelerates replacement cycles across North America and Europe.
Growth Catalysts
- Building efficiency mandates:Germany's multifamily housing sector drives seasonal heater upgrades as efficiency regulations tighten thermal performance requirements for rental units.
- Smart thermostatic control interfaces:Wi-Fi-enabled scheduling and voice integration migrate from luxury positioning to standard consumer expectation, expanding addressable market for connected devices.
- Ceramic heating element sourcing:Chinese contract manufacturers recalibrate component procurement after Southeast Asian labor cost shifts alter assembly economics, improving margin structures for mid-tier producers.
Market Restraints
- Baseline safety engineering costs:US Consumer Product Safety Commission tip-over shutoff and overheat protection mandates elevate entry barriers for new market participants.
- Refrigerant-adjacent technology restrictions:EU F-Gas framework under Ecodesign regulations limits certain heating architectures and pushes manufacturers toward heat-pump-compatible electric designs.
- Silent operation premium positioning:Oil-filled convection models retain margin strength in European commercial settings where noise constraints favor established product categories over disruptive entrants.
Strategic Opportunities
- Battery-buffered cordless designs:Emerging portable powertrain architectures may trigger new UL certification categories before competitors commit capital, creating first-mover advantage.
- Direct-to-consumer channel control:Aggressive IoT feature integration combined with bypassing traditional retail markups enables margin capture and customer data ownership.
- Domestic engineering base leverage:Sustained premium airflow design leadership through captive R&D capabilities differentiates against contract-manufactured alternatives.
Industry Challenges
- Certification timeline compression:New product categories face extended UL evaluation periods as safety standards evolve faster than testing infrastructure capacity.
- Heat-pump-compatible architecture migration:Technical integration complexity increases as electric heating systems must interface with emerging residential HVAC electrification retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Space Heater Market |
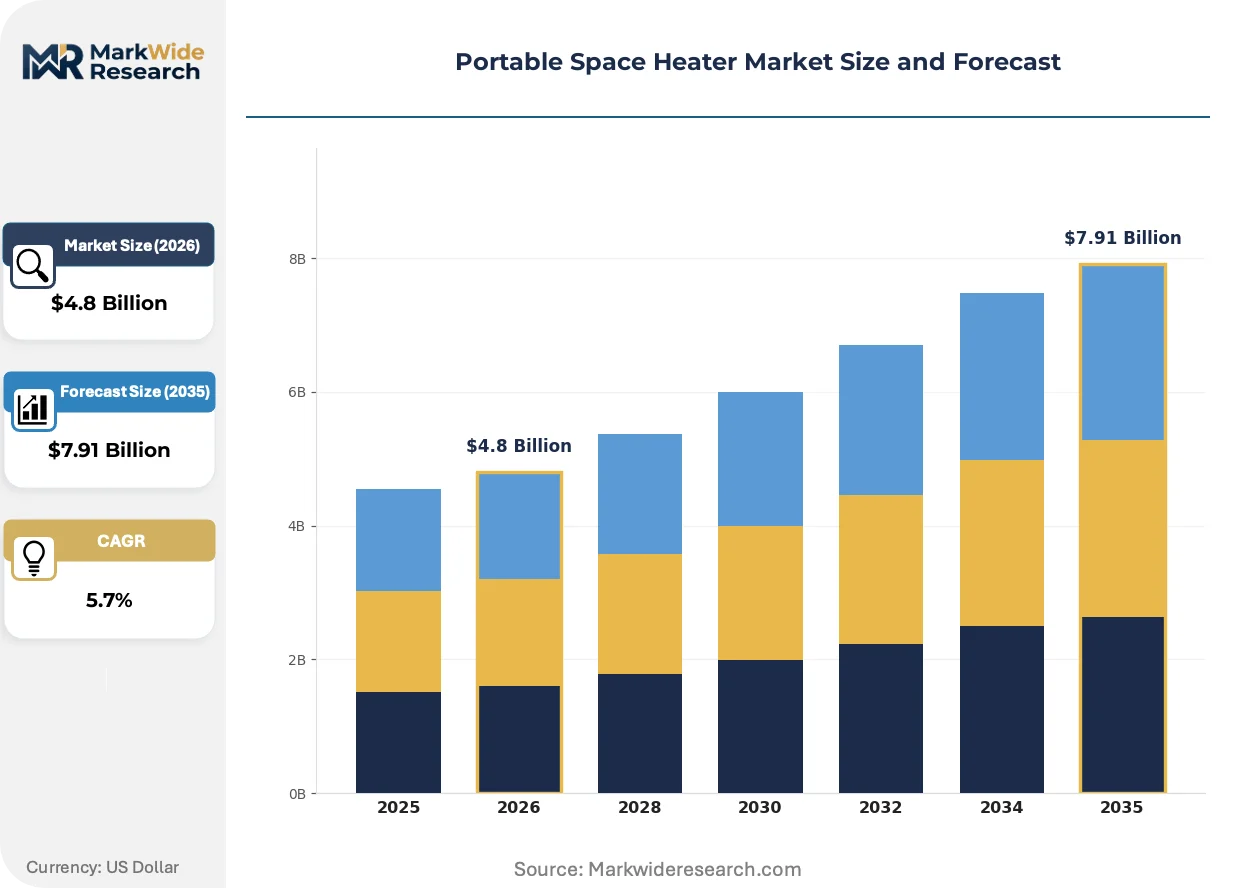
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convection Heaters, Radiant Heaters, Oil-Filled Heaters, Fan Heaters Energy Source: Electric, Gas, Propane, Solar Control Type: Manual, Thermostatic, Smart, Remote-Controlled Application: Residential, Commercial, Industrial, Outdoor |
| Companies Covered | Dyson, Vornado, Dreo, De'Longhi, Comfort Zone, Lasko, Shark, Andily, Honeywell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Space Heater Market Trends and Innovations
Active reshaping of the portable space heater market centers on three vectors: connectivity integration, regulatory-driven electrification, and channel restructuring that favors direct manufacturer-consumer relationships over traditional retail intermediation.
Mesh-networked thermostat controllers are decentralizing household thermal management by enabling room-level climate zoning without central HVAC dependency. Multifamily housing operators in Germany and the Netherlands deploy these systems to comply with individual unit metering mandates while reducing building-wide energy consumption. The technology is decentralizing traditional landlord-tenant utility allocation models and creating recurring software revenue streams for hardware manufacturers.
The EU F-Gas Regulation under the broader Ecodesign framework restricts refrigerant-adjacent heating technologies and mandates heat-pump-compatible electric architectures for new product introductions. Appliance manufacturers face accelerated R&D cycles to redesign thermal cores and control systems before 2027 compliance deadlines. Residential retrofit contractors in France and Belgium report specification shifts toward electric-only portfolios as gas connection permits face municipal moratoria.
Apartment dwellers increasingly purchase heating equipment through manufacturer-direct websites rather than big-box retailers, prioritizing subscription warranty bundles and installation service add-ons over in-store comparison shopping. This channel migration concentrates in urban coastal markets of the United States where same-day delivery logistics networks operate at scale. Traditional distributors respond by unbundling after-sales service contracts to compete on headline pricing while protecting attachment revenue.
Portable Space Heater Market Segmentation
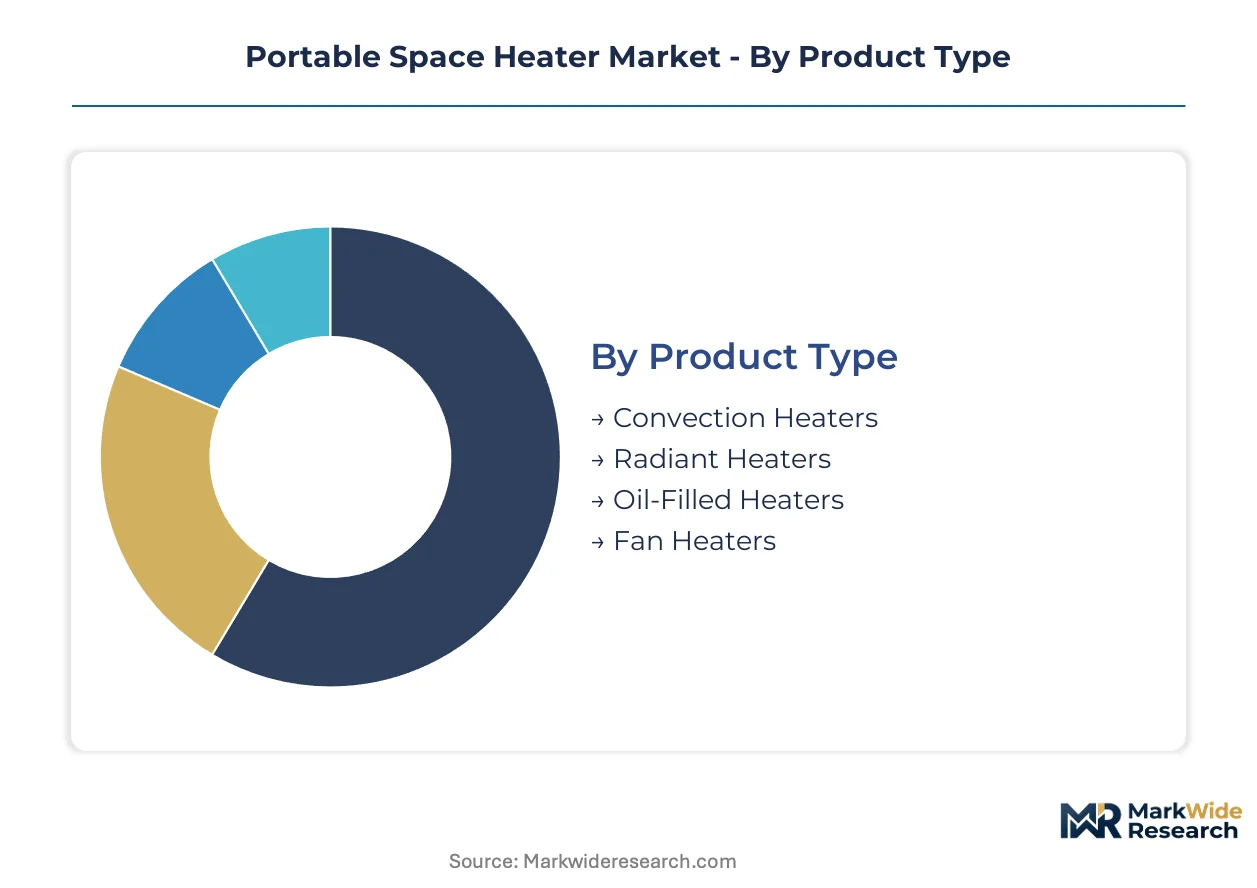
Portable space heater segmentation reveals how thermal engineering specifications, energy conversion architectures, and control interfaces align with distinct use environments. Manufacturers configure component portfolios around these axes to match regulatory constraints and end-user operational requirements.
Product Type:
Heating element architecture determines thermal output characteristics, energy efficiency profiles, and acoustic signatures across deployment contexts.
- Fan Heaters:Electric resistive coils paired with forced-air blowers deliver instantaneous radiant warmth. Demand concentrates in US residential retrofits where aging urban housing stock requires supplemental heating without infrastructure modification. EPA emissions standards for gas appliances accelerate procurement shifts toward electric fan-based units.
- Oil-Filled Heaters:Diathermic oil reservoirs circulate through convection fins for silent, steady heat release. Germany's multifamily housing sector drives procurement where building efficiency mandates require thermal performance upgrades without noise disruption. Silent operation commands premium positioning in European commercial settings.
- Convection Heaters:Natural airflow across heated surfaces distributes warmth through enclosed spaces without mechanical assistance.
- Radiant Heaters:Infrared quartz tubes or ceramic panels emit directional thermal radiation for spot heating applications.
Fan heaters lead on scale; smart-integrated oil-filled units lead on momentum.
Energy Source:
Powertrain selection reflects infrastructure availability, operating cost structures, and emissions compliance requirements across regulatory jurisdictions.
- Electric:Grid-connected resistive or infrared systems dominate residential volume through low first-cost and instant heat delivery. Chinese contract manufacturers recalibrate ceramic element sourcing after Southeast Asian labor cost shifts alter assembly economics. US EPA tightened emissions standards redirect procurement from gas alternatives.
- Gas:Natural gas combustion systems retain installed base in regions with pipeline infrastructure despite regulatory pressure.
- Propane:Liquefied petroleum systems serve off-grid and outdoor applications where electrical infrastructure is unavailable.
- Solar:Photovoltaic-assisted or thermal collection systems address sustainability mandates in premium residential segments.
Electric leads on scale; solar-integrated designs lead on momentum.
Control Type:
Interface sophistication determines user experience differentiation and recurring revenue potential through connected service ecosystems.
- Smart:Wi-Fi-enabled scheduling, voice integration, and mesh-networked thermostat controllers decentralize household thermal management. Multifamily housing operators in Germany and the Netherlands deploy these for individual unit metering compliance. Software subscription bundles create recurring revenue streams beyond hardware margins.
- Thermostatic:Temperature-feedback regulation maintains setpoints without continuous user intervention.
- Remote-Controlled:Infrared or RF handheld interfaces enable adjustment without physical access to the unit.
- Manual:Dial or switch interfaces provide basic operation at lowest cost tier.
Manual controls lead on scale; smart interfaces lead on momentum.
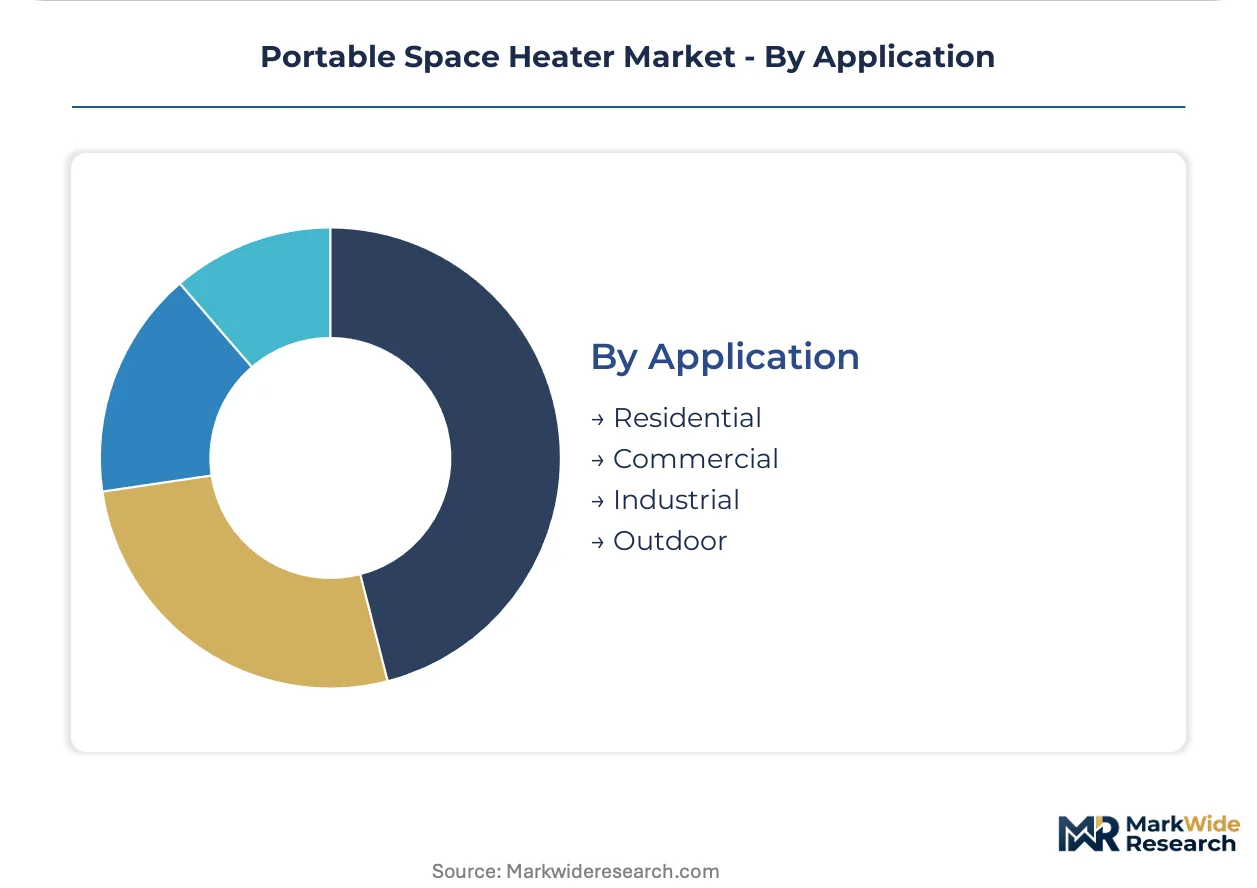
Application:
Use environment dictates safety certification requirements, durability specifications, and distribution channel strategies.
- Residential:Supplemental heating for single-family homes and apartments drives volume through retail and direct-to-consumer channels. US Consumer Product Safety Commission tip-over shutoff and overheat protection mandates elevate baseline engineering costs. Apartment dwellers increasingly purchase through manufacturer-direct websites prioritizing warranty bundles over in-store comparison.
- Commercial:Office, retail, and hospitality deployments require extended duty cycles and professional installation services.
- Industrial:Warehouse, workshop, and construction site applications demand ruggedized enclosures and higher thermal output ratings.
- Outdoor:Patio, event, and temporary heating applications utilize weather-resistant housings and propane or infrared configurations.
Residential leads on scale; commercial smart-zoning deployments lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating final assembly to jurisdictions where safety certification costs and labor arbitrage create margin advantages, with Chinese contract producers recalibrating ceramic element sourcing after Southeast Asian wage shifts altered assembly economics.
United States
Residential retrofitting in aging urban housing accelerates replacement cycles across the Northeast and Midwest. The EPA's tightened emissions standards for gas-powered appliances redirect procurement toward electric alternatives. Chicago and Detroit clusters concentrate distribution infrastructure for fan heater models targeting rental unit upgrades.
Germany
Multifamily housing operators drive seasonal heater upgrades as building efficiency mandates tighten thermal performance requirements for rental units. The EU F-Gas Regulation under Ecodesign restricts refrigerant-adjacent heating technologies. Berlin and Munich anchor specification shifts toward heat-pump-compatible electric architectures before 2027 compliance deadlines.
China
Contract manufacturers recalibrate component procurement for ceramic heating elements after Vietnamese and Indonesian labor cost shifts. The country's national standards regulator enforces GB safety certifications for export-bound production. Shenzhen and Dongguan industrial zones concentrate assembly capacity for mid-tier producers serving North American and European private-label demand.
Netherlands
Multifamily housing operators deploy mesh-networked thermostat controllers to comply with individual unit metering mandates while reducing building-wide energy consumption. The EU Green Deal implementation tightens Ecodesign requirements for connected thermal devices. Amsterdam and Rotterdam clusters concentrate software development for recurring revenue subscription bundles.
France
Residential retrofit contractors report specification shifts toward electric-only portfolios as municipal authorities impose gas connection moratoria. The country's national energy regulator enforces building efficiency standards that accelerate heat pump adoption. Lyon and Lille industrial zones concentrate R&D for thermal core redesigns ahead of 2027 architecture deadlines.
Portable Space Heater Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer channel control and rapid IoT feature integration. The vendor base stratifies across three tiers: premium engineering-led specialists, mid-scale contract-manufactured value players, and digitally native disrupters. Strategic archetypes include domestic engineering-base defenders, vertically integrated Chinese fabricators, and direct-to-consumer platform operators. Competitive moves center on certification-first product development and geographic diversification of assembly footprints.
Among premium-tier engineering specialists, Vornado and Dyson exemplify sustained airflow design leadership through captive R&D capabilities. Dreo occupies a position within the digitally native disrupter archetype, competing through aggressive IoT feature integration and bypassing traditional retail markups. De'Longhi anchors the European commercial segment where silent operation commands premium positioning in oil-filled convection models.
| Leading Market Players |
|---|
| Dyson |
| Vornado |
| Dreo |
| De'Longhi |
| Comfort Zone |
| Lasko |
| Shark |
| Andily |
| Honeywell |
| Others |
Pricing and Supply Chain Analysis
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access by mandating heat-pump-compatible electric architectures before 2027 compliance deadlines. Manufacturers lacking certified thermal core redesigns face exclusion from European procurement while certified suppliers capture margin premiums in Germany and the Netherlands.
Pricing Analysis
Distributor margins and retailer markups compress as direct-to-consumer channel control displaces traditional intermediation. Pricing stratifies across premium engineering-led specialists, mid-scale contract-manufactured value players, and digitally native disrupters based on certification tier and IoT integration depth. Cost compression in the mid-tier intensifies because Chinese contract manufacturers recalibrated ceramic element sourcing after Southeast Asian labor shifts. Residential retrofit contractors in aging US urban housing exhibit highest price sensitivity; commercial multifamily operators in Germany show lowest sensitivity due to efficiency mandate compliance requirements.
Supply Chain Analysis
Domestic-content mandates in the US Inflation Reduction Act and EU Ecodesign framework are reshaping sourcing toward regional assembly footprints. Component supply concentrates in China for ceramic heating elements, Vietnam for electronic control modules, and Mexico for final assembly serving North American demand. Manufacturing rests on aluminum die-cast housings, copper resistive coils, and silicon-controlled rectifier circuits. Single-source vulnerability runs through Shenzhen and Dongguan industrial zones for mid-tier ceramic element production. Distribution runs through manufacturer-direct websites, big-box retail, and HVAC contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between US EPA emissions standards redirecting procurement toward electric alternatives and EU Ecodesign mandates accelerating heat-pump-compatible architecture shifts.
For Market Incumbents: To counter digitally native disrupters like Dreo capturing direct-to-consumer margin through rapid IoT feature integration, incumbents must consolidate channel control through warranty subscription bundling and deepen captive R&D capabilities in airflow design engineering. Certification investment in UL safety categories for emerging battery-buffered cordless designs provides defensive moat construction before new entrants commit capital. For New Entrants and Emerging Players: The EU F-Gas Regulation in Germany and the Netherlands opens a window for mesh-networked thermostat controller deployment targeting multifamily housing operators facing individual unit metering mandates. White-space concentrates in commercial smart-zoning applications and solar-integrated electric architectures for premium residential segments. Go-to-market leverage through installation service add-ons rather than headline hardware pricing captures recurring software revenue streams. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale contract-manufactured value players because Chinese ceramic element sourcing recalibration has improved margin structures and created consolidation-ready targets with established private-label relationships. Long-term viability centers on acquisition of manufacturers with GB safety certifications for export-bound production and heat-pump-compatible thermal core capabilities. The signal to watch is municipal gas connection moratoria accelerating electric-only portfolio specification shifts among residential retrofit contractors.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Launch | Bypasses retail markups and captures customer data ownership for IoT-enabled scheduling bundles. |
| Heat-Pump-Compatible Architecture Migration | Ensures EU F-Gas Regulation compliance before 2027 deadlines in Germany and Netherlands markets. |
| Ceramic Element Sourcing Recalibration | Improves margin structures after Southeast Asian labor cost shifts altered assembly economics. |
| Smart Thermostat Controller Integration | Enables mesh-networked room-level climate zoning for multifamily housing efficiency mandates. |
| Battery-Buffered Cordless Design Certification | Triggers first-mover advantage in emerging UL safety categories before competitor capital commitment. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with product engineering directors, HVAC contractor procurement managers, multifamily housing operators, and retail category buyers with secondary validation. Secondary sources include US Consumer Product Safety Commission enforcement records, EU Ecodesign regulatory filings, customs trade data for ceramic heating element flows, and SEC 10-K disclosures from listed appliance manufacturers. Bottom-up unit shipment modeling triangulates against top-down market value reconstruction.
Rate-of-change decomposition separates volume growth from mix-shift effects across the projection horizon. Segmentation dimensions modeled include heating element architecture, control interface sophistication, energy conversion source, and application environment. CAGRs derive from regression analysis against housing stock age, regulatory compliance deadlines, and replacement cycle acceleration. Industry-specific inputs incorporate EPA emissions standard enforcement timelines and EU F-Gas Regulation implementation phases.
Revisions become necessary when regulatory enforcement delays, supply chain disruptions in Chinese industrial zones, or breakthrough battery powertrain architectures materialize outside modeled assumptions. Forecasts reflect documented assumptions about housing retrofit intensity and electrification policy continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Digital Fault Recorder (DFR) Market
Electrical Power Equipment
Hollow Core Insulator Market
Electrical Power Equipment
Asia-Pacific Air-Insulated Switchgear Market
Electrical Power Equipment
Electric Substation Market
Electrical Power Equipment
South America Air Insulated Switchgear Market
Electrical Power Equipment
US Electric Towers and Poles Market
Electrical Power Equipment
Skid Mounted Unit Substations Market
Electrical Power Equipment
Residential Air Insulated Power Distribution Component Market
Electrical Power Equipment
Global Surge Arrester Market
Electrical Power Equipment
India Instrument Transformer Market
Electrical Power Equipment
Fault Circuit Indicator Market
Electrical Power Equipment
Electric Radiators Market
Electrical Power Equipment
AC Residential Switchgear Market
Electrical Power Equipment
Immersion Heater Market
Electrical Power Equipment
Low Voltage Protection Control Market
Electrical Power Equipment
Containerized Substation Market