
 Immersion Heater Market | 2026-2036
Immersion Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Immersion Heater Market Foresight
Stainless steel sheathing is shifting toward Incoloy and titanium alloys in corrosive-process immersion heaters, reducing replacement frequency and extending service intervals in chemical and marine applications. Chromalox leverages vertical integration across heating element manufacturing to control alloy sourcing costs and delivery timelines. NIBE Group anchors its position through captive production of heat pump immersion heaters, bundling them with residential water heating systems. CIRCOR International competes in industrial process heating through specialized flanged and circulation heater designs for oil and gas downstream operations.
An immersion heater is an electric or fuel-fired device in which a heating element or combustion tube is directly submerged into a liquid to transfer thermal energy, typically achieving watt densities from 10 to 150 W/in² depending on fluid properties and sheath material. Its primary purpose is to raise or maintain liquid temperature in tanks, vessels, and flow loops across industrial process, commercial hot water, and residential heating applications. Electric immersion heaters occupy the largest share of product type demand as grid decarbonization and building electrification policies displace gas-fired alternatives in OECD markets. Resistive technology dominates current installations, though induction immersion heaters are gaining traction in high-purity pharmaceutical and semiconductor fluid heating where contamination risks exclude direct element contact.
The U.S. Department of Energy appliance efficiency standards, EU Ecodesign Directive requirements, and IEC 60335-2-73 safety specifications for immersion heaters collectively shape product design, testing protocols, and market access conditions across North America and Europe. Compliance with these frameworks necessitates redundant thermal cutouts, ground fault protection, and minimum efficiency thresholds that add engineering cost but also create barriers against low-cost imports. Stakeholders must monitor evolving carbon border adjustments and building performance standards that will increasingly tie immersion heater specification to whole-system energy ratings rather than standalone unit efficiency.
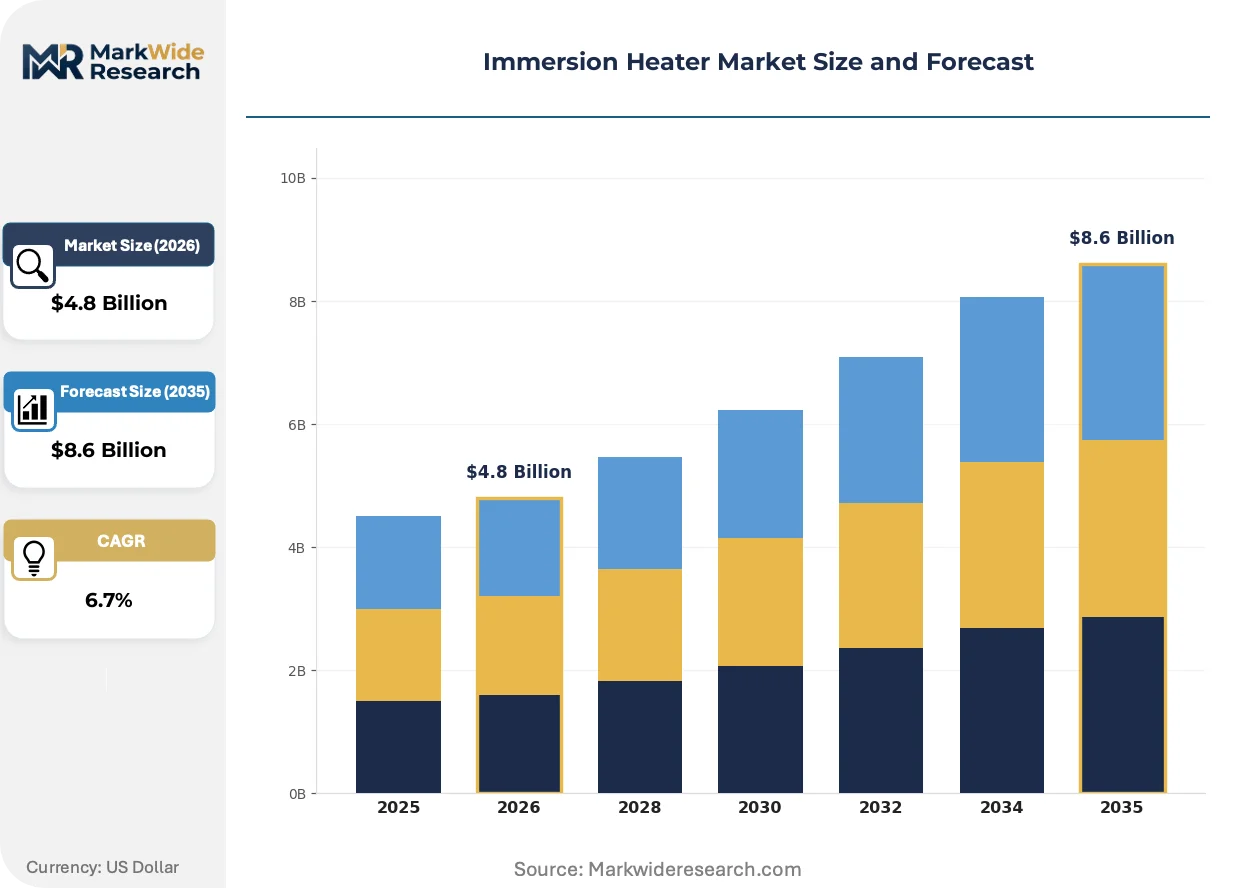
Market Dynamics
Electrification mandates across industrial process heating are dismantling legacy gas-fired infrastructure, forcing capital allocation toward resistive and induction alternatives that align with grid decarbonization timelines.
Growth Catalysts
- EU Ecodesign Directive efficiency thresholds:Minimum performance standards for process heating equipment are compelling facility operators to replace aging combustion-based systems with electric immersion heaters in chemical and food manufacturing plants.
- Induction heating technology:Non-contact thermal transfer eliminates contamination risks in pharmaceutical fluid processing and semiconductor wafer fabrication, opening high-purity applications previously closed to direct element designs.
- China's industrial electrification push:Provincial carbon intensity targets under the dual carbon goals framework are accelerating electric heater deployment in steel, chemical, and textile processing clusters across Jiangsu and Zhejiang provinces.
Market Restraints
- Nickel alloy supply concentration:Incoloy and titanium sheathing materials face sourcing bottlenecks from limited specialty metal producers, exposing heater manufacturers to price volatility and extended lead times.
- Legacy infrastructure lock-in:Existing gas-fired steam systems in mature industrial bases carry sunk capital costs and integrated control architectures that resist piecemeal electric retrofitting.
- Grid capacity constraints:Electrification of thermal processes in Germany and California confronts distribution network limitations that delay project approvals and increase connection costs.
Strategic Opportunities
- Marine and offshore corrosion applications:Titanium-sheathed immersion heaters for seawater heating and ballast water treatment remain underpenetrated in shipbuilding and port infrastructure across South Korea and Japan.
- U.S. Inflation Reduction Act clean manufacturing credits:Production tax incentives for energy-efficient industrial equipment create favorable project economics for electric heater replacements in domestic chemical processing.
- Heat pump-immersion heater hybrid systems:Converging technologies in residential water heating enable bundled offerings that capture both space conditioning and domestic hot water loads in single installations.
Industry Challenges
- IEC 60335-2-73 certification complexity:Redundant thermal cutout and ground fault protection requirements extend product development timelines and testing costs for new heater designs entering European markets.
- Integration with legacy SCADA architectures:Electric immersion heater retrofits in established process plants require protocol bridging and control system reconfiguration that inflates installation budgets and commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immersion Heater Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Immersion Heaters, Gas Immersion Heaters, Solar Immersion Heaters, Heat Pump Immersion Heaters End User: Residential, Commercial, Industrial, Hospitality Technology: Thermal, Resistive, Induction, Hybrid Installation Type: Built-in, Portable, Over-the-Range, Under-sink |
| Companies Covered | NIBE Group, CIRCOR International, Chromalox, Headway Electric Heat Components, Minco Products, Hotset GmbH, Phillips & Temro Industries, Thermal Corporation, Industrial Heater Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immersion Heater Market Shifts & Advancements
Digital thermal management and advanced sheath metallurgy are compressing maintenance intervals while expanding the operational envelope of immersion heaters into previously excluded process environments.
Induction immersion heating is rewriting competitive positioning in high-purity fluid processing. This technology transfers thermal energy through electromagnetic coupling rather than direct resistive element contact, eliminating sheath degradation and particulate shedding. Pharmaceutical manufacturers and semiconductor fabs are adopting induction designs for ultrapure water and process chemical heating. The technology is compressing the addressable market for conventional resistive heaters in contamination-sensitive applications.
REACH substance restrictions on hexavalent chromium coatings are forcing sheath manufacturers to migrate toward plasma-sprayed ceramic and PVD-based alternatives for corrosion protection. Industrial heater OEMs face reformulation costs and supply chain recertification to maintain European market access. Chemical processing operators in Germany and the Netherlands are prioritizing suppliers with verified REACH-compliant coating systems in procurement specifications.
Service unbundling is fragmenting traditional equipment-plus-installation bundles in commercial hot water applications. Facility managers are separating heater procurement from commissioning and maintenance contracts, engaging specialized contractors for each phase. This pattern is most pronounced in U.S. multi-site hospitality and healthcare operators managing distributed boiler and water heater fleets across regional property portfolios.
Immersion Heater Market Segmentation
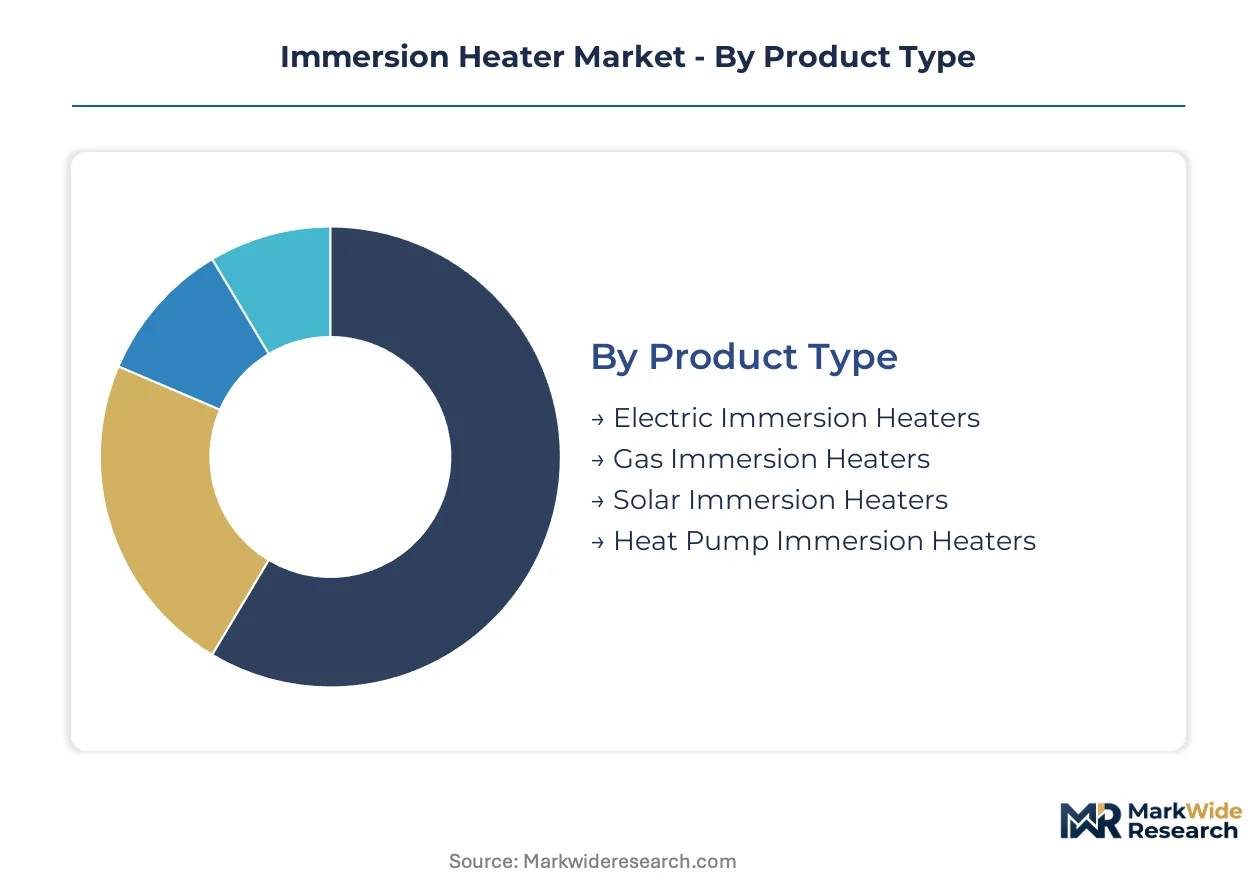
Immersion heater procurement patterns diverge sharply across product architectures, end-use environments, and installation constraints. Technology selection and mounting configuration determine alloy specifications, safety certifications, and maintenance protocols that shape total cost of ownership.
Product Type:
Volume deployment concentrates in standardized electric units, while premium pricing attaches to integrated heat pump and solar-thermal hybrids.
- Electric Immersion Heaters:Resistive element designs with watt densities from 10 to 150 W/in² dominate current installations. Grid decarbonization mandates in Germany and California are accelerating displacement of gas-fired alternatives in residential and light commercial water heating.
- Gas Immersion Heaters:Combustion-tube configurations persist in legacy industrial steam systems and off-grid locations. Sunk capital in existing boiler infrastructure and integrated control architectures resist piecemeal retrofitting in mature manufacturing bases.
- Solar Immersion Heaters:Photovoltaic-coupled resistive elements enable direct DC heating without inverter losses.
- Heat Pump Immersion Heaters:Refrigerant-cycle thermal extraction delivers coefficient-of-performance advantages over direct resistance.
Mature deployment sits with Electric Immersion Heaters. Newer deployment is concentrated in Heat Pump Immersion Heaters.
End User:
Industrial specifications prioritize corrosion-resistant sheathing and redundant thermal protection, while residential demand centers on compact form factors and smart grid compatibility.
- Residential:Tank-mounted and inline units serve domestic hot water and space heating applications. Building electrification timelines in the United States and EU member states are accelerating replacement of gas-fired storage heaters with electric alternatives.
- Industrial:Flanged, circulation, and screw-plug configurations handle process fluids in chemical manufacturing, oil and gas downstream, and food processing. REACH substance restrictions on hexavalent chromium coatings are forcing sheath manufacturers toward plasma-sprayed ceramic alternatives.
- Commercial:Multi-unit installations in healthcare, education, and office facilities emphasize modularity and service access.
- Hospitality:Distributed hot water systems for hotels and restaurants demand rapid recovery rates and scale-resistant element designs.
Volume leadership belongs to Industrial end users. Steepest expansion trajectory is emerging in Residential electrification retrofits.
Technology:
Resistive architectures capture the mass-market cost tier, while induction and hybrid systems command premium positioning in contamination-sensitive process environments.
- Resistive:Direct ohmic heating through nickel-chromium or iron-chromium-aluminum alloy elements remains the dominant installed base. Chromalox and similar OEMs leverage captive alloy sourcing to control material costs and delivery timelines.
- Induction:Electromagnetic coupling eliminates direct element contact, eliminating sheath degradation and particulate shedding in pharmaceutical and semiconductor fluid processing. IEC 60335-2-73 certification complexity extends development timelines for new induction designs entering European markets.
- Thermal:Convection and radiant heat transfer configurations serve specialized low-watt-density applications.
- Hybrid:Combined resistive-induction or heat pump-resistive systems optimize efficiency across variable load conditions.
Installed base concentration favors Resistive technology. Gaining share fastest is Induction in high-purity pharmaceutical and wafer fabrication applications.
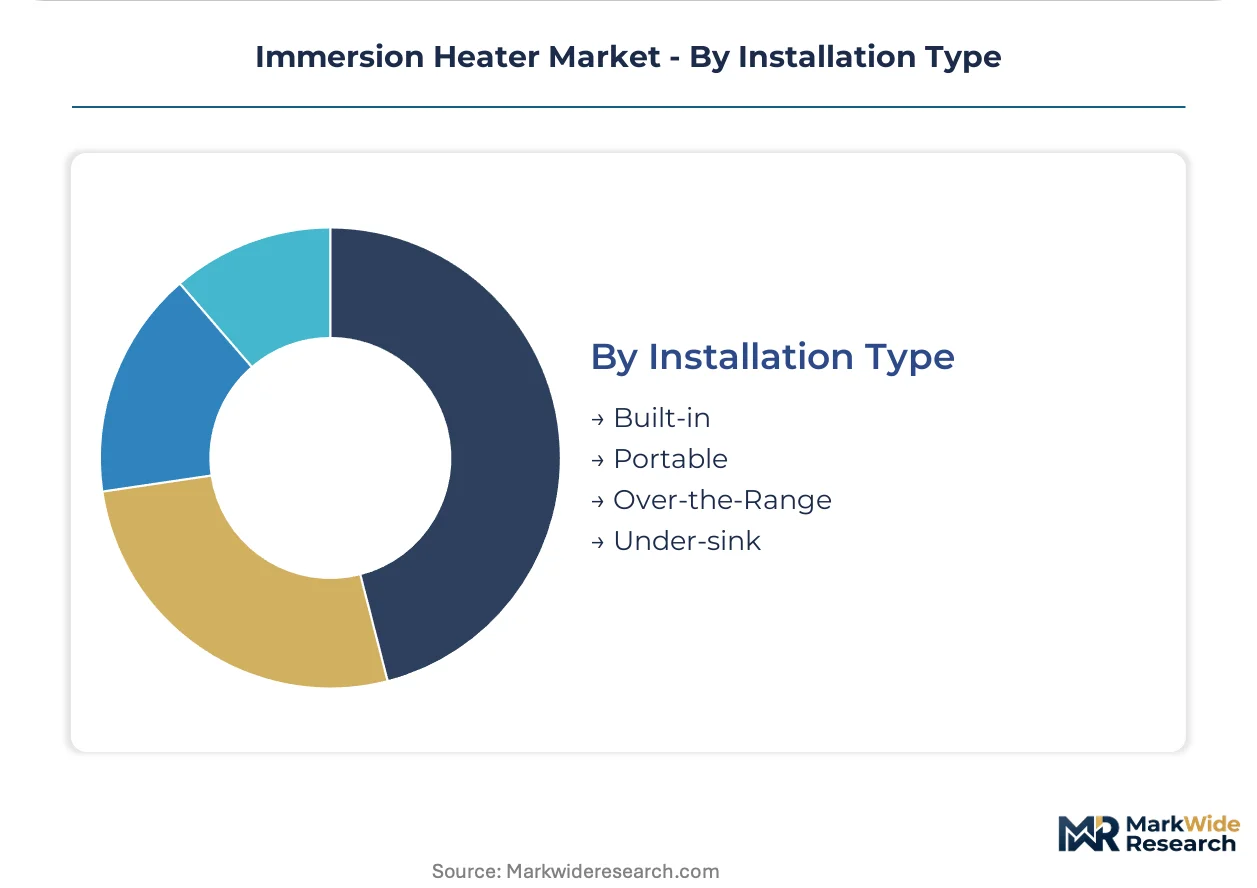
Installation Type:
Built-in configurations anchor replacement demand in existing infrastructure, while portable and point-of-use formats address emerging flexibility requirements.
- Built-in:Permanent tank or vessel integration dominates industrial process heating and residential storage water heaters. Legacy SCADA integration requirements inflate commissioning budgets for electric retrofits in established chemical plants.
- Portable:Plug-in units serve temporary heating, laboratory applications, and construction site requirements. Service unbundling in U.S. multi-site hospitality operators is separating heater procurement from installation and maintenance contracts.
- Over-the-Range:Compact vertical mounting for commercial kitchen and laboratory sink applications.
- Under-sink:Point-of-use instant heating eliminates distribution losses in remote fixtures.
Replacement cycles concentrate in Built-in installations. Emerging specification growth is concentrated in Portable units for distributed and temporary applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, China, and the United States as facility operators replace legacy combustion systems with electric alternatives under tightening efficiency mandates and building decarbonization timelines.
Germany
Chemical processing clusters in North Rhine-Westphalia and Bavaria are accelerating electric heater deployment to meet provincial carbon intensity targets. The EU Ecodesign Directive enforces minimum performance standards that disqualify aging gas-fired units from new installations. BASF and Bayer facilities in Ludwigshafen and Leverkusen are retrofitting process heating with resistive and induction immersion systems.
China
Provincial dual carbon goals under the national framework are driving electrification in Jiangsu and Zhejiang textile and chemical processing hubs. MIIT efficiency standards for industrial thermal equipment mandate phase-out schedules for coal-fired steam systems. State Grid Corporation is expanding distribution capacity in the Yangtze River Delta to accommodate process heating electrification loads.
United States
Petrochemical downstream operations in Texas and Louisiana are evaluating electric alternatives as EPA emissions regulations tighten on combustion-based process heating. The Inflation Reduction Act provides production tax credits for energy-efficient industrial equipment retrofits. California's building performance standards are accelerating residential and commercial water heater electrification in Los Angeles and San Diego metro areas.
Japan
Semiconductor fabrication facilities in Kyushu and Hiroshima prefectures are specifying induction immersion heaters for ultrapure water systems to eliminate contamination risks. METI technology roadmaps prioritize non-contact thermal processing for advanced manufacturing. Shipbuilders in Nagasaki and Kobe are adopting titanium-sheathed units for seawater heating and ballast water treatment applications.
South Korea
Display panel and memory chip manufacturers in Gyeonggi Province are integrating induction heating for high-purity chemical processing. The national K-ESG framework ties corporate carbon disclosure to thermal process electrification timelines. Hyundai Heavy Industries and Samsung Heavy Industries are specifying corrosion-resistant immersion systems for newbuild LNG carriers and offshore platforms.
Immersion Heater Market Competitive Landscape
Portfolio diversification dominates the current landscape as established thermal equipment manufacturers extend into adjacent electrification technologies. The vendor base spans captive-alloy producers, heat pump system integrators, and specialized industrial fabricators with limited geographic overlap. Three archetypes anchor competitive positioning: vertically integrated alloy suppliers controlling sheathing material costs, bundled system providers capturing residential water heating retrofits, and process-specialized OEMs serving oil and gas downstream. M&A activity and strategic partnerships represent the primary competitive vectors as mid-cap players seek scale in European and North American electrification markets.
Among Nordic system integrators, NIBE Group exemplifies the bundled-technology archetype through captive production of heat pump immersion heaters paired with residential water heating systems. Chromalox occupies a position among alloy-integrated manufacturers, leveraging in-house heating element production to manage specialty metal sourcing costs and delivery timelines. CIRCOR International represents the process-specialized tier, competing through flanged and circulation heater designs for industrial downstream applications.
| Leading Market Players |
|---|
| NIBE Group |
| CIRCOR International |
| Chromalox |
| Headway Electric Heat Components |
| Minco Products |
| Hotset GmbH |
| Phillips & Temro Industries |
| Thermal Corporation |
| Industrial Heater Corporation |
| Others |
Supply & Pricing Matrix
EU Ecodesign Directive efficiency thresholds are compelling facility operators to specify premium alloy sheathing and redundant thermal protection, forcing manufacturers to absorb specialty metal sourcing costs or pass them through as tiered product positioning. This procurement specification shift compresses margins on standardized resistive units while creating pricing power for REACH-compliant coating systems and induction designs.
Pricing Analysis
Volume deployment concentrates in transactional per-unit sales of standardized resistive elements, while project-based contracting captures premium margins for custom flanged and circulation configurations. Pricing stratifies across premium, standard, and economy tiers based on certification grade—UL-listed and IEC 60335-2-73-compliant units command 15-25% premiums—and alloy specification, with Incoloy and titanium sheathing carrying material surcharges. Cost compression in the standard tier is intensifying because nickel alloy supply concentration exposes mid-market manufacturers to price volatility. Residential retrofit buyers exhibit highest price sensitivity, prioritizing first-cost minimization over lifecycle efficiency, while pharmaceutical and semiconductor operators prioritize contamination elimination over unit economics.
Supply Chain Analysis
Certification and qualification gating through IEC 60335-2-73 and UL 499 standards restricts qualified supplier pools, concentrating production among captive-alloy manufacturers in Germany, the United States, and Sweden. Raw material dependencies center on nickel-chromium resistance wire from European specialty metal producers, titanium sponge from Japanese and Russian suppliers, and plasma-sprayed ceramic coatings substituting for REACH-restricted hexavalent chromium. Single-source vulnerability in aerospace-grade titanium sheathing exposes lead times to geopolitical disruption. Distribution runs through industrial distributors and OEM direct channels, with aftermarket service contracts increasingly unbundled from initial equipment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The immersion heater market sits in a technology-transition phase as induction heating displaces direct-element resistive designs in contamination-sensitive process applications. This shift rewrites competitive positioning and opens white-space opportunities for specialized entrants.
For Market Incumbents: Extend alloy sourcing control through backward integration into nickel-chromium wire production or long-term offtake agreements with specialty metal producers to defend against price volatility. Accelerate IEC 60335-2-73 certification pipelines for induction product lines before regulatory deadlines harden competitive moats. Chromalox and similar captive-alloy producers should leverage existing vertical control to compress delivery timelines and capture pharmaceutical retrofit demand.
For New Entrants and Emerging Players: Capture underpenetrated marine and offshore corrosion applications through titanium-sheathed designs for South Korean and Japanese shipbuilding customers, where incumbent presence remains limited. Target U.S. Inflation Reduction Act clean manufacturing credit eligibility as a go-to-market wedge, bundling equipment procurement with documentation support for tax credit capture in domestic chemical processing retrofits.
For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with captive alloy supply and existing IEC certification infrastructure, as regulatory compliance costs erect barriers against de novo market entry. Watch for inflection in carbon border adjustment implementation timelines, which would accelerate electric heater displacement of gas-fired alternatives and expand addressable market for certified European suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Supply | Captive nickel-chromium sourcing insulates Chromalox and NIBE from price volatility and extends delivery reliability. |
| Induction Technology Platform Development | Non-contact thermal transfer opens pharmaceutical and semiconductor applications previously closed to resistive designs. |
| REACH-Compliant Coating System Certification | Plasma-sprayed ceramic alternatives maintain European market access as hexavalent chromium restrictions tighten. |
| Heat Pump Immersion Heater Hybrid Bundling | NIBE's captive production captures residential water heating retrofits under building electrification mandates. |
| Marine and Offshore Corrosion Application Expansion | Titanium-sheathed designs for South Korean shipbuilding address underpenetrated ballast water treatment demand. |
Research Methodology
Multi-period observation of alloy price indices, regulatory implementation timelines, and electrification policy announcements anchored the trend analysis, supplemented by interviews with plant engineers at chemical processing facilities, procurement leads at downstream OEMs, aftermarket service heads, and technical R&D directors at heating element manufacturers. Secondary validation drew from MIIT efficiency standard filings, EU Ecodesign Directive implementation documents, SEC 10-K disclosures from listed thermal equipment manufacturers, and customs trade data for nickel alloy imports. Bottom-up unit deployment estimates triangulated against top-down energy consumption projections for industrial process heating.
The input-output matrix framework modeled deployment volumes across technology type, end-use environment, installation configuration, and regional regulatory cluster, with value outputs derived from disclosed transaction pricing and project contract values. CAGRs were computed from fitted growth curves across the projection horizon, incorporating alloy cost pass-through assumptions and electrification policy acceleration scenarios. Industry-specific forecast inputs included State Grid Corporation distribution capacity expansion schedules and EPA emissions regulation tightening trajectories for petrochemical downstream operations.
The model holds under continued enforcement of EU Ecodesign efficiency thresholds and MIIT dual carbon implementation; deviation in carbon border adjustment timing or nickel alloy export restriction intensity would shift replacement demand curves. Forecasts reflect documented assumptions regarding policy continuity and supply chain stability. A model refresh is warranted upon material change in IEC 60335-2-73 certification requirements or REACH substance restriction expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Global Switchgear Monitoring Market
Electrical Power Equipment
Substation Market
Electrical Power Equipment
Gas Water Heater Market
Electrical Power Equipment
India Instrument Transformer Market
Electrical Power Equipment
Digital Fault Recorder (DFR) Market
Electrical Power Equipment
Global Lightning Arrester Market
Electrical Power Equipment
Unitary Heaters Market
Electrical Power Equipment
Bio-Based Transformer Oil Market
Electrical Power Equipment
Global Surge Arrester Market
Electrical Power Equipment
United States Electric Space Heaters Market
Electrical Power Equipment
Fault Circuit Indicator Market
Electrical Power Equipment
Asia Pacific Gas Insulated Switchgear Market
Electrical Power Equipment
Substation Testing Equipment Market
Electrical Power Equipment
Europe Electric Space Heaters Market
Electrical Power Equipment
Solid Vacuum Reclosers Market
Electrical Power Equipment
Storage Water Heater Market