
 North America Induction Motor Market | 2026-2036
North America Induction Motor Market Size, Share, and Industry Trends Forecast 2026-2036
North America Induction Motor Market Analytics
Mexico's manufacturing expansion is rewriting supply chain dynamics for induction motor producers serving North American OEMs. ABB Ltd. leverages its regional service network to sustain aftermarket revenue across Mexican automotive plants. Siemens AG anchors its position through localized production of high-efficiency units for U.S. energy infrastructure. Nidec Motor Corporation specializes in fractional horsepower variants for commercial HVAC OEMs.
An induction motor converts electrical energy into mechanical rotation through electromagnetic induction between stator windings and a conductive rotor, typically operating at fixed speeds determined by supply frequency and pole count. These machines power compressors, conveyors, and pumping systems across industrial and commercial installations. Three phase units dominate heavy-load manufacturing equipment while variable frequency drive pairings capture expanding share in building automation retrofits. Squirrel cage designs occupy the mature volume tier whereas linear induction variants serve niche material handling segments with premium positioning.
The U.S. Department of Energy enforces minimum full-load efficiency standards under 10 CFR 431, compelling manufacturers to redesign copper rotor architectures and reduce stray load losses. Canada's Natural Resources Canada administers parallel regulations through its Energy Efficiency Act, creating dual compliance obligations for cross-border suppliers. NHTSA efficiency mandates for electric vehicle traction systems indirectly stimulate adjacent induction motor R&D. Stakeholders must monitor pending EPA industrial electrification guidance and assess whether DOE rulemaking timelines compress product development cycles.
Market Dynamics
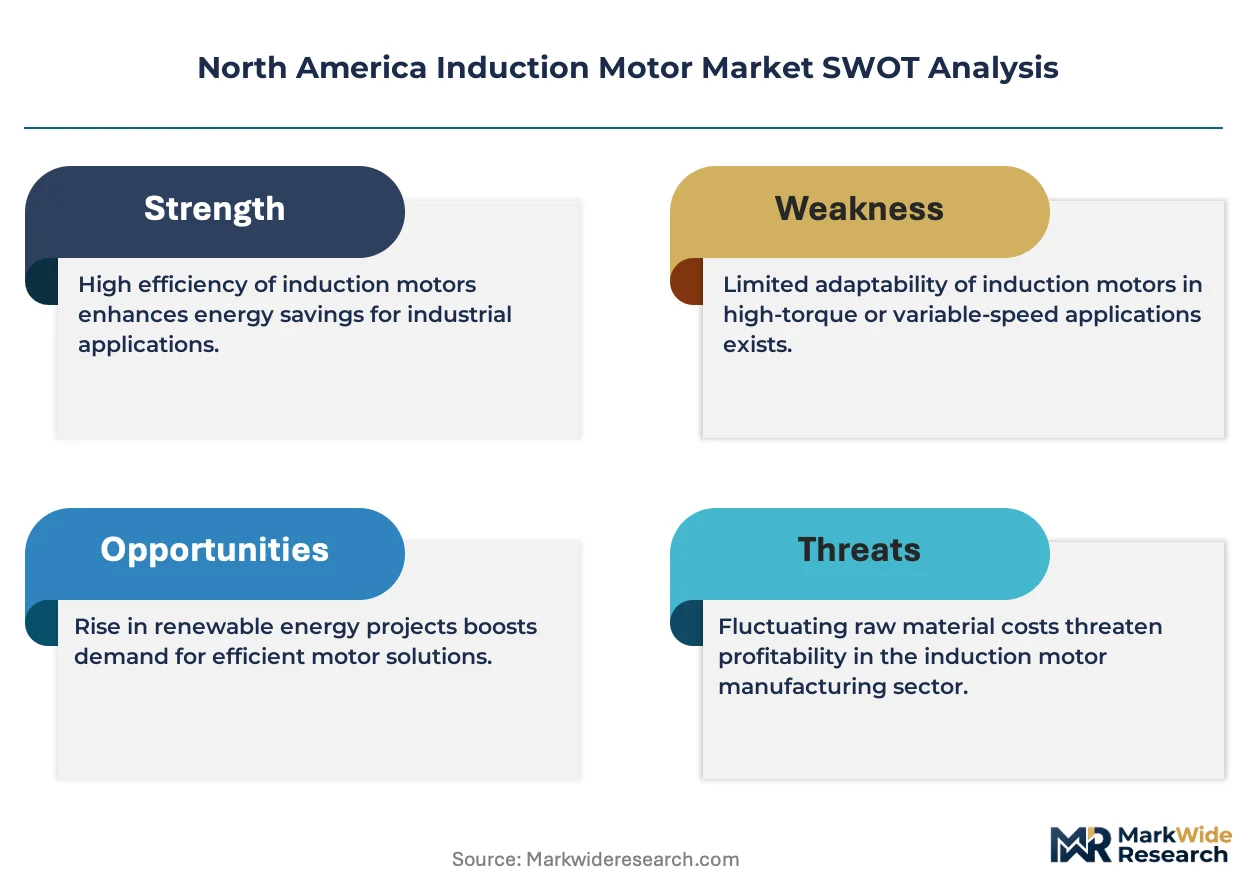
The U.S. Department of Energy's 10 CFR 431 efficiency mandates are forcing wholesale redesign of copper rotor architectures and stator winding configurations across the North American supplier base. Manufacturers now face compressed product development cycles as dual compliance obligations with Canada's Energy Efficiency Act layer additional certification burdens onto cross-border production.
Growth Catalysts
- 10 CFR 431 Efficiency Mandates:The U.S. Department of Energy's full-load efficiency standards compel replacement of aging motor fleets in water treatment facilities and industrial pumping stations.
- Texas Industrial Corridor Expansion:Petrochemical and LNG infrastructure buildout along the Gulf Coast generates concentrated demand for high-horsepower three-phase units in compressor and pump applications.
- Copper Rotor Technology:Advanced die-cast copper rotor designs reduce stray load losses and enable premium efficiency tier certification, unlocking utility rebate eligibility for end-users.
Market Restraints
- Neodymium Price Volatility:Rare earth magnet cost fluctuations in permanent magnet motor supply chains create pricing pressure on induction motor alternatives competing for efficiency-sensitive applications.
- Chinese Stator Lamination Concentration:Overreliance on East Asian electrical steel suppliers exposes North American OEMs to tariff uncertainty and extended lead times for core magnetic materials.
- Fixed-Speed Limitation:Induction motors operating without variable frequency drives cannot match the precise speed control of servo systems in precision material handling applications.
Strategic Opportunities
- Mexico Automotive Manufacturing:OEM supplier park expansion in Guanajuato and Nuevo León creates localized demand for fractional horsepower motors in stamping press and conveyor automation.
- Building Automation Retrofits:VFD-induction pairings displace legacy damper and valve control in commercial HVAC systems, capturing efficiency incentives under utility demand-side management programs.
- Linear Induction Niche Penetration:Material handling applications in airport baggage systems and automated warehouse sorting lanes adopt linear induction for contactless propulsion with reduced maintenance intervals.
Industry Challenges
- Winding Technician Shortage:Specialized skills for precision stator coil insertion and varnish impregnation are scarce across U.S. Midwest manufacturing hubs, constraining domestic production scaling.
- Dual Certification Timelines:Simultaneous DOE and Natural Resources Canada validation processes extend time-to-market for new efficiency tier products by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Induction Motor Market |
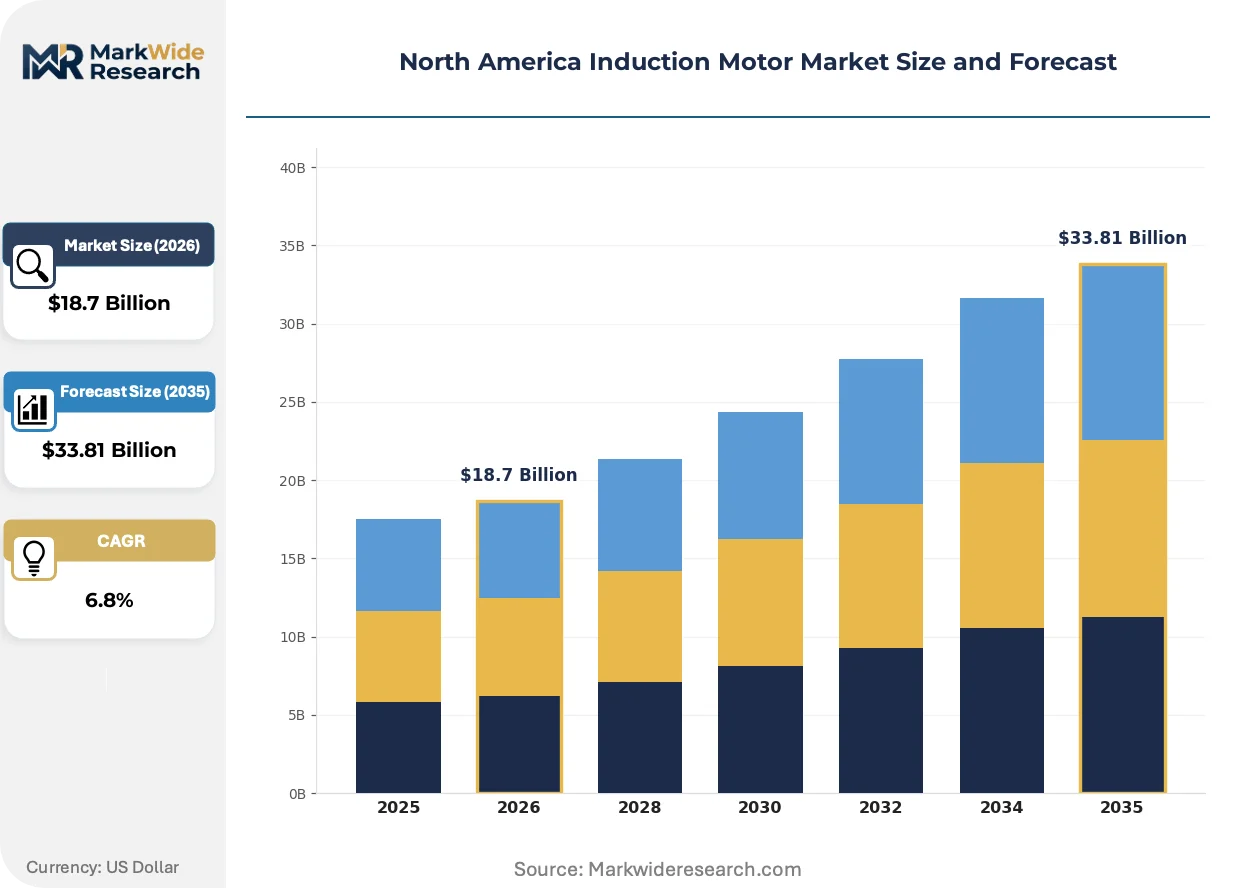
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
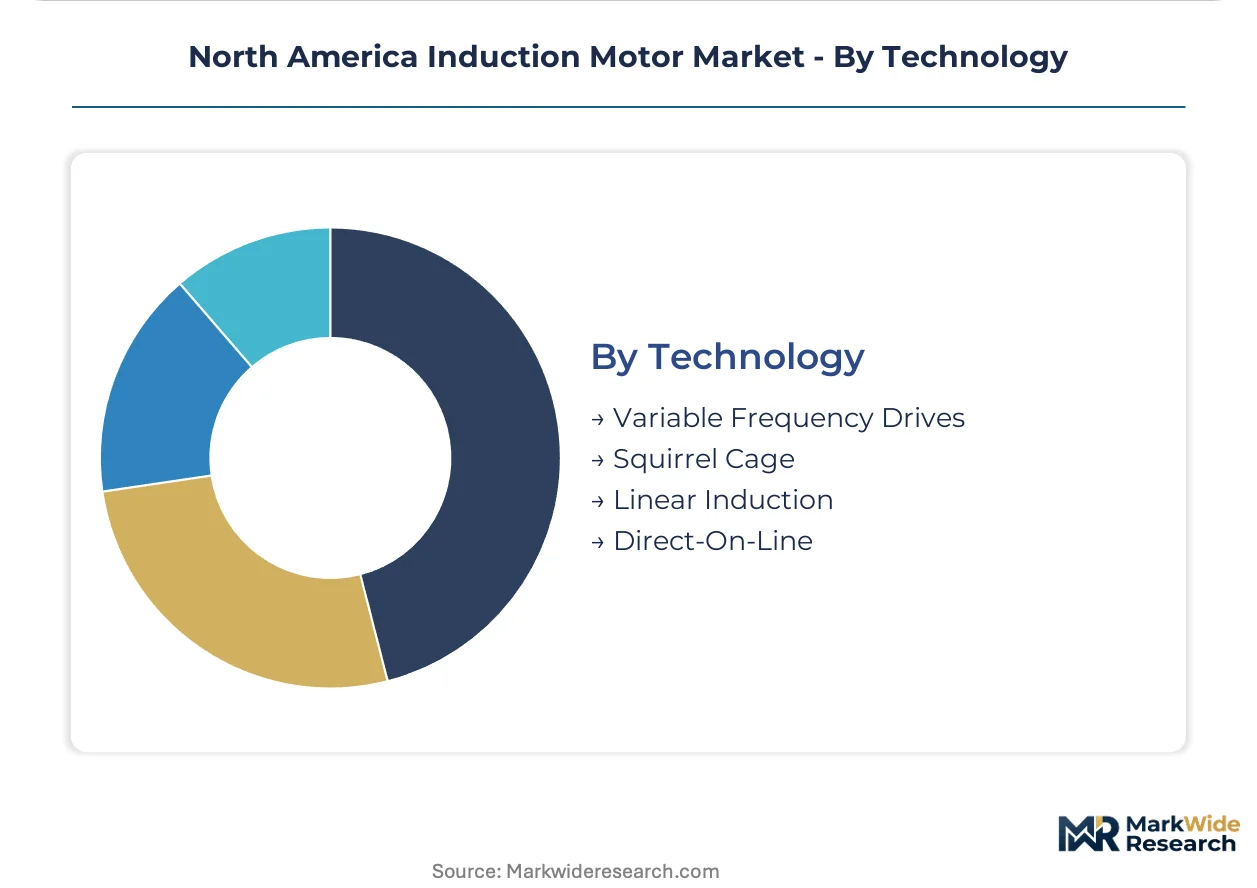
| Segmentation | Product Type: Single Phase, Three Phase, Double Cage, Wound Rotor Application: Agricultural Machinery, HVAC Systems, Manufacturing Equipment, Pumps End User: Building Automation, Industrial, Energy Sector, Transportation Technology: Variable Frequency Drives, Squirrel Cage, Linear Induction, Direct-On-Line |
| Companies Covered | ABB Ltd., Siemens AG, Nidec Motor Corporation, Rockwell Automation, Inc., WEG S.A., Emerson Electric Co., Schneider Electric SE, Regal Rexnord Corporation, Baldor Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Induction Motor Market Evolving Landscape
Electromagnetic design tools and advanced manufacturing processes are compressing development cycles for next-generation induction motor platforms. The competitive frontier now centers on thermal management optimization and predictive maintenance integration rather than incremental efficiency gains.
Copper die-casting technology is migrating from premium industrial segments into mid-range commercial HVAC applications. Building automation contractors in California and Texas are specifying copper rotor units to secure utility rebate thresholds. This material transition is compressing the price premium between standard aluminum and advanced copper architectures, reshaping supplier margin structures across the efficiency tier landscape.
The U.S. Department of Energy's pending expanded efficiency rulemaking under 10 CFR 431 will extend coverage to currently exempt specialty motor categories. Manufacturers serving oil and gas pumping applications must redesign for compliance or exit affected product lines. Canadian regulators are harmonizing adoption timelines, creating synchronized compliance windows that favor suppliers with integrated North American certification capabilities.
Equipment-as-a-service contracting is displacing traditional capital purchase models in municipal water infrastructure. Texas and California utilities now procure pumping systems on performance-based contracts where motor efficiency guarantees determine vendor selection. This financing shift concentrates purchasing authority with integrated solution providers, marginalizing standalone motor distributors in public sector procurement channels.
North America Induction Motor Market Segmentation
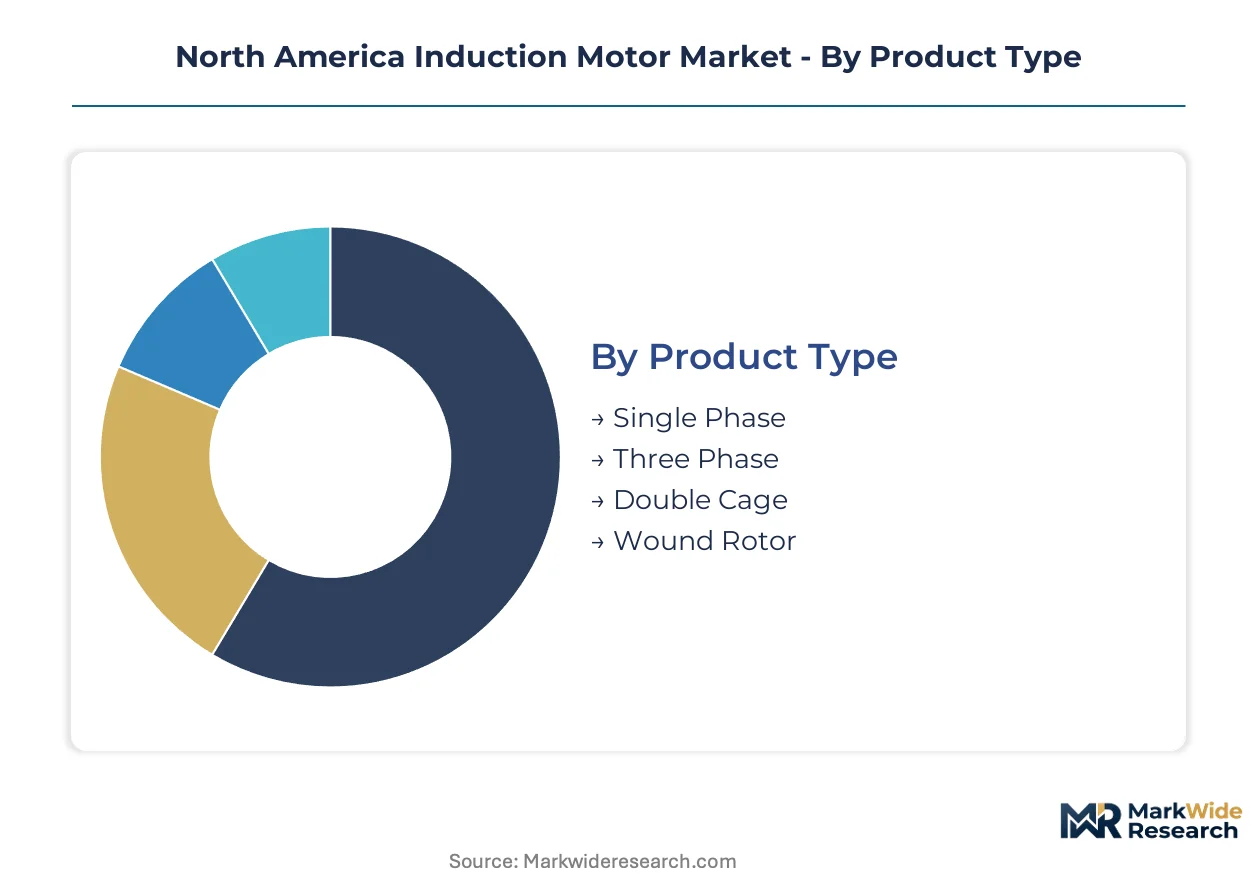
Segmentation reveals how North American procurement specifications diverge across efficiency mandates and duty cycle requirements. Copper rotor architectures and VFD pairings command premium positioning in regulated industrial corridors while standard aluminum designs retain volume dominance in commercial building automation.
Product Type:
After-sales service intensity varies sharply across rotor architectures, with wound rotor units requiring specialized maintenance protocols and copper cage designs demanding minimal field intervention.
- Three Phase:These units power heavy-load manufacturing equipment and petrochemical compressors along the Texas Gulf Coast. DOE efficiency mandates are accelerating fleet replacement in municipal water treatment facilities.
- Single Phase:Fractional horsepower variants serve commercial HVAC OEMs and agricultural auxiliary equipment. California utility rebate programs are concentrating demand for premium efficiency tier certification.
- Double Cage:Dual-cage rotor designs deliver high starting torque for mining conveyors and crusher applications.
- Wound Rotor:External resistance control suits wound rotor configurations for crane hoists and elevator systems requiring precise speed modulation.
Three Phase holds the largest share; momentum sits with Single Phase as building automation retrofits accelerate.
Application:
Cost tier stratification separates specification-grade industrial pumps from commodity HVAC replacements, with utility incentives compressing price premiums at the mid-market boundary.
- Pumps:Municipal water infrastructure and oil field artificial lift systems dominate this segment. Texas and California utilities now procure on performance-based contracts where efficiency guarantees determine vendor selection.
- HVAC Systems:VFD-induction pairings displace legacy damper controls in commercial retrofits. Utility demand-side management programs in California and Texas are capturing expanding share for variable speed configurations.
- Manufacturing Equipment:Conveyor systems and stamping presses in Mexican automotive supplier parks drive fractional horsepower demand.
- Agricultural Machinery:Irrigation pumps and grain handling equipment in Midwest farming corridors specify standard efficiency tier units.
Pumps commands the dominant revenue position; HVAC Systems are climbing the fastest on building electrification incentives.
End User:
Customer type determines procurement channel structure, with industrial buyers negotiating direct manufacturer relationships and building automation contractors purchasing through integrated solution providers.
- Industrial:Petrochemical and LNG infrastructure buildout along the Gulf Coast generates concentrated demand for high-horsepower compressor and pump motors. DOE 10 CFR 431 compliance is forcing wholesale fleet replacement.
- Building Automation:Commercial HVAC retrofits and smart building integration drive VFD-induction pairings. California Title 24 energy codes are mandating variable speed control in new construction.
- Energy Sector:Grid-scale battery storage cooling and renewable generation auxiliary systems specify premium efficiency units.
- Transportation:Airport baggage handling and automated warehouse sorting lanes adopt linear induction for contactless propulsion.
Industrial retains the largest installed base; Building Automation is gaining share fastest on electrification mandates.
Technology:
Supply concentration in East Asian electrical steel shapes competitive positioning across magnetic core architectures, with domestic lamination capabilities determining tariff exposure.
- Variable Frequency Drives:VFD-induction pairings enable precise speed control for building automation and precision material handling. DOE extended product regulations are tightening system-level efficiency requirements.
- Squirrel Cage:Die-cast aluminum and copper rotor designs occupy the mature volume tier across industrial and commercial applications. Copper die-casting technology is migrating from premium segments into mid-range HVAC specifications.
- Linear Induction:Contactless propulsion serves niche material handling in airport baggage systems and automated warehouse sorting lanes.
- Direct-On-Line:Fixed-speed DOL starting remains standard for pumps and compressors in cost-sensitive agricultural and municipal applications.
Squirrel Cage dominates unit volume; Variable Frequency Drives show the steepest expansion trajectory on efficiency regulation tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrical steel lamination supply concentrates in East Asian mills, exposing North American OEMs to tariff volatility and forcing regional fabricators to secure alternative core material sources. Mexico's manufacturing corridor expansion is redrawing procurement patterns for fractional horsepower units serving automotive supplier parks.
United States
Texas Gulf Coast petrochemical buildout and California water treatment retrofits drive concentrated demand for high-horsepower three-phase units. DOE 10 CFR 431 efficiency mandates compel fleet replacement across municipal pumping stations. Houston and Los Angeles industrial corridors anchor procurement volume for premium efficiency tier certification.
Canada
Oil sands artificial lift systems and hydropower auxiliary equipment sustain demand for wound rotor configurations in Alberta and Quebec. Natural Resources Canada's Energy Efficiency Act imposes parallel certification requirements on cross-border suppliers. Toronto and Calgary engineering hubs concentrate specification authority for energy sector procurement.
Mexico
Automotive supplier park expansion in Guanajuato and Nuevo León generates localized demand for fractional horsepower motors in stamping press automation. Federal electricity commission efficiency programs incentivize premium tier adoption in manufacturing facilities. Querétaro and Monterrey industrial clusters anchor regional distribution networks serving North American OEMs.
North America Induction Motor Market Competitive Landscape
Integrated industrial conglomerates and specialized motor fabricators split the market across efficiency tier and application specialization boundaries. The supplier base organizes around three strategic archetypes: full-line industrial automation providers, dedicated motor manufacturers with regional service networks, and fractional horsepower specialists serving HVAC OEM channels. Competitive dynamics center on copper rotor technology licensing and aftermarket service contract capture rather than pure manufacturing scale.
Within the integrated automation tier, ABB Ltd. and Siemens AG occupy positions exemplifying the convergence of motor production with broader electrification portfolios. Nidec Motor Corporation anchors the fractional horsepower specialization vector. These three entities represent distinct competitive postures: Swiss-Swedish and German industrial conglomerates leverage cross-selling synergies, while the Japanese specialist concentrates density in commercial building automation channels.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| Nidec Motor Corporation |
| Rockwell Automation, Inc. |
| WEG S.A. |
| Emerson Electric Co. |
| Schneider Electric SE |
| Regal Rexnord Corporation |
| Baldor Electric Company |
| Others |
Value Network & Pricing Analysis
Port of Houston container freight corridors impose cost volatility on electrical steel imports from East Asian mills, compressing margins for domestic lamination fabricators while amplifying price spreads between premium copper rotor units and standard aluminum designs across Texas and California procurement channels.
Pricing Analysis
DOE 10 CFR 431 dictates the pricing tier structure across the North American induction motor market, separating premium efficiency certified units from standard aluminum rotor alternatives. Price differentiation hinges on copper die-casting certification grade and utility rebate eligibility thresholds, with California Title 24 compliance commanding the steepest premiums. Cost compression in mid-range commercial HVAC specifications is intensifying because copper rotor technology migrates downward from industrial segments. Municipal water utilities exhibit the highest price sensitivity due to capital budget constraints, while petrochemical operators prioritize lifecycle efficiency over first cost.
Supply Chain Analysis
Extended payment terms from East Asian electrical steel suppliers now stretch to 120 days for North American OEMs, straining working capital across domestic lamination fabricators. Magnetic core production draws from China, Japan, and South Korea, with grain-oriented electrical steel, copper cathode, and aluminum ingot constituting critical input dependencies. Single-source vulnerability concentrates in Nippon Steel and POSCO mill allocations for ultra-thin lamination grades. Distribution runs through integrated industrial distributors in Houston and Los Angeles, with aftermarket service contracts increasingly bundled into initial equipment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America induction motor market is entering a cyclical recovery phase, with DOE efficiency mandate compliance deadlines and municipal infrastructure replacement cycles synchronizing demand inflection across the 2026-2035 window.
For Market Incumbents: Pre-empt permanent magnet motor substitution threats by accelerating copper rotor cost reduction programs and locking multi-year lamination supply agreements with non-Chinese mill sources. Secure backward integration into domestic electrical steel slitting operations to defend margin position against tariff volatility. Prioritize certification pre-positioning for pending EPA industrial electrification guidance.
For New Entrants and Emerging Players: Canadian wound rotor applications in Alberta oil sands artificial lift systems offer underpenetrated white-space opportunity with localized technical service requirements that deter distant competitors. Target fractional horsepower building automation retrofits in Texas secondary metro corridors where incumbent service density remains thin. Pursue equipment-as-a-service financing partnerships with municipal utilities to bypass traditional distributor channel barriers.
For Investors and Strategic Acquirers: Pending DOE expanded efficiency rulemaking under 10 CFR 431 reshapes the acquisition landscape by forcing specialty motor line exits among sub-scale competitors. Long-term viability centers on integrated North American certification capabilities spanning DOE and Natural Resources Canada validation timelines. Monitor copper rotor die-casting equipment utilization rates as the inflection signal for sector consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Copper Rotor Technology Licensing | Unlocks utility rebate eligibility under California Title 24 and Texas demand-side management programs. |
| Dual Certification Investment | Compresses time-to-market for simultaneous DOE and Natural Resources Canada efficiency tier validation. |
| Mexico Manufacturing Footprint Expansion | Captures automotive supplier park demand in Guanajuato and Nuevo León with localized production. |
| Equipment-as-a-Service Contracting | Displaces traditional capital purchase models in Texas and California municipal water infrastructure procurement. |
| Domestic Lamination Backward Integration | Reduces tariff exposure from East Asian electrical steel concentration and secures core material supply. |
Research Methodology
Desk research of trade association technical publications, SEC manufacturing filings, and utility regulatory dockets preceded structured interviews with plant engineers at Texas petrochemical facilities, California water treatment operators, and Mexican automotive supplier procurement teams. Primary fieldwork with OEM motor procurement directors and aftermarket service heads was cross-validated against DOE certification databases and Natural Resources Canada efficiency registry records. Bottom-up unit shipment estimates by horsepower tier and application were triangulated against top-down value projections derived from distributor price benchmarking.
Assumptions regarding DOE rulemaking timeline adherence, copper price band stability, and Mexican manufacturing corridor expansion velocity were held fixed across baseline scenarios, with sensitivity analysis applied to tariff rate variation and rare earth magnet substitution acceleration. Segmentation modeling incorporated rotor architecture, phase configuration, end-use application, and regional regulatory cluster dimensions. CAGRs were derived from logistic diffusion curves fitted to historical fleet replacement patterns and mandated efficiency upgrade deadlines. Forecast inputs included municipal capital expenditure plans from Texas and California water utilities and automotive production capacity announcements from Guanajuato state development authorities.
Practitioners should monitor DOE notice-and-comment proceedings, Canadian harmonization timeline announcements, and copper spot price band breaches for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Smart Motors Market
Industrial Motors
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market
Industrial Motors
North America Hazardous Location Motors Market
Industrial Motors
US Electric Motor Market
Industrial Motors
Food Grade Hydraulic Oil Market
Industrial Motors
Power Scraper Market
Industrial Motors
Permanent Magnet Synchronous Motors Market
Industrial Motors
Synchronous Electric Motor Market
Industrial Motors
Latin America Electric Drives Market
Industrial Motors
High Voltage Motor Sleeve Bearing Market
Industrial Motors
Air Heater Tubes Market
Industrial Motors
AC Servo Motors and Drives Market
Industrial Motors
Safety Drives and Motors Market
Industrial Motors
Fractional Horsepower Motor Market
Industrial Motors
Europe Tank Insulation Market
Industrial Motors
Electric Motors for Drones and Electric Vehicle Market