
 Global Permanent Magnet Motor Market | 2026-2036
Global Permanent Magnet Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Permanent Magnet Motor Market Outlook
The EU F-Gas Regulation is broadening the cost-of-entry calculus for HVAC motor suppliers serving the European market. ABB leverages its magnet-to-motor vertical integration to sustain margin stability across rare-earth price cycles. Siemens anchors its position through in-house production of high-grade laminated stators for traction applications. NIDEC CORPORATION dominates the brushless DC segment for hard disk drives and precision robotics.
Permanent magnet motors employ rare-earth or ferrite magnets bonded to rotors, generating torque through synchronous interaction with stator windings at efficiencies exceeding 95% in optimized designs. The AC motor segment leads industrial installations due to mature inverter infrastructure and service networks. Brushless motors represent the fastest-expanding category, driven by electric vehicle traction demands and drone propulsion systems. Stepper motors occupy a mature niche in precision positioning equipment where open-loop control suffices.
The EPA enforces efficiency mandates under NEMA Premium standards that disqualify induction motor retrofits in US industrial facilities. Japan's METI coordinates domestic rare-earth stockpiling programs that stabilize magnet supply for Toshiba Corporation and Yaskawa Electric Corporation. China's MIIT imposes GB energy-efficiency tiers that force motor replacement cycles in domestic manufacturing plants. Stakeholders must monitor magnet recycling technology maturation and alternative topologies that reduce dysprosium dependence.
Market Dynamics
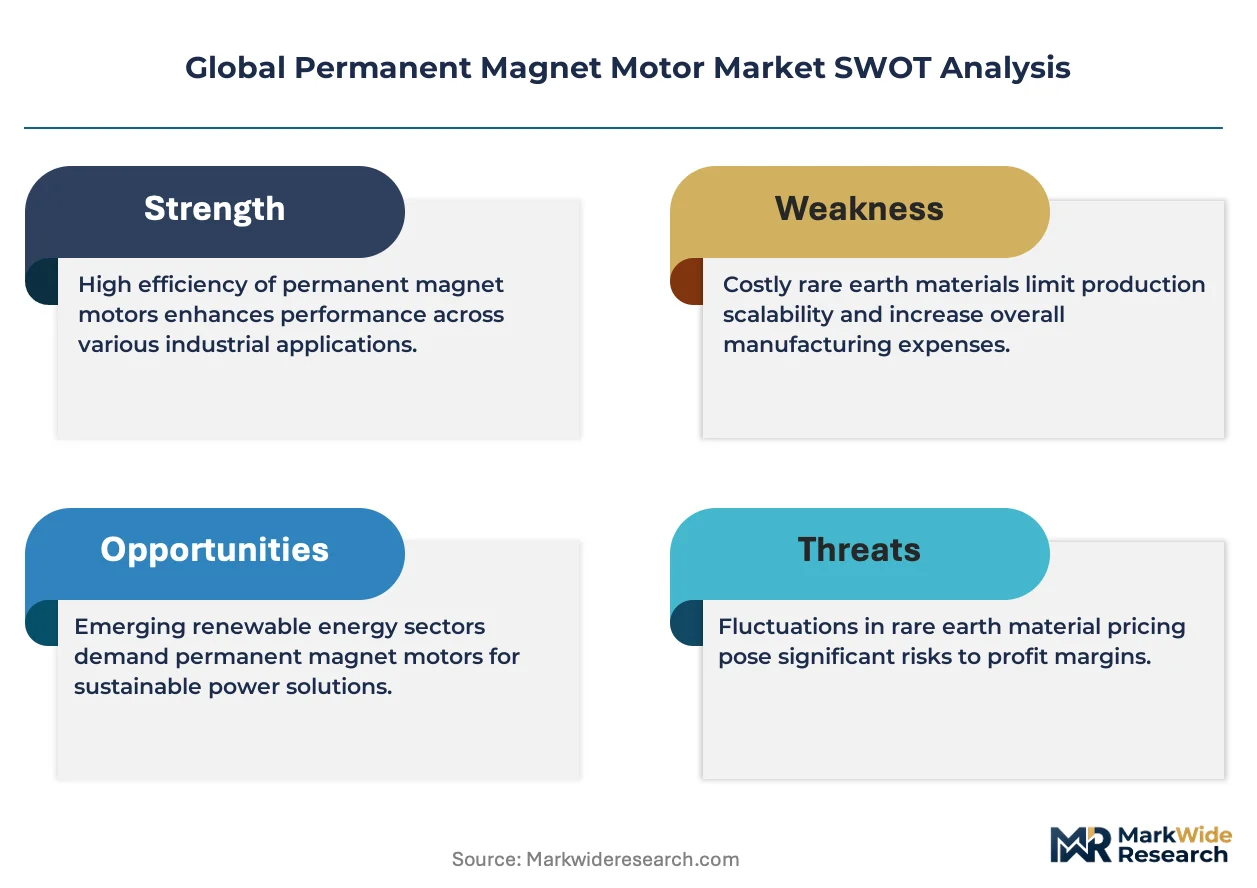
Rare-earth supply concentration in China's Inner Mongolia and Jiangxi provinces is forcing motor manufacturers to reconfigure procurement strategies and accelerate magnet recycling investments. This geographic chokepoint concentrates pricing power among state-controlled refiners and triggers volatile neodymium-dysprosium cost cycles that ripple through downstream motor assembly economics.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants in commercial HVAC systems is mandating high-efficiency compressor retrofits across Germany, France, and Italy, expanding addressable demand for permanent magnet synchronous motors.
- Electric vehicle traction architectures:800-volt platform proliferation in premium automotive segments is eliminating induction motor options and cementing interior permanent magnet rotor designs as the dominant topology.
- Drone propulsion miniaturization:Agricultural spraying and last-mile delivery UAV fleets in Brazil and Australia are standardizing on high-torque-density brushless DC configurations.
Market Restraints
- Neodymium oxide price volatility:Spot market swings exceeding 40% within 18-month windows compress motor assembler margins and deter long-term supply contracts.
- Dysprosium supply concentration:Over 85% of heavy rare-earth separation capacity resides in Chinese state-owned entities, creating single-source vulnerability for high-temperature traction-grade magnets.
- Induction motor residual competitiveness:Copper rotor designs retain cost advantages in constant-speed pump and fan applications where variable frequency drive infrastructure is absent.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cell manufacturing:Domestic battery gigafactory construction is creating localized demand for precision winding equipment and cleanroom-grade servo motors.
- Magnet-to-motor remanufacturing:End-of-life wind turbine and EV drivetrain recovery is yielding secondary rare-earth feedstock at 60-70% of virgin material extraction costs.
- Silicon carbide inverter convergence:Pairing wide-bandgap power electronics with high-pole-count permanent magnet motors is unlocking 99% efficiency thresholds in data center cooling applications.
Industry Challenges
- Laminated stator core tooling lead times:High-speed electrical steel stamping die procurement from Japanese and German toolmakers now extends 14-18 months, constraining capacity expansion timelines.
- Multi-physics simulation talent scarcity:Electromagnetic-thermal-structural co-design expertise remains concentrated among a handful of European and North American engineering consultancies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Permanent Magnet Motor Market |
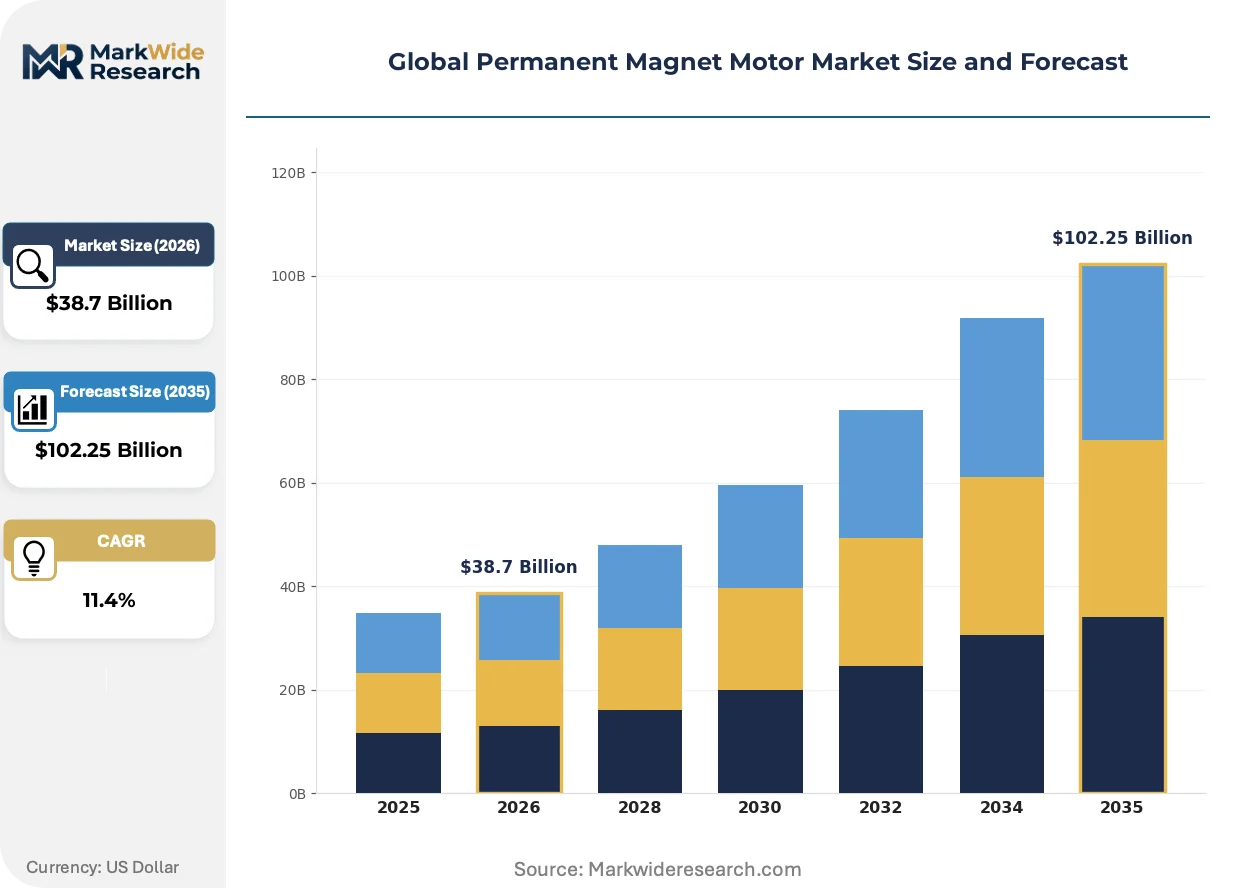
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: AC Motors, DC Motors, Stepper Motors, Brushless Motors End User: Automotive, Industrial Equipment, Consumer Electronics, HVAC Application: Electric Vehicles, Robotics, Home Appliances, Power Tools Technology: In-Hub Motors, Switched Reluctance Motors, Linear Motors, Others |
| Companies Covered | Wolong Electric, Toshiba Corporation, ABB, Yaskawa Electric Corporation, Rockwell Automation, Siemens, WEG, Johnson Electric Holdings Limited, NIDEC CORPORATION, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Permanent Magnet Motor Market Strategic Shifts
Computational magnet design and additive manufacturing of copper windings are compressing motor development cycles and enabling topology optimizations previously inaccessible to mass production. These capabilities are redistributing competitive advantage toward firms with integrated electromagnetic and thermal simulation competencies.
Grain boundary diffusion techniques for heavy rare-earth reduction are automating the substitution of dysprosium-terbium coatings in sintered NdFeB magnets. Automotive traction motor suppliers in Germany and South Korea are adopting these processes at pilot scale to qualify 30% lower heavy rare-earth formulations. This chemistry shift is automating cost de-risking strategies across Tier-1 supplier portfolios exposed to Chinese export quota volatility.
REACH authorization requirements for nickel and cobalt compounds are tightening material traceability obligations for European motor manufacturers. The regulation is compelling supply chain re-documentation and third-party audit investments that favor larger producers with established compliance infrastructure. Small and mid-sized industrial motor assemblers in Italy and Poland are consolidating procurement volumes to share testing laboratory costs.
Fleet electrification mandates in California and the EU are compressing commercial vehicle powertrain replacement cycles from 12-year to 7-year horizons. Municipal bus operators and regional logistics providers are now specifying motor designs with modular stator segments that enable field rewinding rather than full unit replacement. This servitization pivot is visible most acutely in Nordic countries where total-cost-of-ownership contracting has become standard procurement practice.
Global Permanent Magnet Motor Market Segmentation
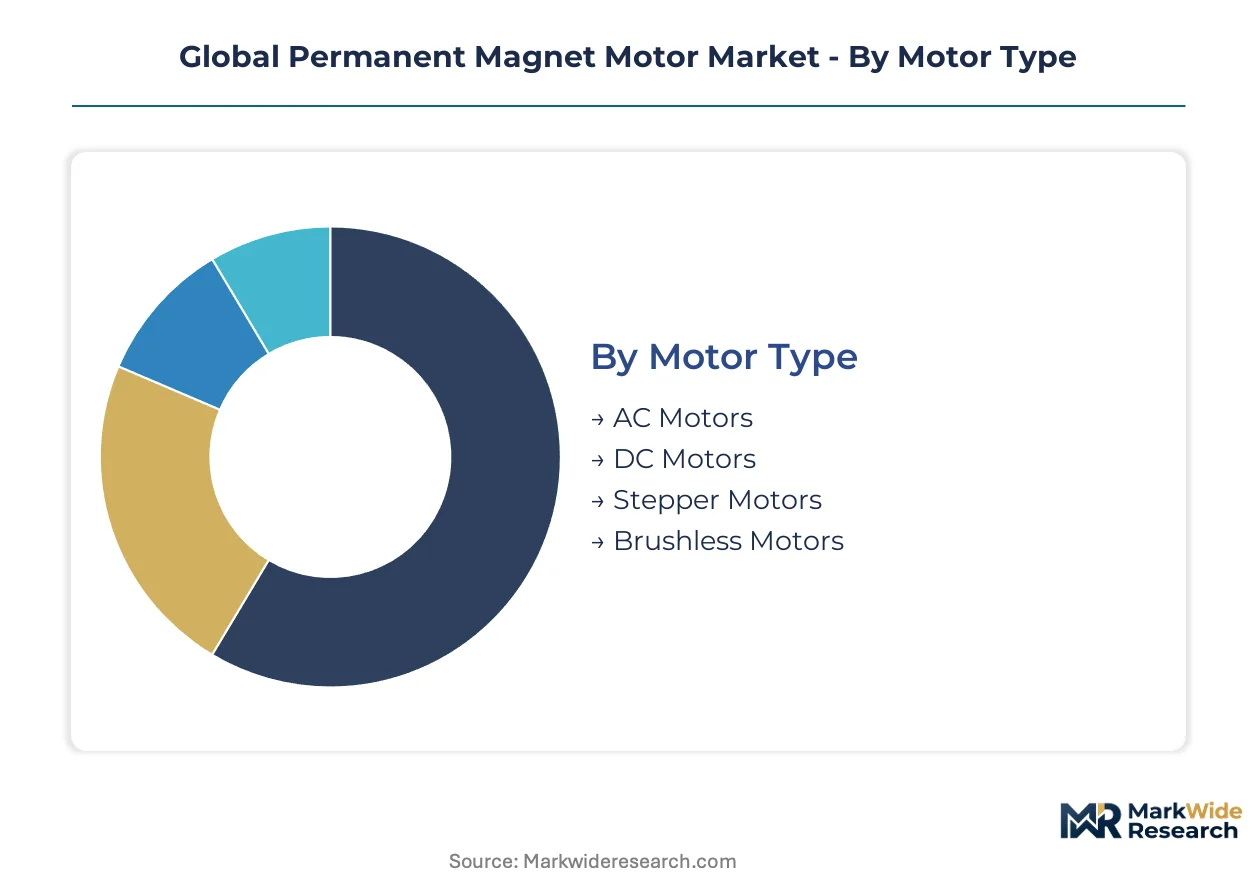
Permanent magnet motor procurement decisions pivot on torque density requirements, thermal envelope constraints, and rare-earth magnet exposure. Buyers in automotive and industrial sectors weight efficiency certification tiers against total lifecycle cost models. Segmentation clarity enables suppliers to align magnet grade selection with specific duty cycles and regulatory exposure.
Motor Type:
Efficiency mandates and inverter infrastructure availability drive motor type selection across end-use verticals.
- AC Motors:Synchronous designs with surface-mounted or interior permanent magnet rotors deliver efficiencies exceeding 95% when paired with modern variable frequency drives. Demand concentrates in German and Japanese industrial facilities where NEMA Premium and IE4 efficiency tiers are mandatory for motor replacement programs.
- Brushless Motors:Electronically commutated architectures eliminate mechanical wear and enable precise torque control through Hall-effect or sensorless position feedback. Electric vehicle traction applications in South Korea and California are standardizing on interior permanent magnet variants for 800-volt platform compatibility.
- DC Motors:Brushed configurations with ferrite or bonded neodymium magnets persist in cost-sensitive applications where electronic commutation overhead is prohibitive.
- Stepper Motors:Hybrid designs with permanent magnet rotors provide precise angular positioning without closed-loop encoders in laboratory automation and textile machinery.
Volume sits with AC Motors; growth tilts toward Brushless Motors.
End User:
Capital intensity and replacement cycle frequency separate industrial procurement from consumer-facing demand.
- Automotive:Traction motor specifications now demand continuous power density above 4 kW/kg for passenger electric vehicles, with separate thermal management circuits for stator windings and rotor magnets. OEMs in Germany and China are qualifying dual-source magnet supply chains to mitigate dysprosium concentration risk.
- Industrial Equipment:Servo motors for CNC machining centers and robotic arms require sub-arcminute positioning accuracy with peak torque overload capacity of 300% rated load.
- HVAC:Permanent magnet synchronous compressors are displacing induction motor alternatives in European commercial refrigeration systems subject to F-Gas Regulation retrofit timelines.
- Consumer Electronics:Miniature brushless motors for hard disk drives and camera autofocus mechanisms prioritize acoustic noise suppression below 25 dB.
Revenue concentration favors Automotive; margin stability resides with Industrial Equipment.
Application:
Duty cycle severity and environmental exposure dictate magnet grade and encapsulation specifications.
- Electric Vehicles:Traction motors must sustain 20,000 RPM maximum speeds with oil cooling integration for direct gearbox lubrication. 800-volt architectures in premium segments are eliminating induction motor options entirely.
- Robotics:Collaborative robot joints demand zero-cogging torque ripple and absolute encoder feedback for human safety certification.
- Power Tools:Cordless drill and angle grinder motors prioritize power-to-weight ratios with ferrite magnet cost floors for professional-grade equipment.
- Home Appliances:Washing machine direct-drive drums and refrigerator compressor motors balance efficiency gains against 15-year service life requirements.
Technology pull is strongest in Electric Vehicles; replacement velocity peaks in Power Tools.
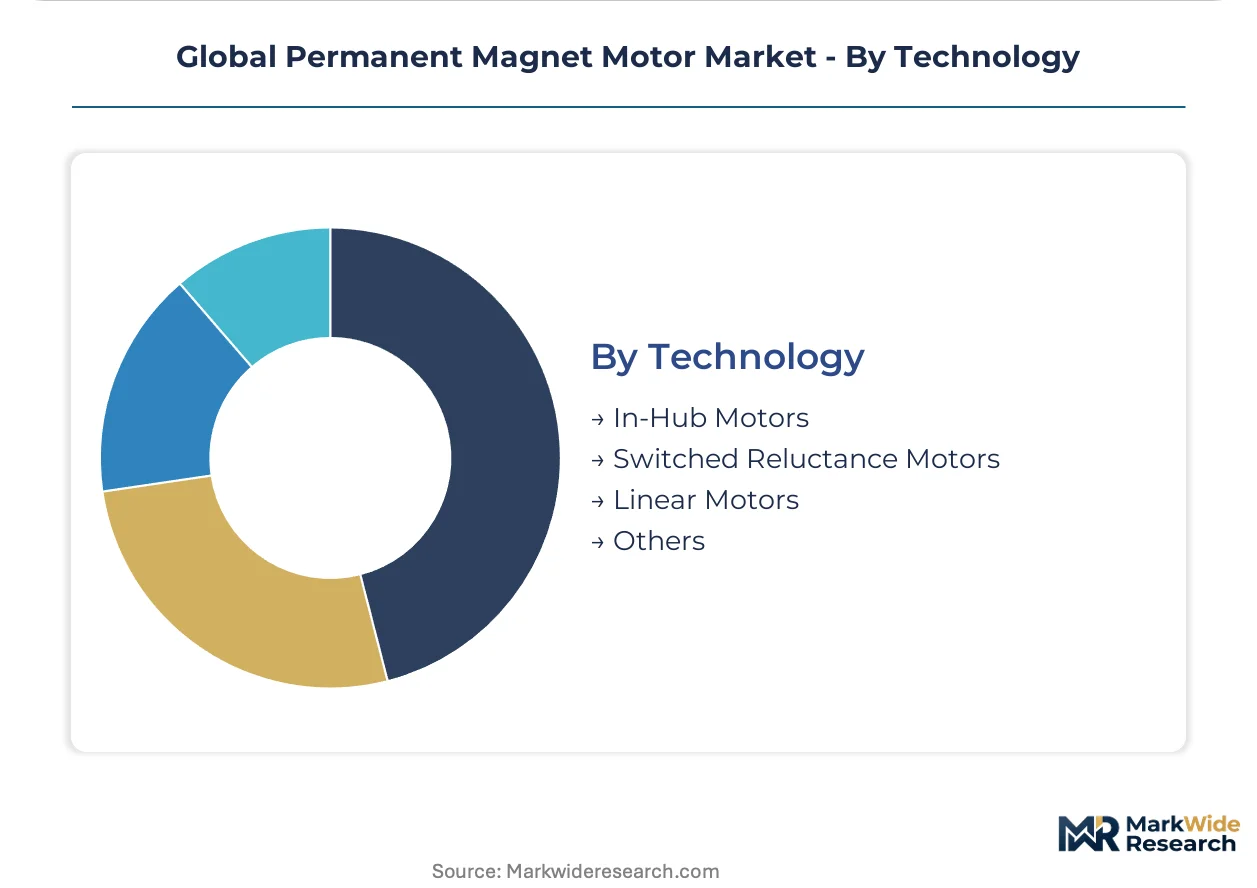
Technology:
Integration depth and motion kinematics separate in-wheel applications from linear positioning systems.
- In-Hub Motors:Direct-drive wheel integrations eliminate transmission losses and enable torque vectoring through independent phase current control. Electric bus fleets in Shenzhen and Santiago are specifying liquid-cooled variants with IP67 environmental sealing.
- Linear Motors:Flat or tubular permanent magnet synchronous designs provide direct linear motion without mechanical conversion in semiconductor wafer handling and high-speed rail braking systems.
- Switched Reluctance Motors:Magnet-free alternatives with salient pole rotors are gaining evaluation in mining equipment where magnet theft and supply disruption are operational risks.
- Others:Limited-angle torque motors and voice coil actuators serve specialized aerospace and medical imaging applications with restricted angular stroke requirements.
Deployment scale favors In-Hub Motors; steepest expansion trajectory belongs to Linear Motors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the dominant share of permanent magnet motor procurement, with Germany and the United States trailing as specialized high-efficiency markets. Japan and South Korea concentrate manufacturing expertise for precision automotive and industrial applications.
China
Domestic EV manufacturers in Shenzhen and Shanghai are scaling 800-volt traction motor production for export-bound vehicle platforms. MIIT enforces GB energy-efficiency tiers that accelerate motor replacement cycles in steel and cement plants. The Jiangxi rare-earth refining corridor supplies magnet feedstock to motor assemblers in Ningbo and Dongguan.
Germany
Commercial HVAC retrofit mandates under the EU F-Gas Regulation are expanding permanent magnet synchronous compressor demand across Frankfurt and Munich industrial zones. The KBA coordinates type-approval standards for automotive traction motors that align with EU Green Deal decarbonization timelines. Bavarian motor manufacturers in Ingolstadt and Nuremberg are qualifying dual-source magnet supply chains.
United States
EPA NEMA Premium standards are disqualifying induction motor retrofits in Texas and California petrochemical facilities. The IRA production tax credits are incentivizing domestic magnet-to-motor assembly investments in the Midwest automotive corridor. Detroit-area suppliers are piloting silicon carbide inverter pairings for data center cooling applications.
Japan
Precision servo motor demand from Tokyo and Osaka robotics manufacturers is concentrating procurement among vertically integrated producers. METI coordinates domestic rare-earth stockpiling programs that stabilize magnet supply for domestic motor assemblers. Nagoya-area industrial clusters are advancing grain boundary diffusion techniques for dysprosium reduction in sintered magnets.
South Korea
Hyundai and Kia electrification programs in Ulsan and Gwangju are standardizing interior permanent magnet rotor designs for 800-volt platforms. The MFDS enforces material traceability standards that align with REACH authorization requirements for nickel compounds. Busan-port logistics providers are consolidating procurement volumes for modular stator segment designs.
Global Permanent Magnet Motor Market Competitive Environment
German and Japanese producers anchor the premium-tier motor segment; Chinese fabricators hold volume-scale positions in standard-efficiency industrial applications. The vendor base splits between consolidated multinational electrical conglomerates and specialized servo motor manufacturers with captive magnet supply arrangements. Two strategic archetypes dominate: vertically integrated magnet-to-motor producers and precision winding specialists serving cleanroom-grade applications. Capacity expansion and strategic partnerships represent the dominant competitive moves across the analysis window.
Among diversified electrical equipment manufacturers, ABB and Siemens exemplify the integrated archetype with in-house magnet procurement and laminated stator production. NIDEC CORPORATION occupies a specialized position in brushless DC configurations for precision robotics and hard disk drive applications. Wolong Electric represents the scale-driven Chinese producer archetype serving industrial motor replacement cycles.
| Leading Market Players |
|---|
| Wolong Electric |
| Toshiba Corporation |
| ABB |
| Yaskawa Electric Corporation |
| Rockwell Automation |
| Siemens |
| WEG |
| Johnson Electric Holdings Limited |
| NIDEC CORPORATION |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed Chinese refiners in Inner Mongolia and Jiangxi provinces anchor upstream magnet feedstock pricing, compressing margin flexibility for motor assemblers while concentrating bargaining power among state-controlled entities that dictate rare-earth oxide contract terms.
Pricing Analysis
Short-lead-time premiums for laminated stator cores and magnet assemblies now command 15-25% markups over standard 14-18 month procurement cycles, while spot inventory of neodymium-dysprosium alloys trades at discounts reflecting quality uncertainty. Contract-based long-term offtake dominates automotive traction procurement, with price differentiation driven by GB/IE4 certification tier and captive magnet supply. Cost compression in standard-efficiency industrial motors is intensifying because ferrite magnet alternatives erode neodymium-grade margins. HVAC retrofit buyers in Germany exhibit highest price sensitivity; precision servo purchasers in Japan show least.
Supply Chain Analysis
Single-source vulnerability sits with Chinese state-owned rare-earth separation capacity, which supplies over 85% of global dysprosium feedstock for high-temperature traction-grade magnets. Manufacturing concentrates in China, Japan, and Germany, with raw material dependencies on neodymium oxide, dysprosium-terbium heavy rare earths, and high-grade electrical steel. Tariff exposure on magnet imports into the EU and US threatens assembler economics. Distribution runs through Tier-1 automotive suppliers and industrial equipment OEMs with direct magnet-to-motor integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation and REACH authorization requirements have erected compliance moats that favor established producers with in-house testing infrastructure and documented material traceability systems.
For Market Incumbents: Acquire magnet recycling and remanufacturing assets to secure secondary rare-earth feedstock at 60-70% of virgin extraction costs. Backward integration into grain boundary diffusion processing mitigates dysprosium concentration risk from Chinese export quota volatility. Capacity addition in South Korea and Germany aligns with 800-volt platform qualification timelines. For New Entrants and Emerging Players: Sensorless field-oriented control algorithms for brushless DC architectures offer technology-first wedge opportunities in agricultural drone propulsion systems. India's PLI scheme for advanced chemistry cell manufacturing creates localized demand for cleanroom-grade servo motors underserved by established Japanese suppliers. Partner with domestic battery gigafactory equipment integrators for precision winding system validation. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap motor assemblers in Italy and Poland facing REACH nickel compound compliance cost burdens. Long-term viability over the next decade hinges on magnet-to-motor remanufacturing capabilities and silicon carbide inverter pairing expertise. Watch grain boundary diffusion yield rates as inflection indicator for dysprosium-substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Magnet Recycling Infrastructure | Secondary rare-earth recovery at Jiangxi refiners reduces virgin material dependence for Japanese motor assemblers. |
| Grain Boundary Diffusion Scale-Up | Pilot adoption in Nagoya industrial clusters enables 30% lower dysprosium formulations for automotive traction. |
| Silicon Carbide Inverter Pairing | Wide-bandgap integration with high-pole-count designs unlocks 99% efficiency thresholds in Frankfurt data centers. |
| Dual-Source Magnet Qualification | Split procurement between Chinese and Australian feedstock mitigates export quota volatility for German OEMs. |
| Modular Stator Segment Design | Field-rewindable architectures align with Nordic total-cost-of-ownership contracting for municipal bus fleets. |
Study Parameters
Multi-period observation of rare-earth oxide spot pricing, laminated core lead times, and efficiency certification adoption rates anchored the trend analysis, supplemented by interviews with motor procurement directors at automotive OEMs, plant engineers at steel and cement facilities, HVAC retrofit contractors in Germany, and rare-earth trading desk analysts. Secondary validation drew from MIIT GB standard filings, EPA NEMA Premium enforcement records, EU F-Gas Regulation implementation timelines, and customs trade data for magnet feedstock flows. Bottom-up motor shipment tallies by application and region triangulated against top-down rare-earth consumption estimates.
Segment-weighting across motor type, end user, application, and technology dimensions structured the analytical framework over the projection horizon. CAGRs were derived from installed base replacement cycle modeling, EV platform rollout schedules, and regulatory mandate compliance deadlines. Industry-specific forecast inputs included dysprosium price elasticity coefficients and silicon carbide inverter adoption curves in data center cooling.
Several conditions sit outside the modeled scope, including geopolitical export quota disruptions, breakthrough induction motor efficiency improvements, and alternative magnet-free topologies reaching commercial scale. Forecasts reflect documented assumptions about rare-earth supply continuity and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
United Kingdom AC Motors Market
Industrial Motors
Industrial Motor Brakes Market
Industrial Motors
Global Switched Reluctance Motor Market
Industrial Motors
Hydraulic Motors Market
Industrial Motors
United States DC Motor Market
Industrial Motors
Asia Pacific Safety Drives and Motors Market
Industrial Motors
Global Refrigeration Oil Market
Industrial Motors
AC Motor Market
Industrial Motors
Oil Mist Collector Market
Industrial Motors
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market
Industrial Motors
Gear Reduction Motors Market
Industrial Motors
Germany AC Motor Market
Industrial Motors
Industrial Personnel and Burden Carriers [Electric] Market
Industrial Motors
Global Explosion-Proof Motor Casting Market
Industrial Motors
Explosion Proof Motor Market
Industrial Motors
Global Sliding Vane Air Motor Market