
 Global Duct Heaters Market | 2026-2036
Global Duct Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Duct Heaters Market Analysis
The direct-to-contractor channel is narrowing as HVAC OEMs consolidate procurement around fewer approved vendors. Watlow leverages its thermal engineering depth to anchor specification-driven sales in semiconductor cleanrooms and pharmaceutical processing. Chromalox competes through vertical control over heating element alloys, sustaining margin pools that independent distributors cannot match. Greenheck extends its air handling dominance into packaged heating modules, occupying a defensible position in commercial rooftop systems.
Duct heaters are forced-air heating devices installed within ventilation systems, typically incorporating open-coil, tubular, or finned heating elements rated from one kilowatt to several megawatts to raise supply air temperature before distribution. Electric duct heaters dominate specification sheets for zero-emission buildings, while gas duct heaters retain installed base in legacy industrial facilities where combustion infrastructure already exists. Convection heating technology leads volume across commercial buildings due to its compatibility with standard air handling units, whereas infrared heating segments command premium positioning in spot-process industrial applications where radiant energy transfer outperforms convective methods.
The U.S. Department of Energy appliance standards and EPA emissions guidelines shape product efficiency minimums and fuel choices across American installations, while the EU F-Gas Regulation and Ecodesign Directive drive electrification preferences in European specifications. China's GB standards for building energy efficiency and MIIT industrial upgrade programs enforce parallel efficiency mandates in the largest Asian construction market. Stakeholders must monitor the divergence between regional electrification timelines and fossil fuel infrastructure lock-in when allocating R&D and manufacturing capacity across geographies.
Market Dynamics
Electrification mandates across major economies are compressing the installed base of gas-fired duct heaters faster than replacement cycles would naturally allow, forcing manufacturers to reconfigure product portfolios around zero-emission specifications.
Growth Catalysts
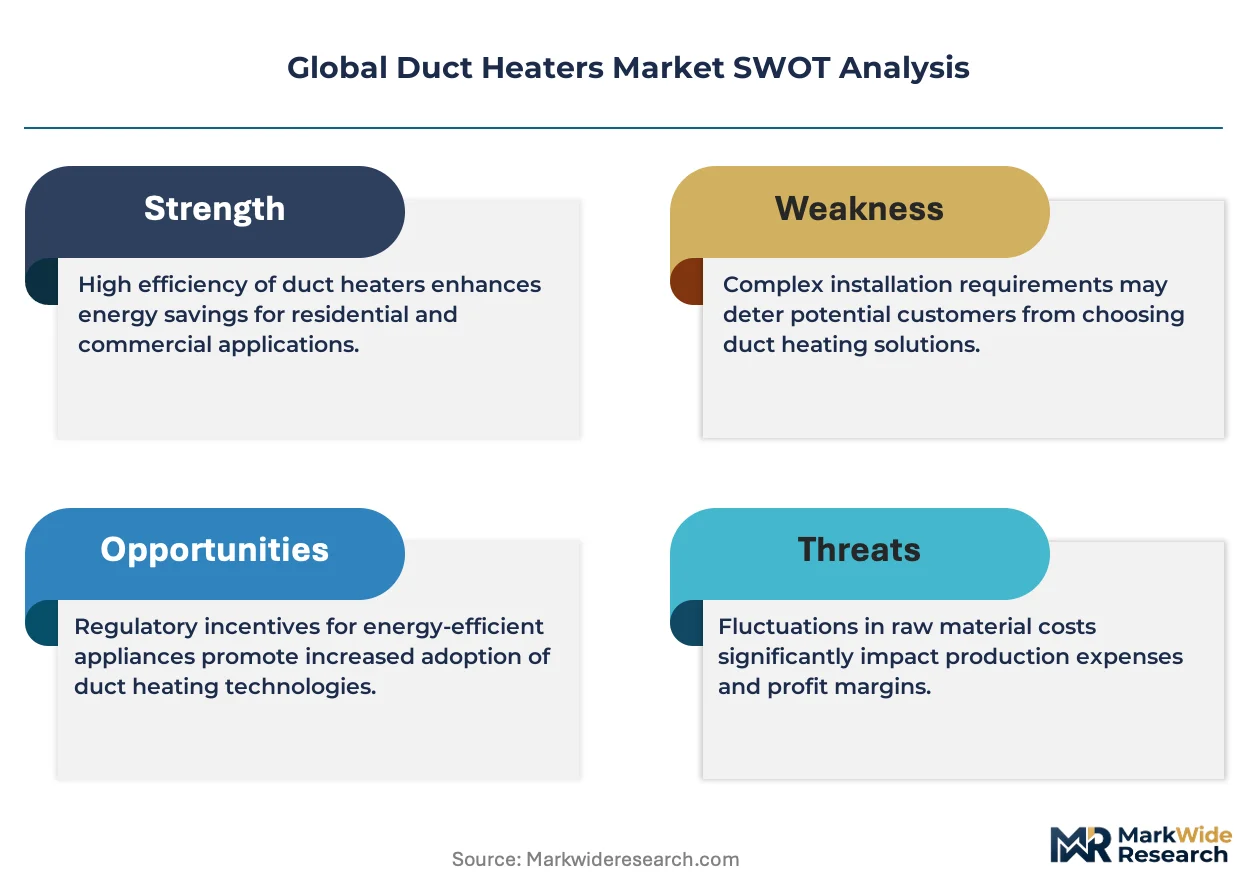
- EU Green Deal building renovation targets:Germany, France, and the Netherlands must retrofit millions of square meters of commercial stock by 2035, creating specification pull for electric duct heaters in HVAC upgrades.
- Semiconductor cleanroom expansion:Taiwan, South Korea, and Arizona fabs require precision temperature control that open-coil electric configurations deliver without combustion contaminants.
- Heat pump hybridization:Cold-climate heat pumps in Nordic countries and the northern United States rely on duct heaters as auxiliary boosters when ambient temperatures drop below heat pump efficiency thresholds.
Market Restraints
- Nickel-chromium alloy supply concentration:Heating element production depends on Russian and Indonesian nickel supply chains subject to export restrictions and ESG scrutiny.
- Gas infrastructure lock-in:Industrial facilities in the United States Gulf Coast and Rotterdam harbor retain sunk costs in combustion duct heaters that resist premature replacement despite electrification incentives.
- EU F-Gas Regulation compliance costs:Refrigerant phase-down rules increase total system costs for heat pump-duct heater combinations, slowing retrofit economics in commercial buildings.
Strategic Opportunities
- India building energy code enforcement:BIS standards for commercial HVAC efficiency create first-mover advantage for electric duct heater suppliers as Indian construction accelerates.
- Data center liquid-to-air cooling integration:Hyperscale facilities in Singapore, Ireland, and Virginia require duct heaters for humidity control in indirect evaporative cooling architectures.
- US Inflation Reduction Act 48C credits:Clean energy manufacturing tax credits subsidize domestic production of high-efficiency heating elements for export-competitive positioning.
Industry Challenges
- UL 1995 and IEC 60335-2-30 certification timelines:Safety testing for new element geometries stretches 14-18 months, delaying product launches behind competitor windows.
- Legacy BMS integration complexity:Building automation protocols from the 1990s lack native Modbus or BACnet compatibility with smart heater controls, requiring costly middleware development.
- Scarce thermal engineering talent:Universities in Germany, Japan, and the United States graduate fewer specialists in resistive heating design than industry retirement rates demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Duct Heaters Market |
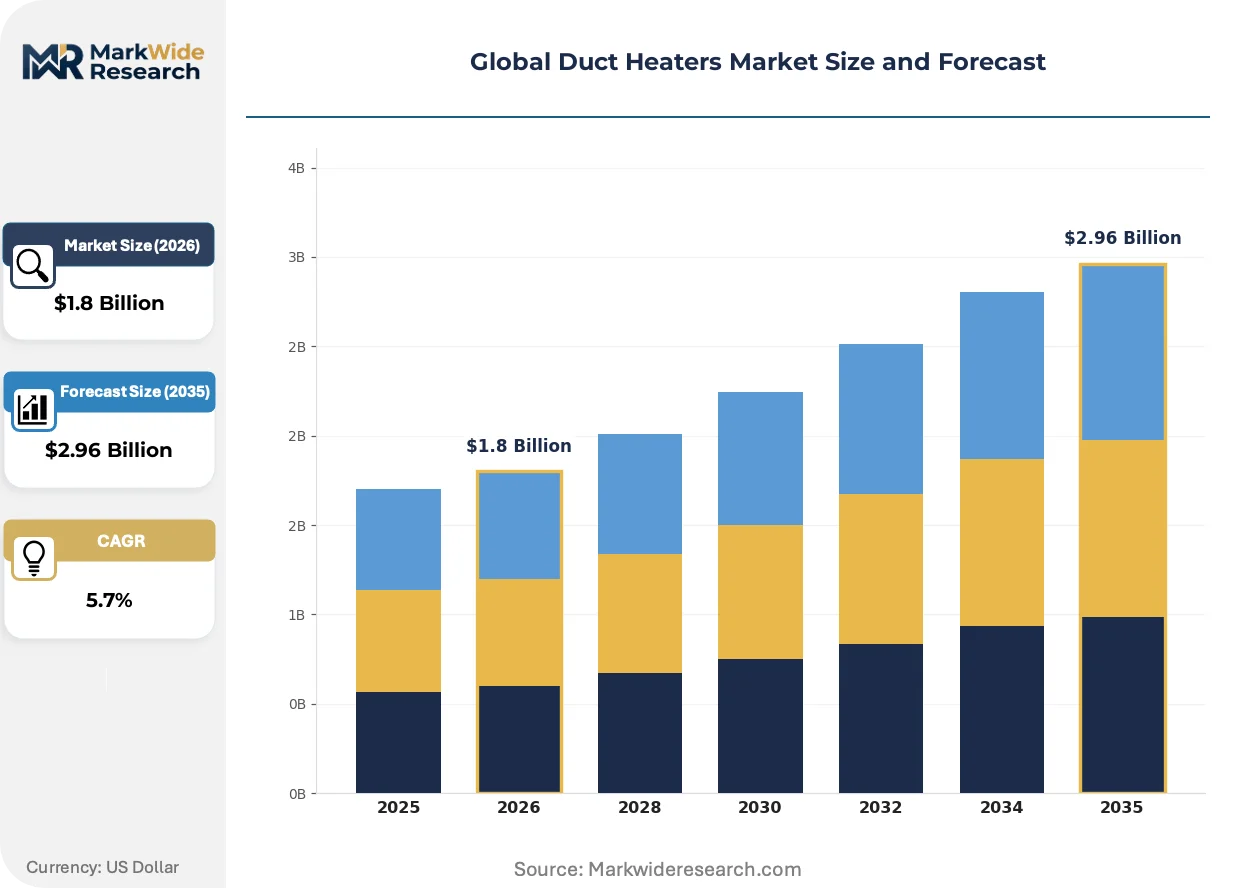
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Duct Heaters, Gas Duct Heaters, Oil Duct Heaters, Hydronic Duct Heaters Technology: Infrared Heating, Convection Heating, Steam Heating, Air Heating End User: Residential, Commercial Buildings, Industrial Facilities, HVAC Contractors Installation: New Construction, Retrofit, Replacement, Modular Systems |
| Companies Covered | Chromalox, Tutco Heating Solutions, Watlow, Accutherm, Backer Hotwatt, Indeeco, Systemair, Greenheck, VEAB Heat Tech AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Duct Heaters Market Emerging Trajectories
Solid-state power control and predictive thermal management are compressing energy waste margins and enabling specification in premium building segments that previously accepted mechanical control trade-offs.
Silicon carbide (SiC) power electronics are replacing traditional thyristor controllers in duct heater applications above 50kW. Pharmaceutical manufacturers in Switzerland and Denmark specify SiC-based units for their sub-second response times and harmonic distortion reduction. The technology is rendering obsolete electromechanical contactor banks that required maintenance every 10,000 cycles.
China's GB 21455-2019 minimum efficiency standards for room air conditioners now extend to ducted systems, compelling domestic manufacturers to redesign heating element geometries. MIIT enforcement inspections in Shanghai and Shenzhen factories have accelerated since 2023. Exporters to China must recertify products under revised test protocols that measure part-load efficiency more stringently than full-load ratings.
Engineering-procurement-construction firms are consolidating vendor lists to three approved duct heater suppliers per region, reversing the previous open-bid model. This concentration privileges OEMs with in-house thermal testing laboratories. The shift is most visible in German and Dutch commercial construction, where general contractors now delegate heater specification to MEP designers rather than leaving selection to mechanical subcontractors.
Global Duct Heaters Market Segmentation
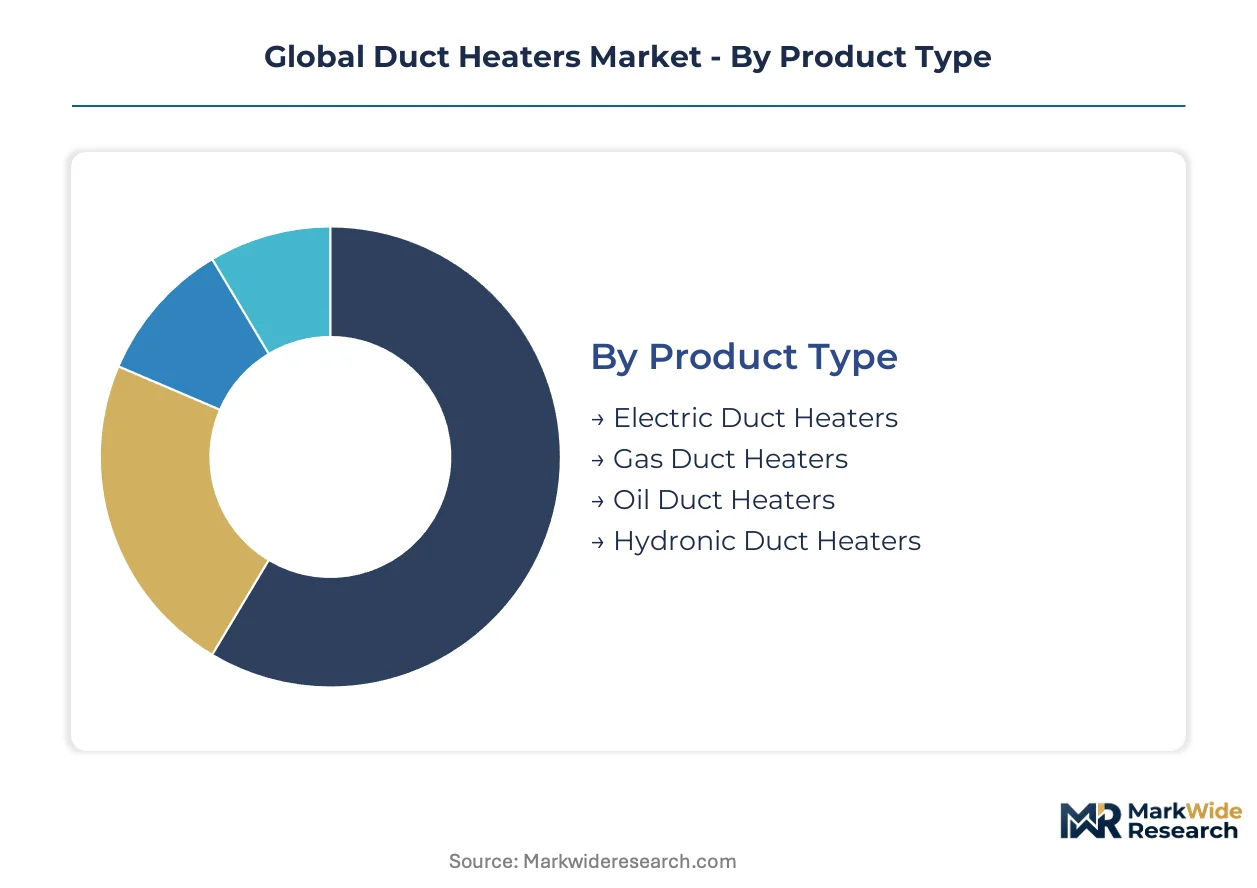
Duct heater procurement patterns diverge sharply across heating media, thermal transfer mechanisms, and project delivery models. Specification engineers weight energy source availability, load profile predictability, and integration complexity differently depending on building type and climate zone.
Product Type:
Equipment selection tracks the electrification timeline of each national building stock, with fuel infrastructure legacy determining replacement economics.
- Electric Duct Heaters:Open-coil and finned tubular configurations rated from 1kW to multi-megawatt outputs dominate zero-emission building specifications. Germany's federal building efficiency standards and California's Title 24 mandates are accelerating displacement of combustion alternatives in commercial retrofits.
- Gas Duct Heaters:Direct-fired and indirect-fired units retain installed base in U.S. Gulf Coast industrial corridors and Rotterdam harbor facilities where pipeline infrastructure represents sunk costs. Operators resist electrification where spark ignition systems would require complete control architecture replacement.
- Oil Duct Heaters:Bunker fuel and diesel configurations persist in remote Arctic installations and maritime heating applications beyond grid reach.
- Hydronic Duct Heaters:Hot water coil units integrate with district heating networks in Copenhagen, Helsinki, and Vienna urban cores.
The dominant share belongs to Electric Duct Heaters, while Gas Duct Heaters retain defensive positions in industrial clusters with legacy fuel infrastructure.
Technology:
Heat transfer physics dictates equipment placement and control precision requirements across building automation hierarchies.
- Convection Heating:Forced-air configurations compatible with standard air handling units lead volume across office towers, hospitals, and educational facilities. The technology's tolerance for variable airflow rates suits VAV-equipped commercial buildings in Chicago, Toronto, and Melbourne.
- Infrared Heating:Radiant energy transfer commands premium positioning in spot-process industrial applications where zonal control outperforms bulk air temperature management. Swiss pharmaceutical manufacturers and Danish food processors specify quartz tube and ceramic element configurations for their instantaneous response characteristics.
- Steam Heating:Jacketed coil designs serve legacy district steam systems in New York City, London, and St. Petersburg where central plant infrastructure predates hot water conversion.
- Air Heating:Direct-fired make-up air units address high ventilation load applications in manufacturing facilities with substantial exhaust requirements.
Convection Heating holds the volume lead, though Infrared Heating is expanding most quickly in precision-controlled process environments.
End User:
Customer archetypes separate by specification authority, maintenance capability, and capital deployment flexibility.
- Commercial Buildings:Property developers and facility managers in Singapore, Sydney, and Dubai specify packaged heating modules for build-to-suit office and retail developments. Procurement concentrates around MEP consultants with approved vendor lists rather than open subcontractor bidding.
- Industrial Facilities:Semiconductor fabs in Taiwan, South Korea, and Arizona require precision temperature control that open-coil electric configurations deliver without combustion contaminants. Process engineers specify redundant heating stages with SIL-rated safety interlocks.
- Residential:Single-family and multifamily developers in Texas, Florida, and Arizona integrate duct heaters as auxiliary heat for heat pump systems in mild climate zones.
- HVAC Contractors:Independent mechanical installers in secondary U.S. markets and Indian tier-2 cities source standard electric units through distributor channels with limited engineering support.
Commercial Buildings command the largest specification volume, while Industrial Facilities are driving the steepest specification upgrades toward premium configurations.
Installation:
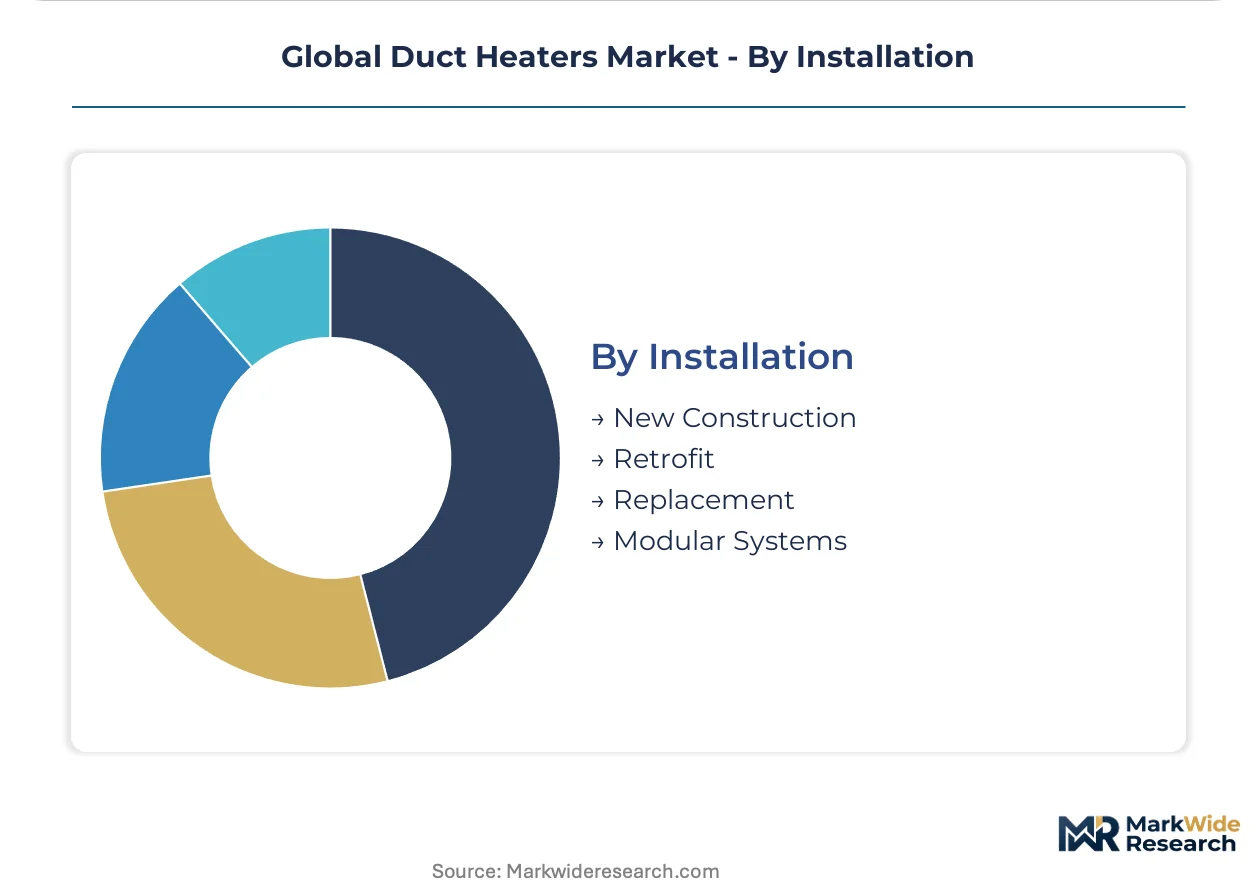
Project delivery mode determines lead time tolerance, engineering support requirements, and margin capture opportunities for equipment suppliers.
- Retrofit:Existing building HVAC upgrades across Germany, France, and the Netherlands must integrate with legacy ductwork and control protocols. Contractors face 1990s-era BMS integration complexity requiring middleware development for Modbus and BACnet compatibility.
- New Construction:Ground-up developments in Indian commercial corridors and Saudi giga-projects allow optimized heater sizing and placement without spatial constraints from existing infrastructure.
- Replacement:Like-for-like swaps in U.S. institutional buildings prioritize minimizing downtime over efficiency gains, preserving market share for incumbent suppliers with dimensional compatibility.
- Modular Systems:Prefabricated plant room and rooftop units from Greenheck and Temtrol compress field installation labor in labor-constrained markets.
Retrofit installations dominate current revenue, though Modular Systems are climbing the fastest as offsite construction methods penetrate commercial HVAC.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specification power concentrates in Germany where the EU Green Deal enforces the strictest retrofit mandates, while Gulf Coast industrial operators in the United States retain pricing leverage through gas infrastructure lock-in. This asymmetry shapes divergent product mix strategies across Atlantic markets.
United States
Data center construction in Northern Virginia and semiconductor fabs in Arizona drive precision electric duct heater demand. The Department of Energy appliance standards and EPA emissions guidelines enforce efficiency minimums that favor electrification in new builds. Gulf Coast petrochemical corridors around Houston resist replacement of combustion units despite available incentives.
Germany
Federal building efficiency standards mandate millions of square meters of commercial retrofit by 2035, pulling specification toward electric configurations. The EU Green Deal and F-Gas Regulation accelerate displacement of gas-fired systems in Hamburg and Frankfurt office towers. Engineering-procurement-construction firms in the Ruhr region consolidate vendor lists to three approved suppliers per project.
China
MIIT industrial upgrade programs and GB 21455-2019 efficiency standards compel domestic manufacturers to redesign heating element geometries. Enforcement inspections in Shanghai and Shenzhen factories intensified since 2023. Yangtze River Delta construction accelerates demand for packaged heating modules in commercial developments.
India
BIS standards for commercial HVAC efficiency create specification opportunities as Indian construction accelerates in Mumbai and Delhi-NCR. Tier-2 city mechanical contractors source standard electric units through distributor channels with limited engineering support. Enforcement gaps between metropolitan and secondary markets produce pricing fragmentation.
South Korea
Semiconductor cleanroom expansion in the Seoul Capital Area and Busan-Ulsan corridor requires open-coil electric configurations without combustion contaminants. MFDS pharmaceutical manufacturing standards and corporate net-zero commitments drive premium specification. Domestic HVAC OEMs consolidate procurement around fewer approved vendors.
Global Duct Heaters Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in heating element alloys and thermal engineering. The vendor base separates into three tiers: multinational HVAC OEMs with packaged air handling dominance, mid-cap thermal component manufacturers with captive alloy production, and regional fabricators serving price-sensitive replacement markets. Consolidation concentrates specification authority among engineering-procurement-construction firms with approved vendor lists. Dominant competitive moves include backward integration into heating element production and geographic expansion through distributor network capture.
Among North American thermal specialists, Chromalox, Watlow, and Tutco Heating Solutions exemplify divergent strategic archetypes. Chromalox represents the vertically integrated model with upstream control over heating element alloys. Watlow anchors the specification-driven segment through thermal engineering depth in precision applications. Tutco Heating Solutions occupies a position in standard electric configurations for commercial and industrial replacement markets. Greenheck extends air handling platform dominance into packaged heating modules, while Systemair leverages European HVAC distribution density for specification reach across German and Dutch commercial construction.
| Leading Market Players |
|---|
| Chromalox |
| Tutco Heating Solutions |
| Watlow |
| Accutherm |
| Backer Hotwatt |
| Indeeco |
| Systemair |
| Greenheck |
| VEAB Heat Tech AB |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European heating element foundries is compressing lead times and hardening supplier pricing power against OEM procurement teams. This utilization squeeze feeds directly into configured-to-order premiums for electric duct heaters specified under EU Green Deal retrofit mandates.
Pricing Analysis
Configured-to-order pricing commands spreads of 40-60% above standard catalog units for electric duct heaters with SIL-rated safety interlocks and SiC power controllers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because Chinese manufacturers with GB 21455-2019 compliance are exporting at volume scale. HVAC contractors in Indian tier-2 cities exhibit highest price sensitivity, while semiconductor fabs in Taiwan and Arizona show least sensitivity due to contamination-risk premiums.
Supply Chain Analysis
Upstream nickel-chromium alloy feedstock draws from Russian and Indonesian supply chains subject to export restrictions and ESG scrutiny. Heating element production concentrates in Germany, China, and the United States, with captive foundry capacity determining margin capture. Single-source vulnerability in nickel supply creates procurement risk for manufacturers lacking long-term offtake agreements. Distribution runs through engineering-procurement-construction firms consolidating vendor lists to three approved suppliers per region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among HVAC OEMs and EPC firms with approved vendor lists, fragmenting pricing leverage for independent distributors. This consolidation demands strategic repositioning across stakeholder archetypes.
For Market Incumbents: Entrench specification authority through captive thermal testing laboratories and backward integration into heating element alloys. Chromalox and Watlow models demonstrate how upstream control over nickel-chromium production sustains margin pools that distributor-dependent competitors cannot match. Anchor long-term service contracts with semiconductor fabs and pharmaceutical processors to resist displacement by modular system integrators. For New Entrants and Emerging Players: Build out distributor networks in Indian tier-2 cities and secondary U.S. markets where specification authority remains fragmented among independent mechanical contractors. White-space concentrates in heat pump auxiliary heater configurations for Nordic cold-climate deployments. Pursue BIS certification early to capture first-mover advantage as Indian building energy code enforcement tightens. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across SiC power electronics integration and in-house thermal testing infrastructure. Mid-cap thermal component manufacturers with captive alloy production and cleanroom-certified facilities represent optimal acquisition targets. Monitor nickel export license restrictions as the primary inflection signal for heating element cost structure disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Element Alloys | Captive nickel-chromium production insulates margins from Russian and Indonesian supply volatility. |
| SiC Power Controller Adoption | Sub-second response times unlock pharmaceutical and semiconductor specification premiums in Switzerland and Denmark. |
| UL 1995 and IEC 60335-2-30 Certification Investment | Accelerated safety testing timelines compress competitor windows for new product launches. |
| Modular System Partnership | Integration with Greenheck and Temtrol rooftop units captures labor-constrained commercial construction demand. |
| India Distribution Network Capture | BIS compliance positioning ahead of building energy code enforcement creates tier-2 city penetration advantage. |
Methodological Framework
Desk research of SEC 10-K filings, EU Ecodesign Directive implementation reports, and MIIT enforcement bulletins preceded structured interviews with HVAC OEM procurement directors, semiconductor fab facilities engineers, and EPC firm MEP designers. Primary fieldwork with thermal component manufacturers and distributor channel managers cross-validated secondary trade flow data and customs records. Bottom-up unit economics triangulated against top-down construction spending forecasts across the analysis window.
Assumptions held electrification mandate timelines and nickel supply chain restrictions fixed, while heat pump adoption rates and semiconductor fab buildout schedules varied across sensitivity scenarios. Segmentation modeling incorporated heating media, thermal transfer technology, end-user archetype, and installation mode dimensions. CAGRs derived from regression analysis of historical retrofit cycles against regulatory enforcement intensity, with semiconductor cleanroom expansion and data center construction as industry-specific demand inputs.
Sensitivities concentrate around nickel export license volatility, EU F-Gas Regulation compliance cost revisions, and Chinese GB standard enforcement intensity. Forecasts reflect documented assumptions regarding regional electrification timeline divergence. Cross-checking against IEA building energy efficiency investment benchmarks and national construction permit databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Global Low Voltage Electric Drives Market
Electrical Power Equipment
Composite Insulators Market
Electrical Power Equipment
Offshore Cables Market
Electrical Power Equipment
Immersion Heater Market
Electrical Power Equipment
Load Bank Market
Electrical Power Equipment
Containerized Substation Market
Electrical Power Equipment
Power Strip Market
Electrical Power Equipment
Overhead Power Cables Market
Electrical Power Equipment
South America Air Insulated Switchgear Market
Electrical Power Equipment
Motor Generator Set Market
Electrical Power Equipment
Industrial Power Supply Market
Electrical Power Equipment
3rd Rail Current Collector Market
Electrical Power Equipment
Solar Combiner Boxes Market
Electrical Power Equipment
Instrument Transformers Market
Electrical Power Equipment
Domestic Hot Water (DHW) Tanks Market
Electrical Power Equipment
Train Contactor Market