
 Global Explosion-Proof Electric Motors and Actuators Market | 2026-2036
Global Explosion-Proof Electric Motors and Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Explosion-Proof Electric Motors and Actuators Market Analysis
China is rewriting capacity assumptions for explosion-proof motor supply as domestic manufacturers scale IECEx-certified production lines. ABB leverages its European testing heritage to sustain premium positioning in hazardous-duty specifications. Siemens anchors automation-integrated actuator bundles for chemical complexes. WEG competes aggressively on induction motor cost structures across Latin American mining operations.
Explosion-proof electric motors and actuators are electromechanical devices engineered with encapsulated windings, flameproof enclosures rated to IP55 or higher, and surface temperature limitations that prevent ignition of surrounding explosive atmospheres; they convert electrical energy into mechanical motion while containing internal faults in oil refineries, chemical plants, and underground extraction sites. Brushless technology dominates where maintenance access is restricted, while induction systems occupy the volume tier in standard-duty petrochemical applications. Oil and gas procurement channels represent the deepest margin pools due to specification stringency and replacement cycles.
IECEx, ATEX directives, and OSHA standards collectively shape product design mandates, testing protocols, and site certification requirements that manufacturers must satisfy before market entry. The EPA and NHTSA influence adjacent environmental and equipment transport rules that ripple into motor packaging and logistics. Stakeholders must monitor how evolving zone classification standards in hazardous locations will reshape R&D allocation and certification timelines.
Market Dynamics
Zone classification harmonization between IECEx and ATEX frameworks is compressing certification timelines while elevating design stringency, forcing manufacturers to consolidate testing protocols across multiple jurisdictions.
Growth Catalysts
- Underground extraction depth:Mining operators in Chile and South Africa are procuring flameproof motors rated for deeper shaft operations where ventilation constraints intensify ignition risk.
- EPA methane rules:US oilfield operators face equipment replacement mandates that favor sealed actuator systems over legacy pneumatic alternatives in wellhead automation.
- Brushless DC penetration:Maintenance-restricted offshore platforms specify permanent magnet motors to eliminate sparking from commutator wear in Zone 1 environments.
Market Restraints
- Copper and rare earth volatility:Permanent magnet supply chains concentrate in Chinese processing facilities, exposing motor manufacturers to input cost swings and export restriction risk.
- IECEx testing backlog:Certification queue lengths at Australian and UK notified bodies extend product launch timelines by eight to fourteen months for new entrants.
- Pneumatic actuator residual:Compressed air infrastructure in legacy Gulf Coast petrochemical plants creates switching friction against electric actuation despite efficiency advantages.
Strategic Opportunities
- India petrochemical buildout:Reliance Industries and Indian Oil are expanding Jamnagar and Paradip complexes with specifications favoring ATEX-certified integrated motor-actuator bundles.
- EU Green Deal alignment:The F-Gas Regulation phase-down creates replacement demand for electric actuators in refrigeration and chemical process cooling systems.
- Digital twin convergence:Vibration monitoring systems married to explosion-proof housings enable predictive maintenance contracts in German chemical clusters.
Industry Challenges
- IECEx-ATEX divergence:Technical interpretation gaps between Brazilian and European notified bodies force redundant testing for multi-jurisdiction product launches.
- Legacy system integration:4-20mA analog control architectures in 1990s-era US refineries resist retrofit with digital actuator communication protocols.
- Specialized winding expertise:Vacuum pressure impregnation technicians for encapsulated hazardous-duty motors remain concentrated in aging European and Japanese workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Explosion-Proof Electric Motors and Actuators Market |
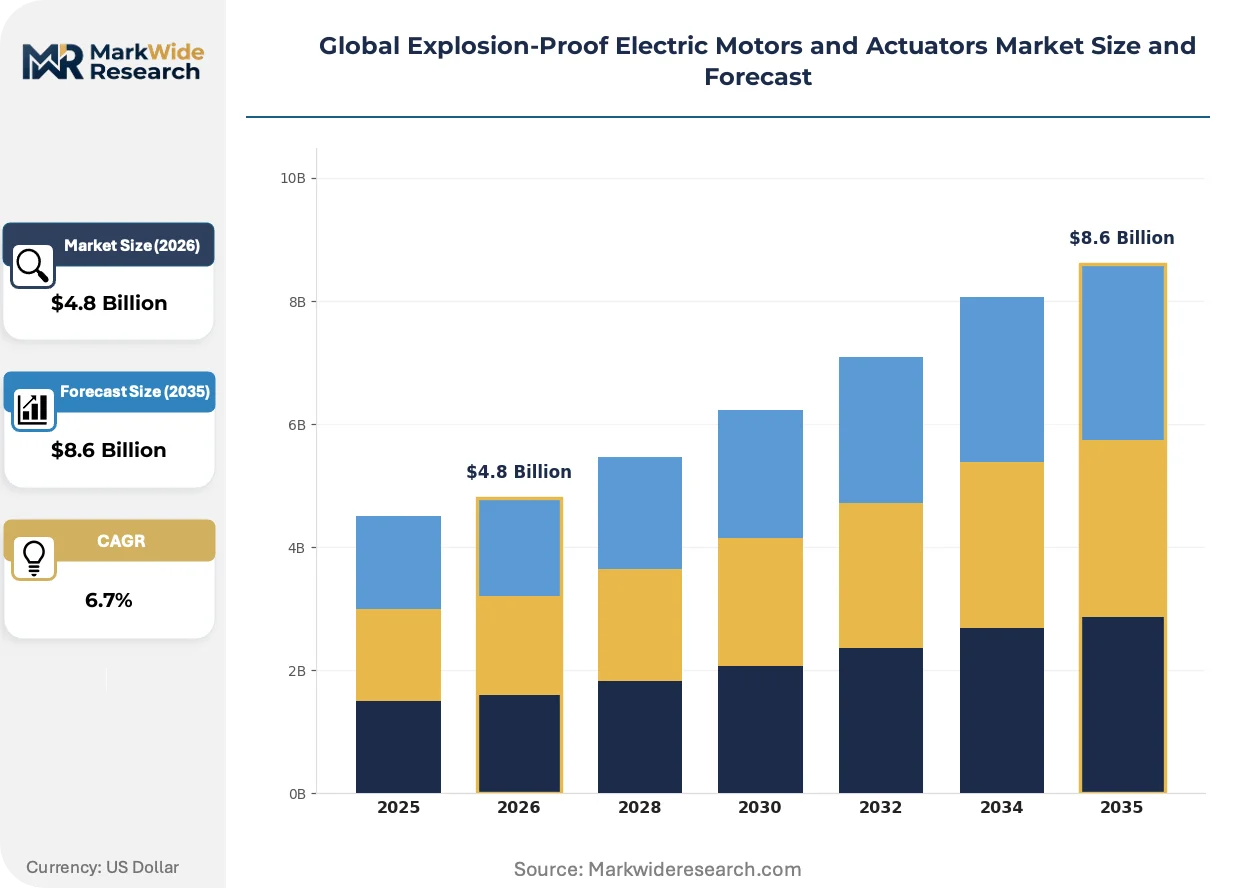
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Actuators, Gear Motors Technology: Brushless, Induction, Synchronous, Linear Application: Oil & Gas, Chemical, Mining, Aerospace End User: Industrial, Manufacturing, Marine, Power Generation |
| Companies Covered | Emerson Electric, Nidec Corporation, ABB, Eaton Corporation, WEG, Siemens, Rockwell Automation, Rotork, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Explosion-Proof Electric Motors and Actuators Market Emerging Trajectories
Digitalization of motor monitoring and control architectures is collapsing the boundary between electromechanical hardware and software-defined automation, reshaping how operators specify and maintain hazardous-duty equipment.
Edge computing modules embedded within explosion-proof enclosures is virtualizing traditional maintenance schedules by enabling real-time thermal and vibration analysis without breaching flameproof boundaries. Offshore platform operators in the North Sea and Gulf of Mexico are specifying these integrated systems for subsea pump and compressor applications. The technology is virtualizing the role of scheduled inspection intervals, compressing total cost of ownership calculations toward energy efficiency and predictive uptime metrics.
REACH substance restrictions on per- and polyfluoroalkyl substances are forcing reformulation of winding insulation varnishes and bearing greases used in hazardous-duty motors. European motor manufacturers are accelerating qualification of bio-based and ceramic-filled alternatives ahead of 2025 sunset dates. The chemical processing sector faces the steepest compliance curve, with German and Dutch operators demanding full material disclosure through supply chains.
Integrated procurement of motor-actuator-control triads is displacing component-level purchasing in large-scale chemical complex expansions. Engineering contractors in China and the Middle East are bundling specification responsibility with single-source accountability, compressing vendor lists. Saudi Aramco's Jafurah unconventional gas development exemplifies this pattern, with lump-sum turnkey contracts transferring integration risk to automation suppliers.
Global Explosion-Proof Electric Motors and Actuators Market Segmentation
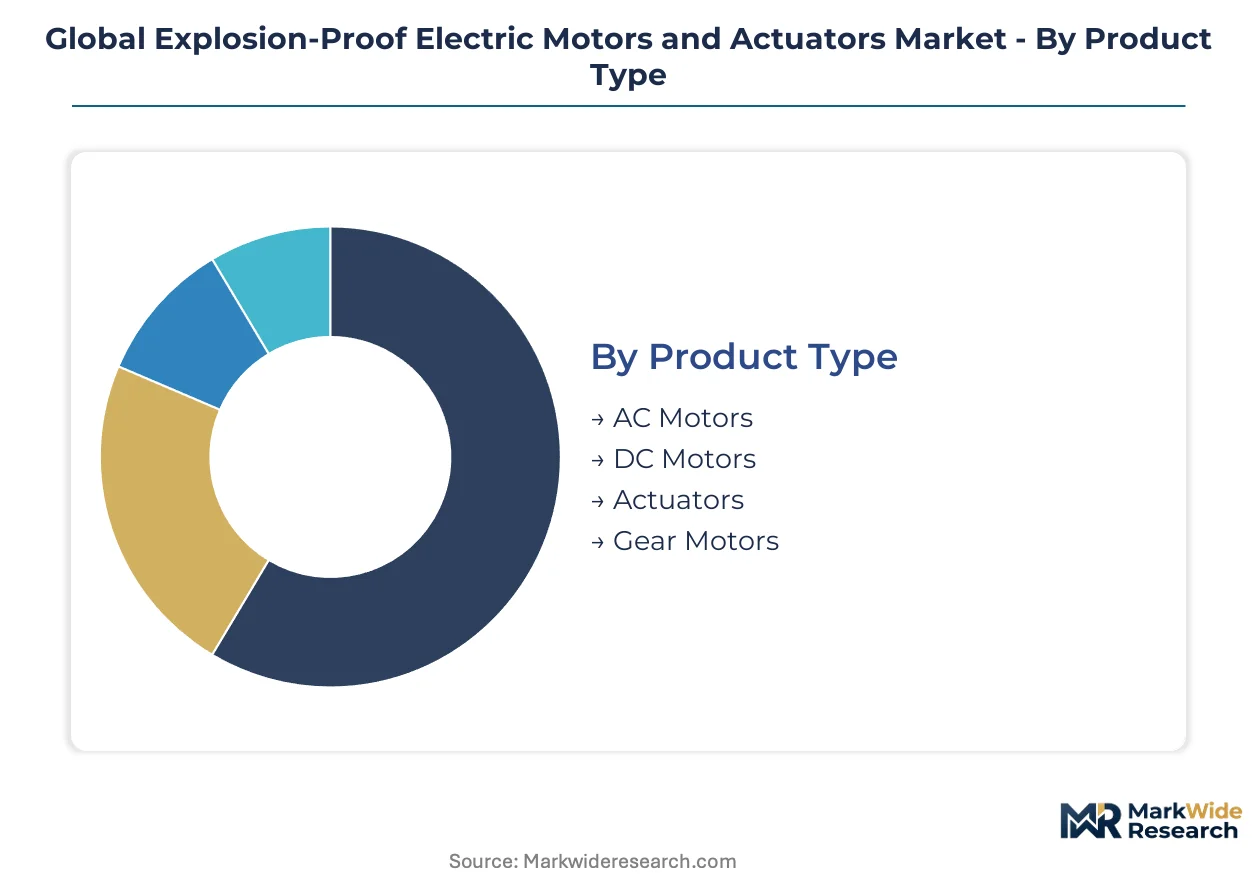
Explosion-proof equipment procurement follows distinct technical and commercial logics across product categories. Segment boundaries determine certification requirements, replacement cycles, and margin structures for manufacturers serving hazardous-duty environments.
Product Type:
Replacement cycles vary sharply across motor architectures, with actuator systems turning over fastest due to control obsolescence while AC induction platforms persist for decades in refinery service.
- AC Motors:Squirrel-cage and wound-rotor designs dominate volume procurement for petrochemical pump and compressor duty. German chemical clusters specify these for continuous-process applications where IECEx-certified enclosures must survive 20-year operational horizons without major overhaul.
- DC Motors:Wound-field and permanent magnet configurations persist in mining haulage and drilling rigs where torque control precision outweighs efficiency penalties. Chilean copper operators maintain fleets of flameproof DC traction motors despite brush maintenance burdens.
- Actuators:Quarter-turn and multi-turn electric valve actuators command premium pricing in wellhead automation. US Gulf Coast operators face EPA methane regulations that accelerate replacement of pneumatic legacy systems.
- Gear Motors:Integrated gearbox-motor combinations reduce footprint in confined processing skids. Chinese refinery expansions specify these for conveyor and agitator drives where space constraints intersect with Zone 1 classification requirements.
AC motors anchor the volume base while actuators gain share at the steepest rate.
Technology:
Cost tiers separate maintenance-intensive legacy platforms from premium sealed architectures that eliminate sparking risk through electronic commutation.
- Brushless:Permanent magnet synchronous motors with electronic commutation eliminate brush sparking and wear particles. Offshore platforms in the North Sea specify these for subsea applications where maintenance access is essentially impossible.
- Induction:Robust cage-rotor designs tolerate contaminated atmospheres and voltage fluctuations. Brazilian mining operations favor these for their tolerance of harsh electrical supply conditions in remote extraction sites.
- Synchronous:Precise speed-holding characteristics suit extruder and mixer drives in polymer production. Reliance Industries specifications for Indian petrochemical expansions emphasize synchronous torque stability.
- Linear:Direct-drive electromagnetic actuation eliminates mechanical transmission losses. Aerospace test facilities and specialized chemical processing applications specify these for precision positioning in explosive atmospheres.
Induction technology captures the broadest installed base while brushless architectures command the fastest expansion trajectory.
Application:
Application concentration determines specification stringency, with oil and gas procurement setting the ceiling for certification requirements that cascade into adjacent sectors.
- Oil & Gas:Drilling, production, and refining operations demand the most rigorous flameproof and increased safety certifications. Saudi Aramco's Jafurah development exemplifies integrated motor-actuator procurement at scale.
- Chemical:Process reactors, distillation columns, and material handling require corrosion-resistant enclosures and surface temperature limits. Dutch and German operators lead demand for REACH-compliant insulation systems.
- Mining:Underground coal and hard-rock extraction specify flameproof (Ex d) enclosures rated for methane and coal dust atmospheres. South African deep-shaft operations drive demand for enhanced cooling designs.
- Aerospace:Fuel handling, paint booths, and propulsion test facilities require specialized certifications beyond standard IECEx/ATEX scopes. Military and civilian airfield applications maintain distinct qualification protocols.
Oil and gas anchors the revenue base while chemical processing applications expand most quickly.
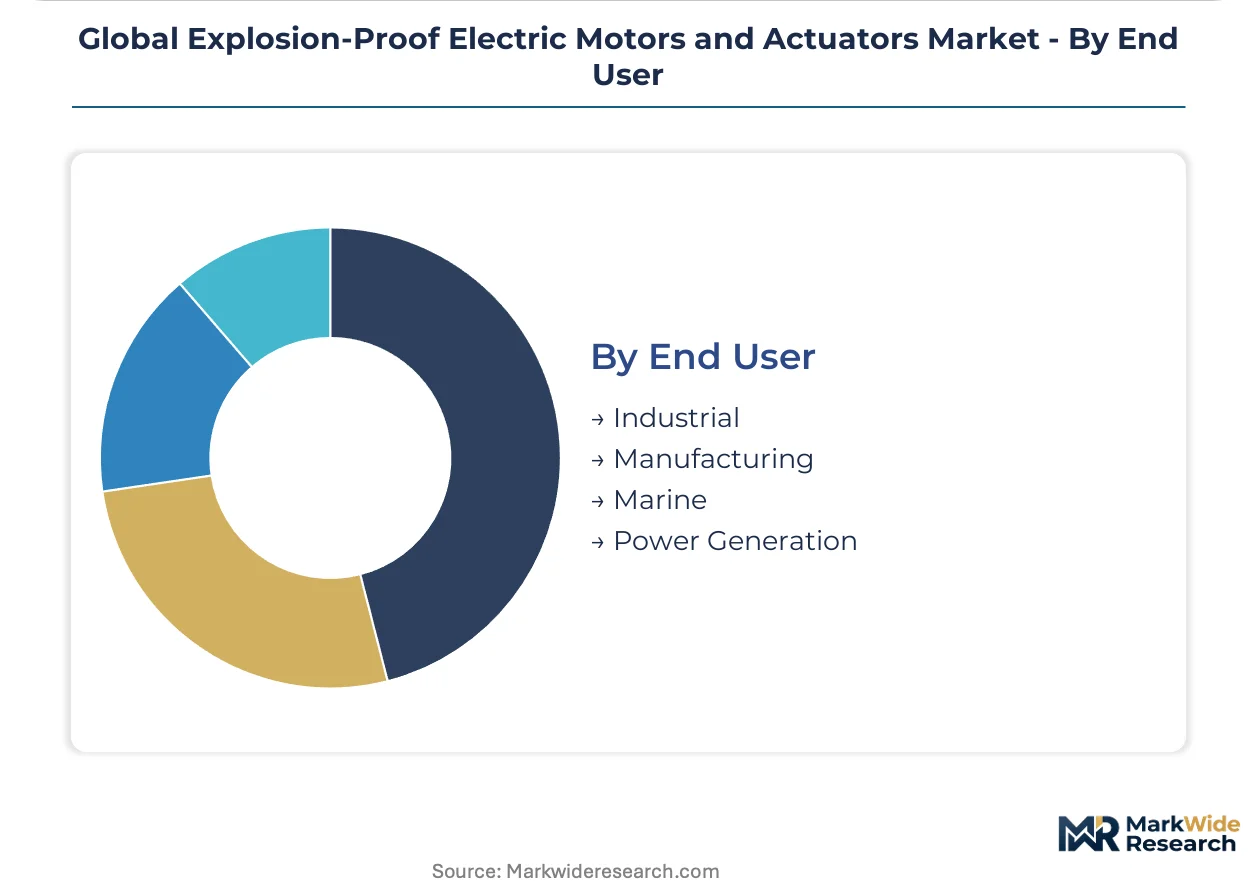
End User:
Customer type shapes procurement channel structure, with industrial operators favoring direct manufacturer relationships while marine buyers route through specialized distributors.
- Industrial:Petrochemical, pharmaceutical, and food processing plants specify integrated automation packages. Siemens and ABB compete for bundled motor-actuator-control contracts in German chemical clusters.
- Manufacturing:Paint shops, solvent handling, and powder processing operations require Zone 2 and Zone 22 equipment. Automotive OEMs in the United States specify these for coating line modernization.
- Marine:Tanker cargo pumps, ballast systems, and engine room ventilation demand salt-resistant flameproof enclosures. Classification society rules from Lloyd's Register and DNV shape certification requirements.
- Power Generation:Coal handling, fuel oil systems, and hydrogen co-firing retrofits require hazardous-area equipment. Utilities in China and India specify these for emissions-compliant plant upgrades.
Industrial end users dominate contract value while marine applications show the steepest specification tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jafurah unconventional gas development anchors Saudi Arabia's position as the Middle East's dominant demand center for integrated motor-actuator systems. Pipeline interconnections across the North Sea basin sustain Norwegian and UK offshore platform procurement cycles.
United States
Gulf Coast petrochemical expansions near Houston and Corpus Christi drive flameproof motor procurement for ethylene crackers and LNG export terminals. EPA methane regulations under the Clean Air Act accelerate electric actuator replacement of pneumatic wellhead systems. The Permian Basin's Delaware sub-basin concentrates drilling automation demand where Zone 1 classifications predominate.
Germany
Ludwigshafen and Leverkusen chemical clusters specify ATEX-certified integrated bundles for continuous-process reliability exceeding twenty-year horizons. REACH substance restrictions on PFAS force winding insulation reformulation ahead of 2025 compliance deadlines. Bavarian automation suppliers anchor predictive maintenance contracts linking vibration sensors to explosion-proof housings.
China
Jamnagar-equivalent refinery expansions at Zhejiang Petrochemical and Hengli Group drive IECEx-certified motor procurement at unprecedented scale. MIIT dual carbon goals tighten efficiency standards for hazardous-duty equipment in coal chemical processing. Yangtze River Delta manufacturers scale certified production lines for export to Belt and Road mining projects.
India
Reliance Industries' Jamnagar complex and Indian Oil's Paradip refinery anchor petrochemical motor-actuator demand on the subcontinent. BIS adoption of IECEx standards compresses certification timelines for domestic manufacturers. Gujarat's Dahej PCPIR zone concentrates procurement for specialty chemical expansions requiring Zone 1 flameproof enclosures.
Brazil
Pre-salt offshore platforms in the Santos Basin specify brushless permanent magnet motors for subsea applications where maintenance access is restricted. ANVISA alignment with ATEX technical interpretations creates redundant testing burdens for multi-jurisdiction product launches. Minas Gerais iron ore operations sustain demand for flameproof DC traction motors in deep-pit haulage.
Global Explosion-Proof Electric Motors and Actuators Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply architecture. The vendor base organizes around three strategic archetypes: diversified electrical conglomerates bundling motor-actuator-control triads, mid-scale regional champions competing on induction motor cost structures, and niche automation houses specializing in valve actuation for wellhead applications. Consolidation pressure intensifies as engineering contractors in China and the Middle East compress vendor lists through lump-sum turnkey contracting. Geographic expansion and backward integration into permanent magnet supply chains represent the dominant competitive vectors.
Among diversified electrical conglomerates, ABB and Siemens exemplify platform-scale positioning through European testing heritage and automation-integrated bundles respectively. WEG occupies a distinct archetype as a regional champion competing aggressively on cost structures across Latin American mining operations. These three anchors illustrate how certification depth, geographic footprint, and vertical scope separate premium-tier system integrators from component-focused competitors.
| Leading Market Players |
|---|
| Emerson Electric |
| Nidec Corporation |
| ABB |
| Eaton Corporation |
| WEG |
| Siemens |
| Rockwell Automation |
| Rotork |
| Schneider Electric |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta manufacturing clusters in Jiangsu and Zhejiang provinces control the bulk of IECEx-certified explosion-proof motor production capacity, translating directly into pricing leverage for domestic exporters serving Belt and Road mining projects. This geographic concentration compresses margins for European manufacturers while enabling Chinese suppliers to undercut on induction motor bids by fifteen to twenty percent in Latin American tenders.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with IECEx-ATEX dual certification commanding the top tier and single-certification domestic products occupying the volume middle. Price differentiation rests on certification depth and after-sales service bundling rather than raw performance specifications. Pricing pressure stems from rare earth magnet cost volatility and copper futures swings that force quarterly contract renegotiations. State-owned oil companies in China and India exhibit the highest price sensitivity due to lump-sum turnkey contracting, while North Sea offshore operators prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Export control regimes on permanent magnet rare earth processing limit supply chain flexibility, with Chinese SAMR licensing requirements constraining neodymium-dysprosium alloy flows to motor manufacturers outside the PRC. Manufacturing concentrates in China, Germany, and Brazil, with winding insulation varnish production anchored in aging European facilities. Raw material dependencies center on copper rod, silicon steel laminations, and ceramic-filled bearing greases. Single-source vulnerability concentrates in vacuum pressure impregnation equipment for encapsulated hazardous-duty windings. Distribution runs through engineering-procurement-construction contractors rather than direct OEM relationships in Middle Eastern and Indian petrochemical buildouts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized winding expertise for hazardous-duty motor production is thinning across the industry as European and Japanese technician cohorts age without replacement pipelines, creating structural bottlenecks that will constrain output expansion regardless of capital deployment.
For Market Incumbents: Entrench certification depth as the primary defensive moat by accelerating IECEx-ATEX dual qualification ahead of Brazilian ANVISA alignment deadlines. Prioritize backward integration into permanent magnet supply chains through offtake agreements with Chinese rare earth processors to offset commodity volatility. Lock in multi-year service contracts with German chemical clusters that bundle predictive maintenance sensors with motor replacements. For New Entrants and Emerging Players: India's Dahej PCPIR specialty chemical zone offers the most penetrable geographic entry point, with BIS adoption of IECEx standards compressing certification barriers for qualified foreign suppliers. Target valve actuator subsystems for wellhead automation where EPA methane rules are accelerating pneumatic-to-electric conversions. Pursue joint qualification partnerships with established European testing houses to bypass fourteen-month certification backlogs at Australian and UK notified bodies. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automation-integrated platform players over component specialists as engineering contractors consolidate vendor lists. Five-to-ten year viability hinges on digital twin convergence capabilities that marry explosion-proof hardware to predictive software contracts. Acquisition targets should demonstrate captive certification expertise and installed base density in German or North American chemical clusters. Monitor IECEx testing queue lengths at notified bodies as the lead indicator for certification capacity constraints that will determine which manufacturers can execute product launches.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Secures neodymium-dysprosium flows against SAMR export licensing volatility. |
| Digital Twin Platform Development | Enables predictive maintenance contracts with BASF and Dow chemical clusters. |
| Dual IECEx-ATEX Certification Acceleration | Preempts redundant testing burdens from Brazilian ANVISA alignment delays. |
| Joint Venture with Indian Domestic Manufacturer | Accesses BIS-fast-tracked certification for Reliance Industries procurement. |
| REACH-Compliant Insulation Reformulation | Qualifies bio-based varnishes ahead of ECHA PFAS sunset deadlines. |
Methodological Framework
A standing panel of plant engineers at petrochemical complexes, procurement leads at oilfield service companies, IECEx certification auditors, and aftermarket service directors provided ongoing calibration against secondary validation. Primary fieldwork combined structured interviews with maintenance directors and OEM procurement teams across German chemical clusters, Gulf Coast refineries, and Chinese coal chemical processing facilities. Secondary sources included customs trade data for explosion-proof equipment flows, SEC 10-K filings from listed electrical conglomerates, IECEx certificate database tracking, and ECHA substance restriction timelines. Bottom-up unit demand estimates triangulated against top-down energy infrastructure investment forecasts.
Scenario-bracketing framed volume projections across the analysis window, with segmentation dimensions spanning motor architecture, certification tier, zone classification requirement, and end-use application concentration. CAGRs derived from installed base replacement cycles, greenfield project pipelines, and regulatory mandate timing rather than extrapolated trend lines. Industry-specific inputs included EPA methane rule implementation schedules, MIIT dual carbon efficiency deadlines, and REACH substance restriction phase-down calendars.
Practitioners should monitor IECEx notified body queue lengths, rare earth export licensing announcements from SAMR, and EPA enforcement patterns for early signals of forecast deviation. Forecasts reflect assumptions about certification timeline stability, commodity price bands, and regulatory harmonization progress. Material shifts in ANVISA-ATEX technical interpretation divergence or sudden PFAS restriction acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Offshore Cables Market
Electrical Power Equipment
Solar Combiner Boxes Market
Electrical Power Equipment
Power Line Carrier System Market
Electrical Power Equipment
Latin America Hazardous Location Motor Starters Market
Electrical Power Equipment
Europe Brushless DC Motors Market
Electrical Power Equipment
Europe Gas Insulated Switchgear Market
Electrical Power Equipment
AC Drives Market
Electrical Power Equipment
Industrial Power Supply Market
Electrical Power Equipment
North America Alternating Current (AC) Drive Market
Electrical Power Equipment
Magneto Optic Current Transformer Market
Electrical Power Equipment
Immersion Heater Market
Electrical Power Equipment
Digital Fault Recorder (DFR) Market
Electrical Power Equipment
AC Residential Switchgear Market
Electrical Power Equipment
Alternating Current (AC) Electric Drives Market
Electrical Power Equipment
Global Electrical SCADA Market
Electrical Power Equipment
Instrument Transformers Market