
 Composite Insulators Market | 2026-2036
Composite Insulators Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Insulators Market Analysis
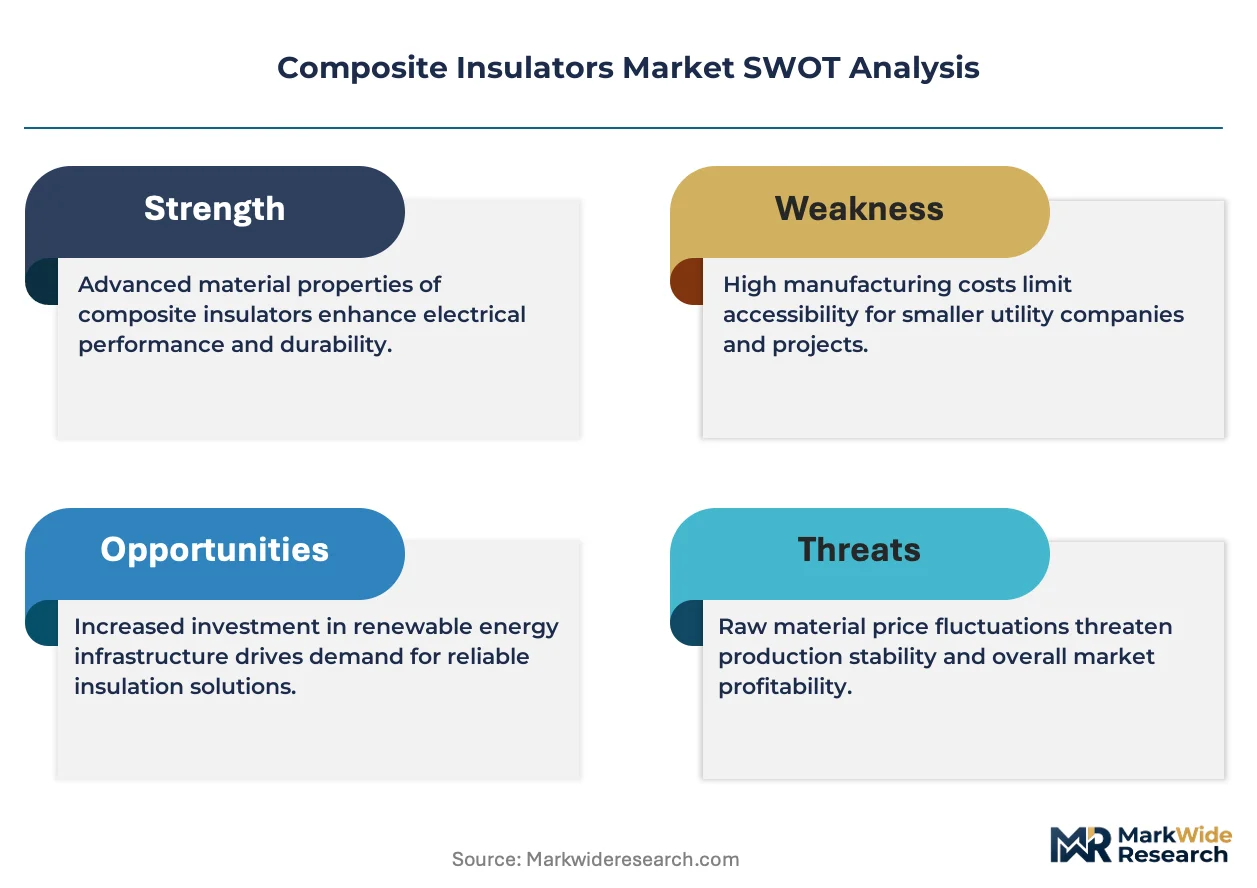
Direct utility procurement channels are rewriting competitive access across the Composite Insulators landscape. Hubbell Power Systems leverages its North American manufacturing footprint to sustain long-term supply agreements with major investor-owned utilities. Siemens Energy anchors European demand through integrated grid solutions that bundle composite insulators with transformer and switchgear packages. CYG Insulator competes aggressively on cost-engineered polymer formulations for emerging market transmission projects.
Composite insulators consist of a fiberglass-reinforced polymer core rod sheathed in silicone rubber or ethylene-propylene-diene-monomer (EPDM) housing, with metal end fittings crimped under controlled compression to achieve mechanical ratings exceeding 60 kN tensile load. Their primary purpose is to mechanically support and electrically isolate conductors in overhead power lines while resisting pollution flashover, ultraviolet degradation, and vandalism damage. Suspension insulators dominate transmission voltage classes above 132 kV where lightweight polymer housings reduce tower structural loading compared to porcelain alternatives. Railway electrification represents the fastest-growing application segment as 25 kV AC and 1.5 kV DC networks expand across Asia-Pacific and European corridors. Polymer composites command the technology category due to superior hydrophobic recovery and reduced maintenance cycles versus traditional ceramic formulations.
FERC transmission planning requirements and NERC reliability standards shape North American procurement specifications for contamination performance and mechanical integrity testing. EMA and EU Green Deal directives accelerate composite insulator replacement schedules across Central European grids targeting reduced lifecycle carbon footprints. India's CEA mandates BIS certification for 400 kV and above polymer insulators deployed under central transmission utility programs. Stakeholders must monitor evolving material qualification protocols and regional content requirements that increasingly determine supplier eligibility in publicly funded grid modernization programs.
Market Dynamics
Ultra-high-voltage grid expansion across Asia is compressing procurement cycles and forcing silicone rubber formulation upgrades to meet IEC 61109 hydrophobicity standards for 800 kV corridors.
Growth Catalysts
- India's Green Energy Corridor mandates:Central transmission utility programs require polymer composite string insulators for renewable integration, accelerating BIS certification demand.
- Railway electrification buildouts:25 kV AC network expansion across Asia-Pacific corridors drives specialized suspension insulator procurement for catenary systems.
- Silicone rubber hydrophobic recovery:Enhanced tracking resistance formulations reduce maintenance cycles versus EPDM alternatives, favoring polymer technology adoption.
Market Restraints
- Glass fiber core rod supply concentration:Specialty fiberglass reinforcement capacity clusters in East Asian manufacturing zones, creating single-source vulnerability.
- EPDM housing degradation in UV-intense climates:Ethylene-propylene-diene-monomer formulations exhibit faster surface erosion than silicone rubber in desert transmission corridors.
- CIGRE technical brochure compliance costs:Mechanical load testing protocols for 60 kN+ ratings require capital-intensive crimping equipment upgrades.
Strategic Opportunities
- EU Green Deal carbon footprint mandates:Lifecycle assessment requirements for grid infrastructure create replacement demand across Central European transmission networks.
- Digital twin integration:Sensor-embedded composite insulators enabling predictive maintenance represent unpenetrated value capture in high-voltage monitoring.
- Africa transmission interconnectors:Cross-border power pool projects lack established supplier relationships, opening procurement channels for qualified polymer manufacturers.
Industry Challenges
- IEC 61109 type test timeline compression:Accelerated aging validation for 400 kV+ ratings extends product qualification cycles beyond typical utility procurement windows.
- End fitting metallurgy expertise scarcity:Controlled compression crimping for 60 kN mechanical ratings requires specialized tooling operators in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Insulators Market |
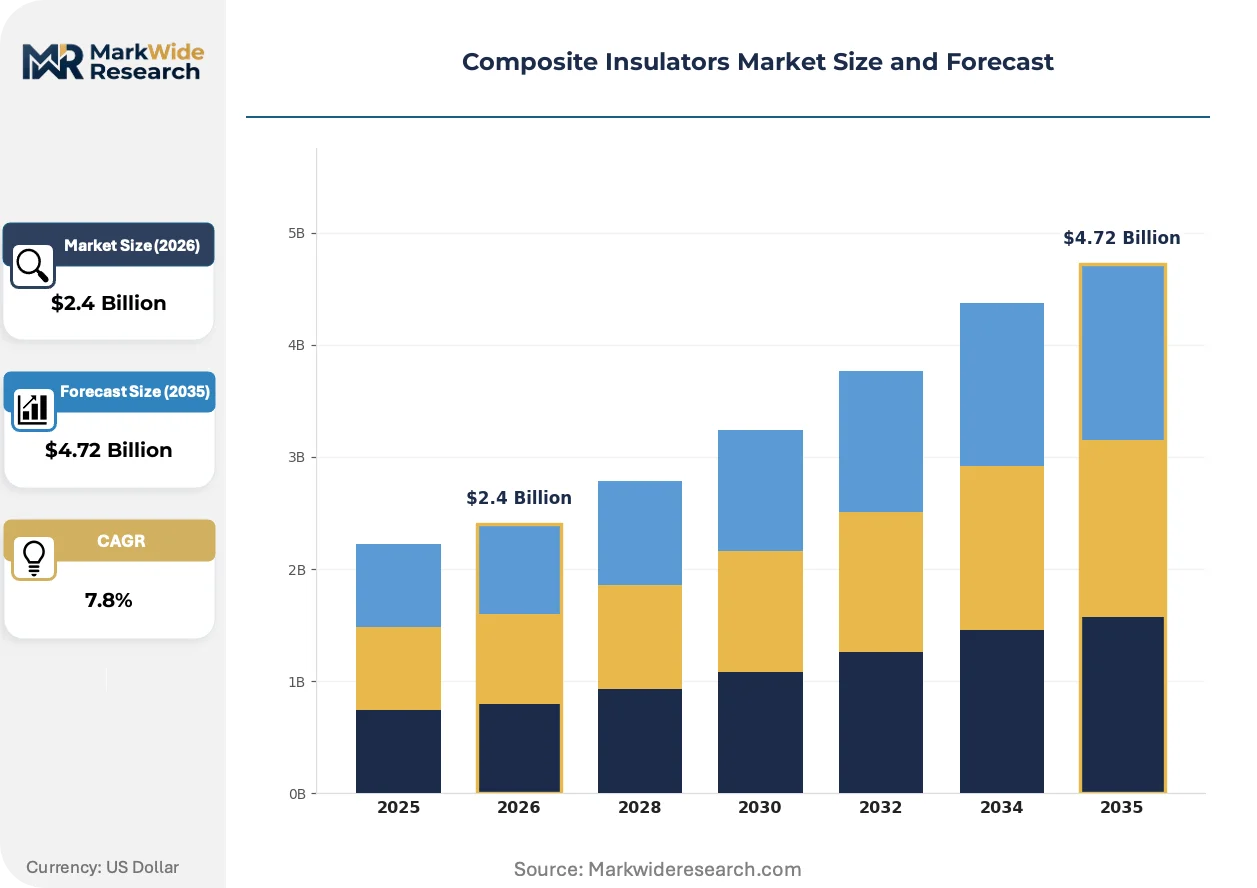
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Insulators, Pin Insulators, Suspension Insulators, Surge Arresters End User: Utilities, Telecommunications, Railways, Renewable Energy Application: Power Transmission, Power Distribution, Railway Electrification, Substation Technology: Polymer Composites, Ceramic Composites, Hybrid Materials, Others |
| Companies Covered | Aditya Birla Power Composites, Hubbell Power Systems, Hitachi Energy, CYG Insulator, NGK Insulators Ltd., Siemens Energy, PFISTERER, Bonomi Eugenio, TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Insulators Market Emerging Trajectories
Silicone rubber chemistry advances and embedded sensing capabilities are redefining performance benchmarks for polymer insulators in contamination-prone environments.
Self-monitoring composite insulators with integrated leakage current sensors are digitizing condition-based maintenance protocols. Transmission operators in China's State Grid are deploying these units across 500 kV corridors to reduce manual inspection frequency. Real-time hydrophobicity monitoring is compressing traditional time-based replacement schedules into predictive intervention models.
REACH restrictions on perfluorinated compounds are forcing housing material reformulations across European supply chains. Manufacturers must validate alternative surface treatments for pollution performance without legacy fluorinated additives. German TSOs now require substance compliance documentation as a procurement gate before technical evaluation.
Direct sourcing from polymer compounders is displacing distributor intermediaries in large utility procurement. State-owned transmission companies in India negotiate silicone rubber formulations directly with chemical suppliers, bypassing traditional insulator vendor markups. This channel compression is most pronounced in 400 kV and above voltage classes where material traceability requirements favor transparent supply chains.
Composite Insulators Market Segmentation
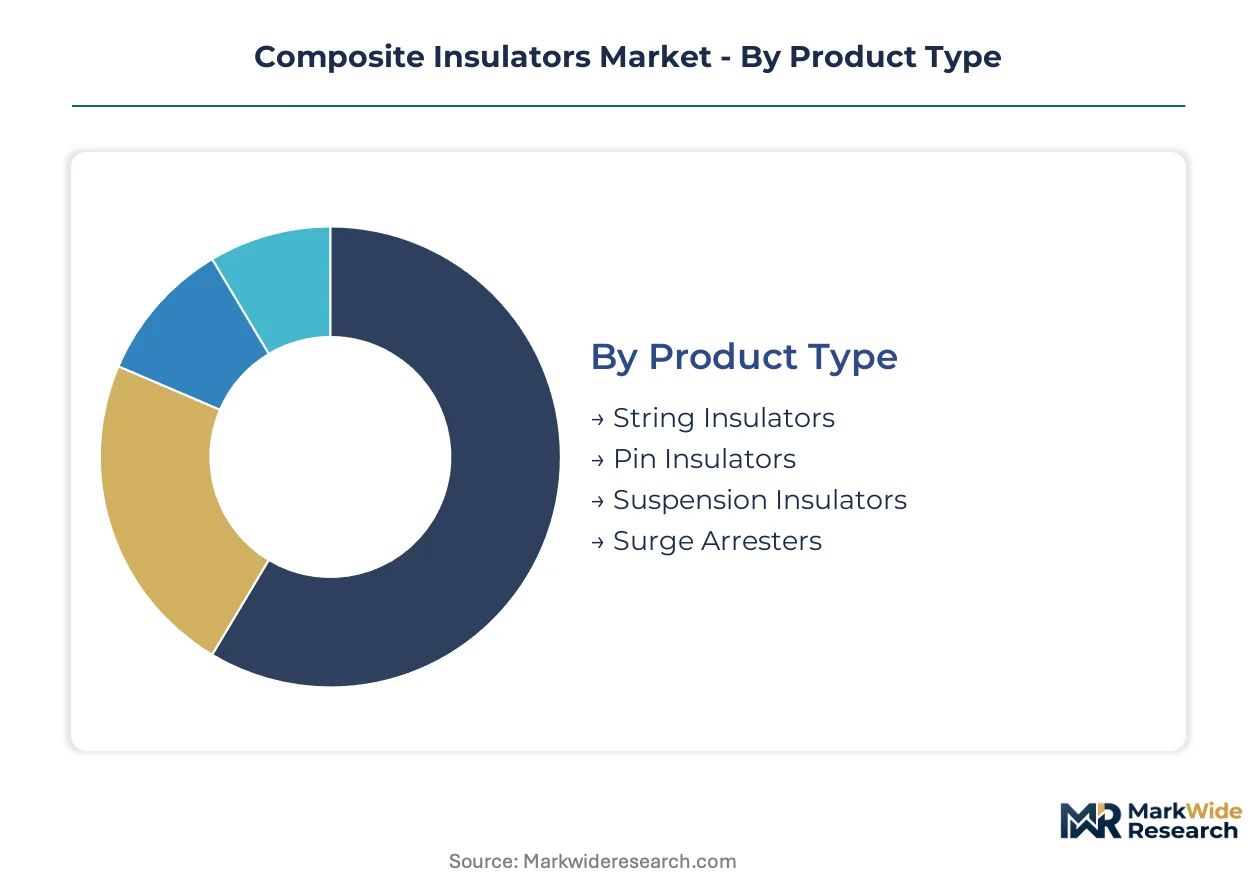
Composite insulator procurement patterns diverge sharply across voltage classes and end-use environments. Material selection and mechanical rating requirements reshape supplier positioning within each segment cluster.
Product Type:
Cost tier differentiation separates mass-market distribution hardware from specialized transmission-grade assemblies requiring extended mechanical validation.
- String Insulators:Fiberglass-reinforced polymer core rods with silicone rubber sheds, rated for 60 kN+ tensile loads in 132 kV to 800 kV corridors. China's State Grid procurement concentrates here for ultra-high-voltage buildouts where tower loading reduction justifies polymer premiums.
- Suspension Insulators:Multi-unit assemblies supporting conductor weight across long transmission spans. Indian Green Energy Corridor projects drive demand for 400 kV ratings with enhanced tracking resistance under BIS certification mandates.
- Pin Insulators:Compact single-piece designs for distribution voltages below 33 kV.
- Surge Arresters:Voltage-limiting devices integrated with polymer housings for substation protection.
String insulators command the established base. The steepest expansion runs through suspension insulators.
End User:
Application environment dictates material specification intensity, from contamination-heavy coastal zones to controlled indoor substations.
- Utilities:Investor-owned and state transmission companies specifying IEC 61109 compliance for high-voltage networks. European TSOs under EU Green Deal mandates accelerate replacement schedules with lifecycle carbon assessments.
- Railways:25 kV AC and 1.5 kV DC catenary systems across Asia-Pacific corridors. Specialized mechanical requirements for vibration resistance and aerodynamic stability under pantograph contact.
- Telecommunications:Antenna support and tower insulation for broadcast infrastructure.
- Renewable Energy:Wind farm collection systems and solar farm switchyard connections.
Utilities anchor volume procurement. The steepest expansion trajectory belongs to railways.
Application:
Voltage level and exposure severity determine housing material selection between silicone rubber and EPDM formulations.
- Power Transmission:High-voltage corridors above 132 kV requiring pollution flashover resistance. Desert installations in the southwestern United States favor silicone rubber recovery properties under intense UV exposure.
- Railway Electrification:Overhead catenary support with dynamic mechanical loading. European corridor expansion and Indian Dedicated Freight routes concentrate procurement for specialized suspension designs.
- Power Distribution:Medium-voltage networks below 33 kV with standardized hardware requirements.
- Substation:Equipment bushings and station post insulators for switchgear isolation.
Power transmission dominates installed base value. Railway electrification gains share fastest.
Technology:
Material chemistry maturity separates proven polymer formulations from developmental hybrid architectures.
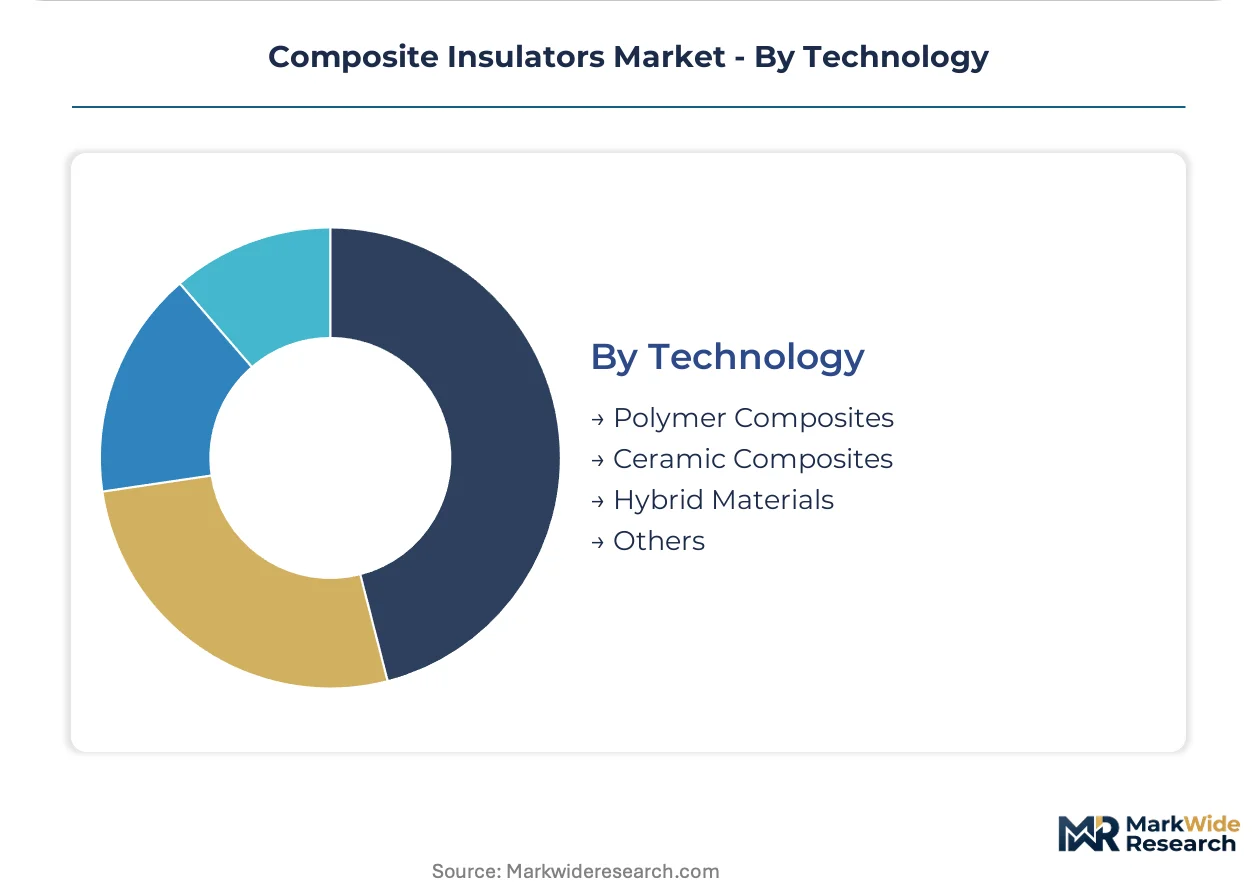
- Polymer Composites:Silicone rubber or EPDM housings over fiberglass cores, commanding preference for hydrophobic recovery and reduced maintenance cycles. REACH restrictions on perfluorinated compounds force European supply chain reformulations without performance degradation.
- Hybrid Materials:Polymer housings with ceramic sheds or graded interfaces for extreme contamination zones. German TSOs evaluate these for North Sea coastal corridors with heavy salt deposit accumulation.
- Ceramic Composites:Traditional porcelain with polymer coatings for legacy grid compatibility.
- Others:Experimental formulations including nanocomposite fillers and bio-based polymers.
Polymer composites hold the established base. Hybrid materials represent the steepest technology climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers command pricing leverage in silicone rubber formulations, while European TSOs absorb cost premiums for REACH-compliant supply chains. This asymmetry shapes procurement patterns across voltage classes and contamination zones.
China
State Grid's ultra-high-voltage buildout concentrates demand for 800 kV string insulators in the Yangtze River Delta manufacturing corridor. GB standards administered by SAMR enforce hydrophobicity testing protocols that exceed IEC 61109 baselines. Jiangsu and Zhejiang provinces host integrated polymer compounding and crimping operations serving domestic and export markets.
India
Green Energy Corridor mandates drive 400 kV suspension insulator procurement for renewable integration across Rajasthan and Gujarat solar zones. CEA mandates BIS certification for polymer insulators deployed under central transmission utility programs. Tamil Nadu's industrial belt houses formulation facilities supplying silicone rubber housings to domestic fabricators.
Germany
EU Green Deal lifecycle carbon mandates accelerate replacement schedules across 380 kV corridors operated by TenneT and 50Hertz. REACH restrictions on perfluorinated compounds force housing material reformulations without performance degradation. Bavaria's chemical cluster supplies alternative surface treatments for North Sea coastal contamination zones.
United States
FERC transmission planning requirements shape contamination performance specifications for southwestern desert installations. NERC reliability standards enforce mechanical integrity testing for 500 kV networks crossing Texas and Arizona. Hubbell's North American manufacturing footprint sustains long-term supply agreements with investor-owned utilities in the Southeast.
Japan
METI grid modernization programs prioritize polymer insulators for earthquake-resistant transmission infrastructure. JIS standards govern tracking resistance validation for coastal installations facing salt deposit accumulation. Chubu region fabricators specialize in hybrid material architectures for extreme contamination zones.
Composite Insulators Market Vendor Landscape
Integrated grid solution providers and specialized polymer formulators split the market across procurement channels. Tier concentration is moderate, with five to eight suppliers holding established positions in major transmission corridors. Strategic archetypes include utility-captive manufacturers with backward integration into silicone rubber compounding, and technology licensors leveraging IEC certification expertise for emerging market entry. Competitive moves center on direct utility procurement channel compression and REACH-compliant material qualification acceleration.
Among Asia-Pacific-based fabricators, CYG Insulator and NGK Insulators Ltd. occupy positions within the cost-engineered polymer tier. Siemens Energy exemplifies the integrated solutions archetype, bundling composite insulators with transformer and switchgear packages. Hubbell Power Systems represents the regional manufacturing footprint strategy, anchoring North American supply security for investor-owned utilities.
| Leading Market Players |
|---|
| Aditya Birla Power Composites |
| Hubbell Power Systems |
| Hitachi Energy |
| CYG Insulator |
| NGK Insulators Ltd. |
| Siemens Energy |
| PFISTERER |
| Bonomi Eugenio |
| TE Connectivity |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on East Asian glass fiber core rod capacity compresses pricing power for European and North American fabricators while simultaneously dictating supply chain geography. This concentration dynamic widens spreads between REACH-compliant silicone rubber formulations and standard-grade EPDM alternatives, forcing procurement officers to navigate trade-offs between performance premiums and material traceability requirements.
Pricing Analysis
The customization-premium spread separates configured-to-order 800 kV string insulators from standard 132 kV distribution hardware. Three-tier pricing structure across IEC 61109-certified transmission-grade, BIS-mandated renewable corridor, and economy distribution tiers reflects certification intensity and mechanical load validation depth. Cost compression in the standard tier intensifies as Chinese manufacturers leverage integrated compounding-to-crimping operations. State-owned transmission utilities in India exhibit highest price sensitivity due to direct silicone rubber sourcing, while German TSOs under EU Green Deal mandates absorb premiums for lifecycle carbon documentation.
Supply Chain Analysis
Extended payment terms from 90 to 180 days characterize supplier-financing arrangements between Indian central transmission utilities and domestic fabricators. Glass fiber reinforcement capacity concentrates in China, Japan, and Germany, with silicone rubber compounding clustered in Jiangsu province and Bavaria's chemical corridor. Specialty fiberglass rod supply draws from Toray and Jushi operations, while housing formulations hinge on Wacker and Momentive silicone supply. Single-source vulnerability in ultra-high-tensile core rod above 60 kN ratings creates procurement risk. Distribution runs through direct utility procurement channels that displace distributor intermediaries in voltage classes above 400 kV.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as railway electrification buildouts and digital twin integration create specialized niches outside incumbent utility-channel dominance. Demand-side shift toward predictive maintenance protocols and sensor-embedded architectures rewards focused technical specialists over integrated grid solution bundlers.
For Market Incumbents: Entrench position through backward integration into silicone rubber compounding to secure REACH-compliant formulation supply against perfluorinated compound restrictions. Acquire crimping equipment operators with 60 kN+ mechanical rating expertise to address end fitting metallurgy scarcity threatening production timelines. Channel control via long-term supply agreements with investor-owned utilities anchors volume against emerging market procurement compression. For New Entrants and Emerging Players: Africa transmission interconnectors offer the most penetrable geography as cross-border power pool projects lack established supplier relationships and qualified polymer manufacturer rosters. Target 25 kV AC railway catenary systems across Asia-Pacific corridors where specialized vibration-resistant designs command technical premiums absent commodity competition. Go-to-market angle centers on IEC 61109 certification acceleration services for local fabricators seeking emerging market entry. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-tier polymer formulators with captive silicone rubber supply and established utility procurement relationships. Long-term viability over the next decade rests on REACH-compliant material qualification capabilities and digital twin integration IP. Acquisition archetype: regional fabricators with BIS or GB standard certification depth and underutilized crimping capacity. Signal to watch: CIGRE technical brochure revision timelines compressing product qualification cycles beyond procurement windows, favoring pre-qualified asset bases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Rubber Compounding | Secures REACH-compliant housing supply against perfluorinated additive restrictions for German TSO contracts. |
| Sensor-Embedded Product Development | Captures predictive maintenance value in China's State Grid 500 kV corridor digitization programs. |
| Long-term Supply Agreement with Central Transmission Utilities | Locks volume through India's Green Energy Corridor procurement mandates under CEA supervision. |
| Certification Acceleration Services | Monetizes IEC 61109 expertise for African power pool entrants lacking qualification infrastructure. |
| Crimping Equipment Operator Training Program | Addresses 60 kN mechanical rating expertise scarcity constraining ultra-high-voltage production scaling. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with transmission utility procurement officers, polymer compounder technical directors, and railway electrification EPC contractors; and secondary validation through IEC technical committee documentation, CIGRE working group reports, BIS certification registries, and customs trade data on silicone rubber formulation imports. Bottom-up triangulation across voltage class demand estimates and top-down reconciliation against national grid investment disclosures anchored market sizing.
Forecast inputs incorporated silicone rubber hydrophobicity degradation curves, railway electrification mileage buildout schedules, and REACH compliance cost trajectories. Segmentation dimensions spanned product type, end user archetype, application environment severity, and technology chemistry maturity. CAGRs derived from regression against historical procurement cycles and projected infrastructure investment flows. Industry-specific inputs included GB standard revision timelines and Green Energy Corridor tender issuance patterns.
Practitioners should monitor CIGRE technical brochure publication schedules and perfluorinated compound restriction expansion for early signals of qualification burden shifts. Forecasts reflect documented assumptions on polymer substitution rates and utility procurement cycle normalization. Macroeconomic infrastructure budget contraction, regulatory timeline acceleration, or silicone rubber feedstock disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Containerized Substation Market
Electrical Power Equipment
Instant Water Heater Market
Electrical Power Equipment
Busway-Bus Duct Market
Electrical Power Equipment
Smart Electric Heater Market
Electrical Power Equipment
Immersion Heater Market
Electrical Power Equipment
Industrial Power Supply Market
Electrical Power Equipment
Composite Line Post Insulators Market
Electrical Power Equipment
North America Gas Insulated Switchgear Market
Electrical Power Equipment
Substation Testing Equipment Market
Electrical Power Equipment
Global Magnetic Circuit Breaker Market
Electrical Power Equipment
Gas Insulated Switchgear Sales Market
Electrical Power Equipment
US Air Filter Market
Electrical Power Equipment
Europe Electric Radiators Market
Electrical Power Equipment
AV Power Conditioners Market
Electrical Power Equipment
South America Air Insulated Switchgear Market
Electrical Power Equipment
Magneto Optic Current Transformer Market