
 Carbon Brush Market | 2026-2036
Carbon Brush Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Brush Market Analysis
The capital-intensity divergence between integrated carbon manufacturers and downstream brush fabricators is unwinding as raw material volatility reshapes competitive economics. Mersen leverages captive graphite sourcing to sustain margin stability across European industrial channels. Schunk Group anchors its position through precision-machining scale in automotive starter-motor supply chains. Morgan Advanced Materials differentiates via ceramic-metal hybrid brush technology for high-RPM aerospace generators.
A carbon brush is a sliding electrical contact, typically composed of electrographite, copper-graphite, or resin-bonded carbon, engineered to transmit current between stationary and rotating components in motors and generators while minimizing frictional wear and electrical arcing. Rectangular brushes dominate volume in heavy-duty industrial machinery due to standardized slot geometries and ease of field replacement, though specialty profiles command premium pricing in precision servo applications. Graphite grades retain the largest material share across power tool and marine segments, while copper-graphite composites are displacing pure carbon in EV regenerative braking systems where current density requirements have intensified.
FDA oversight of carbon brush dust exposure in food-processing equipment, EPA restrictions on copper particulate emissions from metal-composite brushes, and NHTSA motor-safety testing protocols collectively elevate compliance costs for suppliers serving North American OEMs. The EU REACH framework and RoHS substance restrictions further constrain binder chemistry choices for brushes entering European industrial channels. Stakeholders must monitor evolving motor-efficiency certification tiers and raw material traceability mandates to anticipate procurement specification shifts before they harden into contract requirements.
Market Dynamics
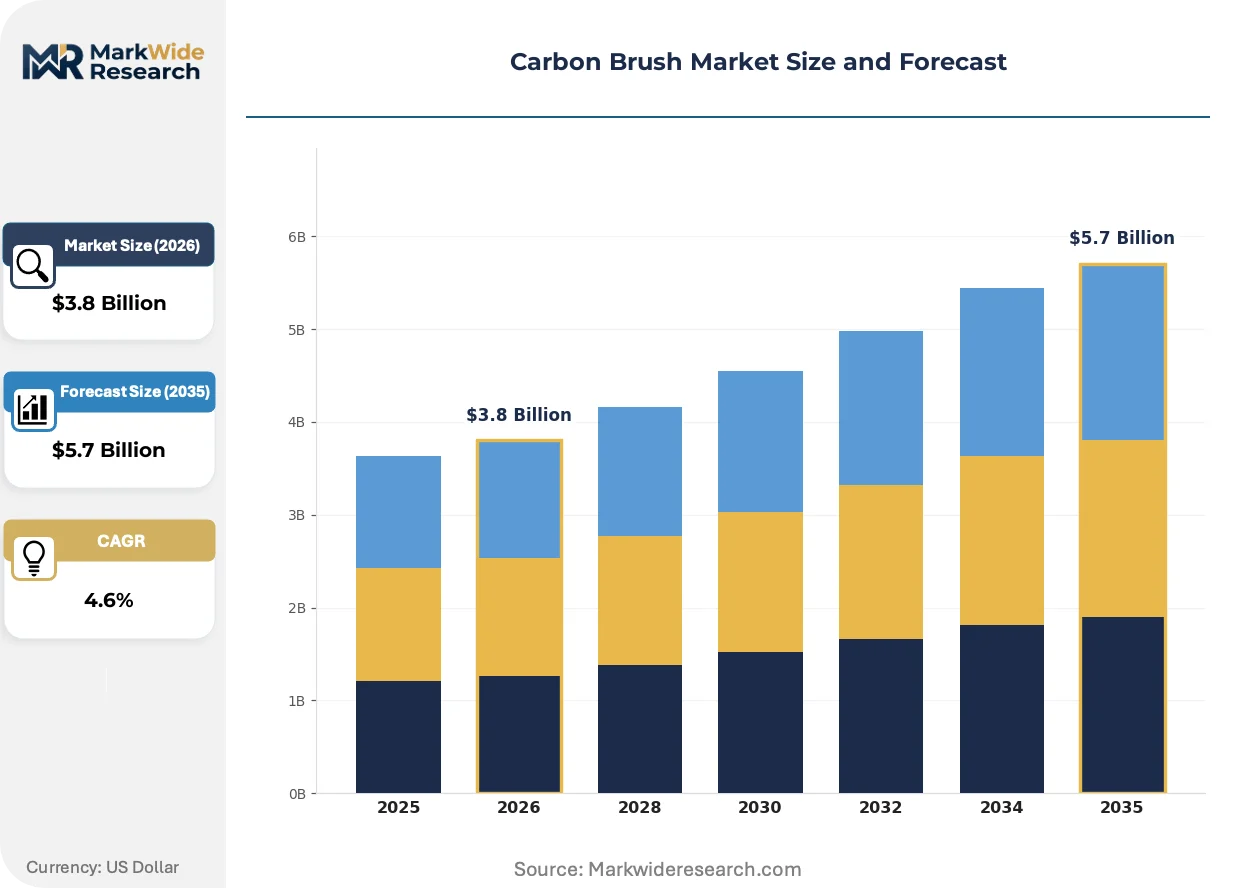
The EU Ecodesign Directive's escalating motor-efficiency tiers are compressing replacement cycles and forcing brush-grade upgrades across European industrial channels, while EV traction-motor proliferation generates parallel demand for copper-graphite composites capable of handling regenerative braking current densities.
Growth Catalysts
- EU Ecodesign Directive:Tiered efficiency mandates under this framework compel OEMs to specify higher-grade electrographite formulations, accelerating brush replacement frequency in industrial motor fleets.
- EV traction motors:Regenerative braking systems in battery-electric vehicles require copper-graphite brushes with elevated current-carrying capacity, opening dedicated supply contracts with automotive tier-1 suppliers.
- Stuttgart-Munich refurbishment corridor:Concentrated industrial motor rebuild activity across southern Germany sustains premium aftermarket demand for precision-machined brush sets.
Market Restraints
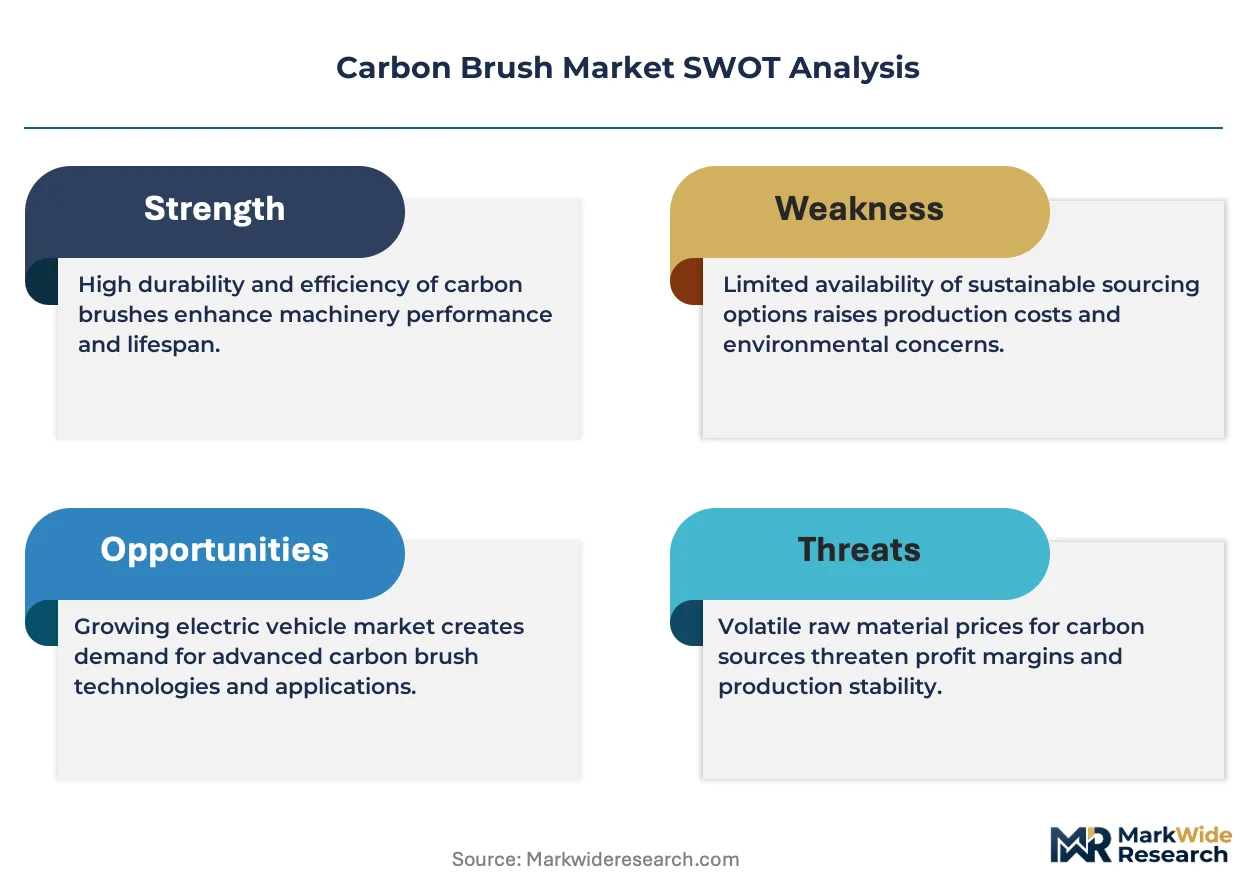
- Graphite price volatility:Electrode-grade graphite feedstock costs fluctuate with steel-arc furnace operating rates, squeezing margin stability for non-integrated brush fabricators.
- REACH substance restrictions:ECHA constraints on phenolic resin binders and copper particulate thresholds limit formulation flexibility for brushes entering European industrial channels.
- Solid-state motor controllers:Variable frequency drives reduce mechanical commutation stress in some industrial applications, extending brush service intervals and compressing unit volume.
Strategic Opportunities
- India BIS certification pipeline:Mandatory ISI marking for industrial motors creates entry barriers for uncertified brush suppliers, rewarding early compliance investment with preferred vendor status.
- Ceramic-metal hybrid convergence:Integration of silicon carbide substrates with copper-graphite matrices enables brush operation above 15,000 RPM, unlocking aerospace generator retrofits.
- Direct-to-rebuild-channel distribution:Bypassing traditional distributor markups through dedicated e-procurement portals serving independent motor rewind shops captures margin previously lost to intermediaries.
Industry Challenges
- Precision-machining skill scarcity:Tight tolerances on automotive starter-motor brushes require CNC grinding expertise that regional vocational pipelines struggle to replenish.
- Dual REACH-RoHS compliance timelines:Parallel substance disclosure and hazardous material restriction certifications delay new product introductions by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Brush Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round, Rectangular, Specialty, Custom Application: Automotive, Industrial Machinery, Power Tools, Marine End User: Manufacturers, Repair Services, On-line Retailers, Wholesalers Material: Graphite, Copper, Carbon Composite, Others |
| Companies Covered | Helwig Carbon Products, AVO Carbon Group, Mersen, Fuji Carbon Manufacturing Co., Ohio Carbon Industries, Schunk Group, Toyo Tanso Co. Ltd., SGL Carbon, Morgan Advanced Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Brush Market Emerging Trajectories
Brush architecture is compressing toward thinner cross-sections and segmented contact faces as motor designers prioritize power density over service accessibility, while regulatory chemistry constraints and digital procurement platforms simultaneously reshape how specifications propagate through supply chains.
Copper-graphite composite formulations with 40-60% metal loading are miniaturizing brush footprints in EV auxiliary motors without sacrificing current density. Tier-1 automotive suppliers specify these materials for HVAC blower and cooling pump applications where package space constraints intensify. The structural consequence is a compression in traditional rectangular brush volumes as cylindrical and wafer-thin profiles capture incremental platform awards.
REACH substance restrictions on polycyclic aromatic hydrocarbons in binder systems are eliminating conventional phenolic resin chemistries from brushes entering EU industrial channels. ECHA's 2023 update to Annex XVII imposes migration limits that legacy formulations breach, forcing reformulation cycles. German motor OEMs now require full material disclosure documentation upstream of contract qualification, shifting competitive advantage to suppliers with captive resin synthesis capabilities.
Aftermarket procurement through dedicated e-procurement portals is displacing traditional electrical distributor relationships for standard industrial brush grades. Independent motor rewind shops in the US Midwest and German Ruhr region now source commodity rectangular brushes through specialized B2B platforms that aggregate demand and compress lead times. This channel shift is most visible in fractional-horsepower motor segments where specification standardization permits digital transaction without engineering consultation.
Carbon Brush Market Segmentation
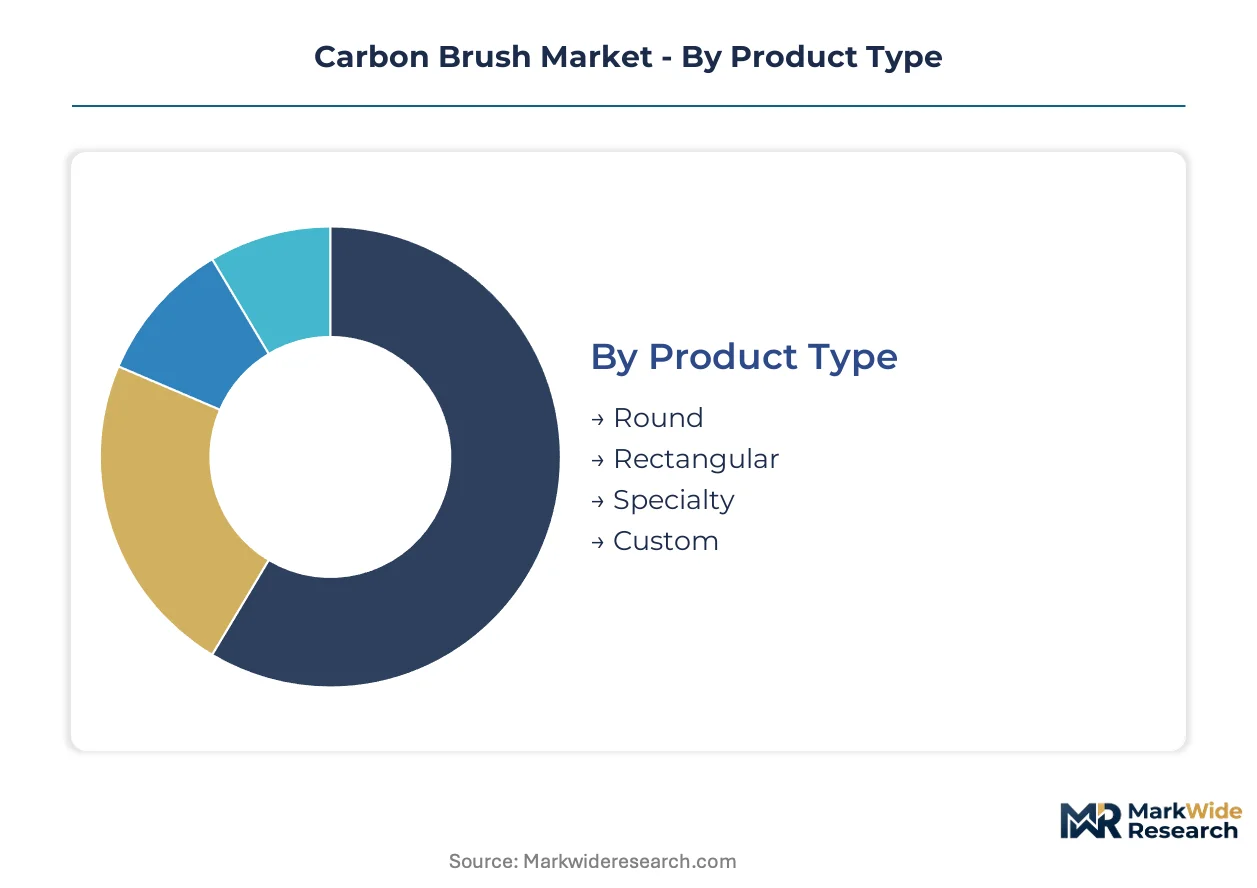
Carbon brush procurement channels diverge sharply by segment, with industrial machinery and automotive OEMs demanding direct mill-certified supply while power tools and marine segments route through distributor networks. Material selection and geometry specifications cascade differently through each channel, creating distinct margin architectures.
Product Type:
Round brushes flow predominantly through automotive tier-1 supply chains, while rectangular configurations dominate industrial distributor catalogs. Specialty and custom profiles command dedicated engineering sales channels.
- Rectangular:Standardized slot geometries enable bulk procurement through electrical distributors serving industrial motor rebuild shops. Demand concentrates in Germany's Stuttgart-Munich refurbishment corridor where EU Ecodesign Directive compliance pressures replacement frequency.
- Round:Cylindrical profiles with precision-ground diameters transmit current in automotive starter motors and EV auxiliary systems. Copper-graphite composites in this geometry capture platform awards from tier-1 HVAC blower suppliers where package constraints intensify.
- Specialty:Segmented contact faces and angled profiles serve aerospace generator applications above 15,000 RPM.
- Custom:Application-specific machining for servo motors and precision instrumentation bypasses standard catalog channels.
By volume, rectangular leads. By growth pace, round is climbing the fastest.
Application:
Cost tier stratification separates premium aerospace and EV traction applications from commodity industrial replacement cycles.
- Industrial Machinery:Heavy-duty motors in steel, cement, and chemical plants drive bulk consumption of electrographite grades. EU motor-efficiency mandates compress service intervals, amplifying aftermarket pull through German and US Midwest rewind shops.
- Automotive:EV regenerative braking systems impose current density requirements that copper-graphite composites alone satisfy. NHTSA safety testing protocols and EPA copper particulate restrictions elevate qualification barriers for North American supply contracts.
- Power Tools:Fractional-horsepower motors in cordless drills and angle grinders specify resin-bonded carbon for cost-sensitive OEM assembly.
- Marine:Salt-resistant graphite grades serve propulsion and winch motors in commercial shipping fleets.
Industrial machinery commands absolute volume. Automotive applications are expanding most quickly.
End User:
Customer type determines specification depth, with manufacturers demanding full material traceability and repair services prioritizing interchangeability.
- Manufacturers:OEM motor builders in Germany, Japan, and the US require REACH-compliant material disclosure and captive resin synthesis capabilities. Contract qualification cycles extend 8-14 months under dual REACH-RoHS timelines.
- Repair Services:Independent rewind shops in the US Midwest and German Ruhr region aggregate demand through e-procurement portals, compressing lead times on standard rectangular grades.
- On-line Retailers:Digital channels capture fractional-horsepower replacement demand where specification standardization permits transaction without engineering consultation.
- Wholesalers:Traditional electrical distributors retain position in marine and specialty segments requiring technical support.
Manufacturers dominate value capture. Repair services are gaining share fastest through channel digitization.
Material:
Supply concentration in electrode-grade graphite feedstock reshapes competitive economics across material tiers.
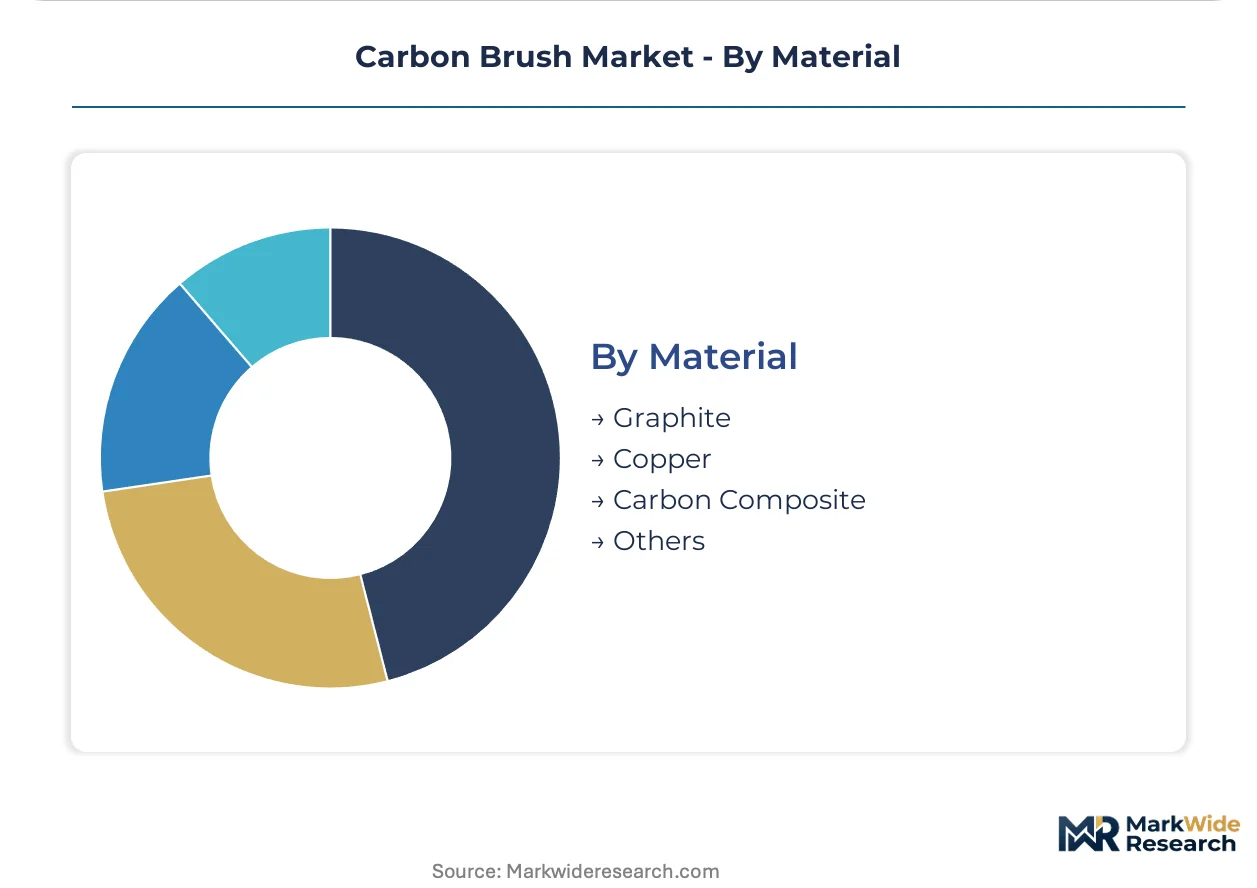
- Graphite:Electrographite grades retain largest share across power tools and marine segments where frictional wear tolerance outweighs current density requirements. Price volatility in steel-arc furnace electrode markets squeezes non-integrated fabricators.
- Copper:Metal-graphite composites with 40-60% copper loading displace pure carbon in EV regenerative braking and high-RPM aerospace generators. EPA restrictions on copper particulate emissions constrain North American formulation flexibility.
- Carbon Composite:Ceramic-metal hybrids integrating silicon carbide substrates enable operation above 15,000 RPM for aerospace retrofits.
- Others:Resin-bonded formulations serve cost-constrained power tool OEMs.
Graphite leads by installed base. Copper-graphite composites show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German brush fabricators command 15-20% price premiums over Chinese suppliers in European industrial channels, while Indian manufacturers undercut both on standard grades by 8-12% in Middle Eastern aftermarket procurement. This asymmetry reflects divergent regulatory compliance burdens and raw material sourcing economics across manufacturing geographies.
Germany
Stuttgart and Munich host Europe's densest clusters of industrial motor refurbishment shops, driving premium aftermarket demand for precision-machined electrographite grades. EU Ecodesign Directive motor-efficiency tiers compress replacement cycles, forcing brush-grade upgrades. Baden-Württemberg's automotive supplier ecosystem generates parallel demand for copper-graphite composites in EV traction systems.
United States
NHTSA motor-safety testing protocols and EPA copper particulate restrictions elevate qualification costs for brushes entering automotive OEM supply chains. The US Midwest's independent motor rewind shops aggregate demand through e-procurement portals, compressing lead times on standard rectangular grades. FDA oversight of carbon brush dust exposure constrains formulations for food-processing equipment applications.
China
Domestic electrode-grade graphite production supplies cost-competitive feedstock for brush fabricators serving Southeast Asian export markets. MIIT industrial motor efficiency standards create regulatory alignment with EU Ecodesign tiers, enabling Chinese suppliers to qualify for European aftermarket contracts. Yangtze River Delta manufacturing clusters concentrate precision-machining capacity for automotive tier-1 suppliers.
India
BIS mandatory ISI marking for industrial motors creates entry barriers rewarding early compliance investment with preferred vendor status. Maharashtra and Gujarat host expanding motor manufacturing bases generating first-fit brush demand. CDSCO and CEA electrical safety regulations constrain formulation choices for brushes entering power infrastructure applications.
Japan
METI energy-efficiency roadmaps for industrial equipment accelerate brush replacement frequency in precision manufacturing sectors. JIS standardization enables specification harmonization across automotive and industrial motor OEMs. Kansai region suppliers specialize in high-RPM aerospace generator applications requiring ceramic-metal hybrid formulations.
Carbon Brush Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated graphite producers sustaining margin stability against raw material volatility while precision-machining specialists capture premium positioning in automotive channels. The market structure concentrates around three strategic tiers: captive-resource integrated manufacturers, automotive-focused precision fabricators, and regional commodity suppliers serving aftermarket distributor networks. Dominant competitive moves include backward integration into electrode-grade graphite sourcing and direct-to-rebuild-channel distribution bypassing traditional electrical distributors.
Among European integrated manufacturers, Mersen and SGL Carbon exemplify the captive-resource archetype through upstream control over graphite feedstock supply. Schunk Group occupies a position within the precision-machining tier, anchoring automotive starter-motor supply chain relationships. Morgan Advanced Materials represents technology differentiation through ceramic-metal hybrid formulations serving aerospace generator applications above 15,000 RPM.
| Leading Market Players |
|---|
| Helwig Carbon Products |
| AVO Carbon Group |
| Mersen |
| Fuji Carbon Manufacturing Co. |
| Ohio Carbon Industries |
| Schunk Group |
| Toyo Tanso Co. Ltd. |
| SGL Carbon |
| Morgan Advanced Materials |
| Others |
Supply Flow & Price Mechanics
EU REACH substance restrictions on phenolic resin binders and copper particulate thresholds simultaneously gate supplier qualification and stratify price tiers, forcing reformulation investments that separate REACH-compliant fabricators from uncertified competitors serving price-sensitive aftermarket channels.
Pricing Analysis
Configured-to-order pricing for ceramic-metal hybrid brushes commands 40-60% premiums over standard electrographite rectangles, with three-tier pricing structure across premium, standard, and economy levels anchored by certification grade and material traceability depth. Price differentiation rests on REACH-compliant material disclosure documentation and captive resin synthesis capabilities. Cost compression in commodity rectangular grades is intensifying because e-procurement portals aggregate demand and compress distributor markups. Independent motor rewind shops exhibit highest price sensitivity, while aerospace OEMs accept premium positioning for high-RPM formulations.
Supply Chain Analysis
China and Germany anchor electrode-grade graphite production and precision-machining capacity respectively, with India emerging as a cost-competitive fabricator for standard grades. Supply chains draw from synthetic graphite feedstock, copper powder metallurgy inputs, and phenolic resin binder chemistries. Single-source vulnerability concentrates in electrode-grade graphite feedstock where steel-arc furnace operating rates drive price volatility. Distribution runs through direct mill-certified supply for automotive OEMs and e-procurement portals serving independent rewind shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state motor controllers and variable frequency drives threaten brush replacement frequency, requiring incumbents to defend application niches where mechanical commutation remains irreplaceable.
For Market Incumbents: Fortify captive graphite sourcing to sustain margin stability against feedstock volatility, while deepening precision-machining scale in automotive starter-motor supply chains to defend against emerging Chinese tier-1 suppliers. Prioritize REACH-compliant resin synthesis capabilities to accelerate contract qualification cycles compressed by dual REACH-RoHS timelines.
For New Entrants and Emerging Players: Lead with BIS certification investment for India's mandatory ISI-marked industrial motor segment, where early compliance secures preferred vendor status before enforcement tightens. Target direct-to-rebuild-channel distribution through specialized B2B platforms serving US Midwest and German Ruhr rewind shops, bypassing entrenched electrical distributor relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across copper-graphite composite formulations as current density requirements intensify, favoring acquisition targets with in-house powder metallurgy capabilities and automotive tier-1 qualifications. Watch for inflection in EV traction-motor platform awards as the signal separating viable scale players from stranded commodity fabricators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Graphite Feedstock | Captive electrode-grade sourcing insulates margin stability from steel-arc furnace volatility. |
| REACH-Compliant Resin Synthesis Investment | In-house binder chemistry capabilities compress 8-14 month dual certification timelines. |
| Ceramic-Metal Hybrid R&D Scale-Up | Silicon carbide substrate integration unlocks aerospace generator retrofits above 15,000 RPM. |
| Direct E-Procurement Portal Launch | Bypassing distributor markups captures margin from independent motor rewind shop aggregation. |
| BIS Certification Pipeline Completion | Early ISI marking compliance secures preferred vendor status in India's expanding motor base. |
Methodological Framework
Desk research of customs trade databases, SEC filings from listed carbon manufacturers, and EU ECHA substance restriction updates preceded structured interviews with OEM procurement managers, independent motor rewind shop operators, automotive tier-1 supplier quality directors, and electrode-grade graphite traders. Primary fieldwork combined with secondary validation from BIS certification records and NHTSA motor-safety testing protocols enabled bottom-up unit consumption estimates triangulated against top-down market value reconstruction.
Variance decomposition across material grade, end-use application, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented demand modeling incorporating EV traction-motor penetration curves, EU Ecodesign Directive tier implementation schedules, and industrial motor fleet refurbishment cycles. Forecast inputs included REACH substance restriction phase-in timelines and MIIT efficiency standard alignment patterns.
Forecasts assume regulatory continuity in EU REACH-RoHS frameworks and BIS certification enforcement; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in motor-efficiency mandate tiers and EV platform award announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Electric Radiators Market
Electrical Power Equipment
Load Bank Market
Electrical Power Equipment
Recloser Market
Electrical Power Equipment
Global Surge Arrester Market
Electrical Power Equipment
Composite Insulators Market
Electrical Power Equipment
Asia Pacific Gas Insulated Switchgear Market
Electrical Power Equipment
North America Surge Arresters Market
Electrical Power Equipment
Instant Water Heater Market
Electrical Power Equipment
Immersion Heater Market
Electrical Power Equipment
HVDC Converter Station Market
Electrical Power Equipment
Magnetic Optical Current Transformer Market
Electrical Power Equipment
North America Protective Relays Market
Electrical Power Equipment
Busbar Protection Market
Electrical Power Equipment
Substation Market
Electrical Power Equipment
Power Line Filters Market
Electrical Power Equipment
Global Explosion-Proof Electric Motors and Actuators Market