
 Super Capacitor Energy Storage System Market | 2026-2036
Super Capacitor Energy Storage System Market Size, Share, and Industry Trends Forecast 2026-2036
Super Capacitor Energy Storage System Market Outlook
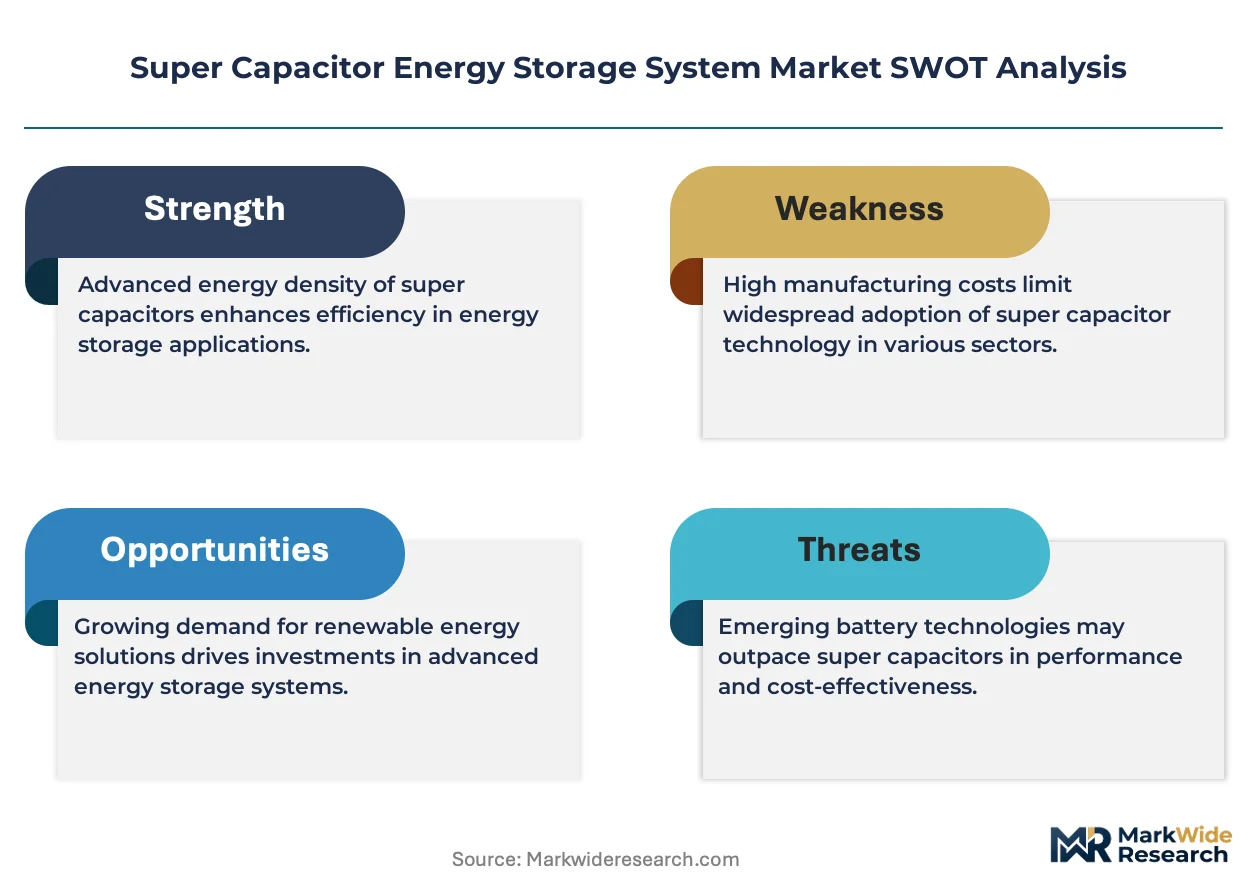
Asset-light leasing models for grid-scale energy storage assets is reconfiguring capital deployment across the super capacitor value chain. Skeleton Technologies leverages its European manufacturing base to anchor premium module supply for heavy-duty transport. Panasonic Corporation sustains R&D intensity in hybrid electrochemical systems for consumer electronics integration. Maxwell Technologies dominates high-reliability defense and aerospace applications through proprietary dry electrode formulations.
A super capacitor energy storage system stores electrical energy through electrostatic double-layer capacitance or fast surface redox reactions, achieving power densities exceeding 10 kW/kg and cycle lives surpassing one million charge-discharge events. These systems buffer transient power loads, recover braking energy, and stabilize renewable intermittency in ways lithium-ion batteries cannot match electrically. Double-layer capacitors occupy the mature volume tier where manufacturing scale has compressed unit costs below hybrid architectures. Pseudocapacitors lead growth in electric vehicle power buffering where energy density requirements are tightening. Hybrid capacitors command the deepest margin pools by bridging the performance gap between electrostatic and electrochemical storage in industrial UPS deployments.
The EPA and FERC in the United States shape demand through emissions enforcement mandates and grid interconnection standards that favor fast-response storage assets. China's MEE and MIIT enforce dual carbon compliance and GB certification thresholds that filter out lower-efficiency super capacitor imports. Stakeholders must monitor how evolving carbon border adjustments and domestic content rules redistribute manufacturing location advantages before committing capital to new production capacity.
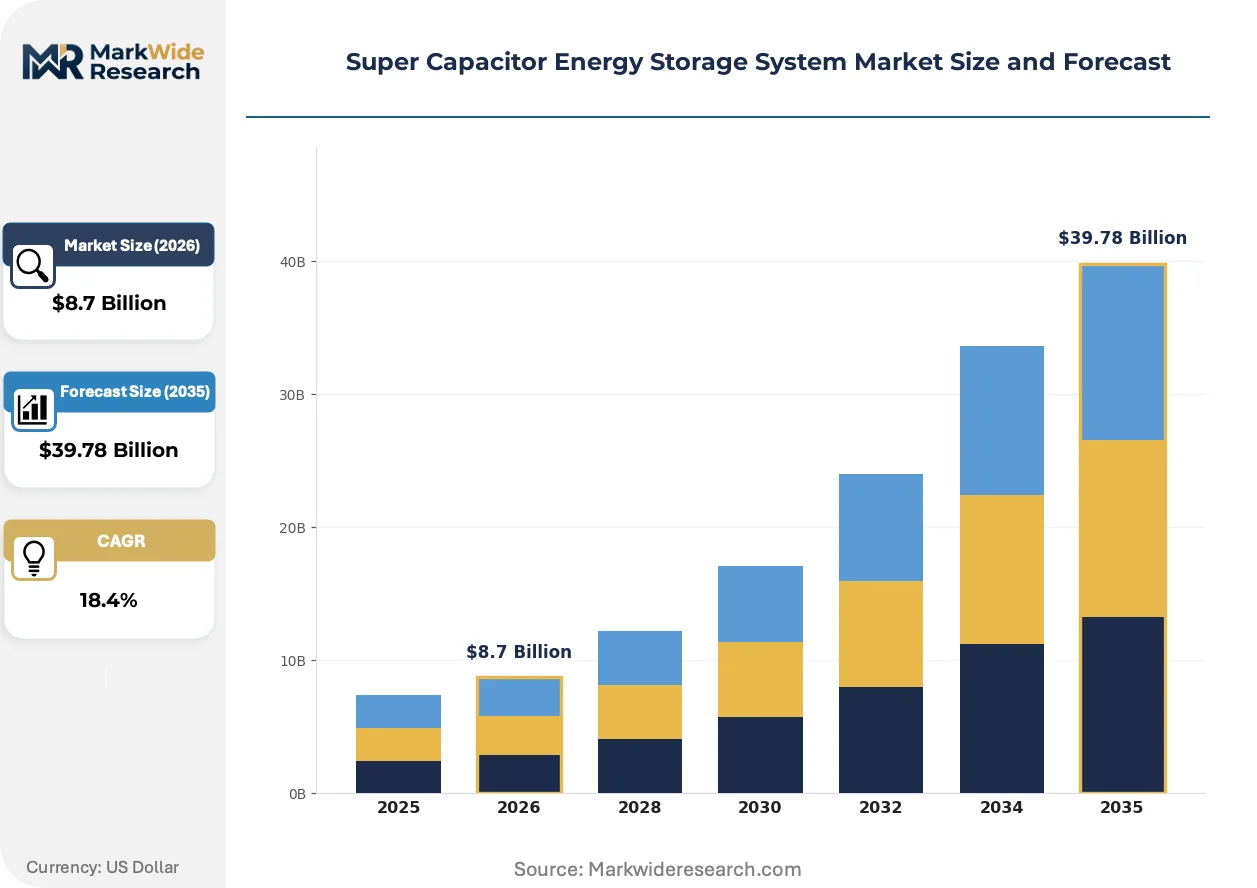
Market Dynamics
China's dual carbon enforcement through MIIT and MEE is compressing import windows for lower-efficiency super capacitor architectures while accelerating domestic certification velocity. This regulatory tightening is redistributing manufacturing location advantages across the value chain.
Growth Catalysts
- Regenerative Braking Mandates:Germany's KBA is tightening efficiency benchmarks for heavy-duty transport electrification. Fleet operators around Stuttgart and Wolfsburg are expanding module procurement for kinetic energy recovery.
- GB Standard Convergence:China's updated GB certification thresholds for energy storage performance are filtering out legacy electrostatic designs. Domestic manufacturers are retooling dry electrode lines to meet tightened capacitance retention requirements.
- Grid Interconnection Standards:FERC Order 841 implementation in the United States is favoring fast-response assets over lithium-ion for frequency regulation. Independent system operators are revising procurement weights toward sub-second ramp rates.
Market Restraints
- Activated Carbon Supply Concentration:High-purity electrode material production clusters in Southeast Asian processing facilities. Single-source dependencies for coconut-shell-derived carbon are amplifying input cost volatility.
- Energy Density Ceiling:Electrostatic double-layer architectures face fundamental physical limits below 10 Wh/kg. Pseudocapacitive materials have not scaled beyond pilot volumes for automotive power buffering.
- RoHS Compliance Friction:REACH substance restrictions on fluorinated electrolytes are forcing reformulation cycles. European module assemblers are absorbing extended certification timelines for alternative ionic liquids.
Strategic Opportunities
- Industrial UPS Convergence:Hybrid capacitor architectures bridging electrostatic and electrochemical storage are penetrating data center backup applications. Siemens and ABB infrastructure divisions are piloting integrated rack systems for hyperscale facilities.
- Aviation Electrification:FAA certification pathways for emergency power systems are opening for high-reliability super capacitor modules. Regional jet retrofit programs are evaluating dry electrode designs for landing gear actuation.
- India PLI Tailwinds:Production-linked incentives for advanced chemistry cell manufacturing are extending to super capacitor assembly. Domestic energy storage parks in Gujarat and Tamil Nadu are attracting electrode slurry investments.
Industry Challenges
- Dry Electrode Talent Scarcity:Solvent-free coating process engineering expertise concentrates at Maxwell Technologies and Skeleton Technologies. Competitors face 18-24 month capability build timelines.
- Multi-Physics Simulation Complexity:Thermal-electrochemical coupled modeling for million-cycle durability prediction requires specialized finite element teams. Module designers are outsourcing to ANSYS-certified consultancies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Super Capacitor Energy Storage System Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Layer Capacitors, Pseudocapacitors, Hybrid Capacitors, Electrochemical Capacitors End User: Automotive, Consumer Electronics, Industrial, Renewable Energy Systems Application: Energy Recovery, Power Buffering, UPS, Electric Vehicles Technology: Electrochemical, Mechanical, Thermal, Hybrid |
| Companies Covered | Maxwell Technologies, Skeleton Technologies, Nippon Chemi-Con Corporation, Eaton Corporation, Panasonic Corporation, LS Mtron, Cap-XX, Ioxus, Nesscap Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Super Capacitor Energy Storage System Market Strategic Shifts
Dry electrode manufacturing is compressing capital intensity and environmental compliance costs while enabling thicker active material loadings. This process shift is redrawing competitive moats across the module assembly tier.
Electrode slurry solvent elimination is virtualizing the traditional coating-drying-calendering sequence. Automotive tier-1 suppliers are piloting Maxwell-derived processes for 100-micron-plus electrode builds. The technology is virtualizing incumbent wet-line equipment depreciation schedules and forcing asset restructuring across European contract manufacturers.
REACH substance restriction expansions are accelerating fluorinated electrolyte phaseouts. Formulators are pivoting toward sulfonium-based ionic liquids with widened electrochemical windows. Industrial UPS deployments in Germany and France are absorbing premium pricing for compliant module supply.
Leasing structures for grid-scale super capacitor assets are displacing outright procurement in United States independent power producer portfolios. Capital-light deployment models are compressing offtake risk for project developers. Texas ERCOT interconnection queues are exhibiting the fastest contract structure migration toward availability-based payments.
Super Capacitor Energy Storage System Market Segmentation
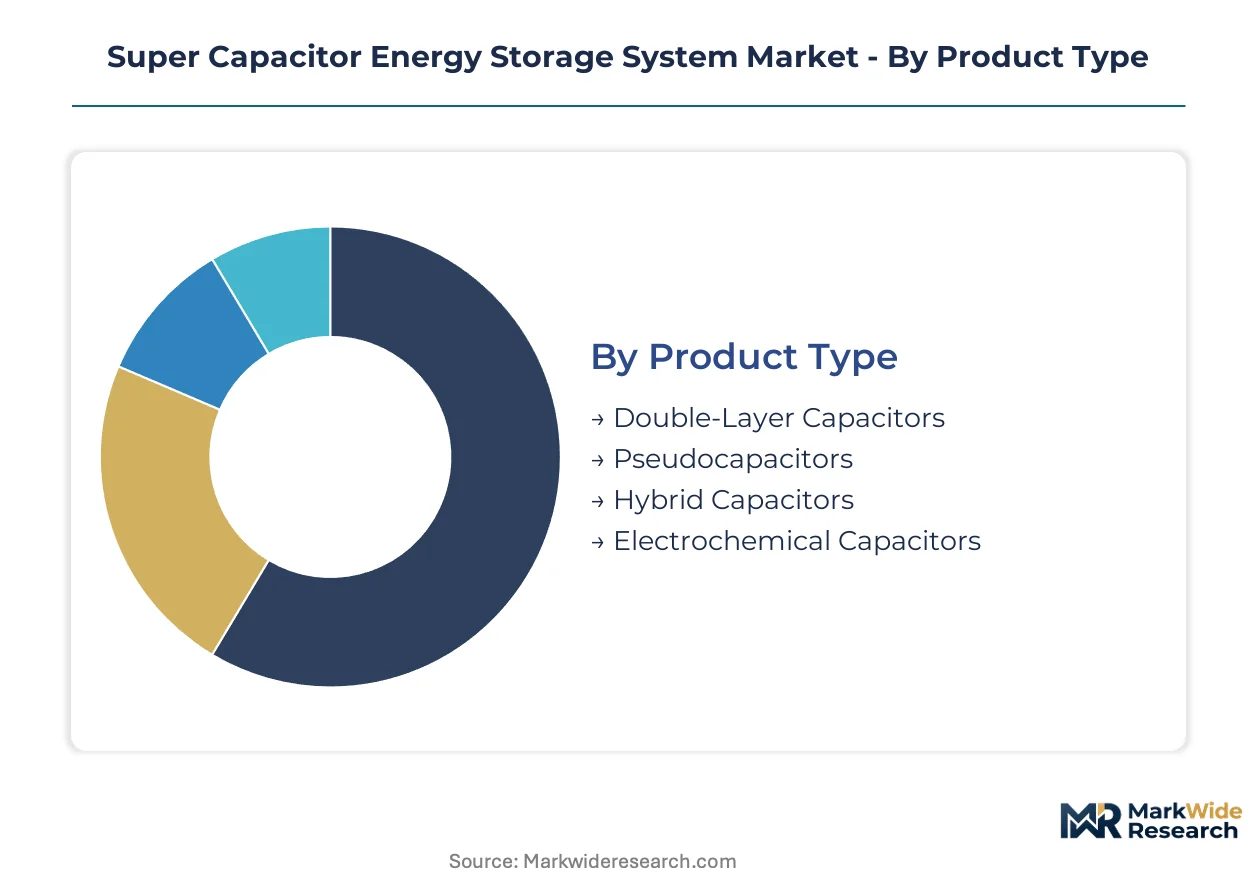
Super capacitor architectures diverge sharply in power density, cycle endurance, and capital intensity. Procurement patterns across automotive, grid storage, and industrial backup applications favor distinct electrochemical configurations.
Product Type:
Transport electrification and grid stabilization needs span electrostatic storage through hybrid electrochemical architectures.
- Double-Layer Capacitors:Electrostatic charge storage at carbon-electrolyte interfaces delivers power densities exceeding 10 kW/kg with million-cycle durability. German fleet operators around Stuttgart deploy these modules for heavy-duty regenerative braking where maintenance intervals must stretch beyond battery replacement cycles.
- Hybrid Capacitors:Asymmetric electrode designs marrying battery-grade anodes with capacitor cathodes bridge the energy density gap for industrial UPS. Siemens infrastructure divisions are piloting integrated rack systems for hyperscale data centers in Frankfurt and Munich where sub-second switchover is mandatory.
- Pseudocapacitors:Fast surface redox reactions on metal oxide electrodes boost energy density for electric vehicle power buffering, though manufacturing scale remains below pilot volumes.
- Electrochemical Capacitors:Faradaic charge transfer mechanisms serve niche defense and aerospace applications requiring extreme temperature tolerance.
Established volume favors double-layer architectures; emerging adoption favors hybrid configurations bridging performance gaps.
End User:
Customer procurement patterns cluster around kinetic energy recovery, electronics miniaturization, and grid stabilization mandates.
- Automotive:OEMs specify modules for start-stop systems, regenerative braking, and torque assist in 48V mild-hybrid architectures. China's MIIT enforcement of dual carbon compliance is accelerating domestic certification for imported electrostatic designs.
- Industrial:Manufacturing facilities and data centers require uninterruptible power with sub-cycle response. ABB infrastructure divisions are integrating hybrid capacitor banks for German automotive supplier plants where voltage sag costs exceed equipment premiums.
- Consumer Electronics:Wearables and handheld devices demand thin-form-factor storage with rapid charge capability.
- Renewable Energy Systems:Solar and wind farms deploy fast-response assets for frequency regulation and ramp rate control.
Automotive procurement commands the deepest margin pools; industrial UPS contracts are climbing the fastest as data center buildouts accelerate.
Application:
Functional deployment spans kinetic energy harvesting through primary traction power support.
- Energy Recovery:Braking energy capture in rail, mining, and port equipment converts dissipative loads into reusable power. KBA efficiency benchmarks for German heavy-duty transport are tightening procurement specifications.
- Power Buffering:Transient load leveling for automated manufacturing and semiconductor fabrication protects sensitive processes from voltage fluctuations.
- UPS:Critical facility backup demands instant switchover without battery warm-up latency.
- Electric Vehicles:Peak power assist and fast-charge buffering extend lithium-ion pack life while enabling thermal management.
Energy recovery applications dominate installed base; power buffering for industrial automation is expanding most quickly.
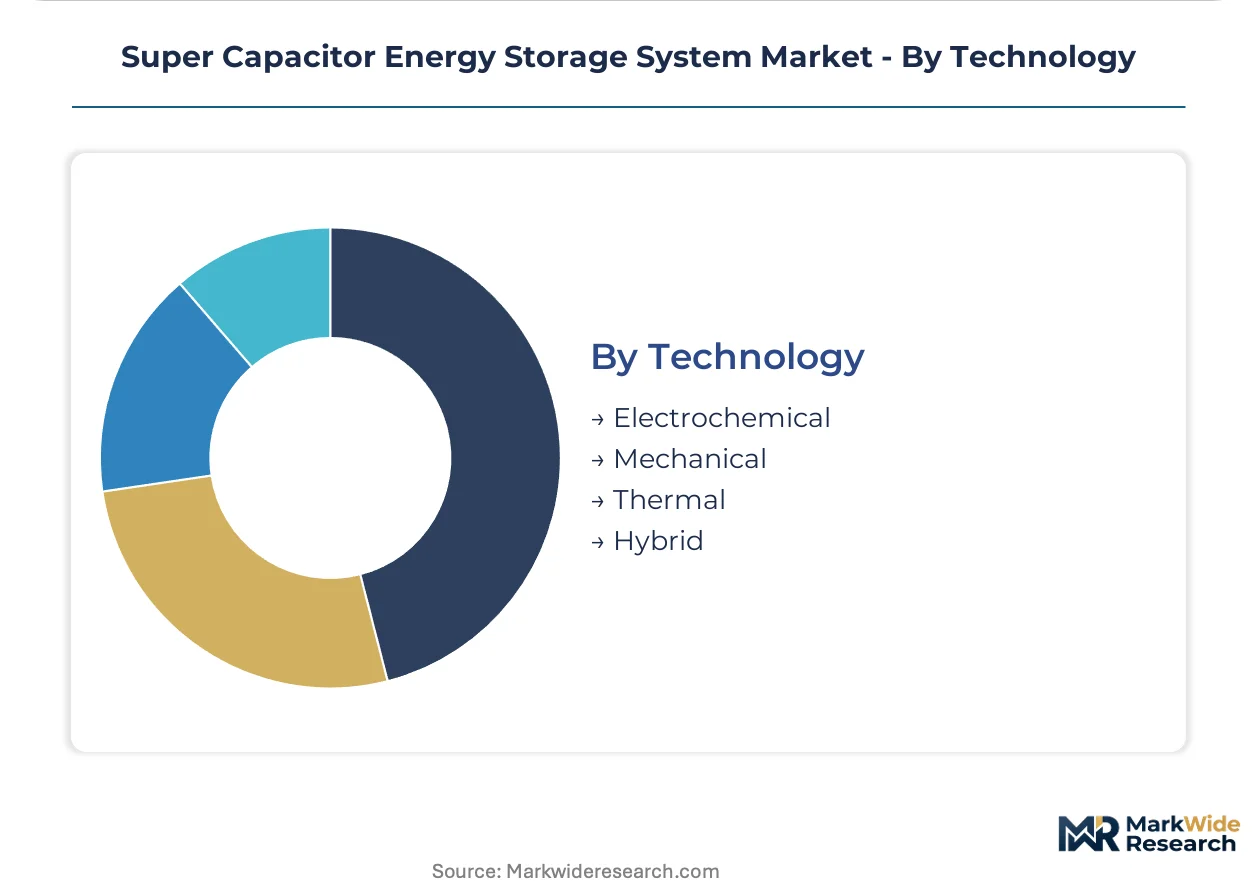
Technology:
Underlying physical mechanisms determine capital intensity, environmental compliance burden, and performance ceiling.
- Electrochemical:Ion migration and redox reactions at electrode surfaces govern all capacitor variants, with dry electrode processing from Maxwell Technologies and Skeleton Technologies compressing solvent use and capital intensity.
- Mechanical:Flywheel and compressed air hybrids serve grid-scale applications where discharge duration exceeds electrostatic economics.
- Thermal:Phase-change and thermoelectric coupling enables extreme environment operation.
- Hybrid:Multi-physics integration combines electrochemical storage with mechanical or thermal buffering for specialized aerospace and defense specifications.
Pure electrochemical platforms anchor manufacturing scale; hybrid technology configurations are gaining share fastest in defense and aviation certification pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement managers at German automotive OEMs and Chinese grid operators command the largest contract volumes, while US independent power producers and Indian manufacturing parks are accelerating module qualification timelines.
China
MIIT enforcement of dual carbon compliance is filtering out legacy electrostatic designs from import channels. Domestic manufacturers are retooling dry electrode lines to meet tightened GB certification thresholds for capacitance retention. Yangtze River Delta industrial parks in Jiangsu and Zhejiang are absorbing electrode slurry investments from tier-1 suppliers.
Germany
KBA efficiency benchmarks for heavy-duty transport electrification are tightening procurement specifications for kinetic energy recovery. Fleet operators around Stuttgart and Wolfsburg are expanding super capacitor module orders for regenerative braking systems. Baden-Württemberg's automotive supplier corridor is piloting hybrid capacitor integration for 48V mild-hybrid architectures.
United States
FERC Order 841 implementation favors fast-response assets over lithium-ion for frequency regulation in ERCOT and PJM interconnection queues. Independent system operators are revising procurement weights toward sub-second ramp rates. Texas ERCOT markets are exhibiting the fastest contract structure migration toward availability-based payments for grid-scale storage.
India
Production-linked incentives for advanced chemistry cell manufacturing are extending to super capacitor assembly under CEA guidelines. Domestic energy storage parks in Gujarat and Tamil Nadu are attracting electrode material investments from automotive tier-1 suppliers. Maharashtra's industrial corridors are qualifying modules for port equipment and rail braking energy recovery.
Japan
METI standards for grid stabilization assets are accelerating certification for hybrid electrochemical systems. Consumer electronics manufacturers in Osaka and Nagoya are integrating thin-form-factor super capacitors for wearable device power buffering. Kansai region industrial facilities are deploying modules for automated manufacturing voltage sag protection.
Super Capacitor Energy Storage System Market Competitive Environment
Channel-controlling players compete with product-specialist players across three discernible tiers. Vertically integrated module assemblers with captive electrode production anchor the premium tier, while contract manufacturers serving automotive tier-1 suppliers occupy the mid-market. Technology licensors and materials specialists populate the third tier. Consolidation pressure is intensifying through dry electrode process licensing and European manufacturing footprint expansion.
Among European-based specialists, Skeleton Technologies and Maxwell Technologies exemplify the vertically integrated archetype with solvent-free coating capabilities. Panasonic Corporation occupies a position bridging consumer electronics integration and hybrid system development. These three anchors represent distinct competitive vectors: European heavy-duty transport focus, US defense-aerospace reliability standards, and Japanese electronics miniaturization expertise.
| Leading Market Players |
|---|
| Maxwell Technologies |
| Skeleton Technologies |
| Nippon Chemi-Con Corporation |
| Eaton Corporation |
| Panasonic Corporation |
| LS Mtron |
| Cap-XX |
| Ioxus |
| Nesscap Energy |
| Others |
Value Chain & Pricing Dynamics
Southeast Asian coconut-shell carbon processing clusters anchor electrode material supply, concentrating margin capture among activated carbon refiners while module assemblers absorb input volatility through long-term offtake structures.
Pricing Analysis
GB certification tier creates the primary spread between qualified and unqualified module supply in China. Three-tier pricing structure across aerospace-grade, automotive-qualified, and industrial-standard levels reflects MIIT enforcement stringency. Cost compression in double-layer architectures is intensifying because dry electrode process licensing is democratizing manufacturing capability. Fleet operators in Germany's automotive corridor show least price sensitivity; contract manufacturers serving consumer electronics exhibit highest elasticity.
Supply Chain Analysis
Export control regimes on fluorinated electrolyte precursors limit flows from European formulators to Asian module assemblers. Electrode material production centers on Indonesia, Sri Lanka, and the Philippines; electrolyte formulation rests on German and Japanese specialty chemical output. Single-source vulnerability concentrates in high-purity coconut-shell activated carbon. Distribution runs through automotive tier-1 supplier networks for OEM qualification, with direct procurement emerging for grid-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German automotive OEMs and Chinese state grid operators, compressing supplier margins and forcing consolidation among mid-tier module assemblers without captive electrode production.
For Market Incumbents: Build process moats around solvent-free coating expertise before Maxwell Technologies and Skeleton Technologies license dry electrode technology more broadly. Secure backward integration into activated carbon refining to neutralize Southeast Asian supply volatility. Defend against emerging Chinese domestic manufacturers retooling for GB certification by accelerating European manufacturing footprint expansion.
For New Entrants and Emerging Players: Build out qualification pipelines for India's PLI-extended super capacitor assembly incentives in Gujarat and Tamil Nadu. Industrial UPS applications for hyperscale data centers offer the most penetrable white-space, with sub-second switchover requirements that hybrid architectures uniquely satisfy. Partner with Siemens or ABB infrastructure divisions for co-development credibility.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with captive dry electrode capability and existing aerospace certification. Long-term viability favors assets that can bridge defense-aerospace reliability standards with automotive volume economics. Watch for FERC Order 841 implementation velocity in Texas ERCOT markets as inflection signal for grid-scale leasing structure adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Dry Electrode Process Licensing | Democratizes solvent-free manufacturing while eroding incumbent equipment depreciation advantages. |
| GB Certification Pre-Qualification | Secures MIIT-compliant import channels before dual carbon enforcement tightens further. |
| Activated Carbon Backward Integration | Neutralizes Southeast Asian supply concentration and input cost volatility. |
| Aviation Emergency Power Certification | Opens FAA pathway for high-reliability modules in regional jet retrofit programs. |
| Grid-Scale Leasing Structure Deployment | Compresses offtake risk for IPPs in Texas ERCOT interconnection queues. |
Study Parameters
A spread of perspectives from super capacitor module design engineers, automotive OEM procurement directors, grid operator planning officers, and specialty chemical formulators converged on the working assumptions. Primary fieldwork combined with secondary validation from FERC filings, MIIT GB standard updates, KBA efficiency benchmark releases, and customs trade data for activated carbon flows. Bottom-up electrode material demand modeling and top-down energy storage deployment projections were triangulated for consistency.
Demand-supply balance dynamics across the projection horizon shaped the analytical framework. Segmentation dimensions included product architecture, end-use industry, application function, and regional regulatory cluster. CAGRs were derived from installed base growth rates and replacement cycle analysis. Dry electrode process adoption curves and aviation certification pipeline velocity served as industry-specific forecast inputs.
Stress conditions across coconut-shell carbon supply disruption, REACH substance restriction expansion, and FERC Order 841 implementation delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology cost trajectories and regulatory enforcement intensity. Material shifts in China's dual carbon compliance velocity or aviation certification pathway acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
ASEAN Energy Storage Devices Market
Energy Storage
Power Bank Market
Energy Storage
Ultracapacitors Market
Energy Storage
Flywheel Energy Storage (FES) Systems Market
Energy Storage
Grid Scale Battery Storage Sales Market
Energy Storage
Gravity Energy Storage Market
Energy Storage
Battery Storage Inverter Market
Energy Storage
Energy Storage Software Market
Energy Storage
Hydrogen-Bromine Flow Battery Market
Energy Storage
Cryogenic Vaporizer Market
Energy Storage
Battery Energy Storage Market
Energy Storage
Sodium Sulfur (Nas) Battery for Energy Storage Market
Energy Storage
Water Electrolysis Machine Market
Energy Storage
Battery Cell Dry Room Dehumidification Systems Market
Energy Storage
Mobile Energy Storage Systems Market
Energy Storage
Hydrogen Liquefaction System Market