
 Europe Induction Motor Market | 2026-2036
Europe Induction Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Induction Motor Market Intelligence
German motor manufacturers is repositioning production capacity toward premium efficiency classes to align with tightening EU Ecodesign requirements. ABB leverages its vertical integration across power electronics and motor manufacturing to sustain margin control across the value chain. Menzel Elektromotoren anchors its competitive stance through heavy-duty custom motor engineering for industrial clients. WEG competes by extending its service network across Central and Eastern European manufacturing corridors.
An induction motor is an alternating-current electric motor in which torque is produced by electromagnetic induction from the magnetic field of the stator winding rather than from direct electrical connection to the rotor, typically operating at speeds determined by supply frequency and pole count with squirrel-cage or wound-rotor configurations. These motors convert electrical energy to mechanical rotation for driving pumps, compressors, conveyors, and machine tools across industrial and commercial installations. Three-phase operation mode dominates installed base volumes due to superior power density and operational efficiency in continuous-duty manufacturing environments. HVAC application segments are gaining structural importance as building energy retrofits accelerate across European commercial real estate. Automotive end users represent a concentrated margin pool where precision motor specifications command technical premiums.
The EU Ecodesign Directive and REACH framework administered by ECHA shape product compliance requirements, efficiency tiers, and material restrictions for motor manufacturers selling into European member states. CE marking obligations under the Machinery Directive further condition market access and technical documentation standards. Germany's KBA influences motor specifications for rail and road transportation applications through vehicle-type approval protocols. Stakeholders must monitor evolving F-Gas Regulation amendments and their secondary effects on HVAC motor specifications and refrigerant system integration requirements.
Market Dynamics
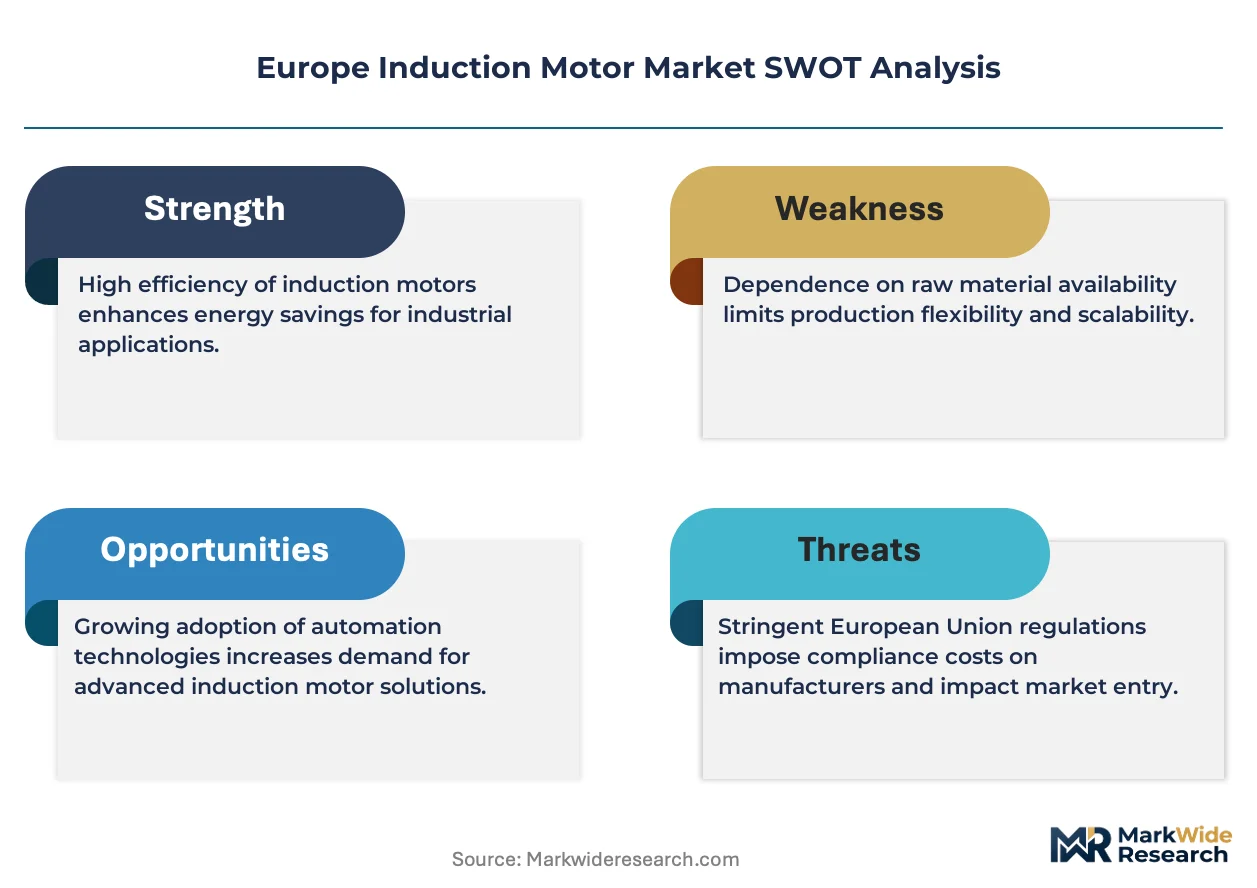
The EU Ecodesign Directive's tightening efficiency tiers are compressing demand toward IE4 and IE5 motor classes, forcing manufacturers to reconfigure production lines and retire legacy IE2 inventories ahead of regulatory deadlines.
Growth Catalysts
- IE5 Synchronous Reluctance Hybrid Designs:These motors combine induction reliability with permanent-magnet efficiency, capturing specification wins in German automotive paint shops and Italian food processing lines where continuous duty cycles dominate.
- France's Building Renovation Wave:Commercial HVAC retrofits in Paris and Lyon are accelerating demand for variable-speed induction drives as the country's national energy efficiency mandates tighten operational carbon thresholds for existing building stock.
- REACH Material Compliance:ECHA's restricted substance lists are pushing motor manufacturers toward copper rotor bar alternatives and bio-based insulation systems that qualify for green public procurement tenders across Nordic municipal infrastructure projects.
Market Restraints
- Copper and Electrical Steel Price Volatility:Raw material input costs for laminated stator cores and wound rotor assemblies fluctuate with commodity exchange pricing, compressing margin predictability for mid-tier European motor assemblers.
- Permanent Magnet Motor Substitution:Rare-earth magnet motors from East Asian suppliers are displacing induction architectures in precision positioning applications where servo-grade dynamics command technical premiums.
- Extended CE Marking Documentation Burden:The Machinery Directive's expanded technical file requirements for safety-related control systems are lengthening time-to-market for new motor-drive combinations by four to eight months.
Strategic Opportunities
- Polish Manufacturing Corridor Expansion:Industrial automation investments in Wrocław and Łódź are creating demand for medium-voltage induction motors in automotive component stamping and battery assembly operations.
- EU Green Deal Public Procurement Rules:Member state tendering authorities must now apply lifecycle cost and embodied carbon criteria, advantaging IE4+ motor suppliers with verified environmental product declarations.
- Digital Twin Integration:Condition monitoring sensors and cloud-based motor analytics are converging with predictive maintenance platforms, enabling motor OEMs to capture recurring revenue through performance-guarantee service contracts.
Industry Challenges
- Electrical Machine Design Talent Scarcity:European universities are producing insufficient graduates with combined power electronics and electromagnetic field simulation expertise to staff R&D departments at incumbent motor manufacturers.
- Legacy Drive Retrofit Integration Complexity:Replacing IE2 motors with IE4 equivalents in existing VFD-controlled systems requires harmonic mitigation and thermal derating analysis that extends commissioning timelines and strains field service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Induction Motor Market |
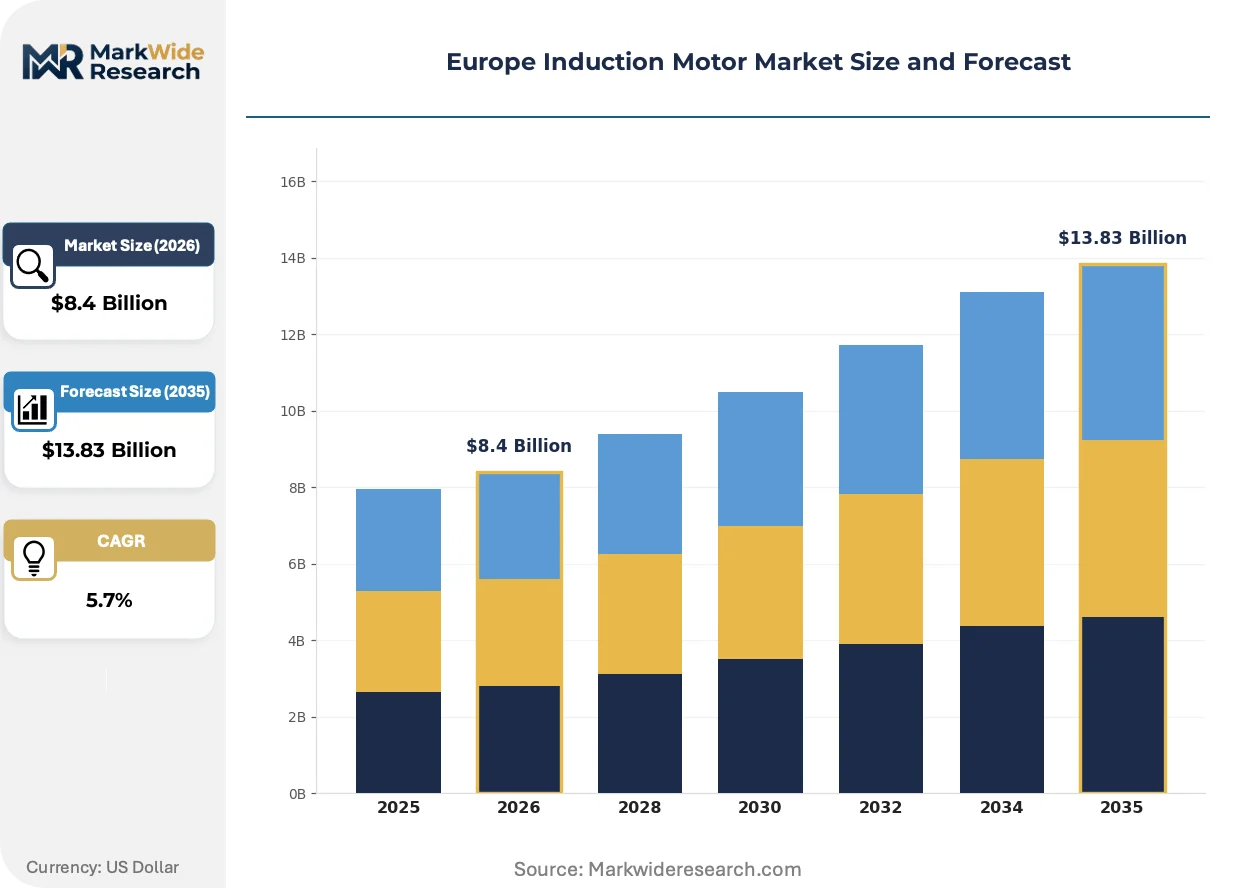
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotor, Stator, Winding, Shaft Application: Manufacturing, HVAC, Transportation, Utilities End User: Automotive, Marine, Aerospace, Agriculture Operation Mode: Single-Phase, Three-Phase, Variable Speed, Synchronous |
| Companies Covered | ABB, Regal Rexnord Corporation, Menzel Elektromotoren, Brook Crompton, CG Power & Industrial Solutions Ltd, Johnson Electric Holdings Limited, WEG, ELPROM HARMANLI, AC-MOTOREN GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Induction Motor Market Strategic Shifts & Innovations
Digitalization of motor systems and material science advances are compressing the traditional trade-off between induction robustness and permanent-magnet efficiency, while regulatory pressure accelerates specification turnover across European industrial installations.
Copper die-cast rotor technology is unifying the cost structure of high-efficiency induction motors with the performance envelope historically reserved for premium permanent-magnet designs. German pump OEMs are specifying these rotors for wastewater and chemical transfer applications where magnetic material supply risk is unacceptable. The technology is unifying two previously separate motor procurement categories into a single sourcing decision for plant engineering teams.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is forcing HVAC motor manufacturers to redesign winding insulation systems for compatibility with lower-global-warming-potential alternatives. Equipment builders in Italy and Spain are accelerating validation programs for propane and ammonia-based systems. Commercial chiller manufacturers face compressed redesign cycles to maintain CE marking validity under updated safety standards.
Buyers are consolidating vendor relationships around full-system suppliers capable of integrating motors, drives, and condition monitoring within unified digital platforms. Industrial maintenance teams in Benelux manufacturing clusters are displacing component-level procurement with lifecycle performance contracts. This concentration is most visible in Dutch chemical processing and Flemish automotive component plants where total cost of ownership modeling dominates capital allocation decisions.
Europe Induction Motor Market Segmentation
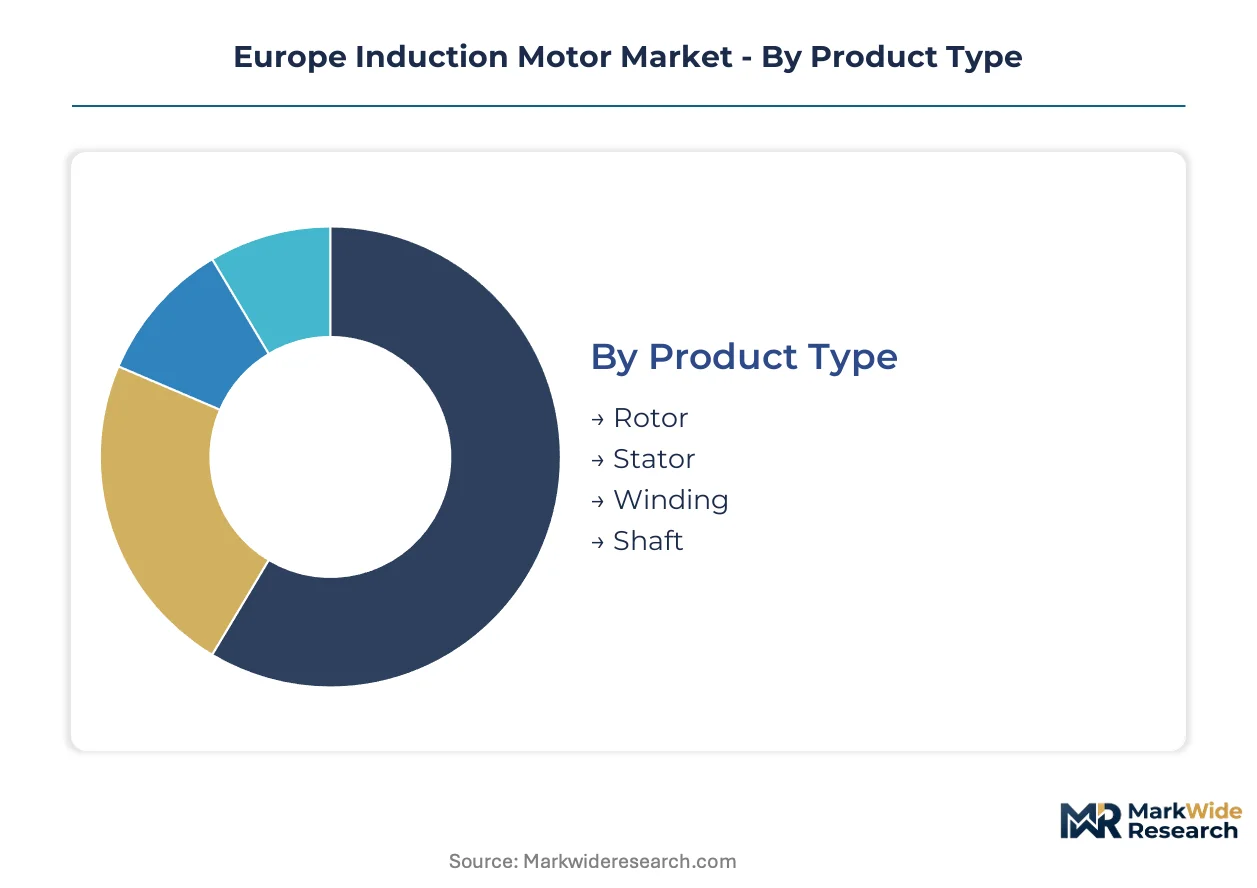
Induction motor procurement in Europe increasingly favors integrated motor-drive systems over standalone hardware. Segmentation reveals where component modularity yields to embedded architectures, particularly as German and Italian OEMs consolidate supplier relationships around full-system vendors.
Product Type:
Rotor and stator assemblies command the deepest integration relationships with European motor OEMs, while discrete winding and shaft components circulate through broader distribution channels serving maintenance and repair operations.
- Rotor:Squirrel-cage configurations dominate industrial volumes through copper die-cast bar technology that narrows efficiency gaps with permanent-magnet alternatives. German wastewater pump manufacturers specify these rotors explicitly to eliminate rare-earth supply dependencies from their procurement portfolios.
- Stator:Laminated electrical steel cores with optimized slot geometries determine motor efficiency class attainment under EU Ecodesign Directive tiers. Italian food processing equipment builders source IE4-rated stator subassemblies from captive suppliers in Emilia-Romagna manufacturing clusters.
- Winding:Insulated copper coil assemblies with bio-based varnish systems qualify for Nordic green public procurement tenders under REACH-compliant material frameworks.
- Shaft:Precision-machined carbon steel and stainless steel power transmission elements serve replacement markets across Benelux maintenance depots.
Rotor assemblies lead volumes today; stator platforms are gaining share fastest through efficiency-tier upgrade cycles.
Application:
Manufacturing and HVAC applications absorb the highest absolute motor volumes, though transportation electrification and utility infrastructure renewal are redirecting R&D investment toward heavier-duty operational envelopes.
- Manufacturing:Continuous-duty conveyor, compressor, and machine tool drives constitute the installed base backbone across German automotive component stamping and Polish battery assembly corridors. Three-phase configurations predominate where power density requirements exceed 15 kW.
- HVAC:Variable-speed induction drives for commercial building retrofits are accelerating under France's national energy efficiency mandates and the EU F-Gas Regulation's refrigerant phase-down timelines. Equipment builders in Milan and Barcelona validate propane-compatible winding insulation systems.
- Transportation:Traction motor specifications for rail and electric vehicle applications fall under Germany's KBA vehicle-type approval protocols, compressing design cycles for automotive-tier suppliers.
- Utilities:Medium-voltage pump and fan drives in water treatment and power generation facilities specify heavy-duty custom engineering from specialized European motor houses.
Manufacturing retains volume leadership; HVAC is expanding most quickly through building retrofit mandates.
End User:
Automotive and marine sectors concentrate specification premiums for precision-engineered induction systems, while aerospace and agriculture present fragmented demand patterns with divergent certification requirements.
- Automotive:Electric vehicle production lines and paint shop automation systems specify IE5 synchronous reluctance hybrid motors combining induction reliability with permanent-magnet-grade efficiency. Stuttgart and Munich OEMs consolidate vendor relationships around full-system suppliers with integrated digital twin capabilities.
- Marine:Heavy-duty custom motors for propulsion and auxiliary systems face Lloyd's Register and DNV classification society compliance alongside EU MRV emissions monitoring integration.
- Aerospace:Ground support equipment and auxiliary power unit testing rigs specify lightweight high-speed induction machines with specialized thermal management for apron operations.
- Agriculture:Irrigation pump drives and grain handling equipment circulate through agricultural machinery OEM supply chains with price-sensitive procurement protocols.
Automotive commands the steepest premium tier; marine is climbing the fastest through classification-driven specification upgrades.
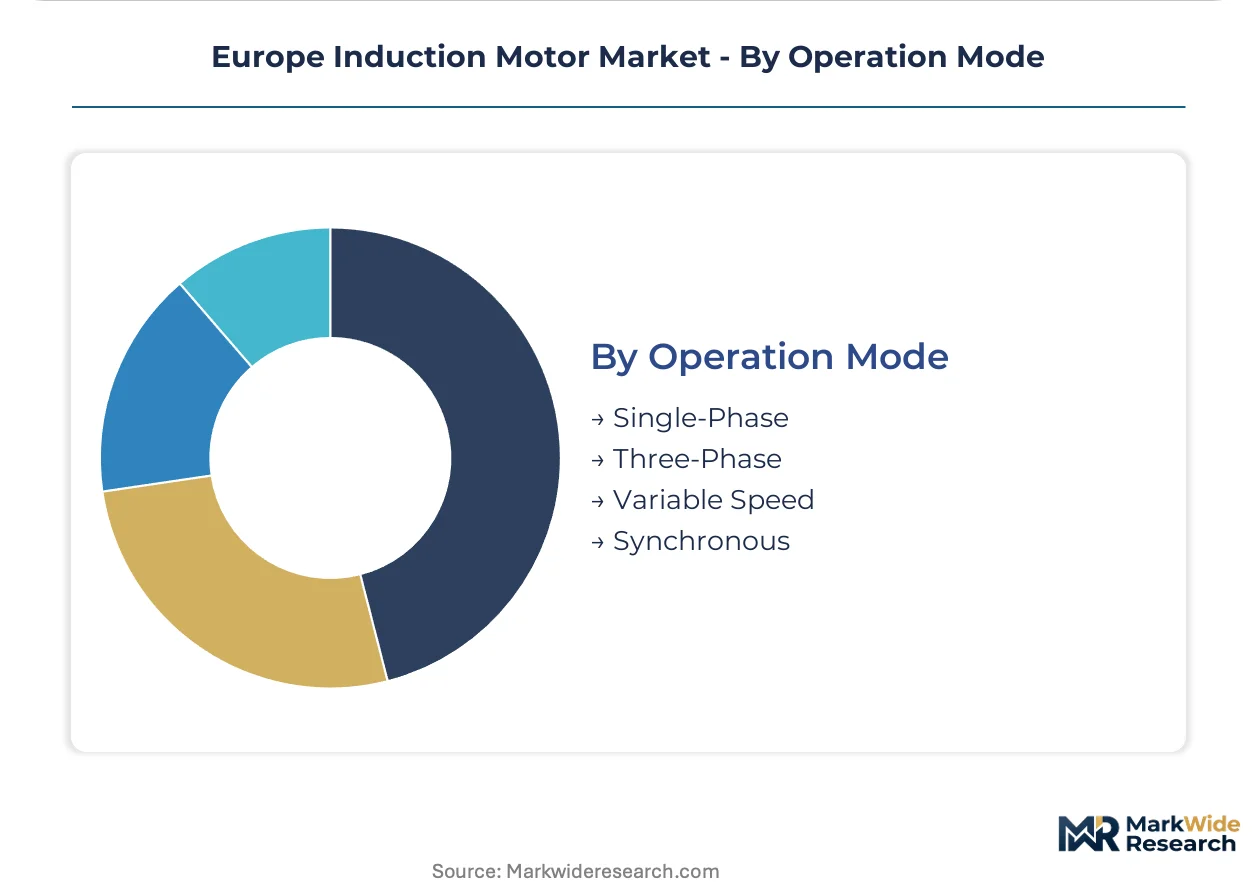
Operation Mode:
Three-phase and variable-speed architectures have displaced single-phase dominance in industrial settings, while synchronous configurations emerge at the efficiency frontier where regulatory pressure tightens most aggressively.
- Three-Phase:Industrial standard for continuous-duty manufacturing environments delivers superior power density and operational efficiency across German automation investments. The installed base concentration creates legacy retrofit complexity when upgrading to IE4 equivalents in existing VFD-controlled systems.
- Variable Speed:VFD-compatible induction motors with enhanced insulation systems capture specification wins in French commercial HVAC retrofits and Dutch chemical processing plants where operational carbon thresholds tighten.
- Single-Phase:Residential and light commercial fractional horsepower applications persist in peripheral European markets with less stringent efficiency enforcement.
- Synchronous:Synchronous reluctance and permanent magnet-assisted designs achieve IE5 efficiency classes for premium automotive and food processing specifications where continuous duty cycles dominate.
Three-phase leads installed volumes today; variable-speed configurations are gaining share fastest through building energy retrofit acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates more induction motor manufacturing capacity than any other European country, while Italy maintains stronger positions in custom heavy-duty engineering for food processing and marine applications.
Germany
Automotive paint shops and battery assembly lines in Stuttgart and Munich specify IE5 synchronous reluctance hybrid motors for continuous-duty automation. The KBA enforces vehicle-type approval protocols that compress design cycles for traction motor suppliers. Bavarian manufacturing clusters around Ingolstadt and Regensburg anchor premium motor specification wins from domestic OEMs.
Italy
Food processing equipment builders in Emilia-Romagna source IE4-rated stator subassemblies from captive regional suppliers. The EU Ecodesign Directive's tightening efficiency tiers force Milan-based HVAC manufacturers to validate propane-compatible winding insulation systems. Turin automotive component plants integrate variable-speed drives for operational carbon compliance.
France
Commercial building retrofits in Paris and Lyon accelerate demand for variable-speed induction drives under national energy efficiency mandates. The EU F-Gas Regulation's refrigerant phasedown forces equipment redesign cycles for chiller manufacturers. Grenoble's industrial automation corridor concentrates medium-voltage motor procurement for chemical processing.
Poland
Automotive component stamping and battery assembly operations in Wrocław and Łódź create demand for medium-voltage induction motors. EU Green Deal public procurement rules advantage IE4+ suppliers with verified environmental product declarations. Silesian manufacturing investments extend German supply chain relationships eastward.
Netherlands
Dutch chemical processing and Flemish automotive component plants displace component-level procurement with lifecycle performance contracts. The Machinery Directive's expanded technical file requirements lengthen time-to-market for motor-drive combinations. Rotterdam port infrastructure renewal specifies heavy-duty custom motors for cargo handling systems.
Europe Induction Motor Market Key Industry Players
German producers anchor one tier; Swiss-Swedish specialists hold premium efficiency positions through vertical integration across power electronics and motor manufacturing. The vendor base concentrates around full-system suppliers capable of integrating motors, drives, and condition monitoring within unified platforms. Two strategic archetypes dominate: diversified industrial conglomerates with captive component supply, and focused motor houses specializing in heavy-duty custom engineering. Capacity reconfiguration toward IE4 and IE5 production lines represents the primary competitive move, alongside geographic expansion of service networks across Central and Eastern European manufacturing corridors.
Within the diversified conglomerate tier, ABB exemplifies backward integration across power electronics and motor manufacturing. Menzel Elektromotoren occupies a position as a focused specialist in heavy-duty custom motor engineering for industrial clients. WEG represents the geographic expansion archetype through service network extension across Central and Eastern European corridors.
| Leading Market Players |
|---|
| ABB |
| Regal Rexnord Corporation |
| Menzel Elektromotoren |
| Brook Crompton |
| CG Power & Industrial Solutions Ltd |
| Johnson Electric Holdings Limited |
| WEG |
| ELPROM HARMANLI |
| AC-MOTOREN GmbH |
| Others |
Cost & Logistics Intelligence
Electrical machine design talent concentration in German industrial regions widens pricing spreads between premium IE5 synchronous reluctance systems and standard IE3 equivalents. Labor-cost differentials between Western European engineering hubs and emerging Polish manufacturing corridors compress margins for mid-tier assemblers while elevating technical-premium capture rates for specialized motor houses.
Pricing Analysis
Capacity additions in Poland and Czechia are reshaping price floors for medium-voltage induction motors serving automotive battery assembly corridors. Pricing stratifies across IE5 premium, IE4 standard, and IE3 economy tiers, with differentiation driven by EU Ecodesign Directive compliance tier and KBA vehicle-type approval certification. Cost compression in IE3 legacy inventories is intensifying because manufacturers must retire stock ahead of regulatory deadlines. Automotive OEMs in Stuttgart and Munich exhibit the lowest price sensitivity, while agricultural irrigation equipment distributors in peripheral markets remain most cost-responsive.
Supply Chain Analysis
Freight cost volatility between Asian electrical steel mills and European lamination facilities is amplifying working capital requirements for stator core manufacturers. Supply concentrates in Germany, Italy, and Poland, with rotor bar copper and grain-oriented electrical steel serving as critical inputs. Single-source vulnerability around rare-earth-independent copper die-cast rotor technology creates procurement risk for wastewater pump OEMs eliminating permanent-magnet dependencies. Distribution runs through captive OEM supply chains in German automotive clusters and independent distributors serving Benelux maintenance depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's manufacturing corridor expansion offers geographic arbitrage against Western European labor costs, with EU Green Deal public procurement rules creating regulatory-premium capture opportunities unavailable in non-member Eastern markets.
For Market Incumbents: To counter permanent-magnet motor substitution from East Asian suppliers, deepen backward integration into power electronics manufacturing and accelerate IE4/IE5 capacity reconfiguration in Bavarian production facilities. Channel control through integrated motor-drive-condition monitoring platforms protects specification wins in Dutch chemical processing clusters. For New Entrants and Emerging Players: Synchronous reluctance hybrid design expertise offers entry into IE5 specification gaps at Italian food processing OEMs and French HVAC retrofit programs. Polish automotive component stamping operations present the most penetrable geography, with lifecycle performance contracting as the preferred go-to-market mechanism versus component transactional sales. For Investors and Strategic Acquirers: Industrial conglomerates with captive power electronics divisions are the most active acquirer in this space, targeting heavy-duty custom engineering specialists with verified environmental product declarations. Five-to-ten year viability hinges on REACH-compliant material transition completion. Monitor ECHA restricted substance list amendments as the critical inflection signal for stranded legacy inventory risk.| Strategic Initiative | Industry Significance |
|---|---|
| IE5 Production Line Conversion | EU Ecodesign Directive deadlines force German manufacturers to reconfigure legacy IE2 capacity or face market exclusion. |
| Copper Die-Cast Rotor Scale-Up | Eliminates rare-earth supply dependencies for wastewater pump OEMs specifying KBA-compliant traction alternatives. |
| Digital Twin Platform Integration | Enables recurring revenue capture through predictive maintenance contracts in Benelux chemical processing installations. |
| Polish Service Network Expansion | WEG and competitors extend coverage to Wrocław battery assembly corridors where medium-voltage demand concentrates. |
| REACH-Compliant Insulation Transition | Bio-based varnish systems qualify Nordic municipal tender winners under green public procurement frameworks. |
Research Approach
Coverage spans Germany, Italy, France, Poland, and Benelux, with primary inputs from each region triangulated against secondary validation. Motor OEM product managers, automotive Tier 1 procurement directors, HVAC equipment builder engineers, and industrial maintenance heads supplied forward-looking specification data. Secondary sources include EU Ecodesign Directive efficiency tier documentation, ECHA REACH substance restriction updates, KBA vehicle-type approval protocols, and customs trade flows for electrical steel and copper rotor bar materials. Bottom-up motor shipment volumes reconcile with top-down industrial automation investment tracking.
Granularity extends to IE efficiency class, rotor technology type, and end-use application across the projection horizon. Segmentation dimensions encompass product type, application vertical, end-user sector, and operation mode, with geographic production cluster as an additional modeled layer. CAGRs derive from installed base replacement cycles, regulatory phase-in schedules, and automotive electrification capital expenditure trajectories. Forecast inputs incorporate EU F-Gas Regulation amendment timelines and France's national building renovation mandate enforcement intensity.
The model holds under steady EU regulatory enforcement and stable copper-electrical steel price corridors; deviation in REACH substance restrictions or KBA protocol revisions would shift specification demand patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Europe Tank Insulation Market
Industrial Motors
North America Induction Motor Market
Industrial Motors
Power Stacker Market
Industrial Motors
China AC Motor Market
Industrial Motors
Oil Mist Collector Market
Industrial Motors
Cryogenic Air Separation Units (Asus) Market
Industrial Motors
Fractional Horsepower Motor Market
Industrial Motors
Industrial Personnel and Burden Carriers [Electric] Market
Industrial Motors
North America Refrigeration Oil Market
Industrial Motors
AC Motor Market
Industrial Motors
Asia-Pacific Induction Motor Market
Industrial Motors
Germany AC Motor Market
Industrial Motors
HVAC Motors Market
Industrial Motors
Brushless DC Motor Market
Industrial Motors
Industrial Motor Brakes Market
Industrial Motors
Global Low Voltage Motors Market