
 Power Line Filters Market | 2026-2036
Power Line Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Power Line Filters Market Analytics
Buyer concentration in the data center segment is shifting as hyperscale operators consolidate procurement while mid-tier colocation providers fragment across regional suppliers. Schroeder Industries leverages captive ferrite-core manufacturing to anchor North American supply relationships. SCHURTER Group competes through IEC 60939-certified product families that sustain pricing power in European medical and industrial channels. Delta Electronics, Inc. dominates Asia-Pacific volume through backward integration into magnetics and capacitor wound components.
Power line filters are electromagnetic interference suppression devices constructed from inductive chokes, capacitive shunts, and ferrite or nanocrystalline cores, typically rated for attenuation between 150 kHz and 30 MHz to prevent conducted noise from disrupting sensitive electronics or polluting utility grids. Passive filter assemblies occupy the largest value share due to their maturity in industrial motor-drive and consumer-appliance applications, though hybrid filter architectures are capturing margin pools in renewable-energy inverter installations where both harmonic correction and EMI attenuation prove necessary. Active filter modules lead growth in telecommunications and data center power distribution units because real-time digital control enables adaptive suppression across variable load profiles without manual retuning.
FCC Part 15 conducted-emission limits in the United States and ECHA RoHS substance restrictions in Europe compel manufacturers to redesign core materials and winding geometries, while China's GB 17625 EMC standards for low-voltage electrical equipment tighten market-access requirements for imported filter assemblies. Stakeholders must monitor evolving regional certification timelines and pre-position compliant component inventories before regulatory transition periods close.
Market Dynamics
Data center operators are consolidating procurement power while tightening emission specifications, forcing filter manufacturers to reconfigure supply chains around captive ferrite production and pre-certified component libraries.
Growth Catalysts
- FCC Part 15 conducted-emission limits:United States data center operators are expanding EMI-suppression filter procurement to meet federal emission ceilings for server power supplies.
- MIIT grid-harmonic standards:China's eastern manufacturing corridor is tightening compliance requirements for industrial motor drives and renewable-energy inverters.
- RoHS-compliant ferrite substitution:Germany's ECHA REACH restrictions are accelerating material transitions toward ceramic and nanocrystalline core alternatives.
Market Restraints
- Raw material concentration:Rare-earth ferrite precursors face supply bottlenecks concentrated in Chinese processing facilities, creating input cost volatility.
- Technical bandwidth ceilings:Passive filter architectures hit attenuation limits above 30 MHz, constraining effectiveness for wideband switching applications.
- Regulatory fragmentation:Divergent EMC certification timelines between FCC, ECHA, and MIIT regimes force redundant testing inventories.
Strategic Opportunities
- Hybrid filter architectures:Renewable-energy inverter installations are creating margin pools where harmonic correction and EMI suppression converge.
- Active filter modules:Telecommunications power distribution units are adopting real-time digital control for adaptive suppression across variable loads.
- Medical device channels:IEC 60939-certified product families are sustaining pricing power in European diagnostic equipment supply chains.
Industry Challenges
- Magnetics engineering scarcity:Specialized winding geometry design talent is concentrated among aging practitioner cohorts in Japanese and German component houses.
- Certification timeline compression:Pre-positioning compliant inventories before regulatory transition windows requires working capital intensity.
- Legacy system integration friction:Retrofitting active filters into existing motor-drive installations demands custom interface engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Line Filters Market |
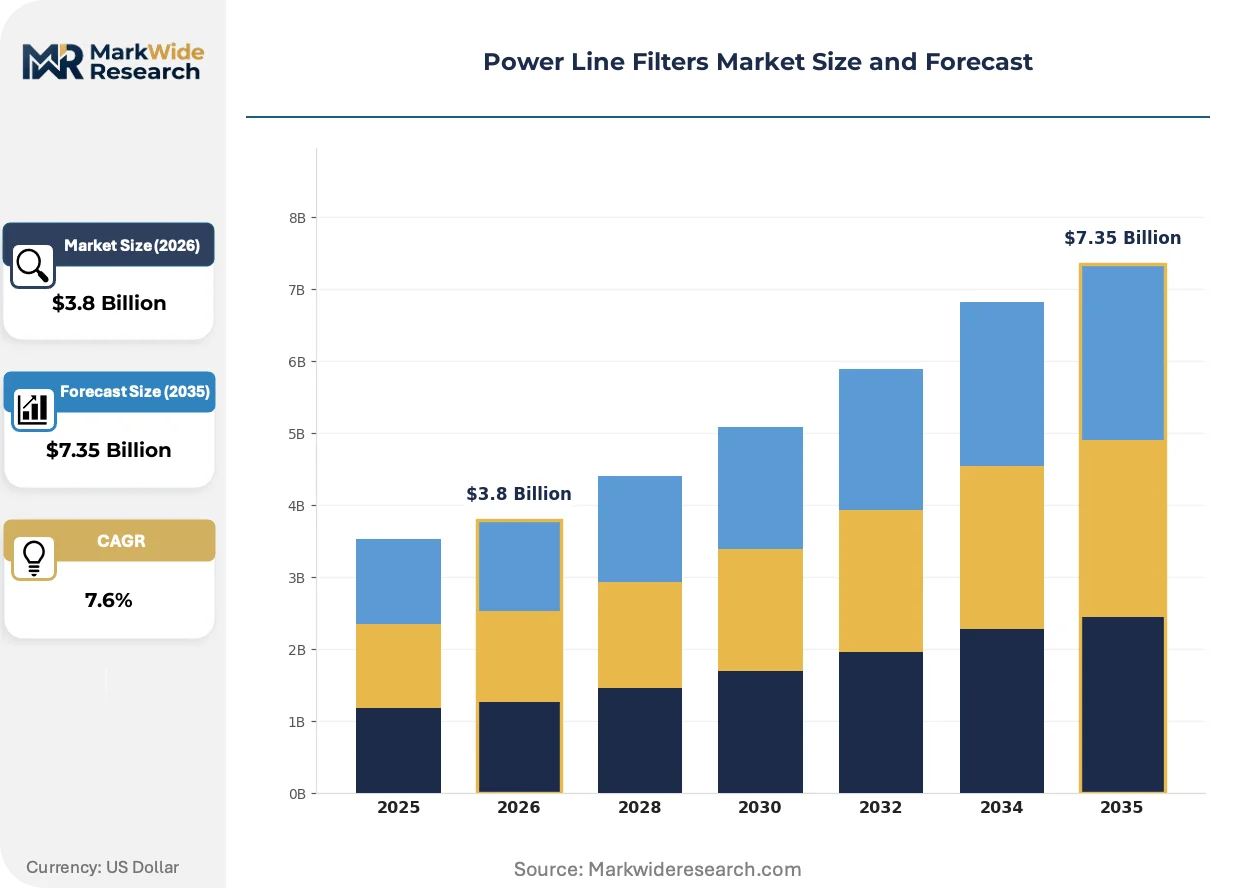
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Filters, Passive Filters, Hybrid Filters, Line Reactors Technology: EMI/RFI Suppression, Surge Protection, Noise Reduction, Signal Conditioning End User: Power Generation, Telecommunications, Industrial Automation, Consumer Electronics Application: Data Centers, Renewable Energy, Medical Equipment, Manufacturing |
| Companies Covered | Schroeder Industries, Genisco Filter, Power Systems & Controls, Inc, Delta Electronics, Inc., SCHURTER Group, Curtis Industries, Astrodyne TDI, Captor Corporation, PLC Hardware, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Line Filters Market Evolving Landscape
Filter architectures are bifurcating between commodity passive assemblies and digitally controlled active systems, with material science advances in nanocrystalline cores enabling performance tier compression.
Nanocrystalline ribbon cores are integrating high-permeability magnetic properties with mechanical flexibility for compact three-phase filter designs. Wind turbine inverter manufacturers are adopting these materials at accelerating rates. The technology is integrating harmonic attenuation and EMI suppression into single magnetic components, collapsing bill-of-materials counts.
ECHA REACH substance restrictions are forcing redesigns of ferrite core dopants and winding insulation chemistries. Manufacturers are qualifying alternative rare-earth formulations ahead of sunset dates. Medical and industrial channels in Germany and France are absorbing premium pricing for pre-certified RoHS-compliant assemblies.
Hyperscale operators are consolidating direct procurement relationships while disintermediating traditional distribution channels. Mid-tier colocation providers are fragmenting across regional suppliers with shorter qualification cycles. This concentration-fragmentation split is most visible in United States and Chinese data center clusters.
Power Line Filters Market Segmentation
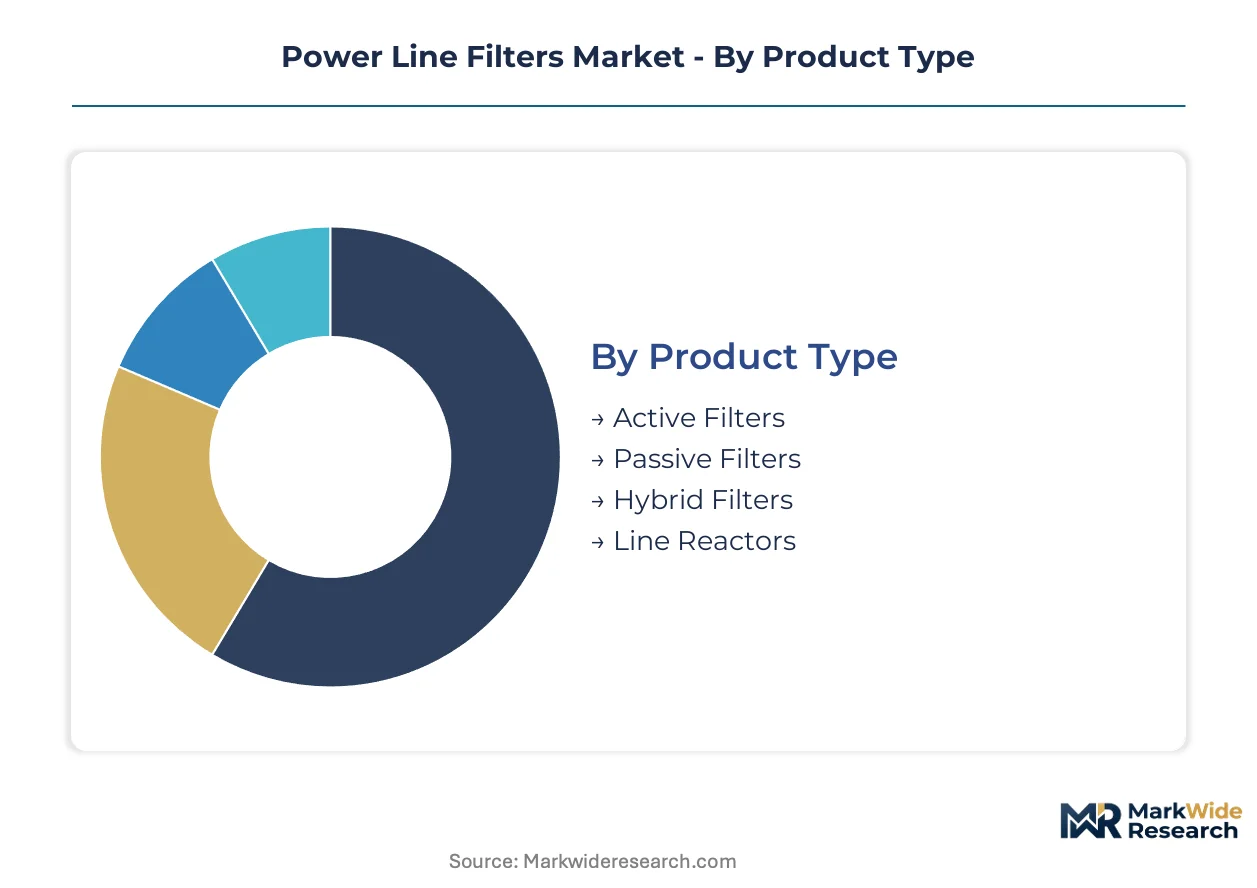
Power line filter procurement splits across fundamentally different technical architectures and compliance regimes. Buyers weigh passive cost efficiency against active adaptability, while end-use applications impose divergent bandwidth and certification requirements.
Product Type:
Capital intensity and performance thresholds drive buyer selection between legacy passive assemblies and digitally controlled alternatives.
- Passive Filters:Inductive choke and capacitive shunt assemblies with ferrite or nanocrystalline cores dominate industrial motor-drive and consumer-appliance installations. Demand concentrates in China's eastern manufacturing corridor where MIIT-mandated grid-harmonic standards tighten for industrial equipment.
- Active Filters:Real-time digital control modules enable adaptive EMI suppression across variable load profiles without manual retuning. Telecommunications power distribution units and hyperscale data centers are absorbing these units fastest as FCC Part 15 emission ceilings tighten.
- Hybrid Filters:Combined harmonic correction and EMI attenuation architectures for renewable-energy inverter installations.
- Line Reactors:Inductive filtering components for motor-drive harmonic mitigation in heavy industrial settings.
Volume sits with Passive Filters; growth tilts toward Active Filters.
Technology:
Application-specific noise profiles determine which suppression mechanism buyers prioritize.
- EMI/RFI Suppression:Conducted noise attenuation between 150 kHz and 30 MHz using ferrite cores and wound components. Data center server power supplies in the United States are expanding procurement to meet FCC conducted-emission limits.
- Surge Protection:Transient voltage suppression for grid-connected industrial and medical equipment.
- Noise Reduction:Broadband filtering for sensitive diagnostic and measurement instrumentation.
- Signal Conditioning:Precision filtering for telecommunications and control systems requiring waveform integrity.
EMI/RFI Suppression commands installed base; Surge Protection is climbing the fastest on renewable grid integration.
End User:
Regulatory exposure and uptime requirements create divergent procurement specifications across verticals.
- Industrial Automation:Motor-drive and robotics installations requiring harmonic compliance and EMI containment. Germany's ECHA REACH restrictions are accelerating substitution toward RoHS-compliant ferrite and ceramic core materials.
- Telecommunications:Base station and data transmission infrastructure with variable load profiles demanding adaptive filtering.
- Power Generation:Grid-tied inverter and converter installations for utility-scale and distributed generation.
- Consumer Electronics:Appliance and device manufacturers with cost-optimized passive filter requirements.
Industrial Automation anchors revenue; Telecommunications shows steepest expansion trajectory on 5G infrastructure buildouts.
Application:
Certification tier and volume scale fragment procurement patterns across installation types.
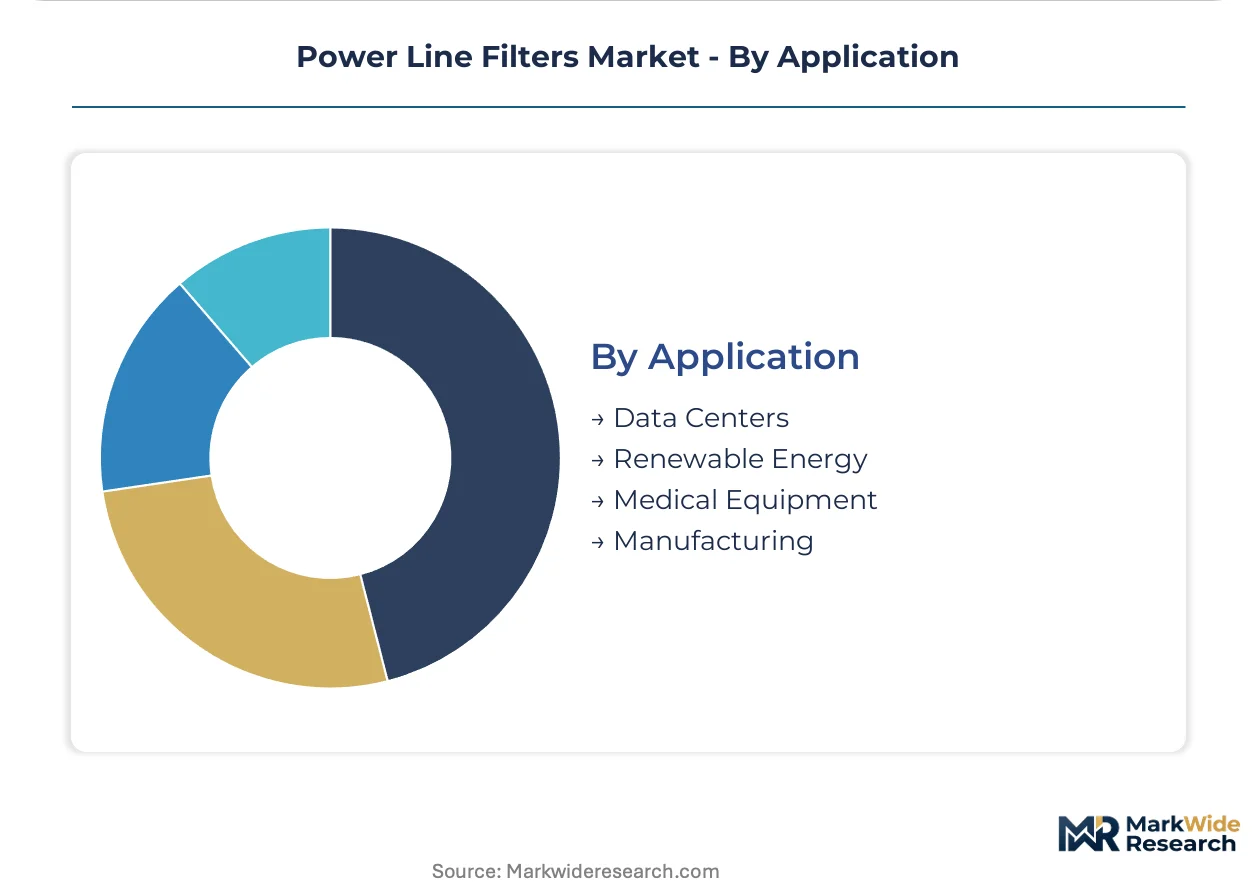
- Data Centers:Hyperscale operators consolidate direct procurement of IEC 60939-certified assemblies while mid-tier colocation providers fragment across regional suppliers. FCC Part 15 compliance mandates are tightening specification windows.
- Renewable Energy:Wind and solar inverter manufacturers are adopting nanocrystalline ribbon cores for compact three-phase designs with combined harmonic and EMI functionality.
- Medical Equipment:European diagnostic equipment supply chains absorb premium pricing for pre-certified RoHS-compliant assemblies under ECHA substance restrictions.
- Manufacturing:Broad industrial motor-drive and automation installations with standard EMI compliance requirements.
Data Centers concentrate value; Renewable Energy is gaining share fastest on inverter deployment rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth ferrite processing facilities in Jiangxi and Hunan provinces anchor Asia-Pacific supply chains, while North American and European demand centers drive specification tightening through divergent regulatory regimes.
United States
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth are consolidating direct procurement of FCC Part 15-compliant filter assemblies. The FCC conducted-emission ceiling enforcement is tightening specification windows for server power supply manufacturers. Ashburn-Loudoun County clusters absorb premium pricing for pre-certified IEC 60939 assemblies.
Germany
Industrial automation OEMs in Baden-Württemberg and Bavaria are accelerating RoHS-compliant ferrite substitution under ECHA REACH substance restrictions. The ECHA authorization list sunset dates are forcing redesigns of core dopants and winding insulation chemistries. Stuttgart-Munich industrial corridors absorb 25-30% cost premiums for pre-certified medical-grade assemblies.
China
Wind turbine inverter manufacturers in Jiangsu and Zhejiang provinces are adopting nanocrystalline ribbon cores for compact three-phase designs. MIIT-mandated GB 17625 grid-harmonic standards are tightening compliance requirements for industrial motor drives. Suzhou-Wuxi manufacturing clusters dominate domestic filter assembly capacity.
Japan
Automotive inverter suppliers in Aichi and Shizuoka prefectures are qualifying next-generation nanocrystalline core materials for EV powertrain applications. METI energy efficiency standards are accelerating EMI suppression requirements for high-frequency switching systems. Nagoya-Toyota industrial zones concentrate precision magnetics engineering talent.
India
Telecommunications infrastructure deployers in Karnataka and Maharashtra are expanding active filter procurement for 5G base station power distribution units. BIS EMC certification requirements are tightening market access for imported filter assemblies. Bengaluru-Pune technology corridors drive demand for adaptive suppression modules.
Power Line Filters Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digitally controlled active architectures and nanocrystalline material integration. The vendor base splits between captive ferrite manufacturers and specialized filter assemblers sourcing wound components externally. Three archetypes dominate: vertically integrated magnetics houses, certification-focused European specialists, and Asia-Pacific volume producers with backward integration into capacitor and core production. Competitive moves center on pre-certification inventory positioning ahead of regulatory transition windows and captive supply agreements for rare-earth ferrite precursors.
Within the captive magnetics tier, Schroeder Industries and Delta Electronics, Inc. exemplify divergent geographic anchoring strategies—North American ferrite-core integration versus Asia-Pacific wound-component control. SCHURTER Group occupies a position representing European certification-focused specialists serving medical and industrial channels with IEC 60939-aligned product families. These three entities illustrate how supply chain configuration and regulatory pre-positioning separate premium-tier positioning from commodity assembly competition.
| Leading Market Players |
|---|
| Schroeder Industries |
| Genisco Filter |
| Power Systems & Controls, Inc |
| Delta Electronics, Inc. |
| SCHURTER Group |
| Curtis Industries |
| Astrodyne TDI |
| Captor Corporation |
| PLC Hardware |
| Others |
Value Network & Pricing Analysis
Nanocrystalline ribbon core adoption is compressing performance tiers while concentrating procurement leverage among wind turbine inverter manufacturers in Jiangsu and Zhejiang provinces, simultaneously raising material costs and rewarding suppliers with captive magnetics capabilities.
Pricing Analysis
Warranty and certification bundling separates premium IEC 60939-certified assemblies from unbundled commodity passive filters in industrial channels. Three-tier pricing structure across medical-grade, industrial-certified, and economy passive tiers reflects divergence in after-sales service inclusion and RoHS pre-certification status. Cost compression in economy passive tiers intensifies as Chinese wound-component producers expand capacity. Hyperscale data center operators exhibit lowest price sensitivity given uptime requirements, while mid-tier colocation providers drive hard bargaining on standard EMI assemblies.
Supply Chain Analysis
Regional distribution centers in Suzhou-Wuxi clusters feed hub-and-spoke patterns across China's eastern manufacturing corridor before final assembly integration. Rare-earth ferrite processing concentrates in Jiangxi and Hunan provinces, with wound capacitor production anchored in Taiwan and South Korea. Supply chain risk centers on single-source vulnerability for nanocrystalline ribbon precursor alloys. Distribution runs through direct procurement relationships with hyperscale operators alongside traditional industrial distribution channels serving fragmented mid-tier buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active filter architectures are displacing legacy passive assemblies in telecommunications and data center applications, compressing the window for incumbents to reconfigure magnetics capabilities.
For Market Incumbents: Anticipate margin erosion in standard passive tiers by accelerating backward integration into ferrite-core production and pre-positioning RoHS-compliant inventories ahead of ECHA REACH sunset dates. Certification investment in IEC 60939-aligned product families defends pricing power in European medical channels against emerging Asian competitors.
For New Entrants and Emerging Players: Digitally controlled active filter modules offer technology-first entry into 5G telecommunications infrastructure where real-time adaptive suppression commands premium positioning. White-space concentration sits with mid-tier Indian data center operators seeking shorter qualification cycles than hyperscale procurement processes permit. Go-to-market execution should leverage BIS EMC certification partnerships to overcome import barriers.
For Investors and Strategic Acquirers: Re-rating potential sits with captive magnetics specialists given nanocrystalline core integration requirements and scarcity of precision winding engineering talent. Long-term viability favors vertically integrated producers with upstream ferrite control and downstream filter assembly capabilities. Monitor MIIT enforcement patterns on GB 17625 grid-harmonic standards as inflection signal for Chinese domestic demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Ferrite Core Integration | Schroeder Industries anchors North American supply relationships through in-house magnetics production. |
| Pre-Certification Inventory Positioning | ECHA REACH compliance deadlines force working capital deployment ahead of regulatory transitions. |
| Active Filter Module Development | Real-time digital control captures telecommunications margin pools from legacy passive displacement. |
| Hybrid Architecture Deployment | Renewable-energy inverter manufacturers consolidate harmonic and EMI functions into single components. |
| Regional Distribution Hub Expansion | Suzhou-Wuxi clusters consolidate final assembly capacity for MIIT-mandated compliance requirements. |
Research Methodology
Document review covered customs trade data, MIIT regulatory filings, and ECHA substance restriction schedules, complemented by interviews with magnetics engineering directors, data center procurement officers, wind turbine inverter supply chain managers, and industrial automation OEM sourcing leads. Secondary validation drew from SEC 10-K filings, IEC certification databases, and rare-earth trade flow statistics. Bottom-up segment sizing triangulated against top-down macroeconomic drivers.
Installed base and revenue estimates emerged from modeling across product type, technology mechanism, end-user vertical, and application installation scale throughout the forecast period. CAGRs derived from regression analysis against regulatory enforcement timelines and inverter deployment trajectories. Nanocrystalline material adoption curves and FCC Part 15 compliance cost pass-through assumptions shaped segment-specific growth differentials.
Forecast precision tightens around the base case; tail outcomes carry wider variance under raw material supply disruption or accelerated ECHA substance restriction timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Global Magnetic Circuit Breaker Market
Electrical Power Equipment
Alternating Current (AC) Electric Drives Market
Electrical Power Equipment
Optical Current Transformer Market
Electrical Power Equipment
HVDC Converter Station Market
Electrical Power Equipment
Battery Charger Market
Electrical Power Equipment
Fault Circuit Indicator Market
Electrical Power Equipment
Nuclear Cables Sales Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Cables Market
Electrical Power Equipment
India Gas Insulated Switchgear Market
Electrical Power Equipment
Substation Market
Electrical Power Equipment
Fuse Link Market
Electrical Power Equipment
Alternators Market
Electrical Power Equipment
Europe Electric Space Heaters Market
Electrical Power Equipment
Subsea Cables Equipment Market
Electrical Power Equipment
Global Surge Arrester Market
Electrical Power Equipment
Magnetic Optical Current Transformer Market