
 Electrical Steel for Electric Vehicle Market | 2026-2036
Electrical Steel for Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Steel for Electric Vehicle Market Insights
Asset-light leasing arrangements for specialty steel processing equipment are narrowing the capital barrier for mid-tier producers seeking entry into electrical steel supply. Nippon Steel Corporation leverages its integrated R&D-to-melting infrastructure to sustain premium-grade silicon steel output for high-efficiency EV motors. POSCO anchors its position through captive raw material sourcing and dedicated cold-rolling capacity in Korea. ArcelorMittal competes across multiple continents with standardized product platforms that reduce customer qualification timelines.
Electrical steel for electric vehicles is a ferrous alloy containing silicon in the range of 0.5% to 6.5%, manufactured through controlled cold rolling and annealing to achieve specific magnetic properties including low core loss and high permeability for efficient energy conversion in traction motors. The material's primary commercial purpose is to minimize hysteresis and eddy current losses in the laminated cores of EV drive motors, directly influencing vehicle range and thermal management. Silicon steel dominates current volume flows due to its established supply base and cost structure, while grain oriented grades command concentrated margin pools in high-performance permanent magnet motor architectures. Specialty alloys represent the fastest-growing product category as OEMs push motor operating frequencies above 10 kHz to achieve power density targets.
The EU Green Deal and REACH frameworks in Europe, EPA fuel economy standards in the United States, and MIIT energy efficiency mandates in China collectively enforce escalating performance thresholds for EV drivetrain components. These regulations translate into material specifications that disqualify lower-grade electrical steels from qualified supplier lists, effectively filtering market access by technical capability rather than price alone. Stakeholders must monitor the divergence between regional efficiency test cycles and the actual magnetic loading profiles those cycles impose on motor laminations.
Market Dynamics
High-frequency motor architectures above 10 kHz are compressing magnetic core tolerances and forcing alloy reformulation across the supply base. This technical inflection is restructuring procurement relationships between steel mills and EV drivetrain integrators.
Growth Catalysts
- ICE Phase-Out Mandates:National combustion engine bans in Germany, France, and the United Kingdom are accelerating EV motor platform deployment and pulling premium-grade silicon steel through qualified supplier channels.
- China MIIT Efficiency Mandates:Domestic energy efficiency thresholds for NEV drivetrain components are disqualifying lower-grade electrical steels from state-supported OEM supply lists.
- Permanent Magnet Motor Architectures:High-performance grain-oriented grades are capturing concentrated margin pools as traction motor power density targets tighten across passenger EV platforms.
Market Restraints
- Silicon Metal Price Volatility:Ferrosilicon input costs swing with energy-intensive smelting economics, compressing margin predictability for non-integrated cold-rolling operations.
- Korean Supply Concentration:Captive raw material sourcing and dedicated annealing capacity in Korea create dependency risk for European and North American motor laminators lacking qualified alternative sources.
- Thin-Gauge Rolling Limitations:Sub-0.20 mm thickness production yields remain technically constrained, capping supply elasticity for next-generation high-frequency motor designs.
Strategic Opportunities
- India PLI Scheme for Auto Components:Production-linked incentives for domestic EV component manufacturing are opening qualified supplier qualification pathways for electrical steel processors.
- 800-Volt Traction Systems:Higher voltage architectures are expanding addressable demand for specialty alloy grades with superior high-frequency magnetic performance.
- Asset-Light Processing Leasing:Third-party toll annealing and slitting services are lowering capital barriers for mid-tier steel producers seeking EV-grade certification.
Industry Challenges
- Metallurgical Talent Scarcity:Deep expertise in controlled atmosphere annealing and texture engineering is concentrated among retiring specialists, constraining quality consistency at scale-up operations.
- OEM Qualification Timelines:Motor lamination validation cycles spanning 18-24 months lock out unproven suppliers even when technical specifications are met.
- Traceability System Integration:Batch-level magnetic property documentation requirements are forcing legacy ERP upgrades at smaller rolling mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Steel for Electric Vehicle Market |
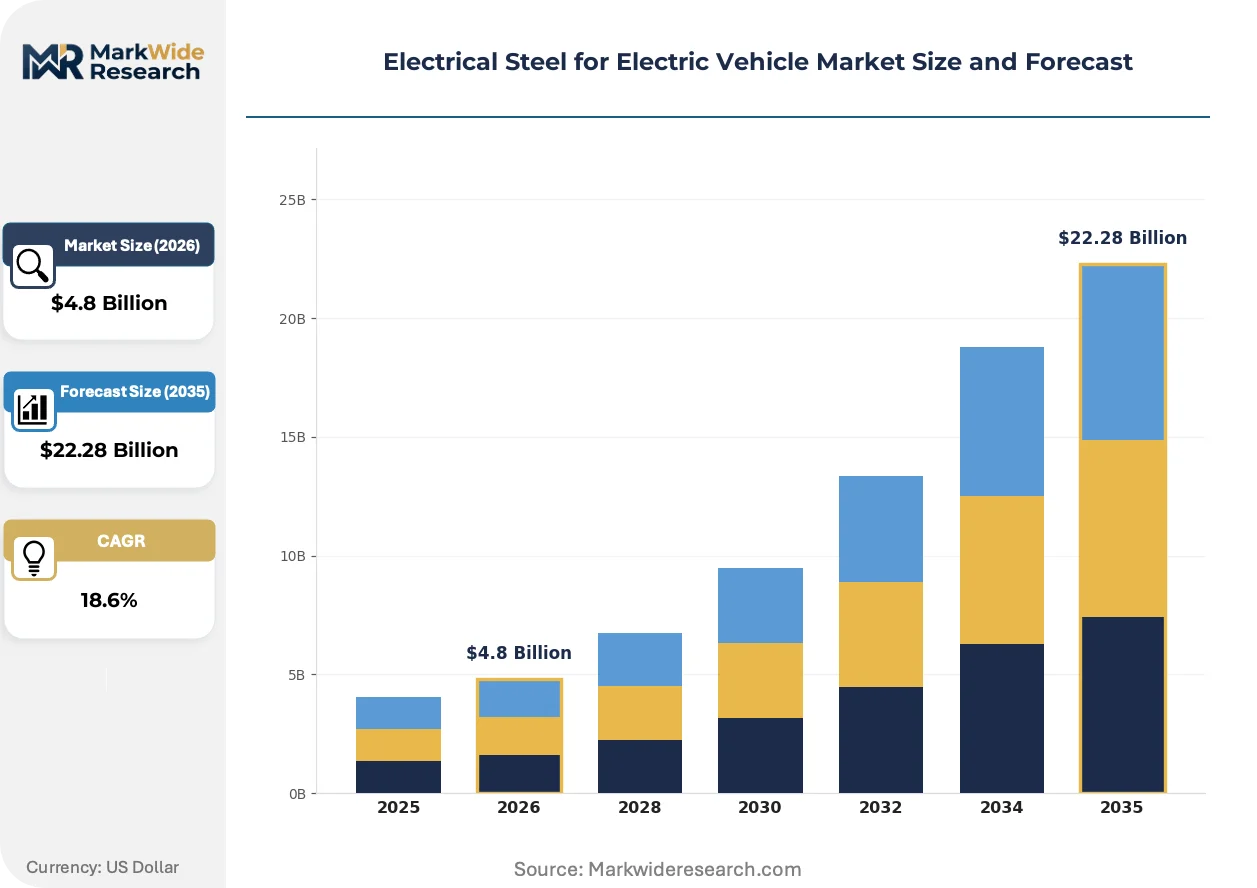
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Steel, Non-Silicon Steel, Specialty Alloys, Grain Oriented Application: Magnetic Components, Motors, Transformers, Inductors End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Manufacturing Stage: Raw Material, Processing, Finishing, Quality Control |
| Companies Covered | ArcelorMittal, China Baowu Steel Group, Nippon Steel Corporation, POSCO, JFE Steel Corporation, Thyssenkrupp, Cleveland-Cliffs, Tata Steel, Voestalpine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Steel for Electric Vehicle Market Trends and Innovations
Motor operating frequency thresholds are rewriting material specification sheets and collapsing traditional grade boundaries. Alloy designers are responding with unconventional silicon-content formulations and hybrid processing routes.
Amorphous metal ribbon is hybridizing with conventional silicon steel laminations in high-efficiency motor cores. Tier 1 suppliers in Germany and Japan are piloting dissimilar-material stacks for next-generation traction motors. This hybridizing approach preserves cost structure while capturing core loss reductions that pure amorphous designs cannot achieve at volume.
REACH framework amendments in Europe are tightening substance restrictions on process chemicals used in electrical steel surface insulation coatings. The European Chemicals Agency is expanding SVHC candidate list scrutiny toward phosphate-based treatments common in grain-oriented grades. Motor laminators serving EU-based OEMs are accelerating qualification of chrome-free and cobalt-free coating alternatives ahead of anticipated sunset dates.
Long-term offtake contracting is displacing spot-market purchasing among high-volume EV motor manufacturers. Procurement teams at major drivetrain integrators in China and the United States are locking three-to-five-year silicon steel supply agreements with fixed-grade, variable-volume structures. This shift is most pronounced in battery-electric passenger vehicle platforms where motor design freeze timelines align with steel mill capacity planning cycles.
Electrical Steel for Electric Vehicle Market Segmentation
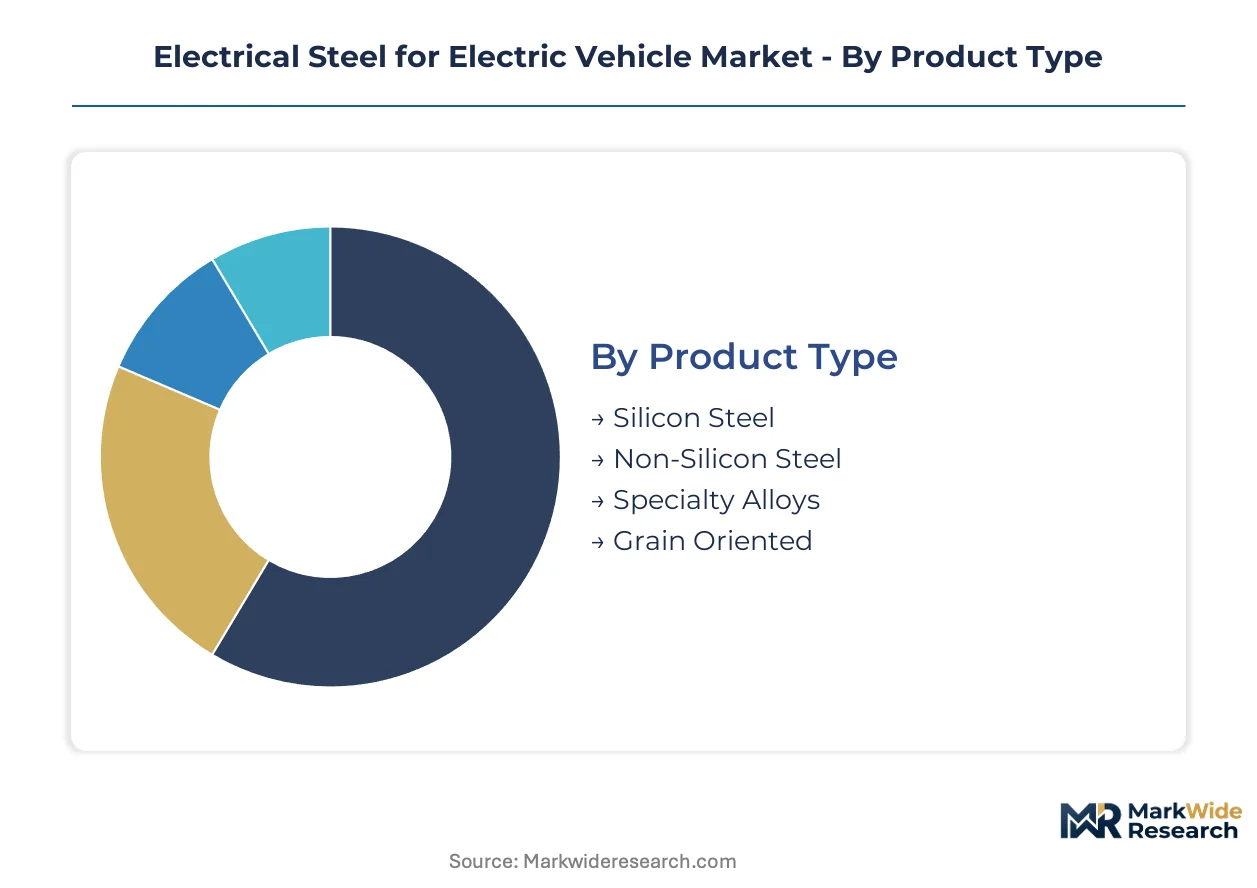
Electrical steel procurement cycles vary dramatically across product grades and end-use applications. Motor laminators qualify materials on 18-24 month timelines, while transformer and inductor specifications refresh on slower cadences. Understanding these velocity differentials shapes inventory positioning and supplier relationship investments.
Product Type:
Cycle times compress as silicon content rises and gauge thickness falls. Grain oriented grades demand the longest qualification periods due to texture engineering sensitivity, while commodity silicon steel turns on annual contract cycles.
- Silicon Steel:Ferrous alloy containing 0.5% to 6.5% silicon, manufactured through controlled cold rolling and annealing to achieve specific magnetic properties including low core loss and high permeability. Demand concentrates in China, Germany, and the United States as domestic EV motor manufacturing capacity scales, with MIIT efficiency mandates in China filtering lower-grade materials from state-supported OEM supply lists.
- Specialty Alloys:Unconventional silicon-content formulations and hybrid processing routes engineered for motor operating frequencies above 10 kHz. Expansion concentrates in 800-volt traction system architectures where superior high-frequency magnetic performance commands premium positioning.
- Non-Silicon Steel:Lower-silicon ferrous grades serving cost-sensitive auxiliary motor applications and legacy drivetrain platforms.
- Grain Oriented:Highly textured silicon steel with magnetic properties optimized along the rolling direction for minimal core loss in high-efficiency permanent magnet motor architectures.
Silicon steel dominates installed base. Specialty alloys are where expansion concentrates.
Application:
Cost tiers separate qualification-intensive traction motor laminations from standard-grade auxiliary applications. Premium pricing attaches to materials surviving thermal cycling validation above 180°C.
- Motors:Laminated core material for EV traction motors, inverters, and auxiliary drive systems where hysteresis and eddy current losses directly influence vehicle range. Demand clusters in battery-electric passenger vehicle platforms across China, Germany, and the United States as ICE phase-out mandates accelerate motor platform deployment.
- Magnetic Components:Precision-engineered laminations for sensors, actuators, and electromagnetic interference shielding in high-voltage architectures. Growth tracks 800-volt system adoption where magnetic component density and thermal management requirements intensify.
- Transformers:Core material for onboard charging and DC-DC conversion systems in EV power electronics.
- Inductors:Wound core applications in filtering and energy storage subsystems within drivetrain inverters.
Motors command the highest material specification stringency. Magnetic components are gaining share fastest as sensor integration proliferates.
End User:
Volume concentration sits with vertically integrated OEMs, while margin pools concentrate among specialized Tier-1 laminators serving multiple platforms.
- OEMs:Automakers with captive motor manufacturing operations in China, Germany, and the United States, qualifying electrical steel through proprietary lamination designs and thermal cycling protocols. Long-term offtake contracting with three-to-five-year structures is displacing spot-market purchasing as motor design freeze timelines align with steel mill capacity planning.
- Tier-1 Suppliers:Independent drivetrain integrators supplying multiple OEM platforms from standardized lamination architectures. Asset-light processing leasing arrangements are narrowing capital barriers for mid-tier producers seeking EV-grade certification through third-party toll annealing services.
- Vehicle Assemblers:Contract manufacturers and platform-sharing partnerships without captive motor production capabilities.
- Aftermarket Providers:Replacement motor core suppliers serving repair and refurbishment channels for legacy EV fleets.
OEMs dominate qualified supplier list access. Tier-1 suppliers are where procurement flexibility concentrates.
Manufacturing Stage:
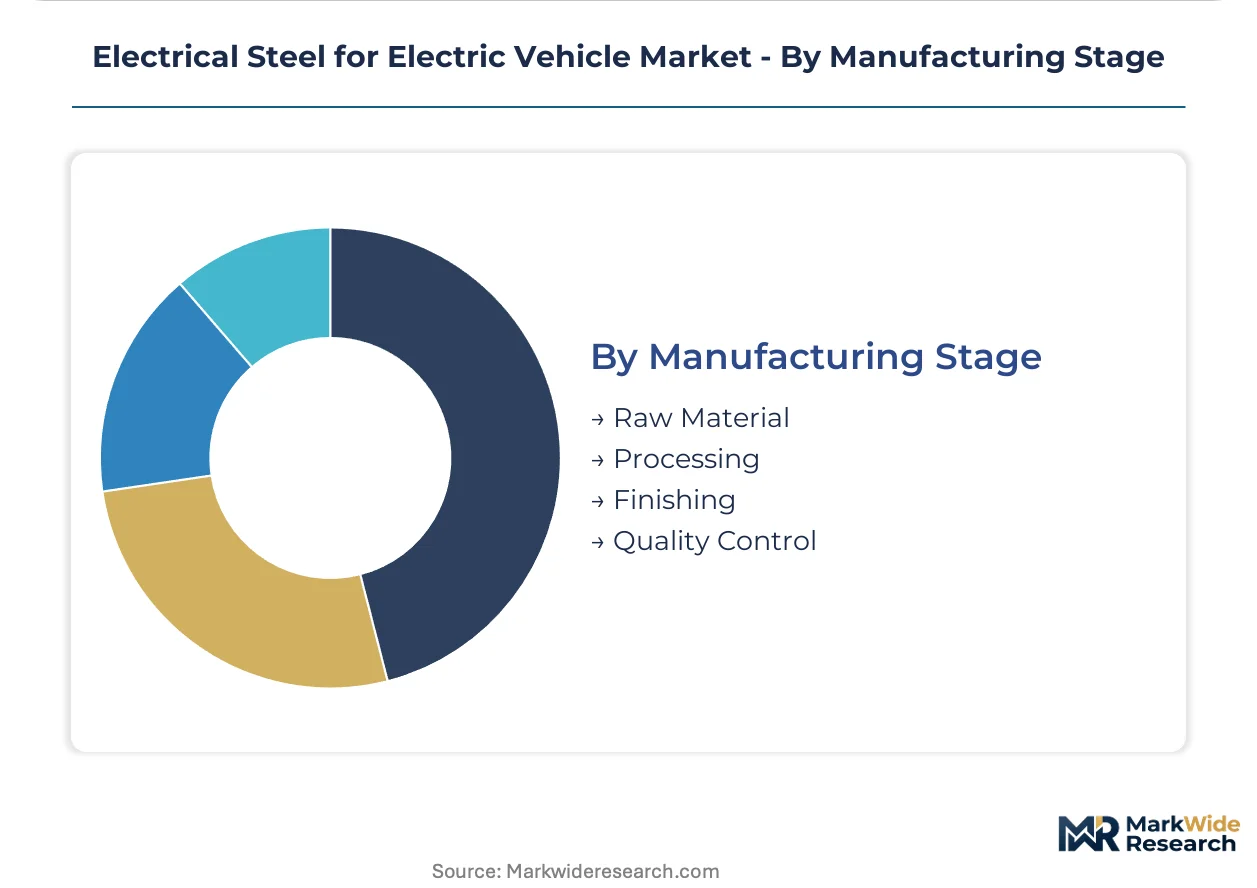
Supply concentration intensifies downstream. Raw material and processing stages fragment across multiple metallurgical bases, while finishing and quality control consolidate among qualified laminators.
- Processing:Cold rolling, annealing, and texture engineering operations transforming hot-rolled feedstock into gauge-specific electrical steel strip. Korean supply concentration creates dependency risk for European and North American motor laminators lacking qualified alternative sources.
- Quality Control:Batch-level magnetic property documentation, core loss testing, and surface insulation coating validation. REACH framework amendments in Europe are tightening substance restrictions on phosphate-based treatments, accelerating qualification of chrome-free and cobalt-free coating alternatives.
- Raw Material:Ferrosilicon smelting and hot-rolled substrate production subject to energy-intensive economics and silicon metal price volatility.
- Finishing:Slitting, edge conditioning, and surface treatment operations preparing laminations for motor core stacking.
Quality control dominates technical barrier height. Processing is where capacity expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vertically integrated OEMs dominate qualified supplier list access in China, Germany, and the United States, while specialized Tier-1 laminators serving multiple platforms concentrate procurement flexibility in Korea and Japan.
China
MIIT energy efficiency mandates for NEV drivetrain components are disqualifying lower-grade electrical steels from state-supported OEM supply lists. The country's national industrial regulator enforces escalating performance thresholds that filter market access by technical capability. Shanghai and the Yangtze River Delta anchor domestic EV motor manufacturing capacity expansion.
Germany
National ICE phase-out mandates are accelerating EV motor platform deployment and pulling premium-grade silicon steel through qualified supplier channels. The KBA enforces stringent vehicle efficiency standards that translate into material specifications for traction motor laminations. Bavaria and Baden-Württemberg concentrate R&D-to-production infrastructure for high-efficiency motor cores.
United States
EPA fuel economy standards enforce escalating performance thresholds for EV drivetrain components across battery-electric passenger vehicle platforms. The federal environmental regulator mandates efficiency test cycles that impose specific magnetic loading profiles on motor laminations. Michigan and the industrial Midwest scale domestic EV motor manufacturing capacity.
South Korea
Captive raw material sourcing and dedicated cold-rolling capacity create supply concentration for grain-oriented grades serving permanent magnet motor architectures. The MFDS and national industrial policy support captive supply chain development for critical materials. Busan-Ulsan and the Seoul Capital Area anchor integrated steel-to-motor production corridors.
Japan
METI efficiency mandates and automotive industry partnerships drive qualification of specialty alloy grades for high-frequency motor designs above 10 kHz. The national trade and industry ministry coordinates R&D investment in next-generation magnetic materials. Nagoya and the Chubu region concentrate precision lamination expertise for hybrid and electric vehicle platforms.
Electrical Steel for Electric Vehicle Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure where integrated steel mills hold qualified supplier list access and mid-tier processors seek certification through toll-annealing partnerships. Consolidation concentrates among Asian and European integrated producers with captive silicon metal supply and dedicated cold-rolling capacity. Three archetypes dominate: integrated mega-mills with R&D-to-melting infrastructure, regional specialists with niche texture engineering capabilities, and asset-light processors leveraging third-party finishing services. Capacity expansion and strategic partnerships represent the dominant competitive moves as OEMs lock three-to-five-year offtake agreements.
Among Asia-Pacific integrated producers, Nippon Steel Corporation and POSCO exemplify the R&D-intensive archetype with established positions in premium-grade silicon steel supply. ArcelorMittal occupies a position as the multi-continental standard-setter competing across standardized product platforms that reduce customer qualification timelines. These three anchors demonstrate how geographic origin and corporate structure correlate with strategic positioning: Tokyo-based Nippon Steel Corporation represents Japanese integrated mill expertise; Pohang-based POSCO exemplifies Korean captive-sourcing models; and Luxembourg-headquartered ArcelorMittal illustrates European multi-regional scale operations.
| Leading Market Players |
|---|
| ArcelorMittal |
| China Baowu Steel Group |
| Nippon Steel Corporation |
| POSCO |
| JFE Steel Corporation |
| Thyssenkrupp |
| Cleveland-Cliffs |
| Tata Steel |
| Voestalpine |
| Others |
Pricing and Supply Chain Analysis
Korean captive sourcing of ferrosilicon and dedicated cold-rolling capacity concentrates upstream margin capture, while downstream pricing power accrues to qualified laminators commanding 18-24 month OEM qualification timelines.
Pricing Analysis
Certification level creates the primary spread between qualified supplier list access and spot-market commodity sales. Contract-based long-term offtake structures dominate volume procurement, with grain-oriented grades commanding premium positioning over commodity silicon steel. Pricing pressure stems from ferrosilicon input cost volatility driven by energy-intensive smelting economics. Tier-1 laminators serving multiple OEM platforms exhibit lowest price sensitivity, while asset-light processors dependent on toll-annealing services face acute margin compression.
Supply Chain Analysis
Ferrosilicon smelting and hot-rolled substrate production draw from China, South Korea, and Japan as primary metallurgical bases. Critical inputs include silicon metal, electrical-grade scrap, and controlled-atmosphere annealing gases. Single-source vulnerability concentrates in Korean grain-oriented capacity serving European and North American motor laminators. Distribution runs through qualified supplier channels with batch-level magnetic property documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward vertically integrated OEMs consolidating three-to-five-year offtake agreements, fragmenting leverage among uncommitted Tier-1 laminators.
For Market Incumbents: Build qualification moats through captive R&D-to-melting infrastructure and texture engineering IP. Deepen backward integration into ferrosilicon supply to offset energy cost volatility. Accelerate chrome-free coating qualification ahead of REACH sunset dates to preempt regulatory displacement. For New Entrants and Emerging Players: India's PLI scheme for auto components offers underpenetrated qualified supplier pathways with state-backed demand visibility. Target toll-annealing partnerships with established Korean or Japanese processors to bypass 18-24 month OEM validation cycles. Pursue specialty alloy grades for 800-volt architectures where technical differentiation overrides incumbency advantages. For Investors and Strategic Acquirers: Capital is best deployed toward regional specialists with niche texture engineering capabilities and existing OEM qualification relationships. Five-to-ten year viability favors processors with demonstrated high-frequency grade production above 10 kHz. Monitor MIIT efficiency mandate threshold revisions as inflection indicators for demand acceleration or grade obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Locks volume commitments from Nippon Steel and POSCO for platform design freeze alignment. |
| Backward Integration | Captive ferrosilicon sourcing insulates margin predictability against energy cost swings. |
| Green Manufacturing Transition | Chrome-free coating qualification satisfies ECHA REACH amendments for EU market access. |
| Capacity Expansion | Dedicated thin-gauge rolling lines address sub-0.20 mm supply constraints for high-frequency motors. |
| Joint Venture | Partnerships with Tier-1 laminators accelerate OEM qualification through shared texture engineering expertise. |
Research Methodology
A spread of perspectives from steel mill technical directors, EV motor platform engineers, Tier-1 procurement leads, and regulatory affairs specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through MIIT efficiency mandate filings, EPA fuel economy standard updates, EU Green Deal implementation documents, and customs trade data for ferrosilicon flows. Bottom-up segment modeling and top-down macroeconomic triangulation anchored volume estimates.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, motor architecture frequency class, end-user integration depth, and regional regulatory cluster. CAGRs derived from slope analysis of historical qualification cycle compression and forward capacity buildout announcements. Industry-specific inputs incorporated OEM motor design freeze timelines and steel mill annealing capacity expansion schedules.
Practitioners should monitor ferrosilicon energy cost spikes, REACH substance restriction amendments, and MIIT threshold revisions for early signals of forecast deviation. Cross-checking against IHS Markit vehicle production databases and steel association shipment statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Frameless Brushless DC Motors Market
Electrical Power Equipment
South America Medium Voltage Switchgear Market
Electrical Power Equipment
Skid Mounted Unit Substations Market
Electrical Power Equipment
North America Oil Filled Electric Heaters Market
Electrical Power Equipment
Immersion Heater Market
Electrical Power Equipment
Gas Circuit Breaker Market
Electrical Power Equipment
Electric Substation Market
Electrical Power Equipment
Domestic Hot Water (DHW) Tanks Market
Electrical Power Equipment
Electric Vehicle Charging Cables Market
Electrical Power Equipment
Packaged Substation Market
Electrical Power Equipment
Subsea Cables Equipment Market
Electrical Power Equipment
Smart Electric Heater Market
Electrical Power Equipment
Fault Circuit Indicator Market
Electrical Power Equipment
Industrial Power Supply Market
Electrical Power Equipment
MV Protection Relay Market
Electrical Power Equipment
Busway-Bus Duct Market