
 Global Induction Motors Market | 2026-2036
Global Induction Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Induction Motors Market Foresight
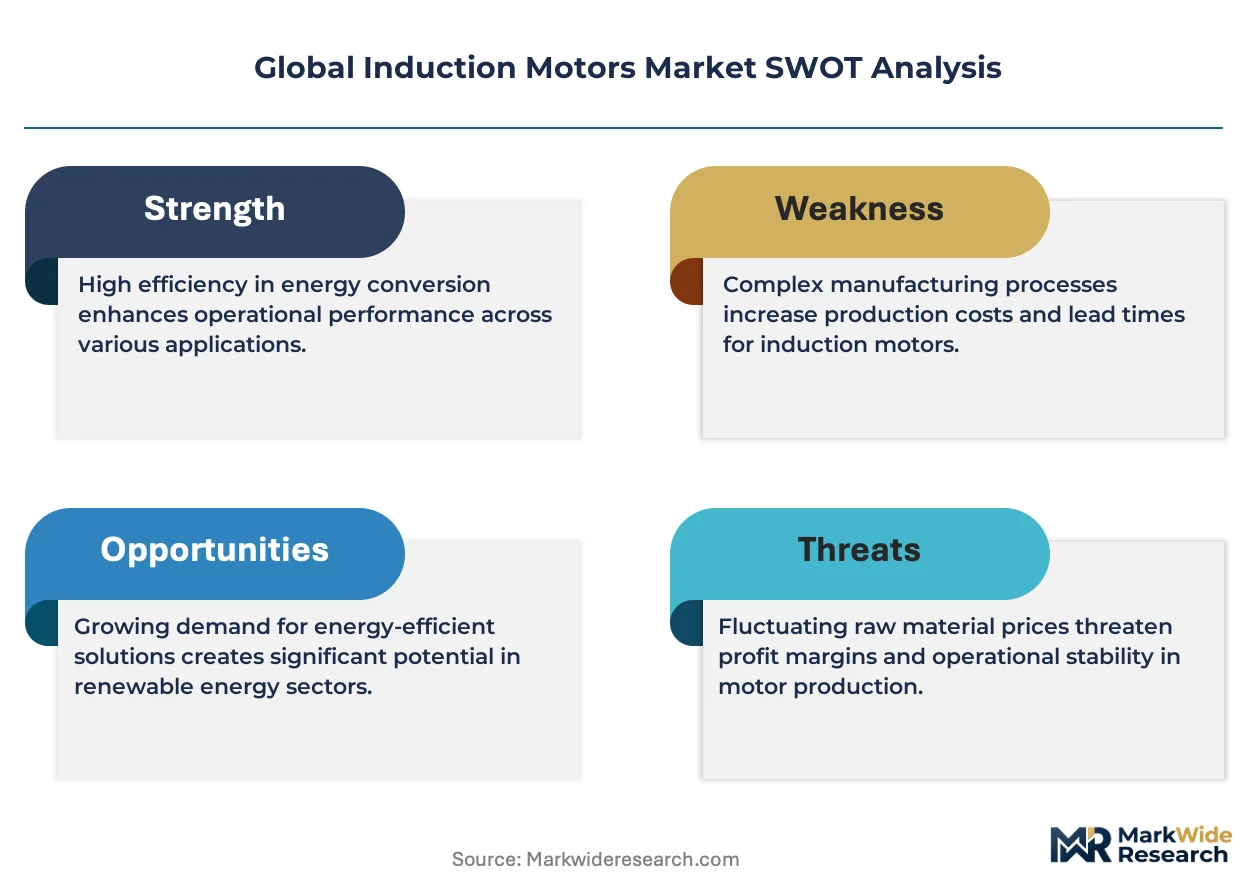
Software-defined motor diagnostics and predictive maintenance subscriptions is rebalancing how OEMs capture lifetime value from installed bases. Siemens leverages its digital twin platform to anchor long-term service contracts across European industrial fleets. ABB competes through integrated automation architectures that extend hardware margins into recurring software revenue streams.
An induction motor is an alternating-current machine in which torque is produced by electromagnetic induction from the magnetic field of the stator winding rather than direct electrical connection to the rotor, with typical operating speeds governed by pole count and supply frequency between 50-60 Hz, designed to convert electrical energy into mechanical rotation for continuous-duty industrial processes. Three-phase squirrel cage units dominate installed capacity due to mechanical simplicity and minimal maintenance requirements, while IE4 and IE5 super-premium efficiency classes represent the fastest-growing technology tier as operating cost scrutiny intensifies across energy-intensive applications. Pumps and compressor drives retain the largest share of application-specific demand, though conveyor system retrofits in automated logistics are gaining traction as a discrete growth pocket.
The U.S. Department of Energy enforces minimum efficiency standards through 10 CFR 431, while the EU Ecodesign Directive and IEC 60034-30-1 efficiency classification framework collectively restrict market access for sub-IE3 products across member states. China's GB 18613 standard and NMPA-aligned certification requirements impose parallel efficiency mandates that reshape import competitiveness and domestic procurement patterns. Stakeholders must monitor regulatory divergence between efficiency tiers as compliance costs and redesign cycles become decisive factors in vendor selection and geographic sourcing strategy.
Market Dynamics
Regulatory compression on efficiency tiers is forcing synchronous redesign cycles across manufacturing footprints, while digital service layers are capturing margin that hardware commoditization has eroded.
Growth Catalysts
- EU Ecodesign Directive:Mandatory phase-out of IE1 and IE2 efficiency classes is accelerating fleet replacement timelines across German and Italian industrial bases.
- Water treatment infrastructure:Municipal investment corridors in India and China are expanding unit demand for pump-duty motors in coastal industrial zones.
- IE4/IE5 super-premium tiers:Operating cost scrutiny in energy-intensive process industries is concentrating procurement preference on highest-efficiency classifications.
Market Restraints
- Copper and rare-earth price volatility:Magnet material cost swings compress margin predictability for wound-rotor and permanent-magnet adjacent designs.
- East Asian supply concentration:Coastal manufacturing corridors in China and South Korea create single-source vulnerability for high-volume OEM supply agreements.
- Technical ceiling on squirrel-cage efficiency:Fundamental electromagnetic constraints limit further loss reduction without topology shifts to synchronous reluctance or permanent-magnet alternatives.
Strategic Opportunities
- Software-defined diagnostics:Predictive maintenance subscriptions anchored to digital twin platforms are extending OEM lifetime value capture beyond hardware shipment.
- Automated logistics retrofits:Conveyor system electrification in European distribution centers represents an underpenetrated application vertical with compressed payback thresholds.
- US IRA efficiency incentives:Federal tax credits for industrial equipment upgrades are lowering adoption barriers for premium-efficiency classes in energy-intensive manufacturing.
Industry Challenges
- Electromagnetic design talent scarcity:Specialized motor modeling expertise is concentrating at Tier-1 OEMs, constraining mid-tier vendor R&D velocity.
- Multi-jurisdiction certification timelines:Parallel IEC 60034-30-1, GB 18613, and 10 CFR 431 compliance cycles extend product launch windows and fragment engineering resources.
- Legacy system integration friction:Retrofit installations face control architecture mismatches between variable-frequency drives and existing programmable logic controller networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Induction Motors Market |
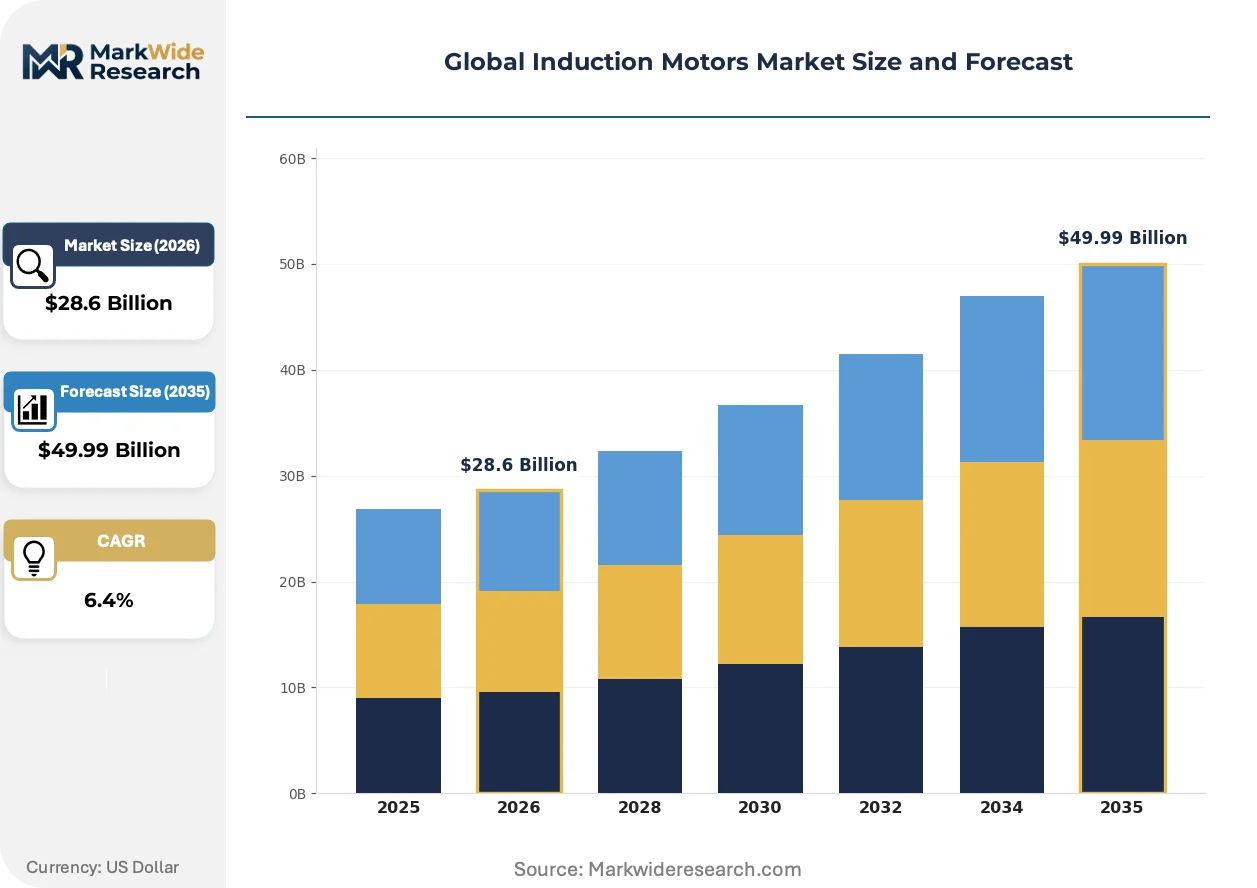
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Squirrel Cage, Wound Rotor, Single Phase, Three Phase, Double Cage Technology: IE1 Standard, IE2 High Efficiency, IE3 Premium Efficiency, IE4 Super Premium, IE5 Ultra Premium Application: Pumps, Compressors, Conveyor Systems, HVAC Equipment, Machine Tools End User: Manufacturing Plants, Water Treatment Facilities, Mining Operations, Food Processing Units, Packaging Companies |
| Companies Covered | ABB, Siemens, Schneider Electric, Regal Rexnord, WEG Electric, Nidec Corporation, Rockwell Automation, Emerson Electric, Marathon Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Induction Motors Market Shifts & Advancements
Digitalization of motor assets is compressing the traditional hardware-service boundary, while efficiency regulations are functionally mandating technology tier migration ahead of natural replacement cycles.
Synchronous reluctance motor technology is overtaking conventional induction designs in variable-speed pump and fan applications. Food and beverage processors across Northern Europe are standardizing on these topologies to circumvent rare-earth supply exposure. The shift is overtaking established procurement patterns that historically prioritized first-cost minimization over ten-year total cost of ownership.
China's GB 18613-2020 efficiency standard is tightening import eligibility for sub-IE3 products and reshaping competitive access to domestic procurement channels. Foreign OEMs face parallel certification requirements through NMPA-aligned testing protocols that extend market entry timelines. Industrial motor distributors are consolidating supplier portfolios to reduce compliance fragmentation exposure.
After-sales service unbundling is fragmenting traditional OEM-captive maintenance relationships. Third-party diagnostics providers are capturing condition-monitoring revenue through cloud-native vibration analysis platforms. This pattern is most visible in German automotive supplier parks where multi-vendor motor fleets favor independent service aggregation over single-source contracts.
Global Induction Motors Market Segmentation
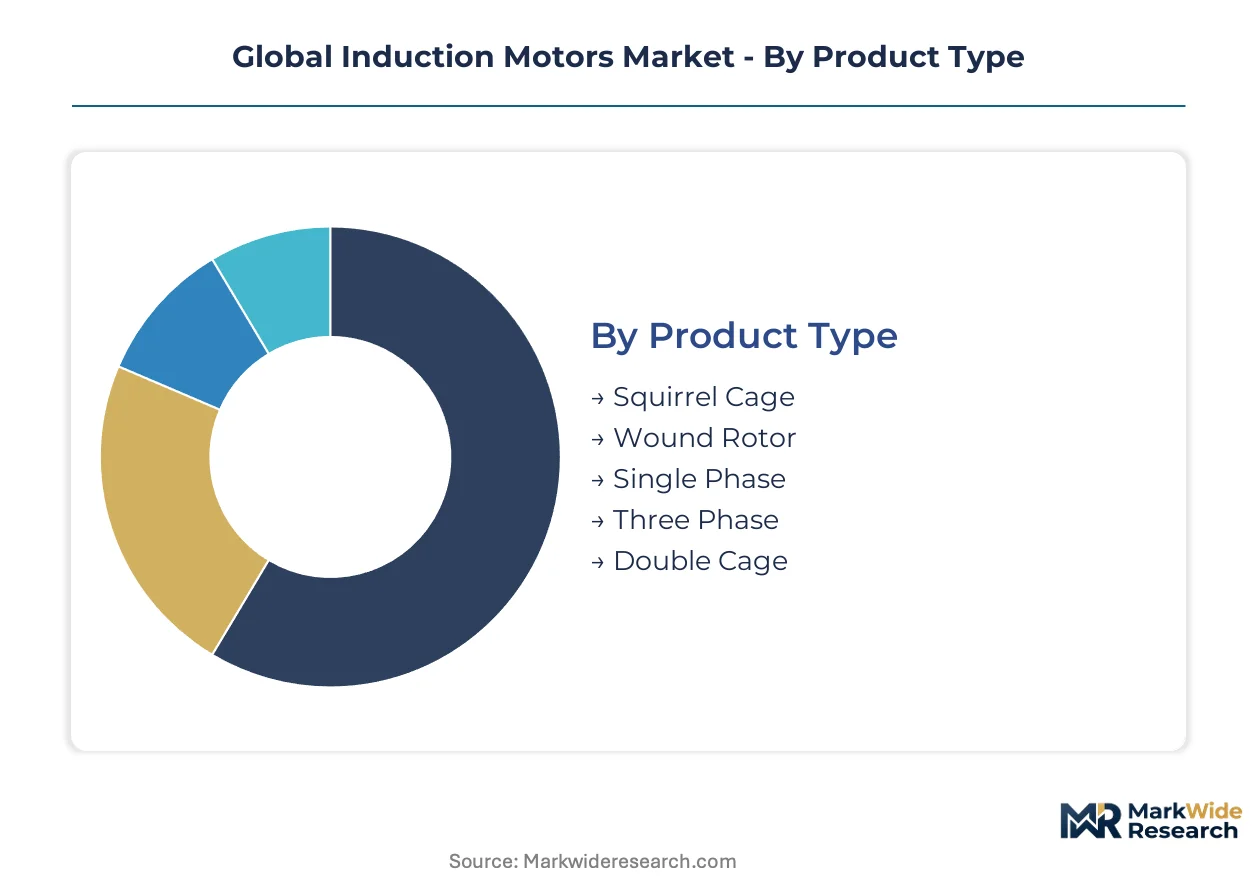
Induction motor procurement patterns diverge sharply across mechanical topology, efficiency tier, application duty cycle, and end-user capital intensity. Understanding these segment boundaries clarifies where OEMs can defend margin through technical differentiation versus where hardware commoditization forces service-based value capture.
Product Type:
Mechanical complexity ranges from zero-maintenance squirrel-cage designs to field-serviceable wound-rotor configurations, with customization depth determining aftermarket revenue potential.
- Squirrel Cage:Cast aluminum or copper rotor bars embedded in laminated steel cores eliminate slip rings and brushes entirely. Demand concentrates in German automotive supplier parks where 24/7 continuous duty and minimal maintenance windows favor mechanical simplicity over efficiency optimization.
- Wound Rotor:External resistance control through three-phase rotor windings enables high starting torque for heavy-inertia loads. Mining operations across Western Australia and Chilean copper belts specify these units for crusher and mill drives where starting current limitation outweighs first-cost premiums.
- Single Phase:Split-phase or capacitor-start designs for fractional-horsepower residential and light commercial loads below 5 kW.
- Three Phase:Industrial workhorse configuration dominating installed capacity above 1 kW across manufacturing corridors.
- Double Cage:Outer high-resistance cage for starting torque combined with inner low-resistance cage for running efficiency in high-inertia pump applications.
Leading the category by volume: Squirrel Cage. Expanding most quickly: Double Cage in water treatment pump retrofits.
Technology:
Regulatory mandates across the EU Ecodesign Directive, China's GB 18613, and US 10 CFR 431 are compressing the viable efficiency tier range, with compliance costs favoring leapfrog adoption over incremental upgrades.
- IE1 Standard:Basic efficiency classification now restricted from EU member state markets and facing phased elimination in Chinese procurement channels. Remaining demand concentrates in price-sensitive Southeast Asian manufacturing where regulatory enforcement lags IEC adoption timelines.
- IE2 High Efficiency:Improved winding materials and reduced air gap losses deliver modest efficiency gains over IE1 baseline. Indian textile mills in Surat and Tiruppur clusters specify IE2 units where capital constraints block IE3 premiums despite favorable payback periods.
- IE3 Premium Efficiency:Mandatory minimum for new installations across EU member states and increasingly required in Chinese state-owned enterprise procurement.
- IE4 Super Premium:Advanced magnetic materials and optimized slot geometries push efficiency toward synchronous machine performance without rare-earth dependency.
- IE5 Ultra Premium:Loss-optimized designs approaching theoretical induction machine limits through copper rotor technology and precision manufacturing tolerances.
Highest shipment volumes: IE3 Premium Efficiency. Steepest expansion trajectory: IE4 Super Premium in Northern European process industries.
Application:
Duty cycle characteristics and speed control requirements fragment motor specification, with constant-torque versus variable-torque load profiles driving fundamentally different thermal and insulation designs.
- Pumps:Centrifugal and positive displacement pump drives retain the largest application share, with municipal water treatment facilities across India and China expanding unit demand. Throttling losses in legacy valve-controlled systems create retrofit opportunity for variable-speed IE4/IE5 upgrades.
- Compressors:Air and refrigeration compression duty subjects motors to high starting frequency and thermal cycling stress. Food processing units in Germany and the Netherlands specify premium efficiency classes to offset refrigeration system energy intensity.
- Conveyor Systems:Automated logistics electrification in European distribution centers represents underpenetrated growth with compressed payback thresholds.
- HVAC Equipment:Fan and blower duty with partial-load operating profiles favoring variable-frequency drive compatibility.
- Machine Tools:Spindle and axis drive applications requiring precise speed regulation and rapid acceleration response.
Dominant by installed base: Pumps. Climbing the fastest: Conveyor Systems in automated logistics retrofits.
End User:
Capital intensity and energy cost exposure determine procurement sophistication, with energy-intensive process industries leading efficiency tier migration while asset-light operators prioritize first-cost minimization.
- Manufacturing Plants:Diverse motor fleets spanning material handling, machining, and process equipment create complexity for maintenance standardization. South Korean automotive and electronics manufacturing corridors concentrate demand for predictive maintenance-enabled IE4 units.
- Water Treatment Facilities:Pump-intensive operations with 24/7 duty cycles and municipal ownership structures that favor lifecycle cost analysis over first-cost constraints. Coastal industrial zones in China and India are expanding procurement pipelines.
- Mining Operations:Harsh environmental conditions and high starting torque requirements favor wound-rotor designs with ruggedized enclosures.
- Food Processing Units:Hygiene-rated washdown motors with stainless steel construction and sealed bearings for sanitary washdown compliance.
- Packaging Companies:Intermittent duty cycles with frequent starts and stops stressing thermal management systems.
Category volume leader: Manufacturing Plants. Gaining share fastest: Water Treatment Facilities on infrastructure investment corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Yangtze River Delta manufacturing corridor concentrates the densest concentration of induction motor procurement, with coastal industrial zones across three continents driving divergent regulatory and demand patterns.
China
Municipal water treatment expansion in Jiangsu and Zhejiang provinces is accelerating IE3 and IE4 motor procurement for pump-intensive facilities. GB 18613-2020 efficiency standards are tightening import eligibility and reshaping competitive access for foreign OEMs. Ningbo's port industrial zone hosts concentrated demand from textile and chemical processing plants upgrading legacy motor fleets.
Germany
Automotive supplier parks in Stuttgart and Wolfsburg specify 24/7 continuous-duty squirrel-cage units with predictive maintenance integration. The EU Ecodesign Directive mandates IE3 minimum efficiency, accelerating phase-out of IE1 and IE2 installations. Ruhr Valley industrial clusters are retrofitting compressor and conveyor systems with IE4 super-premium motors to offset energy cost exposure.
United States
Food processing facilities in Wisconsin and California are standardizing on premium efficiency classes to meet corporate sustainability targets. DOE 10 CFR 431 standards enforce minimum efficiency thresholds, while IRA tax credits lower adoption barriers for industrial equipment upgrades. Houston's petrochemical corridor maintains demand for wound-rotor designs in high-torque process applications.
India
Textile mills in Surat and Tiruppur clusters specify IE2 units where capital constraints block IE3 premiums despite favorable lifecycle economics. CEA efficiency guidelines and state-level procurement mandates are gradually tightening minimum performance requirements. Chennai's automotive manufacturing corridor is emerging as a demand pocket for predictive maintenance-enabled motor systems.
South Korea
Electronics and semiconductor fabrication facilities in Gyeonggi Province require precision-controlled motor systems for cleanroom environments. METI-aligned efficiency standards and corporate carbon neutrality commitments are driving IE4 adoption in energy-intensive processes. Busan-Ulsan industrial belt concentrates demand for integrated automation architectures in shipbuilding and heavy machinery.
Global Induction Motors Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin capture models. The vendor base stratifies between integrated automation conglomerates, specialized motor fabricators, and digital service layer entrants. Three archetypes dominate: full-stack automation suppliers bundling hardware with predictive maintenance subscriptions, efficiency-focused motor specialists capturing regulatory upgrade cycles, and regional fabricants serving price-sensitive procurement channels. Competitive intensity centers on technology licensing partnerships and backward integration into magnetic materials supply.
Within the integrated automation tier, ABB and Siemens exemplify divergent approaches to lifetime value capture—ABB through automation architecture bundling, Siemens through digital twin-anchored service contracts. Among specialized motor fabricators, WEG Electric occupies a position representing Latin American-scale production capabilities. These anchors illustrate how competitive positioning splits between software-defined service models and manufacturing-scale efficiency optimization.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Schneider Electric |
| Regal Rexnord |
| WEG Electric |
| Nidec Corporation |
| Rockwell Automation |
| Emerson Electric |
| Marathon Electric |
| Others |
Supply & Pricing Matrix
IE3-to-IE4 efficiency tier divergence creates distinct pricing corridors that map directly onto supply chain configurations, with premium-copper-rotor manufacturers anchoring captive foundry relationships while commodity aluminum-bar producers source from spot-market metal exchanges.
Pricing Analysis
Margin tightening in IE1 and IE2 legacy tiers reflects regulatory phase-out timelines compressing residual demand into price-sensitive Southeast Asian procurement channels. Three-tier pricing structure across IE4/IE5 premium, IE3 standard, and IE2 economy levels separates vendors through GB 18613 and EU Ecodesign certification status, with municipal buyers in India and China exhibiting highest price sensitivity and German automotive suppliers least.
Supply Chain Analysis
Remanufacturing flows for wound-rotor mining motors create reverse-logistics revenue streams for OEMs servicing Western Australian and Chilean copper belt operations. Magnetic steel laminations and copper rotor bars draw from China, Japan, and Germany; rare-earth-independent synchronous reluctance designs rest on ferrite magnet supply from South Korea. Single-source vulnerability concentrates in coastal Chinese foundry capacity. Distribution runs through industrial distributor networks and direct OEM contracts to plant engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IE4 super-premium and IE5 ultra-premium efficiency classes are displacing conventional IE3 installations ahead of natural replacement cycles, compressing the window for legacy technology monetization.
For Market Incumbents: Deploy predictive maintenance subscription bundling to anchor long-term service contracts against third-party diagnostics entrants capturing aftermarket revenue. Defend margin position through backward integration into precision copper rotor casting and digital twin platform standardization across European industrial fleets.
For New Entrants and Emerging Players: Begin with conveyor system retrofits in automated European logistics distribution centers where payback thresholds compress and incumbent presence remains thin. Target water treatment infrastructure corridors in Indian coastal industrial zones through municipal procurement channels favoring lifecycle cost analysis.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated automation conglomerates seeking to fill efficiency-tier gaps or expand geographic manufacturing footprints. Long-term viability favors vendors with captive magnetic materials supply and software-defined service layers; monitor GB 18613 enforcement intensity and EU Ecodesign Directive expansion scope for inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Development | Siemens anchors recurring revenue through predictive maintenance subscriptions across German automotive supplier parks. |
| Copper Rotor Foundry Integration | Captive casting capacity insulates margin from London Metal Exchange volatility and quality variability. |
| IE4/IE5 Product Line Expansion | Leapfrog positioning captures regulatory upgrade cycles ahead of IEC 60034-30-1 tier compression. |
| Synchronous Reluctance Technology Licensing | Food processors in Northern Europe adopt rare-earth-independent topologies to circumvent supply exposure. |
| Water Treatment Sector Partnership | Municipal investment corridors in Jiangsu and Zhejiang provinces expand pump-duty motor procurement pipelines. |
Research Methodology
Document review covered IEC 60034-30-1 efficiency classification frameworks, GB 18613-2020 standard documentation, and EU Ecodesign Directive regulatory filings, complemented by interviews with plant engineers at German automotive supplier parks, maintenance directors at Indian textile mills, procurement leads at Chinese state-owned water treatment facilities, and aftermarket service heads at Latin American motor distributors. Secondary validation drew from customs trade data, SEC 10-K filings of listed industrial conglomerates, and national energy agency efficiency program disclosures. Bottom-up unit shipment estimates triangulated against top-down energy consumption models across manufacturing corridors.
Segment-level value outputs combined mechanical topology splits with efficiency tier adoption curves across the projection horizon, modeling squirrel-cage, wound-rotor, and synchronous reluctance configurations separately. Product type, technology tier, application duty cycle, and end-user capital intensity dimensions structured the analytical framework. CAGRs derived from regression against historical efficiency standard implementation patterns and infrastructure investment pipeline tracking. Forecast inputs incorporated copper price volatility scenarios and regulatory enforcement lag estimates by jurisdiction.
Underlying measurement precision varies by segment; IE4/IE5 super-premium tiers carry tighter precision than legacy IE1/IE2 residual demand given concentrated OEM reporting. Forecasts reflect assumptions around GB 18613 enforcement timelines, EU Ecodesign Directive expansion scope, and IRA tax credit continuity. Practitioners should monitor NMPA-aligned certification protocol changes and synchronous reluctance technology cost curves for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Global Low Voltage Motors Market
Industrial Motors
Global Refrigeration Oil Market
Industrial Motors
Global Linear Motors Market
Industrial Motors
Europe Hazardous Location Motors Market
Industrial Motors
Charging Nitrogen Gas Systems Market
Industrial Motors
Hydraulic Motors Market
Industrial Motors
Latin America Hazardous Location Motors Market
Industrial Motors
Synchronous Electric Motor Market
Industrial Motors
Global Sliding Vane Air Motor Market
Industrial Motors
United Kingdom DC Motor Market
Industrial Motors
Food Grade Hydraulic Oil Market
Industrial Motors
Cryogenic Air Separation Units (Asus) Market
Industrial Motors
Spargers Market
Industrial Motors
Inverter Duty Motors Market
Industrial Motors
Crude Heater Market
Industrial Motors
Electric Motors for Drones and Electric Vehicle Market