
 Industrial Motor Market | 2026-2036
Industrial Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Motor Market Intelligence
Copper winding substitution with aluminum in fractional horsepower designs is realigning cost structures for entry-level industrial motors. Siemens AG leverages vertical integration in drive systems to sustain margin capture across the powertrain stack. ABB Ltd anchors its position through digital motor monitoring platforms that extend service revenue beyond hardware sales. Nidec Corporation specializes in high-efficiency brushless architectures for precision manufacturing environments.
An industrial motor is an electromechanical device that converts electrical energy into rotational mechanical force, typically operating at power ratings from fractional horsepower to tens of thousands of kilowatts with specified efficiency classes and insulation thermal grades. AC motors dominate installed capacity across process industries due to their rugged construction and direct grid compatibility, while servo motors command premium positioning in robotics applications where closed-loop torque control determines system accuracy. The manufacturing application segment retains the largest volume footprint, though HVAC retrofits represent a concentrated margin pool as building energy codes tighten.
The US Department of Energy enforces minimum efficiency standards through NEMA MG 1 Table 12-12, while the EU Ecodesign Directive mandates IE3 minimums for motors rated above 0.75 kW. China's GB 18613 standard and India's BIS certification program impose parallel efficiency tiers that shape import eligibility and domestic procurement rules. Stakeholders must monitor regulatory divergence between efficiency banding systems when configuring global product platforms.
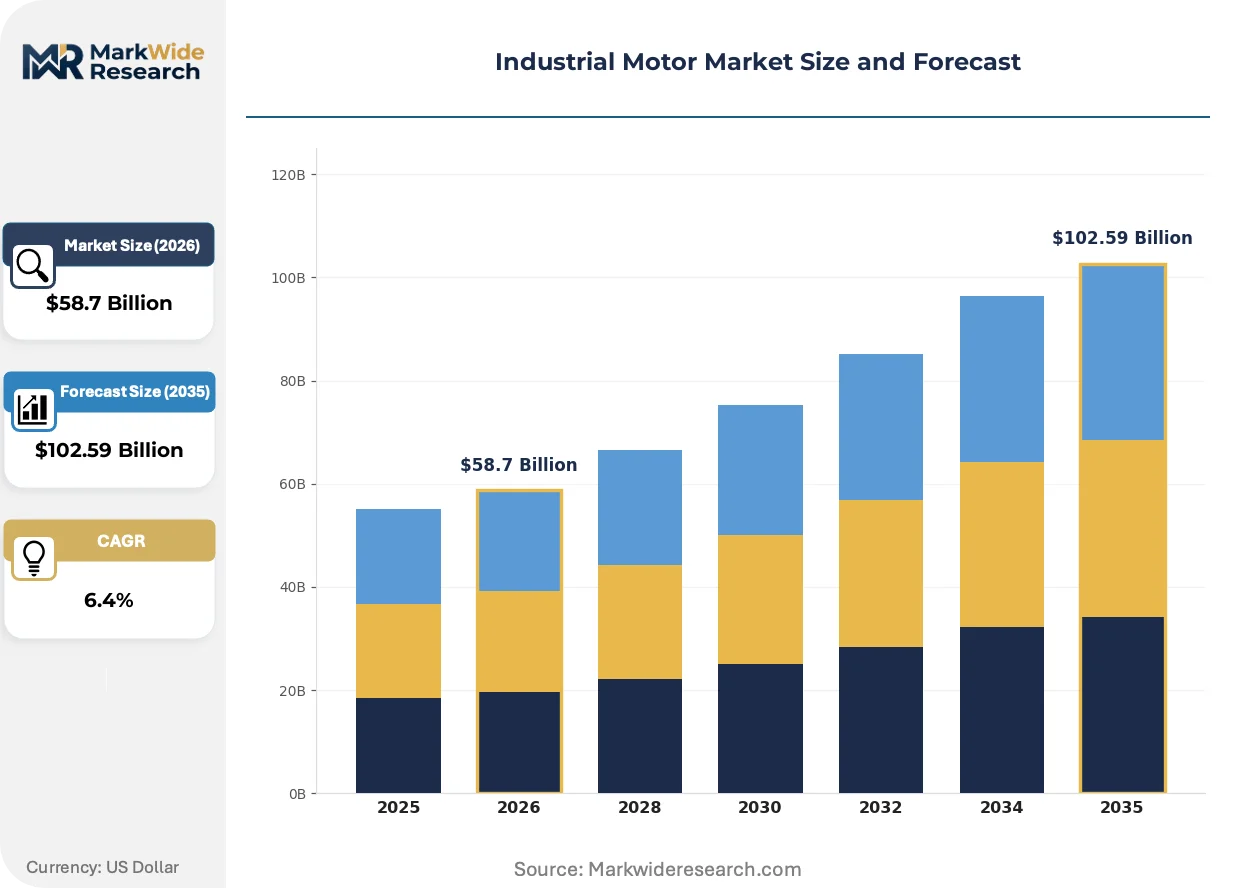
Market Dynamics
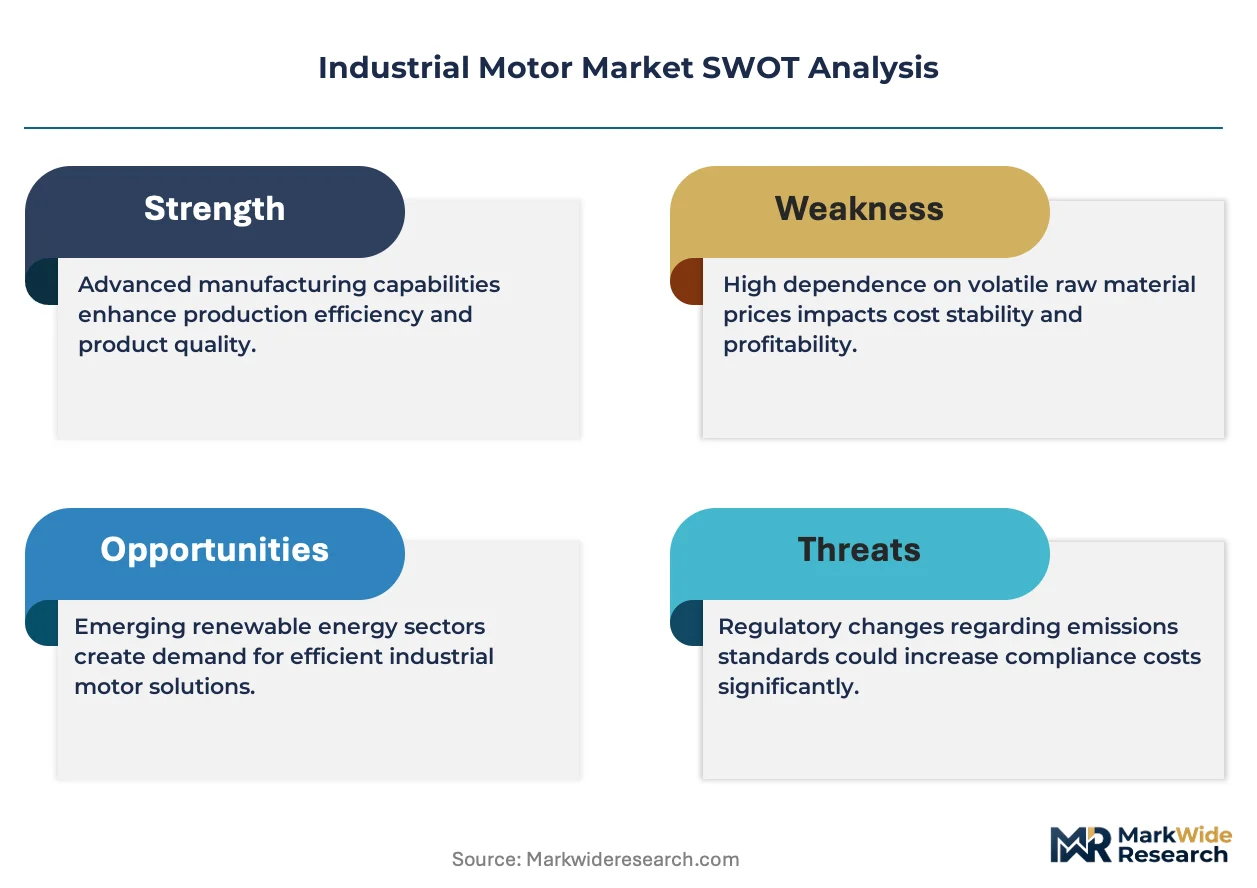
Regulatory mandates for minimum energy efficiency are forcing replacement cycles across aging installed bases, while copper price volatility and supply concentration in rare-earth magnet processing reshape cost structures and sourcing strategies for motor manufacturers.
Growth Catalysts
- IE3 Mandates:The EU Ecodesign Directive and parallel MEPS regulations in multiple jurisdictions compel industrial facilities to retire IE1 and IE2 equipment ahead of mechanical failure.
- Upstream Oil & Gas:Exploration operators in the Permian Basin and North Sea are replacing decades-old drilling rig motors to meet emissions compliance and reduce fuel consumption.
- Permanent Magnet Synchronous Motors:Rare-earth magnet architectures are displacing induction designs in precision manufacturing where variable-speed operation cuts energy draw.
Market Restraints
- Copper Price Volatility:LME copper fluctuations above historical baselines compress margins on wound-rotor and fractional-horsepower product lines.
- Rare-Earth Concentration:NdFeB magnet supply chains concentrate in China's Inner Mongolia processing corridor, exposing procurement to export quota risks.
- IE4 Cost Premium:Super-premium efficiency architectures require specialized lamination steel and tighter manufacturing tolerances that price out cost-sensitive buyers.
Strategic Opportunities
- India Manufacturing:PLI scheme incentives for industrial automation are opening replacement demand in Gujarat and Tamil Nadu textile clusters.
- Predictive Maintenance Platforms:Vibration-sensing motor mounts combined with edge analytics create recurring revenue streams beyond hardware shipment.
- HVAC Retrofit Mandates:ASHRAE 90.1 and equivalent building codes in California and New York compress payback periods for high-efficiency blower and chiller motors.
Industry Challenges
- Winding Technician Shortage:Skilled labor capable of precision rewinding for IE3+ insulation systems is scarce across Midwest US manufacturing corridors.
- Dual Certification Burden:Manufacturers serving both NEMA MG 1 and IEC 60034 markets must maintain parallel testing protocols and documentation systems.
- Legacy Control Integration:Variable frequency drives from the 1990s lack communication protocols compatible with modern motor monitoring architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Motor Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $102.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Stepper Motors, Servo Motors Application: Manufacturing, HVAC, Conveyors, Robotics End User: Oil & Gas, Mining, Construction, Agriculture Technology: Brushless, Induction, Synchronous, Linear |
| Companies Covered | Siemens AG, ABB Ltd, Nidec Corporation, WEG Electric Corp, Regal Rexnord Corporation, Rockwell Automation, Johnson Electric, Toshiba Industrial Products, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Motor Market Strategic Shifts & Innovations
Digitalization of motor systems is accelerating as embedded sensors and cloud connectivity transform hardware into data-generating assets, while material science advances and regulatory tightening compress acceptable efficiency thresholds.
Switched reluctance motor architectures are expanding into conveyor and pump applications where rotor simplicity eliminates rare-earth dependencies. Mining operators in Western Australia and bulk material handlers in the Rhine-Ruhr corridor are piloting these designs to hedge magnet supply risk. The technology is expanding into mid-power ranges previously dominated by induction machines, compressing the addressable market for conventional wound-rotor products.
The US Department of Energy is tightening enforcement of NEMA MG 1 Table 12-12 standards while considering IE4-equivalent thresholds for motors above 50 horsepower. Industrial facilities in Texas and Ohio petrochemical corridors face accelerated depreciation schedules if retrofit timelines slip. Motor distributors are consolidating SKU portfolios to prioritize IE3 and IE4 inventory, squeezing availability of legacy efficiency classes.
Buyers are unbundling aftermarket service from original equipment procurement, awarding maintenance contracts to third-party specialists with diagnostic capabilities. Automotive stamping plants in Michigan and appliance manufacturers in Mexico are separating capital expenditure approval from operational technology budgets. This bifurcation is most visible in North American automotive supply chains where fleet standardization programs favor multi-brand service agreements over single-source motor packages.
Industrial Motor Market Segmentation
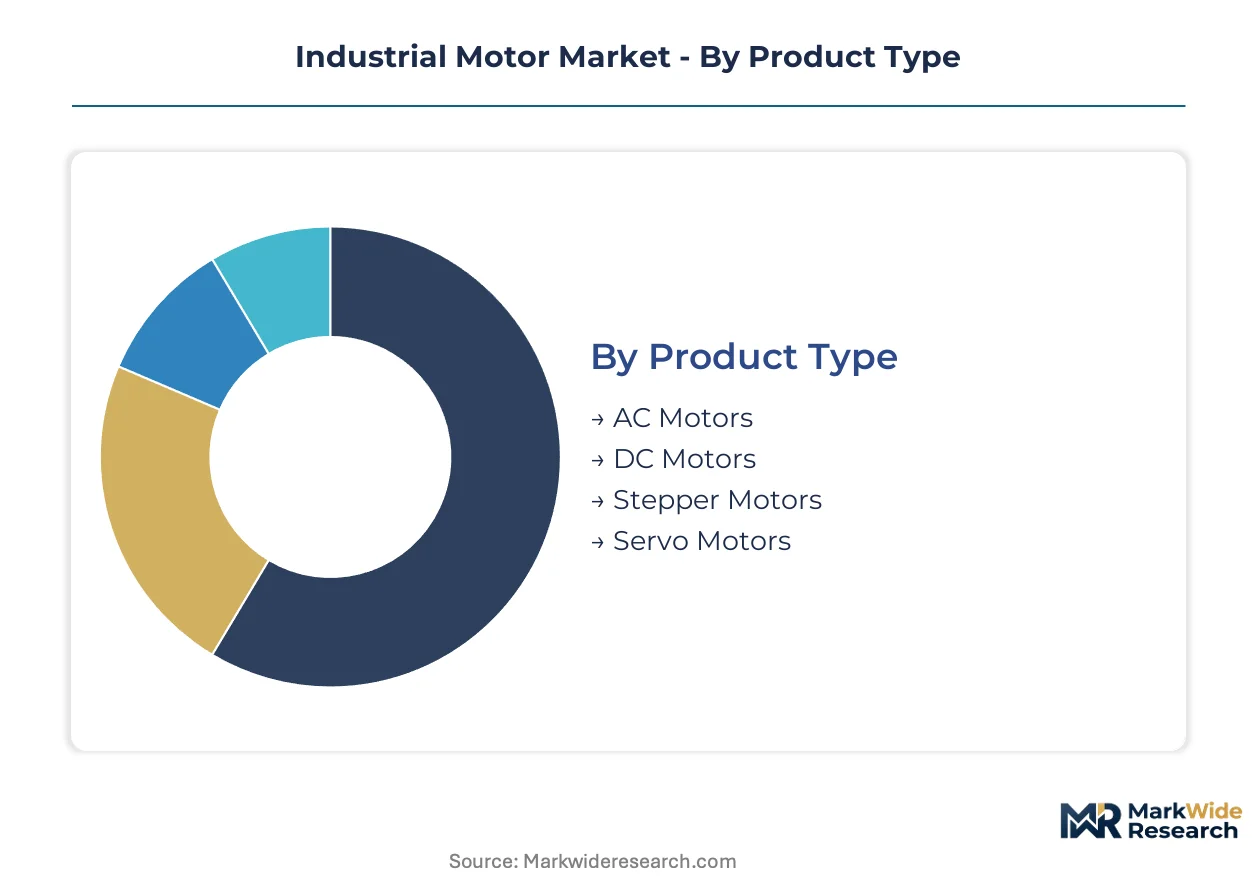
Industrial motor procurement follows distinct technical and economic logics across product architectures, deployment settings, and operational intensities. Segmentation reveals where efficiency mandates, automation requirements, and asset lifecycle pressures concentrate replacement demand and margin capture.
Product Type:
Standardization dominates at the base of the power spectrum, while customization intensity rises with precision requirements and variable-speed operation.
- AC Motors:Rugged squirrel-cage and wound-rotor designs operate across 0.12 kW to 100 MW ratings with direct grid compatibility. Demand concentrates in Chinese steel mills and German automotive stamping plants where IE3 retrofit mandates accelerate replacement of 1980s-era induction fleets.
- DC Motors:Wound-field and permanent magnet architectures deliver high starting torque for hoisting and extrusion equipment. Mining operators in Western Australia and Chilean copper belts specify these for dragline and shovel drives where precise speed control under heavy load determines productivity.
- Stepper Motors:Hybrid and variable reluctance designs provide open-loop positioning for CNC machines and 3D printing equipment.
- Servo Motors:Closed-loop vector control systems enable sub-arcminute positioning accuracy for robotics and semiconductor fabrication.
Leading the category by volume: AC Motors. Expanding most quickly: Servo Motors.
Application:
Volume scales with installed base density, while margin concentrates where energy codes and automation intensity intersect.
- Manufacturing:Metal cutting, forming, and assembly operations deploy motors across the full power spectrum from fractional horsepower feeders to multi-megawatt rolling mill drives. Automotive OEMs in Michigan and appliance producers in Mexico's Bajío region are unbundling motor procurement from aftermarket service contracts.
- HVAC:Centrifugal chillers, air handling units, and cooling tower fans specify high-efficiency designs where ASHRAE 90.1 and California Title 24 compress payback periods. Building retrofits in New York and Texas represent concentrated margin pools as owners face accelerated depreciation schedules for non-compliant equipment.
- Conveyors:Bulk material handling and parcel sorting systems prioritize reliability over precision in continuous-duty environments.
- Robotics:Articulated arms and collaborative cobots demand compact, high-torque-density motors with integrated encoders.
Dominant by installed base: Manufacturing. Steepest expansion trajectory: Robotics.
End User:
Capital intensity and operating environment severity determine specification grade and service attachment rates.
- Oil & Gas:Upstream drilling rigs, midstream compression stations, and downstream refining units specify explosion-proof and severe-duty enclosures. Permian Basin operators and North Sea platforms are replacing decades-old motors to meet emissions compliance and reduce fuel consumption.
- Mining:Surface and underground extraction equipment faces abrasive dust, moisture ingress, and continuous overload conditions. Western Australian iron ore operators pilot switched reluctance designs to eliminate rare-earth magnet dependencies in haul truck and conveyor applications.
- Construction:Mobile cranes, concrete pumps, and tunnel boring machines require high torque-to-weight ratios in intermittent duty cycles.
- Agriculture:Irrigation pumps, grain handling, and livestock ventilation systems prioritize first-cost economy over efficiency premium in price-sensitive procurement.
Highest specification intensity: Oil & Gas. Gaining share fastest: Mining.
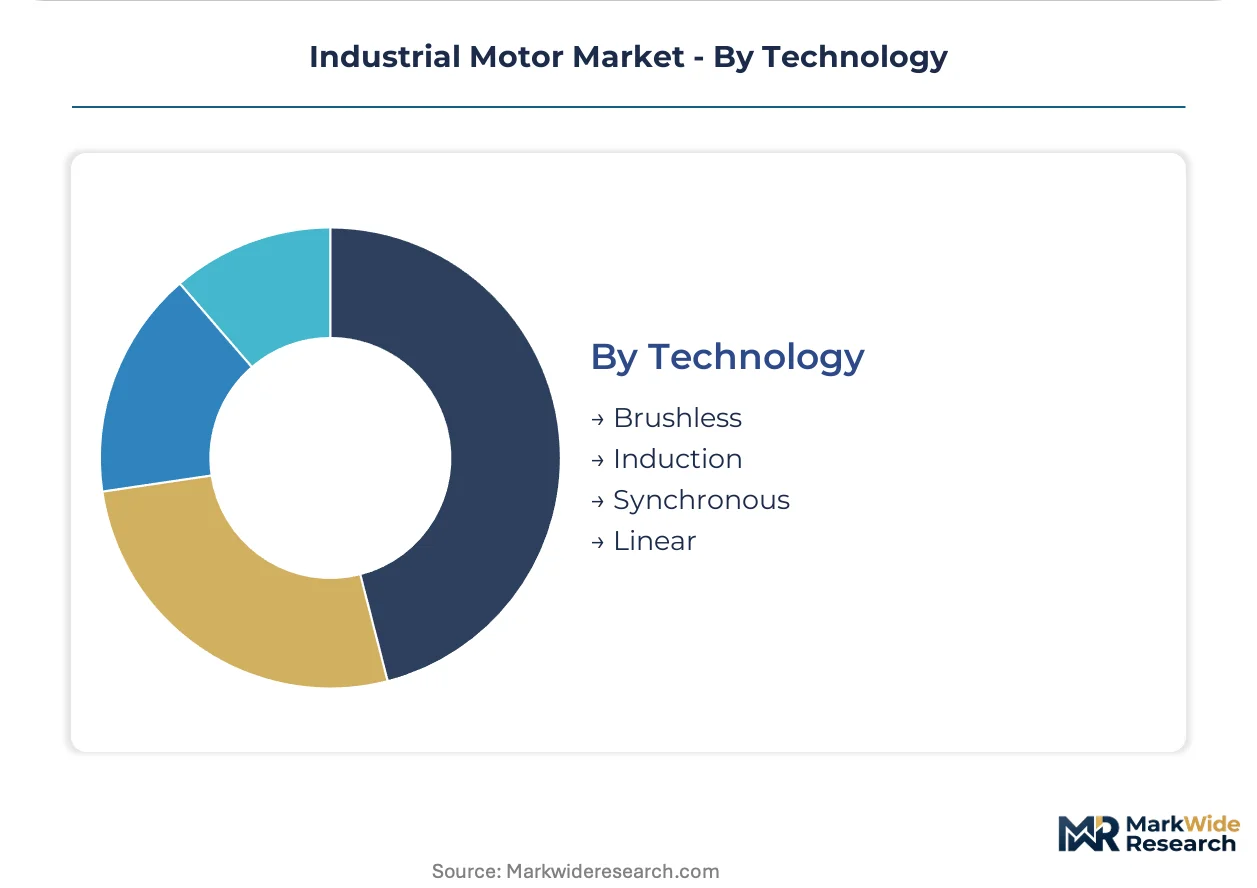
Technology:
Architectural choices trade rotor simplicity against efficiency ceiling and control complexity.
- Brushless:Permanent magnet synchronous and electronically commutated designs eliminate mechanical commutation for maintenance-free operation. Precision manufacturing environments in Japan and South Korea specify these for spindle and positioning applications where thermal stability determines part quality.
- Induction:Squirrel-cage rotors with cast aluminum or copper bars dominate where ruggedness and cost efficiency outweigh premium efficiency requirements. India's textile clusters in Gujarat and Tamil Nadu under PLI scheme incentives are upgrading from IE1 to IE3 induction fleets.
- Synchronous:Wound-rotor and permanent magnet designs maintain constant speed under varying load for process stability.
- Linear:Direct-drive electromagnetic propulsion eliminates mechanical transmission for high-speed positioning and maglev transport.
Widest installed base: Induction. Climbing the fastest: Brushless.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates replacement demand through state-backed industrial modernization programs, while efficiency mandates in Germany and the United States force premature retirement of aging installed bases.
China
State-backed industrial modernization programs and expanding manufacturing clusters drive motor replacement cycles in the Yangtze River Delta. GB 18613 efficiency standards impose parallel tiers that shape domestic procurement rules and import eligibility. Steel mills in Jiangsu province are retiring 1980s-era induction fleets ahead of mechanical failure.
Germany
Automotive stamping plants and precision manufacturing environments sustain premium demand for high-efficiency architectures. The EU Ecodesign Directive mandates IE3 minimums for motors above 0.75 kW, compressing payback periods for retrofit investments. The Rhine-Ruhr corridor pilots switched reluctance designs in bulk material handling to hedge rare-earth supply risk.
United States
Petrochemical corridors in Texas and Ohio face accelerated depreciation schedules for non-compliant equipment under tightening NEMA MG 1 Table 12-12 enforcement. The Department of Energy considers IE4-equivalent thresholds for motors above 50 horsepower. Permian Basin exploration operators replace decades-old drilling rig motors to meet emissions compliance.
India
PLI scheme incentives for industrial automation open replacement demand in Gujarat and Tamil Nadu textile clusters. BIS certification programs impose efficiency tiers that reshape procurement patterns among domestic manufacturers. Mumbai-Pune manufacturing belt facilities upgrade from IE1 to IE3 induction fleets under modernization mandates.
Japan
Precision manufacturing environments in Kanto and Kansai regions specify brushless architectures where thermal stability determines part quality. METI efficiency guidelines align with IEC standards for export-oriented production. Nagoya automotive supply chains unbundle motor procurement from aftermarket service contracts.
Industrial Motor Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in high-efficiency architectures and fragmented competition in commodity induction designs. Tiered structures separate premium digital-integrated platforms from standard-efficiency hardware and economy-grade replacements. Strategic archetypes include vertically integrated drive-system suppliers, digital monitoring platform providers, and rare-earth magnet specialists. Dominant competitive moves span portfolio consolidation around efficiency tiers and geographic expansion into PLI-subsidized manufacturing clusters.
Within the integrated-systems tier, Siemens AG and ABB Ltd occupy positions as European-based industrial conglomerates with captive supply of drive technologies. Nidec Corporation exemplifies the rare-earth magnet specialist archetype as a Japanese Co., Ltd. with concentrated expertise in high-efficiency brushless architectures. These three anchors represent distinct strategic vectors: backward integration into powertrain stacks, extension of service revenue through digital platforms, and specialization in precision manufacturing environments.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| Nidec Corporation |
| WEG Electric Corp |
| Regal Rexnord Corporation |
| Rockwell Automation |
| Johnson Electric |
| Toshiba Industrial Products |
| Eaton |
| Others |
Cost & Logistics Intelligence
Upstream oil and gas operators in the Permian Basin and North Sea anchor premium-tier procurement through emissions-compliant replacement programs, while textile clusters in Gujarat and Tamil Nadu concentrate entry-level demand under India's PLI scheme incentives. This buyer bifurcation sustains a three-tier pricing structure across premium, standard, and economy levels.
Pricing Analysis
Volume concentrates in standard-efficiency induction motors for manufacturing retrofits, while margin pools in IE4 super-premium architectures for precision environments. Price differentiation rests on GB 18613 and NEMA MG 1 certification tiers plus after-sales service bundling. Cost compression in fractional-horsepower wound-rotor lines is intensifying because copper LME volatility above historical baselines squeezes OEM margins. Textile procurement in India shows highest price sensitivity; German automotive stamping plants demonstrate lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated drive-motor systems, while distributor networks serve fragmented aftermarket replacement. Manufacturing concentrates in China, Germany, and Japan. NdFeB magnet processing draws from China's Inner Mongolia corridor, electrical steel feeds from South Korean and Japanese mills, and copper winding supply rests on Chilean and Peruvian mining output. Single-source vulnerability in rare-earth magnet supply chains exposes procurement to export quota risks. Distribution runs through authorized distributor networks with certified service attachment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory efficiency mandates are consolidating the industrial motor landscape, forcing weaker players lacking IE3 certification capabilities or rare-earth magnet sourcing relationships to exit. Margin compression in commodity induction tiers accelerates this Darwinian pressure.
For Market Incumbents: To counter rare-earth supply concentration in China's Inner Mongolia processing corridor, deepen backward integration into magnet recycling and switched reluctance R&D. Capture channel control by embedding predictive maintenance platforms that extend service revenue beyond hardware shipment cycles. For New Entrants and Emerging Players: The price-point gap between premium digital-integrated platforms and economy-grade replacement motors opens white-space in India's PLI-subsidized textile clusters and Mexico's Bajío appliance manufacturing belt. Target HVAC retrofit mandates in California and New York where ASHRAE 90.1 compliance compresses payback periods. Lead with unbundled aftermarket service contracts that separate capital expenditure from operational technology budgets. For Investors and Strategic Acquirers: Distressed-cycle entries favor brushless motor specialists with captive rare-earth sourcing in Japan and South Korea. Long-term viability hinges on 5-10 year positioning around IE4-equivalent architectures as NEMA MG 1 enforcement tightens. Monitor US Department of Energy threshold deliberations for motors above 50 horsepower as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Supply | Captive NdFeB sourcing hedges export quota risks from China's Inner Mongolia corridor. |
| Predictive Maintenance Platform Launch | Vibration-sensing motor mounts with edge analytics create recurring revenue streams beyond hardware. |
| IE4 Super-Premium Certification Investment | NEMA MG 1 threshold tightening above 50 horsepower rewards early compliance positioning. |
| PLI Scheme Manufacturing Footprint | Gujarat and Tamil Nadu textile clusters open subsidized replacement demand under Indian industrial policy. |
| Switched Reluctance Architecture Development | Rotor simplicity eliminates rare-earth dependencies for mining operators in Western Australia. |
Research Approach
Independent corroboration across maintenance directors at process industry facilities, OEM procurement teams at automotive stamping plants, and aftermarket service heads at authorized distributor networks underwrites the qualitative findings. Secondary validation draws from US Department of Energy enforcement bulletins, EU Ecodesign Directive implementation reports, GB 18613 standard updates, and SEC 10-K disclosures from listed motor manufacturers. Bottom-up unit shipment estimates and top-down macroeconomic absorption rates triangulate market sizing.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product architecture, application intensity, end-user capital requirements, and efficiency certification tier. CAGRs derive from regression analysis against industrial production indices and regulatory mandate timelines. Copper LME futures curves and rare-earth export quota announcements feed commodity-sensitive forecast inputs.
Inputs from plant engineer interviews and customs trade databases were available through the study window; gaps in real-time distributor inventory data introduce uncertainty bands around replacement cycle timing. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and commodity price trajectory. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Global Permanent Magnet Motor Market
Industrial Motors
Flatwire & HAIR-PIN Motor Market
Industrial Motors
Global Brushed DC Motor Market
Industrial Motors
Brushless DC Motor Market
Industrial Motors
Global Refrigeration Oil Market
Industrial Motors
Europe Tank Insulation Market
Industrial Motors
Power Scraper Market
Industrial Motors
Power Stacker Market
Industrial Motors
AC Motor Market
Industrial Motors
China AC Motor Market
Industrial Motors
North America Industrial Motors Market
Industrial Motors
Asia Pacific Safety Drives and Motors Market
Industrial Motors
Global Direct Current (DC) Motor Market
Industrial Motors
Charging Nitrogen Gas Systems Market
Industrial Motors
Submersible Pump Motor Market
Industrial Motors
Food Grade Hydraulic Oil Market