
 US Electric Towers and Poles Market | 2026-2036
US Electric Towers and Poles Market Size, Share, and Industry Trends Forecast 2026-2036
US Electric Towers and Poles Market Analysis
Aftermarket service revenue is narrowing toward preventive maintenance and structural health monitoring as utilities extend asset life cycles. Valmont Industries leverages its domestic manufacturing footprint to anchor supply contracts with major regional transmission organizations. Quanta Services sustains field installation dominance through specialized storm-response crews and turnkey EPC capabilities.
US electric towers and poles are load-bearing structures engineered to heights exceeding 100 feet, fabricated from galvanized steel, laminated wood, or fiber-reinforced polymer composites, and designed to withstand NESC-specified wind and ice loading for conductor support across transmission, distribution, and substation applications. Steel transmission towers command the largest installed base but face margin compression from rising alloy costs, while composite distribution poles represent the fastest-expanding material segment as utilities pursue corrosion resistance and reduced lineman exposure in coastal zones. Urban infrastructure applications now outpace rural electrification in pole replacement velocity due to undergrounding resistance and 5G colocation demands.
FERC, the National Electrical Safety Code, and state-level public utility commissions collectively govern structural design standards, right-of-way access, and rate-base treatment for new transmission investments. NESC 2023 edition updates on extreme wind loading are forcing upgrades in Gulf Coast and Atlantic seaboard jurisdictions. Stakeholders must monitor interconnection queue reform proceedings and their downstream effects on tower procurement timing and specification intensity.
Market Dynamics
FERC Order 1000 is forcing interstate transmission planners to unbundle cost allocation from incumbent utility territories, opening procurement to non-incumbent tower fabricators and eroding historical supplier lock-in across regional transmission organizations.
Growth Catalysts
- Renewable interconnection queues:Texas, California, and Midwest ISOs are procuring double-circuit steel towers to clear backlog projects connecting wind and solar farms to bulk power systems.
- NESC 2023 extreme wind loading:Gulf Coast and Atlantic seaboard jurisdictions are mandating structural upgrades that accelerate replacement cycles for aging galvanized steel infrastructure.
- Composite material advances:Fiber-reinforced polymer poles are penetrating coastal distribution networks where salt corrosion degrades traditional wood and steel assets.
Market Restraints
- Alloy cost volatility:Galvanized steel prices fluctuate with zinc and scrap metal commodity markets, compressing fabrication margins for transmission tower suppliers.
- Domestic foundry concentration:Structural steel rolling capacity concentrates in legacy industrial corridors, creating geographic supply bottlenecks during surge demand periods.
- Right-of-way access friction:State-level public utility commission permitting timelines extend project completion horizons, delaying tower installation revenue recognition.
Strategic Opportunities
- 5G colocation infrastructure:Urban distribution poles are being retrofitted with antenna mounting hardware, creating secondary revenue streams for pole owners in dense metropolitan markets.
- Preventive maintenance services:Drone-based structural health monitoring and lineworker safety training contracts represent unbundled service revenue adjacent to hardware sales.
- Storm-hardening mandates:State regulators in hurricane-prone regions are directing utilities toward composite and engineered wood poles with documented resilience ratings.
Industry Challenges
- Lineworker training gaps:Composite pole installation requires specialized climbing and hot-stick techniques that legacy field crews must recertify to perform safely.
- Interconnection queue reform uncertainty:FERC proceedings on cluster study processes are delaying final tower specifications until grid impact studies conclude.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Electric Towers and Poles Market |
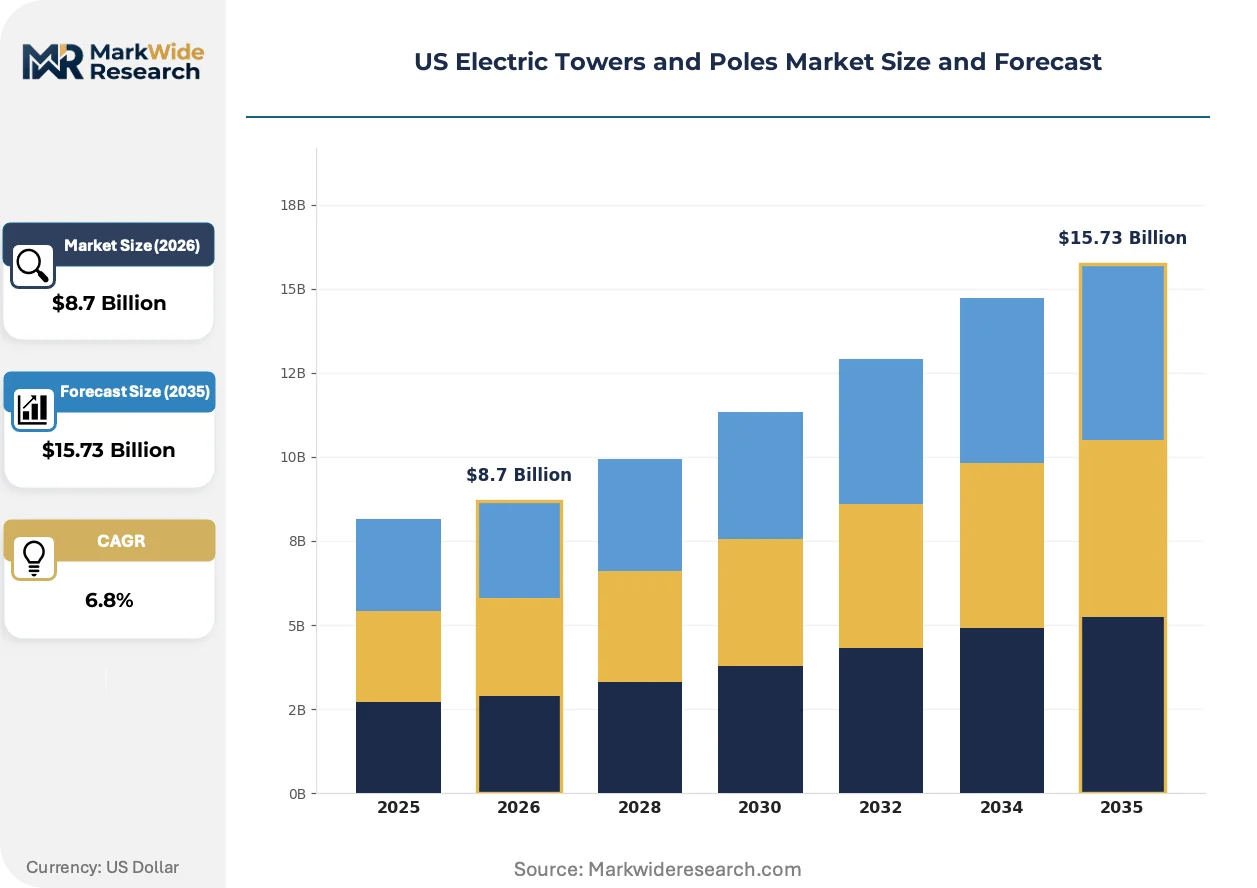
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transmission Towers, Distribution Poles, Substation Structures, Specialty Towers Material: Steel, Concrete, Wood, Composite Application: Power Transmission, Telecommunication, Renewable Energy, Urban Infrastructure Installation Type: Onshore, Offshore, Rural, Urban |
| Companies Covered | Quanta Services, Valmont Industries, Stella-Jones, AECOM, MasTec, Kiewit Corporation, Burns & McDonnell, Sabre Industries, Primoris Services Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Electric Towers and Poles Market Emerging Trajectories
Digital design tools and automated fabrication are compressing tower engineering cycles while regulatory pressure on climate resilience is rewriting material specifications across the value chain.
Fiber-reinforced polymer composite poles are rendering obsolete traditional wood distribution structures in coastal and chemically aggressive environments. Duke Energy and Florida Power & Light are specifying pultruded composite designs for new lateral extensions. The technology is rendering obsolete century-old wood treatment processes that fail under sustained salt spray exposure.
FERC Order 1000 regional transmission planning mandates are unbundling cost allocation from incumbent utility territories. Non-incumbent developers now procure towers independently of legacy transmission owners. Texas ERCOT and PJM Interconnection markets are seeing the most active non-utility developer procurement activity.
Integrated EPC contracting is consolidating field installation and hardware supply under single-source agreements. Traditional tower fabricators without turnkey construction capabilities are losing share to full-service providers. This pattern concentrates in the Southeast where storm-response mobilization requirements favor unified command structures.
US Electric Towers and Poles Market Segmentation
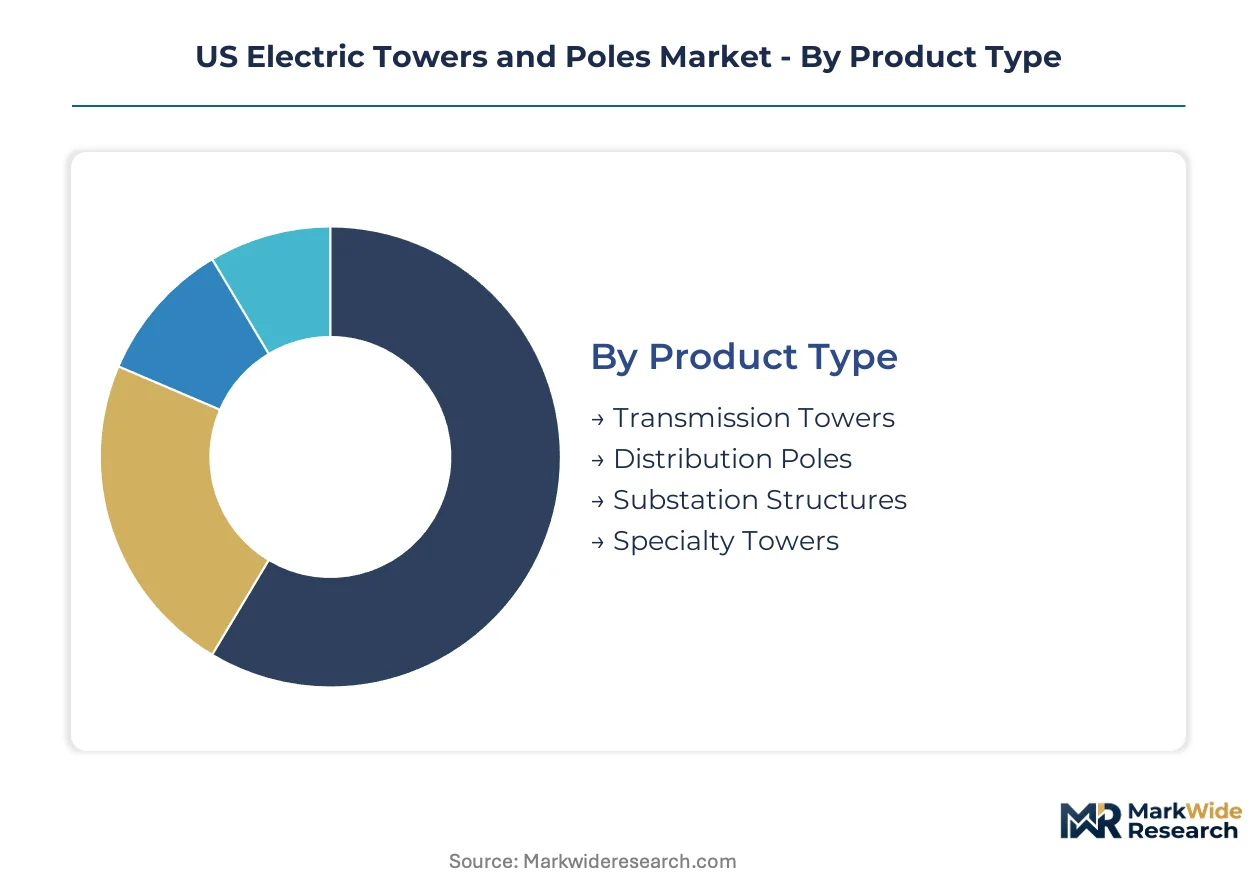
Segmentation in the US Electric Towers and Poles Market reveals divergent procurement patterns across material types and voltage classes. Utilities calibrate specifications to NESC loading zones, coastal corrosion exposure, and colocation revenue potential.
Product Type:
After-sales service intensity varies sharply across voltage tiers, with transmission assets demanding structural health monitoring contracts that distribution poles rarely justify.
- Transmission Towers:Lattice and monopole steel structures engineered for 69kV to 765kV conductor support dominate capital procurement budgets. ERCOT and PJM interconnection queues are driving demand for double-circuit designs that maximize right-of-way utilization across Texas and Mid-Atlantic corridors.
- Distribution Poles:Single-circuit structures under 69kV constitute the highest-volume installed base requiring cyclical replacement. Florida Power & Light and Duke Energy are accelerating composite specifications for coastal lateral extensions where salt spray degrades traditional materials.
- Substation Structures:Dead-end towers, bus supports, and switchyard frames engineered for concentrated mechanical loading.
- Specialty Towers:Guyed-V, delta, and river-crossing configurations for constrained terrain or extreme span requirements.
By volume, Distribution Poles leads. By growth pace, Specialty Towers is ahead.
Material:
Cost tier differentiation separates premium corrosion-resistant specifications from commodity-grade alternatives in utility rate-base filings.
- Steel:Galvanized lattice and tubular structures fabricated from ASTM A572 and A992 grades anchor transmission procurement. Rising zinc and scrap volatility is compressing fabrication margins for domestic rolling mills concentrated in legacy industrial corridors.
- Composite:Fiber-reinforced polymer pultrusions specified for coastal distribution networks are displacing wood in salt-aggressive environments. Duke Energy and Florida Power & Light have adopted pultruded designs for new lateral builds where century-old wood treatment processes fail.
- Concrete:Prestressed spun-cast poles for high-moment applications in hurricane-prone jurisdictions.
- Wood:Southern yellow pine and Douglas fir pressure-treated with pentachlorophenol or CCA preservatives for rural cost-sensitive deployments.
Steel commands the largest installed base. Composite is climbing the fastest.
Application:
Volume concentration centers on bulk power transfer, though colocation revenue is rewriting returns calculations for urban distribution assets.
- Power Transmission:Bulk system interconnection and grid backbone reinforcement across ISO territories. FERC Order 1000 unbundling is opening procurement to non-incumbent developers in ERCOT and PJM markets.
- Urban Infrastructure:Distribution poles retrofitted with 5G antenna mounting hardware in dense metropolitan markets. Verizon and T-Mobile colocation leases are creating secondary revenue streams for pole owners resisting undergrounding mandates.
- Renewable Energy:Wind and solar farm collector systems and substation tie-lines.
- Telecommunication:Dedicated fiber and microwave relay structures outside power utility ownership.
Power Transmission leads by capital deployed. Urban Infrastructure is gaining share fastest.
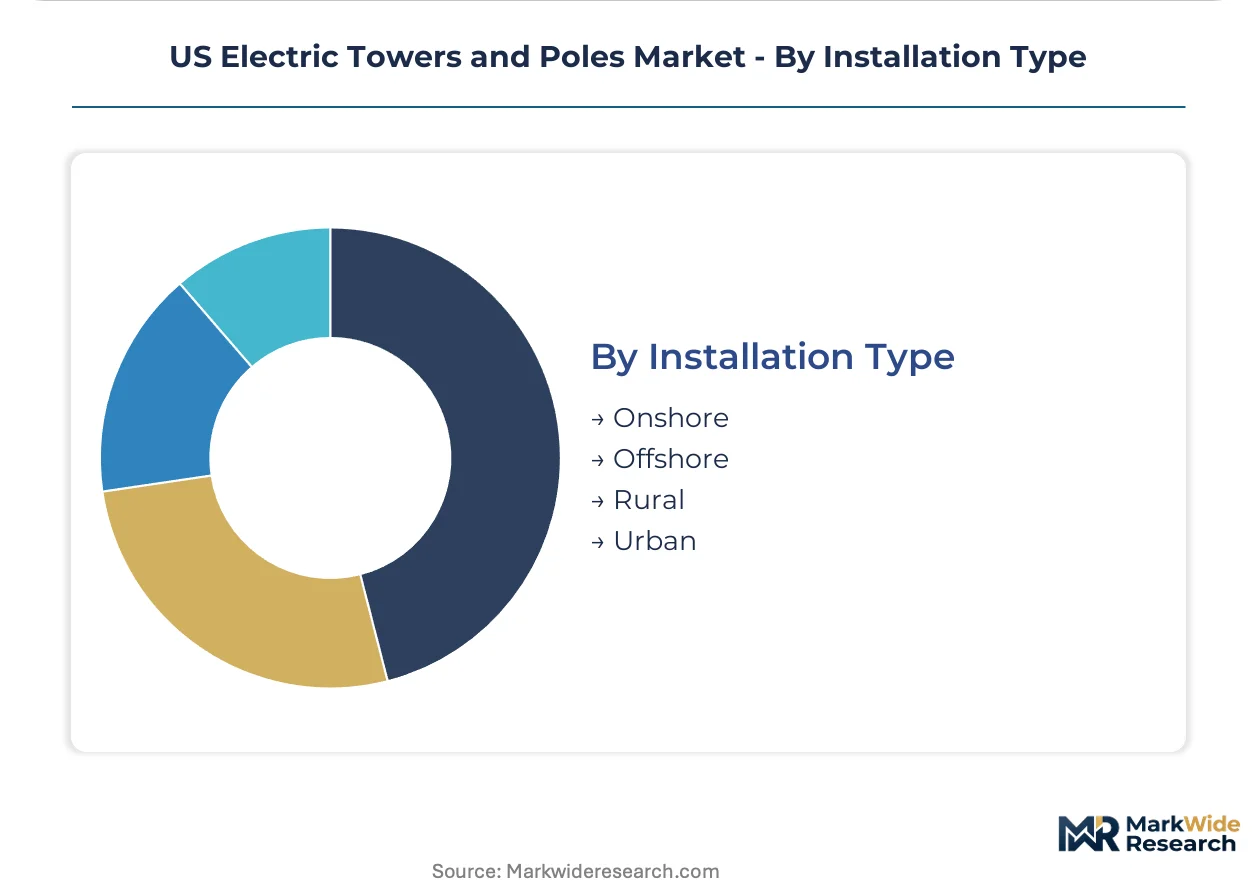
Installation Type:
Geographic deployment patterns reflect population density gradients and coastal exposure severity in procurement specifications.
- Urban:Undergrounding resistance and 5G colocation demands are accelerating pole replacement velocity above rural rates. Municipal permitting complexity extends project timelines but unlocks antenna lease revenue.
- Onshore:Continental interior deployments across Texas, California, and Midwest renewable zones dominate transmission procurement.
- Rural:Cost-optimized wood and steel specifications for low-density feeder extensions.
- Offshore:Submarine cable transition structures and coastal platform support in limited Great Lakes and Atlantic applications.
Onshore leads by unit volume. Urban is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement intensity varies sharply across US sub-regions, with price-sensitive rural utilities in the Mountain West contrasting against specification-driven coastal operators absorbing premium material costs for corrosion resistance.
Texas and ERCOT
Renewable interconnection queues are driving double-circuit steel tower procurement for wind and solar farm tie-lines. FERC Order 1000 unbundling has opened transmission planning to non-incumbent developers independent of legacy utilities. Houston and Dallas-Fort Worth anchor fabrication and EPC contractor concentration.
California and the Southwest
Wildfire hardening mandates and undergrounding resistance are accelerating composite and engineered wood pole specifications. California Public Utilities Commission fire-safety regulations are forcing accelerated replacement of aging infrastructure. Los Angeles Basin and Central Valley distribution networks are prioritizing storm-resilient materials.
Midwest ISO Territories
Wind farm collector systems and bulk transmission backbone expansion are concentrating steel lattice tower demand. State regulators in Illinois and Ohio are implementing NESC 2023 extreme wind loading upgrades. Chicago and Cleveland industrial corridors host structural steel rolling capacity serving regional procurement.
Southeast and Florida
Hurricane hardening directives are displacing traditional wood poles with composite and prestressed concrete specifications. Florida Public Service Commission storm-resilience mandates are rewriting material standards for coastal lateral extensions. Duke Energy and Florida Power & Light operations in the Tampa-Orlando corridor are driving pultruded composite adoption.
Northeast Corridor
Urban undergrounding resistance and 5G colocation demands are sustaining distribution pole replacement velocity above national averages. New York and Massachusetts public utility commissions are balancing municipal permitting complexity with antenna lease revenue opportunities. Boston and New York City metropolitan utilities are retrofitting poles with carrier-neutral mounting hardware.
US Electric Towers and Poles Market Vendor Landscape
Capability concentration sits with specialized fabricators commanding premium specifications; scale advantage sits with integrated EPC providers bundling installation and hardware supply. The market structures around three tiers: domestic steel tower specialists, composite material innovators, and turnkey construction integrators. Dominant competitive moves include backward integration into captive steel rolling capacity and strategic partnerships with regional transmission organizations for long-term supply agreements.
Among US-based operators, Valmont Industries, Quanta Services, and Sabre Industries occupy distinct archetype positions. Valmont Industries exemplifies the domestic manufacturing anchor model, leveraging continental fabrication footprints to secure supply contracts with major regional transmission organizations. Quanta Services represents the integrated EPC tier, sustaining field installation dominance through specialized mobilization capabilities and unified project command structures. Sabre Industries sits within the specialized fabricator tier, focusing on engineered structural solutions for transmission and telecommunications applications.
| Leading Market Players |
|---|
| Quanta Services |
| Valmont Industries |
| Stella-Jones |
| AECOM |
| MasTec |
| Kiewit Corporation |
| Burns & McDonnell |
| Sabre Industries |
| Primoris Services Corporation |
| Others |
Supply Flow & Price Mechanics
Commodity volatility in zinc and scrap steel markets compresses fabrication margins while simultaneously widening spreads between standard-grade galvanized structures and premium corrosion-resistant specifications. This cost pressure forces utilities to bundle long-term service contracts with hardware procurement, reshaping how tower fabricators structure rate-base filings and supplier agreements across FERC-jurisdictional territories.
Pricing Analysis
Aftermarket service revenue from preventive maintenance and structural health monitoring now drives lifetime value capture beyond initial hardware sales. Pricing stratifies across premium composite specifications for coastal corrosion zones, standard galvanized steel for bulk transmission, and economy-treated wood for rural extensions. Cost compression in standard steel tiers is intensifying because zinc price volatility erodes rolling mill margins. Investor-owned utilities in hurricane-prone regions show lowest price sensitivity, absorbing premium material costs for resilience-rated assets, while municipal cooperatives in the Mountain West prioritize economy specifications.
Supply Chain Analysis
Tariff exposure between the US and China dominates structural steel input costs for domestic fabrication. Supply concentrates in legacy industrial corridors around Chicago, Cleveland, and Pittsburgh, with secondary rolling capacity in Texas and California. Raw material flows draw from domestic scrap recycling networks, Canadian zinc refining, and specialized alloy imports. Single-source vulnerability concentrates in high-strength ASTM A572 plate supply for lattice tower fabrication. Distribution runs through regional transmission organization procurement pools and direct utility supply agreements, with storm-response surge capacity held by integrated EPC providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Preventive maintenance service contracts are expanding faster than pole and tower hardware sales, creating a service-attach imperative for every stakeholder archetype in this market. The shift from transactional equipment supply to recurring revenue models rewrites competitive positioning across the value chain.
For Market Incumbents: Insulate core fabrication margins through backward integration into captive steel rolling capacity or strategic tolling agreements with Midwest mills. Lock in long-term supply agreements with ERCOT and PJM regional transmission organizations before FERC Order 1000 procurement unbundling accelerates. Composite material specialists threaten traditional galvanized steel share in coastal distribution; defend through certified installation training programs that raise switching costs for utility field crews.
For New Entrants and Emerging Players: Pursue drone-based structural health monitoring and lineworker safety certification services as unbundled revenue streams adjacent to hardware sales. Target the Southeast storm-hardening mandate environment where Florida Public Service Commission directives are displacing wood with composite specifications faster than incumbent service capacity can absorb. Lead with turnkey EPC bundling that consolidates fabrication and field installation under unified project command.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated service providers over pure-play fabricators. Long-term viability hinges on exposure to recurring maintenance revenue rather than cyclical capital procurement. Acquisition targets should display captive installation capabilities or exclusive regional transmission organization supply relationships. Watch FERC interconnection queue reform proceedings as the signal for inflection in tower specification intensity and procurement timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Rolling | Captive ASTM A572 supply insulates Valmont and Sabre from zinc volatility compressing peer margins. |
| Composite Material Certification Programs | Duke Energy and Florida Power & Light specify pultruded designs requiring installer recertification that raises rival switching costs. |
| Drone-Based Structural Health Monitoring | Preventive maintenance contracts with Gulf Coast utilities create recurring revenue streams beyond hardware replacement cycles. |
| Turnkey EPC Consolidation | Quanta Services sustains field dominance by bundling storm-response mobilization with fabrication supply in Southeast markets. |
| 5G Colocation Hardware Retrofit | Verizon and T-Mobile antenna leases on urban distribution poles generate secondary revenue for owners resisting undergrounding mandates. |
Methodological Framework
Initial hypotheses were tested against primary input from utility transmission planners, EPC contractor project managers, regional transmission organization procurement officers, and composite material R&D directors and refined through secondary validation. Primary fieldwork combined structured interviews with secondary analysis of FERC filings, EIA transmission project databases, NESC code revision records, and utility rate-base documentation. Bottom-up demand modeling from interconnection queue data was triangulated against top-down market sizing from fabricated structure shipment records.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled by material type, voltage class, installation geography, and utility ownership structure. CAGRs were derived from utility capital expenditure projections and renewable interconnection backlog clearance rates. Forecast inputs incorporated NESC 2023 extreme wind loading adoption timelines and FERC Order 1000 regional implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by non-utility transmission developers or rapid composite material cost reduction would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Europe Electric Space Heaters Market
Electrical Power Equipment
Carbon Brush Market
Electrical Power Equipment
Overhead Aluminium Conductors Market
Electrical Power Equipment
Storage Water Heater Market
Electrical Power Equipment
Bio-Based Transformer Oil Market
Electrical Power Equipment
Europe Electric Radiators Market
Electrical Power Equipment
Global Surge Arrester Market
Electrical Power Equipment
Fuse Link Market
Electrical Power Equipment
AC Drives Market
Electrical Power Equipment
Global Lightning Arrester Market
Electrical Power Equipment
North America Air-Insulated Switchgear Market
Electrical Power Equipment
AV Power Conditioners Market
Electrical Power Equipment
Taiwan Electric Power Equipment Market
Electrical Power Equipment
Electric Substation Market
Electrical Power Equipment
Portable Space Heater Market
Electrical Power Equipment
Motor Generator Set Market