
 GCC Idiopathic Pulmonary Fibrosis Treatment Market | 2026-2036
GCC Idiopathic Pulmonary Fibrosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Idiopathic Pulmonary Fibrosis Treatment Market Intelligence
Antifibrotic drug development is fragmenting across kinase inhibitor, lysyl oxidase inhibitor, and integrin antagonist platforms, forcing manufacturers to place divergent chemistry bets. Boehringer Ingelheim International GmbH anchors the GCC region through its established nintedanib franchise and pulmonologist education networks. F. Hoffmann-La Roche Ltd competes via its pirfenidone portfolio and biomarker-driven patient stratification tools. Galapagos NV differentiates through autotaxin inhibitor research and selective geographic partnerships.
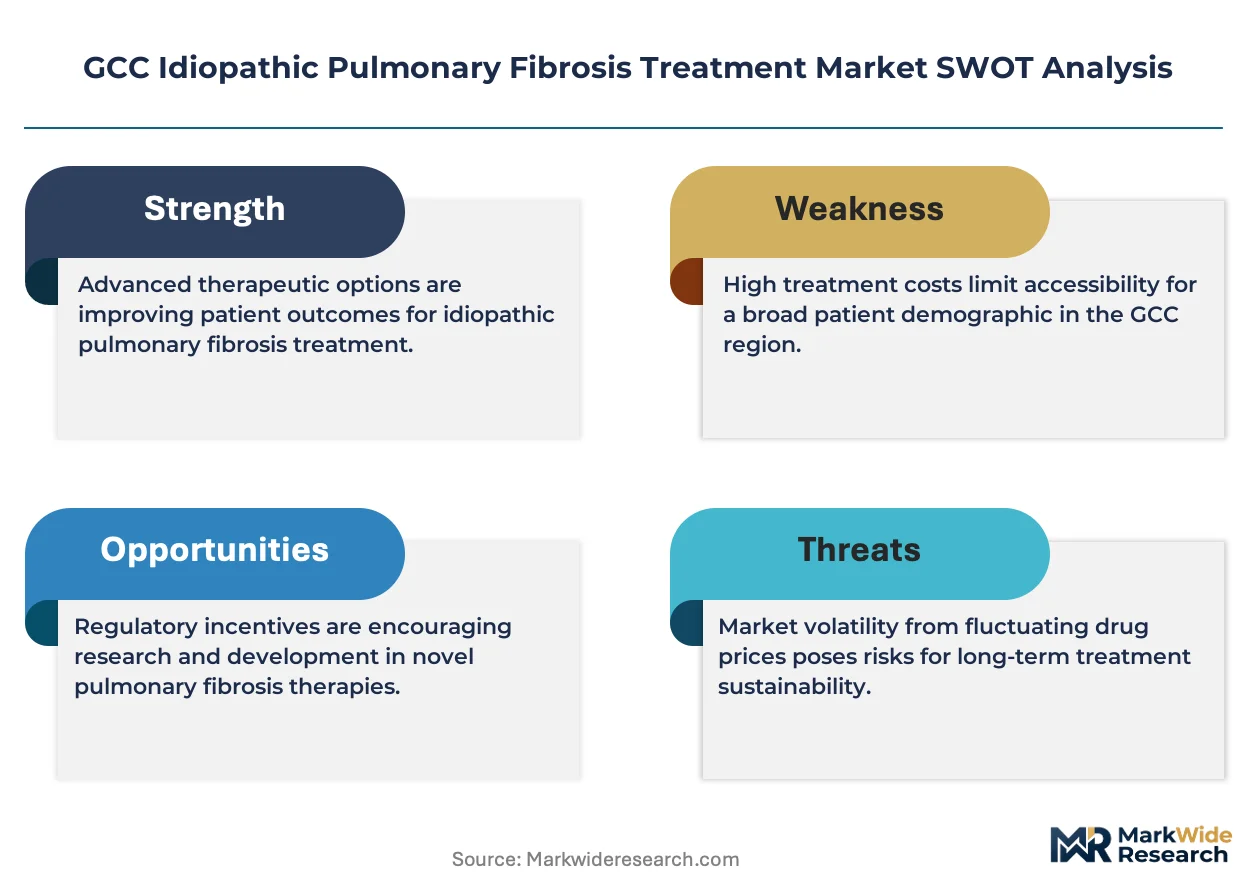
Idiopathic pulmonary fibrosis treatment encompasses pharmaceutical and supportive interventions targeting progressive, irreversible lung scarring of unknown etiology; antifibrotic agents such as nintedanib and pirfenidone function by inhibiting tyrosine kinase signaling and TGF-beta mediated fibroblast activation, respectively, to slow forced vital capacity decline. The primary commercial purpose is delaying disease progression and reducing acute exacerbation frequency in patients with a median survival of three to five years post-diagnosis. Antifibrotic agents command the dominant revenue share due to their disease-modifying label and premium positioning, while oxygen therapy represents the fastest-expanding delivery segment as home-based respiratory support gains reimbursement traction. Oral delivery mode retains the largest patient volume, though subcutaneous formulations are gaining pipeline attention for improved adherence in home care settings.
The SFDA operates the GCC's most influential pharmaceutical regulatory gateway, with its orphan drug incentives directly shaping which therapies enter Saudi Arabia first. The UAE's MOHAP maintains separate but harmonized biologic licensing requirements that manufacturers must navigate for Dubai-Abu Dhabi market access. BIS standards for medical oxygen equipment indirectly structure procurement specifications across Gulf hospital systems. Stakeholders must monitor how Saudi Vision 2030 healthcare localization mandates reshape partnership requirements for multinational drug suppliers.
Market Dynamics
The SFDA's orphan drug incentive framework is concentrating antifibrotic therapy launches into Saudi Arabia's Riyadh-Jeddah corridor ahead of broader GCC registration, reshaping how manufacturers sequence market entry and allocate pulmonologist education resources.
Growth Catalysts
- Orphan drug pathways:The SFDA's accelerated approval mechanisms for rare lung diseases compress registration timelines and attract first-molecule filings from multinational sponsors targeting the Gulf's largest patient pool.
- Tertiary hospital expansion:Saudi Arabia's Vision 2030 healthcare infrastructure investments are adding dedicated interstitial lung disease units in Riyadh and Jeddah, expanding prescriber capacity for antifibrotic initiation.
- Home oxygen reimbursement:MOHAP coverage policies in the UAE are extending portable concentrator subsidies to IPF patients, broadening addressable demand beyond hospital-based pharmaceutical therapy.
Market Restraints
- Biologic API concentration:Active pharmaceutical ingredient supply for kinase inhibitors concentrates among a limited set of European and Indian contract manufacturers, exposing nintedanib production to single-source risk.
- Specialist pulmonologist scarcity:The GCC region maintains fewer than three hundred board-certified interstitial lung disease specialists, creating a bottleneck for diagnosis and antifibrotic prescribing.
- High-dose pirfenidone tolerability:Gastrointestinal adverse events and photosensitivity limit real-world adherence to pirfenidone regimens, compressing effective therapy duration versus clinical trial benchmarks.
Strategic Opportunities
- Kuwait and Bahrain penetration:These smaller GCC markets remain underdeveloped for antifibrotic therapy, presenting first-mover advantages for manufacturers establishing pulmonologist networks ahead of competitor entry.
- Subcutaneous formulation development:Pipeline migration toward injectable delivery modes addresses oral adherence failures and aligns with home nursing capabilities expanding across Saudi Arabia's eastern province.
- Biomarker-guided stratification:KL-6 and SP-D testing protocols are gaining traction in Dubai's private hospital sector, enabling outcome-based contracting for antifibrotic therapy in high-progression-risk patients.
Industry Challenges
- ILD specialist training pipelines:Fellowship programs in interstitial lung disease remain absent across Gulf medical schools, forcing manufacturers to fund external physician education directly.
- Multinational-local partnership mandates:Saudi Vision 2030 localization requirements are forcing restructuring of distribution agreements, with SFDA preferring joint ventures for orphan drug commercialization.
- Real-world evidence collection:Fragmented electronic health record systems across UAE emirates complicate post-marketing surveillance for antifibrotic safety and effectiveness monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Idiopathic Pulmonary Fibrosis Treatment Market |
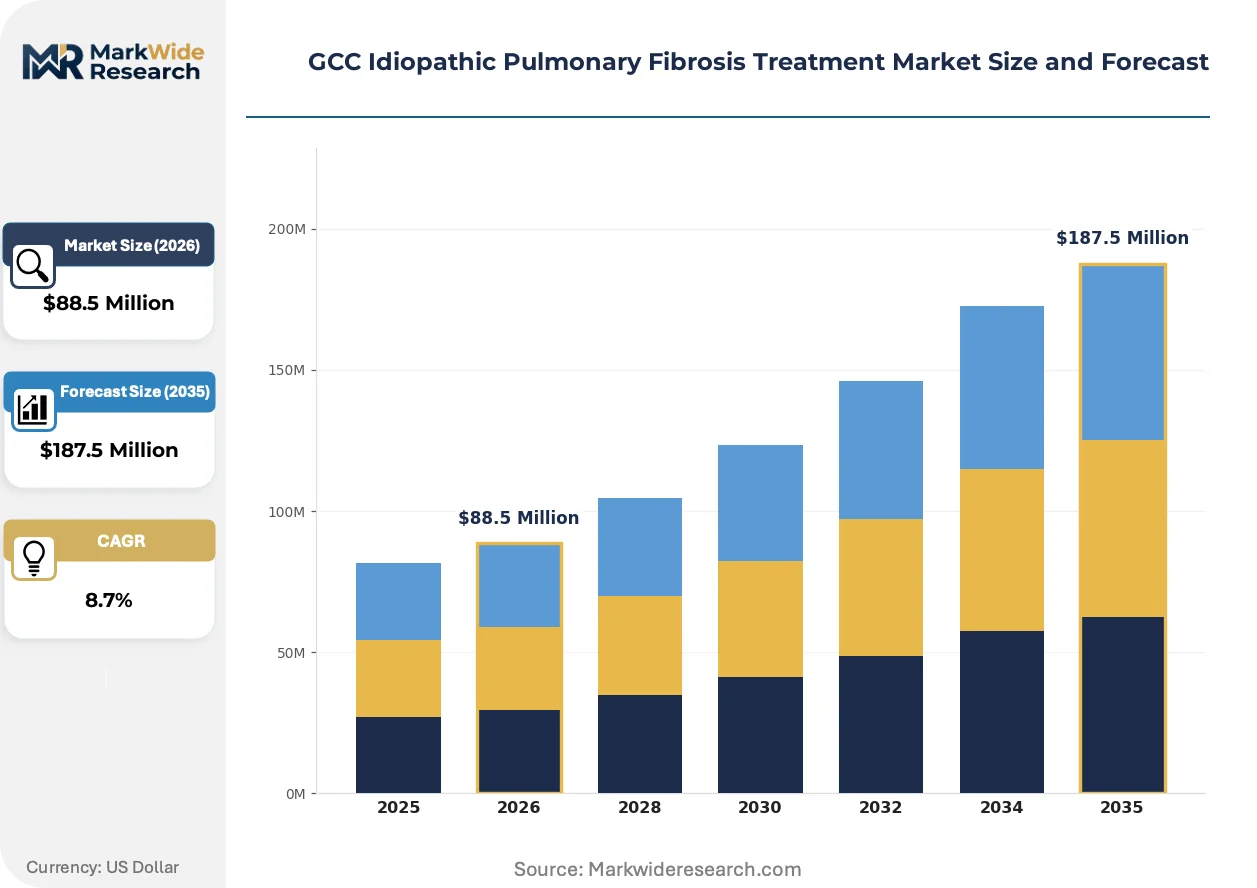
| Market Size in 2026 | $88.5 Million |
| Market Size in 2035 | $187.5 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antifibrotic Agents, Corticosteroids, Immunosuppressants, Oxygen Therapy Therapy Area: Respiratory Diseases, Pulmonology, Critical Care, Chronic Lung Conditions End User: Hospitals, Specialty Clinics, Home Care, Rehabilitation Centers Delivery Mode: Oral, Inhalation, Intravenous, Subcutaneous |
| Companies Covered | Cipla Ltd, Galapagos NV, Boehringer Ingelheim International GmbH, GlaxoSmithKline, Novartis AG, F. Hoffmann-La Roche Ltd, FibroGen Inc., Merck & Co., Inc., Bristol-Myers Squibb Company, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Idiopathic Pulmonary Fibrosis Treatment Market Strategic Shifts & Innovations
Antifibrotic therapy development is fragmenting across divergent molecular platforms, while regulatory gatekeeping and care delivery models compress toward patient stratification and home-based administration.
Lysyl oxidase inhibitor platforms are migrating from preclinical fibrosis models toward phase II IPF trials, with Galapagos NV and smaller biotech sponsors advancing selective LOXL2 antagonists. Saudi Arabia's SFDA is prioritizing review of these novel mechanisms under its orphan drug framework, enabling compressed development timelines relative to standard small-molecule pathways. The structural consequence is a technology bet divergence, forcing manufacturers to allocate chemistry resources across kinase, autotaxin, and LOX inhibitor tracks without clear clinical differentiation signals.
The SFDA's 2023 revision to orphan drug fee waivers and priority review vouchers is redirecting sponsor registration strategies toward Saudi Arabia as the GCC's first-launch market. Manufacturers are responding by front-loading pulmonologist education investments in Riyadh and Jeddah ahead of UAE and Kuwait filings. This regulatory sequencing is compressing competitive windows, with second entrants facing established prescriber relationships and formulary lock-in effects.
Patient advocacy networks in Dubai and Abu Dhabi are consolidating demand-side bargaining power, negotiating directly with manufacturers for compassionate access programs ahead of formal reimbursement. These collective patient organizations are displacing traditional hospital pharmacy procurement as the primary channel for antifibrotic access in uninsured segments. The behavioral shift is most visible in the UAE's private healthcare sector, where MOHAP coverage gaps have created a direct-to-patient distribution channel operating parallel to institutional procurement.
GCC Idiopathic Pulmonary Fibrosis Treatment Market Segmentation
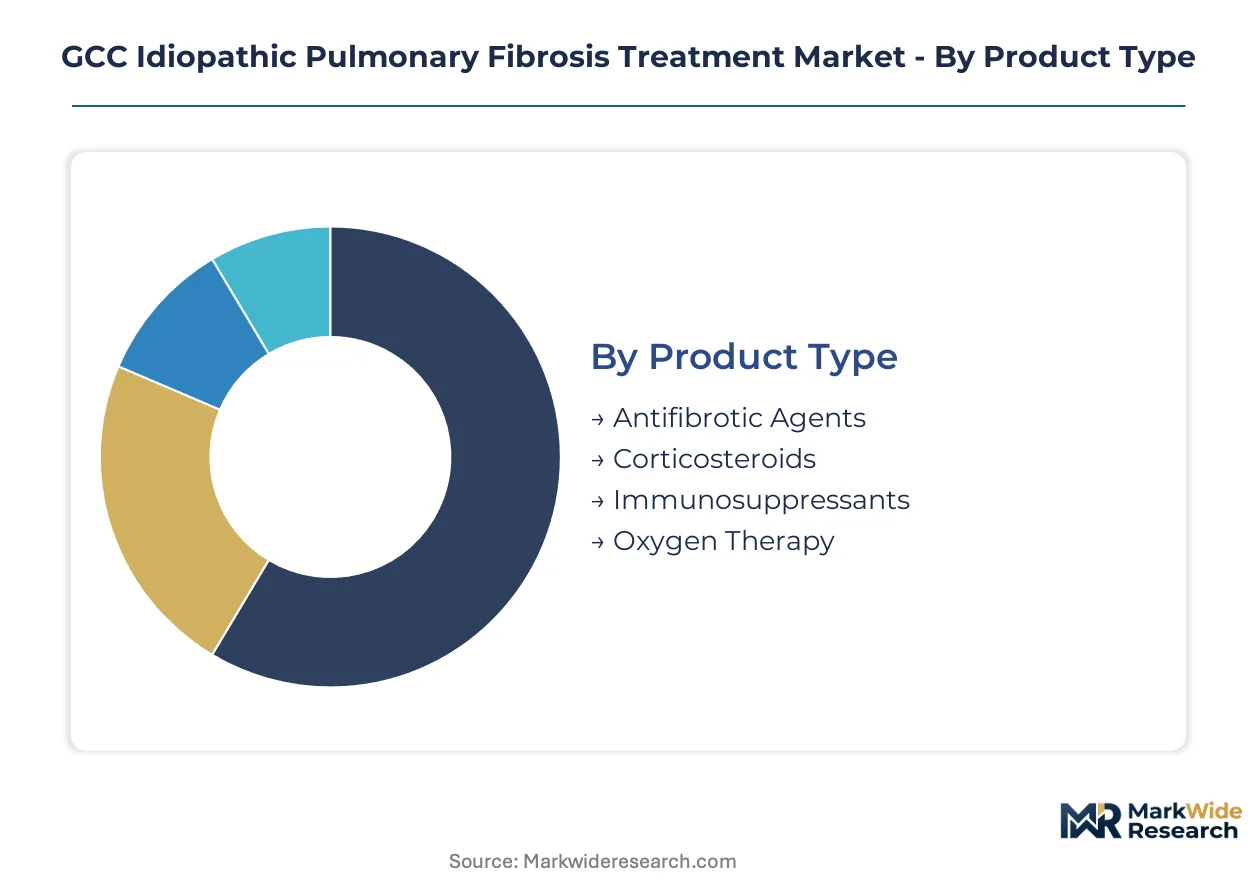
Antifibrotic therapy segmentation in the GCC reflects divergent clinical maturity across molecular platforms and care settings. Manufacturers must align chemistry investments with pulmonologist prescribing patterns and reimbursement pathways that favor disease-modifying agents over supportive interventions.
Product Type:
Mature kinase inhibitor platforms anchor commercial revenue while emerging autotaxin and lysyl oxidase inhibitors reshape pipeline allocation.
- Antifibrotic Agents:Nintedanib and pirfenidone dominate through tyrosine kinase inhibition and TGF-beta pathway modulation respectively. Saudi Arabia's SFDA orphan drug framework accelerates registration for these disease-modifying therapies, concentrating demand in Riyadh-Jeddah tertiary centers where interstitial lung disease units are expanding.
- Oxygen Therapy:Portable concentrators and liquid oxygen systems address hypoxemia in advanced IPF stages. MOHAP reimbursement policies in the UAE are extending home-based respiratory support subsidies, broadening addressable demand beyond hospital pharmaceutical spend.
- Corticosteroids:Prednisone and methylprednisolone serve acute exacerbation management despite limited disease-modifying efficacy.
- Immunosuppressants:Mycophenolate and azathioprine retain niche use in combined pulmonary fibrosis-interstitial pneumonia variants.
Antifibrotic agents retain volume leadership; oxygen therapy holds the steepest expansion curve.
Therapy Area:
Cost tier stratification separates premium disease-modifying therapy from commoditized supportive care across Gulf hospital procurement.
- Respiratory Diseases:Interstitial lung disease specialists in Saudi tertiary hospitals drive antifibrotic prescribing for idiopathic pulmonary fibrosis specifically. The concentration of board-certified pulmonologists in Riyadh and Jeddah creates geographic demand clustering that manufacturers target with education investments.
- Pulmonology:General pulmonology departments manage stable IPF patients and coordinate transitions to home oxygen. Dubai's private hospital sector is adopting KL-6 biomarker protocols to stratify patients for antifibrotic intensity.
- Critical Care:Intensive care units handle acute exacerbations requiring mechanical ventilation and rescue immunosuppression.
- Chronic Lung Conditions:Integrated chronic disease management programs are emerging in Abu Dhabi's healthcare system.
Pulmonology captures the dominant patient volume; respiratory diseases command the premium therapy concentration.
End User:
Customer type fragmentation reflects divergent procurement authority between institutional pharmacy and direct patient access channels.
- Hospitals:Saudi tertiary centers with dedicated ILD units control antifibrotic initiation and formulary placement. Vision 2030 infrastructure investments are adding interstitial lung disease capacity in Riyadh, Jeddah, and Dammam.
- Home Care:Nursing services and oxygen equipment suppliers are gaining procurement influence as MOHAP extends portable concentrator coverage. Eastern Province home nursing capabilities are expanding to support subcutaneous formulation administration.
- Specialty Clinics:Private pulmonology practices in Dubai and Abu Dhabi manage stable patients and biomarker monitoring.
- Rehabilitation Centers:Pulmonary rehabilitation facilities address functional decline in advanced disease stages.
Hospitals retain formulary control; home care is gaining the fastest procurement autonomy.
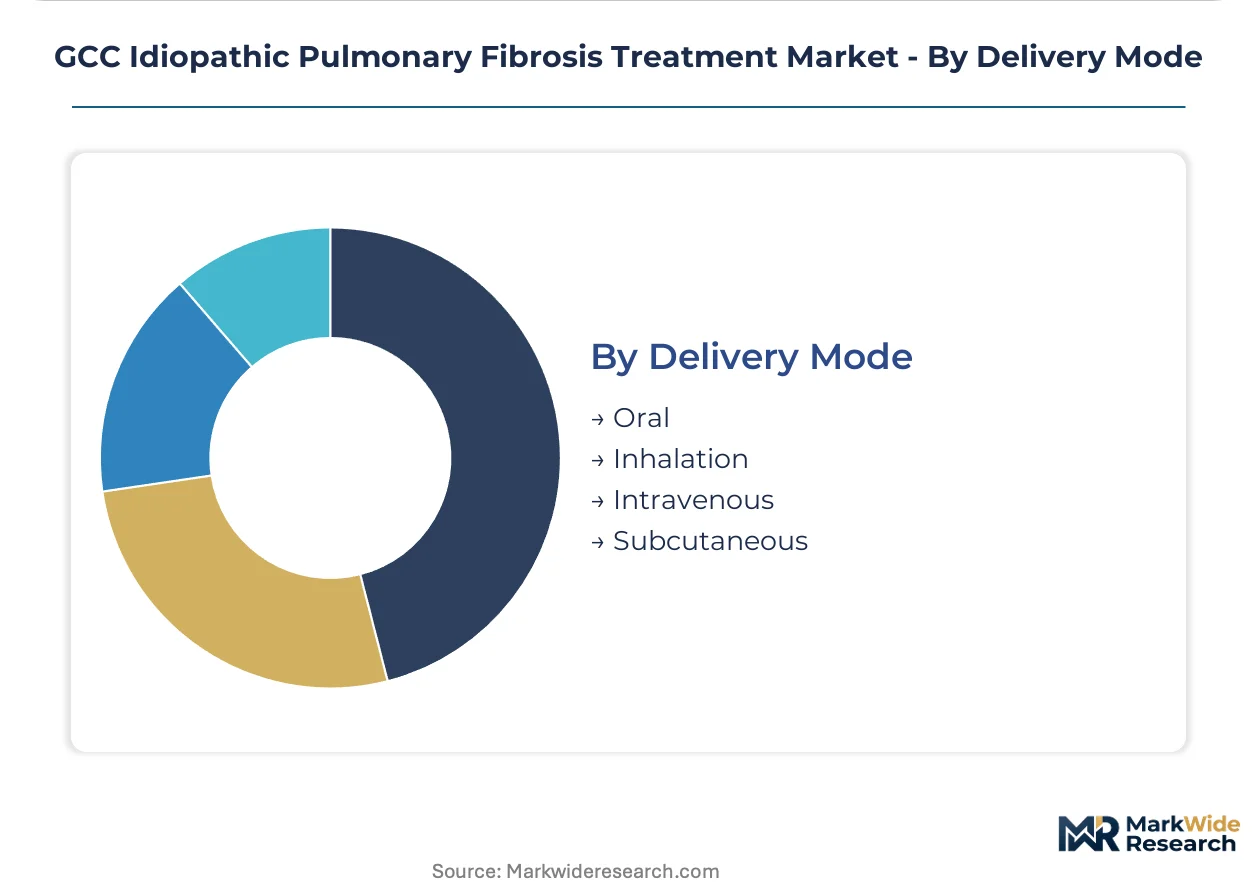
Delivery Mode:
Supply concentration in oral solid dose manufacturing is diverting toward injectable platforms for adherence optimization.
- Oral:Capsule and tablet formulations of nintedanib and pirfenidone retain the largest patient volume through twice-daily and thrice-daily dosing regimens. Gastrointestinal tolerability issues with high-dose pirfenidone compress real-world adherence versus clinical trial benchmarks.
- Subcutaneous:Pipeline migration toward injectable antifibrotics addresses oral adherence failures and aligns with expanding home nursing infrastructure. Galapagos NV and other sponsors are advancing autotaxin inhibitors with subcutaneous delivery for Saudi Arabia's eastern province.
- Inhalation:Nebulized therapies remain investigational for antifibrotic delivery to distal lung parenchyma.
- Intravenous:Hospital-based infusion maintains role for acute exacerbation rescue protocols.
Oral delivery retains patient volume leadership; subcutaneous platforms are climbing the fastest development trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antifibrotic therapy demand flows through Saudi Arabia's Riyadh-Jeddah corridor toward the UAE's Dubai-Abu Dhabi hospital network, with smaller GCC markets absorbing overflow supply through distributor intermediaries.
Saudi Arabia
Vision 2030 healthcare infrastructure investments are expanding interstitial lung disease units in Riyadh and Jeddah tertiary hospitals. The SFDA's orphan drug fee waivers and priority review vouchers compress registration timelines for nintedanib and pirfenidone sponsors. Eastern Province home nursing capabilities are scaling to support subcutaneous antifibrotic administration in Dammam and Al-Khobar.
United Arab Emirates
Dubai's private hospital sector is adopting KL-6 and SP-D biomarker protocols to stratify IPF patients for antifibrotic intensity. MOHAP reimbursement policies extend portable oxygen concentrator subsidies, broadening addressable demand beyond pharmaceutical spend. Abu Dhabi's integrated chronic disease management programs are consolidating procurement authority for antifibrotic therapy across hospital networks.
Kuwait
Underdeveloped antifibrotic prescribing infrastructure creates first-mover advantages for manufacturers establishing pulmonologist networks ahead of competitor entry. The country's national pharmaceutical regulator maintains harmonized licensing requirements with Saudi SFDA standards, enabling streamlined product registration. Kuwait City's tertiary hospitals remain the primary concentration point for interstitial lung disease diagnosis.
Qatar
Hamad Medical Corporation's centralized procurement structure concentrates antifibrotic demand within Doha's flagship hospital network. The national health system's emphasis on specialty care imports creates dependency on multinational supplier relationships forged in Saudi Arabia. Pulmonology fellowship training partnerships with European institutions are slowly expanding local diagnostic capacity.
Bahrain
Smallest GCC market by population, Bahrain presents limited standalone commercial opportunity but serves as a regulatory testbed for Saudi-registered therapies. Salmaniya Medical Complex anchors IPF diagnosis and antifibrotic initiation. Manufacturers route product through distributor relationships managed from Riyadh or Dubai rather than establishing direct commercial presence.
GCC Idiopathic Pulmonary Fibrosis Treatment Market Key Industry Players
Channel-controlling players compete with product-specialist players for formulary placement in Saudi tertiary hospitals and UAE private networks. The market structure concentrates around multinational pharmaceutical sponsors with established pulmonologist education infrastructure and orphan drug registration expertise. Two strategic archetypes dominate: kinase inhibitor platforms exemplified by tyrosine kinase blockade approaches, and TGF-beta pathway modulators targeting fibroblast activation. Competitive moves center on regulatory sequencing strategies and pulmonologist relationship investments ahead of product launch.
Among European-based pharmaceutical sponsors, Boehringer Ingelheim International GmbH and F. Hoffmann-La Roche Ltd anchor the competitive landscape through contrasting mechanism platforms. Belgian biopharmaceutical developer Galapagos NV occupies a distinct position within the autotaxin inhibitor research tier, advancing selective pipeline candidates through geographic partnership structures. These three entities represent divergent chemistry bets—kinase inhibition, TGF-beta modulation, and autotaxin blockade—that manufacturers must evaluate against SFDA orphan drug pathway timing and pulmonologist prescribing patterns.
| Leading Market Players |
|---|
| Cipla Ltd |
| Galapagos NV |
| Boehringer Ingelheim International GmbH |
| GlaxoSmithKline |
| Novartis AG |
| F. Hoffmann-La Roche Ltd |
| FibroGen Inc. |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| Others |
Cost & Logistics Intelligence
European contract manufacturers for kinase inhibitor active pharmaceutical ingredients capture disproportionate margin pools from nintedanib production, concentrating pricing power upstream while Saudi tertiary hospitals and UAE private networks absorb downstream cost pressure through formulary negotiations and MOHAP reimbursement thresholds.
Pricing Analysis
Current-generation oral antifibrotics command premium positioning against prior-generation supportive therapies, while subcutaneous next-generation platforms threaten oral volume through adherence-based value propositions. Three-tier pricing structure across originator antifibrotics, authorized generics, and compounded alternatives separates Boehringer Ingelheim and Roche originator portfolios from Cipla generic entries and regional compounding pharmacies. Cost compression in the generic tier is intensifying because Indian API suppliers are expanding capacity for pirfenidone precursors. Hospital procurement committees in Riyadh and Jeddah demonstrate lowest price sensitivity due to SFDA orphan drug formulary protections, while uninsured patient collectives in Dubai's private sector negotiate hardest on out-of-pocket antifibrotic access.
Supply Chain Analysis
Single-source vulnerability for nintedanib tyrosine kinase inhibitor synthesis concentrates in Germany, Switzerland, and selected Indian pharmaceutical manufacturing zones, exposing GCC supply continuity to European regulatory inspection schedules and Indian export licensing delays. Active pharmaceutical ingredient production draws from specialized fermentation and chemical synthesis inputs including indole derivatives, pyridine cores, and high-purity solvents subject to volatile petrochemical pricing. Tariff exposure between European API exporters and Saudi finished dose manufacturers amplifies landed cost variability for orphan drug shipments. Distribution runs through cold-chain logistics providers serving Riyadh-Jeddah hospital corridors, with secondary routing via Dubai's Jebel Ali pharmaceutical free zone for Kuwait and Bahrain markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antifibrotic therapy platforms are approaching an interoperability inflection where biomarker-guided patient stratification protocols in Dubai's private hospital sector create network effects that lock in prescriber behavior and formulary placement ahead of molecule-specific clinical differentiation.
For Market Incumbents: Insulate nintedanib and pirfenidone franchise positions by deepening pulmonologist education investments in Saudi Arabia's expanding ILD units and securing SFDA priority review voucher allocations for line-extension filings. Threat substitution from autotaxin inhibitors and lysyl oxidase antagonists demands accelerated biomarker companion diagnostic partnerships to maintain stratification-based prescribing control. Vertical integration into home oxygen service provision through distributor acquisitions in the Eastern Province addresses adherence leakage from oral therapy discontinuation. For New Entrants and Emerging Players: Kuwait's underdeveloped antifibrotic prescribing infrastructure offers first-mover white space for manufacturers establishing interstitial lung disease specialist networks ahead of competitor entry. Bahrain's regulatory testbed function enables Saudi-registered therapies to demonstrate real-world effectiveness with minimal commercial infrastructure commitment. Target pulmonology fellowship training sponsorships as the primary go-to-market angle, addressing the GCC's critical specialist scarcity while building prescriber relationships that outlast product launch windows. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors holding exclusive Saudi orphan drug commercialization rights under Vision 2030 localization mandates. Long-term viability hinges on pipeline optionality across kinase, autotaxin, and lysyl oxidase platforms rather than single-molecule concentration. Watch SFDA biomarker protocol adoption rates as the inflection signal indicating when outcome-based contracting will displace volume-based antifibrotic purchasing in premium hospital tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Protocol Adoption | KL-6 and SP-D testing integration in Dubai private hospitals enables outcome-based antifibrotic contracting. |
| Subcutaneous Formulation Development | Injectable delivery platforms address oral pirfenidone adherence failures in Saudi home nursing expansion zones. |
| Pulmonologist Education Investment | ILD fellowship sponsorships build prescriber relationships that outlast molecule-specific competitive windows. |
| Orphan Drug Registration Sequencing | SFDA priority review voucher utilization compresses Saudi first-launch timing ahead of UAE MOHAP filings. |
| Home Oxygen Service Integration | Portable concentrator coverage extension by MOHAP broadens addressable demand beyond pharmaceutical spend. |
Research Approach
Desk research of SFDA registration databases, MOHAP reimbursement bulletins, ClinicalTrials.gov antifibrotic trial listings, and Gulf hospital procurement records preceded structured interviews with Saudi pulmonology department heads, UAE formulary directors, regulatory affairs leads at multinational sponsors, and distributor commercial managers across Riyadh and Dubai. Bottom-up patient volume estimates by therapy line and delivery mode were cross-validated against top-down pharmaceutical spend data from Gulf health ministry disclosures and GPO contract aggregators.
Assumptions held constant across the modeling period include SFDA orphan drug fee waiver continuity, MOHAP portable oxygen subsidy extension, and stable pulmonologist specialist training pipeline output from European partnership programs. Segmentation dimensions incorporated treatment line, molecular platform, administration route, and regional regulatory cluster. CAGRs were derived from log-linear trend fitting across projected patient incidence, diagnosis rate improvement, and therapy penetration scenarios, with antifibrotic initiation rates and acute exacerbation frequency serving as key demand-side inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by autotaxin inhibitor sponsors or lysyl oxidase platform developers would shift outcomes through accelerated biomarker protocol adoption or compressed regulatory sequencing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Chronic Smell and Flavor Loss Treatment Market
Specialty Medicine
APOL1 Mediated Kidney Disease Market
Specialty Medicine
Muscle Wasting Disorders Market
Specialty Medicine
Coagulation Disorders Market
Specialty Medicine
Global Eye Allergy Therapeutics Market
Specialty Medicine
Triple X Syndrome Management Market
Specialty Medicine
Subdural Haematoma Market
Specialty Medicine
Atrial Septal Defect Market
Specialty Medicine
Dermatomyositis Treatment Market
Specialty Medicine
Advance Renal Cell Carcinoma Therapeutics Market
Specialty Medicine
Cystic Fibrosis Market
Specialty Medicine
Geographic Atrophy Market
Specialty Medicine
Global Urea Cycle Disorder Market
Specialty Medicine
Toxic Shock Syndrome Treatment Market
Specialty Medicine
Ragweed Pollen Allergy Treatment Market
Specialty Medicine
Mucous Membrane Pemphigoid Treatment Market