
 Coagulation Disorders Market | 2026-2036
Coagulation Disorders Market Size, Share, and Industry Trends Forecast 2026-2036
Coagulation Disorders Market Outlook
CE marking under the EU Medical Device Regulation is reorganizing which manufacturers can supply coagulation diagnostic platforms and therapeutic devices in European markets. CSL Behring leverages its integrated plasma collection network to sustain recombinant factor VIII supply security. Grifols S.A. anchors its position through vertical control over fractionation capacity across multiple continents. Pfizer Inc. competes by extending its gene therapy pipeline into hemophilia A and B candidates.
Coagulation disorders encompass pathological conditions impairing blood clot formation, including deficiencies in clotting factors VIII, IX, and von Willebrand factor, typically managed through replacement therapies with recombinant or plasma-derived concentrates. These therapies prevent spontaneous hemorrhage, enable surgical intervention, and support prophylactic regimens in severe hemophilia patients. Recombinant factor concentrates command premium positioning due to reduced infection risk and higher purity profiles, while plasma-derived factors retain cost-sensitive volume in emerging markets. Homecare settings represent the fastest-expanding end-user channel as subcutaneous and extended-half-life formulations reduce infusion burden. Diagnostic laboratories concentrate margin pools through specialized coagulation assay services that guide individualized dosing protocols.
FDA's biosimilar approval framework and EMA's MDR compliance requirements jointly elevate clinical evidence standards for new coagulation product entrants, compressing timelines for generic substitution while extending development costs. The WHO's prequalification program and national blood safety regulations in China, Japan, and India further fragment market access requirements across manufacturing geographies. Stakeholders must monitor gene therapy durability data and payer willingness to fund one-time curative interventions versus chronic replacement regimens.
Market Dynamics
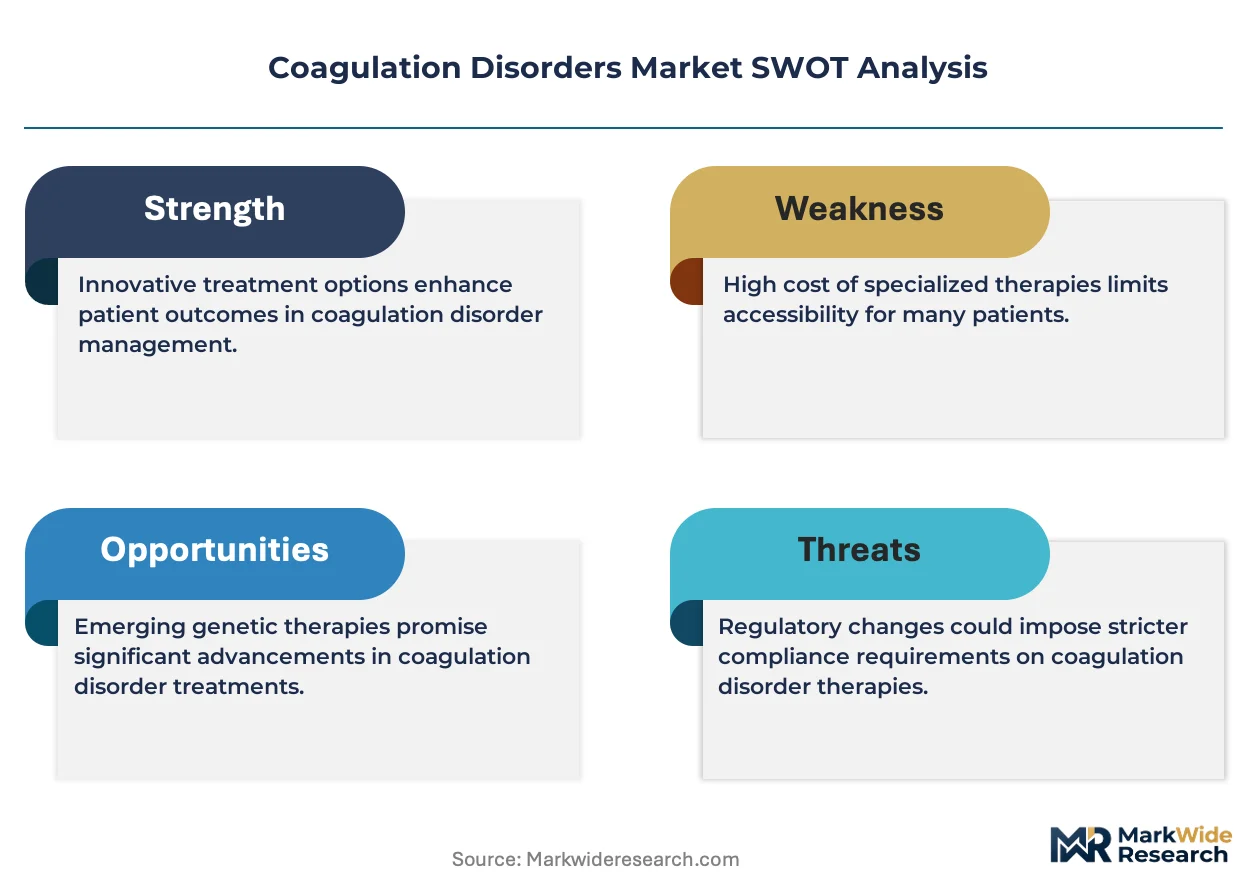
Gene therapy durability uncertainties are reshaping payer calculations across chronic replacement therapy markets, forcing manufacturers to defend long-term revenue streams against one-time curative alternatives while clinical evidence accumulates.
Growth Catalysts
- Extended-half-life formulations:Subcutaneous delivery technologies reduce infusion frequency from thrice-weekly to biweekly or monthly regimens. Hemophilia treatment centers in the United States and Germany are expanding prophylactic protocols based on these pharmacokinetic improvements.
- FDA biosimilar pathway maturation:Abbreviated approval frameworks for recombinant factor VIII and IX concentrates compress generic entry timelines. EMA's parallel biosimilar guidance accelerates competitive substitution across European markets.
- Homecare infrastructure expansion:Specialized infusion nursing networks and patient education programs enable self-administration outside hospital settings. Japan's Ministry of Health, Labour and Welfare reimbursement policies explicitly favor home-based factor prophylaxis.
Market Restraints
- Plasma collection concentration:Fractionation-grade plasma supply concentrates in the United States and select European collection networks. Geographic dependency creates vulnerability to donor pool fluctuations and export restriction policies.
- Gene therapy substitution threat:Valoctocogene roxaparvovec and similar one-time interventions threaten chronic factor replacement markets. Payer cost-benefit analyses increasingly benchmark lifetime replacement costs against single-dose curative pricing.
- EMA MDR compliance burden:CE marking requirements for coagulation diagnostic platforms demand extensive clinical performance data. Small and mid-sized manufacturers face extended certification timelines and elevated documentation costs.
Strategic Opportunities
- India's hemophilia care gap:Underdiagnosis rates exceeding seventy percent in rural districts create latent demand for portable diagnostic platforms. CDSCO streamlined approval pathways for orphan biologics reduce market entry friction.
- Real-world evidence integration:Pharmacovigilance databases and patient registry analytics enable personalized dosing algorithms. Convergence of bioinformatics with therapeutic monitoring supports outcome-based contracting models.
- Direct-to-patient distribution:Specialty pharmacy networks bypass hospital procurement committees for stable chronic patients. Cold-chain logistics investments enable factor concentrate delivery to home addresses in Germany and Japan.
Industry Challenges
- Gene therapy manufacturing scale-up:Viral vector production capacity constraints limit commercial supply of AAV-based hemophilia treatments. Bioreactor yield variability complicates batch scheduling and release timelines.
- ISO 13485 certification maintenance:Quality management system audits for in-vitro diagnostic devices demand continuous documentation updates. Coagulation assay manufacturers face resource allocation trade-offs between product development and compliance activities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coagulation Disorders Market |
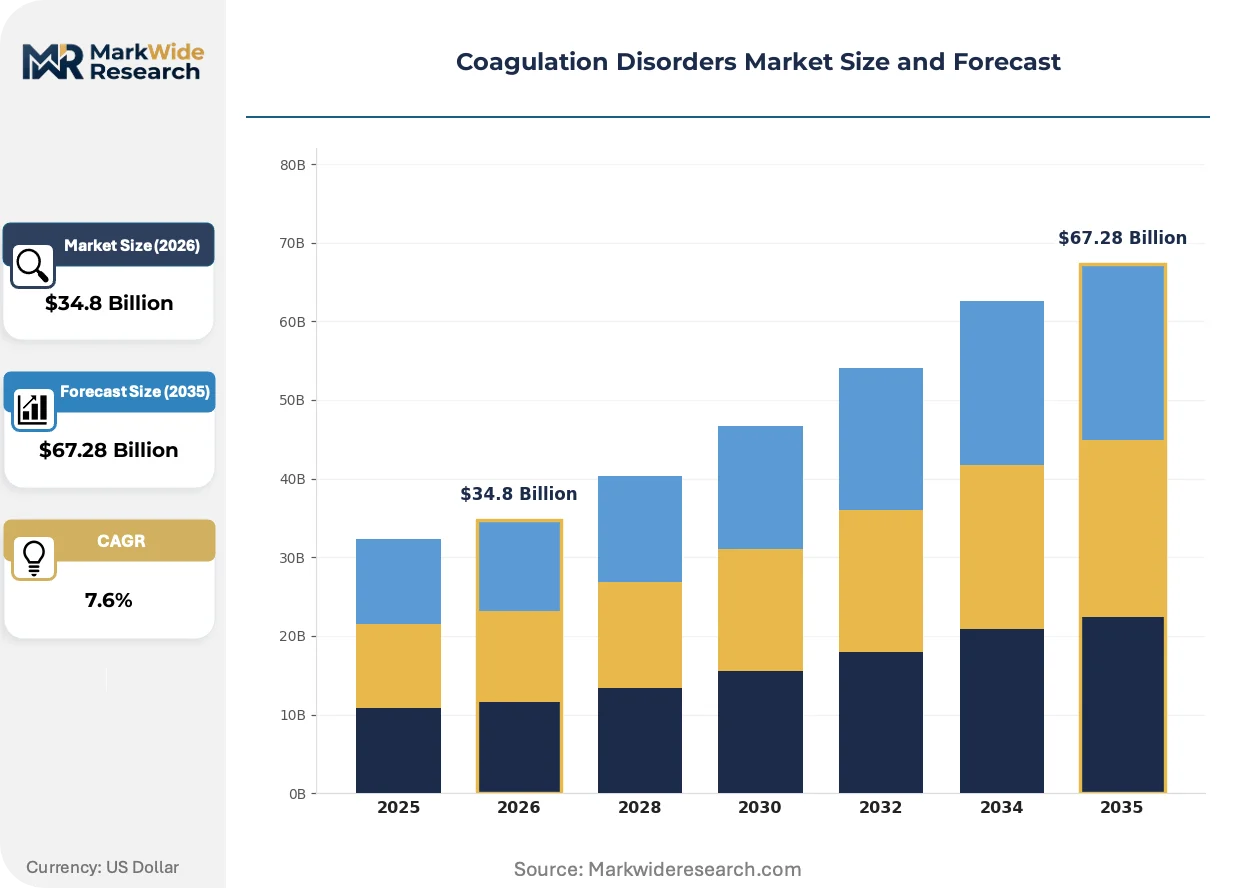
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $67.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant Factor, Plasma-Derived Factor, Antifibrinolytic Agents, Desmopressin End User: Hospitals, Specialty Clinics, Homecare Settings, Diagnostic Laboratories Indication: Hemophilia A, Hemophilia B, Von Willebrand Disease, Acquired Coagulation Disorders Administration Route: Intravenous, Subcutaneous, Oral, Nasal |
| Companies Covered | CSL Behring, Grifols S.A., Bayer AG, Pfizer Inc., Takeda Pharmaceutical Company, Octapharma AG, F. Hoffmann-La Roche Ltd, Abbott Laboratories, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coagulation Disorders Market Strategic Shifts
Digital biomarker integration and subcutaneous delivery platforms are compressing the traditional hospital-centered care model, shifting clinical decision-making toward patient-generated data and decentralized administration settings.
Extended-half-life factor concentrates incorporating Fc-fusion and PEGylation technologies are displacing standard recombinant products in prophylactic regimens. Hemophilia treatment centers in the United States and Germany prioritize these formulations for severe patients. The shift compresses annual infusion burdens from 150-180 to 25-50 administrations, reducing catheter-related complications and nursing costs.
EMA's Medical Device Regulation enforcement is elevating clinical evidence requirements for coagulation diagnostic platforms. Manufacturers must submit expanded performance validation data for CE marking renewal. European laboratories are consolidating procurement around platforms with pre-validated MDR technical files, marginalizing smaller instrument suppliers.
Patient registry data is reshaping factor concentrate purchasing decisions. United States payers increasingly reference ATHN and CDC surveillance databases when negotiating formulary placement. Germany's G-BA now mandates real-world evidence submissions for novel extended-half-life products seeking premium reimbursement tiers.
Coagulation Disorders Market Segmentation
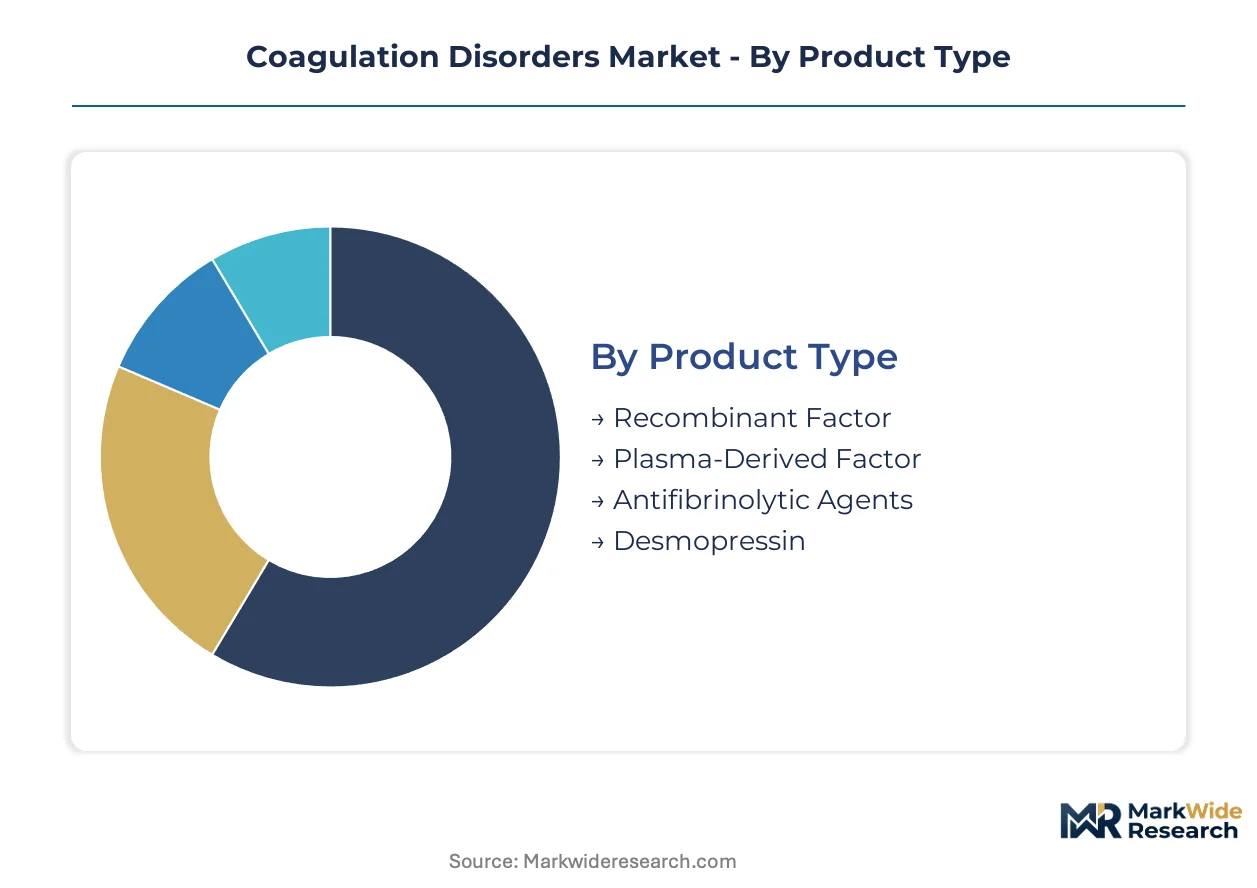
Coagulation disorder therapies fragment across product origin, care setting, and administration method. Each segment carries distinct regulatory pathways, reimbursement codes, and supply chain requirements that determine competitive positioning.
Product Type:
FDA and EMA approval frameworks differentiate recombinant biologics from plasma-derived products through distinct clinical evidence requirements and post-market surveillance obligations.
- Recombinant Factor:Cell culture-produced clotting factors VIII and IX eliminate viral transmission risk. Hemophilia treatment centers in the United States and Germany prioritize these formulations for severe patients requiring lifelong prophylaxis.
- Plasma-Derived Factor:Fractionated from human donor plasma, these concentrates retain cost-sensitive volume in emerging markets where cold-chain infrastructure limits recombinant distribution.
- Antifibrinolytic Agents:Tranexamic acid and epsilon-aminocaproic acid inhibit fibrinolysis in mucosal bleeding episodes.
- Desmopressin:Synthetic vasopressin analog stimulates endogenous factor VIII release in mild hemophilia and von Willebrand disease type 1.
Recombinant Factor handles the majority of throughput; Plasma-Derived Factor is the fastest mover on share.
End User:
Reimbursement policy divergence across care settings is redistributing where factor concentrates are administered and who controls purchasing decisions.
- Hospitals:Acute bleeding episodes and surgical interventions require inpatient factor replacement with intensive monitoring. German DRG codes and US Medicare severity-adjusted diagnosis groups determine payment rates for these high-acuity encounters.
- Homecare Settings:Self-administered prophylaxis reduces annual hospital days and nursing costs. Japan's Ministry of Health, Labour and Welfare explicitly favors home-based factor delivery through dedicated reimbursement categories.
- Specialty Clinics:Hemophilia treatment centers coordinate multidisciplinary care and maintain patient registries.
- Diagnostic Laboratories:Coagulation assay services guide individualized dosing protocols and treatment center formulary decisions.
Hospitals retain the dominant share of acute episode volume; Homecare Settings are expanding most quickly as extended-half-life formulations enable less frequent administration.
Indication:
Prevalence variation and treatment intensity requirements create divergent revenue pools across bleeding disorder categories.
- Hemophilia A:Factor VIII deficiency constitutes the largest addressable population. Prophylactic regimens require 25-50 annual infusions with extended-half-life products, generating sustained concentrate consumption.
- Von Willebrand Disease:Heterogeneous severity and type distribution complicate standardization. Desmopressin-responsive type 1 patients require minimal factor replacement, while type 3 severe cases demand concentrate therapy comparable to hemophilia.
- Hemophilia B:Factor IX deficiency presents lower prevalence but higher per-patient factor consumption due to shorter half-life.
- Acquired Coagulation Disorders:Autoimmune inhibitors and liver disease-related deficiencies require bypassing agents and immunosuppression.
Hemophilia A commands the deepest revenue pool; Von Willebrand Disease is climbing the fastest as underdiagnosis correction expands treatable population estimates.
Administration Route:
Delivery technology innovation is compressing infusion burden and shifting competitive advantage toward formulation chemistry capabilities.
- Intravenous:Direct vascular access remains standard for factor concentrates requiring precise bioavailability. Central venous access devices enable home administration but carry infection and thrombosis risks.
- Subcutaneous:Needle-based delivery beneath the dermis enables patient self-administration without vascular access. Extended-half-life formulations with Fc-fusion or PEGylation technologies achieve therapeutic factor levels through this route.
- Oral:Small-molecule antifibrinolytics and non-factor replacement therapies bypass injection requirements.
- Nasal:Desmopressin spray delivery addresses mild bleeding episodes without needle access.
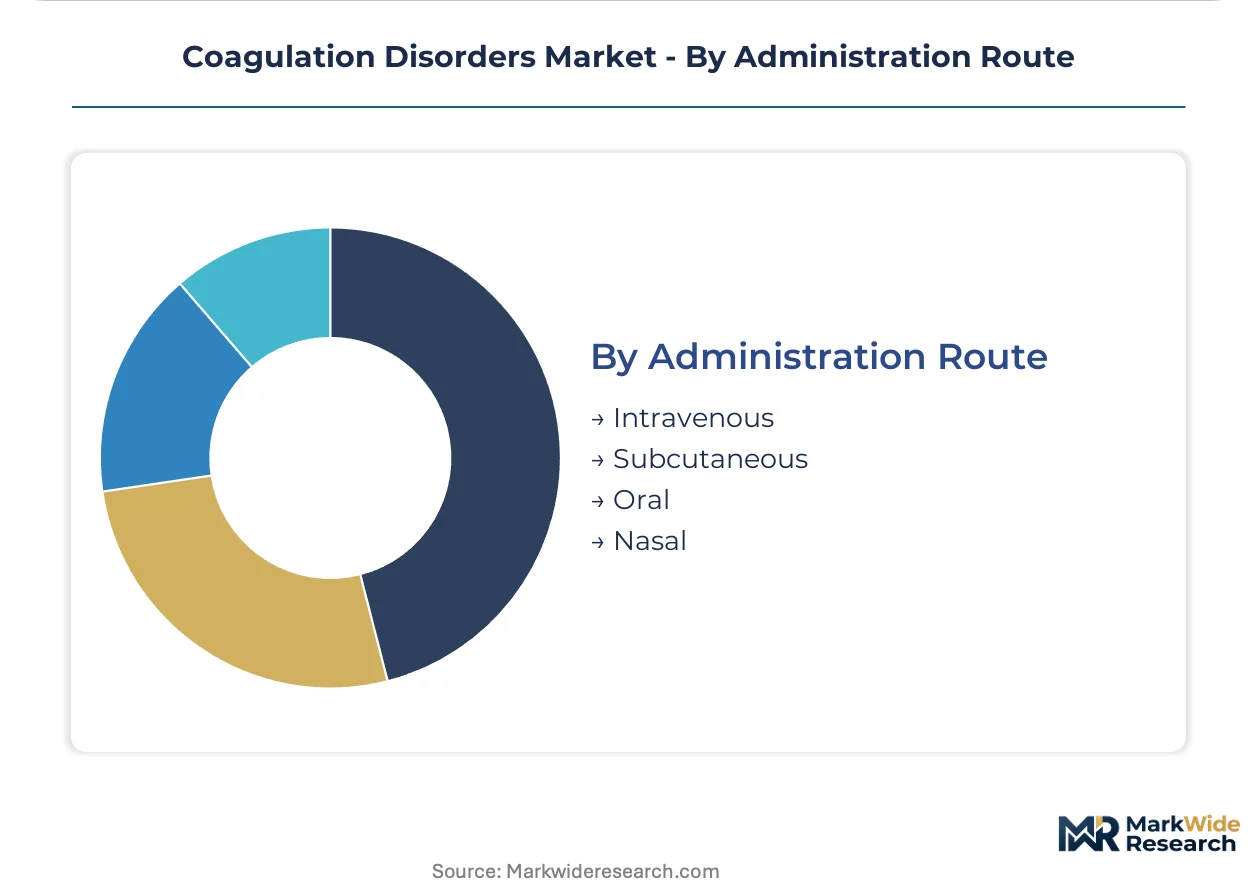
Intravenous maintains procedure volume dominance; Subcutaneous is gaining share fastest as formulation technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's biosimilar pathway acceleration and Japan's homecare reimbursement policies are redistributing procurement authority across national healthcare systems, while EMA's MDR enforcement elevates clinical evidence requirements for European market access.
United States
Hemophilia treatment centers in Boston and New York Metro are expanding prophylactic protocols using extended-half-life formulations. FDA's abbreviated approval frameworks for recombinant factor concentrates compress generic entry timelines for biosimilar entrants. The analysis identifies concentrated procurement activity around specialized coagulation care networks in the Northeast Corridor and California.
Germany
German DRG codes and G-BA reimbursement policies determine payment rates for high-acuity coagulation episodes in university hospitals. EMA's Medical Device Regulation demands expanded performance validation data for CE marking renewal of diagnostic platforms. The Ruhr industrial cluster anchors fractionation capacity investments serving Central European distribution networks.
Japan
Japan's Ministry of Health, Labour and Welfare reimbursement policies explicitly favor home-based factor prophylaxis through dedicated payment categories. PMDA streamlined review pathways for orphan biologics accelerate market entry for novel concentrate formulations. The Kanto region around Tokyo concentrates hemophilia treatment center density and specialized nursing networks.
India
Underdiagnosis rates exceeding seventy percent in rural districts create latent demand for portable diagnostic platforms and factor concentrates. CDSCO streamlined approval pathways for orphan biologics reduce market entry friction for plasma-derived and recombinant products. Maharashtra and Gujarat host emerging fractionation investments targeting domestic supply security.
United Kingdom
NHS England specialized commissioning frameworks concentrate purchasing decisions for hemophilia A and B therapies at the national level. MHRA post-Brexit regulatory autonomy maintains alignment with EMA guidance while preserving independent approval pathways. London and the Southeast anchor patient registry infrastructure and real-world evidence collection networks.
Coagulation Disorders Market Competitive Environment
Player mix skews toward integrated plasma collectors and recombinant biologic specialists with captive fractionation capacity. Market structure concentrates around vertically controlled supply chains and gene therapy pipeline developers. Three archetypes dominate: plasma-integrated multinationals, recombinant factor innovators, and diagnostic platform specialists. Competitive moves center on M&A for fractionation assets and strategic partnerships for viral vector manufacturing scale-up.
Among plasma-integrated multinationals, CSL Behring and Grifols S.A. occupy positions defined by captive collection networks across multiple continents, while Pfizer Inc. represents the gene therapy pipeline archetype with hemophilia A and B candidates in development. These three companies exemplify divergent strategic bets on chronic replacement versus curative intervention models.
| Leading Market Players |
|---|
| CSL Behring |
| Grifols S.A. |
| Bayer AG |
| Pfizer Inc. |
| Takeda Pharmaceutical Company |
| Octapharma AG |
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| Bio-Rad Laboratories |
| Others |
Value Chain & Pricing Dynamics
Fractionation plant scale economies in the United States and Germany compress unit production costs for plasma-derived factors while simultaneously elevating price floors for smaller manufacturers lacking captive collection networks. CSL Behring's integrated North American plasma centers and Grifols S.A.'s multi-continental fractionation footprint anchor supply concentration that translates directly into pricing power across recombinant and plasma-derived concentrate tiers.
Pricing Analysis
Certification level creates the primary spread between premium recombinant factors and economy-tier plasma-derived alternatives. FDA-grade and EMA-compliant biologics command substantial premiums over CDSCO-registered products in emerging markets. Cost compression in the plasma-derived tier is intensifying because biosimilar recombinant entrants are compressing historical price premiums. Hospital procurement committees in the United States and Germany exhibit lowest price sensitivity due to severity-adjusted reimbursement codes, while Indian state tender systems represent the most price-constrained buyer segment.
Supply Chain Analysis
Inventory lead times for fractionation-grade plasma extend 6-12 months from donor collection to finished concentrate release, tethering supply security to sustained donor pool stability. Plasma collection concentrates in the United States, Germany, and Austria, with fractionation capacity clustering around CSL Behring's Kankakee facility and Grifols S.A.'s Barcelona complex. Single-source vulnerability runs through viral vector manufacturing for gene therapy candidates, where bioreactor yield variability constrains batch scheduling. Distribution runs through cold-chain logistics networks serving hemophilia treatment centers and direct-to-patient specialty pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coagulation disorders market is cycling through a post-pandemic recovery phase as deferred surgical procedures and restored prophylactic regimens rebuild baseline factor consumption. Gene therapy durability data accumulation represents the critical cyclical inflection determining long-term replacement therapy viability.
For Market Incumbents: Shield recombinant factor revenue streams by accelerating extended-half-life formulation transitions before gene therapy durability data matures. Secure backward integration into viral vector manufacturing capacity to preserve optionality for curative pipeline assets. Prioritize M&A for fractionation assets in India and Southeast Asia to preempt emerging market supply localization.
For New Entrants and Emerging Players: Anchor in India's underdiagnosed rural districts where portable diagnostic platforms can unlock latent hemophilia A and B patient identification. Target Maharashtra and Gujarat for plasma collection infrastructure partnerships leveraging CDSCO streamlined orphan biologic pathways. Pursue direct-to-patient distribution models bypassing hospital procurement committees for stable chronic patients.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors plasma-integrated multinationals with gene therapy pipeline optionality over pure-play recombinant specialists. Long-term viability across the 5-10 year window hinges on demonstrating durable factor expression from AAV-based interventions. Monitor payer willingness-to-pay thresholds for one-time curative pricing against lifetime replacement cost benchmarks as the decisive inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Viral Vector Manufacturing Scale-Up | Bioreactor yield improvements at Grifols S.A. and Pfizer Inc. facilities determine gene therapy commercial supply security. |
| EMA MDR Compliance Pathway | CE marking renewal for coagulation diagnostic platforms demands expanded clinical performance validation from Bio-Rad Laboratories. |
| Homecare Reimbursement Strategy | Japan's Ministry of Health, Labour and Welfare payment categories explicitly favor self-administered factor prophylaxis models. |
| Real-World Evidence Integration | ATHN and CDC surveillance database convergence enables outcome-based contracting for extended-half-life formulations. |
| Plasma Collection Network Expansion | CSL Behring's integrated North American donor centers sustain recombinant factor VIII supply security against export restrictions. |
Study Parameters
Operator-level perspectives from hemophilia treatment center directors, hospital procurement managers, plasma collection network executives, and regulatory affairs specialists anchored the qualitative base. These primary insights combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient population estimates and top-down revenue triangulation cross-verified segmentation outputs across product type, indication, and administration route dimensions.
Sensitivity analysis tested forecast robustness across gene therapy durability scenarios, biosimilar entry timing assumptions, and plasma supply disruption probabilities. Segmentation modeling incorporated treatment line, factor concentrate origin, care setting, and regional regulatory cluster dimensions. CAGRs derived from historical volume trends, pricing trajectory analysis, and patient population growth projections. Forecast inputs included extended-half-life formulation adoption curves, homecare infrastructure penetration rates, and real-world evidence integration timelines.
Decision-makers should treat outputs as directional under sustained gene therapy clinical uncertainty and evolving payer cost-benefit frameworks; material deviation in durability data or reimbursement policy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Scleritis Market
Specialty Medicine
Large Granular Lymphocytic Leukemia (LGLL) Therapeutics Market
Specialty Medicine
Hemifacial Spasm Market
Specialty Medicine
Hypothyroidism Market
Specialty Medicine
Global Liver Cancer Treatment Market
Specialty Medicine
Asia-Pacific Sports Medicine Market
Specialty Medicine
Triple X Syndrome Management Market
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
Global Autism Spectrum Disorders Market
Specialty Medicine
Global Addison's Disease Treatment Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
Behcet's Syndrome Market
Specialty Medicine
Overt Hepatic Encephalopathy Market
Specialty Medicine
Global Autoimmune Disease Therapeutics Market
Specialty Medicine
Recto-Vaginal Fistula Market
Specialty Medicine
Diverticulitis Disease Market