
 Triple X Syndrome Management Market | 2026-2036
Triple X Syndrome Management Market Size, Share, and Industry Trends Forecast 2026-2036
Triple X Syndrome Management Market Analytics
North American diagnostic laboratories is pivoting toward non-invasive prenatal testing integration for chromosomal aneuploidy detection. Hoffmann-La Roche leverages its molecular diagnostics platform to sustain competitive positioning in karyotyping and fluorescence in situ hybridization workflows. Centogene N.V. anchors its rare disease focus with specialized genetic testing panels for sex chromosome abnormalities. Illumina Inc competes through next-generation sequencing instrument placement in clinical reference labs.
Triple X syndrome management encompasses clinical interventions for trisomy X, a chromosomal condition affecting approximately one in one thousand female births characterized by an extra X chromosome (47,XXX karyotype). Primary management addresses developmental delays, learning disabilities, and endocrine dysfunction through coordinated multidisciplinary care rather than curative therapy. Hormonal therapy represents the most established segment with sustained prescribing for premature ovarian insufficiency and estrogen deficiency management. Diagnostic tools constitute the fastest-expanding category as non-invasive prenatal screening and postnatal chromosomal microarray adoption accelerate detection rates. Telehealth delivery mode shows structural momentum driven by psychiatric consultation access gaps in rural and underserved regions.
FDA oversight governs diagnostic assay validation and therapeutic orphan drug incentives, while HIPAA frameworks shape telehealth platform compliance requirements for genetic counseling services. State-level newborn screening program expansion in the United States directly determines addressable patient identification rates and downstream service demand. Stakeholders must monitor reimbursement policy evolution for genetic counseling CPT codes and chromosomal microarray testing to assess service model viability.
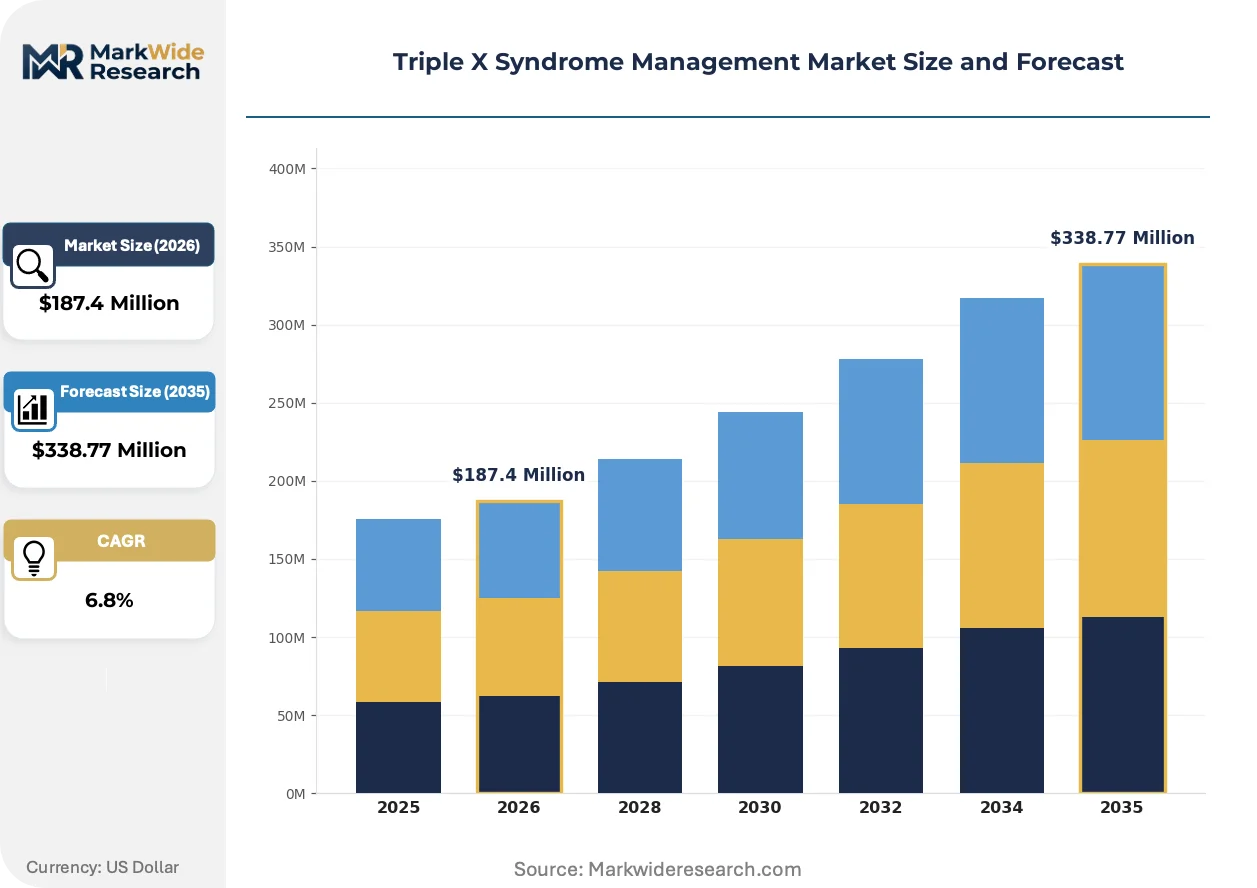
Market Dynamics
Non-invasive prenatal testing integration is compressing diagnostic timelines for chromosomal aneuploidy detection while reshaping referral patterns between obstetric practices and genetic counseling services.
Growth Catalysts
- HIPAA-compliant telehealth expansion:Rural psychiatric consultation access gaps are driving platform adoption for genetic counseling delivery across underserved United States counties.
- Newborn screening infrastructure:State-level program expansion in the United States is accelerating patient identification rates and downstream service demand for rare chromosomal conditions.
- Chromosomal microarray technology:Postnatal detection capabilities are improving diagnostic yield for sex chromosome abnormalities in pediatric and adolescent populations.
Market Restraints
- Genetic counselor workforce scarcity:Specialized training pipeline limitations constrain service capacity expansion despite rising detection rates.
- Reimbursement code fragmentation:Inconsistent CPT coding for chromosomal microarray testing creates payment uncertainty across United States commercial and Medicaid plans.
- Estrogen therapy supply concentration:Hormonal therapeutic manufacturing relies on a limited supplier base for pharmaceutical-grade formulations.
Strategic Opportunities
- Orphan drug designation pathway:FDA incentives for rare disease therapeutics are attracting development investment toward targeted endocrine interventions.
- Integrated care coordination platforms:Technology convergence between electronic health records and telehealth is enabling multidisciplinary team management for developmental delay interventions.
- School-based screening programs:Educational system partnerships in the United States offer underpenetrated channels for early learning disability identification and referral.
Industry Challenges
- Genetic data privacy compliance:State-level variation in biometric information protection laws complicates telehealth platform architecture for interstate counseling services.
- Multidisciplinary care integration:Coordination friction between endocrinology, psychiatry, and developmental pediatrics delays treatment initiation for complex presentations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Triple X Syndrome Management Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Behavioral Therapy, Hormonal Therapy, Supportive Care, Psychosocial Intervention End User: Pediatric Clinics, Hospitals, Rehabilitation Centers, Home Care Product Type: Therapeutic Devices, Diagnostic Tools, Educational Resources, Supplement Products Delivery Mode: Oral, Injectable, Telehealth, In-person Sessions |
| Companies Covered | Hoffmann-La Roche, Novartis AG, Pfizer Inc, Centogene N.V., Illumina Inc, Invitae Corporation, Quest Diagnostics Incorporated, Natera Inc, PerkinElmer Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Triple X Syndrome Management Market Evolving Landscape
Detection methodology shifts and care delivery reconfiguration are fundamentally altering how trisomy X cases enter clinical management pathways and how services are reimbursed.
Cell-free DNA screening platforms are absorbing market share from traditional serum analyte testing in first-trimester aneuploidy detection workflows. United States maternal-fetal medicine practices are adopting these platforms at accelerating velocity for high-risk pregnancies. The technology is absorbing capital allocation that previously supported karyotyping infrastructure expansion.
FDA orphan drug designation incentives are reshaping therapeutic development prioritization for sex chromosome aneuploidy conditions. Pharmaceutical developers are redirecting pipeline resources toward conditions with established regulatory fast-track pathways. Pediatric endocrinology segments in the United States are responding with expanded investigator-initiated trial participation for premature ovarian insufficiency therapies.
Direct-to-consumer genetic testing awareness is compressing traditional physician-mediated diagnostic pathways for adult women. Primary care practices in the United States are encountering patients with self-identified chromosomal findings requiring clinical confirmation and counseling. This behavioral shift is most visible in metropolitan markets with high digital health literacy penetration.
Triple X Syndrome Management Market Segmentation
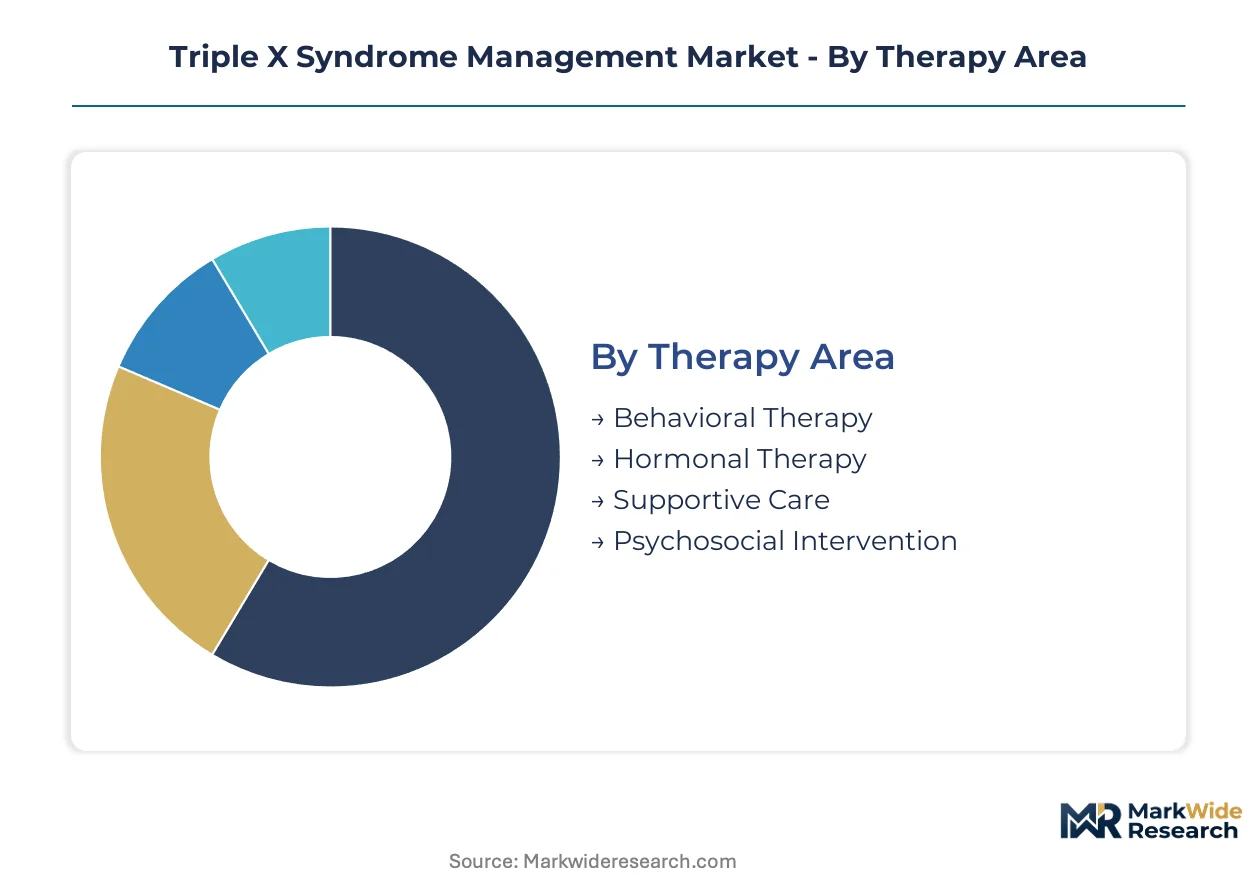
Segmentation in Triple X syndrome management reveals how patient identification pathways and reimbursement structures concentrate demand across distinct service categories. Each dimension captures a different axis of clinical workflow integration and care coordination complexity.
Therapy Area:
Upgrade cycles in therapeutic protocols are accelerating as chromosomal microarray detection expands the addressable patient base earlier in life stages.
- Hormonal Therapy:Estrogen replacement protocols address premature ovarian insufficiency and pubertal delay in 47,XXX karyotype patients. Pediatric endocrinology practices in the United States sustain the highest prescription volumes due to established referral pathways from newborn screening programs.
- Behavioral Therapy:Speech-language and occupational interventions target developmental delays and learning disabilities characteristic of trisomy X presentations. School district partnerships in California and Texas are driving demand concentration as individualized education plan eligibility expands.
- Supportive Care:Coordinated nursing and developmental monitoring services manage multisystem complications. These services concentrate in academic medical center networks with dedicated sex chromosome aneuploidy clinics.
- Psychosocial Intervention:Psychiatric and counseling services address anxiety, depression, and social cognition deficits. Rural access gaps are compressing delivery into telehealth platforms across underserved United States counties.
Hormonal therapy sits at the top of the volume ranking, with behavioral therapy climbing the fastest.
End User:
Cost tier stratification separates high-acuity inpatient management from longitudinal outpatient coordination.
- Pediatric Clinics:Primary care and developmental pediatrics practices conduct initial screening referrals and coordinate multidisciplinary follow-up. United States Medicaid managed care contracts are concentrating patient attribution into large clinic networks with genetic counseling capacity.
- Hospitals:Academic medical centers and children's hospitals manage complex presentations requiring endocrine, psychiatry, and genetics co-management. Major pediatric referral hubs in Boston, Philadelphia, and Houston anchor regional patient capture.
- Rehabilitation Centers:Physical and cognitive therapy services address motor coordination and learning disability manifestations. These facilities compete for school-age referrals through individualized education plan funding mechanisms.
- Home Care:Nursing support and therapy delivery in residential settings serves geographically dispersed populations. Reimbursement limitations constrain expansion outside Medicare Advantage and commercial managed care plans with home health benefits.
Pediatric clinics command the largest patient volume footprint, with telehealth-enabled home care gaining share fastest.
Product Type:
Application intensity varies sharply between diagnostic detection workflows and ongoing therapeutic management.
- Diagnostic Tools:Chromosomal microarray, karyotyping, and fluorescence in situ hybridization platforms enable definitive 47,XXX identification. United States reference laboratories are prioritizing non-invasive prenatal testing integration for first-trimester aneuploidy detection.
- Therapeutic Devices:Hormone delivery systems and assistive technologies for developmental support comprise this category. Limited device-specific reimbursement codes restrict adoption outside endocrine therapy pumps.
- Educational Resources:Curriculum adaptations and learning disability intervention materials serve school-based management. State department of education procurement in the United States determines regional vendor selection.
- Supplement Products:Nutritional and wellness formulations target associated metabolic and bone health complications. Direct-to-consumer distribution channels dominate given minimal clinical evidence requirements.
Diagnostic tools generate the highest revenue concentration, with educational resources expanding most quickly through school district contract channels.
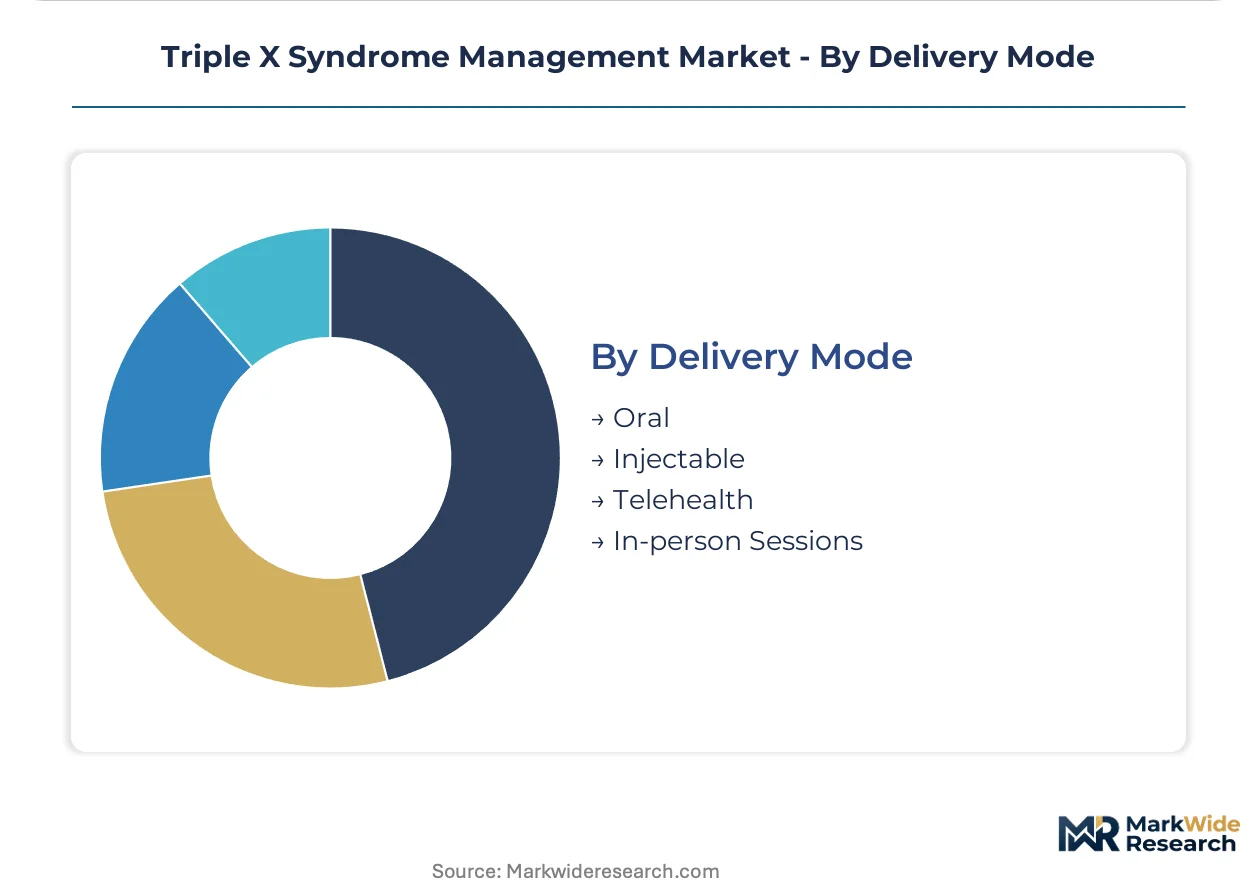
Delivery Mode:
Customer type stratification separates institutional procurement from individual patient access pathways.
- Oral:Estrogen and related hormonal formulations represent the dominant therapeutic administration route. Pharmaceutical supply chain concentration in United States generic manufacturing sustains cost accessibility.
- Telehealth:Psychiatric consultation and genetic counseling delivery bypass geographic specialist scarcity. HIPAA-compliant platform adoption accelerated following state-level parity law expansion for telebehavioral health reimbursement.
- Injectable:Depot hormone formulations and biologic therapies serve non-compliant or complex patients. Endocrinology practices in major metropolitan United States markets maintain injection administration capacity.
- In-person Sessions:Traditional clinic-based therapy and counseling remains required for developmental and behavioral interventions. Workforce scarcity limits expansion despite detection rate increases.
Oral delivery maintains volume leadership, with telehealth posting the steepest expansion trajectory across all therapy areas.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States diagnostic infrastructure outpaces Canadian detection capacity by a factor of ten, while European regulatory harmonization lags behind North American reimbursement velocity for rare chromosomal conditions.
United States
Newborn screening program expansion in Texas and California drives patient identification rates upward. HIPAA frameworks govern telehealth platform compliance for interstate genetic counseling delivery. Boston's academic medical corridor anchors multidisciplinary sex chromosome aneuploidy clinic concentration with established endocrinology-psychiatry co-management protocols.
Germany
Reference laboratory consolidation in Bavaria and North Rhine-Westphalia accelerates chromosomal microarray adoption. EMA orphan drug designation pathways attract therapeutic development investment toward premature ovarian insufficiency interventions. Heidelberg's molecular diagnostics cluster sustains fluorescence in situ hybridization workflow specialization for prenatal screening programs.
United Kingdom
National Health Service genomic medicine service integration expands postnatal detection capabilities for sex chromosome abnormalities. NHS England commissioning frameworks determine regional genetic counseling capacity allocation. London's Great Ormond Street Hospital network coordinates pediatric endocrinology referrals with dedicated developmental delay assessment pathways.
Japan
Maternal-fetal medicine specialist scarcity in rural prefectures compresses non-invasive prenatal testing adoption into metropolitan Tokyo and Osaka corridors. PMDA regulatory timelines for diagnostic assay validation exceed FDA review durations by approximately eighteen months. Yokohama's biotechnology research quarter hosts chromosomal microarray platform development for Asia-Pacific market adaptation.
Australia
Medicare reimbursement expansion for chromosomal microarray testing in Victoria and New South Wales improves diagnostic accessibility for pediatric presentations. TGA oversight of laboratory-developed tests creates compliance complexity for United States-based platform imports. Melbourne's Murdoch Children's Research Institute anchors sex chromosome aneuploidy longitudinal cohort studies with integrated behavioral intervention tracking.
Triple X Syndrome Management Market Competitive Landscape
United States diagnostics conglomerates anchor one tier; European rare disease specialists hold differentiated positioning in chromosomal anomaly detection workflows. Market structure concentrates around three strategic archetypes: vertically integrated pharmaceutical-diagnostic hybrids, pure-play genetic testing laboratories, and molecular platform technology vendors. Capacity expansion through reference laboratory acquisition and strategic partnerships for newborn screening program access represent dominant competitive vectors.
Among Swiss pharmaceutical-diagnostic hybrids, Hoffmann-La Roche occupies a position exemplifying integrated molecular diagnostics platform leverage. German rare disease specialist Centogene N.V. and United States sequencing technology vendor Illumina Inc sit within distinct competitive tiers, with the former representing specialized genetic testing panel concentration and the latter anchoring next-generation sequencing instrument placement strategies in clinical reference laboratories.
| Leading Market Players |
|---|
| Hoffmann-La Roche |
| Novartis AG |
| Pfizer Inc |
| Centogene N.V. |
| Illumina Inc |
| Invitae Corporation |
| Quest Diagnostics Incorporated |
| Natera Inc |
| PerkinElmer Inc |
| Others |
Value Network & Pricing Analysis
FDA orphan drug designation pathways gate qualified supply for premium-tier hormonal therapeutics while compressing margins on undifferentiated diagnostic assays. State-level newborn screening procurement in the United States concentrates purchasing power among Medicaid managed care plans, forcing price differentiation between certified reference laboratories and uncertified testing providers.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for chromosomal microarray testing as reference laboratories compete for newborn screening program contracts. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated diagnostic platforms from laboratory-developed tests and direct-to-consumer genetic screening kits. Cost compression in the economy tier is intensifying because Medicare Advantage plans are narrowing genetic testing networks. Pediatric endocrinology practices show the least price sensitivity due to limited alternative suppliers for pharmaceutical-grade estrogen formulations.
Supply Chain Analysis
Freight costs for temperature-controlled hormone shipments from Germany and Switzerland to United States distribution centers add 12-15% to landed therapeutic costs. Pharmaceutical-grade estrogen active pharmaceutical ingredients draw from concentrated manufacturing in Germany, China, and India. Single-source vulnerability pervades the diagnostic reagent supply chain, where Illumina sequencing consumables anchor next-generation testing workflows. Distribution runs through specialty pharmaceutical distributors and direct-to-laboratory contracts for chromosomal microarray platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
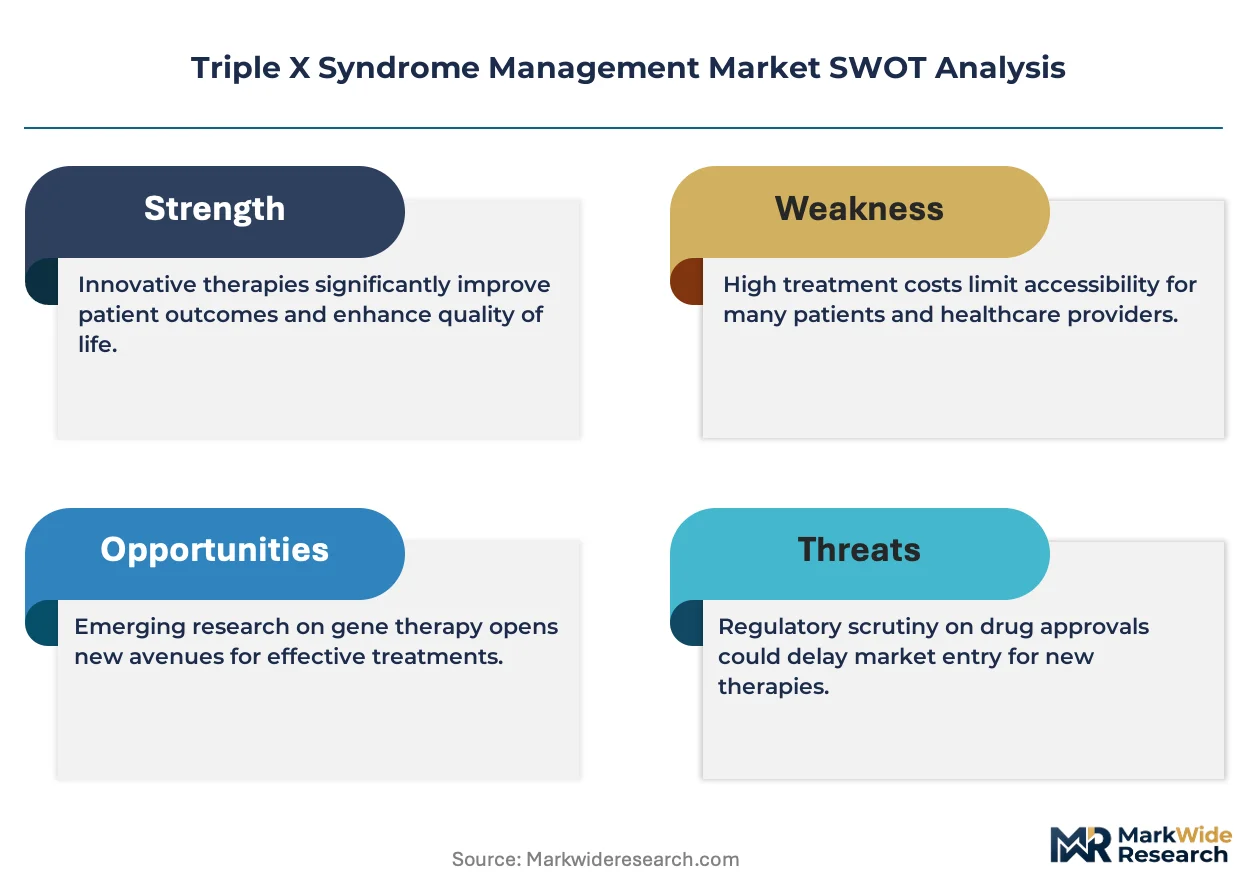
This market compounds regulatory value as FDA orphan drug designation milestones for premature ovarian insufficiency therapeutics accelerate development investment and expand reimbursable indication coverage.
For Market Incumbents: Acquire specialized genetic counseling practices to secure referral channel control against telehealth platform disintermediation. Consolidate chromosomal microarray testing capacity in Texas and California where newborn screening program expansion concentrates patient identification volume. Backward integration into estrogen active pharmaceutical ingredient sourcing mitigates supply concentration risk from German and Chinese manufacturers. For New Entrants and Emerging Players: Launch via school-based screening partnerships in underserved United States counties where individualized education plan funding mechanisms bypass traditional diagnostic referral bottlenecks. Target rural psychiatric consultation gaps through HIPAA-compliant telehealth platforms. White-space concentration exists in behavioral therapy curriculum development for learning disability intervention in California and Texas school districts. For Investors and Strategic Acquirers: Roll-up economics work for regional genetic testing laboratories because state-level newborn screening procurement creates fragmented local monopolies with sticky Medicaid managed care contracts. Five-to-ten-year viability hinges on reimbursement policy evolution for chromosomal microarray CPT codes. Monitor FDA orphan drug designation grants for premature ovarian insufficiency as the inflection signal for therapeutic pipeline value creation.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA fast-track status attracts venture funding for endocrine therapeutic development in rare chromosomal conditions. |
| Reference Laboratory Acquisition | Consolidation captures newborn screening program contracts in Texas and California Medicaid networks. |
| Telehealth Platform Integration | HIPAA-compliant infrastructure penetrates rural psychiatric consultation gaps across underserved United States counties. |
| School District Partnership Development | Individualized education plan eligibility pathways compress diagnostic timelines for developmental delay identification. |
| Chromosomal Microarray Reimbursement Strategy | CPT code advocacy determines reference laboratory viability under Medicare Advantage network narrowing. |
Research Methodology
Multiple input streams — primary interviews with pediatric endocrinologists and genetic counselors, regulatory filing analysis from FDA and EMA databases, and newborn screening program procurement records — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from ClinicalTrials.gov entries, CMS Medicare reimbursement data, hospital GPO contracts, and state health department screening program reports. Conversations with Medicaid managed care formulary directors and reference laboratory operations executives informed service model viability assessments.
Data-stream reconciliation across therapy area, end user, product type, and delivery mode segmentation generated volume and value estimates throughout the forecast period. CAGRs were derived from patient identification rate modeling tied to newborn screening infrastructure expansion and telehealth parity law adoption patterns. Hormonal therapy prescription volumes, chromosomal microarray test reimbursement trajectories, and genetic counselor workforce supply constraints served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under state-level CPT code fragmentation scenarios and pharmaceutical-grade estrogen supply disruptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Treatment-Resistance Depression Treatment Market
Specialty Medicine
Cystic Fibrosis Market
Specialty Medicine
Global Attention Deficit Hyperactivity Disorder Market
Specialty Medicine
APAC Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Glioma Therapeutics Market
Specialty Medicine
Advance Renal Cell Carcinoma Therapeutics Market
Specialty Medicine
Non Small Cell Lung Cancer (NSCLC) Therapeutics Market
Specialty Medicine
Solid Tumor Therapeutics Market
Specialty Medicine
Global Breast Cancer Therapeutics Market
Specialty Medicine
Global Prurigo Nodularis Treatment Market
Specialty Medicine
Blastomycosis Treatment Market
Specialty Medicine
US Opioid Use Disorder (OUD) Market
Specialty Medicine
Americas Gerd and Nerd Treatment Market
Specialty Medicine
China Precision Medicine Market
Specialty Medicine
Stuttering Therapeutics Market
Specialty Medicine
Hyperuricemia Market